
 Gabon Oil and Gas Downstream Market | 2026-2036
Gabon Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Gabon Oil and Gas Downstream Market Foresight
Product flow channels across Gabon's downstream network are tilting toward direct bulk supply arrangements with industrial consumers. TotalEnergies SE leverages its integrated logistics footprint to serve mining and maritime clients along the Atlantic coast. Perenco SA anchors its position through control of coastal storage terminals and pipeline delivery systems. VAALCO Energy Inc. competes by specializing in high-volume fuel supply to remote extraction sites in the interior.
The Gabon Oil and Gas Downstream sector encompasses refining, storage, distribution, and marketing of petroleum derivatives including gasoline with octane ratings typically ranging from 91 to 95, diesel conforming to Euro 2 through Euro 4 sulfur specifications, and residual fuel oils for industrial combustion. Its primary commercial purpose is converting crude oil into usable energy products for domestic consumption and limited re-export through Atlantic terminals. Refined petroleum products command the largest revenue pool given transportation fuel demand, while liquefied petroleum gas represents the fastest-growing product category as households and small industries switch from wood and charcoal. Pipeline networks capture premium margin structures due to their efficiency in moving volumes from Port-Gentil refinery complexes to inland demand centers.
Gabon's national hydrocarbon regulator and the Ministry of Petroleum enforce local content quotas and environmental compliance standards for downstream operations, while the country's central bank monitors foreign exchange availability for fuel import settlements. These frameworks shape capital deployment timelines and determine which distribution channel configurations qualify for operating licenses. Stakeholders must monitor regulatory enforcement consistency and foreign currency access conditions when evaluating terminal expansion or retail network investments.
Market Dynamics
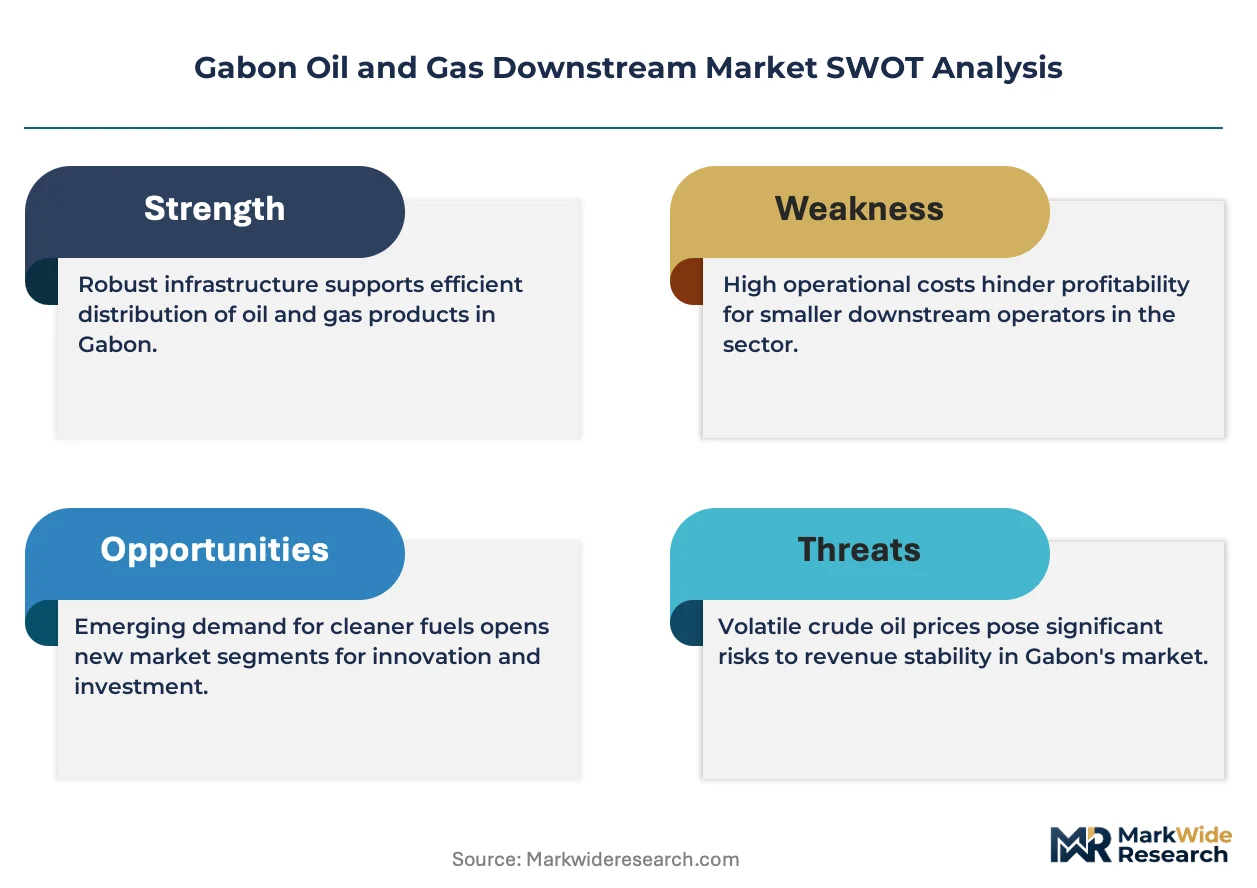
The Gabon Oil and Gas Downstream Market is being fundamentally restructured by the government's revised hydrocarbon code, which mandates tighter local content quotas across refining and distribution licensing. This regulatory tightening forces foreign operators to reconfigure capital deployment timelines and terminal ownership structures.
Growth Catalysts
- Haut-Ogooué Mining Expansion:Industrial diesel and heavy fuel oil consumption is accelerating as extraction operations scale across the interior province, pulling product flows inland from coastal terminals.
- LPG Substitution Mandates:Households and small industries are switching from wood and charcoal to liquefied petroleum gas, expanding the fastest-growing product category in the downstream portfolio.
- Pipeline Infrastructure Premium:Efficient bulk delivery systems from Port-Gentil refinery complexes to inland demand centers capture margin structures that road transport cannot match.
Market Restraints
- Foreign Exchange Constraints:The central bank's monitoring of currency availability for fuel import settlements creates settlement friction for distributors dependent on imported refined products.
- Single-Refinery Concentration:Downstream supply security depends on Port-Gentil refining capacity, exposing the market to operational disruption risks at one coastal complex.
- Euro 2-4 Sulfur Specifications:Diesel quality requirements lag European standards, limiting product interchangeability with regional trading partners and complicating supply diversification.
Strategic Opportunities
- Libreville Industrial Cluster Proximity:Co-located port infrastructure and manufacturing zones enable direct bulk supply arrangements that bypass traditional retail distribution layers.
- Remote Site Fuel Logistics:Specialized high-volume delivery to interior extraction locations represents an underserved segment where operational expertise creates defensive positioning.
- Local Content Partnership Structures:Joint venture configurations with Gabonese entities satisfy revised hydrocarbon code requirements while unlocking operating licenses for terminal expansion.
Industry Challenges
- Technical Skills Pipeline:Refining operations and pipeline maintenance require specialized engineering competencies that domestic training institutions have not scaled to meet.
- Environmental Compliance Timelines:The national hydrocarbon regulator's enforcement of emissions standards for storage terminals demands capital upgrades on compressed schedules.
- Legacy Storage Integration:Coastal tank farm modernization must accommodate existing marine loading infrastructure without disrupting continuous product availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gabon Oil and Gas Downstream Market |
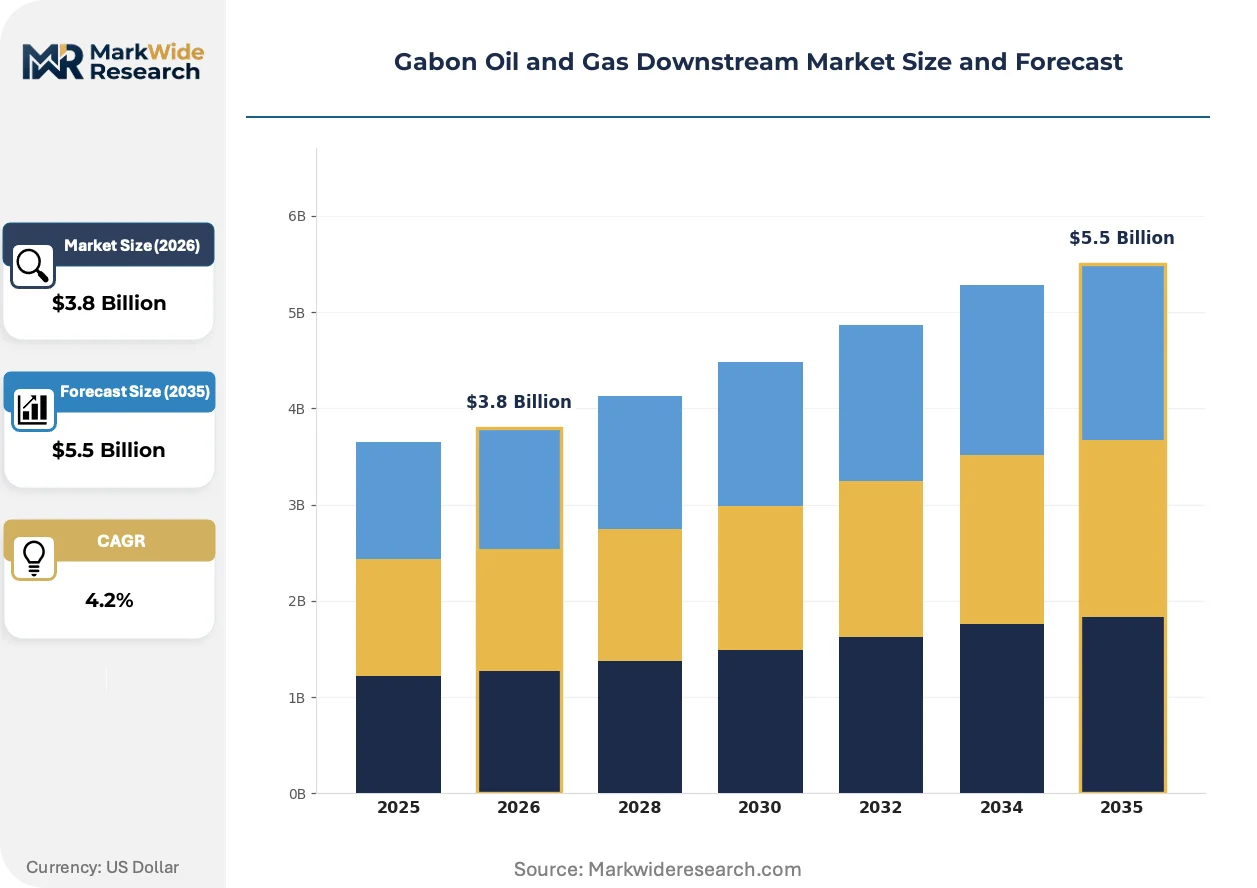
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Petroleum Products, Liquefied Petroleum Gas, Asphalt, Lubricants Application: Transportation Fuel, Power Generation, Industrial Fuel, Residential Heating Distribution Channel: Fuel Stations, Direct Bulk Supply, Pipeline Networks, Export Terminals End User Industry: Manufacturing Plants, Mining Operations, Maritime Shipping, Construction Companies |
| Companies Covered | Gabon Oil Company, TotalEnergies SE, Total SA, Maurel et Prom SA, VAALCO Energy Inc., Perenco SA, Eni SpA, BW Energy, Engen Petroleum Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gabon Oil and Gas Downstream Market Shifts & Advancements
Digital logistics platforms and regulatory transparency requirements are compressing traditional intermediation layers across Gabon's petroleum product distribution network. These forces are reshaping how volumes move from refinery gate to end-use consumption point.
Cloud-based inventory management systems are virtualizing terminal stock visibility for industrial buyers. Mining operators in Haut-Ogooué now monitor real-time fuel levels at remote storage sites, triggering automated replenishment orders before depletion. This capability is virtualizing the traditional bulk supply relationship, reducing safety stock requirements and compressing working capital cycles for both supplier and consumer.
Gabon's revised hydrocarbon code introduces mandatory local content reporting for downstream license holders. The framework requires documented Gabonese participation in refining, storage, and distribution activities, with enforcement delegated to the Ministry of Petroleum. Smaller distributors lacking partnership structures face license renewal friction, while integrated operators with established local joint ventures secure operational continuity.
Industrial procurement teams are consolidating fuel purchasing through direct refinery offtake agreements rather than layered distributor networks. Maritime and mining clients in Port-Gentil negotiate volume commitments with terminal operators, bypassing wholesale intermediaries. This concentration is most visible along the Atlantic coast, where integrated logistics footprints enable supplier-to-consumer contracting that eliminates margin stacking.
Gabon Oil and Gas Downstream Market Segmentation
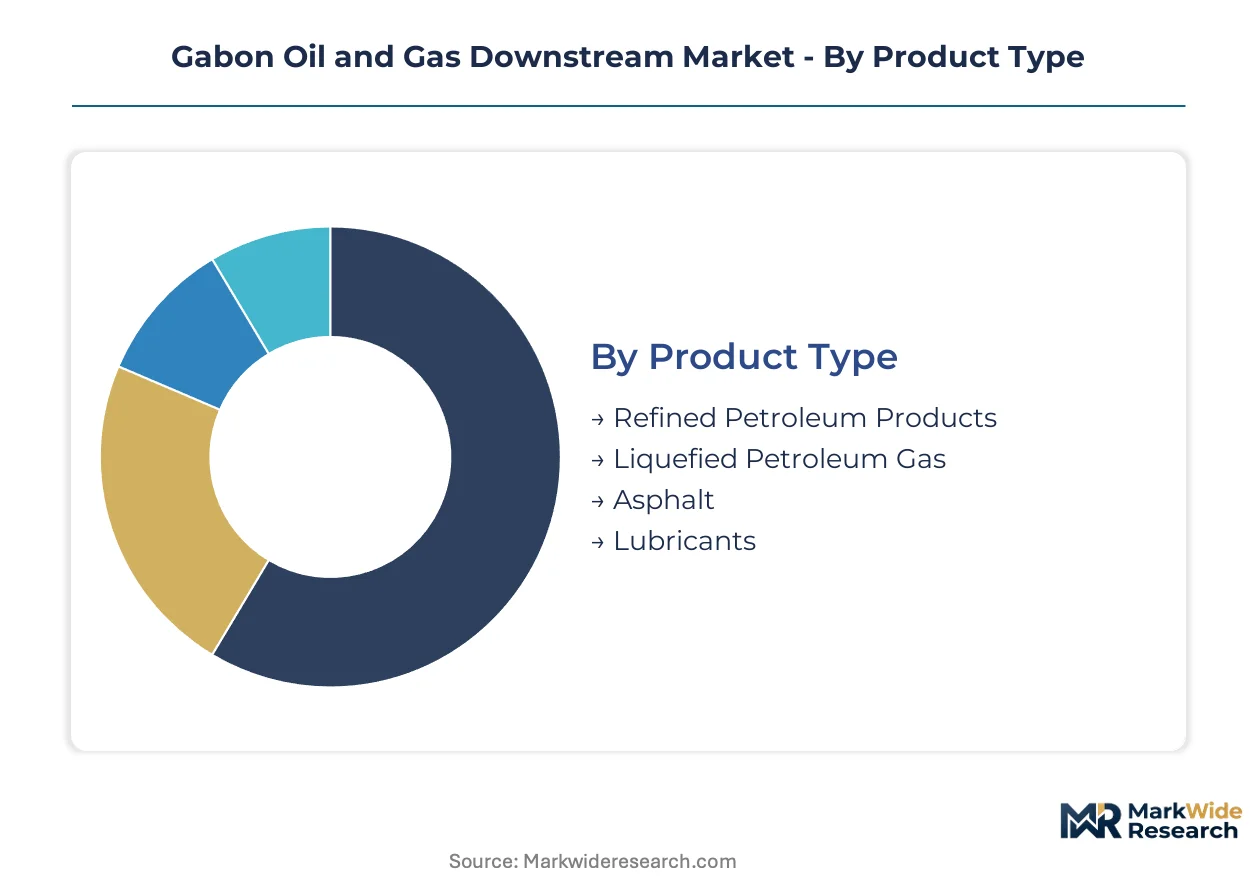
Downstream segmentation in Gabon tracks how petroleum derivatives flow from the Port-Gentil refinery complex to distinct consumption patterns across mining provinces, coastal industrial clusters, and urban household markets. Product specifications, delivery infrastructure, and end-use intensity vary sharply between interior extraction sites and Atlantic port facilities.
Product Type:
Cost tier stratification separates commodity fuels from specialty derivatives, with sulfur content and processing depth determining margin structures.
- Refined Petroleum Products:Gasoline blends with 91-95 octane ratings and diesel conforming to Euro 2-4 sulfur specifications dominate volume throughput. Transportation fuel demand concentrates in Libreville's vehicle fleet and Port-Gentil's maritime logistics hub, constrained by single-refinery supply security risks.
- Liquefied Petroleum Gas:Propane-butane mixtures packaged in cylinder distribution networks serve household cooking substitution from wood and charcoal. Residential clusters in Libreville and Franceville drive category expansion as the Ministry of Petroleum enforces clean fuel transition mandates.
- Asphalt:Residual bitumen fractions from vacuum distillation units supply road construction binders.
- Lubricants:High-viscosity base oils with additive packages protect mining equipment and marine engines in Haut-Ogooué and Port-Gentil.
Refined petroleum products command the established base. The steepest expansion runs through liquefied petroleum gas.
Application:
End-use intensity patterns map directly to Gabon's economic geography, with industrial combustion pulling volumes inland while coastal zones anchor transportation demand.
- Transportation Fuel:Diesel and gasoline power road freight corridors linking Port-Gentil to Libreville and interior mining provinces. Fleet operators in the Haut-Ogooué logistics chain account for concentrated consumption, challenged by foreign exchange availability for import settlements.
- Industrial Fuel:Heavy fuel oils and diesel feed stationary combustion equipment at manufacturing plants and ore processing facilities. Mining operations in Moanda and Mounana generate sustained demand for high-volume direct bulk supply arrangements.
- Power Generation:Diesel-fired reciprocating engines and HFO boilers supply grid stability and remote site electricity.
- Residential Heating:Kerosene and LPG serve limited household thermal applications in Libreville's urban perimeter.
Transportation fuel retains volume leadership. Industrial fuel captures the fastest margin expansion as mining scales.
Distribution Channel:
Supply concentration shapes competitive positioning, with pipeline infrastructure creating protected corridors and direct arrangements eliminating intermediary layers.
- Direct Bulk Supply:Refinery gate offtake contracts connect terminal operators to mining and maritime clients, bypassing wholesale distributors. TotalEnergies SE and Perenco SA leverage coastal storage control to serve Haut-Ogooué extraction sites and Port-Gentil vessel bunkering.
- Pipeline Networks:Dedicated product lines from Port-Gentil refinery complexes to inland demand centers capture efficiency premiums unavailable to road transport. The national hydrocarbon regulator licenses these corridors under revised local content quotas.
- Fuel Stations:Retail dispensing networks serve fragmented vehicle and small commercial demand in Libreville and secondary cities.
- Export Terminals:Marine loading facilities handle limited re-export volumes to regional Atlantic markets.
Pipeline networks defend the highest margin structure. Direct bulk supply is gaining share fastest as industrial procurement consolidates.
End User Industry:
Customer scale and location specificity determine logistics configuration, with remote interior sites requiring specialized delivery capabilities.
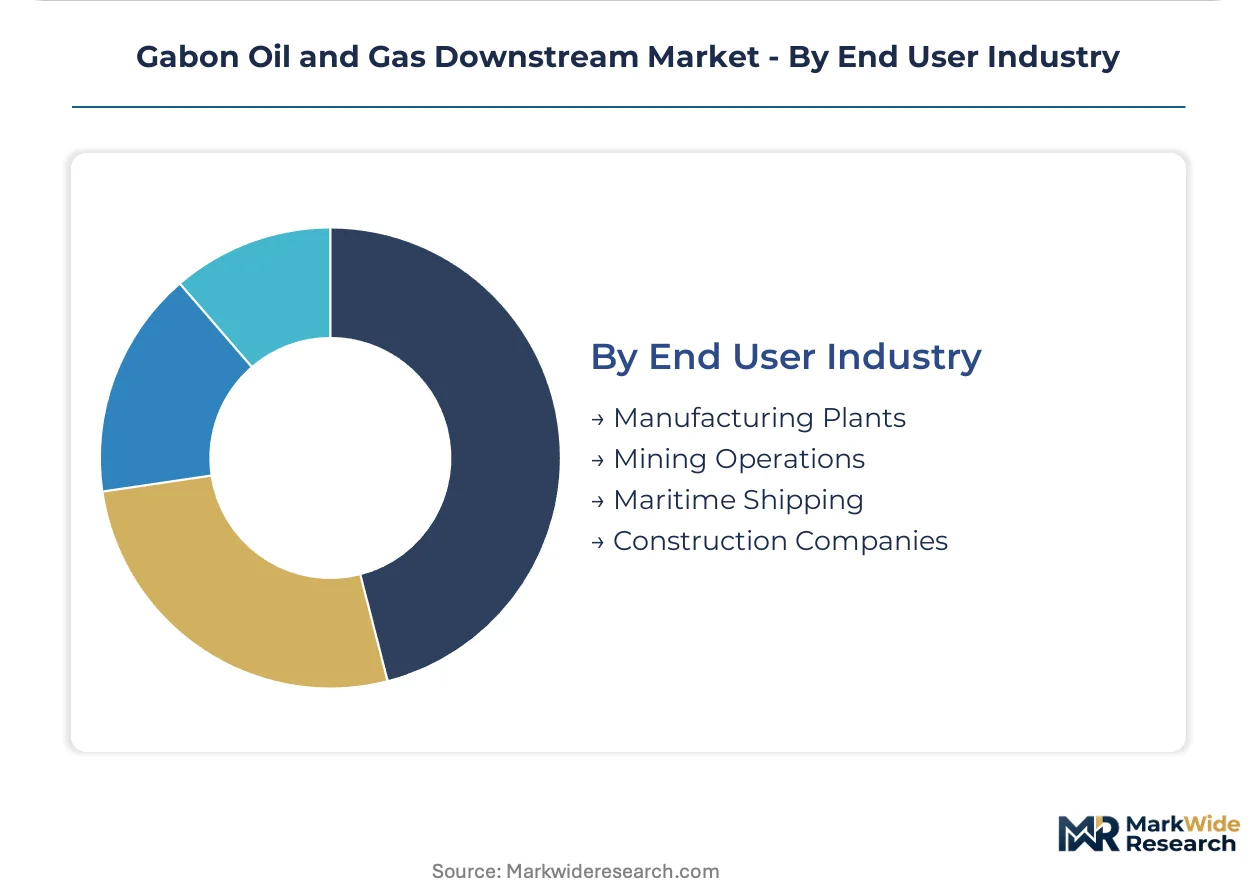
- Mining Operations:Open-pit extraction and ore processing in Haut-Ogooué province consume diesel for haul trucks and heavy fuel oil for thermal processing. VAALCO Energy Inc. competes through high-volume supply to remote sites where pipeline infrastructure terminates.
- Maritime Shipping:Coastal vessel bunkering and offshore support operations in Port-Gentil anchor residual fuel oil and marine diesel demand. Port infrastructure co-location enables direct terminal access without intermediate storage.
- Manufacturing Plants:Industrial clusters in Libreville's Owendo district purchase diesel and LPG for process heat and captive power.
- Construction Companies:Road building and urban development projects source asphalt and diesel through project-based procurement.
Mining operations anchor the volume base. Maritime shipping provides the most stable contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts sharply toward Port-Gentil and Libreville, where coastal infrastructure and industrial co-location create margin premiums unavailable in interior provinces dependent on road haulage.
Estuaire Province
Libreville's vehicle fleet and Owendo manufacturing district anchor gasoline and diesel consumption. The Ministry of Petroleum enforces local content quotas for distribution licensing. Industrial clusters in Owendo purchase direct bulk supply, bypassing retail layers.
Ogooué-Maritime Province
Port-Gentil's refinery complex and marine loading infrastructure concentrate national downstream capacity. The national hydrocarbon regulator licenses pipeline corridors under revised environmental standards. Vessel bunkering and offshore support operations generate residual fuel oil demand.
Haut-Ogooué Province
Moanda and Mounana extraction sites pull diesel and heavy fuel oil inland from coastal terminals. The central bank monitors foreign exchange availability for fuel import settlements. Mining haul trucks and ore processing facilities sustain high-volume direct supply arrangements.
Ngounié Province
Franceville residential clusters drive liquefied petroleum gas cylinder distribution for household cooking substitution. Clean fuel transition mandates from the Ministry of Petroleum accelerate category expansion. Urban perimeter demand concentrates in standardized packaging networks.
Ogooué-Lolo Province
Secondary road freight corridors link interior logistics chains to Atlantic port facilities. Euro 2-4 sulfur specifications limit product interchangeability with regional trading partners. Sparse population density constrains retail station economics.
Gabon Oil and Gas Downstream Market Competitive Landscape
Integrated majors and specialized independents split the market between coastal infrastructure control and remote site logistics. Three strategic archetypes dominate: terminal operators leveraging storage assets, pipeline network licensees capturing efficiency premiums, and remote supply specialists serving extraction sites beyond pipeline reach. Capacity expansion and local content joint ventures represent the dominant competitive moves as operators reconfigure ownership structures under revised hydrocarbon code requirements.
Among France-based integrated operators, TotalEnergies SE and Perenco SA anchor the coastal infrastructure tier through Port-Gentil terminal control and pipeline delivery systems. VAALCO Energy Inc. exemplifies the remote supply archetype, positioning around high-volume fuel logistics to interior extraction sites where pipeline infrastructure terminates. These three operators represent distinct strategic postures: integrated coastal dominance, storage-centric licensing advantage, and specialized inland penetration.
| Leading Market Players |
|---|
| Gabon Oil Company |
| TotalEnergies SE |
| Total SA |
| Maurel et Prom SA |
| VAALCO Energy Inc. |
| Perenco SA |
| Eni SpA |
| BW Energy |
| Engen Petroleum Ltd |
| Others |
Supply & Pricing Matrix
Port-Gentil's refinery complex concentrates national downstream capacity, translating coastal infrastructure control into pricing power for terminal operators serving Atlantic-facing industrial buyers. The Ministry of Petroleum's local content mandates reshape ownership economics, forcing joint venture structures that redistribute margin capture between foreign operators and Gabonese partners.
Pricing Analysis
Configured-to-order pricing for direct bulk supply to Haut-Ogooué mining operations commands substantial premiums over standard retail channel rates. Contract-based long-term offtake agreements dominate, with price differentiation driven by volume scale commitments and pipeline delivery access versus road haulage. Cost compression in retail gasoline is intensifying because single-refinery supply security limits product interchangeability. Fleet operators in Libreville exhibit highest price sensitivity, while maritime bunkering clients in Port-Gentil accept premium positioning for guaranteed terminal access.
Supply Chain Analysis
Export-control regimes on refining technology and catalyst systems limit equipment flows into Gabon's downstream sector, constraining capacity expansion timelines. Geographic supply concentration centers on France, Italy, and Belgium for specialized refining equipment and engineering services. Raw material dependencies include crude feedstock from domestic offshore fields, imported catalysts, and sulfur treatment chemicals. Single-source vulnerability runs through the sole Port-Gentil refinery complex. Distribution runs through pipeline corridors to inland demand centers, supplemented by coastal marine loading for re-export volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering competencies for refining operations and pipeline maintenance remain scarce within domestic training institutions, creating structural bottlenecks that constrain operational scaling and capital deployment timelines.
For Market Incumbents: Entrench coastal infrastructure control by accelerating terminal modernization timelines ahead of environmental compliance deadlines. Deepen backward integration into captive storage capacity at Port-Gentil to defend against emerging logistics competitors. Prioritize local content joint venture structures that satisfy revised hydrocarbon code requirements while locking in license renewal pathways. For New Entrants and Emerging Players: Establish a beachhead in remote site fuel logistics to Haut-Ogooué extraction locations beyond pipeline termination points. Target direct bulk supply arrangements with mid-tier mining operators underserved by integrated majors. Pursue digital logistics platform partnerships as the primary go-to-market angle, offering real-time inventory visibility that compresses working capital cycles. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because pipeline network licensing under tightened local content rules creates durable competitive moats. Focus acquisition screening on terminal operators with established Gabonese partnership structures and coastal storage assets. Watch enforcement consistency of foreign exchange availability for fuel import settlements as the critical inflection signal for distributor profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Joint Venture | Satisfies Ministry of Petroleum licensing requirements while unlocking terminal expansion permits. |
| Pipeline Infrastructure Investment | Captures efficiency premiums unavailable to road transport between Port-Gentil and inland demand centers. |
| Digital Logistics Platform Deployment | Enables real-time inventory monitoring for Haut-Ogooué mining clients, reducing safety stock requirements. |
| Remote Site Fuel Logistics Specialization | Defends positioning in interior extraction locations where pipeline infrastructure terminates. |
| Environmental Compliance Upgrade | Preempts enforcement action by the national hydrocarbon regulator on coastal storage terminal emissions standards. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs records, and project development databases. Interviews with refinery operations managers, mining procurement leads, terminal logistics coordinators, and Ministry of Petroleum officials provided operational ground-truth. Secondary validation drew from national hydrocarbon regulator licensing records, central bank foreign exchange monitoring reports, and infrastructure project disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Forecast inputs include crude production trajectories, mining sector capital expenditure cycles, and household fuel substitution elasticities. Segmentation dimensions encompass product type, application intensity, distribution channel configuration, and end-user industry scale. CAGRs were derived through exponential growth curve fitting against historical demand patterns and announced capacity additions. Industry-specific inputs incorporate Euro 2-4 sulfur specification compliance timelines and LPG cylinder distribution network buildout schedules.
Sensitivities concentrate around regulatory enforcement consistency, foreign exchange availability conditions, and single-refinery operational disruption scenarios. Forecasts reflect documented assumptions on mining expansion timelines and clean fuel transition mandate implementation pace. Material shifts in hydrocarbon code local content thresholds or central bank currency allocation priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Floating Production System Sales Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market