
 South America Pumped Hydro Storage Market | 2026-2036
South America Pumped Hydro Storage Market Size, Share, and Industry Trends Forecast 2026-2036
South America Pumped Hydro Storage Market Insights
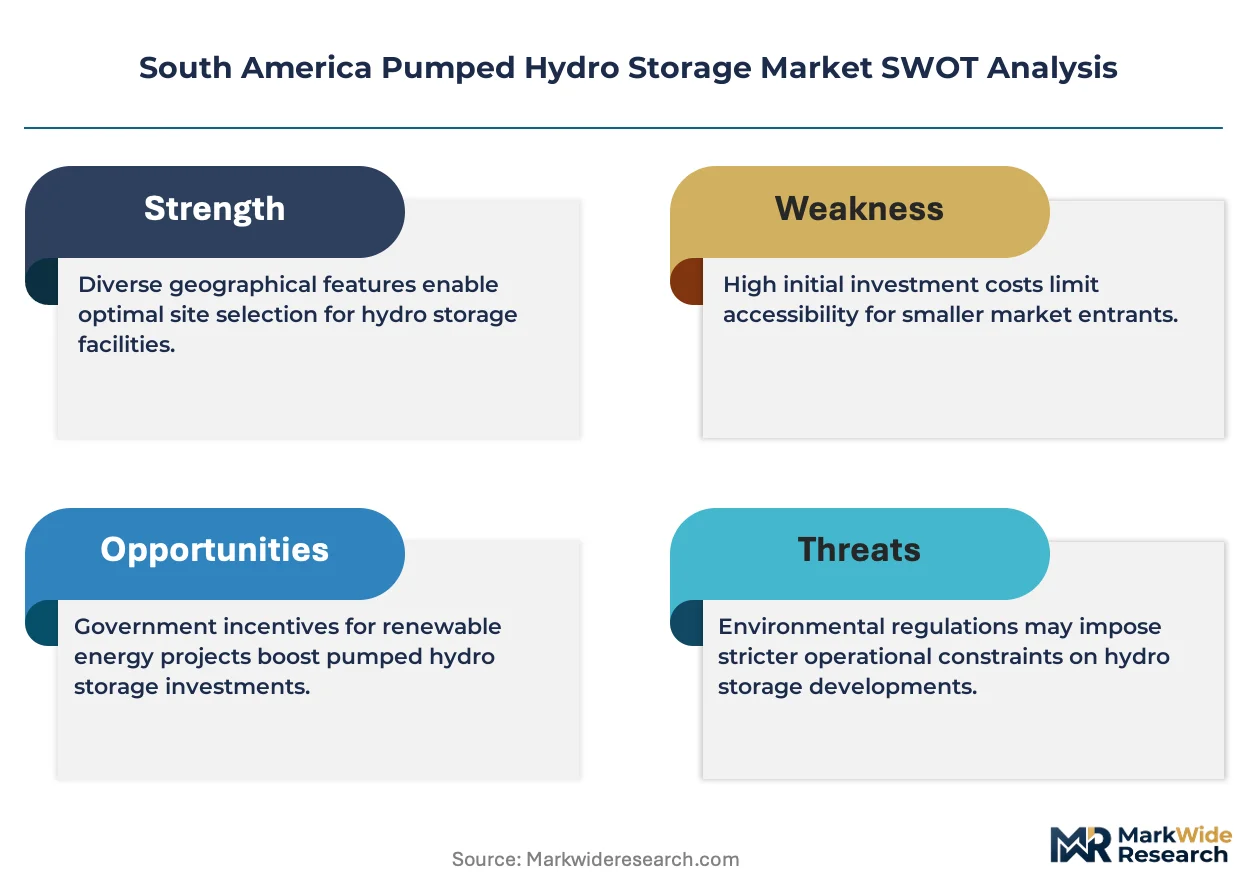
ISO 55000 asset management certification is reorganizing vendor qualification for pumped hydro projects across South America, raising barriers for equipment suppliers without documented lifecycle governance protocols. Voith GmbH & Co KGaA leverages its turbine-generator integration expertise to anchor premium positions in conventional installations. Andritz AG sustains competitive footing through hydraulic machinery specialization for variable-speed configurations. Siemens AG dominates electrical systems and grid synchronization technology, competing on digital control platforms that optimize round-trip efficiency.
Pumped hydro storage harnesses gravitational potential energy by pumping water from a lower reservoir to an upper reservoir during low-demand periods, then releasing it through reversible Francis or Pelton turbines to generate electricity when grid demand peaks; typical head heights range from 100 to 800 meters with cycle efficiencies of 70-85 percent. Conventional technology occupies the mature installed base but yields thinner margins as EPC contracts standardize. Variable speed installations represent the fastest-growing technology segment, commanding premium pricing through enhanced grid stabilization and partial-load operational flexibility. Electric utilities drive the dominant share of end-user demand, though independent power producers are gaining ground under Brazil's distributed generation regulatory framework.
ANEEL in Brazil and Colombia's UPME shape project economics through storage-specific tariff structures and connection code mandates that dictate equipment interoperability standards. Chile's Ministry of Energy enforces environmental impact thresholds for reservoir construction that filter developer eligibility and extend permitting timelines. Peru's OSINERGMIN regulates ancillary service remuneration, directly influencing whether pumped hydro competes against battery alternatives for frequency control contracts. Stakeholders must monitor how each national regulator recalibrates storage remuneration mechanisms as renewable penetration thresholds cross critical inflection points.
Market Dynamics
ANEEL's 2024 storage remuneration reforms are forcing Brazilian utilities to recalibrate capital allocation toward pumped hydro assets, compressing project development timelines and reshaping vendor qualification protocols across the Andean region.
Growth Catalysts
- ANEEL Regulatory Reforms:Brazil's grid-connected storage asset framework accelerates project approvals for independent power producers, unlocking capital flows into off-stream pumped hydro development.
- Variable-Speed Turbine Adoption:Enhanced grid stabilization capabilities from variable-speed configurations are displacing conventional fixed-speed installations in frequency control contracts.
- Colombia's Mountainous Topography:Steep elevation gradients and existing reservoir infrastructure in the Andean cordillera enable cost-effective closed-loop project economics without riverine dependency.
Market Restraints
- Extended Permitting Timelines:Chile's Ministry of Energy environmental impact thresholds for reservoir construction filter developer eligibility and delay commercial operation dates.
- Capital Intensity Concentration:Front-loaded civil engineering costs for tunneling and dam construction concentrate project finance requirements with multilateral development banks.
- Battery Storage Substitution:Lithium-ion systems compete for ancillary service contracts in Peru's OSINERGMIN-regulated frequency control markets with faster deployment cycles.
Strategic Opportunities
- Ecuador's Untapped Hydrology:Glacial-fed watersheds in the northern Andes offer exceptional head heights for greenfield pumped hydro development with minimal environmental conflict.
- ISO 55000 Certification Arbitrage:Asset lifecycle governance protocols create vendor qualification barriers that premium equipment suppliers can exploit for margin expansion.
- Hybrid Renewable Pairing:Co-location with Colombia's expanding wind corridor in La Guajira enables synthetic reservoir charging from surplus renewable generation.
Industry Challenges
- Geotechnical Engineering Scarcity:Specialized tunneling expertise for high-head underground powerhouses concentrates with aging European engineering consultancies, constraining project execution capacity.
- Grid Synchronization Complexity:Integration of variable-speed pump-turbines with legacy transmission infrastructure in Brazil's southeastern grid requires custom control system retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Pumped Hydro Storage Market |
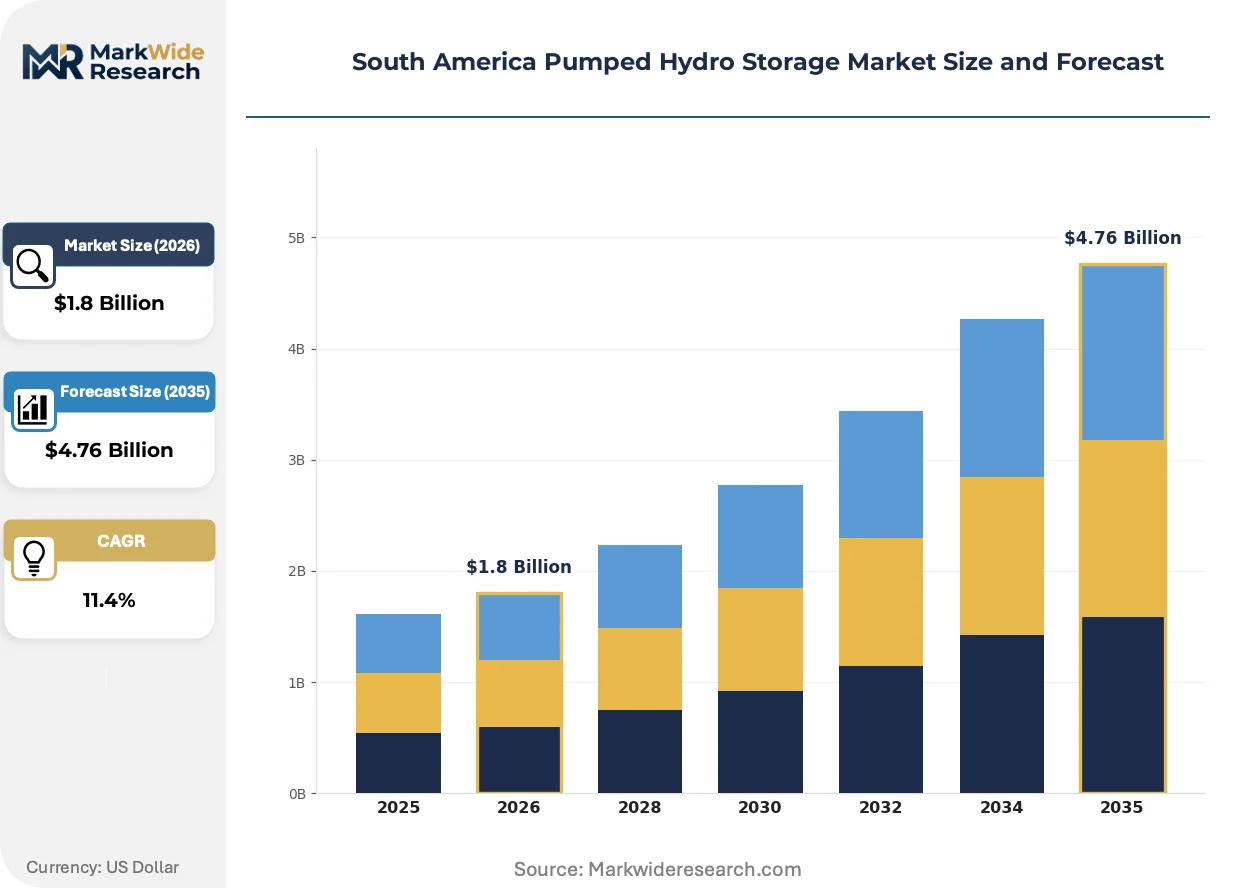
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Conventional, Variable Speed, Pumped Storage, Off-Stream End User: Electric Utilities, Independent Power Producers, Industrial Users, Government Entities Installation Type: New Build, Retrofit, Expansion, Upgradation Operation Mode: Base Load, Peak Load, Load Following, Ancillary Services |
| Companies Covered | Voith GmbH & Co KGaA, Andritz AG, Siemens AG, ContourGlobal PLC, Vale SA, Centrais Eletricas Brasileiras SA, Norte Energia SA, Iberdrola SA, Mitsubishi Heavy Industries Ltd, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Pumped Hydro Storage Market Trends and Innovations
Digital control platforms and modular civil engineering approaches are compressing development cycles and enabling smaller-scale pumped hydro configurations that previously failed economic viability thresholds.
Advanced ternary pump-turbine designs is miniaturizing the viable project scale for pumped hydro development. Colombian utilities are piloting sub-100 MW installations in remote Andean valleys. This technology is compressing the minimum economic threshold from 500 MW toward 50 MW, opening tributary watersheds previously excluded from consideration.
Colombia's UPME storage-specific tariff structures are mandating equipment interoperability standards that force turbine-generator suppliers toward standardized control interfaces. This regulatory pressure is consolidating vendor ecosystems around IEC 61850 communication protocols. Brazilian independent power producers are responding by pre-qualifying equipment packages that satisfy multi-jurisdictional connection codes.
Electric utilities are unbundling engineering-procurement-construction contracts into separable civil works and electromechanical packages. This procurement fragmentation is displacing integrated turnkey contractors with specialized consortia. The shift is most visible in Brazil's southeastern states, where ANEEL's distributed generation framework encourages IPP-led project structures.
South America Pumped Hydro Storage Market Segmentation
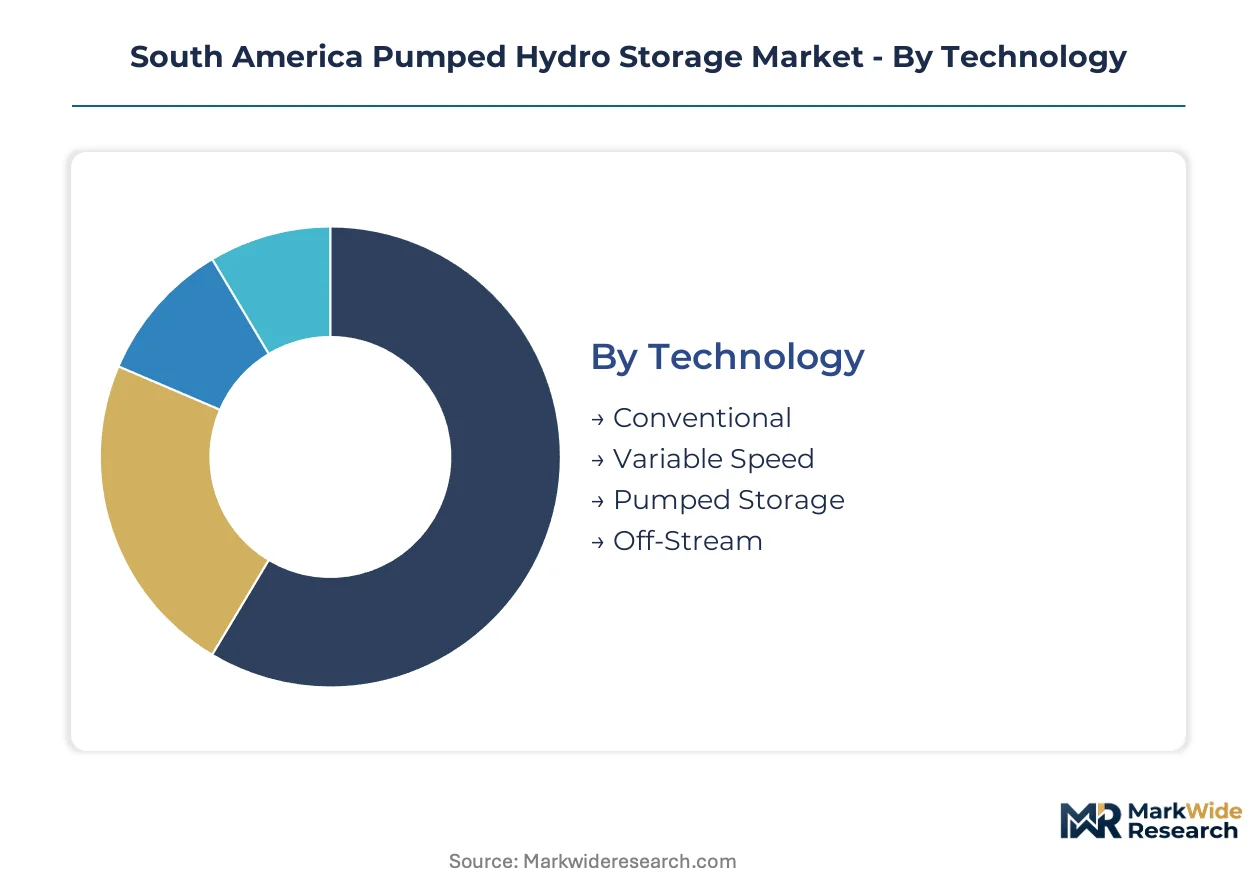
Pumped hydro storage deployment across South America fragments along technology maturity curves and regulatory-driven customer structures. Equipment vendors and EPC contractors calibrate product portfolios against these segment boundaries to capture margin concentration in variable-speed configurations and utility-scale installations.
Technology:
Premium margins pool in advanced electromechanical packages, while conventional installations commoditize around standardized EPC contracting.
- Variable Speed:These configurations deploy doubly-fed induction machines or full-converter architectures that enable partial-load pumping and rapid frequency response. Demand concentrates in Brazil's southeastern grid where ANEEL's ancillary service tariffs reward grid stabilization capabilities.
- Conventional:Fixed-speed pump-turbine pairs with synchronous generators dominate the installed base across Colombia's existing reservoir infrastructure. Brazilian utilities favor these for bulk energy arbitrage where rapid response is less critical than capital efficiency.
- Pumped Storage:Closed-loop systems without natural inflow dependency are gaining traction in Chile's water-scarce northern regions where environmental permits for new reservoirs face extended review.
- Off-Stream:Development configurations using existing lower reservoirs or artificial lower pools minimize riverine ecological impact. Colombia's UPME connection codes explicitly favor these designs in Andean watersheds.
Conventional technology holds installed capacity. Variable Speed is rotating up the share rankings.
End User:
Customer-type segmentation tracks regulatory authorization to own grid-connected storage assets across national jurisdictions.
- Electric Utilities:Vertically integrated state-owned and private utilities command the dominant procurement volume, particularly in Brazil where Eletrobras subsidiaries and regional distributors execute multi-gigawatt development pipelines. These customers specify IEC 61850-compliant control packages and demand 25-year service agreements.
- Independent Power Producers:Brazil's ANEEL distributed generation framework has unlocked IPP participation in storage asset ownership, with developers in Minas Gerais and São Paulo states pursuing off-stream projects under merchant or contracted revenue structures.
- Industrial Users:Mining conglomerates in Chile's Atacama and Peru's central Andes evaluate captive pumped hydro for reliability-isolated operations.
- Government Entities:National development banks and sovereign wealth vehicles in Ecuador and Bolivia direct strategic reserve capacity construction.
Electric Utilities anchor procurement volumes. Independent Power Producers are climbing the fastest as regulatory barriers fall.
Installation Type:
Project delivery mode determines civil works risk allocation and electromechanical procurement sequencing.
- New Build:Greenfield developments on virgin sites concentrate in Colombia's untapped Andean tributaries and Ecuador's glacial-fed watersheds. These projects carry front-loaded geological risk and extended permitting timelines.
- Retrofit:Electromechanical replacement at existing conventional plants enables capacity uprates and efficiency recovery. Brazilian utilities pursue these at aging installations in the Southeast to avoid greenfield environmental review.
- Expansion:Additional generating units at operational sites leverage existing reservoirs and transmission interconnections. Chilean developers favor this mode to circumvent Ministry of Energy reservoir construction thresholds.
- Upgradation:Control system modernization and turbine runner replacements extend asset life without civil works expansion. Peruvian utilities execute these under OSINERGMIN-mandated reliability programs.
New Build commands development attention. Retrofit is expanding most quickly as aging infrastructure requires renewal.
Operation Mode:
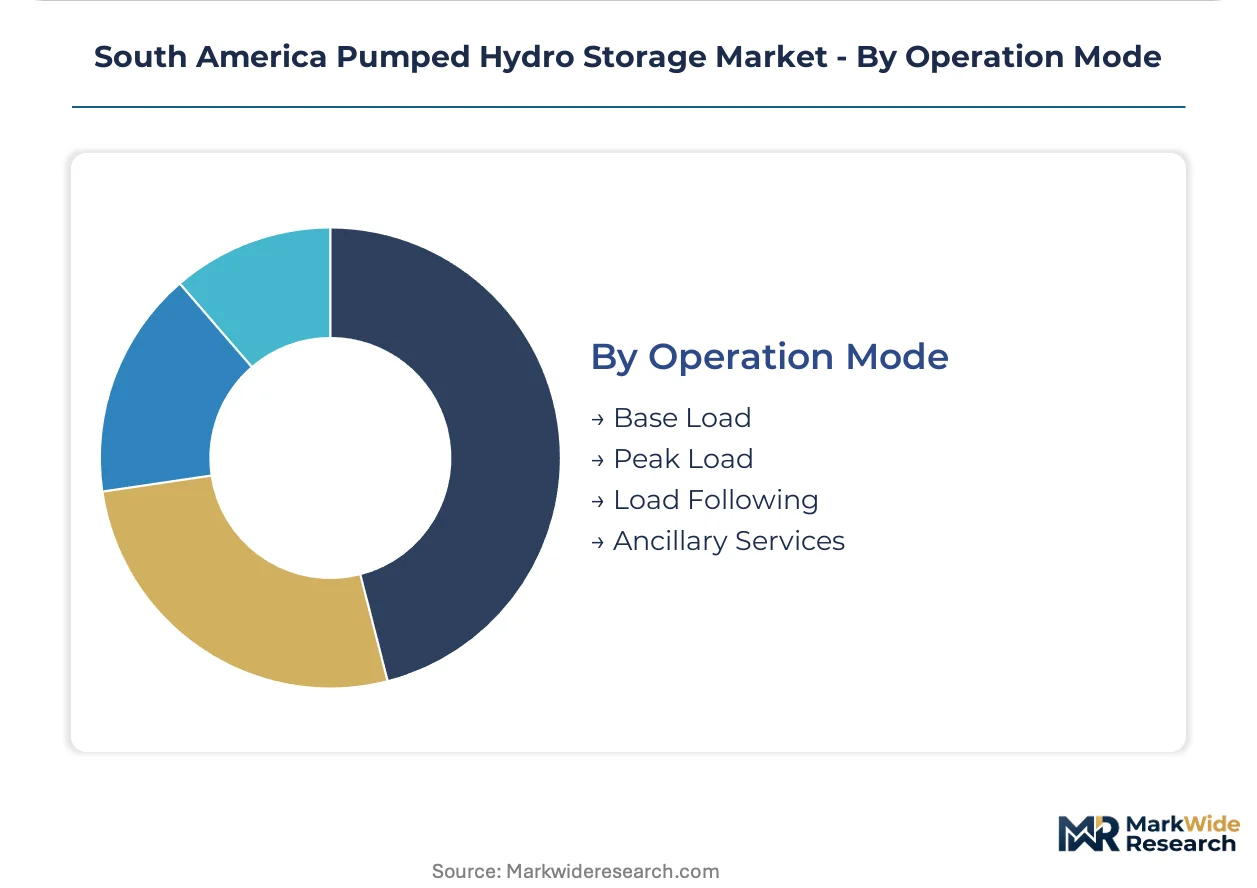
Revenue stack composition varies by grid service category, with ancillary services commanding premium pricing in frequency-constrained systems.
- Ancillary Services:Frequency regulation, spinning reserve, and voltage support contracts remunerate rapid-response capability. Peru's OSINERGMIN and Brazil's ANEEL have established specific tariff structures that favor variable-speed technology for these services.
- Peak Load:Daily arbitrage between off-peak pumping and peak generation underpins project economics at Colombia's existing reservoir infrastructure where UPME storage tariffs provide revenue certainty.
- Base Load:Bulk energy shifting across seasonal hydrological variation supports renewable portfolio integration in Brazil's hydro-dominated system.
- Load Following:Intermediate dispatch scheduling bridges between baseload and peaking operations, particularly relevant for hybrid wind-pumped hydro configurations in Colombia's La Guajira corridor.
Peak Load holds operational hours. Ancillary Services is gaining share fastest as renewable penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANEEL's 2024 storage remuneration reforms are accelerating capital deployment across the Andean region, compressing development timelines for off-stream projects while reshaping vendor qualification protocols throughout Brazil and Colombia.
Brazil
Minas Gerais and São Paulo states anchor development activity, with independent power producers pursuing merchant revenue structures under ANEEL's distributed generation framework. The southeastern grid's legacy transmission infrastructure demands custom control system retrofits for variable-speed integration. Eletrobras subsidiaries execute multi-gigawatt pipelines specifying IEC 61850-compliant packages and 25-year service agreements.
Colombia
UPME storage-specific tariff structures mandate equipment interoperability standards, consolidating vendor ecosystems around standardized control interfaces. The Andean cordillera's steep elevation gradients enable cost-effective closed-loop economics without riverine dependency. La Guajira's expanding wind corridor enables synthetic reservoir charging from surplus renewable generation.
Chile
The Ministry of Energy enforces environmental impact thresholds for reservoir construction that filter developer eligibility and extend permitting timelines. Water-scarce northern regions favor closed-loop systems without natural inflow dependency. Developers favor expansion modes at operational sites to circumvent reservoir construction thresholds.
Peru
OSINERGMIN regulates ancillary service remuneration, directly influencing whether pumped hydro competes against battery alternatives for frequency control contracts. Mining conglomerates in the central Andes evaluate captive installations for reliability-isolated operations. Utilities execute control system modernizations under OSINERGMIN-mandated reliability programs.
Ecuador
Glacial-fed watersheds in the northern Andes offer exceptional head heights for greenfield development with minimal environmental conflict. National development banks direct strategic reserve capacity construction. The untapped hydrology supports premium project economics relative to neighboring jurisdictions.
South America Pumped Hydro Storage Market Competitive Landscape
Player mix skews toward European electromechanical specialists and diversified industrial conglomerates with hydro heritage. Market structure concentrates around three strategic tiers: premium turbine-generator integrators, hydraulic machinery specialists, and electrical systems providers. Consolidation pressures favor specialists with documented ISO 55000 lifecycle governance protocols. Competitive moves center on procurement fragmentation into separable civil works and electromechanical packages, plus technology licensing for variable-speed configurations.
Among European electromechanical specialists, Voith GmbH & Co KGaA and Andritz AG occupy anchor positions representing integrated turbine-generator expertise and hydraulic machinery specialization respectively. Siemens AG exemplifies the electrical systems tier through grid synchronization and digital control platform capabilities. These three entities sit within the premium vendor tier where asset management certification requirements create qualification barriers for margin expansion.
| Leading Market Players |
|---|
| Voith GmbH & Co KGaA |
| Andritz AG |
| Siemens AG |
| ContourGlobal PLC |
| Vale SA |
| Centrais Eletricas Brasileiras SA |
| Norte Energia SA |
| Iberdrola SA |
| Mitsubishi Heavy Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at European turbine-generator foundries anchors cost structures across South America's pumped hydro value chain, concentrating electromechanical pricing power with Voith, Andritz, and Siemens while compressing margins for second-tier hydraulic machinery suppliers without ISO 55000 certification.
Pricing Analysis
Certification level creates the primary spread between premium electromechanical packages and commodity fixed-speed installations. Three-tier pricing structure across ISO 55000-certified premium, standard IEC-compliant, and uncertified economy levels stratifies vendor tiers. Cost compression in conventional fixed-speed configurations is intensifying because Brazilian utilities unbundle EPC contracts into separable civil and electromechanical packages. Independent power producers exhibit highest price sensitivity, while Eletrobras subsidiaries prioritize 25-year service agreements over upfront capital efficiency.
Supply Chain Analysis
Strategic stockpiling of specialized steel forgings and Francis turbine runners dominates inventory strategy, contrasting with just-in-time procurement for electrical control systems. Manufacturing concentrates in Germany, Austria, and Switzerland for precision turbine components, while Brazil and Colombia host localized civil works contractors. Supply chains draw from forged steel castings, high-voltage switchgear, and custom control system architectures. Single-source vulnerability sits with aging European tunneling engineering consultancies for high-head underground powerhouses. Distribution runs through EPC consortia and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America's pumped hydro market sits in early-cycle expansion, with ANEEL's 2024 storage remuneration reforms accelerating project approvals faster than equipment vendor qualification pipelines can absorb.
For Market Incumbents: Secure ISO 55000 lifecycle governance certification to maintain qualification barriers against emerging hydraulic machinery specialists from East Asia. Anchor capacity addition in Minas Gerais and São Paulo states where IPP-led merchant structures concentrate demand. Defend against battery storage substitution in Peru's frequency control markets by emphasizing 70-85 percent round-trip efficiency against lithium-ion degradation curves.
For New Entrants and Emerging Players: Differentiate on modular civil engineering approaches that compress development timelines for sub-100 MW installations in Colombia's remote Andean valleys. Target Ecuador's glacial-fed watersheds where exceptional head heights enable premium project economics with minimal environmental conflict. Pursue technology licensing partnerships with European turbine specialists rather than greenfield R&D investment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors variable-speed electromechanical specialists over conventional fixed-speed commoditized vendors. Five-to-ten year viability hinges on exposure to Brazil's southeastern grid modernization and Colombia's UPME-mandated interoperability standards. Watch ANEEL's recalibration of ancillary service tariffs as the critical inflection signal for frequency control contract allocation between pumped hydro and battery alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Technology Licensing | Andritz and Voith licensing agreements enable IPP access to premium grid stabilization capabilities under ANEEL's ancillary service tariffs. |
| ISO 55000 Certification Program | Asset lifecycle governance protocols create vendor qualification barriers that premium equipment suppliers exploit for margin expansion. |
| Hybrid Renewable Pairing Development | Co-location with La Guajira wind corridors enables synthetic reservoir charging from surplus Colombian renewable generation. |
| Modular Civil Engineering Expansion | Advanced ternary pump-turbine designs compress minimum economic thresholds toward 50 MW, opening previously excluded tributary watersheds. |
| Strategic Reserve Capacity Construction | Ecuador's national development banks direct sovereign capital toward glacial-fed northern Andes projects with exceptional head heights. |
Research Methodology
Desk research of regulatory filings from ANEEL, UPME, and OSINERGMIN preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Brazil, Colombia, and Chile. Secondary validation drew from project development databases, IEA hydropower reports, and equipment vendor technical specifications. Bottom-up installation pipeline analysis triangulated against top-down renewable integration targets across the Andean region.
Variance decomposition across technology type, end-user regulatory authorization, and installation mode shaped the analytical framework over the projection horizon. CAGRs derived from capacity-weighted average project economics and tariff structure evolution. Modeled inputs included ANEEL's distributed generation framework penetration, UPME storage-specific tariff adoption curves, and Chilean Ministry of Energy permitting timeline distributions.
Material uncertainties — regulatory recalibration of storage remuneration mechanisms, geotechnical execution delays, and battery storage cost trajectories — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding renewable penetration thresholds and multilateral development bank financing availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market