
 Netherlands Offshore Oil and Gas Decommissioning Market | 2026-2036
Netherlands Offshore Oil and Gas Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Offshore Oil and Gas Decommissioning Market Foresight
Market Context
The North Sea Transition Deal is recalibrating contractor procurement timelines across Dutch offshore waters. Allseas Group S.A. leverages its Pioneering Spirit single-lift vessel capacity to dominate heavy infrastructure removal campaigns. Royal Boskalis Westminster N.V. anchors coastal logistics through its integrated marine transport and disposal networks. Veolia Environnement SA specializes in hazardous waste streams from platform dismantling, extending its treatment footprint across Rotterdam industrial zones.
Technical Definition and Structural Segments
Netherlands offshore oil and gas decommissioning encompasses the engineered dismantling, removal, and environmental restoration of fixed and floating production installations, well plugging, and seabed clearance to original state or approved alternate-use conditions. The process requires explosive cutting, heavy-lift marine operations, and controlled onshore dismantling at licensed yards such as those clustered around Rotterdam and Vlissingen. Infrastructure removal leads service-type revenue pools due to the capital intensity of platform and pipeline extraction, while robotic systems within the technology segment represents the fastest-growing category as operators deploy remotely operated vehicles for seabed surveys and cutting operations to reduce diver exposure. Waste management maintains mature, stable margins through long-term hazardous material handling contracts tied to specific field liabilities.
Regulatory Framework and Outlook
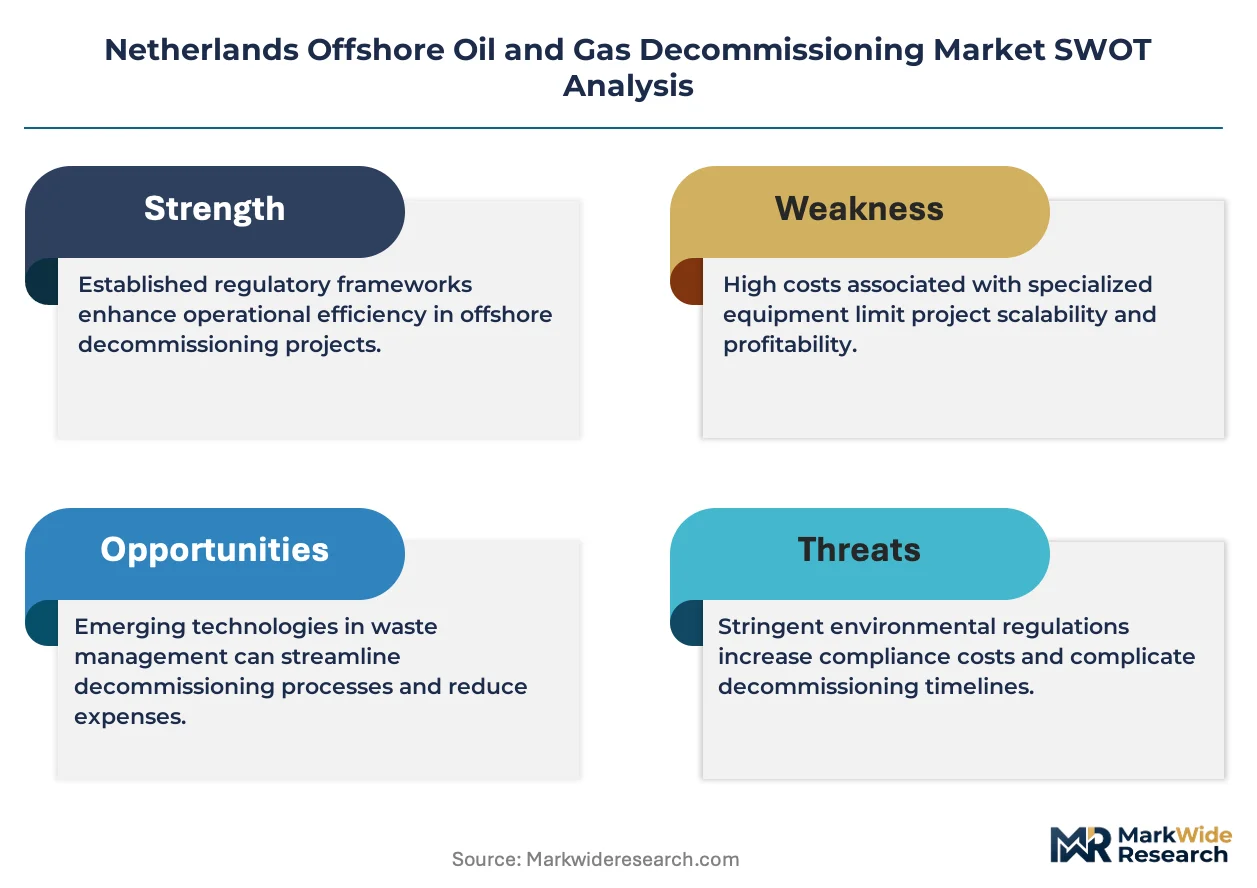
The Netherlands Enterprise Agency (RVO) enforces decommissioning security obligations under the Mining Act, while the State Supervision of Mines (SodM) inspects platform abandonment compliance against offshore safety directives aligned with EU environmental frameworks. The North Sea Agreement between Dutch authorities, operators, and contractors standardizes cost-sharing for shared infrastructure, directly shaping which fields proceed to full removal versus reefing programs. Stakeholders must monitor how evolving EU methane regulations and North Sea seabed restoration mandates reshape liability allocation between supermajors and late-life asset buyers.
Market Dynamics
The North Sea Transition Deal is compressing decommissioning timelines across Dutch offshore waters, forcing operators to accelerate platform retirement while single-lift vessel capacity concentrates among a handful of marine contractors capable of executing heavy removals.
Growth Catalysts
- EU methane regulations:The European Union's tightening methane emission standards are compelling operators to plug aging wellbores ahead of schedule, directly expanding decommissioning service demand across Dutch gas fields.
- Rotterdam-Vlissingen industrial cluster:Concentrated onshore dismantling capacity at licensed yards along the Southern North Sea corridor reduces logistics friction and accelerates project turnaround for infrastructure removal campaigns.
- Robotic seabed cutting systems:Remotely operated vehicles equipped with diamond wire saws are displacing diver-dependent cutting operations, compressing project timelines while improving safety metrics for platform jacket severance.
Market Restraints
- Heavy-lift vessel scarcity:The global fleet of single-lift vessels capable of handling integrated topsides remains concentrated among three operators, creating booking bottlenecks and rate volatility for large-scale removal contracts.
- Steel price volatility:Fluctuations in scrap steel markets directly impact the economics of platform recycling versus reefing decisions, complicating operator cost-recovery projections under the Mining Act security obligations.
- Seabed clearance technical limitations:Deep-buried pipeline sections and concrete mattress degradation present persistent challenges for complete site restoration, forcing residual liability retention under State Supervision of Mines protocols.
Strategic Opportunities
- Reefing program expansion:The North Sea Agreement's framework for alternate-use site designation creates regulatory pathways for jacket retention as artificial reefs, reducing removal costs while meeting biodiversity targets.
- Zeeland sub-region development:Underutilized yard capacity around Vlissingen offers expansion potential for specialized hazardous waste processing as Rotterdam facilities approach throughput limits.
- Electrification infrastructure reuse:Converting decommissioned platform jackets to offshore wind substation foundations represents a convergent opportunity between oil and gas retirement and renewable energy installation timelines.
Industry Challenges
- Explosive ordnance disposal certification:Severance operations requiring shaped charges demand specialized clearance protocols from SodM, extending permitting timelines and compressing seasonal weather windows for marine campaigns.
- Wellsite plugging skill scarcity:Experienced P&A engineers capable of executing permanent well abandonment in high-pressure gas reservoirs are concentrating among a shrinking cohort of contractors, inflating day rates and project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Offshore Oil and Gas Decommissioning Market |
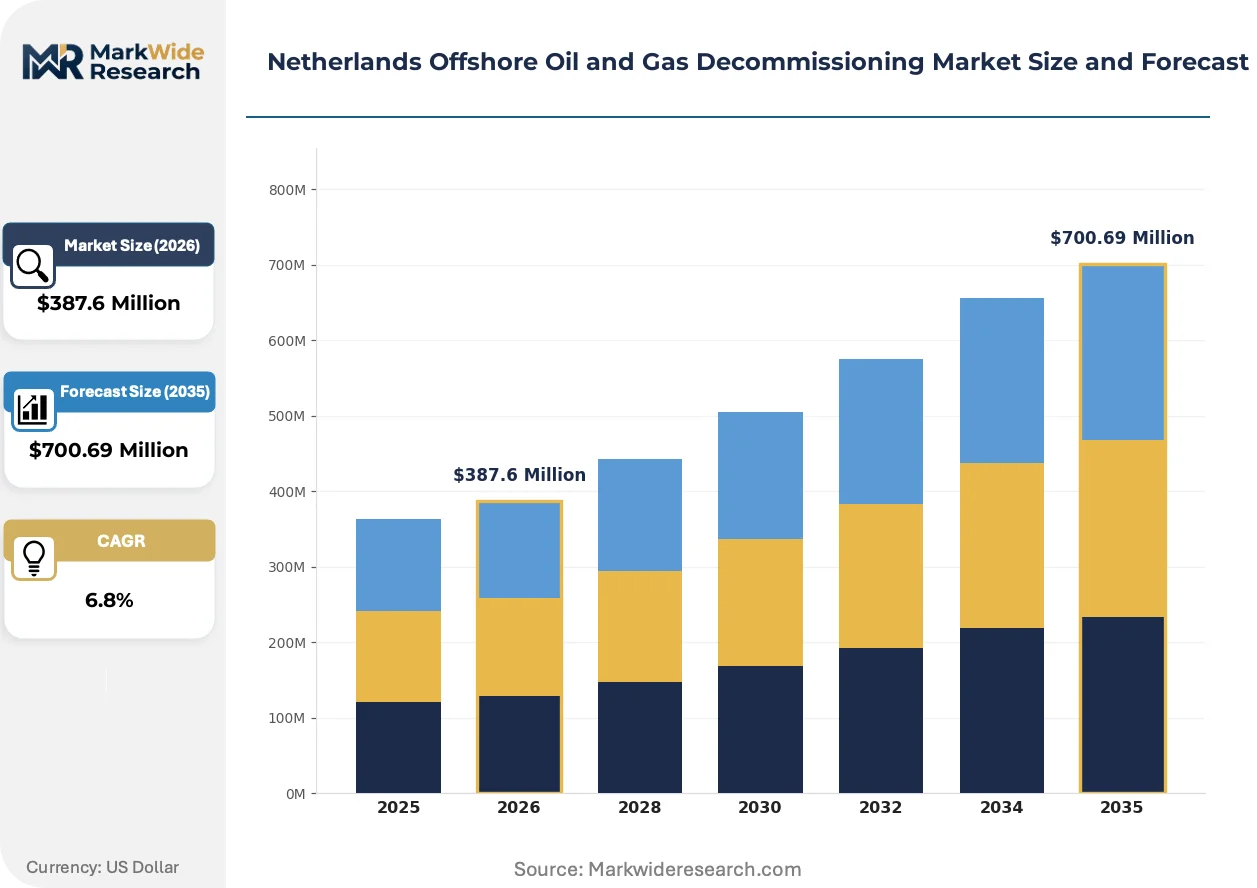
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Site Remediation, Waste Management, Infrastructure Removal, Environmental Assessment Technology: Robotic Systems, Remotely Operated Vehicles, Subsea Equipment, Decommissioning Software End User: Oil Companies, Government Agencies, Environmental Organizations, Contractors Deployment Model: Onshore Disposal, Offshore Operations, Hybrid Solutions, Integrated Services |
| Companies Covered | Veolia Environnement SA, Allseas Group S.A., Nexstep, Subsea 7 S.A., TechnipFMC, Royal Boskalis Westminster N.V., Saltwater Engineering B.V., Royal IHC, Neptune Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Offshore Oil and Gas Decommissioning Market Shifts & Advancements
Digital twin technology and autonomous marine systems are restructuring how Dutch operators plan and execute offshore dismantling, shifting competitive advantage toward contractors with integrated data-analytics capabilities.
Single-lift vessel technology is expanding into integrated topside removal campaigns that previously required multi-vessel campaigns lasting months. Dutch operators are now contracting Allseas Group S.A.'s Pioneering Spirit for complete platform removals that compress schedules from ninety days to under two weeks. This capability is expanding into adjacent markets including floating production unit decommissioning and offshore wind turbine installation.
The Netherlands Enterprise Agency is enforcing stricter decommissioning security calculations under revised Mining Act guidelines, requiring operators to front-load financial guarantees earlier in field life cycles. This policy shift is redirecting capital allocation among late-life asset buyers and supermajors divesting mature properties. Smaller independent operators are responding by accelerating field abandonment ahead of security obligation triggers.
Contracting models are migrating from unit-rate daywork to lump-sum turnkey structures as operators seek cost certainty for multi-year decommissioning programs. This behavioral shift is compressing margins for marine contractors while rewarding integrated service providers with in-house heavy-lift, waste processing, and regulatory compliance capabilities. The Southern North Sea corridor from Den Helder to Rotterdam exhibits the most pronounced shift toward fixed-price decommissioning agreements.
Netherlands Offshore Oil and Gas Decommissioning Market Segmentation
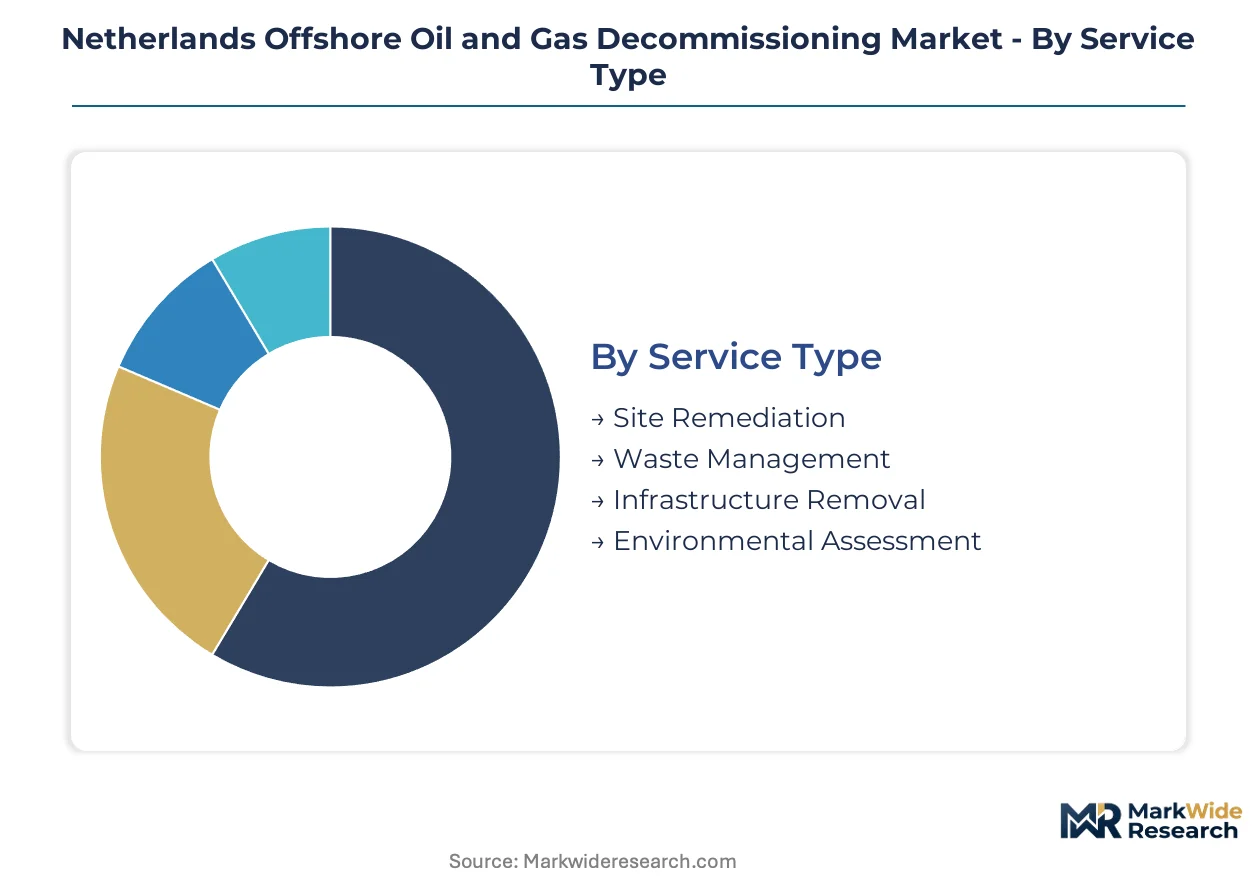
Decommissioning procurement in Dutch offshore waters fragments across service capabilities, technology platforms, and contracting structures. Each segment carries distinct regulatory security obligations under the Mining Act and divergent certification requirements from the State Supervision of Mines.
Service Type:
Infrastructure Removal demands SodM permits for explosive cutting and marine lift operations, while Waste Management requires hazardous substance handling licenses from Rotterdam port authorities.
- Infrastructure Removal:Heavy-lift marine operations encompassing platform topsides, jackets, and pipeline extraction using single-lift vessels and controlled demolition. Demand concentrates around the Rotterdam-Den Helder corridor where aging gas platform clusters require complete physical extraction under compressed North Sea Transition Deal timelines.
- Waste Management:Hazardous material processing including NORM-contaminated scale, mercury-laden sludge, and hydrocarbon-impacted debris at licensed treatment facilities. Operators in the Southern North Sea region are locking in long-term disposal contracts as Rotterdam yards approach throughput saturation.
- Site Remediation:Seabed restoration to original state or approved alternate-use conditions following infrastructure extraction.
- Environmental Assessment:Pre-abandonment surveys and post-removal verification against EU seabed restoration mandates.
Leading the category by volume: Infrastructure Removal. Expanding most quickly: Waste Management.
Technology:
Technology selection determines project duration, diver safety exposure, and compliance with evolving EU methane monitoring requirements.
- Robotic Systems:Diamond wire saws and autonomous cutting platforms eliminating diver-dependent severance operations. Deployment is accelerating across high-pressure Dutch gas fields where wellhead accessibility constraints favor machine precision over human intervention.
- Remotely Operated Vehicles:Tethered subsea systems conducting visual surveys, debris clearance, and pre-cut inspections. Dutch operators are standardizing ROV-integrated campaigns to compress seasonal weather windows and reduce vessel day rates.
- Subsea Equipment:Specialized lifting frames, dredging tools, and mattress removal systems for seabed clearance operations.
- Decommissioning Software:Digital twin platforms and project management systems for campaign planning and regulatory documentation.
Dominating current procurement: Robotic Systems. Gaining share fastest: Decommissioning Software.
End User:
End-user categories reflect divergent risk appetites for lump-sum contracting versus unit-rate daywork structures.
- Oil Companies:Supermajors and independents holding field equity and Mining Act security obligations. Shell and Neptune Energy are front-loading decommissioning budgets to preempt RVO guarantee calculations.
- Government Agencies:The Netherlands Enterprise Agency and State Supervision of Mines enforcing compliance and managing cost-sharing frameworks under the North Sea Agreement.
- Contractors:Integrated service providers bundling heavy-lift, waste processing, and regulatory compliance capabilities.
- Environmental Organizations:Stakeholders monitoring reefing program eligibility and biodiversity outcome verification.
Controlling capital allocation: Oil Companies. Expanding contractual influence: Government Agencies.
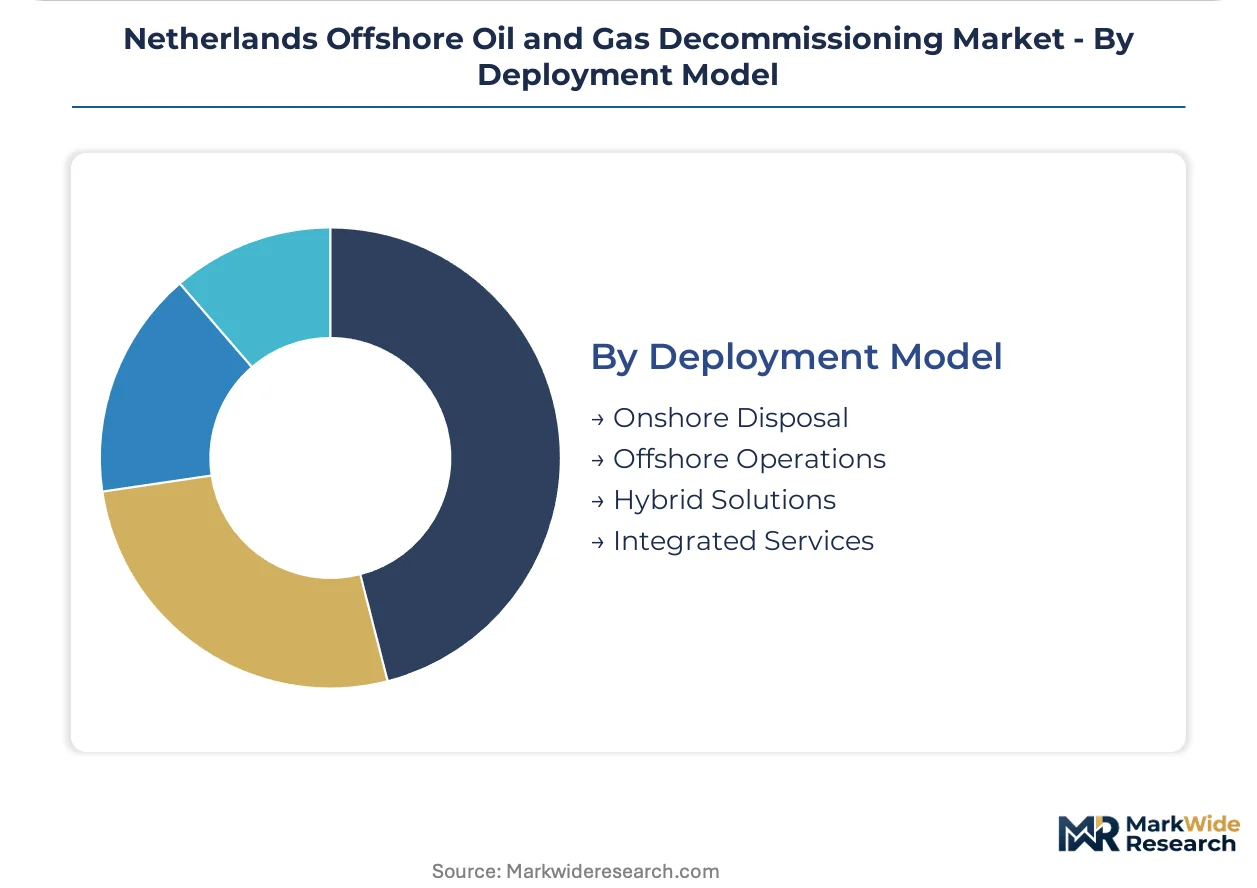
Deployment Model:
Deployment structure determines logistics friction and residual liability retention under Dutch offshore safety directives.
- Integrated Services:Turnkey contracts spanning offshore removal through onshore dismantling and waste certification. This model is capturing preference among late-life asset buyers seeking cost certainty against volatile steel scrap markets.
- Offshore Operations:Marine campaigns conducted at platform sites including well plugging, severance, and lift operations.
- Onshore Disposal:Yard-based dismantling, component segregation, and material recycling at Rotterdam and Vlissingen facilities.
- Hybrid Solutions:Mixed structures combining operator-managed well abandonment with contractor-executed infrastructure removal.
Capturing procurement momentum: Integrated Services. Facing margin compression: Hybrid Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Den Helder corridor concentrates Dutch decommissioning demand where aging gas infrastructure clusters meet licensed dismantling yards.
Southern North Sea Corridor
Platform retirement campaigns concentrate between Rotterdam and Den Helder where Neptune Energy and other operators hold mature gas field equity. The State Supervision of Mines enforces Mining Act abandonment timelines that compress project schedules. Allseas Group S.A. deploys single-lift vessels from Rotterdam port facilities to execute heavy topside removals.
Rotterdam Industrial Zone
Hazardous waste processing demand from NORM-contaminated scale and mercury-laden sludge concentrates at Veolia Environnement SA treatment facilities. The Netherlands Enterprise Agency requires front-loaded financial guarantees under revised security obligation guidelines. Licensed dismantling yards at Waalhaven and Botlek handle jacket severance and component segregation.
Vlissingen Sub-Region
Underutilized yard capacity in Zeeland offers expansion potential as Rotterdam facilities approach throughput saturation. The North Sea Agreement's cost-sharing frameworks influence whether operators route infrastructure to this secondary cluster. Royal IHC maintains fabrication and marine equipment capabilities at this southwestern location.
Den Helder Marine Base
Offshore logistics and vessel mobilization operations support northern field campaigns from this historic naval and energy services hub. Subsea 7 S.A. and TechnipFMC maintain operational presence for pipeline decommissioning and well intervention. The concentration of diving and ROV contractors here reduces mobilization costs for seabed clearance operations.
Amsterdam Capital Region
Corporate headquarters and regulatory compliance functions concentrate where operators interface with the Netherlands Enterprise Agency on security obligation calculations. Nexstep coordinates joint industry decommissioning programs from this administrative center. Saltwater Engineering B.V. provides specialized structural engineering services to campaigns across all sub-regions.
Netherlands Offshore Oil and Gas Decommissioning Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integrated service bundling and heavy-lift vessel access. The market exhibits concentrated capability among single-lift vessel operators and fragmented competition in waste processing and engineering services. Two strategic archetypes dominate: integrated marine contractors controlling rare heavy-lift assets, and specialized environmental service providers with hazardous material licenses. Competitive moves center on turnkey contract structures and vertical integration into waste certification.
Within the integrated marine contractor tier, Allseas Group S.A. and Royal Boskalis Westminster N.V. exemplify scale-driven positioning through single-lift vessel deployment and coastal logistics networks. Veolia Environnement SA anchors the environmental services archetype with hazardous waste treatment infrastructure. These three entities represent the capability concentration that shapes contracting dynamics across Dutch offshore waters.
| Leading Market Players |
|---|
| Veolia Environnement SA |
| Allseas Group S.A. |
| Nexstep |
| Subsea 7 S.A. |
| TechnipFMC |
| Royal Boskalis Westminster N.V. |
| Saltwater Engineering B.V. |
| Royal IHC |
| Neptune Energy |
| Others |
Supply & Pricing Matrix
Turnkey contracting preferences among late-life asset buyers are compressing margins for marine contractors while rewarding integrated service providers with in-house heavy-lift and waste certification capabilities across Dutch offshore waters. This procurement shift forces supply-side consolidation around rare single-lift vessel operators and licensed Rotterdam-Vlissingen dismantling yards.
Pricing Analysis
Outcome-based pricing tied to platform removal throughput anchors contractor compensation structures in this market. Three-tier pricing stratifies across integrated turnkey, hybrid operator-managed, and unit-rate daywork levels. Price differentiation hinges on heavy-lift vessel access and hazardous waste certification grade. Cost compression in standard-tier services is intensifying because lump-sum contracts transfer weather-delay risk to contractors. Independent operators exhibit highest price sensitivity; supermajors front-loading security obligations show lowest.
Supply Chain Analysis
Dutch domestic-content requirements under the North Sea Agreement reshape sourcing toward Rotterdam-Den Helder corridor facilities. Heavy-lift vessel capacity concentrates in the Netherlands, Norway, and Belgium; specialized cutting equipment and ROV systems draw from the United Kingdom, the United States, and France. Supply chain risk centers on single-source vulnerability for single-lift vessel bookings. Distribution runs through integrated marine contractors controlling offshore removal through onshore dismantling workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as lump-sum turnkey obligations force smaller contractors without integrated waste processing or heavy-lift assets toward exit or acquisition.
For Market Incumbents: Acquire underutilized yard capacity in the Zeeland sub-region to capture overflow demand as Rotterdam facilities saturate. Secure captive supply of diamond wire saw ROV systems to reduce subcontractor exposure. Defensive positioning requires locking multi-year waste processing contracts with Neptune Energy and other operators holding compressed North Sea Transition Deal timelines. For New Entrants and Emerging Players: Enter via specialized explosive ordnance disposal certification services where SodM permitting creates artificial scarcity and extends seasonal campaign windows. Target the Vlissingen sub-region for hazardous waste processing expansion as Rotterdam throughput limits bite. Go-to-market leverage rests on partnerships with established marine contractors lacking in-house environmental certification capabilities. For Investors and Strategic Acquirers: The window for entry favors integrated service providers with bundled heavy-lift, waste processing, and regulatory compliance capabilities over pure-play engineering consultancies. Long-term viability across the 5-10 year decommissioning wave hinges on access to single-lift vessel slots and licensed treatment infrastructure. Monitor Allseas Group S.A. vessel deployment schedules as the inflection signal for contractor rate volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Bundling | Captures preference from late-life asset buyers seeking cost certainty against volatile steel scrap markets. |
| Zeeland Yard Capacity Expansion | Positions operators to handle NORM-contaminated scale overflow as Rotterdam facilities approach throughput limits. |
| Robotic Cutting System Acquisition | Eliminates diver-dependent severance operations in high-pressure Dutch gas fields where wellhead accessibility constrains human intervention. |
| Reefing Program Certification | Unlocks alternate-use site designation under North Sea Agreement frameworks, reducing removal costs while meeting biodiversity targets. |
| Electrification Infrastructure Reuse | Converts decommissioned platform jackets to offshore wind substation foundations, bridging oil retirement and renewable installation timelines. |
Research Methodology
Independent corroboration across decommissioning project directors, SodM regulatory inspectors, and Rotterdam port authority licensing officers underwrites the qualitative findings. Primary interviews with heavy-lift vessel operators, waste treatment facility managers, and late-life asset acquisition executives combined with secondary validation from Netherlands Enterprise Agency security obligation filings, State Supervision of Mines abandonment compliance records, and EU methane regulation directives. Bottom-up project pipeline enumeration and top-down market sizing triangulate volume estimates.
Historical reference periods spanning completed platform removals, well plugging campaigns, and yard throughput rates anchored the forecast window construction. The analytical framework models service type, technology platform, and deployment model segmentation dimensions alongside field-specific liability allocation structures. CAGRs derive from regression analysis against North Sea Transition Deal timeline acceleration scenarios. Forecast inputs incorporate single-lift vessel fleet utilization curves and Rotterdam-Vlissingen yard capacity expansion trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended SodM permitting delays or accelerated EU seabed restoration mandate enforcement. The analytical envelope reflects assumptions regarding steel scrap market stability and contractor consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Global Mobile Offshore Drilling Units Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Subsea Production and Processing System Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
South America Offshore Energy Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market