
 Denmark Oil and Gas Market | 2026-2036
Denmark Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Oil and Gas Market Outlook
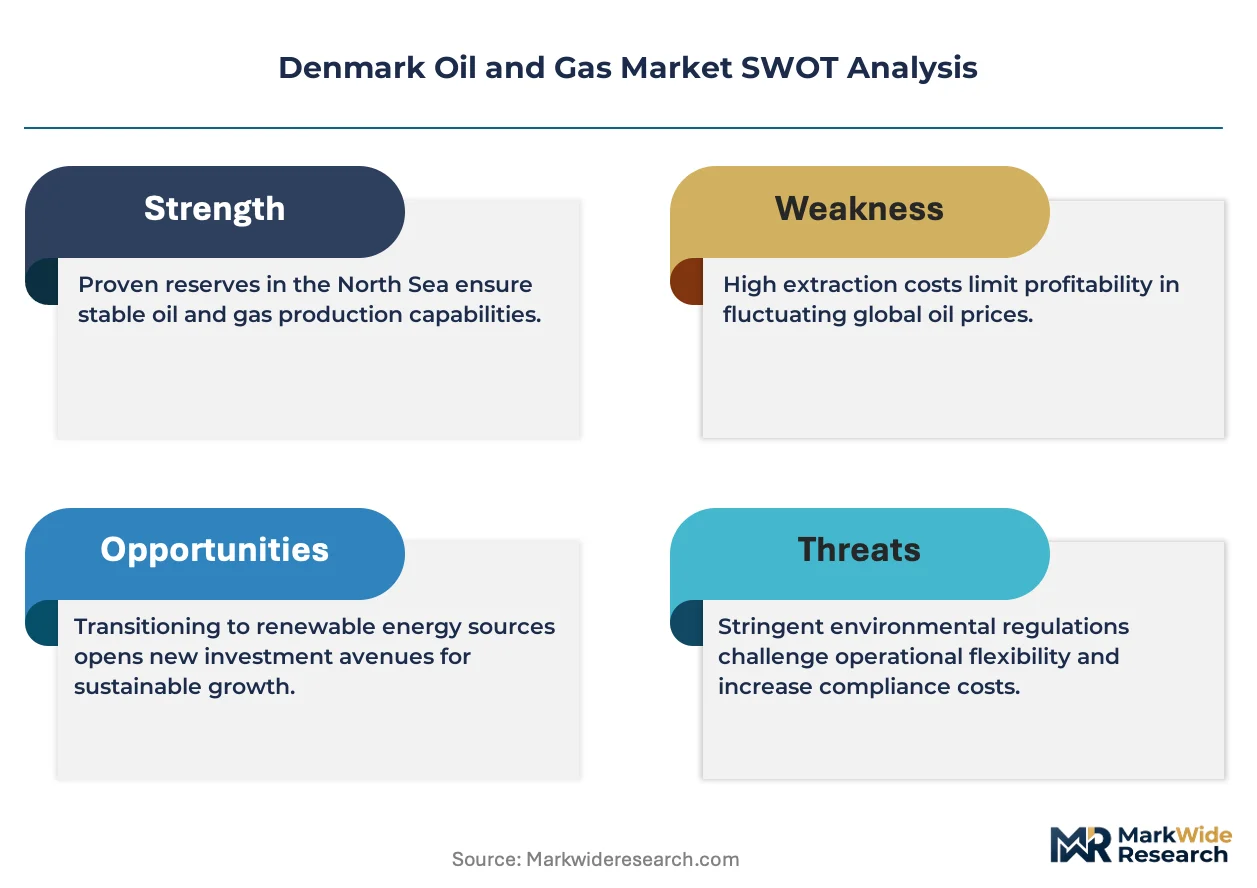
The Danish Climate Act is realigning capital allocation across Denmark's offshore basin, compelling operators to retrofit extraction assets for carbon capture readiness. Equinor ASA anchors North Sea production through its Sverdrup field interests, leveraging subsea tieback expertise to sustain output from mature reservoirs. TotalEnergies SE competes through integrated energy positioning, while Ørsted differentiates via offshore wind-to-hydrogen pilot projects that share port infrastructure with legacy oil and gas operations.
Denmark oil and gas encompasses hydrocarbon exploration, production, refining, and distribution activities conducted within Danish territorial waters and the onshore Jutland peninsula, primarily involving natural gas with associated condensate and light crude. The sector serves baseload power generation, industrial process heat, and petrochemical feedstock supply for northern European manufacturing clusters. Exploration and production services dominate value capture given the maturity of the Danish Underground Consortium's legacy fields, while enhanced oil recovery technology represents the fastest-growing segment as operators deploy polymer flooding and CO2 injection to extend field life. Distribution services occupy stable margin pools through Energinet's regulated gas transmission monopoly connecting offshore platforms to German and Swedish interconnectors.
The Danish Energy Agency enforces field abandonment bonds and decommissioning timelines under the Subsoil Act, while EU F-Gas Regulation and REACH constrain offshore chemical discharge and equipment refrigerant choices. The Danish Climate Act mandates sectoral emissions ceilings that force operators to integrate carbon capture or face production curtailments. Stakeholders must monitor whether the Danish Underground Consortium reopens licensing rounds for carbon storage acreage before existing North Sea infrastructure reaches technical retirement.
Market Dynamics
The Danish Climate Act is compressing operational timelines for North Sea operators, forcing simultaneous investment in carbon capture retrofitting and field decommissioning while gas demand from Copenhagen's industrial corridor persists.
Growth Catalysts
- Carbon capture mandates:The Danish Climate Act imposes sectoral emissions ceilings that compel operators to integrate capture technology with existing offshore infrastructure, preserving production licenses.
- Enhanced oil recovery deployment:Polymer flooding and CO2 injection techniques are extending productive life of mature reservoirs in the Danish Underground Consortium's legacy fields.
- District heating interconnection:Greater Copenhagen's gas-fired cogeneration plants anchor baseload demand through Energinet's regulated transmission network connecting to Swedish and German interconnectors.
Market Restraints
- Decommissioning liability concentration:The Subsoil Act imposes field abandonment bonds with strict timelines, concentrating capital drain on operators with aging platform infrastructure.
- Natural gas substitution pressure:Biomethane injection and electrification of industrial process heat threaten long-term offtake from Jutland's manufacturing clusters.
- REACH chemical discharge constraints:Offshore production chemistry choices face narrowing approval pathways, increasing operational compliance costs for platform maintenance.
Strategic Opportunities
- Carbon storage acreage licensing:The Danish Underground Consortium may reopen licensing rounds for CO2 storage before existing pipeline infrastructure reaches technical retirement, creating new revenue streams.
- Offshore wind-to-hydrogen convergence:Port infrastructure sharing between legacy oil and gas operations and emerging hydrogen pilots enables asset repurposing without greenfield development.
- Enhanced recovery service expansion:Subsea tieback expertise developed for mature reservoirs transfers to carbon capture integration projects requiring similar technical capabilities.
Industry Challenges
- Cross-disciplinary skill scarcity:Simultaneous demand for petroleum engineering and carbon capture system design creates recruitment bottlenecks for integrated project teams.
- Legacy platform integration complexity:Retrofitting 1970s-era offshore structures for carbon capture readiness requires structural reinforcement beyond original design specifications.
- Dual compliance timeline compression:Operators must satisfy both Subsoil Act decommissioning schedules and Danish Climate Act emissions ceilings with overlapping capital allocation demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Oil and Gas Market |
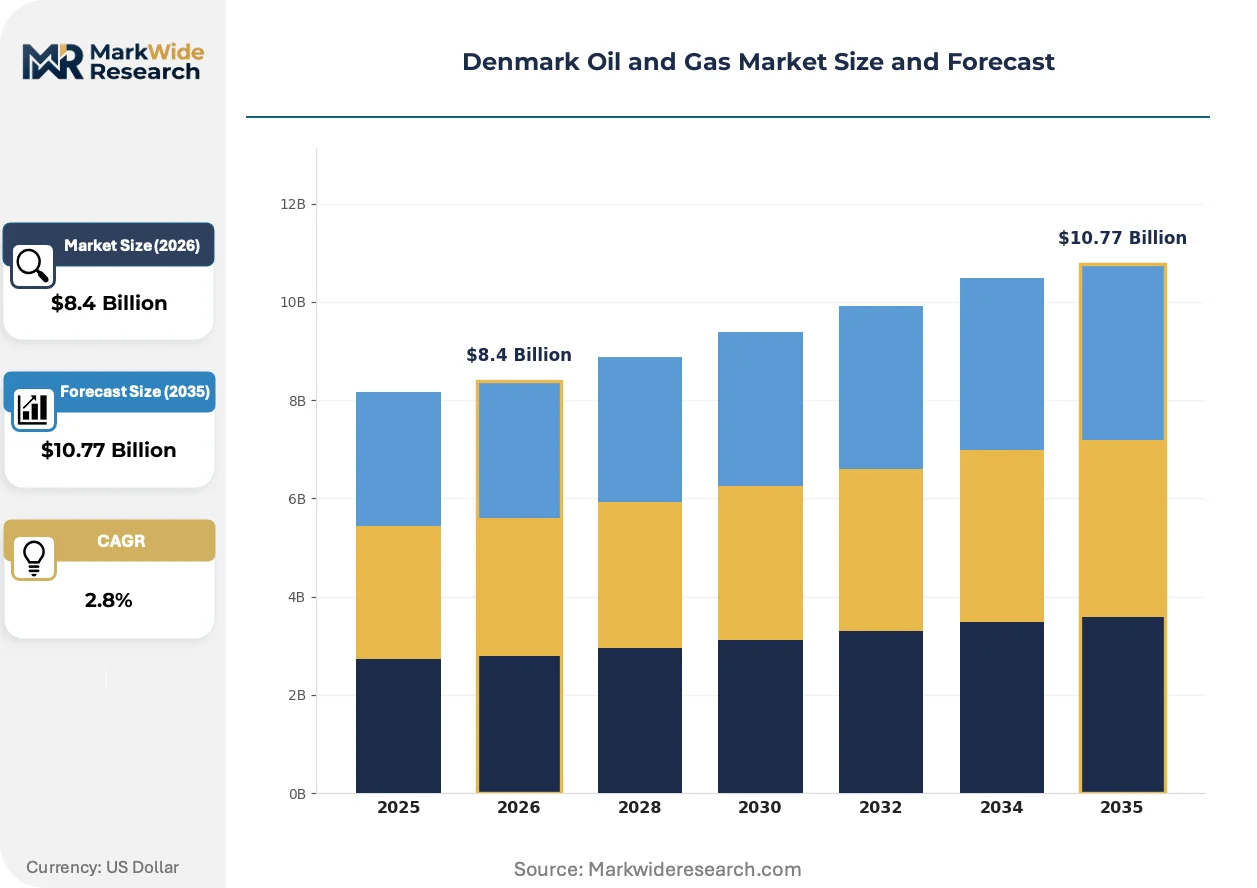
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Refining, Distribution Technology: Seismic Imaging, Drilling Technologies, Subsea Systems, Enhanced Oil Recovery End User: Utilities, Industrial Manufacturers, Oil Traders, Marine Operators Application: Power Generation, Heating, Transportation, Petrochemicals |
| Companies Covered | Equinor ASA, TotalEnergies SE, Shell PLC, Maersk Oil, Ørsted, Energinet, Danske Commodities, Norwegian Energy Company ASA, Energinet DK Gaslager A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Oil and Gas Market Strategic Shifts
Digital twin technology and subsea electrification are compressing operational expenditure structures while regulatory carbon accounting forces transparency through the production chain.
Subsea processing modules are overtaking topside facility expansion as the preferred approach for mature field development. Maersk Oil's former operators and current North Sea independents deploy these systems to eliminate platform deck space constraints. This technology is overtaking conventional tieback architectures by reducing offshore personnel exposure and enabling remote reservoir management from onshore control centers.
The EU F-Gas Regulation constrains refrigerant selection for offshore cooling and gas processing equipment, forcing equipment replacement cycles ahead of technical obsolescence. Danish platform operators face compressed retrofit schedules to maintain production licenses. The regulation most affects gas compression and treatment facilities where synthetic refrigerants previously dominated, driving adoption of ammonia-based alternatives with modified safety protocols.
Industrial buyers in the Greater Copenhagen corridor now contract for firm thermal delivery rather than commodity gas volumes, transferring price risk to suppliers while securing process heat reliability. This unbundling of molecule from service compresses supplier margins and favors integrated operators with captive storage and flexible generation assets. The pattern is most visible among pharmaceutical and food processing facilities with continuous thermal demand profiles.
Denmark Oil and Gas Market Segmentation
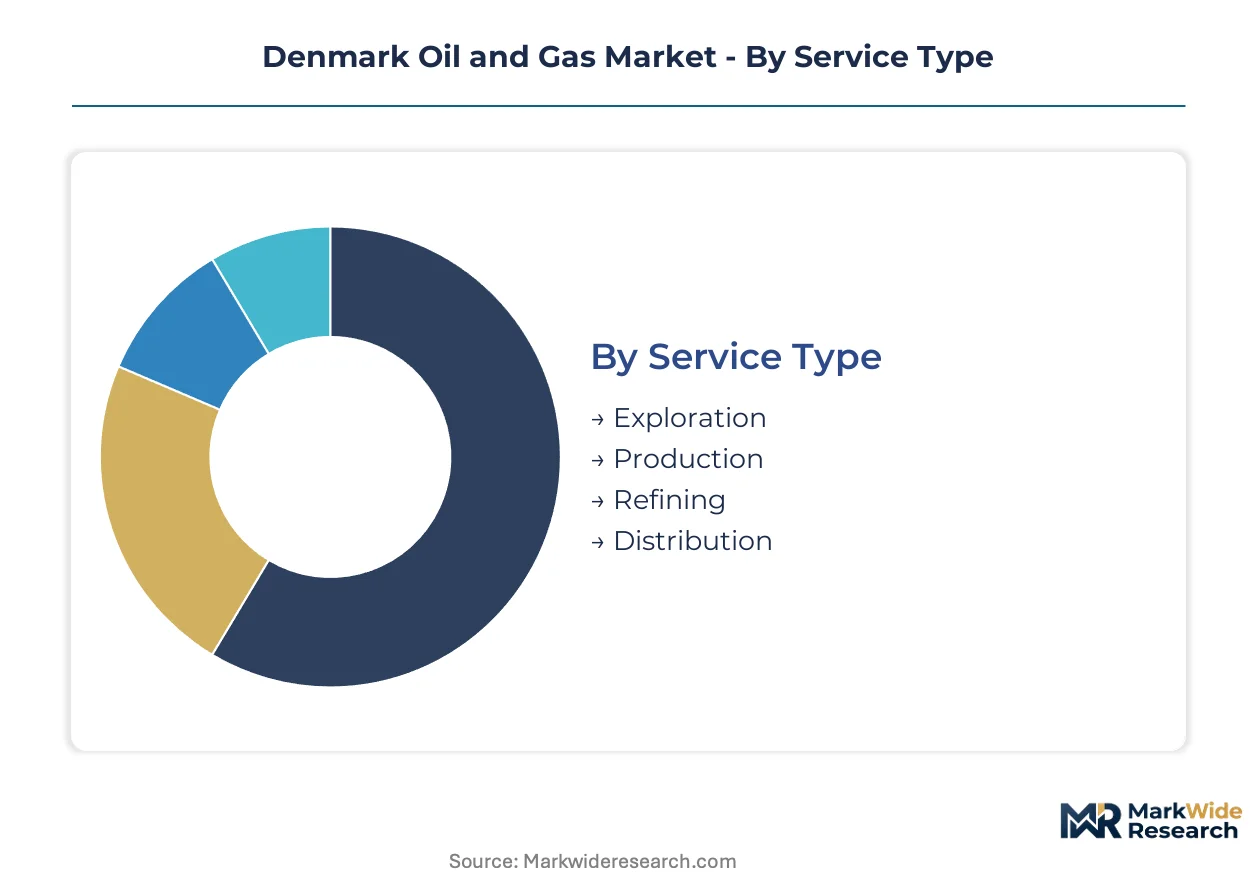
Segmentation reveals how Denmark's offshore maturity redirects capital toward carbon-capture-ready infrastructure and enhanced recovery services. Each axis exposes distinct competitive pressures from the Danish Climate Act and the Subsoil Act's overlapping compliance demands.
Service Type:
Service specialization reflects the capital intensity of extending field life versus exiting mature assets.
- Exploration:Geophysical surveying and appraisal drilling concentrate on the Danish Underground Consortium's remaining unappraised blocks near existing pipeline corridors. The Danish Energy Agency's licensing moratorium on new exploration permits compresses activity to re-evaluation of legacy seismic datasets.
- Production:Hydrocarbon extraction from the North Sea's chalk reservoirs and associated gas processing generates the dominant revenue pool. Operators deploy subsea tiebacks to satellite fields while integrating carbon capture modules at Tyra and Dan platform complexes.
- Refining:Kalundborg's single refinery processes light crude and condensate for regional petrochemical feedstock. The facility faces margin pressure from electrification of road transport and biomethane substitution in industrial offtake.
- Distribution:Energinet's regulated transmission monopoly connects offshore platforms to German and Swedish interconnectors. The segment captures stable fee-based returns through capacity reservations from Copenhagen's district heating operators.
Production leads on scale; exploration leads on contraction velocity.
Technology:
Technology selection determines retrofit feasibility for 1970s-era platform infrastructure.
- Seismic Imaging:4D time-lapse surveys monitor waterflood fronts in chalk reservoirs. Operators reprocess vintage data rather than acquiring new surveys under capital discipline imposed by decommissioning timelines.
- Drilling Technologies:Extended-reach horizontal wells access bypassed oil from existing platform slots. Directional drilling services face demand compression as well inventory depletes without replacement exploration.
- Subsea Systems:Processing modules and tieback architectures eliminate topside expansion needs. Subsea electrification reduces offshore personnel exposure while enabling remote reservoir management from Esbjerg control centers.
- Enhanced Oil Recovery:Polymer flooding and CO2 injection extend productive life of Tyra, Halfdan, and Dan fields. The Danish Underground Consortium pilots carbon capture integration to satisfy Climate Act emissions ceilings while maintaining output.
Enhanced Oil Recovery leads on momentum; Subsea Systems leads on deployment breadth.
End User:
End-user concentration in the Greater Copenhagen corridor shapes contract structures and price risk allocation.
- Utilities:Energinet and municipal district heating operators contract for firm thermal delivery rather than commodity molecules. Price risk transfers to suppliers while reliability obligations intensify under district heating decarbonization targets.
- Industrial Manufacturers:Pharmaceutical and food processing facilities in Kalundborg and Copenhagen maintain continuous process heat demand. Biomethane injection and electrification threaten long-term offtake volumes from this anchor segment.
- Oil Traders:Physical arbitrage between Danish production and German industrial demand generates trading margins. Storage capacity at Fredericia terminal enables seasonal positioning around heating demand peaks.
- Marine Operators:Bunkering demand at Copenhagen and Fredericia ports faces displacement by methanol and ammonia fuel pilots. The segment contracts as EU FuelEU Maritime regulations accelerate vessel fleet turnover.
Industrial Manufacturers lead on scale; Utilities lead on contract innovation.
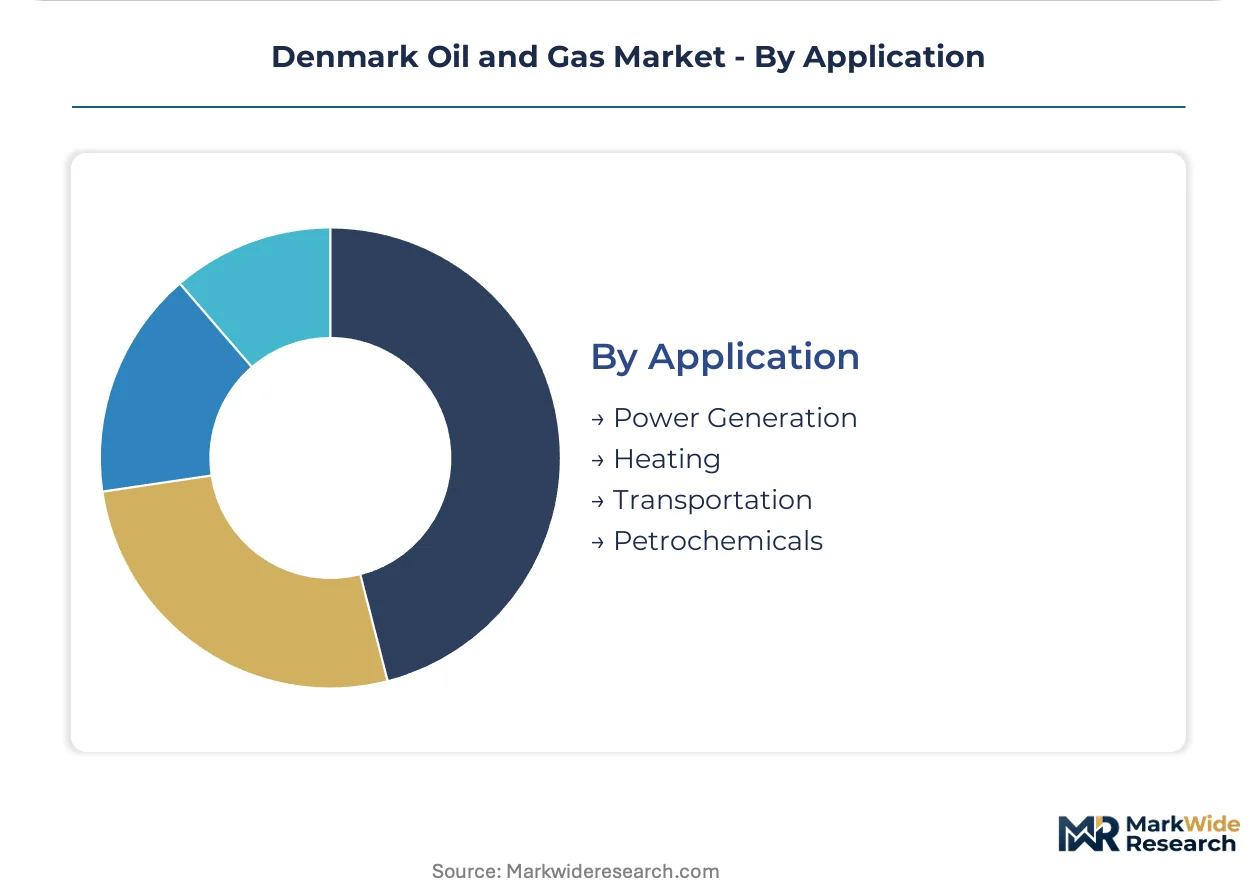
Application:
Application mix reveals substitution vulnerability across Denmark's energy transition pathway.
- Power Generation:Gas-fired plants at Avedøreværket and Amagerværket provide peaking capacity and grid stability services. Wind intermittency sustains dispatch revenue even as renewable share climbs.
- Heating:District heating networks integrate gas cogeneration with biomass and heat pumps. The Danish Climate Act mandates sectoral emissions ceilings that force fuel switching or carbon capture retrofits at central plant sites.
- Transportation:Road fuel demand declines under electrification while marine bunkering faces ammonia and methanol competition. The application contracts fastest across all end-uses.
- Petrochemicals:Kalundborg's refinery supplies naphtha and LPG to Scandinavian polymer producers. Feedstock demand proves more durable than combustion applications against substitution pressures.
Heating leads on scale; Petrochemicals leads on demand durability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Danish oil and gas sector traces its commercial origins to the 1972 discovery of the Kraka field, which established the Danish Underground Consortium and positioned the North Sea basin as a mature hydrocarbon province serving northern European industrial demand.
Capital Region
The Greater Copenhagen industrial corridor generates concentrated thermal demand through pharmaceutical manufacturing and food processing facilities. The Danish Climate Act imposes sectoral emissions ceilings that compel district heating operators to integrate carbon capture at Avedøreværket and Amagerværket cogeneration plants. Kalundborg's refinery and manufacturing cluster anchors petrochemical feedstock consumption while piloting biomethane injection into Energinet's transmission network.
Central Denmark Region
Esbjerg serves as the operational command center for North Sea production, hosting onshore control centers that manage subsea tieback infrastructure. The Danish Energy Agency enforces Subsoil Act decommissioning timelines that concentrate abandonment liability planning among operators with aging platform assets. The port infrastructure supports offshore wind-to-hydrogen pilots that share logistics with legacy oil and gas supply chains.
North Denmark Region
The Tyra field redevelopment drives capital allocation toward platform carbon capture readiness and enhanced oil recovery deployment. Danish Underground Consortium members face overlapping compliance demands from climate mandates and field retirement schedules. The region's offshore infrastructure connects to German and Swedish interconnectors through Energinet's regulated transmission monopoly.
South Denmark Region
Fredericia terminal enables seasonal gas storage positioning for industrial buyers contracting firm thermal delivery rather than commodity volumes. The EU F-Gas Regulation constrains refrigerant selection for regional gas processing facilities, accelerating equipment replacement cycles. Biomethane production facilities in rural Jutland threaten long-term natural gas offtake from agricultural processing industries.
Zealand Region
Marine bunkering demand at Copenhagen and Fredericia ports faces displacement from methanol and ammonia fuel pilots under EU FuelEU Maritime regulations. The region's industrial gas consumption concentrates in continuous process heat applications with limited electrification feasibility. Carbon storage licensing rounds for depleted offshore fields may create new revenue streams before existing pipeline infrastructure reaches technical retirement.
Denmark Oil and Gas Market Competitive Environment
Capital-heavy producers compete with asset-light traders across Denmark's hydrocarbon value chain. The market structure concentrates upstream production among North Sea operators holding Danish Underground Consortium licenses, while midstream and trading functions fragment across specialized logistics providers and energy merchants. Three archetypes dominate: integrated majors with carbon capture integration capabilities, state-affiliated transmission monopolies, and independent commodity traders with storage arbitrage expertise. Competitive dynamics center on securing decommissioning liability partnerships and capturing carbon storage acreage before infrastructure retirement.
Within the integrated major tier, Equinor ASA and TotalEnergies SE occupy positions defined by subsea tieback expertise and North Sea reservoir management. Ørsted represents the energy transition archetype, repurposing offshore competencies toward wind-to-hydrogen pilots that share port infrastructure with legacy operations. Energinet anchors the regulated infrastructure segment as Denmark's transmission system operator. These three entities exemplify the strategic divergence between hydrocarbon extraction and decarbonization service provision that characterizes competitive positioning under the Danish Climate Act.
| Leading Market Players |
|---|
| Equinor ASA |
| TotalEnergies SE |
| Shell PLC |
| Maersk Oil |
| Ørsted |
| Energinet |
| Danske Commodities |
| Norwegian Energy Company ASA |
| Energinet DK Gaslager A/S |
| Others |
Value Chain & Pricing Dynamics
Captive integration of carbon capture modules into existing offshore platforms anchors both supply security and pricing leverage for Danish Underground Consortium operators facing simultaneous decommissioning and emissions compliance timelines. This vertical control over retrofit engineering capacity insulates integrated majors from spot-market volatility in specialized subsea contracting while compressing margins for independent service providers lacking platform access.
Pricing Analysis
Firm thermal delivery contracts dominate Copenhagen's industrial corridor, transferring commodity price risk from pharmaceutical and food processing buyers to suppliers with captive storage assets. Price differentiation rests on reliability guarantees and carbon intensity certification rather than molecule quality alone. Cost compression in standard gas volumes is intensifying because biomethane injection expands supply alternatives. Industrial manufacturers with continuous process heat demand prove least price-sensitive, while intermittent heating operators exhibit highest elasticity.
Supply Chain Analysis
Freight costs for heavy subsea equipment from Norway, Germany, and the Netherlands concentrate procurement leverage among operators with dedicated heavy-lift vessel contracts. Raw material dependencies span specialized polymers for enhanced recovery, high-grade steel for platform reinforcement, and ammonia-based refrigerants replacing synthetic alternatives under EU F-Gas Regulation. Single-source vulnerability in carbon capture membrane technology creates supply chain risk. Distribution runs through Energinet's regulated transmission monopoly connecting offshore production to German and Swedish interconnectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Denmark oil and gas market functions as a stable compounder where district heating interconnection and industrial process heat demand generate predictable offtake despite energy transition headwinds.
For Market Incumbents: Extend productive life of Tyra and Dan fields through polymer flooding deployment while securing carbon storage licensing ahead of pipeline infrastructure retirement. Biomethane substitution threatens long-term gas volumes from Jutland manufacturing clusters. Backward integration into subsea engineering capabilities preserves margin capture against independent service providers.
For New Entrants and Emerging Players: Capture carbon capture integration services for 1970s-era platform retrofits where incumbent operators lack specialized structural reinforcement expertise. The Danish Underground Consortium's licensing rounds for CO2 storage acreage represent the most penetrable entry point. Partner with Esbjerg port authorities for shared logistics infrastructure to minimize greenfield capital requirements.
For Investors and Strategic Acquirers: Roll-up economics work for enhanced oil recovery specialists because field maturity concentrates demand for polymer flooding and CO2 injection services among shrinking operator pools. Long-term viability extends through the analysis window for assets with carbon capture readiness and district heating interconnection. Watch for Danish Energy Agency signals on carbon storage licensing timeline as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | Preserves production licenses under Danish Climate Act emissions ceilings at Tyra platform complex. |
| Enhanced Recovery Deployment | Extends productive life of Halfdan and Dan chalk reservoirs through polymer flooding investment. |
| Carbon Storage Licensing | Creates new revenue streams from depleted fields before North Sea pipeline infrastructure retires. |
| Port Infrastructure Sharing | Enables offshore wind-to-hydrogen pilots to leverage Esbjerg logistics without duplicative capital. |
| Subsea Electrification | Reduces offshore personnel exposure while enabling remote reservoir management from onshore centers. |
Study Parameters
Multiple input streams — primary interviews with Danish Energy Agency officials, Danish Underground Consortium operators, and Esbjerg port logistics managers — were reconciled against secondary validation from Energinet transmission data, EU F-Gas Regulation filings, and Subsoil Act decommissioning schedules. Bottom-up field-level production estimates and top-down national energy balance triangulation anchored volume assessments. Stakeholder roles spanned reservoir engineers, district heating procurement officers, carbon capture technology specialists, and industrial thermal buyers.
Historical production decline curves were cross-referenced against expert panel inputs on enhanced recovery deployment timelines. Segmentation dimensions modeled include service type, technology category, end-user industry, and application across the projection horizon. CAGRs derived from vintage field decline rates, carbon capture integration capital schedules, and district heating demand elasticity. Forecast inputs incorporated Danish Climate Act sectoral emissions ceilings and Subsoil Act abandonment bond requirements.
Underlying measurement precision varies by segment; production and distribution services carry tighter precision than exploratory activities where licensing moratoriums compress visibility. Forecasts reflect assumptions on carbon storage licensing timing and biomethane substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
Floating Production Systems (FPS) Market
Offshore Oil and Gas
Indonesia Oil and Gas Upstream Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
Oil and Gas Fishing Market