
 Gulf of Mexico Subsea Systems Market | 2026-2036
Gulf of Mexico Subsea Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Gulf of Mexico Subsea Systems Market Foresight
The US Gulf Coast is narrowing the engineering gap between shallow-water legacy assets and next-generation deepwater installations. TechnipFMC PLC leverages integrated project delivery to dominate subsea production system integration. Baker Hughes Company sustains technology leadership in submersible pump and control module architectures. Subsea 7 SA anchors its position through specialized offshore construction and umbilical installation capabilities.
Gulf of Mexico subsea systems encompass seabed-mounted production equipment, tieback infrastructure, and remote intervention tools engineered to withstand pressures exceeding 15,000 psi and temperatures above 400°F in water depths surpassing 10,000 feet. These systems enable hydrocarbon extraction, processing, and transport from reservoirs that surface platforms cannot economically access. Subsea production systems command the largest value share due to their capital intensity and custom engineering requirements, while monitoring systems represent the fastest-expanding technology segment as operators pursue reservoir optimization and predictive maintenance. Flowline systems occupy a mature but critical position linking wellheads to host facilities across sprawling deepwater field developments.
BSEE mandates govern well integrity and blowout prevention equipment testing across US federal waters, while API RP 17 series standards define subsea equipment design and operational protocols. The US Coast Guard coordinates spill response planning with state regulators in Louisiana and Texas, creating layered compliance obligations for subsea contractors and oil and gas operators. Stakeholders must weigh capital allocation between brownfield tieback expansions and greenfield developments as reservoir depletion profiles and regulatory scrutiny intensify simultaneously.
Market Dynamics
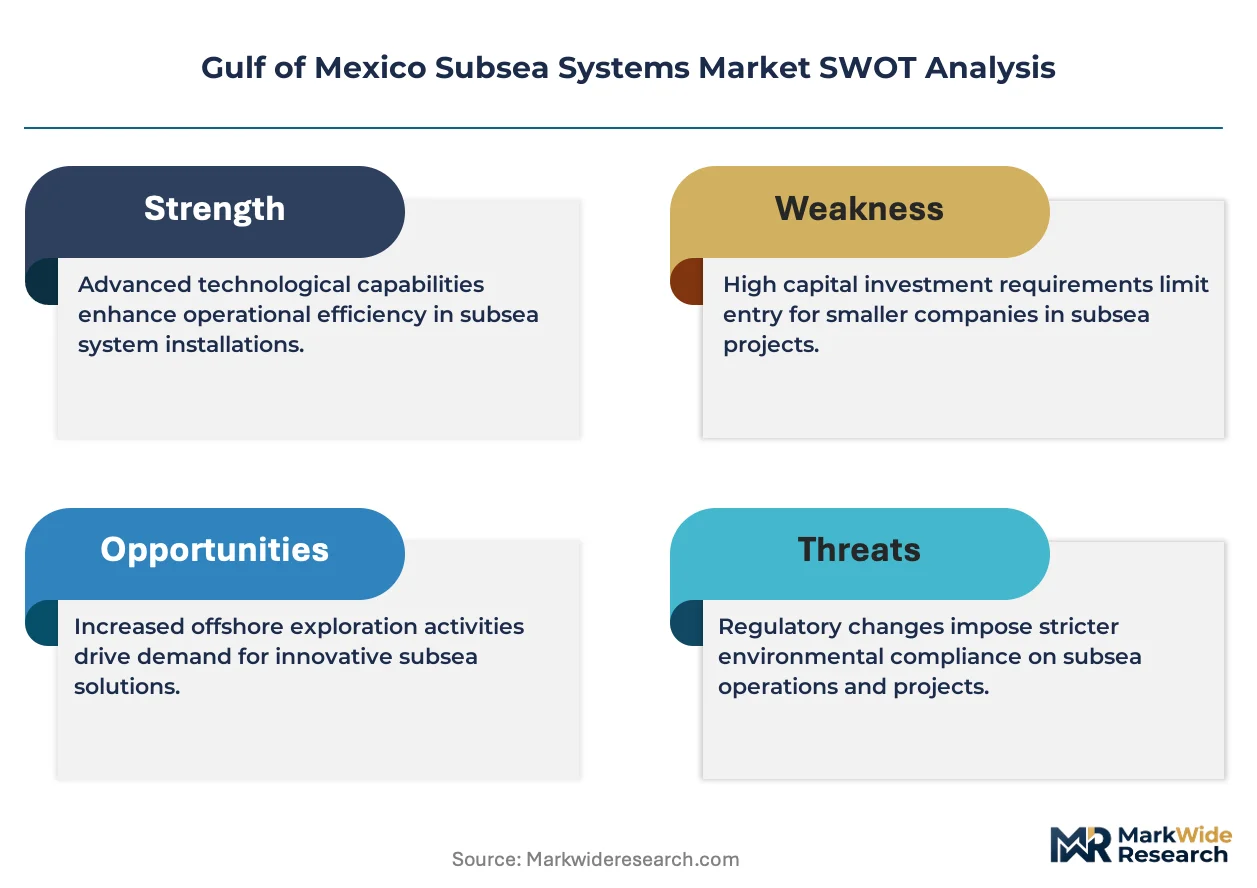
Deepwater operators in the US Gulf Coast face intensifying pressure to extend field life while BSEE tightens well control certification timelines, compressing project schedules and forcing capital redeployment toward brownfield tiebacks over greenfield developments.
Growth Catalysts
- Ultra-deepwater reservoir access:Subsea processing technology unlocks stranded reserves in water depths exceeding 10,000 feet where surface platforms prove economically unviable.
- BSEE well integrity mandates:Regulatory pressure for blowout preventer testing and documentation drives replacement cycles for aging subsea infrastructure across federal lease blocks.
- Electrification of subsea architectures:All-electric actuation systems reduce hydraulic fluid complexity and enable longer step-out distances from host facilities.
Market Restraints
- Specialized steel alloy supply concentration:High-yield sour service grades for wellhead connectors concentrate among a limited set of qualified mills, creating input bottlenecks.
- API RP 17N qualification timelines:Extended testing protocols for subsea equipment in HPHT conditions stretch product development cycles and delay field deployment.
- Surface platform economics:Floating production unit day rates and steel fabrication costs constrain project sanctioning thresholds for marginal deepwater discoveries.
Strategic Opportunities
- Subsea tieback expansions:Satellite well connections to existing infrastructure offer lower capital intensity than standalone developments in maturing basins like Mars-Ursa.
- Digital twin integration:Real-time reservoir simulation combined with subsea sensor networks enables predictive intervention and optimized production profiles.
- Plug and abandonment liability transfers:Specialized contractors assume decommissioning obligations from supermajors seeking balance sheet relief on end-of-life assets.
Industry Challenges
- HPHT welding certification scarcity:Qualified technicians for super duplex and nickel alloy fabrication remain concentrated among a handful of Gulf Coast service yards.
- Legacy hydraulic system interoperability:Brownfield electrification requires complex interface engineering with existing hydraulic control umbilicals and distribution units.
- Spill response equipment staging:US Coast Guard contingency planning mandates dictate redundant capping stack positioning across dispersed offshore installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gulf of Mexico Subsea Systems Market |
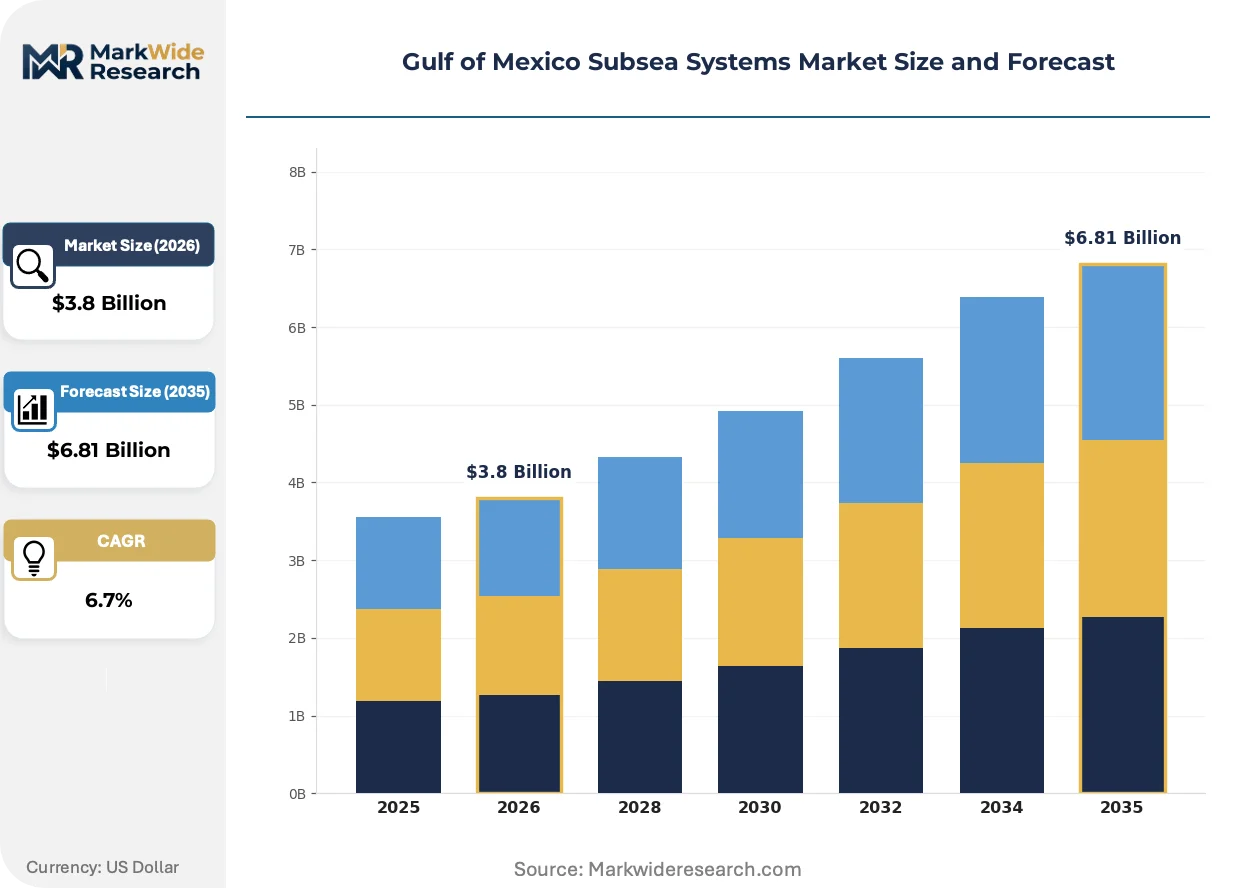
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Subsea Production System, Umbilical System, Manifold System, Flowline System Technology: Remote Operated Vehicle, Submersible Pump, Control Modules, Monitoring Systems Application: Deepwater Oil Extraction, Gas Gathering, Environmental Monitoring, Subsea Processing End User: Oil & Gas Operators, Engineering Firms, Subsea Contractors, Government Agencies |
| Companies Covered | TechnipFMC PLC, Subsea 7 SA, Baker Hughes Company, Oceaneering International, Inc., National-Oilwell Varco Inc., Schlumberger Ltd., Halliburton Co., Aker Solutions, Dril-Quip Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gulf of Mexico Subsea Systems Market Shifts & Advancements
Subsea engineering is pivoting toward autonomous intervention capabilities and modular standardization as operators confront rising development costs and regulator-mandated response time compression.
Subsea boosting technology is migrating from gas-lift dependent architectures to multiphase pump systems that maintain reservoir pressure without surface gas injection. Independent operators in the Lower Tertiary trend adopt these systems to improve recovery factors from high-pressure, low-permeability formations. The technology is migrating from bespoke project engineering toward standardized skid-mounted configurations that reduce fabrication lead times and enable fleet-based maintenance strategies.
BSEE implemented more rigorous blowout preventer inspection intervals following post-Macondo rulemaking, requiring real-time monitoring data transmission to shore-based control centers. Operators must now demonstrate functional testing of shear rams under simulated wellbore conditions before each drilling campaign. Deepwater drillship contractors in the US Gulf Coast absorb compliance costs through extended mobilization schedules and specialized technician certifications.
Asset ownership patterns among exploration and production companies favor capital-light operating models where subsea infrastructure remains vendor-financed or leased. Private equity-backed independents acquire mature Gulf of Mexico fields and outsource production system maintenance to integrated service providers. This restructuring concentrates operational risk with contractors while shifting balance sheet exposure away from oil price volatility.
Gulf of Mexico Subsea Systems Market Segmentation
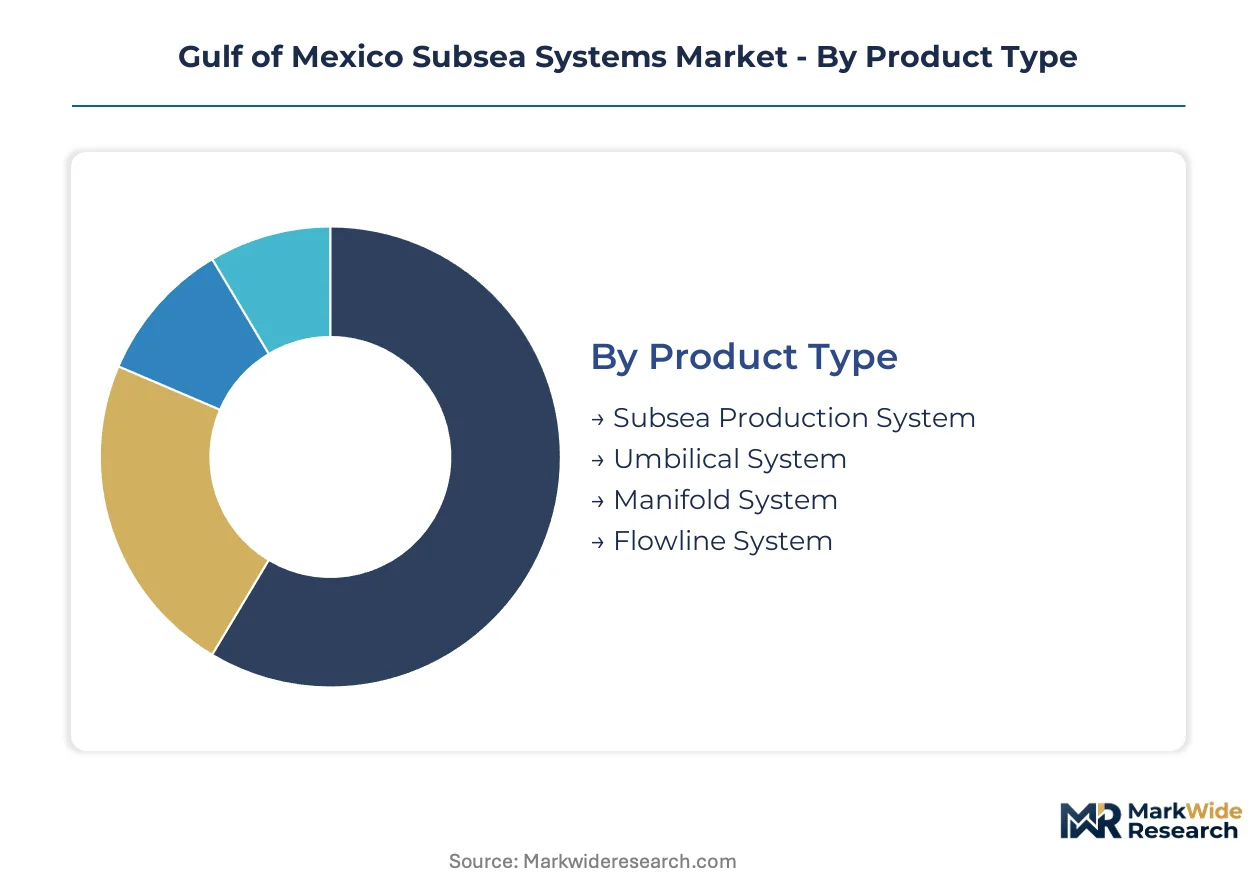
Subsea system procurement in the US Gulf Coast diverges sharply by water depth, reservoir pressure, and regulatory exposure. Operators segment capital deployment across production hardware, intervention technologies, and monitoring architectures based on field maturity and tieback economics.
Product Type:
Capital allocation tracks the engineering intensity required across seabed-to-surface infrastructure layers.
- Subsea Production System:Wellheads, trees, and jumpers engineered for HPHT conditions dominate capital budgets in ultra-deepwater developments. Demand concentrates in federal lease blocks off Louisiana where BSEE mandates accelerated replacement cycles for aging blowout preventer stacks.
- Flowline System:Rigid and flexible pipelines connecting wellheads to host facilities span 10-50 mile step-out distances in Lower Tertiary fields. Procurement volumes in Texas offshore waters reflect tieback prioritization over standalone platform investments.
- Manifold System:Distribution hubs consolidating multiple well streams reduce riser count and simplify host facility design.
- Umbilical System:Hydraulic and electro-hydraulic control lines transmit power and data between surface and seabed equipment.
Established volume favors flowline infrastructure; emerging adoption favors integrated production systems with real-time monitoring capabilities.
Technology:
Intervention and control architectures split between hydraulic legacy systems and electrified next-generation platforms.
- Monitoring Systems:Distributed fiber-optic sensing and acoustic surveillance networks enable predictive maintenance and reservoir optimization. Adoption accelerates in maturing deepwater fields where production decline rates justify sensor deployment for intervention timing.
- Submersible Pump:Multiphase and seabed boosting systems maintain reservoir pressure without surface gas injection. Operators in the Mars-Ursa corridor deploy these pumps to extend plateau production from high-pressure, low-permeability formations.
- Control Modules:Subsea distribution units manage valve actuation and chemical injection across well clusters.
- Remote Operated Vehicle:Tethered intervention systems perform inspection, maintenance, and repair in depths exceeding diver limits.
Electrified control architectures are expanding most quickly; hydraulic intervention platforms retain installed-base dominance.
Application:
Field development strategies determine whether systems target hydrocarbon extraction or regulatory compliance functions.
- Deepwater Oil Extraction:Subsea trees and processing equipment unlock reserves in 5,000-10,000 foot water depths where platform economics fail. Investment concentrates in Lower Tertiary trends where reservoir quality justifies subsea boosting and separation.
- Subsea Processing:Seabed separation, compression, and water injection systems reduce topside facility sizing. Pilot deployments in the Gulf of Mexico test multiphase pumping and gas compression architectures previously proven in North Sea fields.
- Gas Gathering:Wet gas compression and flow assurance systems transport associated gas to processing facilities.
- Environmental Monitoring:Leak detection and subsea plume tracking systems satisfy BSEE spill response planning mandates.
Production-focused applications command current capital; processing and monitoring functions show steepest expansion trajectory.
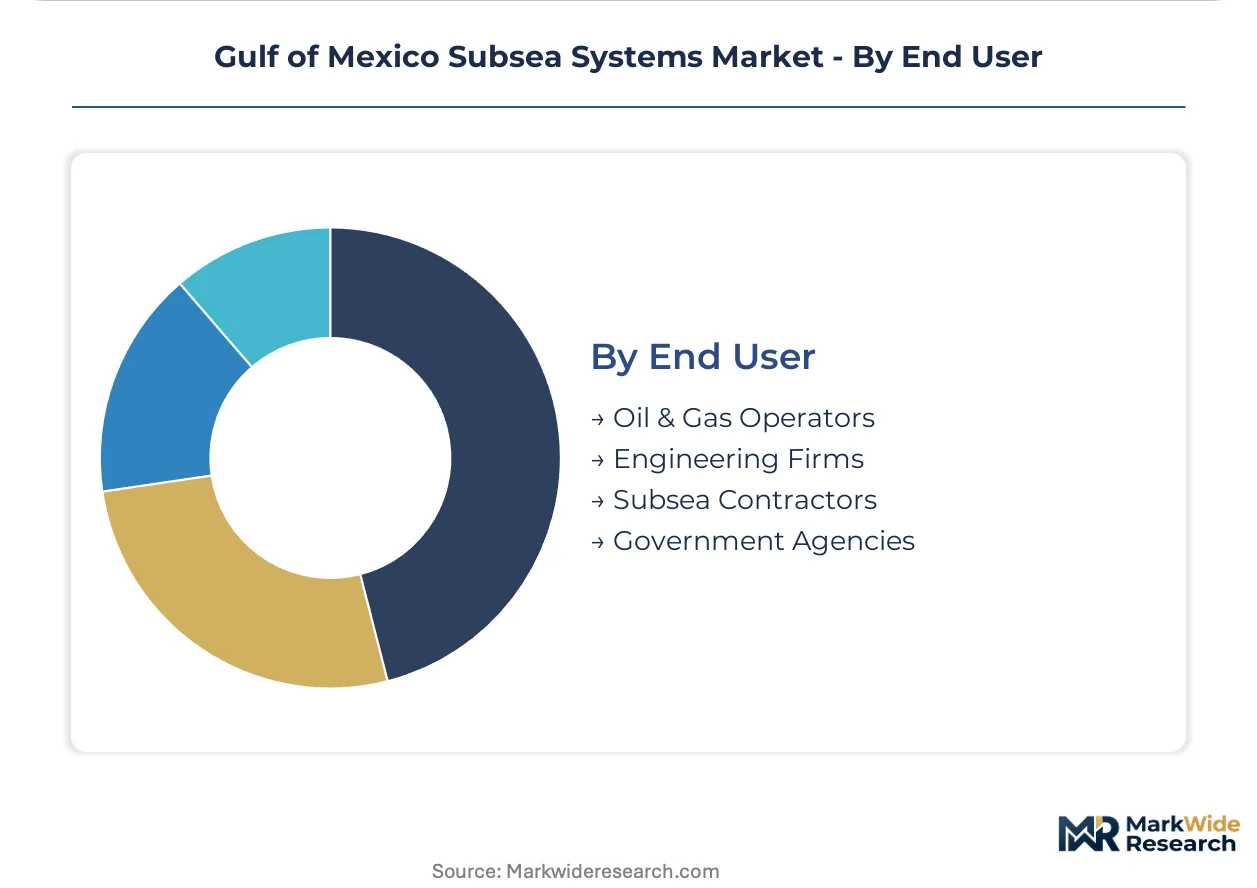
End User:
Procurement authority fragments across asset owners, engineering integrators, and regulatory enforcement bodies.
- Oil & Gas Operators:Supermajors and independents sanction subsea capital based on reservoir depletion profiles and tieback proximity to existing infrastructure. Private equity-backed firms in the Gulf of Mexico increasingly outsource system maintenance to specialized contractors.
- Subsea Contractors:Installation and intervention service providers assume operational risk through vendor-financed equipment leases. These arrangements concentrate in brownfield acquisitions where balance sheet relief outweighs long-term cost premiums.
- Engineering Firms:Front-end design contractors specify equipment packages and interface requirements for integrated project delivery.
- Government Agencies:BSEE and US Coast Guard mandate equipment certification, inspection intervals, and spill response staging without direct procurement authority.
Operator direct purchasing dominates sanctioning-phase decisions; contractor-led financing is reshaping brownfield maintenance economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BSEE mandates anchor subsea system procurement across federal waters off Louisiana and Texas, where ultra-deepwater developments concentrate capital deployment. The US Gulf Coast dominates engineering capacity and regulatory jurisdiction for HPHT equipment qualification.
Louisiana Offshore
Lower Tertiary discoveries in Walker Ridge and Keathley Canyon drive demand for subsea production systems rated above 15,000 psi. BSEE well control regulations mandate accelerated blowout preventer replacement cycles for aging infrastructure. Port Fourchanchors fabrication yards specializing in super duplex welding for wellhead connectors.
Texas Offshore
Maturing fields in the Mars-Ursa corridor favor tieback expansions over greenfield platform investments. API RP 17N qualification timelines constrain product development for HPHT flowline systems. Houston hosts engineering design centers specifying integrated subsea packages for independents acquiring mature assets.
Mississippi Canyon
Legacy deepwater infrastructure requires monitoring system upgrades to satisfy predictive maintenance mandates. US Coast Guard spill response planning dictates redundant capping stack positioning across dispersed installations. Subsea intervention vessel operators stage from Venice, Louisiana to serve decommissioning obligations on end-of-life fields.
Alaminos Canyon
Frontier ultra-deepwater prospects test electrified subsea architectures with extended step-out distances from host facilities. FERC coordinates pipeline safety oversight with BSEE equipment certification requirements. Specialized contractors assume plug and abandonment liabilities from supermajors seeking balance sheet relief.
Gulf of Mexico Subsea Systems Market Competitive Landscape
Capability concentration sits with integrated project delivery specialists; scale advantage sits with diversified energy service conglomerates. The vendor base stratifies across three tiers: full-system integrators owning design-through-installation workflows, component specialists dominating specific hardware categories, and installation contractors competing on vessel availability and offshore execution speed. Dominant competitive moves include vendor-financed equipment leases for brownfield acquisitions and strategic partnerships to combine subsea processing technology with installation capacity.
Within the integrated systems tier, TechnipFMC PLC and Baker Hughes Company exemplify divergent strategic positions—one anchored in project delivery integration, the other in rotating equipment and control module architectures. Subsea 7 SA occupies a distinct position among installation specialists, with offshore construction and umbilical deployment capabilities that anchor brownfield expansion economics. These three represent the primary competitive archetypes shaping procurement authority among Gulf of Mexico operators.
| Leading Market Players |
|---|
| TechnipFMC PLC |
| Subsea 7 SA |
| Baker Hughes Company |
| Oceaneering International, Inc. |
| National-Oilwell Varco Inc. |
| Schlumberger Ltd. |
| Halliburton Co. |
| Aker Solutions |
| Dril-Quip Inc. |
| Others |
Supply & Pricing Matrix
Houston-to-Port Fourchon heavy-lift barge corridors carry super duplex wellhead components at rates that compress margins for fabrication yards serving Louisiana ultra-deepwater blocks while amplifying price spreads between API-certified premium tiers and standard-grade alternatives sourced through less specialized channels.
Pricing Analysis
Price spreads between Houston engineering centers and Port Fourchon fabrication yards reach widest divergence for HPHT-qualified wellhead connectors, where BSEE certification tiers separate premium API RP 17N-validated systems from standard-pressure alternatives. Project-based long-term contracting dominates procurement for greenfield developments, while spot purchasing concentrates in brownfield maintenance where private equity-backed independents prioritize capital efficiency over lifecycle cost. Cost compression in standard-grade flowline systems intensifies as vendor-financed lease arrangements displace direct operator ownership. Supermajors exhibit lowest price sensitivity, absorbing certification premiums for accelerated replacement cycles; independents acquiring mature Mars-Ursa corridor assets drive hardest bargain on maintenance outsourcing rates.
Supply Chain Analysis
US export controls on advanced subsea control system technologies limit electro-hydraulic actuation component flows to qualified offshore contractors, concentrating high-specification manufacturing among domestic Gulf Coast facilities and select Norwegian specialized suppliers. High-yield sour service steel alloys draw from qualified mills in the United States, Japan, and Germany; super duplex welding consumables and nickel alloy forgings feed from a narrower supplier base anchored in European specialty metals producers. Single-source vulnerability concentrates in HPHT sealing element manufacturing, where qualified elastomer compounders number fewer than five globally. Distribution runs through integrated project delivery specialists who consolidate equipment packages for operator sanctioning decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across brownfield acquisition financing, electrified architecture migration, and regulatory compliance services creates niche entry points as capital-light operating models displace integrated operator ownership of subsea infrastructure.
For Market Incumbents: Harden vendor-financed lease portfolios against default exposure from private equity-backed independents by tightening collateral requirements on aging Mars-Ursa corridor assets. Expand backward integration into super duplex welding certification programs to capture technician scarcity premiums rather than ceding margin to specialized Gulf Coast service yards. Prioritize API RP 17N qualification pipeline investment to compress product development timelines as BSEE mandates accelerate replacement cycles. For New Entrants and Emerging Players: Establish a beachhead in plug and abandonment liability assumption services, where supermajors seek balance sheet relief on end-of-life Mississippi Canyon infrastructure. Target environmental monitoring system deployment for BSEE spill response compliance, a segment where specialized contractors face limited incumbent concentration. Pursue direct contracting relationships with private equity-backed field acquirers who outsource production system maintenance rather than building internal technical capabilities. For Investors and Strategic Acquirers: Specialized subsea intervention vessel operators with captive capping stack positioning represent the most defensible acquisition archetype, given US Coast Guard contingency planning mandates that create sticky demand. Long-term viability hinges on electrification transition exposure; contractors anchored in legacy hydraulic system maintenance face obsolescence risk as all-electric architectures expand in Alaminos Canyon frontier developments. Watch electrified control module adoption rates as the inflection signal distinguishing growth-stage from declining-service asset bases.| Strategic Initiative | Industry Significance |
|---|---|
| HPHT Equipment Certification Investment | Accelerated BSEE replacement cycles reward pre-qualified API RP 17N inventory positions. |
| Vendor-Financed Lease Structuring | Capital-light operator models concentrate equipment ownership risk with specialized contractors. |
| Electrified Architecture Partnership | All-electric actuation systems reduce hydraulic complexity for extended Lower Tertiary step-outs. |
| Plug and Abandonment Liability Assumption | Balance sheet relief demand from supermajors creates recurring decommissioning revenue streams. |
| Digital Twin Integration Development | Real-time reservoir simulation combined with subsea sensor networks enables predictive intervention timing. |
Research Methodology
A spread of perspectives from subsea project engineers, BSEE compliance officers, private equity acquisition directors, and Port Fourchon fabrication yard managers converged on the working assumptions governing field development economics and regulatory enforcement intensity. Primary interview intelligence was cross-referenced against BSEE incident reporting databases, API standards publication timelines, federal lease block production records, and SEC filings from integrated service providers to establish baseline market sizing. Bottom-up equipment procurement tracking was reconciled with top-down operator capital expenditure disclosures across the analysis window.
Demand-supply balance modeling anchored volume projections on reservoir depletion profiles in federal lease blocks off Louisiana and Texas, segmented by water depth tier, pressure-temperature classification, and tieback proximity to existing host facilities. Technology adoption curves for electrified control architectures and multiphase pumping systems were calibrated against North Sea deployment precedents and Gulf of Mexico pilot project outcomes. CAGRs were derived from equipment replacement cycle analysis, regulatory mandate implementation schedules, and brownfield acquisition activity levels rather than extrapolated historical growth rates.
Stress conditions across crude price volatility bands, BSEE inspection interval tightening scenarios, and specialized steel alloy supply disruption events were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding operator capital allocation preferences between greenfield developments and brownfield tiebacks. Material shifts in electrification technology cost curves or federal offshore leasing policy moratoriums would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Azerbaijan Oil and Gas Upstream Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Norway Oil and Gas Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Egypt Oil and Gas Downstream Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market