
 South America Offshore Seismic Survey Market | 2026-2036
South America Offshore Seismic Survey Market Size, Share, and Industry Trends Forecast 2026-2036
South America Offshore Seismic Survey Market Analytics
Brazilian vessel operators is restructuring fleet deployment around pre-salt basin campaigns, shifting multi-client library strategies toward deeper-water blocks. Schlumberger Ltd anchors integrated seismic-to-drilling workflows across Santos Basin contracts. CGG SA specializes in high-resolution imaging for complex salt geometries. PGS SA extends its position through multi-client 3D data libraries offshore Brazil and Uruguay.
Offshore seismic survey denotes the acquisition, processing, and interpretation of subsurface acoustic reflection data using towed streamer arrays, ocean-bottom nodes, or electromagnetic sensors deployed in marine environments, typically operating at frequencies between 5 Hz and 200 Hz depending on target depth and resolution requirements. The technique maps hydrocarbon reservoirs, geohazards, and seafloor conditions to de-risk drilling decisions and field development planning. 3D seismic dominates current value generation across South America given its established role in pre-salt exploration, while 4D time-lapse acquisition represents the fastest-expanding service category as producing fields require reservoir monitoring. Ocean bottom seismometers command premium pricing due to technical complexity and limited vessel availability, whereas 2D seismic has matured into a commoditized reconnaissance tool.
ANP, Brazil's national petroleum regulator, mandates specific seismic data standards for bid round participation and production sharing agreements, directly influencing contractor technical requirements and certification protocols. Environmental licensing processes administered by IBAMA and comparable agencies in Guyana and Suriname constrain seasonal operational windows and equipment specifications. Stakeholders must weigh multi-client data commitments against proprietary survey economics as licensing rounds accelerate across the Atlantic margin.
Market Dynamics
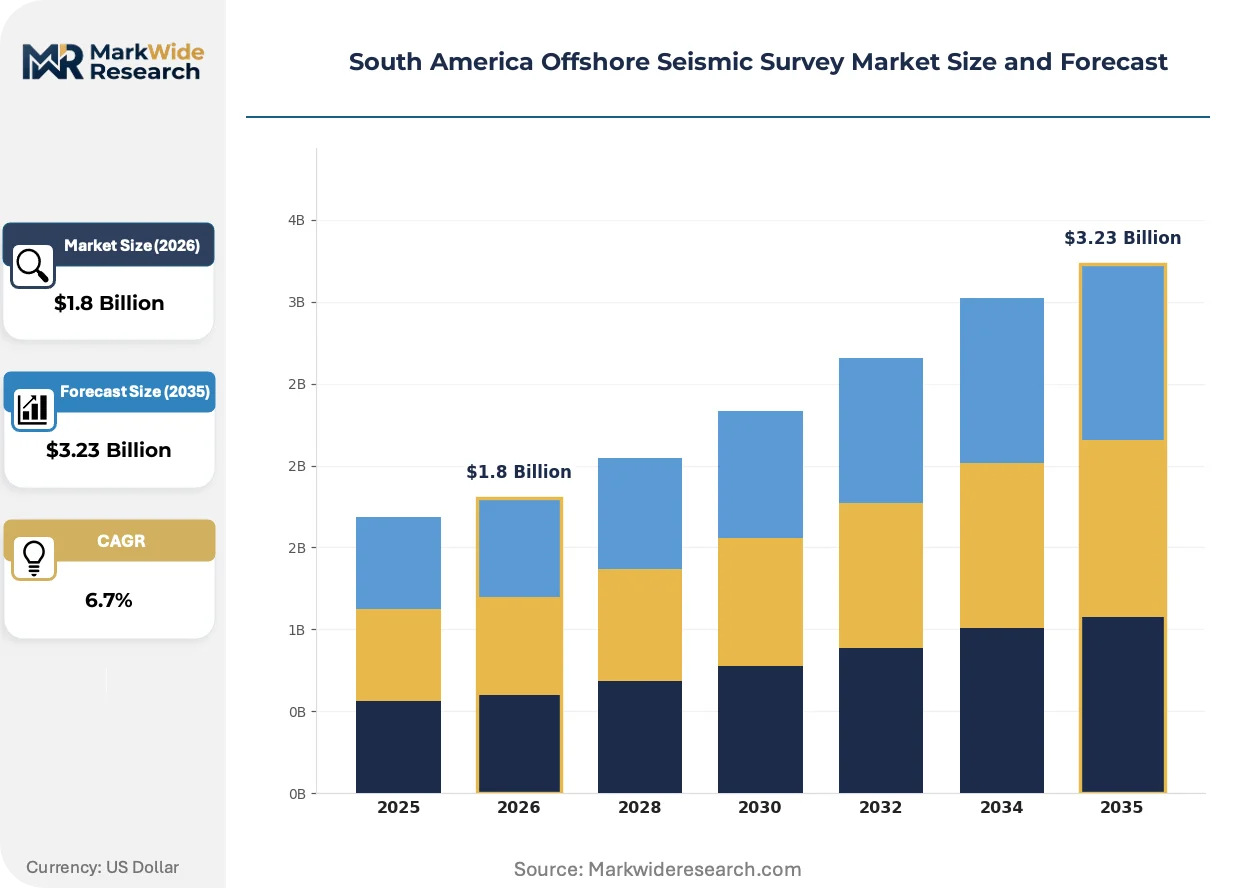
Brazil's pre-salt licensing acceleration is compressing survey procurement cycles, forcing contractors to pre-position specialized acquisition vessels ahead of ANP bid round announcements while balancing multi-client library economics against proprietary contract margins.
Growth Catalysts
- ANP Production Sharing Agreements:Brazil's regulator mandates 3D seismic coverage for pre-salt block qualification, creating guaranteed demand pull for high-specification acquisition services.
- Guyana-Suriname Basin Opening:ExxonMobil-operated discoveries offshore Guyana are extending survey demand northward along the Atlantic margin into underexplored Suriname blocks.
- Ocean Bottom Seismometer Deployment:Ultra-deepwater pre-salt imaging requirements are accelerating node-based acquisition for salt-proximity resolution beyond conventional streamer capabilities.
Market Restraints
- Specialized Vessel Scarcity:Global fleet concentration among Norwegian and Singapore-flagged operators limits surge capacity during Brazil's seasonal acquisition windows.
- IBAMA Licensing Delays:Brazil's environmental agency processing timelines frequently compress operational seasons, forcing costly standby rates or survey postponement.
- Electromagnetic Method Substitution:Marine CSEM and MT techniques are displacing some 2D seismic reconnaissance for direct hydrocarbon indication in frontier blocks.
Strategic Opportunities
- Uruguay Offshore Licensing:ANCAP's upcoming frontier round presents first-mover positioning for multi-client data library investment in untested Punta del Este Basin acreage.
- 4D Time-Lapse Services:Producing pre-salt fields require repeat seismic monitoring for reservoir management, opening recurring revenue streams distinct from exploration contracting.
- Regulatory Streamlining:Brazil's new environmental decree aims to unify federal and state licensing, potentially compressing approval timelines for integrated survey-to-drilling programs.
Industry Challenges
- Geophysicist Talent Pipeline:Specialized salt-velocity modeling expertise concentrates among aging professionals, constraining processing throughput for complex pre-salt imaging.
- Node Recovery Logistics:Deepwater ocean bottom seismometer operations require precision ROV deployment and retrieval, with weather downtime compressing effective acquisition rates.
- Multi-Client Data Amortization:Pre-survey commitments must reach threshold coverage before vessel mobilization, creating working capital intensity and pre-sale risk concentration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Offshore Seismic Survey Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 2D Seismic, 3D Seismic, 4D Seismic, Data Processing End User: Oil & Gas Companies, Mining Firms, Environmental Agencies, Research Institutions Technology: Marine Wireless, Ocean Bottom Seismometers, Electromagnetic Methods, High-Resolution Imaging Application: Hydrocarbon Exploration, Environmental Monitoring, Geotechnical Assessment, Seafloor Mapping |
| Companies Covered | Halliburton Company, Schlumberger Ltd, CGG SA, PGS SA, BGP Inc, Fugro NV, SAExploration Holdings Inc, TGS ASA, Shearwater Geoservices, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Offshore Seismic Survey Market Evolving Landscape
Seismic acquisition technology is converging with autonomous marine systems and real-time processing architectures, compressing the interval between data acquisition and drilling decision while reducing crewed vessel exposure in deepwater environments.
Dual-sensor streamer technology is integrating pressure and particle motion measurements to deliver broadband seismic data with enhanced low-frequency content for salt penetration. Petrobras and international operators operating Santos Basin pre-salt blocks are specifying these systems for new acquisition tenders. The technology is integrating processing workflows that previously required separate vessel passes, collapsing survey duration and reducing day-rate exposure.
ANP's updated technical guidelines for seismic data submission now mandate specific pre-processing standards and metadata formats for bid round eligibility. This regulatory tightening forces contractors to standardize acquisition parameters and quality control protocols across campaigns. Processing houses serving Brazil's pre-salt segment are investing in automated velocity model building to meet compressed turnaround requirements.
Operators are unbundling seismic processing from acquisition contracts, establishing direct relationships with specialized imaging boutiques for iterative velocity model refinement. This procurement fragmentation disintermediates traditional integrated service providers in favor of component specialists. The shift is most visible among independent operators in Brazil's pre-salt consortiums seeking competitive differentiation through proprietary imaging algorithms.
South America Offshore Seismic Survey Market Segmentation
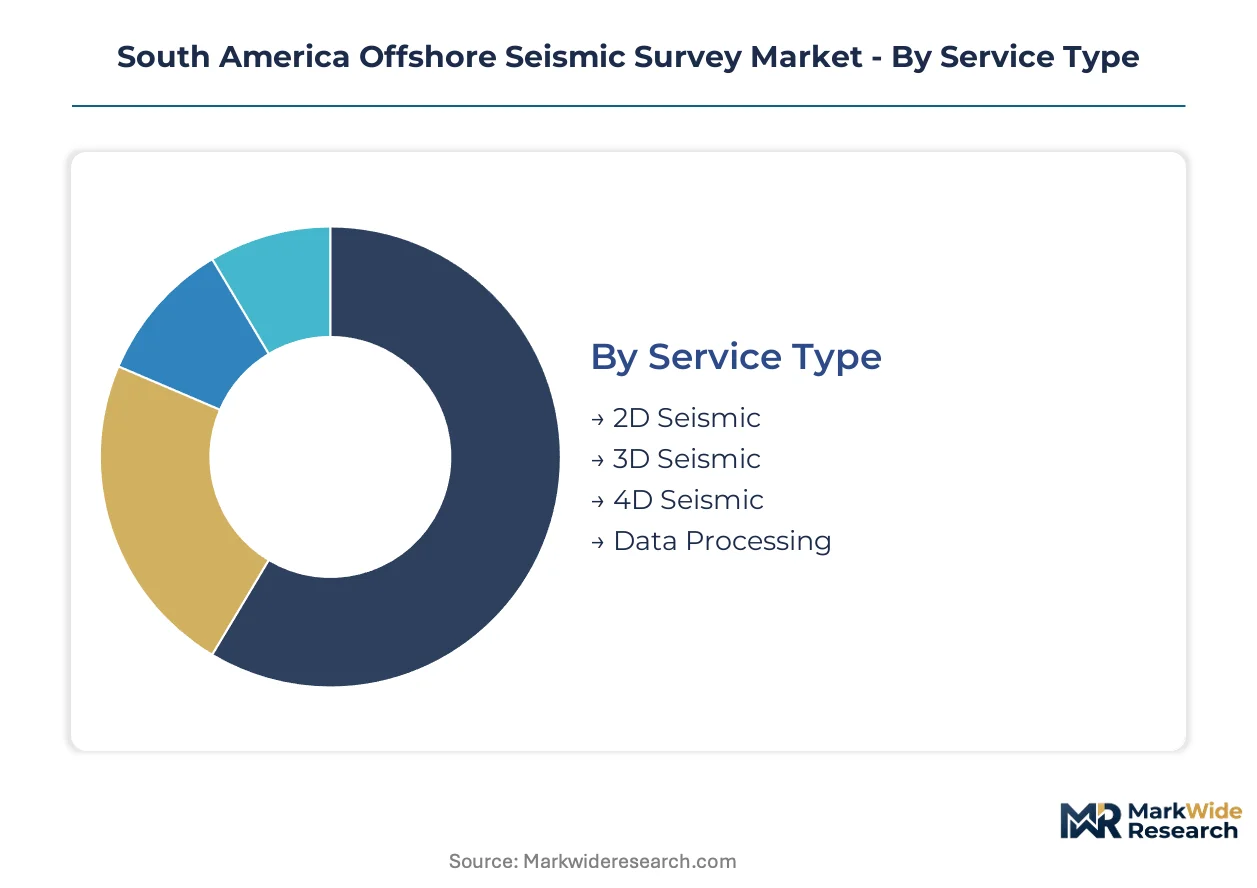
Seismic survey procurement patterns in South America diverge sharply across service tiers and client types. Contractors must align vessel specifications, sensor technologies, and data processing workflows to distinct commercial requirements spanning pre-salt exploration through environmental compliance.
Service Type:
Supply concentration tilts heavily toward high-specification 3D and 4D acquisition as Brazil's ANP mandates advanced seismic coverage for pre-salt qualification.
- 3D Seismic:Multi-azimuth streamer acquisition generates volumetric subsurface models through dense source-receiver geometries. Brazilian operators in the Santos and Campos basins specify 3D coverage as baseline for pre-salt block entry, with Petrobras and international consortiums driving tender volumes.
- 4D Seismic:Time-lapse repeat surveys monitor reservoir depletion and fluid movement across producing pre-salt fields. Demand concentrates among Libra and Búzios field operators seeking production optimization data, with repeat acquisition cycles creating recurring revenue distinct from exploration contracting.
- 2D Seismic:Reconnaissance line surveys support frontier block screening in Uruguay and untested Suriname acreage.
- Data Processing:Velocity model building and depth imaging services unbundle from acquisition contracts as operators seek specialized imaging boutiques.
Today's leader: 3D Seismic. Tomorrow's challenger: 4D Seismic.
End User:
Cost tier stratification separates capital-intensive exploration programs from regulatory-driven survey mandates.
- Oil & Gas Companies:Supermajors and national oil companies dominate procurement value, with Petrobras, ExxonMobil, and Shell consortiums specifying integrated seismic-to-drilling workflows. Pre-salt production sharing agreements require these operators to fund multi-client library development or proprietary acquisition campaigns.
- Environmental Agencies:IBAMA and comparable regulators in Guyana and Suriname commission baseline surveys for licensing compliance and marine protected area delineation. Budget constraints limit these contracts to 2D reconnaissance or repurposed multi-client data purchases rather than new acquisition.
- Mining Firms:Seabed mineral prospectors in the Clarion-Clipperton zone periphery represent nascent demand for geotechnical seismic data.
- Research Institutions:Universities and oceanographic centers acquire seismic profiles for crustal studies and climate archive research, typically through government grant funding.
Volume concentrates with Oil & Gas Companies. Margin expansion sits with Environmental Agencies as compliance requirements tighten.
Technology:
Application requirements dictate sensor selection, with deepwater pre-salt imaging forcing migration from conventional streamers to seabed-deployed systems.
- Ocean Bottom Seismometers:Autonomous nodes record full-azimuth, full-offset data for salt-proximity imaging beyond streamer capabilities. Petrobras specifications for Santos Basin ultra-deepwater blocks mandate OBS deployment, with limited global vessel availability creating pricing premiums and scheduling bottlenecks.
- Electromagnetic Methods:Marine CSEM and MT surveys detect resistivity contrasts for direct hydrocarbon indication in frontier blocks. Guyana-Suriname basin opening accelerates EM reconnaissance as operators screen acreage before committing to 3D seismic.
- High-Resolution Imaging:Shallow-penetration, high-frequency systems support geohazard assessment and seafloor infrastructure routing.
- Marine Wireless:Radio-linked surface systems enable real-time quality control and reduced crew exposure in harsh weather windows.
Maturity favors Marine Wireless. Steepest expansion trajectory belongs to Ocean Bottom Seismometers.
Application:
Customer type and project economics align survey specifications to distinct risk-reward profiles across the exploration-to-production lifecycle.
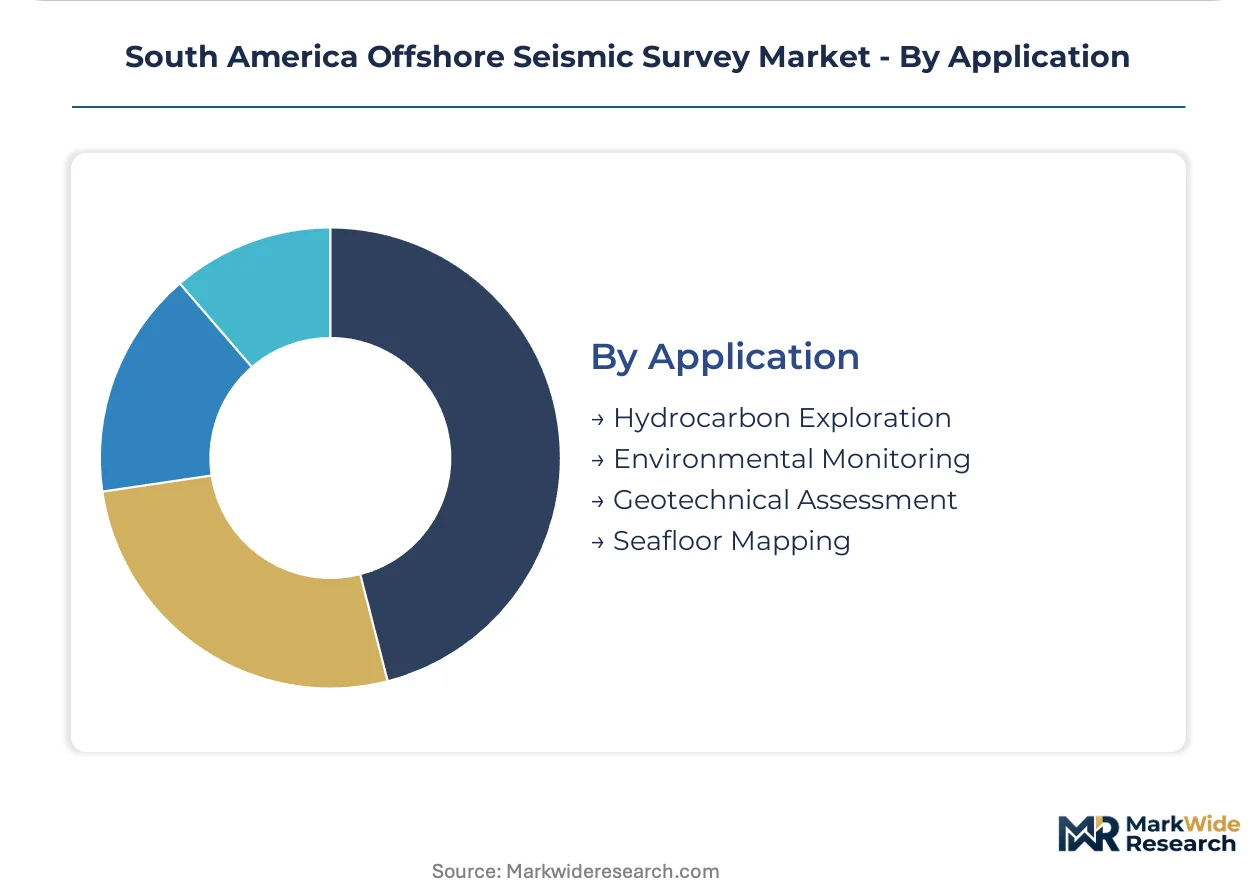
- Hydrocarbon Exploration:Pre-salt prospect de-risking consumes the majority of acquisition capacity, with ANP bid round timing compressing procurement cycles. Brazilian block qualification requirements guarantee demand for 3D and 4D services regardless of oil price volatility.
- Environmental Monitoring:Post-drilling baseline surveys and marine mammal observation protocols extend contract scope beyond pure exploration. IBAMA licensing conditions increasingly mandate repeat seismic for ecosystem impact assessment.
- Geotechnical Assessment:Foundation studies for platforms, pipelines, and subsea equipment require high-resolution shallow penetration data.
- Seafloor Mapping:Bathymetric and sub-bottom profiler surveys support cable routing and offshore wind site screening.
Revenue dominance rests with Hydrocarbon Exploration. Regulatory tailwinds favor Environmental Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage across South America favors Brazil's pre-salt corridor, where ANP production sharing agreements guarantee survey demand despite environmental compliance costs that operators accept as entry price for block qualification. Cost-of-compliance gaps between Brazilian federal licensing and Guyana's emerging framework are redirecting some frontier exploration capital northward along the Atlantic margin.
Brazil
ANP bid round acceleration drives 3D and 4D seismic procurement cycles, with Petrobras consortiums in Santos Basin specifying ocean bottom seismometer deployment for ultra-deepwater salt imaging. IBAMA environmental licensing constrains seasonal operational windows, forcing contractors to pre-position vessels ahead of regulatory approvals. Rio de Janeiro anchors the regional service hub, with vessel operators and processing houses clustering around the city's port infrastructure.
Guyana
ExxonMobil-operated discoveries offshore Guyana extend survey demand into underexplored Stabroek Block acreage, with 3D seismic preceding each development phase. The country's petroleum regulator mandates baseline environmental surveys before drilling permits, creating dual-revenue contracts combining exploration and compliance objectives. Georgetown serves as the logistics coordination center, with support vessels staging from Guyanese ports for campaigns extending into Suriname waters.
Suriname
Apache Corporation and TotalEnergies discoveries in Block 58 validate the petroleum system, accelerating 3D seismic acquisition for adjacent open blocks ahead of future bid rounds. The national oil company Staatsolie administers licensing frameworks that require seismic data submission for production sharing negotiations. Paramaribo hosts the administrative coordination, though vessel operations depend on cross-border supply chains from Trinidad and Tobago.
Uruguay
ANCAP's frontier licensing round in Punta del Este Basin attracts multi-client data library investment as operators seek first-mover positioning in untested acreage. The absence of established environmental licensing precedents creates regulatory uncertainty that contractors price into survey economics. Montevideo provides the onshore coordination point, with seismic vessels mobilizing from Argentine or Brazilian ports given limited domestic marine infrastructure.
Argentina
Offshore seismic activity concentrates in the North Malvinas Basin, where YPF and international partners evaluate extension of Vaca Muerta-equivalent source rocks into Atlantic waters. The national hydrocarbons secretary enforces data submission requirements that mirror Brazilian ANP standards. Mar del Plata functions as the operational base, with vessel support services and crew rotations managed through the city's port facilities.
South America Offshore Seismic Survey Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electromagnetic method specialization and autonomous marine system integration. The vendor base stratifies across three tiers: integrated energy service conglomerates controlling multi-client data libraries, independent seismic contractors competing on vessel availability, and technology boutiques unbundling processing from acquisition. Strategic archetypes include streamer-based volume operators, node-based premium specialists, and imaging algorithm developers. Competitive moves center on fleet repositioning ahead of ANP bid round announcements and processing workflow automation to compress turnaround timelines.
Among integrated service providers, Schlumberger Ltd and CGG SA exemplify contrasting strategic positions within the South America offshore seismic survey market. Schlumberger anchors integrated seismic-to-drilling workflows through Santos Basin contracts, representing the full-service archetype that bundles acquisition, processing, and interpretation. CGG SA occupies a specialized imaging position, with its technical reputation built on high-resolution velocity model building for complex salt geometries. PGS SA represents the multi-client library model, extending data coverage across Brazilian and Uruguayan waters through speculative survey investment ahead of licensing rounds.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger Ltd |
| CGG SA |
| PGS SA |
| BGP Inc |
| Fugro NV |
| SAExploration Holdings Inc |
| TGS ASA |
| Shearwater Geoservices |
| Others |
Value Network & Pricing Analysis
Dual-sensor streamer technology migration simultaneously compresses survey duration economics and concentrates procurement leverage among Norwegian and Singapore-flagged vessel operators capable of deploying integrated pressure-particle motion arrays. ANP's pre-salt qualification mandates create inelastic demand for high-specification acquisition, while limited global fleet availability transfers pricing power upstream to specialized contractors.
Pricing Analysis
Direct-to-operator contracting eliminates distributor margins, compressing price realization to vessel day-rates and processing workflow fees. Three-tier pricing structure across premium OBS node deployment, standard 3D streamer acquisition, and commoditized 2D reconnaissance reflects technical complexity gradients. Cost compression in 2D seismic intensifies as electromagnetic methods displace reconnaissance demand. Environmental agencies exhibit highest price sensitivity, while Petrobras consortiums accept premium OBS pricing for salt-proximity resolution.
Supply Chain Analysis
Node recovery and refurbishment flows anchor operational economics, with precision ROV retrieval cycles determining effective utilization rates for capital-intensive seabed equipment. Manufacturing concentration centers on Norway, Singapore, and the United States for specialized acquisition vessels and seismic sensor arrays. Supply chains draw from Japanese fiber-optic cable, German hydrophone components, and Dutch seismic processing software. Single-source vulnerability concentrates in ultra-deepwater ROV systems. Distribution runs through Rio de Janeiro service hubs and cross-border staging from Trinidad and Tobago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as pre-salt production sharing agreements guarantee recurring survey demand regardless of oil price cycles. ANP's technical mandate creates contractual floor volumes that stabilize contractor revenue visibility.
For Market Incumbents: To counter specialized vessel scarcity compressing seasonal windows, anchor multi-client library positions ahead of Uruguay's frontier licensing round and backward integrate into automated velocity model building to capture processing margin from unbundling trends. For New Entrants and Emerging Players: Launch via electromagnetic method specialization targeting Guyana-Suriname basin reconnaissance before operators commit to 3D seismic capital. Environmental monitoring contracts offer lowest competitive density for pure-play positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among independent processing boutiques with proprietary salt-velocity algorithms. The five-to-ten year viability thesis rests on 4D time-lapse recurring revenue maturation. Monitor ANP bid round frequency acceleration as inflection signal for fleet utilization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Pre-Positioning | Vessel operators staging in Santos Basin ahead of ANP announcements capture seasonal window economics. |
| Multi-Client Library Investment | Speculative survey coverage in Uruguay's Punta del Este Basin secures first-mover data ownership. |
| Processing Workflow Automation | Automated velocity model building compresses turnaround timelines for iterative pre-salt imaging. |
| OBS Node Fleet Expansion | Deepwater salt-proximity resolution commands premium pricing with limited global vessel availability. |
| Environmental Compliance Integration | Dual-revenue contracts combining exploration and IBAMA-mandated monitoring extend contract scope. |
Research Methodology
Multiple input streams — vessel operator utilization disclosures, ANP bid round documentation, and IBAMA licensing records — were reconciled against proprietary seismic tender databases and Petrobras procurement filings. Primary interviews with acquisition vessel fleet managers, seismic processing geophysicists, ANP regulatory affairs officers, and E&P project engineers were validated against customs data for seismic equipment imports, SEC filings from listed contractors, and industry association vessel tracking reports. Bottom-up vessel day-rate modeling and top-down market sizing triangulated volume estimates.
Data-stream reconciliation anchored forecast construction across service type, technology tier, and end-user segmentation dimensions. CAGRs were derived from contracted backlog analysis and licensing round schedule projections. Modeled inputs included ANP production sharing agreement seismic coverage mandates, pre-salt field development phase transitions, and electromagnetic method penetration rates in frontier basins.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IBAMA licensing delay scenarios and vessel mobilization disruptions. Forecasts reflect assumptions around regulatory schedule adherence and fleet availability without contingency for extreme weather compression. Practitioners should monitor ANP technical guideline revisions and OBS node manufacturing lead times for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Indonesia Oil and Gas Upstream Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Egypt Oil and Gas Downstream Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
South Sudan Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
LNG Satellite Station Market