
 Canada Oil and Gas Downstream Market | 2026-2036
Canada Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Oil and Gas Downstream Market Outlook
The marine end-user vertical is pivoting toward low-sulfur residual fuels and bunker fuel alternatives as international shipping rules tighten. Suncor Energy leverages its integrated refining and retail network to capture margin across the value chain. Imperial Oil sustains competitive positioning through technology leadership in synthetic crude processing at its Strathcona facility. Enbridge dominates midstream connectivity, controlling pipeline corridors that feed Ontario and Quebec demand centers.
Canada oil and gas downstream operations encompass refining crude oil into transportation fuels, heating oils, petrochemical feedstocks, and specialty products such as lubricants and asphalt, with typical refinery complexity measured by the Nelson Complexity Index ranging from 6 to 14 depending on coking and hydrocracking capacity. These facilities serve as the critical bridge between upstream extraction and end-use consumption across industrial, transportation, and residential sectors. The refined fuels product category anchors current revenue pools given established gasoline and diesel infrastructure, while petrochemicals represents the fastest-growing segment as Alberta's Heartland Petrochemical Complex expands ethylene and derivative output. Within applications, transportation maintains volume leadership though industrial demand is deepening as manufacturing reshoring initiatives strengthen Ontario and Quebec consumption.
Health Canada and Environment and Climate Change Canada jointly enforce the Clean Fuel Regulations, which mandate declining carbon intensity for liquid fuels and reshape refinery investment toward hydrogen addition and carbon capture retrofits. The Canadian Energy Regulator oversees pipeline tariffs and capacity allocation, directly influencing which refiners secure cost-competitive feedstock access. Provincial regulators in Alberta and Ontario layer additional emissions compliance requirements that filter equipment standards and operational permits. Stakeholders must monitor federal carbon price trajectory and provincial renewable fuel mandates to calibrate capital deployment between conventional refining upgrades and alternative fuel pathways.
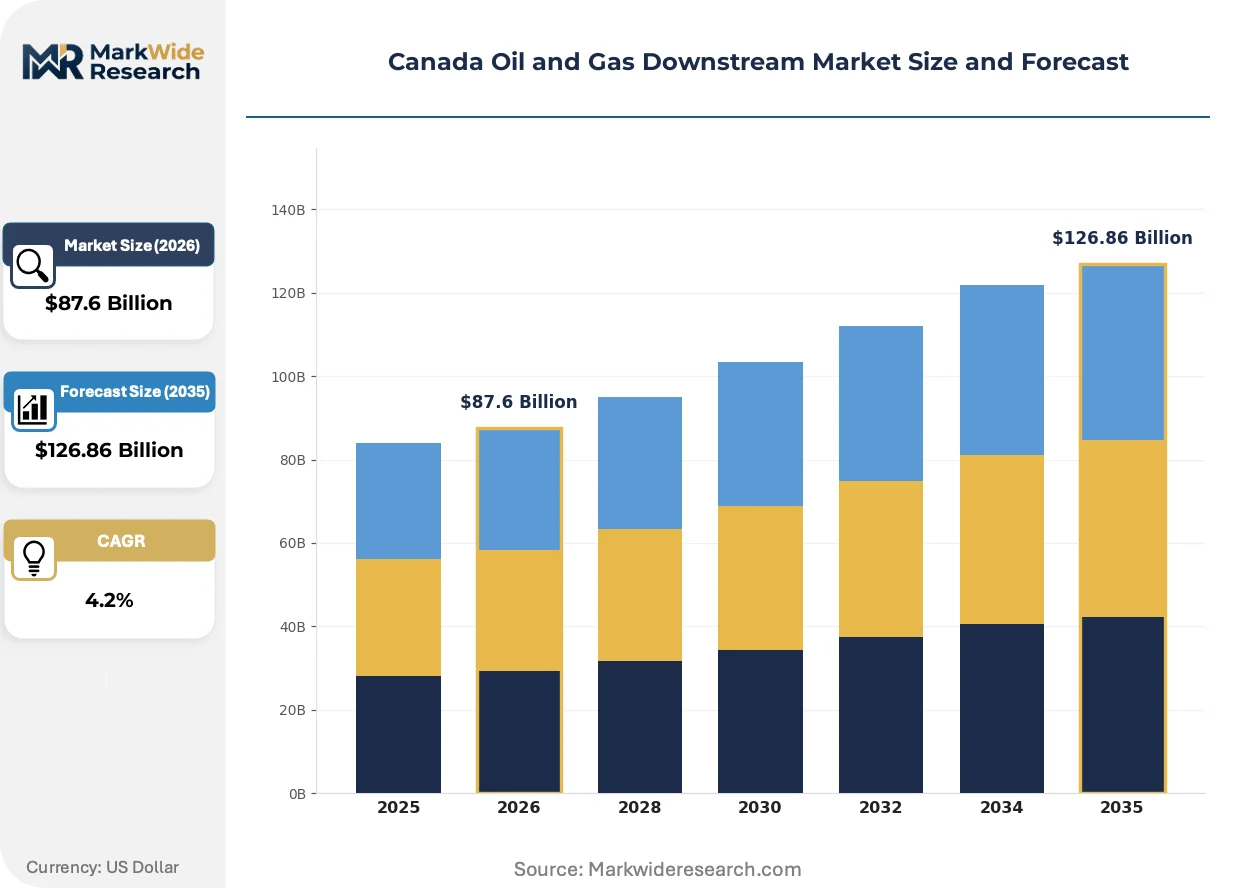
Market Dynamics
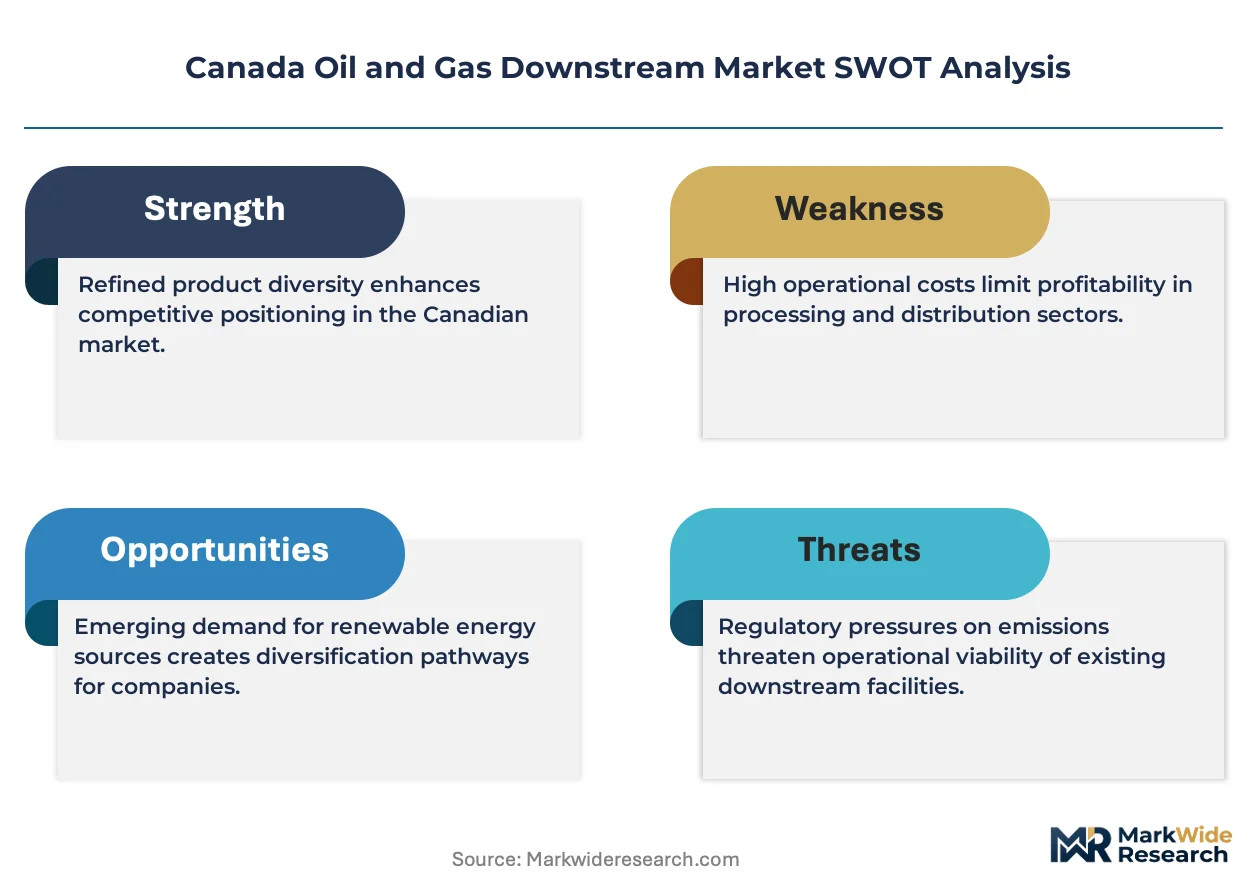
Canada's downstream oil and gas sector faces a structural squeeze between the Clean Fuel Regulations mandating carbon intensity reductions and the capital requirements of hydrogen addition and carbon capture retrofits at aging refinery infrastructure.
Growth Catalysts
- Clean Fuel Regulations:Federal mandates under Environment and Climate Change Canada force refiners toward low-carbon hydrogen and biofuel integration, creating compliant product premiums in Ontario and Quebec transportation corridors.
- Alberta's Heartland Petrochemical Complex:Ethylene and derivative capacity expansion pulls natural gas liquids into higher-margin chemical feedstocks, diversifying revenue beyond transportation fuels.
- Marine fuel switching:International Maritime Organization sulfur rules drive low-sulfur residual fuel demand through Vancouver and Atlantic Canada port infrastructure.
Market Restraints
- Western Canadian Select price volatility:Heavy crude discounts against WTI compress refining margins unpredictably, exposing operators to feedstock cost swings without corresponding product price adjustments.
- Pipeline capacity concentration:Enbridge's dominance over Alberta-to-Ontario corridors creates tariff leverage and bottleneck risk for independent refiners lacking integrated midstream assets.
- Carbon capture technical limitations:Post-combustion amine systems face energy penalty constraints above 60% capture rates, capping emissions reduction potential at complex refineries.
Strategic Opportunities
- Quebec biorefinery white space:Provincial renewable fuel mandates exceed current domestic production capacity, opening import substitution potential for agricultural feedstock processors.
- Synthetic crude integration:Alberta oil sands upgraders and Strathcona-area refiners can deepen synthetic crude processing integration, capturing margin across extraction and refining stages.
- Hydrogen hub convergence:Federal hydrogen strategy funding aligns with Alberta's carbon capture utilization and storage infrastructure, enabling blue hydrogen supply to Edmonton-area industrial clusters.
Industry Challenges
- Process control engineering scarcity:Specialized talent for hydrocracker and coker unit optimization retires faster than training programs replace capability, particularly at complex refineries in the Sarnia corridor.
- Clean Fuel Regulations compliance timeline:Refiners face compressed capital deployment windows to meet annual carbon intensity reduction benchmarks while maintaining operational uptime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Oil and Gas Downstream Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $126.86 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Petrochemicals, Lubricants, Asphalt Application: Transportation, Industrial, Residential, Commercial Distribution Channel: Retail Outlets, Bulk Supply, Direct Sales, Online Sales End User: Automotive, Manufacturing, Power Generation, Marine |
| Companies Covered | Parkland Fuel, TC Energy, Suncor Energy, Keyera, Enbridge, Imperial Oil, Pembina Pipeline Corporation, Superior Plus, Husky Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Oil and Gas Downstream Market Strategic Shifts
Refinery technology trajectories center on carbon intensity reduction hardware, regulatory compliance automation, and feedstock flexibility investments that reconfigure Alberta's synthetic crude processing advantage.
Electrolytic hydrogen production integrated with existing steam methane reformers is rewriting refinery hydrogen economics. Sarnia and Edmonton operators pilot solid oxide electrolyzer cell installations to displace gray hydrogen with grid-powered alternatives. This dual-feed approach is compressing the carbon intensity gap between conventional and renewable fuel pathways ahead of regulatory deadlines.
Environment and Climate Change Canada's Clean Fuel Regulations enforcement through 2030 tightens liquid fuel carbon intensity benchmarks annually. Refiners must document supply chain emissions through third-party verification or face market access restrictions. The transportation segment bears primary compliance burden, accelerating renewable diesel and ethanol blending infrastructure deployment across Ontario retail networks.
Industrial buyers in Alberta's petrochemical corridor now contract for certified low-carbon feedstocks through long-term offtake agreements rather than spot market purchases. This procurement consolidation shifts volume risk onto producers while guaranteeing supply security for polyethylene and derivative manufacturers. The pattern concentrates most visibly around the Heartland Petrochemical Complex north of Edmonton.
Canada Oil and Gas Downstream Market Segmentation
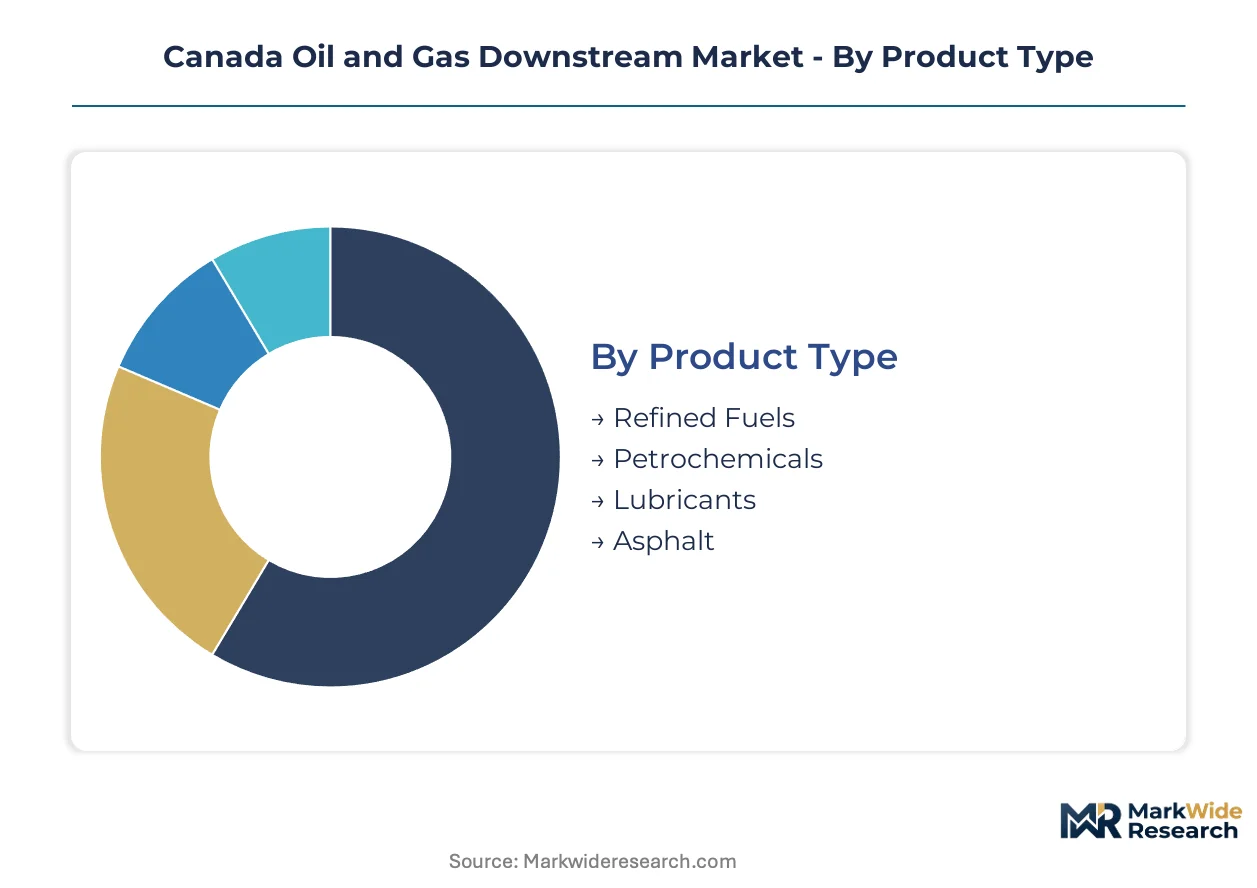
Downstream segmentation in Canada tracks how federal carbon intensity regulations and provincial feedstock advantages reshape product mix and channel economics. Refiners allocate capital across segments based on Clean Fuel Regulations compliance timelines and Alberta's Heartland Petrochemical Complex expansion trajectories.
Product Type:
Specification profiles determine margin capture potential as carbon intensity benchmarks tighten across federal compliance windows.
- Refined Fuels:Gasoline, diesel, and jet fuel formulations dominate current throughput at Sarnia and Edmonton refineries. Transportation demand in Ontario and Quebec corridors absorbs the majority of output, though carbon intensity reduction requirements are forcing hydrogen addition retrofits at aging coker units.
- Petrochemicals:Ethylene, propylene, and aromatic derivatives constitute the fastest-expanding product category. Alberta's Heartland Petrochemical Complex pulls natural gas liquids into higher-margin chemical feedstocks, diversifying revenue beyond transportation fuels as polyethylene manufacturers contract for certified low-carbon supply.
- Lubricants:Base oil blending and additive packages serve industrial maintenance schedules across manufacturing clusters. Premium synthetic formulations command compliance premiums under Environment and Climate Change Canada reporting requirements.
- Asphalt:Road construction binders and roofing materials track provincial infrastructure spending cycles. Seasonal demand concentration in Ontario and Quebec creates storage and logistics optimization priorities.
Mature deployment sits with Refined Fuels. Newer deployment is concentrated in Petrochemicals.
Application:
End-use intensity varies sharply across customer types, with industrial buyers consolidating procurement through long-term offtake structures.
- Transportation:Light-duty vehicle gasoline and heavy-duty diesel absorb the largest volume share. Federal Clean Fuel Regulations impose annual carbon intensity reduction benchmarks that accelerate renewable diesel and ethanol blending infrastructure deployment across Ontario retail networks.
- Industrial:Process heat, feedstock, and combined heat-and-power applications concentrate in Alberta's petrochemical corridor and Ontario manufacturing zones. Manufacturing reshoring initiatives strengthen consumption as buyers contract for certified low-carbon feedstocks rather than spot market purchases.
- Residential:Heating oil and propane serve rural and remote communities beyond natural gas pipeline reach. Atlantic Canada and northern Quebec maintain structural demand despite electrification incentives.
- Commercial:Fleet fueling, building heat, and backup generation span fragmented customer bases. Bulk supply contracts dominate procurement over retail channel purchases.
Transportation maintains volume leadership. Industrial applications are climbing the fastest as procurement consolidation shifts volume risk onto producers.
Distribution Channel:
Channel selection reflects customer scale and product specification requirements, with regulatory documentation driving integration between physical delivery and carbon accounting systems.
- Retail Outlets:Branded and unbranded service stations serve light-duty vehicle demand across Ontario and Quebec transportation corridors. Federal renewable fuel mandates require blending infrastructure that independent operators struggle to finance.
- Bulk Supply:Terminal-to-tanker deliveries serve industrial and commercial accounts with volume thresholds above retail economics. Enbridge pipeline connectivity determines which refiners secure cost-competitive feedstock access for bulk product manufacturing.
- Direct Sales:Refiner-to-end-user contracts bypass intermediaries for large industrial and marine accounts. Long-term offtake structures predominate in Alberta's petrochemical corridor.
- Online Sales:Digital procurement platforms for lubricants and specialty products serve fragmented commercial maintenance operations. Carbon intensity certification documentation integrates with enterprise purchasing systems.
Bulk Supply anchors current infrastructure investment. Direct Sales are gaining share fastest as procurement consolidation concentrates volume with integrated suppliers.
End User:
User segment requirements diverge on sulfur content specifications, carbon intensity certification, and delivery reliability standards.
- Automotive:Light-duty and heavy-duty vehicle fleets drive gasoline and diesel formulation requirements. Ontario and Quebec transportation corridors concentrate demand where pipeline infrastructure connects to export-ready refining capacity.
- Manufacturing:Petrochemical feedstocks, process heat, and combined heat-and-power applications span plastics, chemicals, and metals processing. Alberta's Heartland Petrochemical Complex expansion deepens synthetic crude integration for polyethylene production.
- Power Generation:Peaking plants and remote community diesel generation maintain residual fuel oil demand. Carbon intensity regulations accelerate displacement by natural gas and renewables in grid-connected markets.
- Marine:International Maritime Organization sulfur rules drive low-sulfur residual fuel and bunker fuel alternatives through Vancouver and Atlantic Canada port infrastructure. Scrubber-equipped vessels and LNG dual-fuel engines split compliance pathways.
Automotive maintains installed base dominance. Marine is expanding most quickly as port infrastructure adapts to international sulfur regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alberta produces the bulk of Canada's crude supply while Ontario and Quebec consume the majority of refined products, creating a continental pipeline dependency that shapes infrastructure economics.
Ontario
Transportation fuel demand concentrates in the Toronto-Windsor corridor where Sarnia-area refineries process Western Canadian Select into gasoline and diesel. The Clean Fuel Regulations enforce annual carbon intensity benchmarks that accelerate renewable diesel blending infrastructure deployment. Sarnia's petrochemical cluster deepens integration with Alberta feedstock via Enbridge's Line 9 reversal capacity.
Quebec
Provincial renewable fuel mandates exceed domestic production capacity, opening import substitution opportunities for agricultural feedstock processors. Environment and Climate Change Canada compliance documentation integrates with enterprise purchasing systems for industrial buyers. Montreal's port infrastructure adapts to low-sulfur marine fuel demand as International Maritime Organization rules tighten Atlantic shipping lanes.
Alberta
The Heartland Petrochemical Complex north of Edmonton expands ethylene and derivative output, pulling natural gas liquids into higher-margin chemical feedstocks. Federal hydrogen strategy funding aligns with provincial carbon capture utilization and storage infrastructure. Strathcona-area refiners process synthetic crude from oil sands upgraders, capturing margin across extraction and refining stages.
British Columbia
Vancouver's port infrastructure serves low-sulfur residual fuel demand from Pacific shipping routes transitioning under international sulfur regulations. Provincial clean fuel standards layer additional compliance requirements beyond federal benchmarks. Burnaby refinery operations balance domestic transportation supply with export-ready marine fuel formulations.
Atlantic Canada
Heating oil and propane maintain structural demand in rural communities beyond natural gas pipeline reach. Marine fuel switching drives bunker fuel alternatives through Halifax and Saint John port terminals. Regional refiners face compressed capital deployment windows to meet federal carbon intensity reduction timelines.
Canada Oil and Gas Downstream Market Competitive Environment
Top-tier vendors anchor integrated refining and midstream operations, while independent marketers and regional distributors occupy service-station and bulk-supply tiers. The vendor base stratifies around feedstock access, regulatory compliance capability, and retail network density. Three archetypes dominate: pipeline-integrated refiners capturing margin across extraction through distribution, petrochemical specialists leveraging Alberta natural gas liquids advantages, and fuel marketers optimizing last-mile logistics. Consolidation pressures concentrate around carbon capture retrofit requirements and renewable fuel mandate compliance costs.
Among integrated operators, Suncor Energy and Imperial Oil exemplify the refinery-retail network archetype, while Enbridge occupies a distinct position as midstream infrastructure gatekeeper. Parkland Fuel represents the independent marketer segment, optimizing distribution reach without captive production. These three anchors illustrate how Canadian downstream competition stratifies around asset integration depth rather than scale alone.
| Leading Market Players |
|---|
| Parkland Fuel |
| TC Energy |
| Suncor Energy |
| Keyera |
| Enbridge |
| Imperial Oil |
| Pembina Pipeline Corporation |
| Superior Plus |
| Husky Energy |
| Others |
Value Chain & Pricing Dynamics
Western Canadian Select crude discounts flow through Alberta upgraders and Ontario refineries, compressing margin capture at each processing stage while Enbridge pipeline tariffs layer fixed-cost pressure on independent operators lacking integrated midstream assets.
Pricing Analysis
Margin tightening in transportation fuels reflects Clean Fuel Regulations compliance costs that refiners cannot fully pass to Ontario and Quebec retail markets. Three-tier pricing structure across premium low-carbon formulations, standard blended products, and economy conventional grades separates certified supply from commodity spot. Carbon intensity certification premiums widen spreads as industrial buyers in Alberta's petrochemical corridor lock in long-term offtake structures. Independent marketers show highest price sensitivity, lacking hydrogen addition retrofit scale to absorb regulatory capital burdens.
Supply Chain Analysis
Domestic-content mandates under Environment and Climate Change Canada reporting requirements reshape feedstock sourcing toward Alberta synthetic crude and certified low-carbon natural gas liquids. Supply concentrates in Canada, with secondary dependencies on US Gulf Coast specialty additives and Asian catalyst suppliers. Pipeline capacity concentration creates single-source vulnerability for Ontario and Quebec refiners without alternative rail or marine receipt infrastructure. Distribution runs through Enbridge terminal networks feeding bulk supply contracts to industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pipeline bottleneck constraints prop pricing power for integrated operators while independent refiners face feedstock access rationing that concentrates margin capture upstream.
For Market Incumbents: Hedge carbon intensity exposure through hydrogen hub convergence at Edmonton-area industrial clusters, securing blue hydrogen supply ahead of federal funding allocation. Deepen synthetic crude integration with Alberta oil sands upgraders to capture margin across extraction and refining stages. Clean Fuel Regulations compliance timelines threaten operational uptime for aging coker units without retrofit investment. For New Entrants and Emerging Players: Digital procurement platforms for lubricants and specialty products bypass established terminal infrastructure, serving fragmented commercial maintenance operations with carbon intensity certification integration. Quebec biorefinery white space offers import substitution potential as provincial renewable fuel mandates exceed domestic production capacity. Agricultural feedstock processing angles align with certified low-carbon procurement consolidation trends. For Investors and Strategic Acquirers: Federal hydrogen strategy funding allocation is the leading indicator that blue hydrogen supply infrastructure will consolidate around Alberta carbon capture utilization and storage clusters. Five-to-ten year viability favors pipeline-integrated refiners with captive feedstock access over independent marketers exposed to tariff leverage. Target acquisition archetype: complex refineries with Nelson Complexity Index above 10 and existing coker-hydrocracker optimization capability.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Addition Retrofit | Strathcona-area refiners deploy solid oxide electrolyzer cells to displace gray hydrogen ahead of regulatory deadlines. |
| Carbon Capture Utilization and Storage Integration | Heartland Petrochemical Complex operators anchor emissions reduction claims in third-party verified supply chain documentation. |
| Long-term Low-carbon Feedstock Offtake | Polyethylene manufacturers shift volume risk onto producers through certified supply contracts at Edmonton industrial clusters. |
| Pipeline Capacity Lock-in | Enbridge Line 9 reversal secures cost-competitive Western Canadian Select access for Sarnia petrochemical processors. |
| Marine Fuel Formulation Certification | Vancouver and Atlantic Canada port infrastructure adapts to International Maritime Organization sulfur rules through low-sulfur residual supply. |
Study Parameters
Multi-period observation of refinery throughput rates, carbon intensity benchmarks, and pipeline utilization factors anchored the trend analysis, supplemented by interviews with refinery operations managers, hydrogen supply specialists, petrochemical procurement leads, and Environment and Climate Change Canada regulatory officers. Secondary validation drew from Canadian Energy Regulator pipeline filings, Alberta Energy Regulator production statistics, SEC 10-K disclosures from integrated operators, and Clean Fuel Regulations compliance documentation. Bottom-up segment sizing triangulated against top-down macroeconomic energy demand projections.
Segment-weighting applied product type, application intensity, and distribution channel economics across the modeling period, with refined fuels, petrochemicals, and lubricants carrying distinct margin and growth trajectories. CAGRs derived from historical throughput trends, regulatory compliance cost curves, and capital deployment schedules for hydrogen and carbon capture infrastructure. Industry-specific inputs included Nelson Complexity Index distributions across Canadian refineries and Western Canadian Select-WTI differential volatility patterns.
Inputs from refinery operations data and federal regulatory filings were available through the study window; gaps in real-time carbon capture performance metrics and private offtake contract terms introduce uncertainty bands around emissions reduction trajectory assumptions. Forecasts reflect documented assumptions regarding Clean Fuel Regulations enforcement intensity and hydrogen hub funding allocation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Floating Production System Sales Market
Offshore Oil and Gas
Floating Production Systems (FPS) Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Azerbaijan Oil and Gas Upstream Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Norway Oil and Gas Downstream Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Indonesia Oil and Gas Upstream Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market