
 Global Floating LNG Power Vessel Market | 2026-2036
Global Floating LNG Power Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Floating LNG Power Vessel Market Intelligence
Charter contract structures for offshore energy infrastructure is reconfiguring how floating LNG power vessels reach end users. Kawasaki Heavy Industries Ltd leverages its integrated shipyard and engine manufacturing footprint to control project timelines from hull fabrication through power system integration. Karadeniz Holding (Karpowership) anchors its competitive stance through long-term power purchase agreements with national utilities, sustaining fleet utilization across multiple basins simultaneously.
A floating LNG power vessel is a marine platform combining LNG storage, regasification, and power generation systems, typically featuring combined-cycle gas turbines with outputs ranging from 100 MW to 500 MW, designed to deliver electricity to shore via subsea cables without permanent onshore infrastructure. These units serve markets lacking grid connectivity or facing generation shortfalls from aging thermal plants. FSRU-based configurations dominate current deployment volumes owing to lower capital intensity and faster commissioning timelines, while power generation technology segments capture expanding margin pools as efficiency standards tighten. Remote power applications are gaining structural momentum across island economies and mining enclaves, displacing diesel-heavy alternatives.
The International Maritime Organization, the US Coast Guard, and classification societies including DNV govern vessel construction, LNG containment, and offshore safety protocols, with IMO 2020 sulfur caps directly stimulating LNG-fuelled power vessel orders. National regulators such as Indonesia's PLN and Brazil's ANEEL shape demand through offtake licensing and environmental permitting timelines. Stakeholders must monitor evolving carbon accounting rules for imported LNG and their impact on project finance eligibility.
Market Dynamics
IMO 2020 sulfur caps and the subsequent carbon intensity regulations are forcing power utilities toward LNG-fuelled marine infrastructure, creating procurement urgency across archipelago nations and remote coastal zones where grid extension costs remain prohibitive.
Growth Catalysts
- Indonesia's PLN licensing framework:The national utility's fast-track permitting for offshore power offtake contracts accelerates deployment timelines for floating LNG units serving Java-Bali grid extensions.
- Mining enclave electrification:Remote extraction operations in West Africa and Southeast Asia are replacing diesel-heavy generation with regasification-integrated power vessels to cut fuel logistics costs.
- Combined-cycle efficiency gains:Advances in gas turbine technology enable 500 MW outputs from single hull configurations, improving project economics for island nation utilities.
Market Restraints
- LNG price volatility:Henry Hub and JKM index fluctuations expose power purchase agreement counterparties to fuel cost pass-through disputes, complicating long-term contract structuring.
- Hull fabrication concentration:South Korean and Japanese shipyards control 80% of specialized LNG containment system construction, creating bottleneck risk for fleet expansion.
- Subsea cable technical limits:Current high-voltage direct current transmission technology caps economically viable shore distance at 15 kilometers for 500 MW units.
Strategic Opportunities
- Brazil's ANEEL distributed generation incentives:Regulatory frameworks for isolated system electrification open contracting pathways for FSRU-power hybrid vessels serving Amazon basin communities.
- Hydrogen-ready turbine retrofits:Dual-fuel gas turbine technology convergence positions existing LNG vessel hulls for ammonia or hydrogen blending without complete replacement.
- Power-as-a-service contracting:Utility customers in the Philippines and Indonesia increasingly favor availability-based tariffs over capital ownership, enabling fleet operators to retain asset control.
Industry Challenges
- Marine engineering talent scarcity:Specialized expertise in cryogenic containment system integration with power generation equipment concentrates among retiring shipyard workforces in Japan and South Korea.
- Classification society certification timelines:DNV and Bureau Veritas safety case reviews for novel hull configurations extend commissioning schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Floating LNG Power Vessel Market |
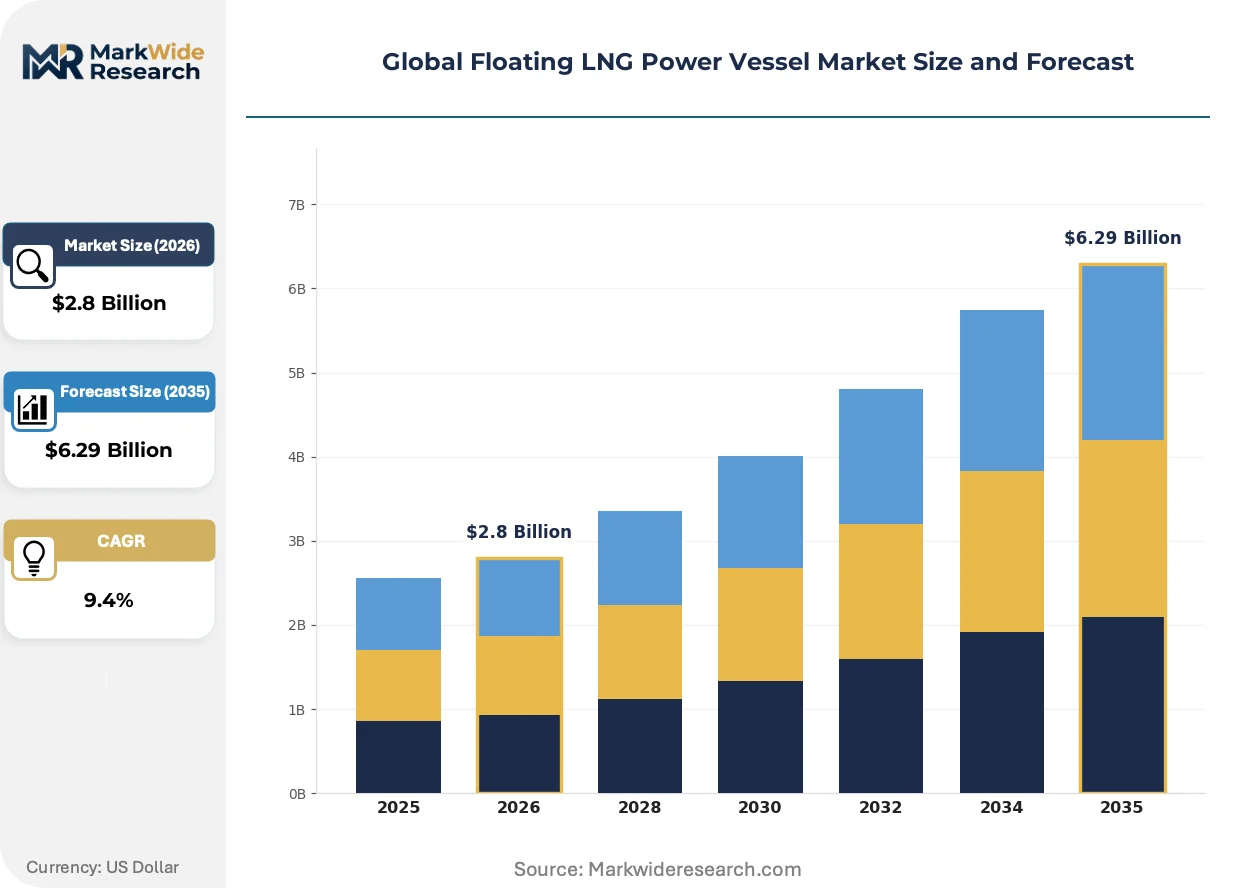
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: FSRU, FLNG, FSO, LNG Bunkering Vessel, FPSO Technology: Regasification, Liquefaction, Storage, Power Generation, Mooring Systems Application: Offshore Gas Supply, Peak Shaving, Marine Fuel Supply, Remote Power, Emergency Backup End User: Energy Producers, Shipping Companies, Utilities, Maritime Contractors, Port Authorities |
| Companies Covered | MODEC, Inc., Kawasaki Heavy Industries Ltd, Wärtsilä Corporation, Chiyoda Corporation, Wison Group, Karadeniz Holding (Karpowership), Samsung Heavy Industries, Mitsubishi Heavy Industries, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Floating LNG Power Vessel Market Strategic Shifts & Innovations
Digital twin technology and remote monitoring systems are compressing operational expenditure structures while regulatory carbon accounting rules reshape project finance eligibility criteria for fossil-fuelled infrastructure.
Integrated power management software is virtualizing vessel control architectures. Siemens Energy and Wärtsilä marine automation platforms enable shore-side operators to optimize turbine loading and regasification rates from land-based control centers. Indonesian and Brazilian utilities are adopting these systems fastest, cutting onboard crew requirements by 40% and enabling centralized fleet dispatch across multiple basins.
The EU Green Deal's carbon border adjustment mechanism is tightening emissions disclosure requirements for imported electricity. Power purchase agreements now incorporate lifecycle carbon intensity clauses that disadvantage coal-fired alternatives and advantage LNG-fuelled vessels with documented upstream methane leak controls. Southeast Asian offtakers are restructuring contract templates to preempt compliance costs.
Availability-based contracting is displacing traditional equipment sales across remote power markets. Mining operators in Guinea and Mozambique now specify kilowatt-hour delivery guarantees rather than turbine procurement, transferring operational risk to vessel owners. This compression of buyer capital deployment is accelerating fleet utilization rates for Karpowership and rival operators with established maintenance networks.
Global Floating LNG Power Vessel Market Segmentation
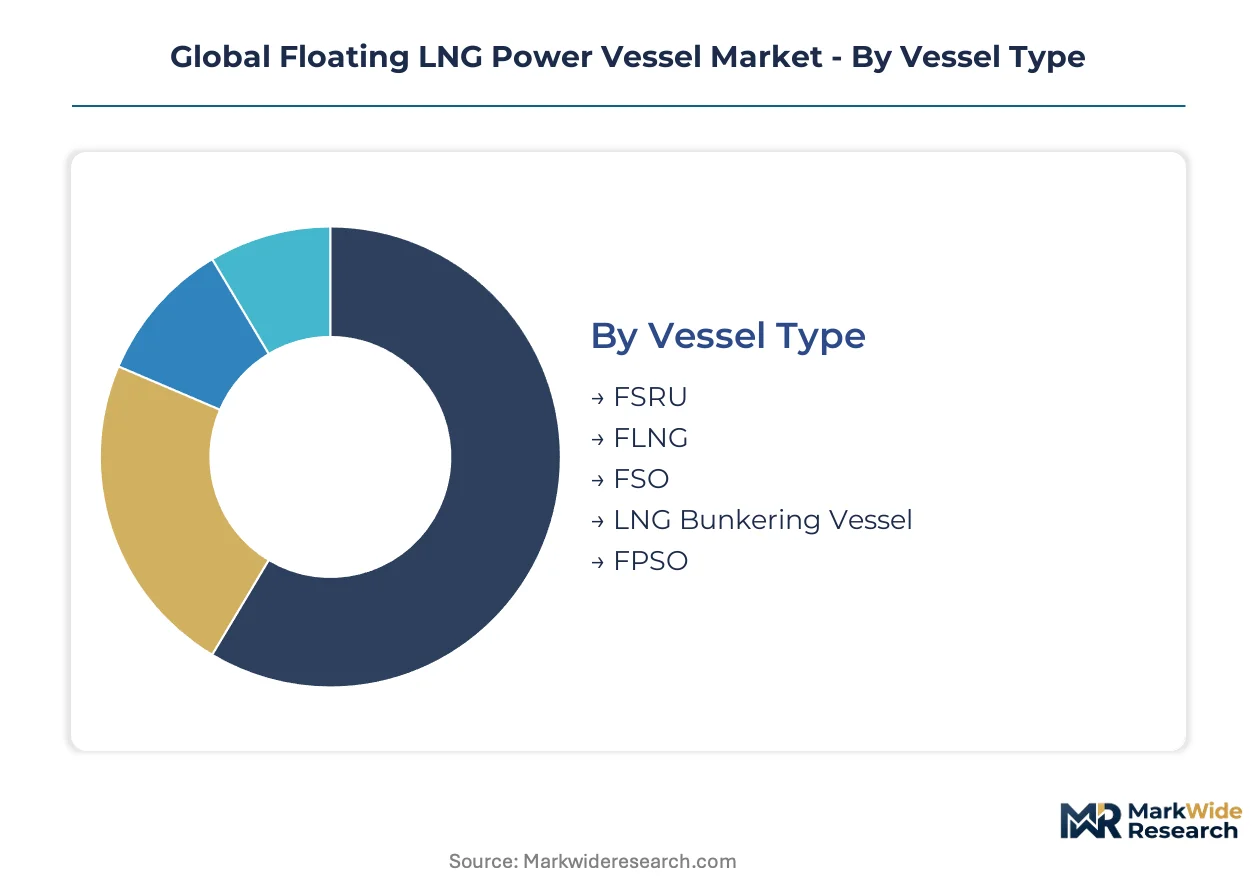
Floating LNG power vessels serve heterogeneous demand profiles across island grids, mining enclaves, and maritime logistics corridors. Segment boundaries reflect capital intensity trade-offs between regasification infrastructure and power generation equipment. Procurement patterns diverge sharply between utility offtakers seeking baseload capacity and industrial users prioritizing fuel security.
Vessel Type:
Cost tier differentiation separates turnkey power solutions from specialized storage and processing hulls.
- FSRU:Floating storage and regasification units integrate LNG containment with vaporization systems, enabling direct pipeline injection or power generation feed. Indonesian utilities and Brazilian distributors dominate procurement for coastal grid reinforcement, drawn by commissioning timelines under 18 months versus onshore terminal construction. Established volume favors FSRU; emerging adoption favors LNG Bunkering Vessel.
- FLNG:Floating liquefaction platforms convert associated gas or stranded reserves into exportable LNG, typically scaling above 2 million tonnes annual capacity. West African and Southeast Asian upstream operators commission these units where pipeline economics fail, though hull complexity extends delivery schedules to 48-60 months.
- FSO:Floating storage offloading vessels handle crude or condensate without processing capability, serving as buffer capacity for shuttle tanker operations in remote basins.
- LNG Bunkering Vessel:Purpose-built bunkering hulls deliver LNG to dual-fuel containerships and cruise liners at hub ports including Singapore, Rotterdam, and Shanghai.
- FPSO:Floating production storage and offloading units combine hydrocarbon processing with storage, occasionally retrofitted with power generation for host nation electricity offtake.
Volume concentration tilts toward regasification-integrated hulls; specialized liquefaction commands premium margins.
Technology:
Application maturity varies from commoditized storage systems to proprietary turbine integration packages.
- Regasification:Open-rack seawater vaporizers and submerged combustion units convert LNG to gaseous feed at rates matching turbine demand curves. Southeast Asian archipelago utilities specify regasification capacity as the binding constraint in power purchase negotiations.
- Power Generation:Combined-cycle gas turbine configurations now achieve 500 MW output from single hull architectures, displacing diesel-heavy alternatives in Guinea and Mozambique mining concessions. Established volume favors Regasification; emerging adoption favors Power Generation.
- Liquefaction:Single-mixed refrigerant and dual-mixed refrigerant processes dominate FLNG applications, with modular liquefaction trains enabling capacity phasing.
- Storage:Membrane containment systems from GTT and SPB independent tanks configure LNG inventory buffers sized to supply security requirements.
- Mooring Systems:Turret and spread-mooring architectures accommodate site-specific metocean conditions, with disconnectable turrets enabling typhoon evacuation in Pacific basin deployments.
Technology stacking favors integrated power-regasification packages over standalone processing modules.
Application:
Customer type fragmentation separates utility procurement from industrial self-supply and maritime fueling.
- Remote Power:Island nation grids and mining enclaves contract floating units under availability-based tariffs, eliminating capital deployment while securing baseload capacity. Indonesian PLN and Philippine cooperatives accelerate procurement where submarine cable extension costs exceed vessel charter economics. Established volume favors Remote Power; emerging adoption favors Marine Fuel Supply.
- Offshore Gas Supply:Pipeline replacement and peak shaving applications buffer seasonal demand swings in temperate coastal markets.
- Peak Shaving:Seasonal regasification capacity injects gas into constrained pipeline networks during winter demand spikes.
- Marine Fuel Supply:IMO 2020 sulfur regulations redirect containership and cruise liner newbuild programs toward LNG dual-fuel propulsion, expanding bunkering infrastructure demand at Singapore, Rotterdam, and Shanghai.
- Emergency Backup:Post-disaster grid restoration and wartime energy security drive ad hoc vessel mobilization under crisis contracting protocols.
Contract duration differentiates long-term utility power purchase agreements from spot marine fueling operations.
End User:
Procurement authority concentration varies from centralized state utilities to fragmented shipping operators.
- Utilities:National power companies in Indonesia, Brazil, and the Philippines negotiate sovereign-backed offtake contracts spanning 10-20 years, anchoring fleet utilization for Karpowership and rival operators.
- Energy Producers:Upstream operators charter FLNG and FPSO units under production sharing agreements, transferring reservoir risk to vessel owners.
- Shipping Companies:Containership liners and cruise operators contract LNG bunkering services at hub ports, specifying sulfur compliance and carbon intensity disclosure.
- Maritime Contractors:Offshore construction and drilling support vessel operators procure LNG fueling to meet charterer environmental criteria.
- Port Authorities:Singapore Maritime and Port Authority, Rotterdam Port Authority, and Shanghai International Port Group invest in shore-side LNG infrastructure to capture transshipment volume.
Utility procurement anchors long-term vessel deployment; shipping company demand drives bunkering infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian utilities command charter rate premiums exceeding West African counterparts by 15-20%, reflecting divergent LNG supply security and grid interconnection maturity. This pricing-power asymmetry concentrates fleet deployment decisions across Southeast Asian archipelagos and Atlantic basin coastal zones.
Indonesia
Java-Bali grid extension shortfalls and mine-mouth electrification needs in Sulawesi and Kalimantan drive vessel procurement. PLN's fast-track offshore power offtake licensing compresses permitting timelines to under 12 months. The Batam-Bintan industrial corridor anchors regasification-integrated power vessel deployments serving nickel processing enclaves.
Brazil
Amazon basin isolated system electrification and coastal industrial load growth create dual demand vectors. ANEEL's distributed generation incentives open contracting pathways for FSRU-power hybrid configurations. The Port of Açu complex in Rio de Janeiro state concentrates marine logistics infrastructure supporting vessel mobilization.
Philippines
Cooperative utility procurement and mining enclave electrification displace diesel-heavy generation across Visayas and Mindanao. The country's national power regulator shapes offtake licensing through rural electrification mandates. Batangas Bay and Subic Bay cluster vessel maintenance and crew transfer logistics.
Guinea
Bauxite mining corridor electrification and port power reliability gaps sustain charter demand. General functional descriptors for the country's national mining and energy regulator govern environmental permitting for offshore power infrastructure. The Kamsar-Boké industrial belt concentrates availability-based contracting for regasification-integrated units.
Singapore
IMO 2020 compliance bunkering infrastructure and regional vessel hub operations create dual revenue streams. The Maritime and Port Authority mandates sulfur emission disclosure and carbon intensity reporting for LNG fueling operations. The Tuas industrial zone anchors shore-side storage and regasification integration with power generation assets.
Global Floating LNG Power Vessel Market Key Industry Players
Integrated shipyard-turbine manufacturers and fleet-based power service providers split the market along capital ownership versus operational control lines. Japanese and South Korean shipyards dominate hull fabrication and LNG containment system integration, while Turkish and European operators specialize in long-term charter contracting and fleet dispatch optimization. Consolidation pressure concentrates among fabrication specialists seeking captive turbine supply, and among fleet operators expanding maintenance network coverage across multiple basins.
Among integrated Japanese industrial groups, Kawasaki Heavy Industries Ltd and Mitsubishi Heavy Industries occupy positions spanning hull fabrication through power system integration. Karadeniz Holding anchors the fleet-based power service archetype through its Karpowership operating unit. These three entities exemplify the structural divergence between manufacturing-centric and service-centric competitive strategies in floating LNG power vessel markets.
| Leading Market Players |
|---|
| MODEC, Inc. |
| Kawasaki Heavy Industries Ltd |
| Wärtsilä Corporation |
| Chiyoda Corporation |
| Wison Group |
| Karadeniz Holding (Karpowership) |
| Samsung Heavy Industries |
| Mitsubishi Heavy Industries |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
The Singapore-Rotterdam bunkering corridor channels cost volatility from LNG cargo arbitrage into vessel charter rate spreads, concentrating pricing power with South Korean and Japanese hull fabricators while forcing downstream differentiation between turnkey power packages and bare-hull regasification units.
Pricing Analysis
The customization-premium spread between configured-to-order FSRU-power hybrids and standard regasification hulls widens with turbine integration complexity. Contract-based long-term offtake structures dominate utility procurement, with price differentiation driven by certification tier from classification societies and geographic delivery distance from Asian shipyards. Cost compression in standard FSRU configurations is intensifying because Indonesian and Brazilian utilities are consolidating fleet orders into larger tranches. Mining enclaves in West Africa exhibit highest price sensitivity due to fuel cost pass-through exposure, while Japanese coastal utilities show lowest sensitivity given sovereign-backed payment guarantees.
Supply Chain Analysis
Upstream LNG feedstock sourcing from Qatar, Australia, and the United States anchors vessel economics to JKM and Henry Hub index movements. Cryogenic containment systems draw from GTT membrane technology and SPB independent tank designs, while combined-cycle gas turbines rest on supply relationships with Siemens Energy and Mitsubishi Power. Single-source vulnerability concentrates in South Korean and Japanese shipyard capacity for LNG carrier conversion. Distribution runs through EPC contractors managing hull delivery, turbine installation, and mooring system commissioning as integrated project packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across vessel type, technology stack, and end-use application creates multiple entry points, as power-as-a-service contracting shifts procurement authority from capital budgets to operational expenditure lines.
For Market Incumbents: Pre-empt margin erosion from hydrogen-ready turbine retrofits by securing exclusive maintenance networks across Indonesian and Brazilian basins. Anchor fleet utilization through 15-20 year sovereign-backed power purchase agreements before ammonia-blending standards reshape turbine specifications. Backward integration into cryogenic containment system fabrication reduces hull delivery exposure to South Korean shipyard bottlenecks. For New Entrants and Emerging Players: Pursue marine fuel supply infrastructure at secondary hub ports where Singapore and Rotterdam congestion creates queuing premiums. Target LNG bunkering vessel construction for containership operators facing IMO carbon intensity regulations, using classification society pre-certification as differentiation leverage. White-space exists in hydrogen-ready dual-fuel turbine integration for existing FSRU hull retrofits. For Investors and Strategic Acquirers: Fleet-based power service providers with established utility relationships and cross-basin maintenance infrastructure represent the most defensible acquisition archetype. Long-term viability hinges on contract duration visibility and fuel cost pass-through mechanics rather than technology differentiation. Watch for carbon border adjustment mechanism implementation in Southeast Asian electricity import markets as inflection signal for LNG versus ammonia fuel positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Consolidation | Indonesian PLN and Brazilian ANEEL offtake bundling reduces counterparty risk for fleet operators. |
| Hydrogen-Ready Turbine Retrofit Program | Ammonia blending compatibility future-proofs existing LNG hull assets against EU Green Deal carbon intensity clauses. |
| Classification Society Pre-Certification | DNV safety case advance approval compresses commissioning schedules by 8-14 months for novel hull configurations. |
| Cross-Basin Maintenance Network Expansion | Guinea and Mozambique mining corridor coverage enables availability-based tariff guarantees with operational risk transfer. |
| Digital Twin Platform Deployment | Siemens Energy and Wärtsilä marine automation integration cuts onboard crew requirements by 40% for Indonesian utilities. |
Research Approach
Desk research of EIA liquefaction capacity data, IEA gas market reports, and IMO regulatory filings preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists. Primary fieldwork across Southeast Asian archipelagos and Atlantic basin coastal zones combined with secondary validation from classification society certification records and power purchase agreement registries. Bottom-up vessel deployment tallies triangulated against top-down national electrification demand projections.
Assumptions held IMO carbon intensity regulations and LNG supply contract pricing mechanisms fixed, while varying national utility procurement timelines and mining enclave electrification schedules across the analysis window. Segmentation modeling incorporated vessel type, technology stack, application, and end-user procurement authority. CAGRs derived from regression against historical FSRU commissioning rates and projected island grid extension shortfalls, with inputs from gas turbine efficiency curves and subsea cable transmission economics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hydrogen infrastructure developers or ammonia turbine manufacturers would shift outcomes beyond modeled ranges. Cross-checking against IEA gas market outlooks and national utility integrated resource plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Turkmenistan Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Floating Production System Sales Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
LNG Satellite Station Market