
 Brazil Offshore Energy Market | 2026-2036
Brazil Offshore Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Offshore Energy Market Outlook
Integrated maintenance and life-of-field service contracts is restructuring how operators monetize offshore assets beyond initial extraction. Petrobras anchors Brazil's pre-salt development through its dominant position in ultra-deepwater operations. Equinor leverages its floating offshore wind expertise to diversify beyond oil into hybrid energy systems. Shell sustains competitive positioning through subsea technology leadership and extensive Santos Basin acreage.
Brazil offshore energy encompasses hydrocarbon extraction and renewable power generation in marine environments, typically operating at water depths exceeding 400 meters using tension-leg platforms, FPSO vessels, or floating wind turbines engineered to withstand Atlantic swell conditions. Its primary purpose is delivering reliable energy supply to industrial consumers and grid operators while accessing reserves unreachable through onshore or shallow-water development. Subsea systems and floating platforms command the largest current investment share, reflecting the technical demands of pre-salt geology at depths surpassing 2,000 meters. Renewable technologies and hybrid solutions represent the fastest-expanding technology category, driven by regulatory pressure and corporate decarbonization commitments among oil majors.
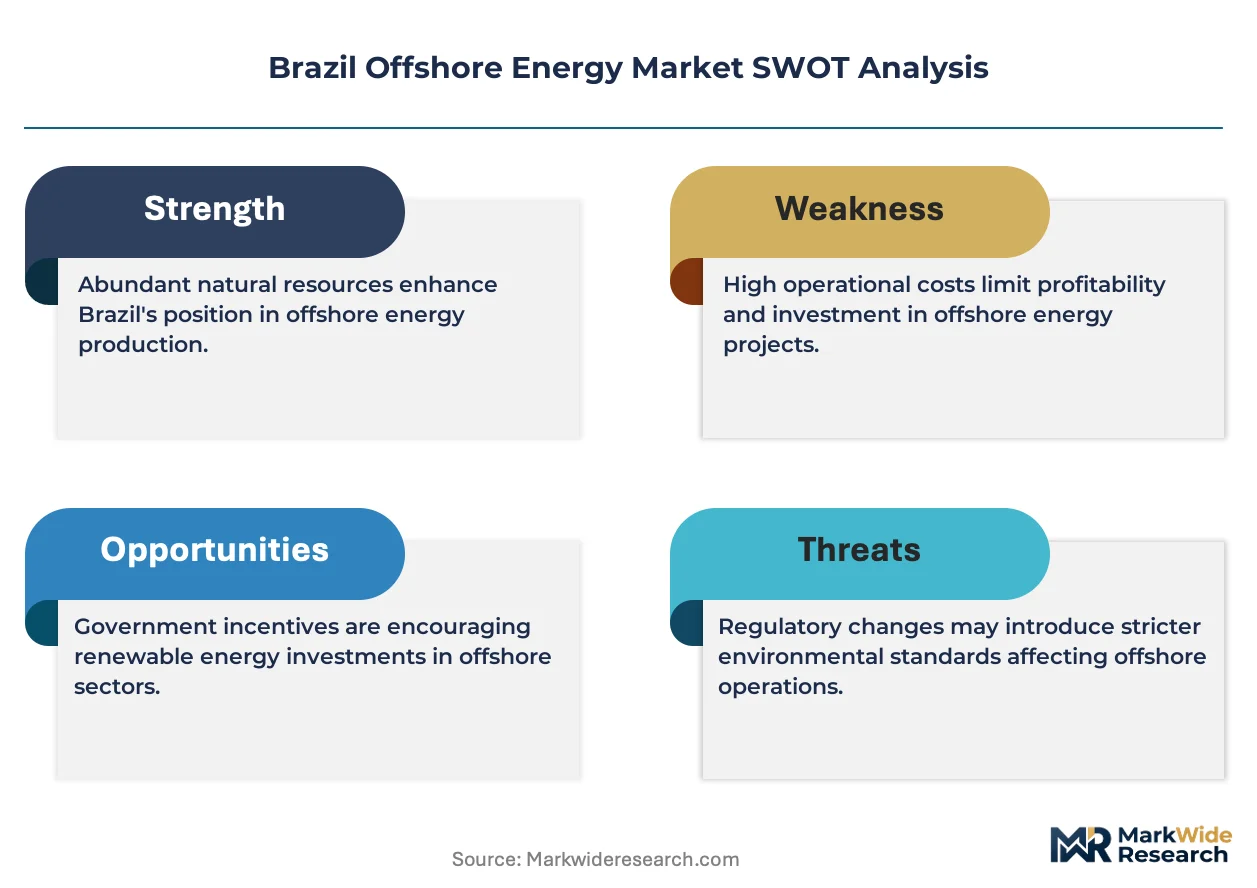
ANVISA environmental licensing requirements, ANP concession rounds, and IBAMA marine protection protocols collectively determine project approval timelines, equipment specifications, and operational constraints across Brazilian federal waters. These frameworks mandate local content thresholds, environmental impact assessments, and decommissioning guarantees that shape capital allocation decisions. Stakeholders must monitor regulatory evolution around floating wind permitting and pre-salt unitization agreements to anticipate competitive access shifts.
Market Dynamics
Pre-salt geology at depths exceeding 2,000 meters is absorbing the majority of capital deployment, forcing operators to restructure field development economics around floating production systems and subsea tiebacks rather than conventional platform architectures.
Growth Catalysts
- ANP Concession Rounds:Regular licensing cycles for ultra-deepwater blocks in the Santos Basin are accelerating exploration commitments and attracting international operator consortia to Brazilian federal waters.
- Pre-salt Cluster Development:Interconnected field architectures in the Santos Basin off São Paulo state are enabling shared infrastructure and reducing per-barrel development costs through economies of scale.
- Hybrid Energy Systems:Integration of offshore wind generation with existing oil and gas platforms is creating new revenue streams and decarbonization pathways for mature assets.
Market Restraints
- Local Content Mandates:ANP requirements for domestic equipment sourcing are inflating project costs and extending procurement timelines for specialized subsea components.
- Environmental Licensing Complexity:IBAMA marine protection protocols and ANVISA assessments are creating multi-year approval bottlenecks that compress productive asset windows.
- Steel and Alloy Volatility:Specialized metallurgy for high-pressure high-temperature reservoirs is exposing operators to raw material cost swings that erode project returns.
Strategic Opportunities
- Campos Basin Revitalization:Mature fields in Rio de Janeiro state present brownfield redevelopment potential through enhanced recovery and platform electrification.
- Floating Wind Permitting:Emerging regulatory frameworks for offshore renewable installations are opening lease opportunities in shallower Atlantic waters.
- Subsea Processing:Seabed separation and compression technologies are reducing topside footprint and enabling development of marginal pre-salt accumulations.
Industry Challenges
- Deepwater Engineering Talent Scarcity:Specialized expertise in tension-leg platform design and subsea architecture is concentrating among a limited pool of contractors, inflating labor costs.
- Legacy FPSO Integration:Retrofitting existing floating production vessels for carbon capture and power generation is creating technical conflicts with original safety systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Offshore Energy Market |
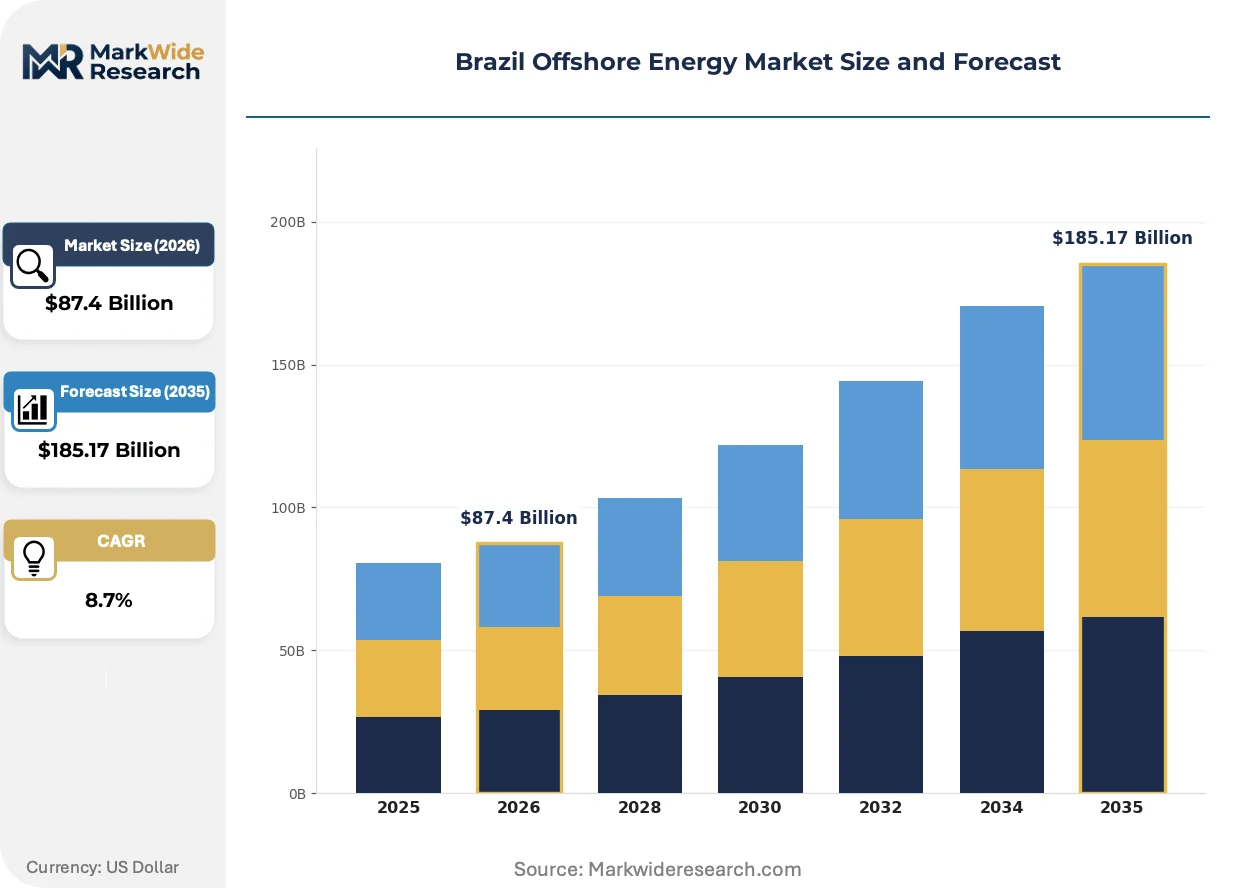
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Extraction, Transportation, Drilling Technology: Subsea Systems, Floating Platforms, Renewable Technologies, Hybrid Solutions End User: Utilities, Oil Companies, Industrial Sector, Government Agencies Installation: Onshore Installation, Offshore Installation, Modular Assembly, Maintenance Services |
| Companies Covered | Shell, Equinor, Petrobras, Enel Green Power S.p.A., TotalEnergies, Chevron Corporation, Repsol SA, Siemens Gamesa Renewable Energy SA, Exxon Mobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Offshore Energy Market Strategic Shifts
Digital twin deployment and autonomous subsea inspection are compressing operational expenditure profiles while extending field life. These capabilities are restructuring how operators manage reservoir performance and asset integrity across dispersed offshore installations.
Electrification of floating production platforms is absorbing capital from traditional diesel-powered systems. Petrobras and international partners are retrofitting existing FPSO vessels with shore power connections and offshore substations. This infrastructure shift is absorbing maintenance budgets previously allocated to generator overhauls and fuel logistics.
ANVISA environmental licensing requirements are mandating real-time marine ecosystem monitoring during drilling and production phases. Operators must deploy continuous water quality sensors and acoustic monitoring arrays as permit conditions. Deepwater projects in the Santos Basin are responding by integrating environmental data streams directly into operational control centers.
Integrated service contracting is displacing discrete equipment procurement across major developments. Operators now bundle drilling, completion, and subsea installation under single-vendor arrangements spanning multiple field phases. This consolidation is most visible in pre-salt developments where project complexity favors long-term partnership models over transactional purchasing.
Brazil Offshore Energy Market Segmentation
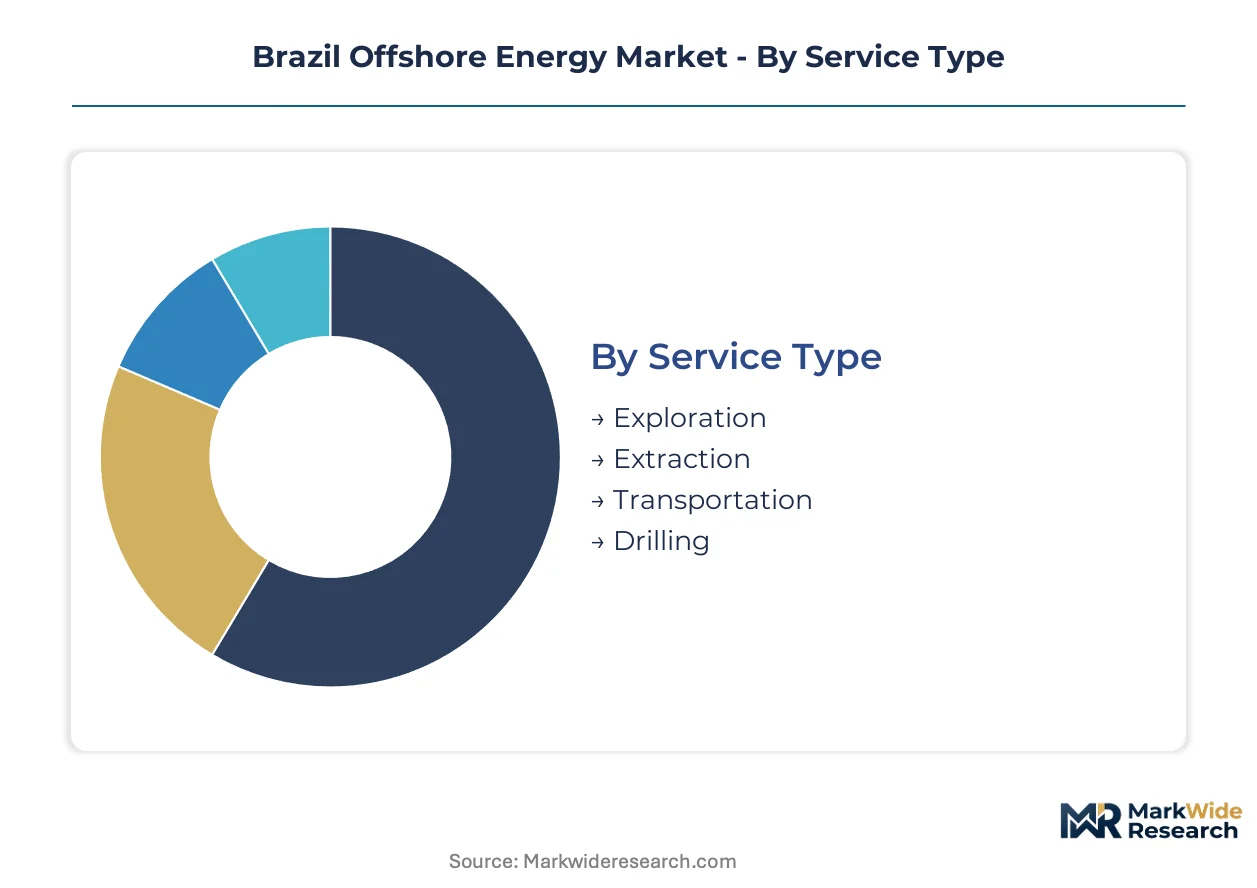
Segmentation in Brazil's offshore energy sector reveals how capital allocation priorities shift between mature hydrocarbon extraction and emerging renewable platforms. Each dimension exposes distinct procurement patterns, regulatory exposure, and technology upgrade cycles that reshape vendor relationships and project economics.
Service Type:
Replacement and upgrade cycles dominate service procurement as pre-salt fields mature and environmental licensing tightens operational windows.
- Exploration:Seismic acquisition and wildcat drilling programs target ultra-deepwater blocks in the Santos Basin. ANP concession rounds are driving demand for high-specification drillships capable of operating below 2,000 meters.
- Extraction:Subsea production systems and FPSO hookups constitute the largest revenue pool. Petrobras pre-salt commitments are sustaining long-term frame agreements for subsea tree installation and flowline connection.
- Transportation:Pipeline installation and shuttle tanker contracting link offshore production to coastal refineries. Local content mandates are forcing operators to source steel pipe from domestic mills despite cost premiums.
- Drilling:Extended-reach and managed-pressure drilling services address salt layer complexity. Rig availability constraints in Brazilian waters are extending dayrates and compressing drilling campaign windows.
Volume placements concentrate in Extraction; the faster expansion belongs to Exploration as frontier blocks advance toward development decisions.
Technology:
Cost tier differentiation separates proven subsea architectures from capital-intensive floating wind systems still seeking scale economies.
- Subsea Systems:Manifolds, risers, and flowlines form the backbone of pre-salt production. High-pressure high-temperature metallurgy requirements are concentrating supply among specialized fabricators with ANP certification.
- Floating Platforms:FPSO vessels, tension-leg platforms, and semi-submersibles dominate current deployment. Santos Basin operators are standardizing hull designs to reduce fabrication lead times and local content compliance costs.
- Renewable Technologies:Floating offshore wind turbines and wave energy converters represent emerging infrastructure categories. IBAMA marine protection protocols are creating permitting bottlenecks that delay first-mover projects.
- Hybrid Solutions:Integrated oil and gas platforms with offshore wind generation and battery storage are attracting pilot investments. Petrobras electrification roadmaps are mandating shore power connections that enable renewable hybridization.
Volume placements concentrate in Floating Platforms; the steepest expansion trajectory belongs to Hybrid Solutions as decarbonization commitments harden.
End User:
Customer type determines contract structure, with oil majors favoring integrated service frames and utilities seeking discrete equipment procurement.
- Utilities:Grid operators and power distributors are entering offshore wind lease competitions. ANEEL regulatory frameworks are defining offtake mechanisms that determine project bankability.
- Oil Companies:Integrated majors and independent operators anchor hydrocarbon investment. Petrobras dominates capital deployment through pre-salt unitization agreements and shared infrastructure commitments.
- Industrial Sector:Petrochemical complexes and mining operations consume offshore gas and power. Demand concentrates in São Paulo state industrial corridors with pipeline access to Santos Basin production.
- Government Agencies:ANP, IBAMA, and BNDES shape market access through licensing, environmental enforcement, and development financing. Local content thresholds and decommissioning guarantees flow from federal procurement mandates.
Volume placements concentrate in Oil Companies; the fastest share gains belong to Utilities as floating wind pipelines mature.
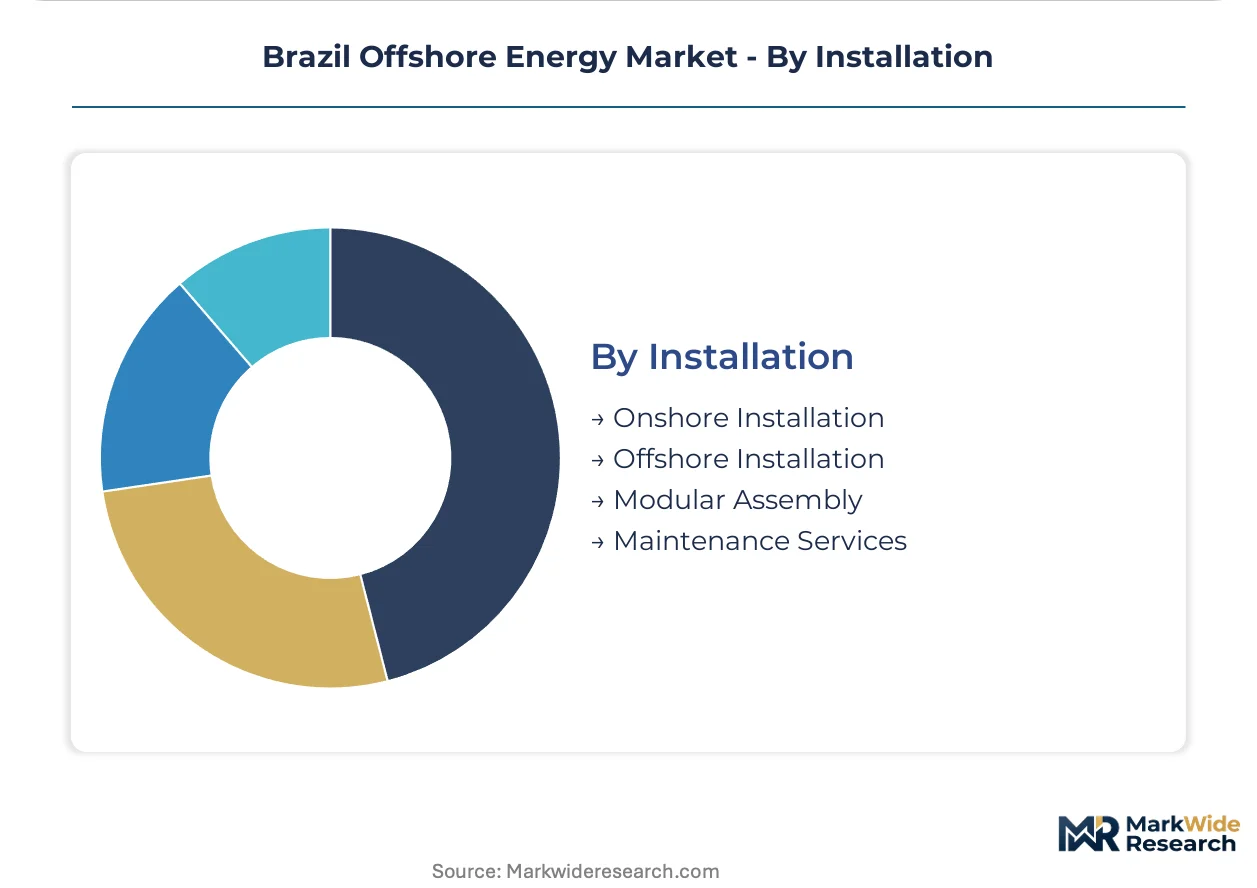
Installation:
Supply concentration in heavy-lift vessel availability is forcing operators to pre-book installation windows years ahead of first production.
- Onshore Installation:Module fabrication and pre-commissioning occur at coastal yards in Rio de Janeiro and Espírito Santo. Local content requirements are mandating domestic steel processing and labor utilization.
- Offshore Installation:Platform integration, hookup, and commissioning demand specialized marine spreads. Seasonal weather windows in the South Atlantic compress campaign durations and inflate dayrate costs.
- Modular Assembly:Standardized subsea component packages reduce offshore construction exposure. Fabricators are pre-assembling manifolds and jumpers to minimize offshore welding and testing.
- Maintenance Services:Life-of-field contracts cover inspection, repair, and equipment replacement. Digital twin deployment is shifting maintenance from calendar-based to condition-triggered interventions.
Volume placements concentrate in Offshore Installation; the most rapid expansion belongs to Maintenance Services as pre-salt assets age and integrity management intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity in Brazil's offshore basins outpaces coastal refining throughput, forcing operators to balance export commitments against domestic supply obligations. The Santos Basin pre-salt cluster absorbs capital while mature Campos fields require revitalization. State-level regulatory variation and local content mandates reshape project economics across federal waters.
São Paulo
Pre-salt hydrocarbon extraction dominates capital deployment in the Santos Basin cluster off São Paulo state. ANP concession rounds and ANVISA environmental licensing requirements compress development timelines for ultra-deepwater blocks. The São Paulo industrial corridor consumes offshore gas through pipeline networks serving petrochemical complexes and manufacturing facilities.
Rio de Janeiro
Campos Basin mature field operations and coastal fabrication yards concentrate activity in Rio de Janeiro state. IBAMA marine protection protocols mandate real-time ecosystem monitoring during drilling campaigns in environmentally sensitive Atlantic waters. The Macaé offshore services hub hosts maintenance contracts for aging FPSO vessels and subsea infrastructure.
Espírito Santo
Shallow-water legacy production and coastal module fabrication sustain Espírito Santo's offshore presence. Local content thresholds under ANP regulations force domestic steel sourcing from regional mills despite cost premiums. The Vitória metropolitan area anchors supply chain logistics for platform integration and pre-commissioning activities.
Rio Grande do Sul
Emerging floating wind lease opportunities attract utility investment to southern Atlantic waters beyond existing hydrocarbon infrastructure. ANEEL regulatory frameworks define offtake mechanisms for offshore renewable projects seeking grid interconnection. The Porto Alegre industrial base positions for turbine component manufacturing under evolving local content rules.
Bahia
Mid-Atlantic offshore blocks and potential hybrid energy pilot sites draw exploratory interest from diversified operators. BNDES development financing shapes capital access for projects requiring extended payback periods in frontier basins. The Camaçari petrochemical complex creates demand pull for offshore gas supply diversification.
Brazil Offshore Energy Market Competitive Environment
Capital-heavy integrated operators compete with asset-light service specialists and technology licensors across Brazil's offshore value chain. The market structure concentrates around a dominant national champion with international majors operating through consortium arrangements. Three archetypes define competitive positioning: state-backed integrated operators with concession control, international oil majors leveraging global technology portfolios, and renewable-focused utilities entering floating wind segments. Competitive moves center on pre-salt unitization negotiations and hybrid energy system partnerships that combine hydrocarbon extraction with electrification infrastructure.
Among international majors active in Brazilian federal waters, Shell, Equinor, and Petrobras exemplify distinct strategic archetypes. Shell occupies a position reflecting extensive Santos Basin acreage and subsea technology leadership. Equinor represents the offshore floating wind specialist diversifying beyond oil into hybrid energy configurations. Petrobras anchors the competitive structure through its dominant pre-salt unitization agreements and ultra-deepwater operational scale.
| Leading Market Players |
|---|
| Shell |
| Equinor |
| Petrobras |
| Enel Green Power S.p.A. |
| TotalEnergies |
| Chevron Corporation |
| Repsol SA |
| Siemens Gamesa Renewable Energy SA |
| Exxon Mobil Corporation |
| Others |
Value Chain & Pricing Dynamics
ANVISA environmental licensing mandates gate qualified supply access for subsea component fabricators and FPSO operators, with compliance costs feeding premium-tier pricing for pre-salt development contracts. Tier-one contractors commanding ANP-certified metallurgy capabilities extract margin premiums from operators facing compressed project timelines in the Santos Basin.
Pricing Analysis
Margin tightening in integrated service contracts reflects Petrobras frame-agreement consolidation and limited qualified vendor pools for high-pressure high-temperature systems. Project-based long-term offtake structures dominate, with price differentiation hinging on ANP local content certification tiers and after-sales life-of-field service bundling. Cost-down pressure accelerates as international operators benchmark Brazilian procurement against Gulf of Mexico and West African deepwater economics. Independent operators exhibit highest price sensitivity; Petrobras anchors premium-tier absorption through scale commitments.
Supply Chain Analysis
Specialized welder and subsea engineer scarcity in Rio de Janeiro and Espírito Santo coastal yards extends fabrication lead times and inflates labor premiums. Supply concentrates in Brazil, South Korea, and Singapore for FPSO hull construction and subsea tree manufacturing. Raw material dependencies span high-grade steel plate from domestic mills, nickel alloy forgings from European specialty foundries, and subsea control systems from Norwegian technology licensors. Single-source vulnerability concentrates in tension-leg platform tendon fabrication. Distribution runs through Macaé and Vitória logistics hubs to offshore installation vessels pre-booked under multi-year charter agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy-lift vessel and specialized drillship availability constraints prop pricing power for qualified contractors across the Santos Basin pre-salt cluster. Capacity bottlenecks in ANP-certified fabrication yards sustain premium capture for incumbent service providers.
For Market Incumbents: Anticipate floating wind hybridization threats from Equinor and utility entrants by securing exclusive platform electrification partnerships with Petrobras. Defend subsea technology margins through backward integration into seabed processing module manufacturing. Prioritize ANVISA real-time monitoring certification investments to preempt regulatory compliance arbitrage by emerging competitors. For New Entrants and Emerging Players: Brownfield Campos Basin operators represent an underserved buyer archetype seeking enhanced recovery and platform electrification without pre-salt capital intensity. Target Rio de Janeiro state maintenance and integrity management contracts where incumbent labor costs have inflated. Pursue modular subsea component pre-assembly positioning to minimize offshore construction exposure and local content compliance burden. For Investors and Strategic Acquirers: First ANEEL floating wind lease auction awards are the leading indicator that utility capital allocation is shifting toward Atlantic renewable infrastructure. Long-term viability favors asset-light technology licensors and hybrid system integrators over capital-heavy FPSO owner-operators. Monitor IBAMA marine protection protocol enforcement intensity as the signal for regulatory risk repricing in hydrocarbon-exposed portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| FPSO Electrification Retrofit | Petrobras shore power commitments enable renewable hybridization and carbon intensity reduction. |
| Subsea Processing Technology Licensing | Seabed compression capabilities unlock marginal pre-salt accumulations previously below economic threshold. |
| Floating Wind Lease Acquisition | ANEEL framework clarity positions first-movers for grid interconnection priority in southern Atlantic waters. |
| Integrated Service Contract Consolidation | Multi-phase drilling-to-production bundling reduces operator procurement friction and vendor transition risk. |
| Digital Twin Platform Deployment | Real-time reservoir performance monitoring shifts maintenance from calendar to condition-triggered interventions. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Brazil offshore energy assessment. Primary interviews with Petrobras project planners, ANP licensing officers, FPSO contractor procurement leads, and IBAMA environmental enforcement specialists cross-validated operational assumptions. Secondary sources included ANP concession round documentation, BNDES development financing disclosures, and subsea equipment import manifests. Bottom-up field development cost modeling reconciled against top-down basin-level capital deployment tracking.
Reconciling vessel dayrate indices, steel price benchmarks, and rig availability curves shaped the analytical framework across the projection horizon. Segmentation dimensions spanned service type, technology category, end-user archetype, and installation phase. CAGRs derived from weighted average of operator capex guidance, contractor backlog disclosures, and regulatory schedule visibility. Forecast inputs incorporated ANVISA licensing timeline probability distributions and ANP local content threshold evolution scenarios.
Revisions become necessary when ANP concession round cancellations, IBAMA marine sanctuary designations, or Petrobras capital allocation redirection materialize outside baseline assumptions. Material deviation in these triggers warrants pause and re-evaluation of basin-level deployment schedules and vendor contract viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Marine Seismic Equipment and Acquisition Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Subsea Production and Processing System Market