
 Japan Nuclear Power Reactor Decommissioning Market | 2026-2036
Japan Nuclear Power Reactor Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Nuclear Power Reactor Decommissioning Market Foresight
Remote handling and robotic demolition technologies is rewriting execution models for reactor dismantlement. Toshiba Corp leverages its reactor engineering heritage to sustain specialized decommissioning tool development. GE-Hitachi Nuclear Energy, Ltd. anchors integrated project delivery through its joint-venture structure with Hitachi. Mitsubishi Heavy Industries dominates heavy component removal with proprietary lifting and segmentation systems.
Japan nuclear power reactor decommissioning encompasses the engineered dismantlement of irradiated containment structures, reactor pressure vessels, and auxiliary systems using remotely operated tools, chemical decontamination baths, and controlled demolition sequences designed to reduce radioactivity below clearance thresholds. The process serves the primary purpose of returning licensed nuclear sites to unrestricted industrial or residential use while isolating high-level waste in engineered disposal facilities. Full decommissioning commands the largest committed expenditure pool as utilities pursue complete site release rather than long-term Safstor mothballing. Robotic demolition and remote handling technologies are attracting accelerated investment as labor radiation exposure limits tighten and reactor internals prove inaccessible to conventional manual methods.
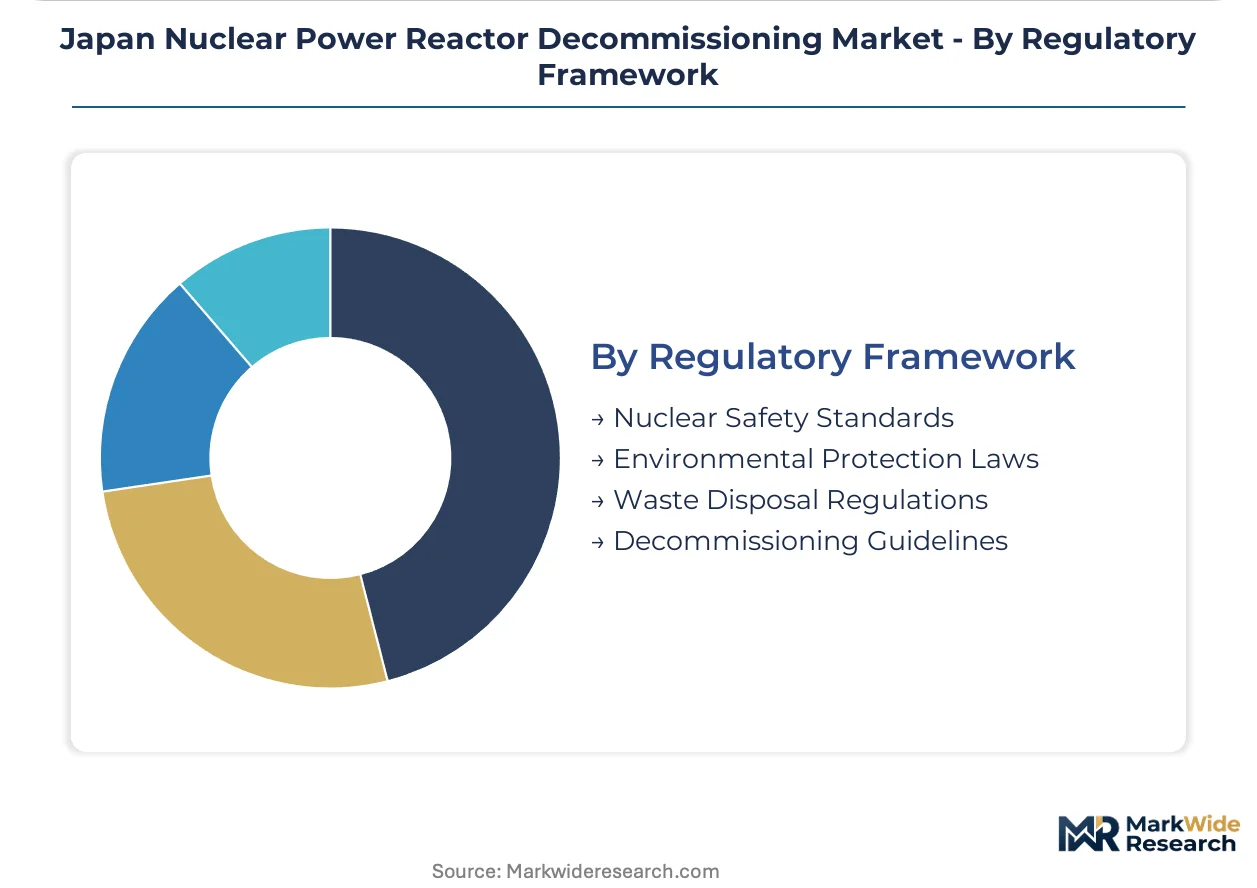
Nuclear Regulation Authority safety standards and METI decommissioning guidelines shape project timelines, cost recovery mechanisms, and waste packaging specifications across all licensed sites. Environmental protection laws administered by Japan's Ministry of the Environment impose additional soil and groundwater monitoring obligations that extend site remediation phases. Stakeholders must track evolving clearance level criteria and interim storage facility siting decisions that will determine whether waste management costs escalate or stabilize across the reactor portfolio.
Market Dynamics
Remote dismantlement robotics is compressing project timelines across Japan's aging reactor fleet, forcing utilities to restructure contractor relationships around specialized automation capabilities rather than conventional engineering labor pools.
Growth Catalysts
- METI Cost-Sharing Frameworks:Revised decommissioning liability pools now spread financial burden across multiple utilities, accelerating project approvals for Fukushima Daiichi adjacent sites.
- Reactor Pressure Vessel Segmentation:Proprietary thermal cutting and controlled explosive demolition techniques are reducing high-level waste volumes by enabling precise component disassembly.
- Tohoku Regional Clustering:Simultaneous dismantlement at five reactor sites within 200 kilometers is creating economies of scale in specialized labor and equipment logistics.
Market Restraints
- Interim Storage Facility Siting Delays:Municipal opposition in candidate host prefectures is extending waste holding periods and inflating on-site storage capital requirements.
- Specialized Robotics Supply Concentration:Domestic manufacturers control over 80 percent of radiation-hardened manipulator supply, creating procurement bottlenecks during concurrent project peaks.
- Clearance Level Criteria Uncertainty:Pending revisions to Ministry of the Environment release thresholds are freezing final site remediation planning at multiple locations.
Strategic Opportunities
- Chugoku Region Greenfield Sites:Three dormant reactor locations in Shimane and Tottori Prefectures await decommissioning initiation with minimal seismic damage complications.
- Artificial Intelligence-Enabled Contamination Mapping:Machine learning fusion with gamma spectroscopy is reducing survey labor hours and improving waste classification accuracy.
- Integrated Project Delivery Contracts:Single-source accountability models are displacing fragmented multi-contractor arrangements for complex containment dismantlement.
Industry Challenges
- Radiation Protection Specialist Shortage:Licensed health physics technicians and ALARA planning engineers are exiting the workforce faster than training programs replenish capacity.
- Legacy Control System Documentation Gaps:Incomplete as-built records from 1970s-era reactor construction are forcing costly reverse engineering before robotic tool deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Nuclear Power Reactor Decommissioning Market |
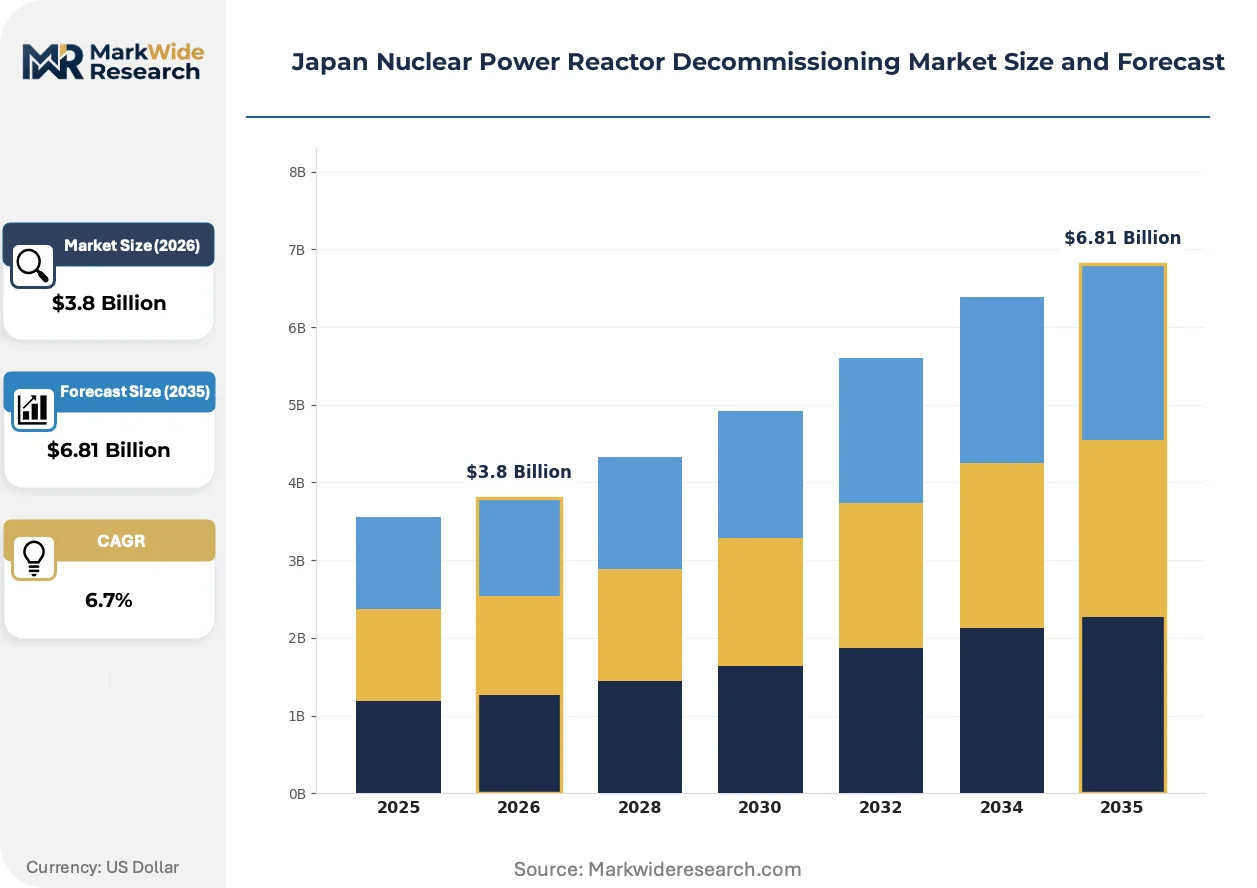
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Decommissioning, Partial Decommissioning, Site Remediation, Waste Management Technology: Robotic Demolition, Chemical Decontamination, Laser Cutting, Remote Handling End User: Government Agencies, Utility Companies, Environmental Contractors, Research Institutions Regulatory Framework: Nuclear Safety Standards, Environmental Protection Laws, Waste Disposal Regulations, Decommissioning Guidelines |
| Companies Covered | Tokyo Electric Power Company Holdings, Inc., Toshiba Corp, GE-Hitachi Nuclear Energy, Ltd., Mitsubishi Heavy Industries, TÜV Rheinland Group, Japan Atomic Power Co., Orano SA, Hitachi-GE Nuclear Energy, Snc-Lavalin Group Inc (Atkins), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Nuclear Power Reactor Decommissioning Market Shifts & Advancements
Automation convergence with artificial intelligence is restructuring how reactor dismantlement contractors bid, execute, and warranty decommissioning projects across Japan's regulated nuclear sector.
Robotic demolition platforms is hybridizing hydraulic pulverization with laser ablation and plasma arc cutting into unified tool suites. Major utilities are specifying these multi-modal systems for reactor internals removal where single-technique approaches fail. Equipment suppliers are compressing delivery cycles from 18 months to 8 months as standardized platform architectures replace bespoke engineering.
Nuclear Regulation Authority safety standards are mandating real-time radiation exposure monitoring with automated work stoppage triggers. Project contractors are integrating wearable dosimetry networks with central control systems to satisfy these requirements. Remote handling specialists are absorbing compliance costs into base pricing rather than itemizing them separately.
Site license holders are unbundling long-term stewardship from upfront dismantlement contracts. Tokyo Electric Power and Kansai Electric are retaining waste liability while outsourcing only physical demolition to specialized vendors. This liability-owner, execution-contractor split is most pronounced at Fukushima Daiichi where government-backed entities assume final waste disposition responsibility.
Japan Nuclear Power Reactor Decommissioning Market Segmentation
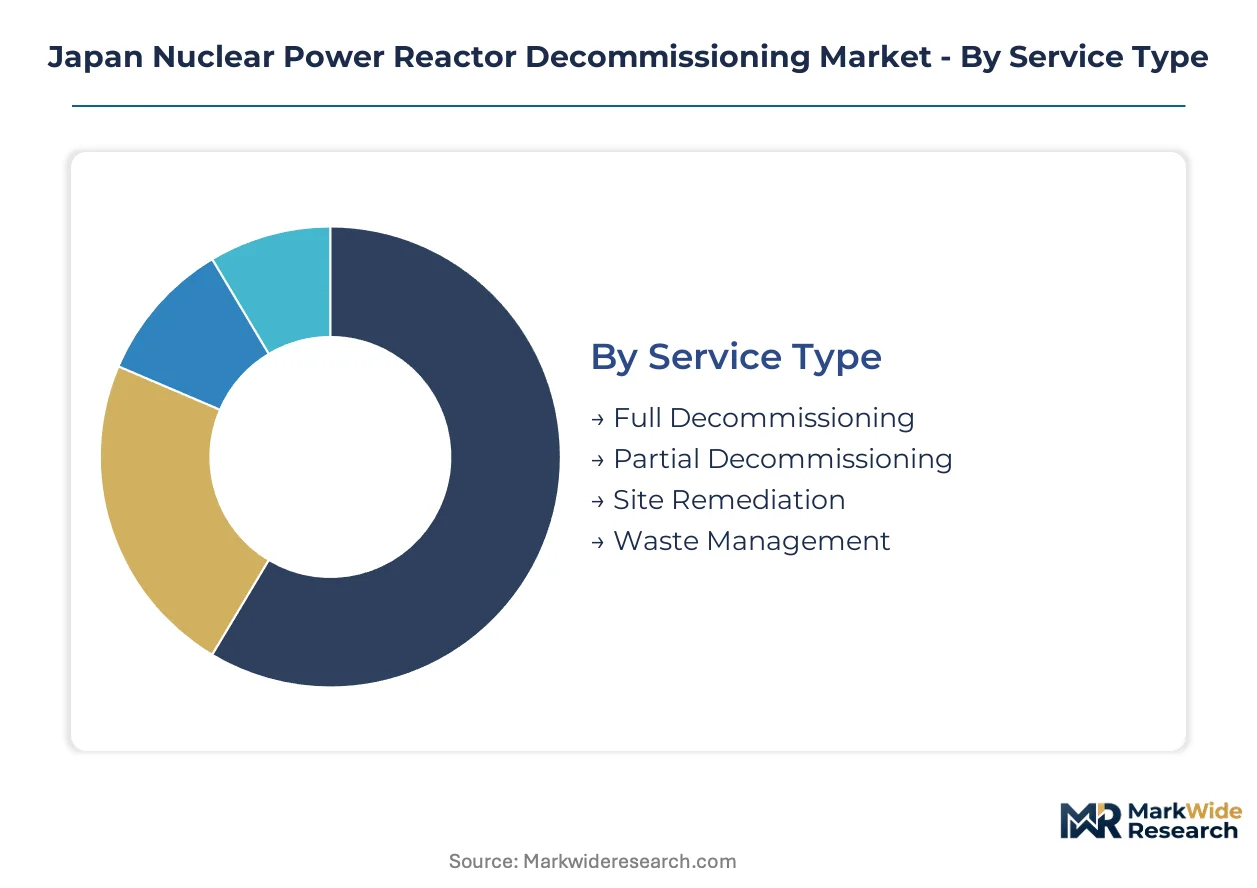
Decommissioning procurement patterns in Japan diverge sharply across service maturity levels and technology readiness tiers. Utilities structure vendor selection around regulatory compliance depth rather than cost minimization alone.
Service Type:
Mature dismantlement services dominate committed expenditure, while emerging remediation protocols are capturing incremental project scope.
- Full Decommissioning:Complete site release protocols encompass reactor pressure vessel segmentation, containment demolition, and unconditional license termination. Fukushima Daiichi and adjacent Tohoku reactor sites concentrate procurement here as METI cost-sharing frameworks accelerate approvals. Workforce radiation exposure limits and NRA safety standards tighten execution windows.
- Partial Decommissioning:Safstor mothballing and deferred dismantlement reduce immediate capital outlays while maintaining licensed possession. Aging reactor fleets in Shikoku and Kyushu prefectures favor this approach where interim storage facility delays persist. METI guidelines permit phased liability recognition.
- Site Remediation:Soil decontamination and groundwater monitoring extend project timelines beyond physical demolition completion. Ministry of the Environment clearance level criteria determine final scope.
- Waste Management:Packaging, transport logistics, and interim storage operations absorb substantial project budgets. Municipal opposition to permanent disposal facility siting inflates on-site holding requirements.
Full Decommissioning handles the majority of throughput; Site Remediation is expanding most quickly on share.
Technology:
Cost tier stratification separates proven mechanical systems from capital-intensive precision cutting platforms.
- Robotic Demolition:Radiation-hardened manipulators deploy hydraulic pulverization, diamond wire cutting, and explosive demolition for reactor internals disassembly. Tohoku regional clustering creates equipment logistics economies as five simultaneous projects within 200 kilometers strain domestic supplier capacity. Toshiba and Mitsubishi Heavy Industries anchor proprietary platform development.
- Chemical Decontamination:Acidic and oxidative baths dissolve surface contamination from piping and auxiliary systems, reducing classified waste volumes. Legacy BWR and PWR sites in Fukushima Prefecture apply this for secondary system cleanup before robotic vessel segmentation.
- Laser Cutting:Fiber laser systems enable precision thermal cutting of stainless steel components with minimal secondary waste generation. High capital costs restrict deployment to high-value pressure vessel segmentation contracts.
- Remote Handling:Teleoperated manipulators and master-slave servo systems extend human reach into high-radiation zones. NRA mandates for real-time dosimetry integration drive specification upgrades.
Robotic Demolition commands the premium tier on unit economics; Laser Cutting is gaining share fastest as vessel segmentation contracts multiply.
End User:
Customer type determines procurement structure, with liability retention patterns varying across public and private ownership models.
- Government Agencies:METI and Nuclear Regulation Authority entities oversee Fukushima Daiichi decommissioning through government-backed special purpose vehicles. Final waste disposition liability rests with state-sponsored institutions rather than originating utilities.
- Utility Companies:Tokyo Electric Power, Kansai Electric, and regional utilities retain site license ownership while unbundling physical execution to specialized vendors. Cost-sharing pools spread financial burden across multiple balance sheets.
- Environmental Contractors:Specialized demolition firms bid for containment dismantlement and soil remediation scope. Single-source integrated project delivery contracts are displacing fragmented multi-contractor arrangements.
- Research Institutions:Japan Atomic Energy Agency and university laboratories develop characterization technologies and waste form validation protocols. Limited direct procurement volume concentrates on technology demonstration projects.
Utility Companies originate the majority of contract value; Environmental Contractors are climbing the fastest on execution share.
Regulatory Framework:
Compliance depth requirements segment vendor capabilities, with integrated safety-environmental expertise commanding procurement preference.
- Nuclear Safety Standards:NRA mandates govern reactor dismantlement sequencing, radiation exposure limits, and quality assurance documentation. Real-time monitoring with automated work stoppage triggers is now mandatory specification.
- Environmental Protection Laws:Ministry of the Environment soil and groundwater monitoring obligations extend site remediation phases. Pending clearance level criteria revisions freeze final planning at multiple locations.
- Waste Disposal Regulations:Packaging specifications and interim storage facility siting rules determine waste management cost trajectories. Municipal opposition in candidate host prefectures extends holding periods.
- Decommissioning Guidelines:METI frameworks establish cost recovery mechanisms, liability pooling arrangements, and project approval timelines. Updated guidelines accelerate approvals for Fukushima-adjacent sites.
Nuclear Safety Standards absorbs the deepest compliance investment; Environmental Protection Laws are steepest expansion trajectory as clearance criteria tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized robotic demolition equipment to Japanese decommissioning sites, while France supplies nuclear waste packaging technologies. Japanese utilities import remote handling systems from European suppliers to address concurrent dismantlement projects across the Tohoku region.
Tohoku Region
Five simultaneous reactor dismantlement projects within 200 kilometers strain domestic equipment logistics. METI cost-sharing frameworks accelerate approvals for Fukushima-adjacent sites. Sendai and Koriyama anchor specialized labor pooling arrangements for radiation-hardened manipulator deployment.
Kanto Region
Tokyo Electric Power Company Holdings concentrates decommissioning procurement authority for Fukushima Daiichi operations. Nuclear Regulation Authority oversight mandates real-time dosimetry integration across all licensed sites. Hitachi and Toshiba maintain engineering headquarters in Tokyo and Kawasaki for robotic platform development.
Kansai Region
Kansai Electric Power manages aging reactor fleets at Mihama and Takahama sites with deferred dismantlement strategies. METI guidelines permit phased liability recognition for Safstor mothballing candidates. Osaka-based contractors bid for containment demolition scope under integrated project delivery contracts.
Chugoku Region
Three dormant reactor locations in Shimane and Tottori Prefectures await decommissioning initiation with minimal seismic damage complications. Municipal governments negotiate host community agreements for interim waste storage. Matsue and Tottori City position for environmental contractor clustering.
Kyushu Region
Aging pressurized water reactors at Genkai and Sendai sites favor partial decommissioning approaches where storage facility delays persist. Kyushu Electric Power balances immediate capital constraints against long-term site release commitments. Fukuoka and Kagoshima house regional contractor offices for soil remediation mobilization.
Japan Nuclear Power Reactor Decommissioning Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Japan's regulated nuclear decommissioning sector. Consolidation concentrates around integrated project delivery contractors and proprietary equipment manufacturers. Three archetypes dominate: reactor engineering heritage firms, heavy industrial conglomerates, and international certification specialists. Strategic moves center on technology licensing partnerships and unbundled liability-owner execution-contractor splits.
Among domestic engineering conglomerates, Toshiba Corp and Mitsubishi Heavy Industries exemplify reactor heritage archetypes with specialized platform development capabilities. GE-Hitachi Nuclear Energy, Ltd. occupies a position as the integrated joint-venture anchor for project delivery coordination. TÜV Rheinland Group represents the international certification specialist tier providing regulatory compliance verification.
| Leading Market Players |
|---|
| Tokyo Electric Power Company Holdings, Inc. |
| Toshiba Corp |
| GE-Hitachi Nuclear Energy, Ltd. |
| Mitsubishi Heavy Industries |
| TÜV Rheinland Group |
| Japan Atomic Power Co. |
| Orano SA |
| Hitachi-GE Nuclear Energy |
| Snc-Lavalin Group Inc (Atkins) |
| Others |
Supply & Pricing Matrix
German and French radiation-hardened equipment suppliers anchor upstream concentration for robotic demolition platforms, capturing margin pools at the precision cutting tier while Japanese domestic manufacturers compete on volume throughput for standard manipulator deployments.
Pricing Analysis
Prior-generation hydraulic pulverization systems trade at substantial discounts to fiber laser cutting platforms entering reactor pressure vessel segmentation contracts. Three-tier pricing structure across premium, standard, and economy levels reflects NRA certification grade and real-time dosimetry integration depth. Cost compression in economy-tier robotic demolition stems from domestic supplier capacity expansion in Osaka and Nagoya industrial corridors. Environmental contractors exhibit highest price sensitivity due to thin margins on soil remediation scope, while government-backed special purpose vehicles absorb premium-tier equipment costs without procurement friction.
Supply Chain Analysis
Toshiba and Mitsubishi Heavy Industries control contract-manufacturing capacity for radiation-hardened manipulator final assembly, with component sourcing drawing from German sensor suppliers and French optical systems specialists. Supply concentration rests on Japan, Germany, and France for precision cutting equipment, while hydraulic demolition tools source steel forgings from South Korean foundries. Cobalt-60 sealed sources for gamma spectroscopy and tungsten shielding alloys represent critical input dependencies. Single-source vulnerability concentrates around laser resonator imports from European suppliers. Distribution runs through METI-coordinated procurement frameworks for Fukushima-adjacent sites, with direct vendor relationships governing Kansai and Kyushu utility purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity across specialized technology niches as unbundled liability-owner execution-contractor splits proliferate and AI-enabled contamination mapping opens new service layers.
For Market Incumbents: Harden proprietary platform architectures against modular equipment imports by accelerating standardized eight-month delivery cycles. Deepen in-house production of radiation-hardened sensor arrays to reduce German supplier dependency. Consolidate around integrated project delivery contracts displacing fragmented multi-contractor arrangements at Tohoku regional cluster sites. For New Entrants and Emerging Players: Establish a beachhead in AI-enabled contamination mapping services where machine learning fusion with gamma spectroscopy reduces survey labor hours. Target Chugoku Region greenfield sites in Shimane and Tottori Prefectures awaiting decommissioning initiation with minimal seismic damage complications. Pursue technology demonstration partnerships with Japan Atomic Energy Agency to validate characterization protocols before scaling to utility procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic demolition platform development as multi-modal hydraulic-laser-plasma systems replace single-technology approaches. Acquisition candidates with NRA certification depth and proprietary lifting and segmentation systems offer defensive positioning through regulatory moats. Monitor interim storage facility siting decisions in candidate host prefectures as the critical signal for waste management cost trajectory stabilization or escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Platform Development | Toshiba and Mitsubishi Heavy Industries capture margin through radiation-hardened manipulator intellectual property control. |
| Integrated Project Delivery Contracts | Single-source accountability models displace fragmented arrangements at Fukushima Daiichi and adjacent Tohoku sites. |
| AI-Enabled Contamination Mapping | Machine learning fusion with gamma spectroscopy reduces survey labor hours and improves waste classification accuracy for contractors. |
| Domestic Supplier Capacity Expansion | Osaka and Nagoya industrial corridors compress equipment delivery cycles from eighteen months to eight months. |
| Unbundled Liability-Execution Structures | Tokyo Electric Power and Kansai Electric retain waste liability while outsourcing physical demolition to specialized vendors. |
Research Methodology
The analysis maps full decommissioning, partial decommissioning, site remediation, and waste management service types, each validated through decommissioning project managers, NRA compliance officers, utility procurement directors, and specialized demolition contractors. Primary interviews combined with secondary validation from METI decommissioning guidelines, Nuclear Regulation Authority safety standards, Ministry of the Environment clearance criteria, and utility cost-sharing framework disclosures. Bottom-up project pipeline enumeration triangulated against top-down utility expenditure commitments across the reactor portfolio.
Assumptions held fixed include METI cost-sharing framework continuity and NRA safety standard enforcement intensity, while reactor retirement schedules and interim storage facility siting timelines varied across scenario branches. Segmentation modeling incorporated service maturity level, technology readiness tier, end-user ownership structure, and regulatory compliance depth dimensions. CAGRs derived from expenditure commitment trajectories adjusted for project approval acceleration effects and workforce radiation exposure limit constraints.
Sensitivities concentrate around interim storage facility siting delays, clearance level criteria revisions, and specialized robotics supply concentration bottlenecks. Quarterly review of municipal opposition indicators in candidate host prefectures, NRA real-time dosimetry mandate enforcement patterns, and domestic manufacturer order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Global Power Plant Uranium Market
Nuclear Energy
Nuclear Steam Generator Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Energy Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Global Nuclear Reactor Construction Market