
 Nigeria Oil and Gas Downstream Market | 2026-2036
Nigeria Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Oil and Gas Downstream Market Foresight
Industrial offtakers are bifurcating from residential kerosene buyers as the dominant demand archetype in Nigeria's downstream sector. Dangote Oil Refinery Company Ltd anchors the supply transformation through its integrated refining and petrochemical complex. Nigerian National Petroleum Corporation sustains strategic control over crude allocation and import substitution programs. Oando Plc competes across retail distribution and storage infrastructure, leveraging its coastal terminal network.
Nigeria Oil and Gas Downstream encompasses refining, storage, transportation, and marketing of petroleum products including petrol, diesel, kerosene, and liquefied petroleum gas, with specifications typically conforming to West African quality standards for sulfur content and octane ratings. The sector processes crude oil into finished fuels and petrochemical precursors for power generation, mobility, and manufacturing feedstock. Petrol and diesel command the largest volume pools, while liquefied petroleum gas represents the fastest-growing product category as urban households and small enterprises switch from kerosene. The automotive end-user segment absorbs the majority of refined product volumes, though industrial buyers of diesel for captive power generation constitute the most margin-accretive customer class.
The Petroleum Industry Act, enforced by the Nigerian Upstream Petroleum Regulatory Commission and the Nigerian Midstream and Downstream Petroleum Regulatory Authority, restructures licensing, pricing, and domestic supply obligations for downstream operators. The Department of Petroleum Resources enforces product quality standards and depot integrity audits that determine market access for importers and local refiners. Stakeholders must monitor crude supply contract renegotiations, refinery output ramp schedules, and regulatory enforcement capacity to anticipate margin compression or arbitrage windows in the evolving supply landscape.
Market Dynamics
The Dangote Refinery commissioning is fragmenting Nigeria's import-dependent supply architecture, forcing legacy fuel importers to reposition around storage and retail logistics as domestic refining capacity scales.
Growth Catalysts
- Petroleum Industry Act:The Nigerian Midstream and Downstream Petroleum Regulatory Authority now licenses private sector refiners and marketers, dismantling NNPC's historical import monopoly and enabling new entrants to secure downstream operating permits.
- Industrial diesel demand:Manufacturing clusters in Lagos and Kano states are expanding captive power generation capacity, creating sustained offtake for high-sulfur diesel that local refiners can produce more competitively than imported alternatives.
- Liquefied petroleum gas penetration:Urban households in Abuja and Port Harcourt are switching from kerosene to LPG for cooking, compressing kerosene demand while expanding cylinder distribution networks and coastal import terminal utilization.
Market Restraints
- Crude allocation uncertainty:NNPC's commitment to supply 300,000 barrels daily to Dangote remains subject to production shortfalls and fiscal disputes, threatening refinery throughput stability and domestic product availability.
- Foreign exchange illiquidity:The Central Bank of Nigeria's rationed dollar access forces fuel importers to source hard currency through parallel markets, inflating landed costs and compressing margins on petrol and aviation fuel.
- Pipelines and jetties decay:The Trans-Niger Pipeline and Escravos-Lagos Pipeline System suffer recurrent sabotage and deferred maintenance, forcing 90% of product movement onto higher-cost road tankers.
Strategic Opportunities
- North-Central LPG corridors:Kaduna and Plateau states show underpenetrated household gas adoption, offering first-mover advantages for cylinder retail franchises and mini-LNG logistics operators.
- Automated fuel retail:Smart dispensing systems and fleet card platforms are compressing cash-handling costs and enabling real-time inventory management for independent petrol station operators.
- Petrochemical feedstock pivot:Dangote's polypropylene and polyethylene output creates backward integration opportunities for Nigerian packaging manufacturers currently importing resin from Saudi Arabia and Singapore.
Industry Challenges
- Refinery technician scarcity:Process engineers and catalyst specialists with experience in hydrocracking and reforming units command premium wages, constraining local refiners' ability to staff 24/7 operations.
- Product quality enforcement gaps:The Nigerian Midstream and Downstream Petroleum Regulatory Authority lacks portable testing capacity at retail stations, allowing adulterated petrol and off-spec diesel to circulate through informal blending.
- Legacy depot integration:Independent marketers' storage terminals use incompatible gauging and loading systems, complicating throughput agreements with the new refinery's automated dispatch protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Oil and Gas Downstream Market |
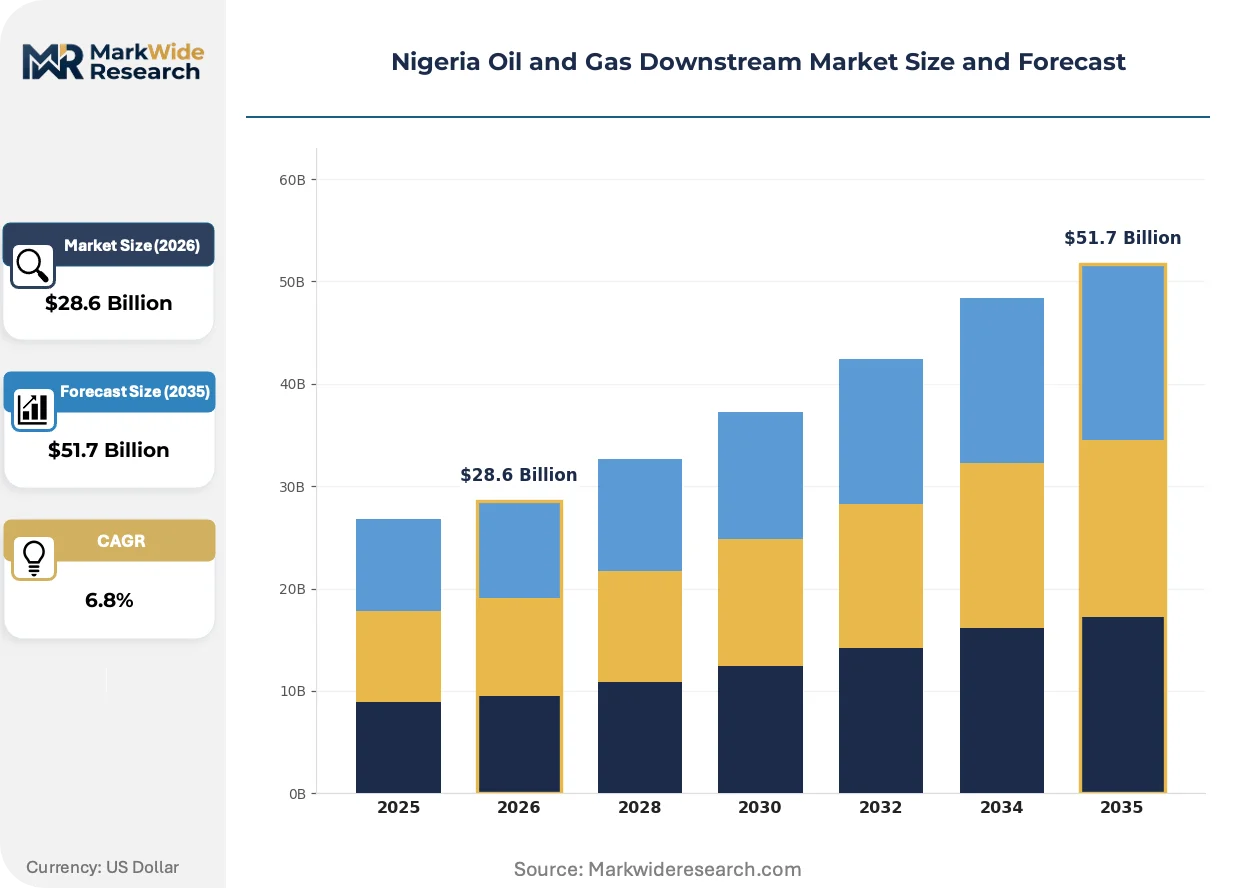
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Petrol, Diesel, Kerosene, Liquefied Petroleum Gas End User: Automotive, Residential, Industrial, Commercial Distribution Channel: Retail Outlets, Bulk Supply, Wholesalers, Online Platforms Service Type: Storage, Transportation, Delivery, Refining |
| Companies Covered | Indorama Eleme Petrochemicals Limited, Oando Plc, Nigerian National Petroleum Corporation, 11 Plc, TotalEnergies Marketing Nigeria Plc, Dangote Oil Refinery Company Ltd, Midoil Refining & Petrochemicals Company Limited, Ardova Plc, NDEP Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Oil and Gas Downstream Market Shifts & Advancements
Digital fuel distribution platforms and modular refining technologies are compressing the dominance of centralized import-and-depot models, while regulatory enforcement of domestic supply obligations is accelerating infrastructure localization.
Modular skid-mounted refineries are fragmenting the economics of small-scale fuel production across Niger Delta states. Rural industrial clusters and mining operations in Edo and Delta states are adopting these 1,000-5,000 barrel-per-day units to process stranded crude and supply captive diesel demand. The technology is fragmenting NNPC's historical role as sole supplier to remote industrial zones, enabling direct producer-to-consumer fuel relationships outside the national grid.
The Petroleum Industry Act's domestic crude supply obligation mandates NNPC to allocate 20% of production to local refiners before export. This provision is compressing the arbitrage margins of international trading houses that previously dominated Nigerian crude offtake. Dangote Refinery and any subsequent private refiners gain preferential access to Bonny Light and Qua Iboe grades, altering feedstock cost structures for domestic versus export-oriented processing.
Corporate fleet operators in Lagos and Abuja are consolidating fuel purchasing through integrated energy service contracts. Transport logistics companies and manufacturing groups are unbundling station retail from bulk supply, negotiating direct offtake agreements with depot operators and bypassing branded petrol station networks. This behavior is compressing the volume throughput of traditional retail marketers and forcing reinvestment into non-fuel convenience services to retain site profitability.
Nigeria Oil and Gas Downstream Market Segmentation
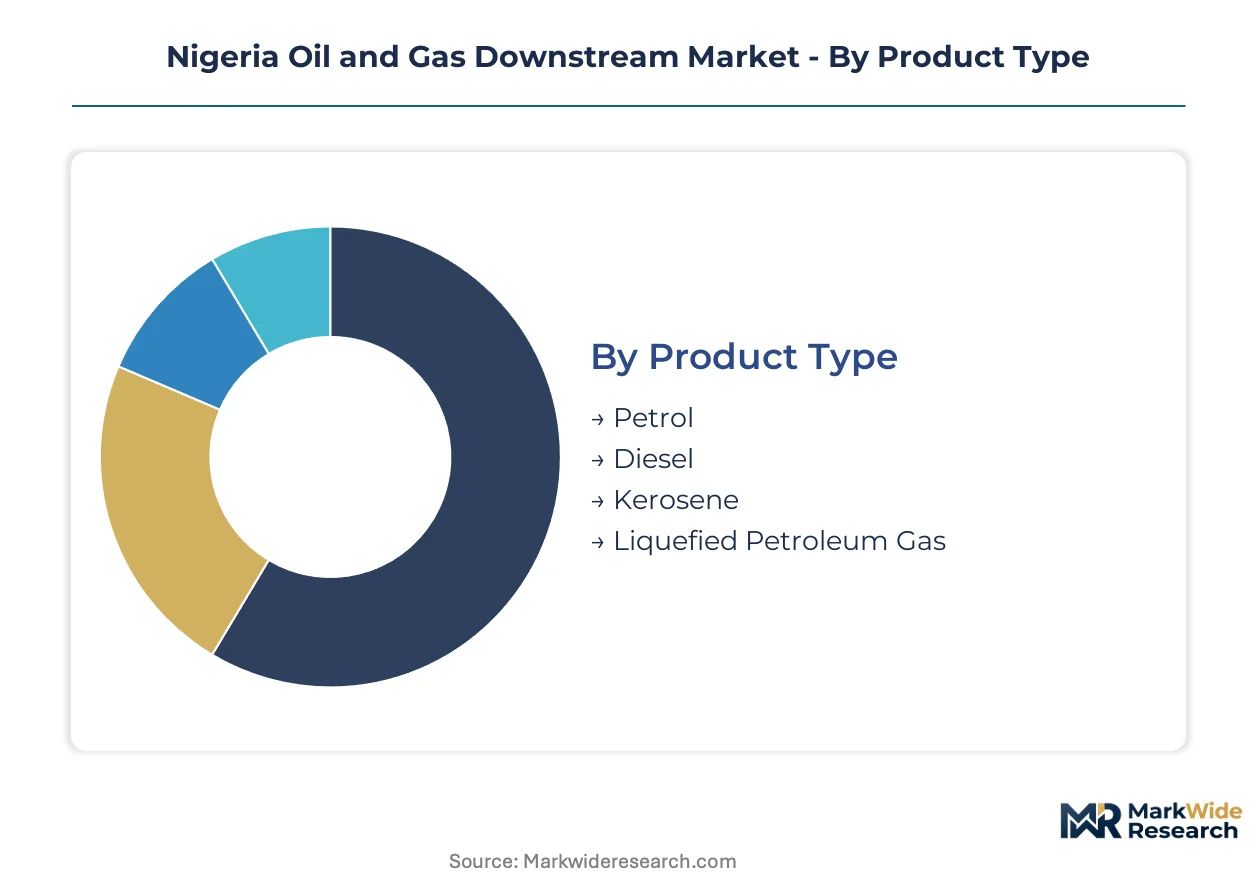
Segmentation in Nigeria's downstream sector reveals how regulatory enforcement and infrastructure gaps reshape competitive boundaries across product categories and customer classes. The Petroleum Industry Act's licensing reforms and Dangote Refinery's commissioning are redefining which segments capture margin and which face displacement.
Product Type:
The Nigerian Midstream and Downstream Petroleum Regulatory Authority applies differentiated sulfur limits and octane specifications across fuel categories, creating compliance cost tiers that favor local refining for heavier products while keeping light distillates import-dependent.
- Petrol:Motor spirit with 95 RON minimum specification dominates volumetric throughput across Lagos State filling stations and Abuja corporate fleets. Demand concentrates in urban automotive corridors where the Nigerian National Petroleum Corporation maintains price modulation authority, constraining independent marketer margins.
- Diesel:High-sulfur automotive gas oil serves captive power generation for manufacturing clusters in Kano and Ogun states where grid reliability fails. Industrial buyers in these zones absorb the largest share of Dangote Refinery's initial output, displacing historical imports through the Apapa and Calabar jetties.
- Kerosene:Dual-purpose illuminating fuel faces demand compression as LPG substitution accelerates in Port Harcourt and Ibadan households.
- Liquefied Petroleum Gas:Propane-butane blend for cooking and light industrial heating is climbing the fastest adoption curve across Nigerian cities, with cylinder distribution networks expanding into North-Central states previously dependent on kerosene.
Established volume favors petrol; emerging adoption favors liquefied petroleum gas.
End User:
Customer type determines pricing freedom under current regulatory architecture, with industrial offtakers securing direct depot agreements while residential consumers remain subject to administered price bands.
- Automotive:Private vehicle owners and commercial transport operators account for the majority of petrol station throughput across Nigerian road networks. Fleet operators in Lagos and Abuja are consolidating purchasing through integrated energy service contracts, bypassing branded retail networks.
- Industrial:Manufacturing and mining operations requiring diesel for captive power generation constitute the most margin-accretive customer class, with direct offtake agreements from depot operators replacing traditional retail relationships.
- Residential:Household cooking fuel demand is shifting rapidly from kerosene to LPG in urban centers, compressing legacy product volumes while expanding cylinder retail infrastructure.
- Commercial:Small enterprises and service sector fuel purchases fragment across informal retail channels with limited regulatory oversight.
Margin capture concentrates with industrial buyers; volume expansion tracks automotive and residential LPG transition.
Distribution Channel:
Channel economics diverge sharply based on storage infrastructure ownership and Nigerian Midstream and Downstream Petroleum Regulatory Authority licensing tier.
- Retail Outlets:Branded petrol stations with automated dispensing systems dominate urban fuel access in Lagos, Port Harcourt, and Abuja, though cash-handling costs and inventory leakage compress profitability for independent operators.
- Bulk Supply:Direct depot-to-consumer agreements for industrial diesel and aviation fuel bypass retail markups, with Dangote Refinery's automated dispatch protocols favoring large-volume offtakers.
- Wholesalers:Independent marketers with legacy storage terminals in Niger Delta corridor states intermediate between importers and rural retail networks.
- Online Platforms:Digital fuel ordering and fleet card systems are compressing transaction costs for corporate customers in major cities.
Physical infrastructure governs rural access; digital platforms gain traction in corporate segments.
Service Type:
Value chain position determines exposure to Dangote Refinery's vertical integration and NNPC's crude allocation decisions.
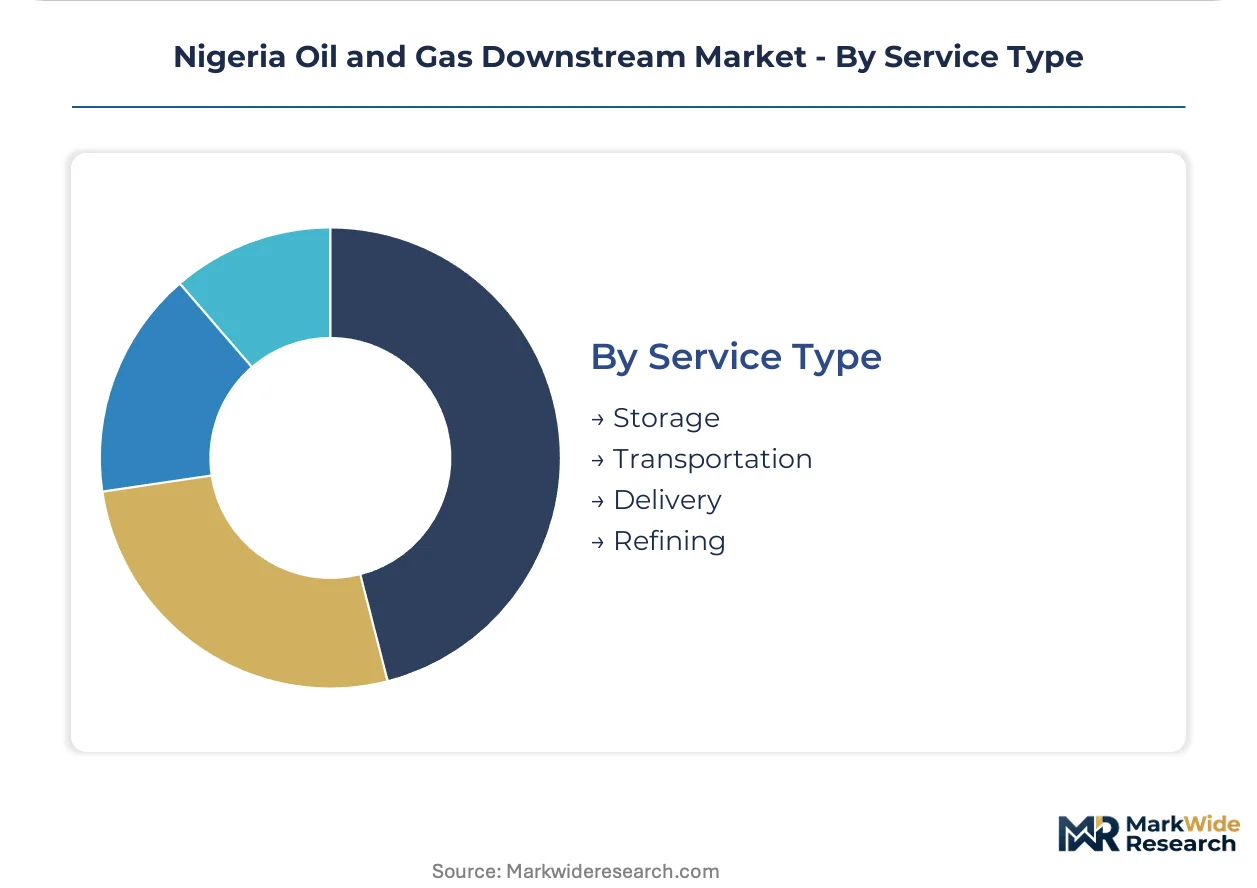
- Refining:Hydrocracking and reforming operations at Dangote's Lekki complex and modular units across Edo and Delta states are displacing historical import dependence for diesel and kerosene.
- Storage:Coastal terminals and inland depots in Lagos, Calabar, and Kaduna states face utilization pressure as domestic refinery output reduces import volumes.
- Transportation:Road tanker fleets dominate product movement due to pipeline sabotage and deferred maintenance on the Trans-Niger and Escravos-Lagos systems.
- Delivery:Last-mile logistics for LPG cylinder distribution and automated retail replenishment are attracting new entrants with specialized fleet assets.
Upstream service integration favors refining; infrastructure legacy constrains transportation margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial diesel buyers cluster in Lagos State and the Niger Delta corridor, while residential kerosene demand contracts fastest in Port Harcourt and Ibadan urban centers. LPG substitution accelerates household fuel transition across North-Central states previously dependent on kerosene.
Lagos State
Manufacturing clusters in Ogun and Lagos states expand captive power generation capacity, absorbing high-sulfur diesel from Dangote Refinery's initial output. The Nigerian Midstream and Downstream Petroleum Regulatory Authority licenses private depot operators in Apapa and Ijora, dismantling NNPC's historical import monopoly. Fleet operators in Lagos Island and Victoria Island consolidate fuel purchasing through integrated energy service contracts, bypassing branded retail networks.
Niger Delta Corridor
Modular skid-mounted refineries in Edo and Delta states process stranded crude for rural industrial clusters and mining operations. The Petroleum Industry Act's domestic crude supply obligation mandates NNPC to allocate feedstock to these units before export. Coastal terminals in Warri and Port Harcourt face utilization pressure as domestic refinery output reduces import volumes through legacy jetties.
Kano State
Textile and food processing factories in Kano and Kaduna states rely on diesel generators due to grid reliability failures, creating sustained offtake for local refiners. The Nigerian Electricity Regulatory Commission's tariff reforms push industrial users toward self-generation. Distributors in the Kano metropolis negotiate direct depot agreements, replacing traditional wholesale relationships with bulk supply contracts.
North-Central States
Kaduna and Plateau states show underpenetrated household LPG adoption, offering first-mover advantages for cylinder retail franchises. The Department of Petroleum Resources enforces product quality standards at inland depots, determining market access for mini-LNG logistics operators. Mini-distribution networks in Jos and Abuja expand cylinder penetration into peri-urban settlements previously dependent on kerosene.
Abuja Federal Capital Territory
Corporate fleet operators and government vehicle pools concentrate diesel and petrol demand in the central business district. The Nigerian Midstream and Downstream Petroleum Regulatory Authority's automated fuel retail licensing favors smart dispensing systems in Garki and Wuse districts. Digital fuel ordering platforms compress transaction costs for federal ministries and embassy compounds with consolidated purchasing.
Nigeria Oil and Gas Downstream Market Competitive Landscape
Player mix skews toward state-affiliated incumbents and integrated refinery operators with crude allocation privileges. The downstream sector exhibits tiered concentration around NNPC's strategic control of crude supply and Dangote Refinery's vertical integration into petrochemical output. Three archetypes dominate: state-linked refiners with preferential feedstock access, independent marketers with legacy storage infrastructure, and modular operators serving captive industrial demand. Competitive moves center on capacity commissioning timelines and depot throughput agreements with the new refinery's automated dispatch protocols.
Within the state-affiliated tier, Nigerian National Petroleum Corporation anchors crude allocation and import substitution programs, while Dangote Oil Refinery Company Ltd exemplifies integrated refining and petrochemical complex operations. Oando Plc occupies a position across retail distribution and coastal terminal networks, representing the independent marketer archetype with storage infrastructure leverage.
| Leading Market Players |
|---|
| Indorama Eleme Petrochemicals Limited |
| Oando Plc |
| Nigerian National Petroleum Corporation |
| 11 Plc |
| TotalEnergies Marketing Nigeria Plc |
| Dangote Oil Refinery Company Ltd |
| Midoil Refining & Petrochemicals Company Limited |
| Ardova Plc |
| NDEP Plc |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with Platts-indexed crude linkage anchor supply access and price visibility for Nigerian diesel buyers, locking in feedstock costs while exposing industrial offtakers to Brent volatility. The Petroleum Industry Act's domestic supply obligation reshapes these arrangements by mandating NNPC crude allocation to local refiners before export, compressing arbitrage margins for importers.
Pricing Analysis
Cost-plus contracts with Platts-indexed diesel pricing dominate industrial procurement in Lagos and Kano manufacturing clusters. Price differentiation rests on sulfur content grades and volume scale, with high-sulfur diesel commanding premiums from captive power generators. Cost compression in imported petrol runs through parallel-market dollar sourcing, while industrial diesel buyers show lowest price sensitivity due to grid-reliability failures.
Supply Chain Analysis
Strategic stockpiling at coastal terminals in Lagos and Calabar compensates for pipeline sabotage risks, while just-in-time road tanker dispatch dominates last-mile delivery. Supply draws from Nigerian crude production, Saudi refined product imports, and Singapore petrochemical feedstock. Single-source vulnerability concentrates around NNPC crude allocation decisions. Distribution runs through coastal depots, inland storage terminals, and branded retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dangote Refinery commissioning constitutes a structural disruption, altering feedstock economics and displacing historical import dependence through domestic refining scale.
For Market Incumbents: Compound storage infrastructure utilization by negotiating throughput agreements with Dangote's automated dispatch protocols. Secure backward integration into LPG cylinder distribution networks in North-Central states before mini-LNG operators capture first-mover positions. NNPC crude allocation uncertainty and modular refinery fragmentation threaten legacy depot margins. For New Entrants and Emerging Players: Nigerian Midstream and Downstream Petroleum Regulatory Authority licensing fast-tracks enable depot operator permits for independent marketers with coastal terminal assets. White-space targets concentrate in Kaduna and Plateau LPG cylinder retail, plus automated fuel retail systems for Lagos fleet operators. Direct depot-to-industrial agreements bypass branded station networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among industrial diesel offtakers with captive power generation contracts. Long-term viability favors integrated refining and petrochemical complexes with crude allocation privileges over pure-play storage operators facing utilization pressure. Watch Dangote polypropylene output ramp as signal for backward integration opportunities in Nigerian packaging manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Crude Supply Contract Renegotiation | NNPC allocation terms determine feedstock cost structures for domestic refiners versus export arbitrage. |
| LPG Cylinder Distribution Expansion | North-Central retail networks capture household fuel transition from kerosene in Kaduna and Plateau states. |
| Automated Fuel Retail Deployment | Smart dispensing systems compress cash-handling costs for Lagos and Abuja fleet operators. |
| Modular Refinery Capacity Addition | Skid-mounted units in Edo and Delta states process stranded crude for rural industrial clusters. |
| Petrochemical Feedstock Pivot | Polypropylene offtake from Dangote enables packaging manufacturers to replace Saudi resin imports. |
Research Methodology
Desk research of Nigerian regulatory filings, NNPC crude allocation disclosures, and Petroleum Industry Act implementation guidelines preceded structured interviews with refinery operations managers, depot licensing officers, industrial procurement leads, and LPG distribution network operators. Secondary validation drew from Nigerian Midstream and Downstream Petroleum Regulatory Authority licensing databases, customs import records, and Department of Petroleum Resources quality audit reports. Bottom-up capacity commissioning timelines and top-down demand segmentation were triangulated.
Variance decomposition across product type, end-user segment, distribution channel, and service type dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from segment-level volume and value build-ups. Forecast inputs incorporated Dangote Refinery output ramp schedules, NNPC crude supply commitment reliability, and LPG cylinder penetration rates in underpenetrated North-Central states.
The analysis sits within stated boundaries; outcomes outside sustained Dangote throughput stability and NNPC allocation compliance would require recalibration. Forecasts reflect assumptions about pipeline sabotage frequency, central bank dollar access rationing, and regulatory enforcement capacity. Revision becomes warranted when crude production shortfalls or fiscal disputes cross thresholds affecting domestic supply obligations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market