
 Managed Pressure Drilling Services Market | 2026-2036
Managed Pressure Drilling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Pressure Drilling Services Market Outlook
Closed-loop automation with real-time pressure telemetry is reshaping how offshore wells are engineered and executed. SLB leverages integrated hardware-software platforms to anchor its position in deepwater MPD deployments. Halliburton sustains competitive density through specialized wellbore pressure management in high-temperature formations. Baker Hughes Company differentiates via advanced choke manifold systems that extend operational envelopes in narrow-margin drilling.
Managed Pressure Drilling Services encompass engineered systems that maintain precise annular pressure profiles through automated choke control and continuous mud circulation, typically operating within margins of 0.3 to 1.5 ppg equivalent to prevent influx or fracture. These services enable drilling through pressure-depleted zones, salt formations, and extended-reach laterals where conventional methods risk well control events or lost circulation. The technology dimension tilts toward Automatic Control Systems, where margin pools deepen as operators demand closed-loop response times below five seconds to surface pressure fluctuations. Application-weighted demand skews toward Development Drilling, which occupies the largest revenue share as brownfield projects multiply in mature basins, while Exploratory Drilling registers the fastest expansion as frontier provinces open in ultra-deepwater blocks.
Regulatory oversight from BSEE in the United States and NORSOK standards in Norway mandates redundant pressure barriers and real-time monitoring for subsea drilling operations, directly elevating specification thresholds for MPD equipment procurement. Brazil's national petroleum regulator enforces well integrity protocols that compel operators to adopt constant bottom-hole pressure methods in pre-salt fields, creating structural demand pull for certified service providers. Stakeholders must monitor how emerging carbon-accounting frameworks for drilling emissions reshape contractor selection criteria and capital allocation toward lower-circulation MPD variants.
Market Dynamics
Closed-loop automation is compressing the operational envelope for deepwater drilling, forcing contractors to replace manual choke control with sub-second response systems that prevent kicks in narrow pressure windows. BSEE well integrity mandates and Brazil's pre-salt protocols are structurally eliminating conventional drilling methods from certified project scopes.
Growth Catalysts
- BSEE Subsea Regulations:Redundant pressure barrier requirements in the United States Gulf of Mexico are compelling operators to specify certified MPD systems for all deepwater completions.
- Pre-salt Development:Brazil's national petroleum regulator mandates constant bottom-hole pressure methods, creating structural demand pull for automated pressure control in the Santos Basin.
- Narrow-margin Drilling:Depleted reservoir zones in the North Sea require automated choke response below five seconds, accelerating replacement of conventional riser systems.
Market Restraints
- Specialized Equipment Costs:High-specification choke manifolds and real-time telemetry hardware impose capital intensity that excludes smaller independent operators from deepwater tenders.
- Service Provider Concentration:Deepwater MPD deployment capability clusters among integrated energy service companies, limiting competitive pressure on day-rate pricing.
- Integration Complexity:Retrofitting closed-loop systems onto legacy drilling rigs requires extensive topside modification, extending project timelines and elevating contract risk.
Strategic Opportunities
- Carbon-accounting Frameworks:Emerging emissions disclosure requirements for drilling operations are elevating contractor selection criteria toward lower-circulation MPD variants that reduce mud volume and transport intensity.
- Extended-reach Laterals:Unconventional onshore basins in the Permian are adopting adaptive pressure control to manage fracture gradients in longer horizontal sections.
- NORSOK Certification Expansion:Norwegian standardization of subsea MPD equipment is creating exportable qualification protocols that accelerate market entry for certified providers into the Barents Sea.
Industry Challenges
- Control Systems Expertise Gap:Shortage of engineers capable of programming and maintaining automated pressure algorithms is constraining fleet expansion for specialized contractors.
- Multi-vendor Integration:Combining hardware from separate suppliers with proprietary software platforms creates commissioning delays and voids warranty coverage during initial operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Pressure Drilling Services Market |
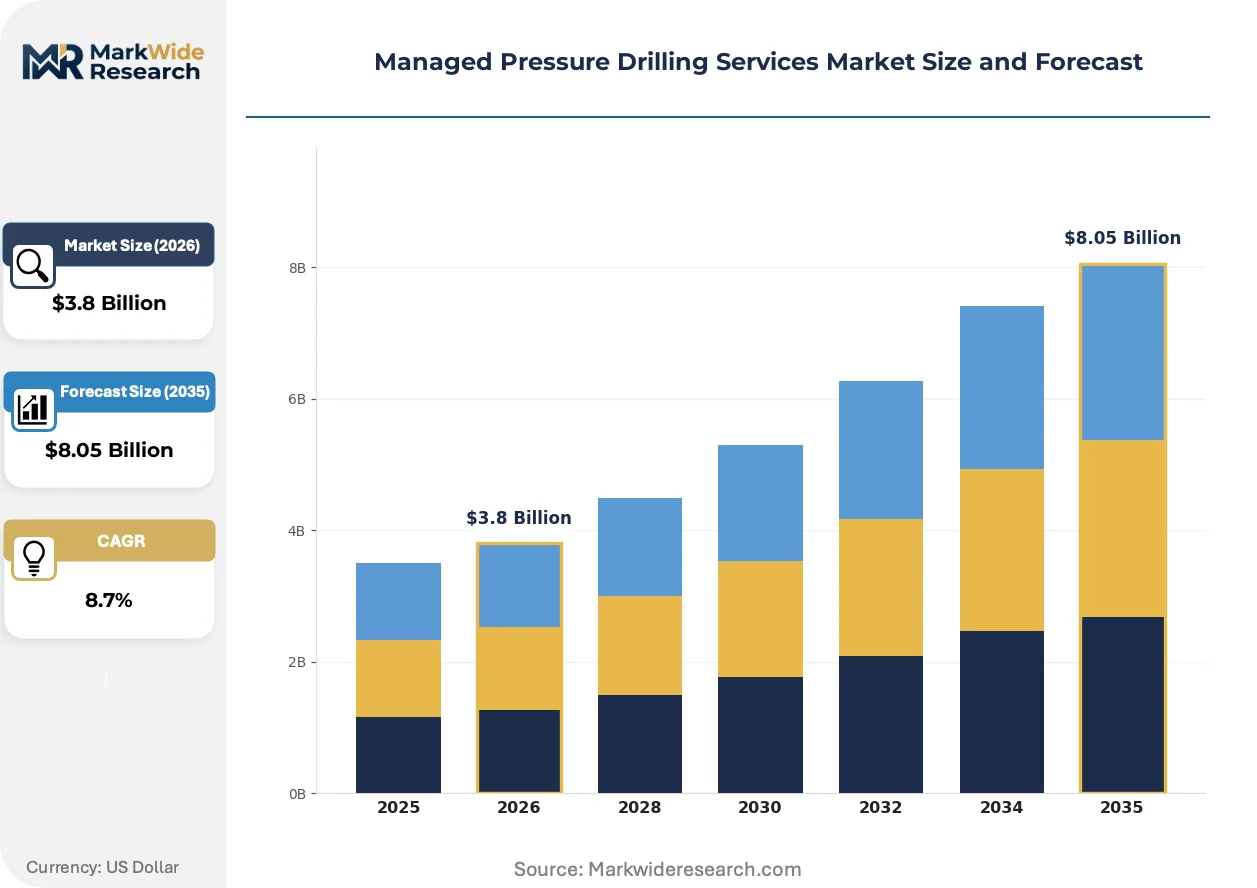
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Pressure Drilling, Conventional Drilling, Underbalanced Drilling, Continuous Circulation End User: Oil & Gas Companies, Service Providers, Offshore Operators, Onshore Operators Technology: Automatic Control Systems, Drilling Riser Systems, Choke and Kill Systems, Data Acquisition Systems Application: Exploratory Drilling, Development Drilling, Well Intervention, Decommissioning |
| Companies Covered | Baker Hughes Company, Halliburton, SLB, Weatherford International plc, NOV Inc., Aker Solutions ASA, Enhanced Drilling AS, Nabors Industries Ltd, ADC Energy Services Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Pressure Drilling Services Market Strategic Shifts
Digital twin architectures are virtualizing how pressure control systems are tested and commissioned before offshore deployment. Real-time simulation platforms now enable scenario modeling that reduces rig-site calibration time and compresses project startup schedules.
Digital twin technology is virtualizing pre-deployment validation of MPD control algorithms through high-fidelity wellbore simulation. Offshore operators in Brazil and the Gulf of Mexico are adopting these platforms to reduce commissioning risk in ultra-deepwater blocks. This virtualization is compressing the timeline between contract award and first drilling, enabling faster capital rotation on high-specification rigs.
EU CSRD disclosure requirements are extending sustainability reporting obligations to offshore drilling contractors operating in European waters. Scope 3 emissions tracking now encompasses mud circulation volumes and logistics intensity, elevating specification thresholds for lower-footprint MPD configurations. North Sea operators are responding by embedding carbon intensity metrics into tender evaluation criteria alongside technical capability scores.
Integrated service contracting is displacing discrete equipment rental in deepwater project structures. National oil companies in Brazil now bundle MPD services within integrated drilling packages rather than sourcing choke systems separately. This consolidation is most visible in pre-salt block awards, where single-source accountability for well integrity is becoming a mandatory commercial structure.
Managed Pressure Drilling Services Market Segmentation
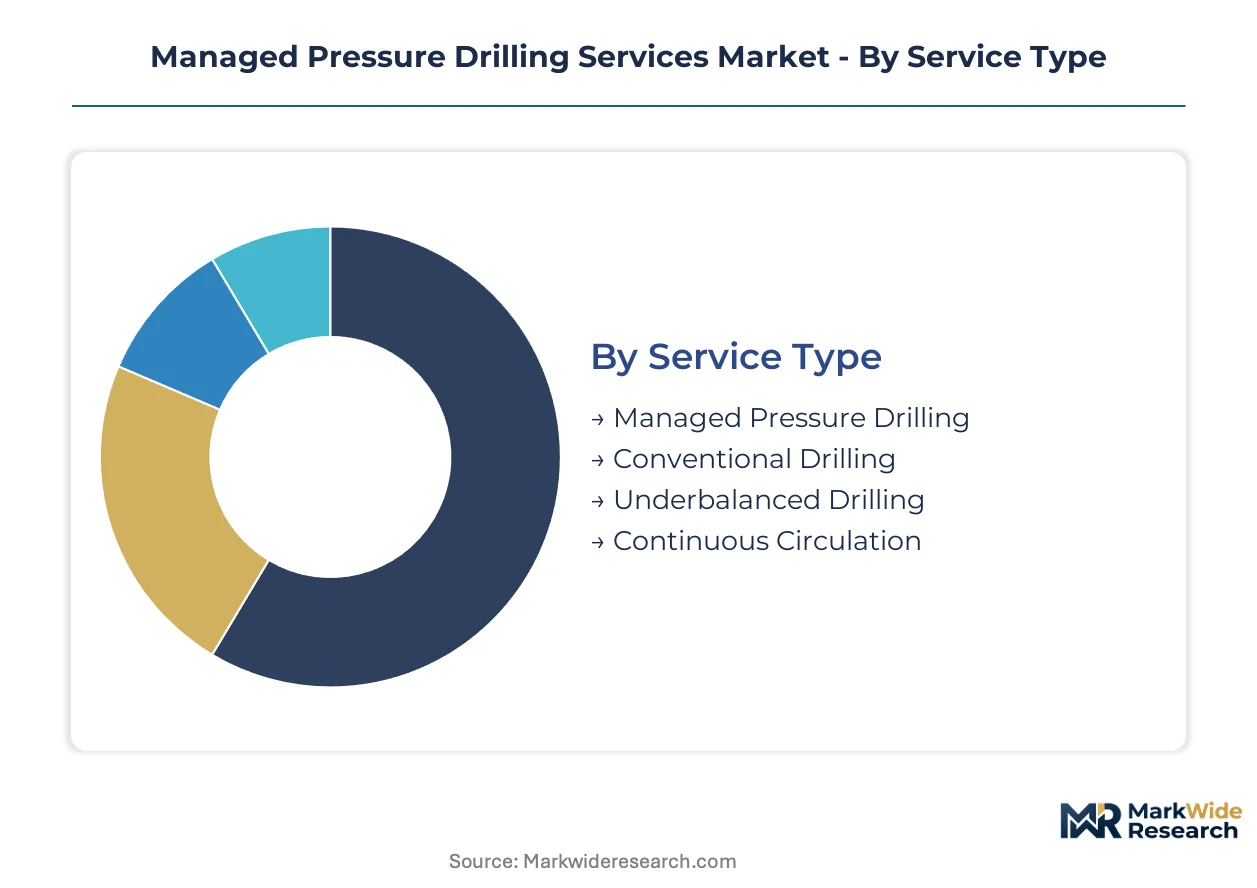
Service differentiation in managed pressure drilling reflects how pressure window complexity and regulatory mandates reshape procurement patterns. Segmentation reveals where technology premiums concentrate and which customer configurations drive specification intensity.
Service Type:
Application complexity determines which pressure control methodology operators specify for formation-specific challenges.
- Managed Pressure Drilling:Automated annular pressure management maintains constant bottom-hole pressure through real-time choke adjustment. Pre-salt operators in Brazil mandate this method for narrow-margin formations where conventional techniques risk well control events.
- Conventional Drilling:Static mud weight systems without active pressure control dominate mature onshore basins with wide operational windows. Gulf of Mexico deepwater projects are phasing out this approach as BSEE tightens well integrity requirements for subsea completions.
- Underbalanced Drilling:Intentionally lower bottom-hole pressures than formation pore pressure protect reservoir permeability in depleted zones.
- Continuous Circulation:Uninterrupted mud flow during connections prevents pressure spikes that fracture weak formations.
Managed Pressure Drilling holds installed capacity. Continuous Circulation is rotating up the share rankings.
End User:
Customer scale and regulatory exposure shape specification thresholds and contract structures across the service base.
- Oil & Gas Companies:Integrated operators with capital deployment authority specify high-telemetry MPD packages for deepwater exploration. Brazilian pre-salt blocks and US Gulf ultra-deepwater projects anchor demand concentration for these national oil companies and majors.
- Offshore Operators:Contract drillers operating high-specification rigs face direct liability for well integrity failures. North Sea contractors are retrofitting closed-loop systems to meet NORSOK certification requirements for subsea pressure barriers.
- Service Providers:Equipment rental and pressure control specialists supply discrete choke manifolds and telemetry hardware.
- Onshore Operators:Permian Basin independents adopt adaptive pressure control for extended-reach laterals where fracture gradients vary along horizontal sections.
Oil & Gas Companies anchor procurement volume. Offshore Operators are climbing the fastest as certification mandates tighten.
Technology:
Hardware-software integration depth separates premium deployments from commodity pressure control configurations.
- Automatic Control Systems:Closed-loop algorithms with sub-five-second response times to surface pressure fluctuations. Deepwater Brazil and Gulf of Mexico deployments require these systems for narrow-margin drilling where manual choke adjustment risks kicks or lost circulation.
- Choke and Kill Systems:High-specification manifolds with redundant pressure barriers form the mechanical core of MPD installations. Baker Hughes and SLB compete on operational envelope extension in high-temperature, high-pressure formations.
- Drilling Riser Systems:Conventional riser configurations without active pressure management serve wide-margin applications.
- Data Acquisition Systems:Real-time telemetry networks transmit bottom-hole pressure, flow rate, and temperature to surface controllers.
Automatic Control Systems command technology premiums. Data Acquisition Systems are gaining share fastest as digital twin validation expands.
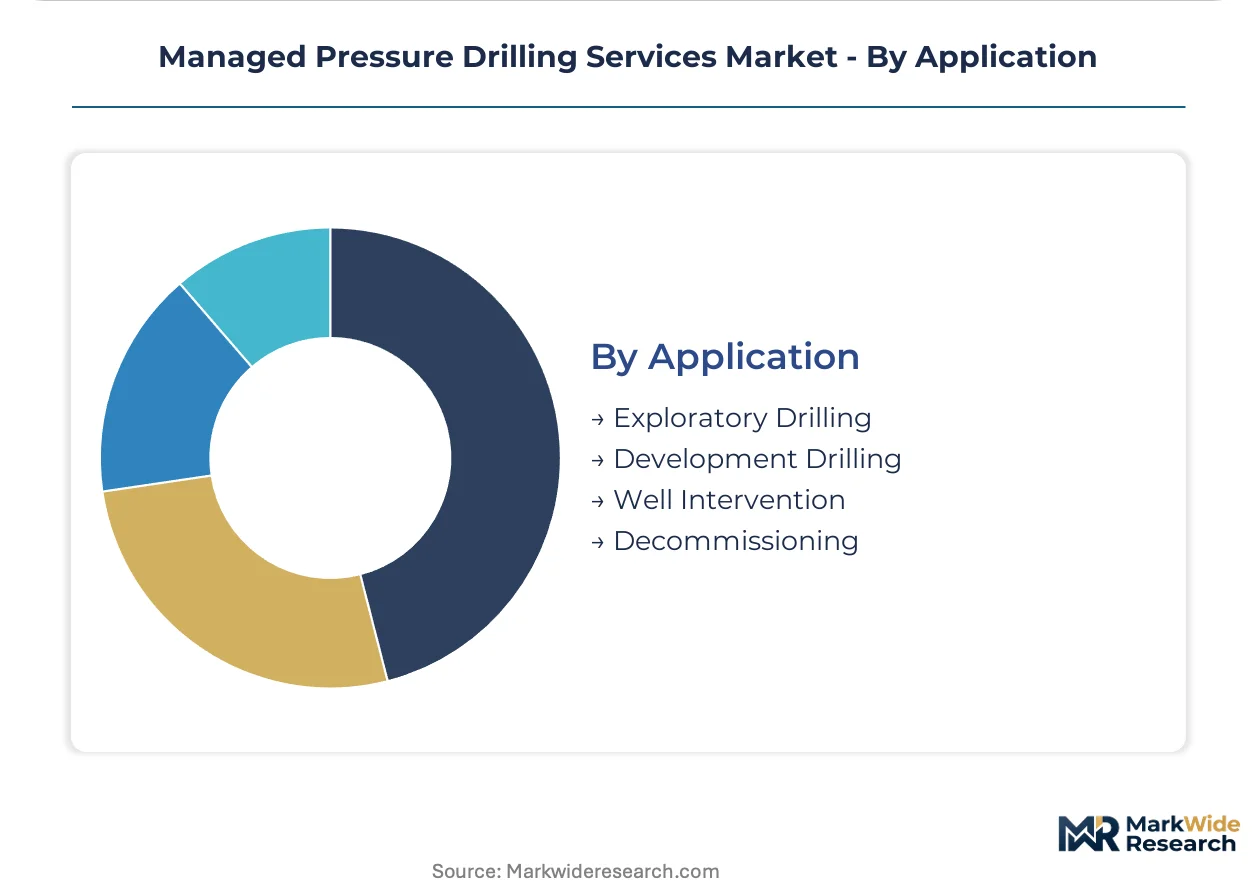
Application:
Project lifecycle stage determines pressure control precision requirements and contract duration structures.
- Development Drilling:Brownfield infill and pre-salt production drilling in Brazil's Santos Basin require constant bottom-hole pressure to navigate depleted zones and salt formations. National oil companies bundle these services within integrated drilling packages rather than sourcing equipment separately.
- Exploratory Drilling:Frontier ultra-deepwater blocks in the Gulf of Mexico and Barents Sea demand adaptive pressure control where formation pressures are unknown. This segment is expanding most quickly as operators push into geologically complex provinces.
- Well Intervention:Workover and recompletion operations in pressure-depleted reservoirs use MPD to maintain wellbore stability.
- Decommissioning:Plug and abandonment activities require pressure control for safe barrier placement in aging wells.
Development Drilling anchors revenue concentration. Exploratory Drilling represents the steepest expansion trajectory as frontier blocks open.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports MPD engineering expertise and integrated service packages to West African offshore operators developing analogous pre-salt formations. Norwegian technology flows into North Sea projects and Barents Sea frontier blocks through certified equipment protocols.
United States
BSEE mandates redundant pressure barriers for all Gulf of Mexico deepwater completions, eliminating conventional drilling from certified scopes. Houston anchors the engineering concentration where service companies retrofit closed-loop systems onto legacy rigs. Permian Basin operators adopt adaptive pressure control for extended-reach laterals with variable fracture gradients.
Brazil
Pre-salt development in the Santos Basin requires constant bottom-hole pressure methods to navigate narrow-margin salt formations. The national petroleum regulator enforces well integrity protocols that structurally mandate automated MPD for all new production drilling. Rio de Janeiro clusters the project management and offshore logistics coordination for integrated service contracts.
Norway
NORSOK certification standards for subsea pressure barriers accelerate replacement of conventional riser systems in the North Sea. The country's petroleum safety authority mandates real-time monitoring for all drilling operations in environmentally sensitive waters. Stavanger concentrates the engineering centers developing exportable qualification protocols for Barents Sea expansion.
United Kingdom
Depleted reservoir zones in the North Sea require automated choke response below five seconds to prevent kicks in narrow pressure windows. The North Sea Transition Authority ties licensing approvals to well integrity demonstrations using certified pressure control technologies. Aberdeen maintains the service hub where contractors integrate digital twin validation into project commissioning schedules.
Saudi Arabia
Aramco's offshore gas development in the Arabian Gulf deploys high-temperature MPD systems for sour gas formations with narrow operational windows. The national oil company bundles pressure control services within integrated drilling contracts rather than sourcing equipment separately. Dhahran anchors the engineering coordination for Red Sea frontier blocks requiring adaptive pressure management.
Managed Pressure Drilling Services Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structured around integrated service bundling versus discrete equipment supply. The vendor base clusters into three tiers: full-service energy companies with proprietary hardware-software platforms, specialized pressure control contractors with certified choke manifold expertise, and regional service providers supplying telemetry and data acquisition components. Strategic moves concentrate on vertical integration into closed-loop automation and geographic expansion through NORSOK-equivalent certification acquisition.
Among Houston-based integrated service corporations, Baker Hughes Company, Halliburton, and SLB occupy positions representing the full-service archetype with control over both equipment manufacturing and offshore deployment capability. These entities anchor the premium tier where national oil companies source bundled drilling packages rather than discrete pressure control components. Norwegian specialists including Aker Solutions ASA and Enhanced Drilling AS exemplify the regional-certification pathway, leveraging NORSOK standards to access North Sea and export markets. Weatherford International plc and NOV Inc. sit within the equipment-specialist segment, supplying choke manifolds and riser systems that integrate into broader service architectures.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Halliburton |
| SLB |
| Weatherford International plc |
| NOV Inc. |
| Aker Solutions ASA |
| Enhanced Drilling AS |
| Nabors Industries Ltd |
| ADC Energy Services Ltd. |
| Others |
Value Chain & Pricing Dynamics
Houston-Rio de Janeiro freight corridors for high-specification choke manifolds impose cost volatility that amplifies pricing power for integrated service providers while squeezing margins for equipment-only suppliers. Tariff exposure between the United States and Brazil compounds this dynamic, forcing procurement officers to balance landed cost against certification compliance.
Pricing Analysis
Cost-plus contracts with steel and electronics indexation dominate deepwater MPD procurement. Three-tier pricing structure across premium, standard, and economy levels separates NORSOK-certified integrated packages from regional equipment rentals. Cost compression in the standard tier is intensifying because Brazilian national oil companies are consolidating procurement into bundled drilling contracts. Independent operators in the Permian Basin exhibit highest price sensitivity, while pre-salt operators in Brazil prioritize technical specification over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for telemetry hardware and sensor components. Manufacturing concentrates in the United States for choke manifolds, Norway for NORSOK-certified control systems, and South Korea for specialized riser connectors. The supply chain draws from high-grade steel alloys, subsea electronics, and hydraulic actuators. Single-source vulnerability persists for sub-five-second response control algorithms. Distribution runs through integrated service contractors rather than discrete equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of engineers capable of programming automated pressure algorithms constrains fleet expansion and elevates acquisition premiums for control systems expertise. This capability gap defines competitive mobility across the forecast window.
For Market Incumbents: Pre-empt specialist contractor acquisition to secure closed-loop automation talent before NORSOK-equivalent certification requirements proliferate. Backward integration into proprietary choke manifold manufacturing reduces exposure to steel tariff volatility. SLB and Halliburton should anchor premium positioning through captive supply of real-time telemetry hardware.
For New Entrants and Emerging Players: Pursue NORSOK certification acquisition as the fastest pathway into North Sea and exportable Barents Sea markets. White-space concentration sits in extended-reach lateral applications for Permian Basin independents where adaptive pressure control penetration remains below deepwater offshore levels. License digital twin validation platforms from established software providers to compress commissioning timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated service companies with proprietary hardware-software platforms over equipment-only specialists. Long-term viability rests on carbon-accounting compliance capabilities as EU CSRD disclosure requirements extend to offshore drilling contractors. The signal to watch is national oil company procurement consolidation into single-source integrated packages.
| Strategic Initiative | Industry Significance |
|---|---|
| NORSOK Certification Acquisition | Unlocks North Sea access and creates exportable protocols for Barents Sea expansion. |
| Backward Integration into Choke Manufacturing | Reduces steel tariff exposure and secures supply continuity for high-temperature formations. |
| Digital Twin Platform Licensing | Compresses commissioning timelines for ultra-deepwater blocks in Brazil and Gulf of Mexico. |
| Carbon-Accounting Capability Buildout | Aligns contractor selection criteria with EU CSRD emissions disclosure requirements. |
| Specialist Control Systems Acquisition | Captures scarce automation engineering talent ahead of regulatory certification proliferation. |
Study Parameters
Operator-level perspectives from drilling engineers, well integrity officers, procurement leads at national oil companies, and subsea project managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through BSEE regulatory filings, ANP pre-salt development protocols, NORSOK equipment standards, and customs data for high-specification drilling equipment trade flows. Bottom-up rig fleet analysis triangulated against top-down energy service company revenue segmentation.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include service type complexity, technology integration depth, application lifecycle stage, and regional regulatory framework intensity. CAGRs were derived from rig-day rate trajectories and equipment deployment density curves. Forecast inputs incorporated pre-salt well count projections and BSEE subsea completion mandates.
Macroeconomic conditions sit as an overlay; deviation in offshore capital expenditure cycles and steel commodity prices would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and certification standard harmonization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
North America Natural Gas Market
Oil & Gas
North America Coiled Tubing Services Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Copper Mining Market
Oil & Gas
North America Perforating Gun Market