
 Argentina Oil and Gas Downstream Market | 2026-2036
Argentina Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Oil and Gas Downstream Market Outlook
Refinery digitalization with advanced process control systems is tilting capital deployment toward real-time optimization platforms. Yacimientos Petrolíferos Fiscales SA anchors the national refining base through its dominance of the Luján de Cuyo and La Plata complexes. Pan American Energy SL leverages integrated upstream-downstream logistics to sustain cost advantages across Patagonian supply corridors. Axion Energy competes through specialized lubricant blending capacity at its Campana facility.
Argentina oil and gas downstream operations encompass crude oil refining, product storage, and fuel distribution infrastructure producing transport fuels and petrochemical feedstocks with typical refinery complexity indices ranging from 6.5 to 9.2 Nelson complexity. The primary purpose centers on converting imported and domestic crude into gasoline, diesel, and jet fuel for internal consumption and limited export. Petrol retains the largest volume share across product type segments, though diesel is gaining ground from agricultural mechanization and freight logistics expansion. The automotive end user segment commands the deepest margin pool, while power generation represents the fastest-growing demand category as gas-to-liquid substitution accelerates in northern provinces.
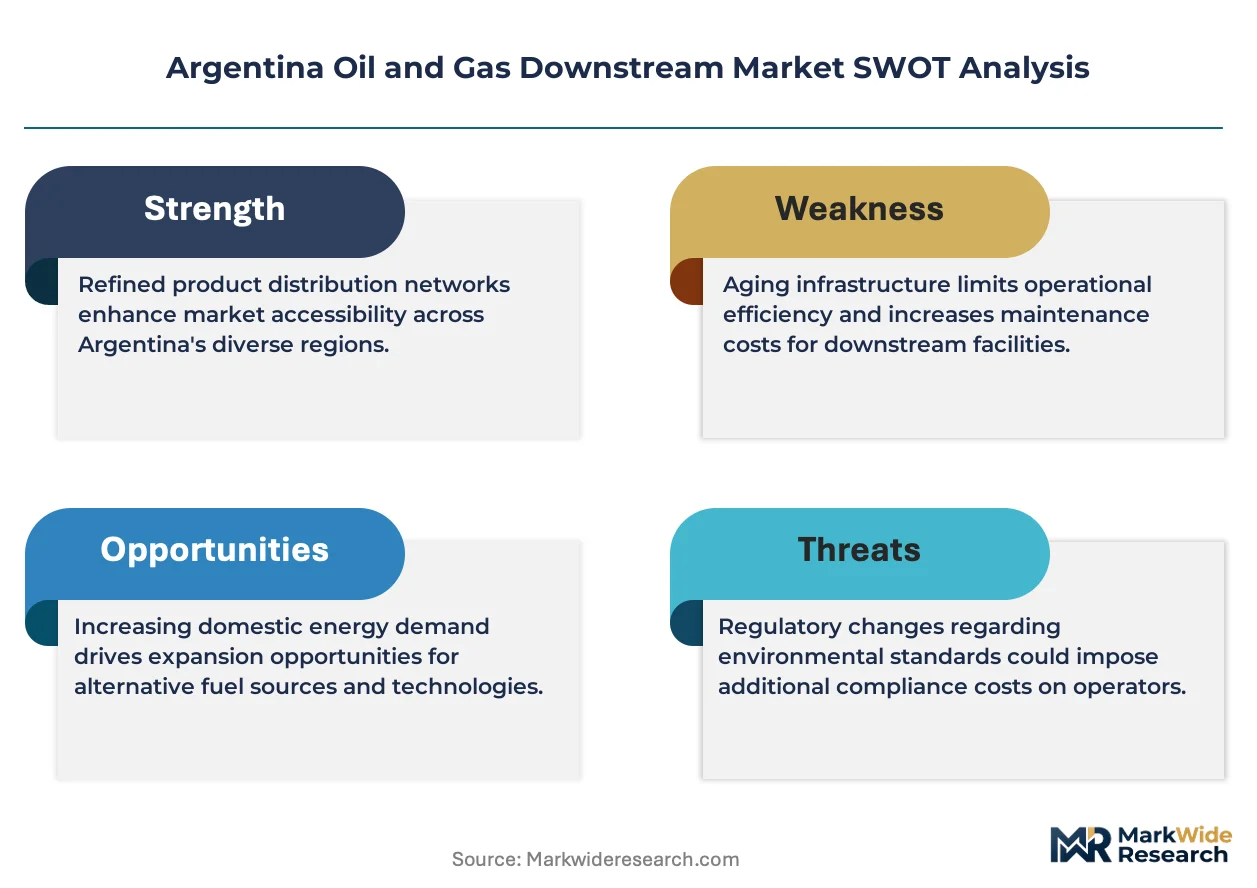
The Argentine Secretariat of Energy enforces biofuel blending mandates that reshape refinery yield slates and product certification requirements. The country's national environmental regulator imposes atmospheric emission standards that force continuous investment in sulfur recovery and flaring reduction systems. The Instituto Argentino del Petróleo y del Gas maintains technical protocols governing product quality and pipeline integrity. Stakeholders must monitor how federal energy pricing interventions interact with import parity mechanisms to determine sustained reinvestment feasibility.
Market Dynamics
Refinery modernization programs are compressing capital cycles as operators deploy advanced process control systems to squeeze yield improvements from aging infrastructure. The Argentine Secretariat of Energy's biofuel blending mandates are forcing simultaneous investments in renewable diesel hydrotreaters and conventional FCC unit upgrades, creating dual-track capital allocation pressure.
Growth Catalysts
- Renewable diesel integration:The Secretariat of Energy's escalating biofuel mandates are redirecting refinery output streams toward hydrotreated vegetable oil processing capacity.
- Buenos Aires automotive fleet expansion:Concentrated demand growth in Argentina's most populous province is pulling high-octane gasoline formulations through dedicated distribution corridors.
- Patagonian logistics integration:Upstream-downstream corridor consolidation is compressing crude delivery costs from Vaca Muerta formation to coastal refining centers.
Market Restraints
- Import parity pricing volatility:Federal energy pricing interventions create reinvestment uncertainty when domestic fuel prices disconnect from international crude benchmarks.
- Refinery complexity ceiling:Nelson complexity indices plateauing below 9.2 limit residue upgrading options and force continued fuel oil production.
- Sulfur recovery capex burden:The national environmental regulator's tightening atmospheric emission standards mandate continuous investment in Claus unit expansions.
Strategic Opportunities
- Mendoza province petrochemical feedstock gap:Underdeveloped propylene and aromatics extraction capacity creates white space for integrated refinery-petrochemical complexes.
- Power generation gas-to-liquid substitution:Northern provincial grids are accelerating diesel-fired backup capacity as pipeline gas reliability fluctuates.
- Digital twin deployment:Real-time optimization platforms are opening margin capture opportunities through predictive maintenance and energy efficiency gains.
Industry Challenges
- Process control systems integration:Legacy DCS architectures resist seamless integration with modern advanced process control layers, forcing costly rip-and-replace decisions.
- Hydrotreater catalyst supply security:Specialized noble metal catalyst procurement depends on concentrated international suppliers, exposing operations to freight and customs delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Oil and Gas Downstream Market |
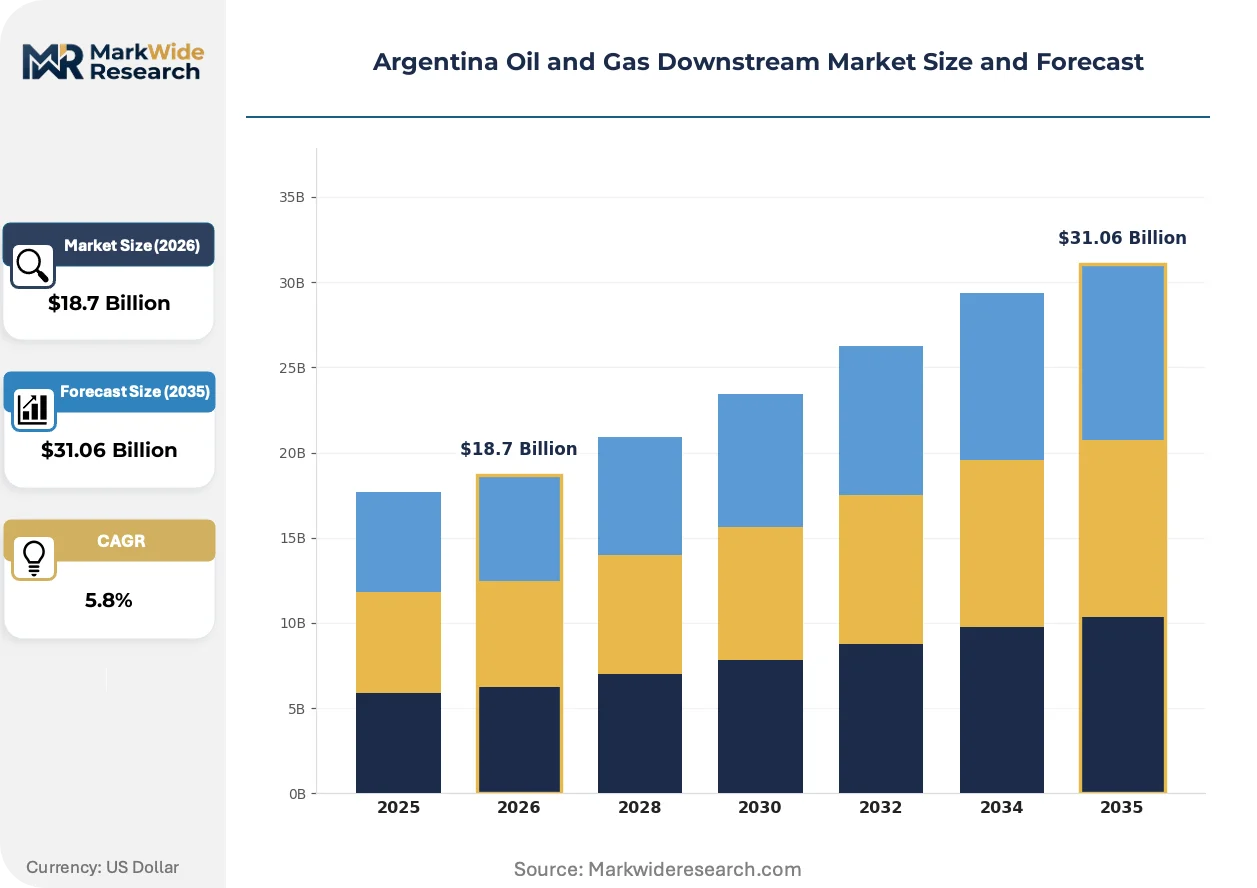
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Petrol, Diesel, Jet Fuel, Lubricants End User: Automotive, Aviation, Manufacturing, Power Generation Distribution Channel: Retail, Wholesale, Direct Sales, Online Sales Service Type: Refining, Storage, Transportation, Maintenance |
| Companies Covered | Pan American Energy SL, Puma Energy, Yacimientos Petrolíferos Fiscales SA, Refinor SA, Royal Dutch Shell PLC, Raizen SA, Pampa Energia SA, Campana Refinery Operations, Axion Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Oil and Gas Downstream Market Strategic Shifts
Digitalization is penetrating refinery operations through layered automation architectures that compress response times and flatten organizational hierarchies. Three interconnected developments are restructuring how Argentine downstream assets generate returns.
Advanced process control systems are hybridizing refinery unit operations by overlaying model-predictive algorithms atop distributed control system infrastructure. YPF's Luján de Cuyo complex is deploying these layers to optimize FCC reactor severity against real-time product pricing signals. The structural consequence is compressing the gap between laboratory analysis and setpoint adjustment from hours to minutes.
The Secretariat of Energy's biofuel certification protocols are tightening product quality documentation requirements across the entire supply chain. Refiners must now maintain chain-of-custody records from feedstock origin through blending terminal delivery. Diesel distribution networks bear the heaviest compliance burden as renewable diesel batches require segregated storage and dedicated certification pathways.
Fleet operators in Buenos Aires province are consolidating procurement through direct refinery offtake agreements that bypass traditional wholesale intermediaries. Large logistics companies are negotiating dedicated product streams with guaranteed sulfur and cetane specifications. This disintermediation is most visible in the agricultural mechanization segment, where seasonal demand spikes reward volume-commitment contracts over spot market exposure.
Argentina Oil and Gas Downstream Market Segmentation
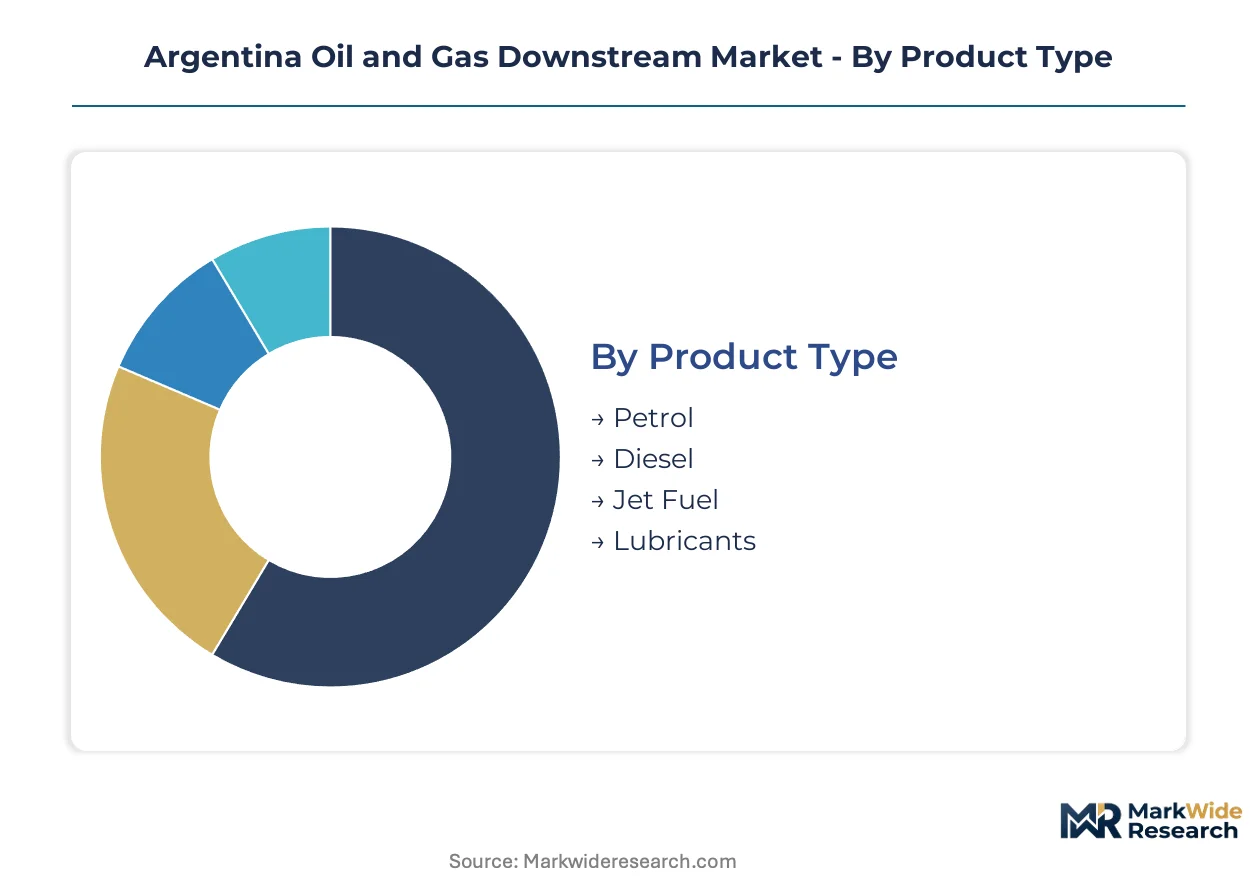
Segmentation in Argentina's downstream oil and gas sector reveals how capital cycles, regulatory exposure, and logistics complexity vary across product streams and customer interfaces. Understanding these fault lines helps operators allocate capacity investments and pricing power where structural advantages persist.
Product Type:
Inventory velocity diverges sharply across refined products, with transport fuels turning over in days while specialty lubricants sit in working capital for months.
- Petrol:High-octane formulations dominate Argentine refinery yield slates, with Buenos Aires province automotive fleets absorbing the bulk of premium-grade output. Argentine Secretariat of Energy biofuel blending mandates force continuous reformulation to maintain octane ratings while integrating ethanol streams.
- Diesel:Agricultural mechanization in the Pampas region and freight corridor expansion along Route 9 concentrate demand for low-sulfur diesel with precise cetane specifications. Refiners face dual pressure from renewable diesel hydrotreater investments and conventional hydrocracker upgrades to meet tightening sulfur protocols.
- Jet Fuel:Aeroparque and Ezeiza international airports anchor aviation kerosene demand, with strict Jet A-1 certification requirements limiting qualified supply sources.
- Lubricants:Specialized blending operations at Campana and Luján de Cuyo complexes serve industrial maintenance cycles with extended replacement intervals.
Petrol dominates installed base. Diesel is where expansion concentrates.
End User:
Margin capture potential scales inversely with price transparency, creating tiered profitability across customer categories with varying procurement sophistication.
- Automotive:Individual vehicle owners and fleet operators in Córdoba and Santa Fe provinces generate predictable demand for standardized gasoline and diesel formulations, with seasonal planting and harvest cycles amplifying volume spikes.
- Aviation:International carriers and domestic operators at Argentina's 33 commercial airports require certified Jet A-1 with documented cold-flow properties and traceable supply chain custody from refinery to wing.
- Manufacturing:Industrial process heat applications in Mendoza and San Juan provinces consume fuel oil and diesel for captive power generation, with Argentine Secretariat of Energy emission standards forcing continuous burner technology upgrades.
- Power Generation:Northern provincial grids in Formosa and Chaco deploy diesel-fired backup capacity where pipeline gas reliability fluctuates, creating the steepest expansion trajectory among end-use categories as gas-to-liquid substitution accelerates.
Automotive anchors volume throughput. Power Generation commands the steepest margin expansion.
Distribution Channel:
Channel economics reflect working capital intensity and customer concentration, with direct relationships compressing intermediation costs at scale.
- Retail:Branded service stations across Argentina's national route network maintain consumer-facing fuel sales with regulated pricing exposure to federal energy policy interventions.
- Wholesale:Independent distributors and cooperatives aggregate demand from smaller commercial fleets, absorbing inventory risk in exchange for volume-based margin structures.
- Direct Sales:Large agricultural conglomerates and mining operations in Catamarca and San Juan negotiate refinery offtake agreements with guaranteed specifications and dedicated delivery windows.
- Online Sales:Digital procurement platforms for lubricants and specialty products are gaining traction among industrial maintenance departments seeking transparent pricing and consolidated vendor management.
Retail commands the widest geographic footprint. Direct Sales captures the deepest per-liter margins.
Service Type:
Asset intensity and regulatory scrutiny vary across the value chain, with refining absorbing the heaviest capital deployment and maintenance generating the most recurring revenue.
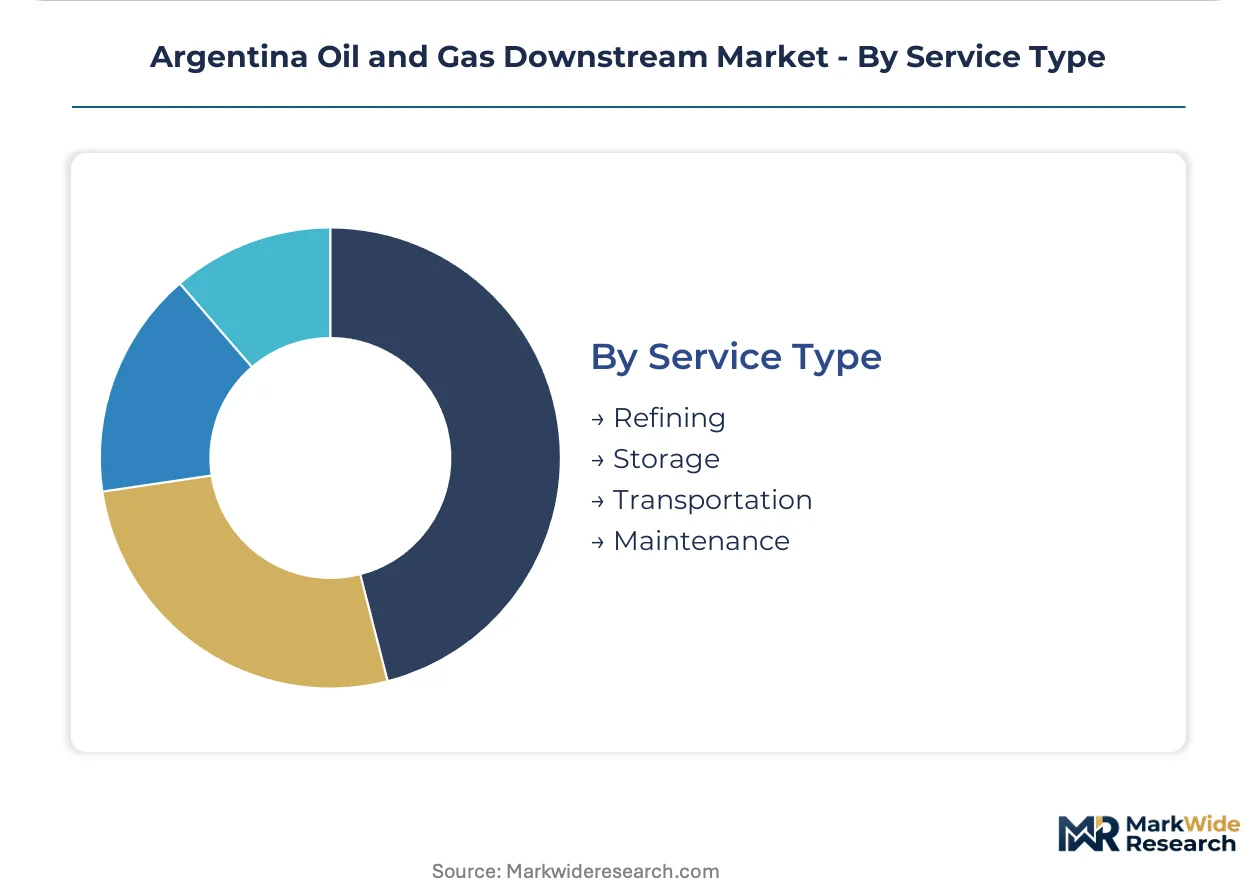
- Refining:Crude conversion operations at Luján de Cuyo, La Plata, and Campana complexes transform domestic Vaca Muerta and imported crudes into transport fuels, with Nelson complexity indices between 6.5 and 9.2 limiting residue upgrading options.
- Storage:Tank farm operations at coastal terminals and inland distribution hubs buffer supply disruptions, with Argentine environmental regulations mandating secondary containment and vapor recovery systems.
- Transportation:Pipeline networks, rail tankers, and tanker trucks move refined products from coastal refineries to interior consumption centers, with Patagonian corridor consolidation reducing crude delivery costs.
- Maintenance:Turnaround services and catalyst replacement cycles generate recurring demand from refiners seeking to maximize run lengths between planned outages.
Refining absorbs the largest capital base. Transportation infrastructure is where network effects concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina exports refined petroleum products to neighboring Mercosur members and Andean markets, with Patagonian crude flowing north to Chilean refineries and diesel crossing into Paraguay and Uruguay through dedicated pipeline corridors.
Buenos Aires Province
Buenos Aires automotive fleet expansion concentrates demand for high-octane gasoline formulations across the Greater Buenos Aires metropolitan area. The Argentine Secretariat of Energy enforces biofuel blending mandates that redirect refinery output toward renewable diesel integration at La Plata and Campana complexes. Fleet operators in the provincial capital negotiate direct offtake agreements with guaranteed sulfur and cetane specifications.
Mendoza Province
Underdeveloped propylene and aromatics extraction capacity creates white space for integrated refinery-petrochemical complexes in Argentina's western wine-growing region. The national environmental regulator imposes atmospheric emission standards that force continuous investment in sulfur recovery systems at Luján de Cuyo. Industrial process heat applications in the provincial capital consume fuel oil and diesel for captive power generation.
Patagonian Corridor
Upstream-downstream corridor consolidation compresses crude delivery costs from Vaca Muerta formation to coastal refining centers across Neuquén and Río Negro provinces. Pan American Energy SL leverages integrated logistics to sustain cost advantages through dedicated transport infrastructure. The Luján de Cuyo complex anchors refining capacity for Vaca Muerta light sweet crude processing.
Northern Provinces
Formosa and Chaco provincial grids accelerate diesel-fired backup capacity as pipeline gas reliability fluctuates, creating the steepest expansion trajectory among end-use categories. Power generation represents the fastest-growing demand category as gas-to-liquid substitution accelerates. Seasonal agricultural mechanization in these provinces amplifies volume spikes for low-sulfur diesel with precise cetane specifications.
Córdoba and Santa Fe
Individual vehicle owners and fleet operators in these central provinces generate predictable demand for standardized gasoline and diesel formulations. The Instituto Argentino del Petróleo y del Gas maintains technical protocols governing product quality and pipeline integrity across the distribution network. Agricultural conglomerates in these regions negotiate refinery offtake agreements with dedicated delivery windows.
Argentina Oil and Gas Downstream Market Competitive Environment
On the supply side, the industry is consolidated around a dominant state-affiliated operator with integrated midstream assets, flanked by international majors with specialized lubricant and retail positioning. Strategic archetypes include national champions controlling refining complexity, international traders optimizing import parity arbitrage, and regional specialists capturing agricultural procurement cycles. Dominant competitive moves center on refinery modernization capex deployment and direct fleet offtake contract negotiation.
Within the national champion archetype, Yacimientos Petrolíferos Fiscales SA anchors the domestic refining base through its dominance of the Luján de Cuyo and La Plata complexes. Pan American Energy SL occupies a position exemplifying integrated upstream-downstream logistics across Patagonian supply corridors. Axion Energy represents the specialized blending capacity segment at its Campana facility.
| Leading Market Players |
|---|
| Pan American Energy SL |
| Puma Energy |
| Yacimientos Petrolíferos Fiscales SA |
| Refinor SA |
| Royal Dutch Shell PLC |
| Raizen SA |
| Pampa Energia SA |
| Campana Refinery Operations |
| Axion Energy |
| Others |
Value Chain & Pricing Dynamics
Refinery undercapacity in Mendoza province is compressing supplier margins while amplifying pricing power for operators with spare hydrotreater capacity. Argentine Secretariat of Energy biofuel mandates are forcing simultaneous renewable diesel and conventional unit investments, creating dual-track cost pressures that transmit differentially across product grades.
Pricing Analysis
Legacy FCC unit pricing diverges sharply from hydrotreater-upgraded renewable diesel streams, with the technology-generation gap widening as certification requirements tighten. Three-tier pricing structure across premium low-sulfur diesel, standard highway diesel, and economy-grade fuel oil segments dominates transactional structures. Price differentiation hinges on sulfur content certification and volume-commitment scale, with agricultural conglomerates commanding steepest discounts through direct offtake contracts. Cost compression in standard diesel is intensifying because hydrotreater catalyst procurement bottlenecks are elevating unit operating costs. Fleet operators in Buenos Aires province exhibit lowest price sensitivity due to specification-locked procurement, while independent wholesale distributors face margin erosion from spot market volatility.
Supply Chain Analysis
Upstream Vaca Muerta light sweet crude feeds from Neuquén province while imported medium sour crudes draw from Brazil, Colombia, and US Gulf Coast terminals. Noble metal catalysts, specialized hydrotreater internals, and advanced process control systems rest on concentrated international suppliers, exposing operations to freight and customs delays. Single-source vulnerability in hydrotreater catalyst procurement creates operational risk when Argentine customs processing extends beyond standard windows. Distribution runs through coastal refining centers at La Plata and Campana, with pipeline networks extending to Buenos Aires province distribution hubs and Patagonian corridor consolidation reducing crude delivery costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized hydrotreater engineering talent and renewable diesel certification expertise are in critically short supply across Argentine downstream operations, constraining how quickly operators can execute mandated capacity transitions.
For Market Incumbents: Insulate refining margin pools by accelerating captive renewable diesel hydrotreater capacity at Luján de Cuyo and La Plata complexes before regulatory mandates tighten further. Secure long-term offtake agreements with Buenos Aires province fleet operators to lock in volume commitments ahead of potential import parity pricing volatility. Prioritize backward integration into Vaca Muerta crude logistics through dedicated pipeline capacity to compress feedstock delivery costs. For New Entrants and Emerging Players: Northern provincial power generation diesel supply represents the most penetrable white-space segment, with Formosa and Chaco grids accelerating gas-to-liquid substitution and incumbent distributors underweight in backup capacity logistics. Mendoza province petrochemical feedstock extraction capacity offers secondary entry point through propylene and aromatics supply gaps. Pursue direct refinery offtake relationships with agricultural cooperatives in Córdoba and Santa Fe provinces, bypassing wholesale intermediation through guaranteed cetane and sulfur specifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across renewable diesel hydrotreater installations as dual-track conventional and biofuel unit investments compress project returns. Target acquisition profile centers on mid-scale refiners with stranded FCC assets convertible to hydrotreater service, particularly those with existing La Plata corridor pipeline access. Monitor Argentine Secretariat of Energy biofuel mandate escalation announcements as primary inflection signal for reinvestment feasibility windows.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Diesel Hydrotreater Deployment | YPF's Luján de Cuyo complex anchors compliance with escalating Secretariat of Energy biofuel mandates. |
| Vaca Muerta Logistics Integration | Pan American Energy SL compresses crude delivery costs through dedicated Patagonian corridor infrastructure. |
| Direct Fleet Offtake Agreements | Buenos Aires province agricultural conglomerates secure guaranteed sulfur specifications bypassing wholesale channels. |
| Digital Twin Process Control Implementation | Real-time optimization platforms at La Plata reduce laboratory-to-setpoint adjustment cycles from hours to minutes. |
| Propylene Extraction Capacity Addition | Mendoza province integrated refinery-petrochemical complexes address underdeveloped aromatics supply gaps. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refinery operations directors, downstream logistics managers, biofuel compliance officers, and agricultural fleet procurement heads. Secondary validation drew from Argentine Secretariat of Energy regulatory filings, Instituto Argentino del Petróleo y del Gas technical protocols, customs crude import records, and refinery capacity utilization disclosures. Bottom-up unit economics modeling triangulated against top-down sector expenditure patterns.
Calibration against historical capacity additions, regulatory implementation timelines, and feedstock cost trajectories anchored projection parameters across the analysis window. Segmentation dimensions modeled include product type, end user category, distribution channel structure, and service type complexity. CAGRs were derived from slope analysis of segment-specific demand curves and supply-side capacity response functions. Forecast inputs incorporated Nelson complexity index constraints, hydrotreater catalyst replacement cycles, and biofuel mandate escalation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by international traders optimizing import parity arbitrage would shift outcomes beyond modeled ranges. Unanticipated regulatory acceleration, Vaca Muerta production volatility, or hydrotreater catalyst supply disruptions could compress or extend capacity utilization trajectories. Quarterly review of Secretariat of Energy mandate announcements, hydrotreater catalyst freight indices, and northern provincial grid diesel procurement tenders is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Europe LNG Bunkering Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
Floating Liquefied Natural Gas (FLNG) Market
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Norway Oil and Gas Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Norway Oil and Gas Downstream Market