
 Nuclear Power Market | 2026-2036
Nuclear Power Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Power Market Analysis
The specialized welding and reactor vessel fabrication workforce is rotating toward next-generation construction programs, tightening labor availability for conventional projects. Electricité de France leverages its vertically integrated engineering division to retain captive talent pools for European pressurized water reactor builds. Rosatom State Atomic Energy Corporation dominates turnkey export contracts across emerging nuclear entrants, sustaining long-term fuel-cycle revenue through integrated service agreements. China National Nuclear Corporation anchors the largest domestic order book, positioning its supply chain for serial manufacturing of indigenous reactor designs.
Nuclear power denotes the controlled fission of uranium-235 or plutonium-239 isotopes within moderated reactor cores to generate thermal energy, typically operating at primary coolant pressures of 15.5 MPa in pressurized water configurations and achieving thermal efficiencies of 33-37 percent for electricity conversion. Pressurized water reactor technology occupies the dominant installed base, while small modular and advanced reactor variants attract the fastest-growing capital allocation. Engineering services and fuel supply segments command concentrated margin pools due to regulatory barriers and long-term contractual structures. Decommissioning activity expands as first-generation reactors reach end-of-design-life, creating demand for specialized waste handling and site remediation expertise.
The US Nuclear Regulatory Commission's Part 52 licensing framework and the EU's F-Gas Regulation together shape equipment standards and coolant chemistry requirements across Western markets. China's National Nuclear Safety Administration and the State Administration for Market Regulation enforce indigenous construction codes that constrain foreign vendor participation. India's Atomic Energy Regulatory Board and the Department of Atomic Energy maintain public-sector control over reactor siting and fuel cycle operations. Stakeholders must monitor regulatory divergence between Western certification regimes and state-driven approval pathways, as this fragmentation determines vendor eligibility and project finance availability for cross-border reactor exports.
Market Dynamics
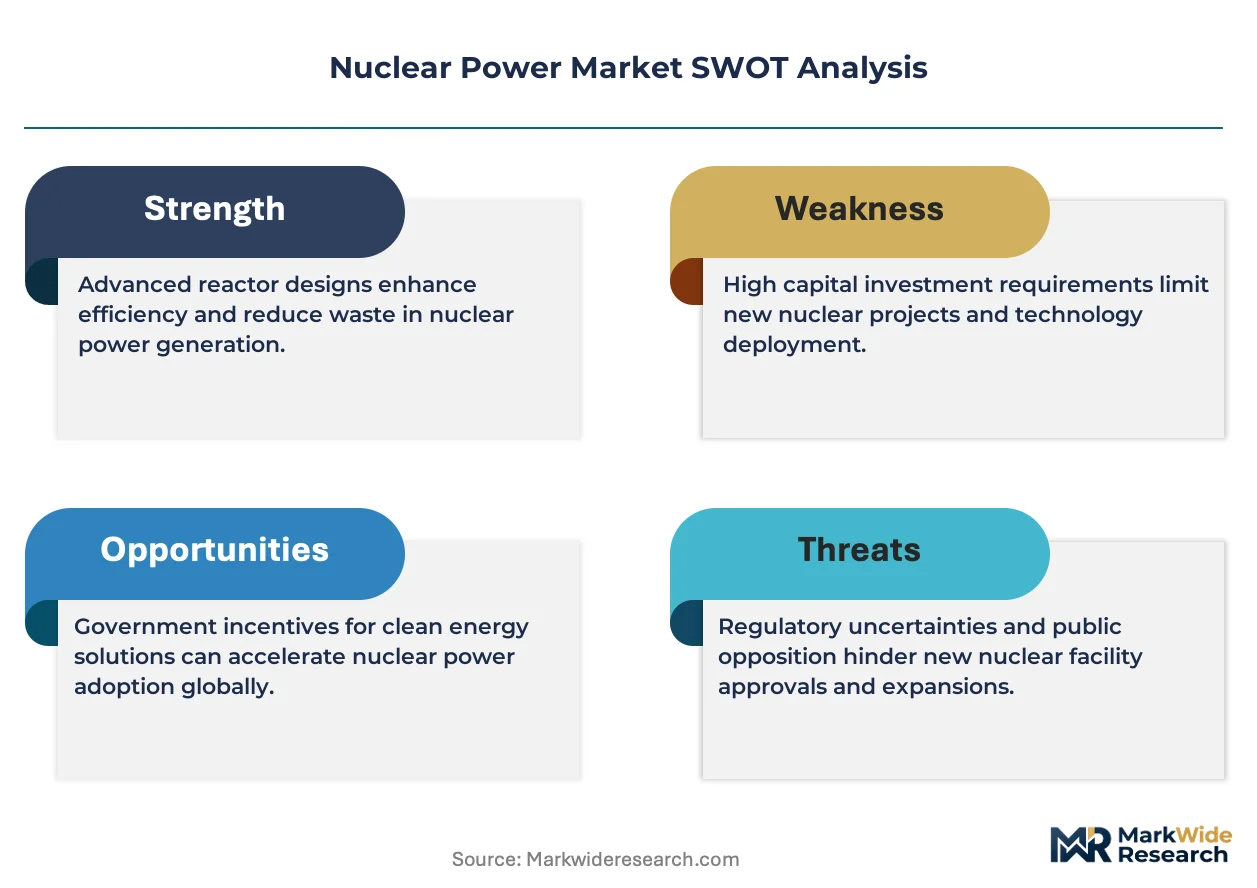
The US Nuclear Regulatory Commission's Part 52 licensing framework is compressing project approval timelines for small modular reactors while fragmenting vendor eligibility across Western and state-driven certification pathways.
Growth Catalysts
- EU Taxonomy Recognition:The European Union's classification of nuclear as a sustainable activity under the EU Green Deal redirects institutional capital toward reactor construction and refurbishment programs.
- Baseload Electrification:Data center operators and heavy industrial facilities are contracting dedicated nuclear capacity to secure carbon-free power supply with 24/7 availability guarantees.
- SMR Design Certification:The US Nuclear Regulatory Commission's streamlined approval pathways for small modular reactor designs are accelerating deployment timelines for standardized factory-built units.
Market Restraints
- Uranium Fuel Concentration:Enrichment services and conversion capacity concentrate in a limited set of state-controlled suppliers, exposing Western utilities to supply disruption risks.
- Construction Cost Escalation:Specialized reactor vessel forging, precision welding, and civil concrete work face input cost volatility due to constrained qualified contractor pools.
- Long-Term Waste Liability:The absence of operational high-level waste repositories in the United States and several European markets creates indefinite interim storage obligations.
Strategic Opportunities
- Export Market Expansion:Emerging nuclear entrants in Southeast Asia and Eastern Europe present turnkey construction opportunities for vendors with integrated fuel-cycle service capabilities.
- Hydrogen Co-Production:High-temperature reactor designs enable thermochemical hydrogen production, opening industrial decarbonization applications beyond electricity generation.
- Decommissioning Services:First-generation reactor fleets in France, Japan, and the United States are reaching end-of-design-life, creating demand for specialized waste handling and site remediation expertise.
Industry Challenges
- Certification Timeline Compression:The US Nuclear Regulatory Commission's design certification and combined license processes extend 5-7 years, delaying revenue recognition and straining project finance structures.
- Welding Workforce Scarcity:ASME Section IX qualified nuclear welders and reactor vessel fabrication specialists are rotating toward small modular reactor programs, tightening availability for conventional large-scale builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Power Market |
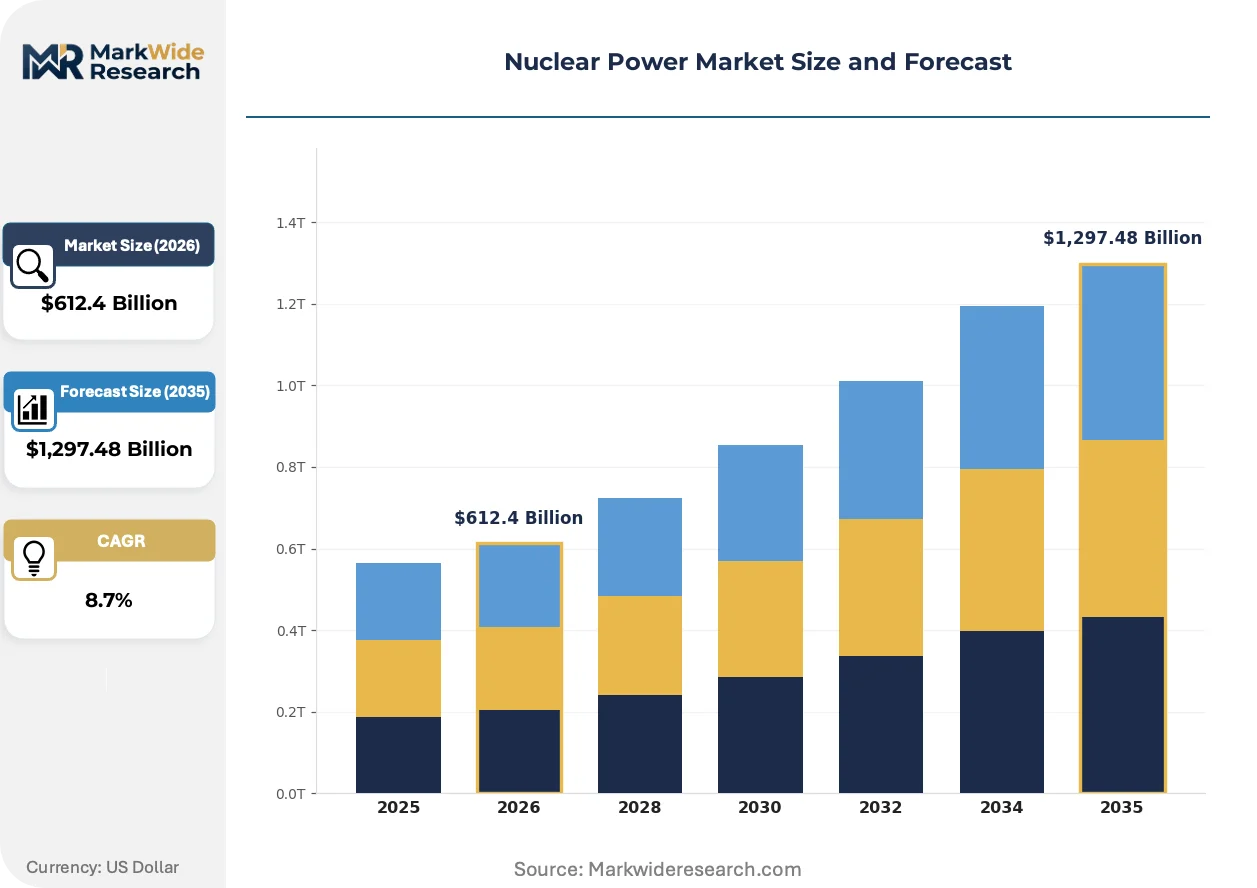
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,297.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pressurized Water Reactor, Boiling Water Reactor, Advanced Gas-cooled Reactor, Liquid Metal Fast Breeder Reactor End User: Utilities, Government Agencies, Industrial Plants, Research Institutions Service Type: Operation & Maintenance, Decommissioning, Fuel Supply, Engineering Services Application: Electricity Generation, Desalination, District Heating, Research |
| Companies Covered | Electricité de France (EDF), Rosatom State Atomic Energy Corporation, Korea Electric Power Corporation (KEPCO), Constellation Energy Corp., Duke Energy Corporation, Exelon Corporation, China National Nuclear Corporation, NextEra Energy, Cameco Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Power Market Emerging Trajectories
Reactor technology trajectories are diverging between evolutionary large-scale designs and standardized small modular platforms, with regulatory frameworks and capital structures adapting to accommodate both pathways simultaneously.
Small modular reactor development is bifurcating the supply base into two distinct tiers. Factory-fabricated SMR designs from NuScale, Rolls-Royce, and China's CNNC are attracting venture capital and sovereign wealth fund commitments for serial manufacturing. This technology is bifurcating procurement patterns away from field-constructed gigawatt-scale projects toward repeatable module deployment with compressed construction schedules.
The European Union's F-Gas Regulation is tightening coolant chemistry standards for reactor auxiliary systems and spent fuel pool cooling circuits. Equipment suppliers must reformulate heat transfer fluids and sealing materials to comply with phasedown schedules for high-global-warming-potential substances. French and German component manufacturers are accelerating R&D programs to certify alternative chemistries before the 2030 restriction deadlines.
Utility procurement departments are unbundling long-term service agreements into discrete fuel supply, engineering support, and outage management contracts. This purchasing pattern shift disrupts the traditional integrated vendor model that Rosatom and Westinghouse have deployed for decades. Independent engineering firms and specialized fuel brokers are capturing margin pools in the United States and United Kingdom markets where competitive tendering rules now apply.
Nuclear Power Market Segmentation
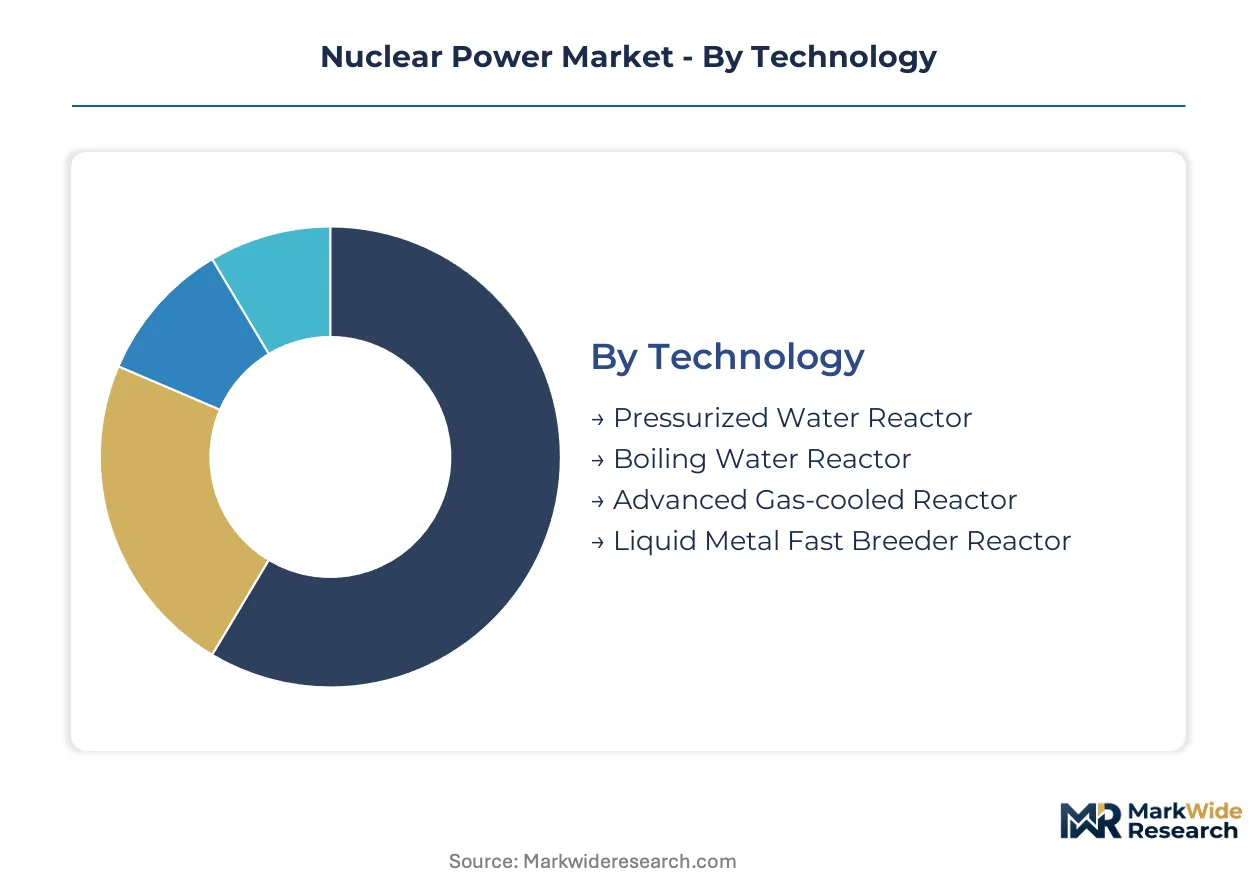
Technology choices in nuclear power lock in decades-long capital commitments and regulatory pathways. Segmentation reveals how reactor design, customer type, and service structure determine vendor eligibility and margin capture across divergent national frameworks.
Technology:
The US Nuclear Regulatory Commission's Part 52 framework and China's National Nuclear Safety Administration operate divergent certification pathways that reshape vendor competitiveness by reactor type.
- Pressurized Water Reactor:Light water moderated systems operating at 15.5 MPa primary pressure dominate installed capacity globally. Chinese state-backed construction programs in Fujian and Guangdong provinces concentrate demand for indigenous Hualong One variants, while EDF's Flamanville 3 project in France illustrates Western deployment challenges.
- Boiling Water Reactor:Direct-cycle designs eliminate steam generators, reducing capital cost but requiring larger containment structures. Japan's Nuclear Regulation Authority has prioritized BWR restarts at Kashiwazaki-Kariwa under post-Fukushima safety standards, sustaining domestic supply chains for Hitachi-GE joint ventures.
- Advanced Gas-cooled Reactor:Carbon dioxide-cooled graphite-moderated systems operate at higher thermal efficiency. The United Kingdom's EDF Energy operates the remaining AGR fleet at Hunterston and Torness, with decommissioning timelines accelerating specialized waste handling demand.
- Liquid Metal Fast Breeder Reactor:Sodium-cooled configurations enable plutonium breeding and actinide transmutation. Russia's BN-800 at Beloyarsk represents the sole commercial-scale operational unit, with India's Prototype Fast Breeder Reactor at Kalpakkam pursuing indigenous fuel cycle closure.
Pressurized water designs handle the majority of throughput; liquid metal fast breeder reactors are expanding most quickly on share as closed-fuel-cycle programs advance.
End User:
Customer concentration varies sharply between state-controlled procurement and competitive tendering regimes, with implications for contract structure and vendor financing.
- Utilities:Vertically integrated power generators with baseload portfolio mandates drive reactor construction decisions. Électricité de France and China National Nuclear Corporation maintain captive engineering divisions that internalize construction risk and retain specialized welding workforces.
- Government Agencies:Sovereign entities control siting, fuel cycle operations, and strategic reserve policies. India's Department of Atomic Energy maintains public-sector exclusivity over reactor ownership, constraining private capital participation.
- Industrial Plants:Heavy manufacturing and chemical processing facilities contract dedicated nuclear capacity for process heat and carbon-free power supply. Data center operators in Northern Virginia and Frankfurt are negotiating offtake agreements with SMR developers for 24/7 availability guarantees.
- Research Institutions:National laboratories and university consortia operate experimental reactors for materials testing and isotope production. Oak Ridge National Laboratory's High Flux Isotope Reactor in Tennessee supplies medical radioisotopes to domestic healthcare networks.
Utilities command the dominant procurement volume; industrial plants are gaining share fastest as corporate decarbonization targets harden.
Service Type:
Regulatory barriers and long-term liability structures fragment service provision between integrated vendors and specialized independents.
- Operation & Maintenance:Refueling outages, in-service inspection, and primary system maintenance require ASME Section XI qualified personnel. Westinghouse and Framatome compete for outage management contracts at US and European utilities unbundling from historical service agreements.
- Decommissioning:Reactor dismantlement, spent fuel removal, and site remediation create demand for radiological characterization and waste packaging expertise. France's CEA and the UK's Nuclear Decommissioning Authority are tendering major contracts as first-generation reactors reach end-of-design-life.
- Fuel Supply:Uranium conversion, enrichment, and fabrication services concentrate in state-controlled suppliers. Rosatom's TVEL subsidiary and Orano in France sustain long-term fuel-cycle revenue through integrated service agreements with emerging nuclear entrants.
- Engineering Services:Design certification support, licensing documentation, and construction supervision command premium margins due to regulatory complexity. Jacobs Engineering and Wood Group are capturing market share in the United Kingdom and United States as competitive tendering rules displace captive utility engineering divisions.
Operation and maintenance absorbs the largest service expenditure; decommissioning is climbing the fastest as reactor fleets age.
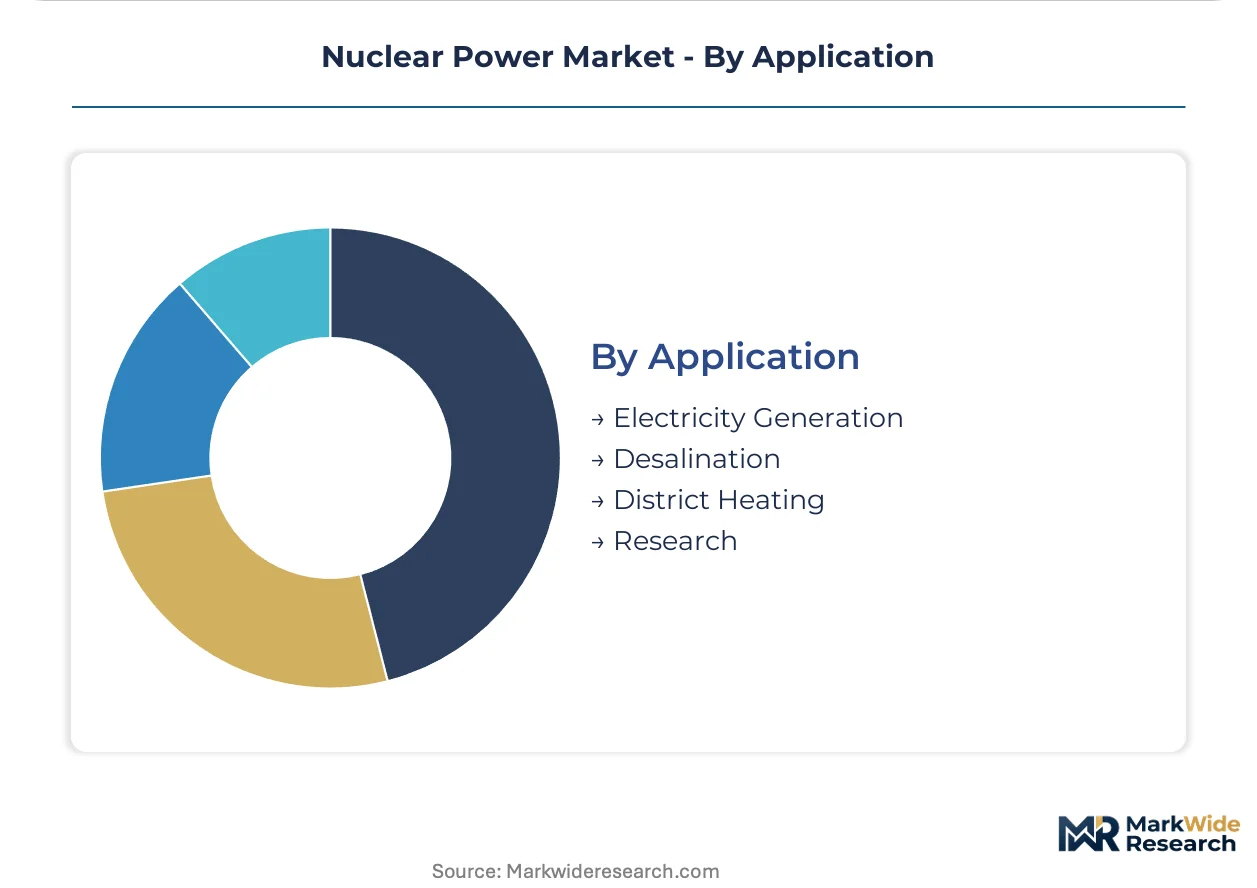
Application:
Non-electric applications are redirecting capital toward high-temperature reactor designs with process heat output capabilities.
- Electricity Generation:Grid-connected baseload supply remains the dominant revenue application. China's State Grid Corporation integrates reactor output into ultra-high-voltage transmission corridors spanning provincial boundaries.
- Desalination:Cogeneration configurations pair thermal desalination with electricity production. Saudi Arabia's Saline Water Conversion Corporation has evaluated SMR coupling for Red Sea coastal facilities.
- District Heating:Low-temperature reactor output supplies municipal heating networks in cold climates. Russia's Leningrad NPP-2 delivers district heat to Saint Petersburg suburbs through dedicated heat distribution infrastructure.
- Research:Materials testing, medical isotope production, and training reactor operations serve specialized institutional demand. Australia's OPAL reactor at Lucas Heights supplies molybdenum-99 to domestic and Asia-Pacific healthcare markets.
Electricity generation retains the dominant application share; district heating is gaining traction fastest where municipal infrastructure permits direct thermal integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Nuclear Regulatory Commission's Part 52 licensing framework anchors the dominant Western market, while China's National Nuclear Safety Administration drives the largest state-backed construction pipeline. Deployment patterns diverge sharply between these regulatory regimes.
United States
Data center operators in Northern Virginia and Texas are contracting dedicated nuclear capacity for carbon-free baseload supply. The US Nuclear Regulatory Commission's SMR design certification pathways are compressing approval timelines for factory-built reactor modules. Dominion Energy and Duke Energy are advancing small modular reactor projects in the Southeast, leveraging existing transmission infrastructure.
China
State-backed construction programs in Fujian and Guangdong provinces are outpacing Western deployment timelines for indigenous Hualong One designs. The National Nuclear Safety Administration and State Administration for Market Regulation enforce construction codes that constrain foreign vendor participation. CNNC's supply chain in Zhejiang and Jiangsu is scaling for serial manufacturing of pressurized water reactor components.
France
Électricité de France is leveraging its vertically integrated engineering division for European pressurized water reactor builds at Flamanville and Penly. The EU Green Deal taxonomy classification redirects institutional capital toward refurbishment and new construction programs. The Grand Carénage life extension program is sustaining specialized welding workforces at Creusot Forge and other component fabricators.
Russia
Rosatom State Atomic Energy Corporation dominates turnkey export contracts across emerging nuclear entrants in Bangladesh, Turkey, and Egypt. The BN-800 fast breeder reactor at Beloyarsk represents the sole commercial-scale operational unit of its type. TVEL subsidiary maintains long-term fuel-cycle revenue through integrated service agreements with import-dependent utilities.
India
The Department of Atomic Energy maintains public-sector exclusivity over reactor siting and fuel cycle operations, constraining private capital participation. The Atomic Energy Regulatory Board oversees construction of indigenous pressurized heavy water reactors at Kakrapar and Rajasthan. The Prototype Fast Breeder Reactor at Kalpakkam is pursuing closed-fuel-cycle capability with sodium-cooled technology.
Nuclear Power Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with state-backed entities occupying positions that Western vendors cannot replicate. The upper tier commands turnkey export contracts and captive fuel-cycle services, while mid-tier specialists compete for discrete engineering and outage management contracts. Two strategic archetypes dominate: sovereign integrated vendors with complete fuel-cycle control, and unbundled service providers capturing margin in competitive tendering markets. Competitive moves center on design certification acceleration and workforce retention through captive engineering divisions.
Among state-backed integrated vendors, Electricité de France and Rosatom State Atomic Energy Corporation exemplify the sovereign archetype with vertically controlled construction and fuel supply capabilities. Constellation Energy Corp. occupies a position within the competitive unbundled tier, representing utilities that have separated generation assets from integrated vendor structures. These three entities span the structural divide between state-directed and market-driven procurement regimes.
| Leading Market Players |
|---|
| Electricité de France (EDF) |
| Rosatom State Atomic Energy Corporation |
| Korea Electric Power Corporation (KEPCO) |
| Constellation Energy Corp. |
| Duke Energy Corporation |
| Exelon Corporation |
| China National Nuclear Corporation |
| NextEra Energy |
| Cameco Corp. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at specialized reactor vessel forges in France and Japan sits above 85 percent, concentrating pricing power among qualified fabricators while compressing margins for second-tier engineering contractors competing on conventional nuclear construction programs.
Pricing Analysis
Geographic price spreads for nuclear-grade steel forgings and precision welding services run 40-60 percent higher in Western Europe than in China's Zhejiang and Jiangsu manufacturing clusters, where state-backed capacity expansion has compressed supplier margins. Contract-based long-term offtake agreements dominate utility procurement, with price differentiation driven by ASME Section IX certification tier and after-sales outage management bundling. Cost compression in standard pressurized water reactor components is intensifying as Chinese serial manufacturing scales, while margins are tightening for specialized fast breeder reactor fabricators due to limited order volumes. State-owned utilities in China and Russia exhibit the lowest price sensitivity, while competitive tendering regimes in the United Kingdom and United States force Western vendors to absorb more construction risk.
Supply Chain Analysis
China, Russia, and France anchor the global supply base for reactor pressure vessels, fuel assemblies, and integrated fuel-cycle services. The supply chain draws from Kazakhstan and Canada for uranium ore conversion, Uzbekistan and Namibia for yellowcake feedstock, and Russia's TVEL subsidiary for enrichment services. Single-source vulnerability concentrates in Rosatom's integrated fuel supply agreements, which tether emerging nuclear entrants to long-term contractual dependencies. Distribution runs through turnkey export contracts for state-backed vendors and competitive tendering channels for unbundled service providers in Western markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nuclear power hardware deployment generates substantial downstream service-attach potential, with decommissioning and specialized waste handling contracts expanding faster than new reactor construction revenue across aging Western fleets.
For Market Incumbents: Compound captive engineering workforce retention through vertically integrated construction divisions that internalize welding and reactor vessel fabrication expertise. Defend market position by accelerating small modular reactor design certification with the US Nuclear Regulatory Commission before emerging entrants secure first-mover regulatory approval. Prioritize fuel-cycle service agreement extensions with import-dependent utilities in Southeast Asia and Eastern Europe to lock in long-term revenue streams against independent fuel brokers.
For New Entrants and Emerging Players: Lead with specialized decommissioning and site remediation capabilities targeting first-generation reactor fleets in France, Japan, and the United States where incumbent vendors lack dedicated service units. Target the United Kingdom's competitive tendering regime for engineering services and outage management contracts, where unbundling from historical service agreements has opened procurement to independent specialists. Pursue direct contracting relationships with data center operators in Northern Virginia and Frankfurt seeking dedicated nuclear capacity for carbon-free baseload supply.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering service specialists with ASME Section XI qualified personnel and radiological characterization capabilities over pure-play reactor developers facing extended certification timelines. Long-term viability hinges on exposure to decommissioning liability management and fuel-cycle services rather than construction-dependent revenue. Monitor regulatory divergence between the US Nuclear Regulatory Commission's Part 52 framework and China's National Nuclear Safety Administration as the primary inflection indicator for vendor eligibility and cross-border project finance availability.
| Strategic Initiative | Industry Significance |
|---|---|
| SMR Design Certification | US Nuclear Regulatory Commission approval compresses deployment timelines for factory-built reactor modules. |
| Fuel-Cycle Service Extension | Rosatom's TVEL subsidiary sustains long-term revenue through integrated agreements with import-dependent utilities. |
| Decommissioning Capability Buildout | France's CEA and UK's Nuclear Decommissioning Authority tender major contracts as reactor fleets age. |
| Welding Workforce Retention | EDF's vertically integrated engineering division retains captive talent pools for European pressurized water reactor builds. |
| Hydrogen Co-Production Partnership | High-temperature reactor designs enable thermochemical hydrogen production for industrial decarbonization applications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, nuclear reactor engineering directors, fuel supply procurement leads, and specialized welding contractor supervisors. Secondary validation drew from US Nuclear Regulatory Commission licensing databases, International Atomic Energy Agency reactor construction tracking, European Union taxonomy implementation reports, and national nuclear safety administration filings in China and India. Bottom-up project pipeline enumeration was triangulated against top-down capacity expansion announcements from state-backed utilities.
Across the analysis window, the forecasting framework modeled reactor technology type, end-user procurement regime, service structure unbundling, and regional regulatory cluster segmentation. CAGRs were derived from installation capacity trajectories, decommissioning liability schedules, and fuel-cycle contract renewal patterns. Key inputs included state-backed construction program announcements in Fujian and Guangdong provinces, US data center offtake negotiations, and European pressurized water reactor build timelines at Flamanville and Penly.
Forecasts assume regulatory continuity in the US Nuclear Regulatory Commission Part 52 framework, the EU Green Deal taxonomy, and China's National Nuclear Safety Administration approval pathways; material policy shifts would require re-modeling vendor eligibility and project finance availability. Specific risks include uranium supply disruption from state-controlled enrichment concentration, welding workforce scarcity compressing construction schedules, and waste repository licensing delays extending interim storage obligations. Recalibration cycles align with material shifts in regulatory divergence, SMR certification milestones, and decommissioning contract award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Nuclear Energy Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Decommissioning Services Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Small Modular Reactor (SMR) Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market