
 Global Thorium Reactor Market | 2026-2036
Global Thorium Reactor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thorium Reactor Market Foresight
Nuclear physicist and molten salt chemist availability is bifurcating the competitive landscape into teams that can staff prototype builds and those stalled at conceptual design. TerraPower leverages its Bill Gates-backed funding base to anchor advanced reactor demonstration timelines in the United States. Flibe Energy specializes in liquid fluoride thorium reactor engineering and occupies a distinct niche in fuel salt chemistry intellectual property. China National Nuclear Corporation dominates domestic thorium resource utilization and extends its state-backed development pipeline across multiple reactor concepts.
A thorium reactor utilizes thorium-232 as a fertile fuel material, typically bred into uranium-233 through neutron capture in a thermal or fast neutron spectrum, operating at temperatures between 600°C and 900°C depending on coolant selection, with molten salt or high-pressure gas serving as primary heat transfer media to generate electricity or process heat. Molten Salt Reactor configurations attract the majority of private venture capital and government demonstration grants due to their passive safety characteristics and online refueling potential, while Heavy Water Reactor variants benefit from existing CANDU infrastructure and regulatory familiarity in Canada and India. Electricity Generation applications command the largest absolute investment commitment, though Research & Development end use captures disproportionate public funding share as national laboratories validate fuel cycle performance.
The United States Nuclear Regulatory Commission and Department of Energy coordinate on advanced reactor licensing framework updates, while China's National Nuclear Safety Administration and Ministry of Ecology and Environment enforce construction and operational permits under evolving GB standards for Generation IV systems. India's Atomic Energy Regulatory Board maintains separate thorium-specific oversight protocols tied to the country's three-stage program and domestic fuel reserve mandate. Stakeholders must monitor which jurisdiction first achieves full-scale commercial licensing, as that regulatory precedent will reshape international supply chain and intellectual property migration patterns.
Market Dynamics
The thorium reactor sector pivots on a single structural force: the bifurcation between teams possessing operational molten salt chemistry expertise and those stalled at conceptual design. This talent scarcity concentrates viable prototype construction within a handful of national laboratories and venture-backed consortia, compressing competitive timelines and reshaping partnership structures.
Growth Catalysts
- India's three-stage nuclear program:Domestic thorium reserve mandates and existing heavy water infrastructure create dedicated demand pull for breeder reactor deployment.
- China's dual carbon goals:Updated GB standards for Generation IV systems accelerate regulatory review timelines for molten salt demonstrations.
- Passive safety characteristics:Molten salt configurations attract government demonstration grants due to online refueling potential and reduced meltdown risk profiles.
Market Restraints
- High-purity fluoride salt supply:Limited commercial production capacity for LiF-BeF2 mixtures concentrates input sourcing through Chinese state-controlled chemical processors.
- Nuclear physicist scarcity:Decades of reduced university program enrollment in neutron transport physics constrains staffing for prototype builds.
- Licensing pathway uncertainty:The United States Nuclear Regulatory Commission's Part 53 framework remains incomplete, extending pre-construction approval timelines.
Strategic Opportunities
- Process heat applications:Industrial desalination and hydrogen production facilities in Saudi Arabia and the UAE present offtake anchors beyond electricity grids.
- Canada's CANDU infrastructure:Existing heavy water reactor expertise and regulatory familiarity enable thorium fuel bundle retrofits without greenfield construction.
- EU taxonomy alignment:The EU Green Deal's sustainable finance classification for nuclear energy unlocks institutional capital pools previously restricted from fission investments.
Industry Challenges
- Molten salt chemist recruitment:The specialized skill intersection of high-temperature corrosion management and radiochemistry exceeds available labor pool depth.
- Materials certification timelines:Hastelloy-N and alternative nickel alloy qualification for 700°C+ operational environments extends component approval cycles.
- Intellectual property fragmentation:Dispersed patent holdings across national laboratories and private ventures complicate licensing for integrated reactor designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thorium Reactor Market |
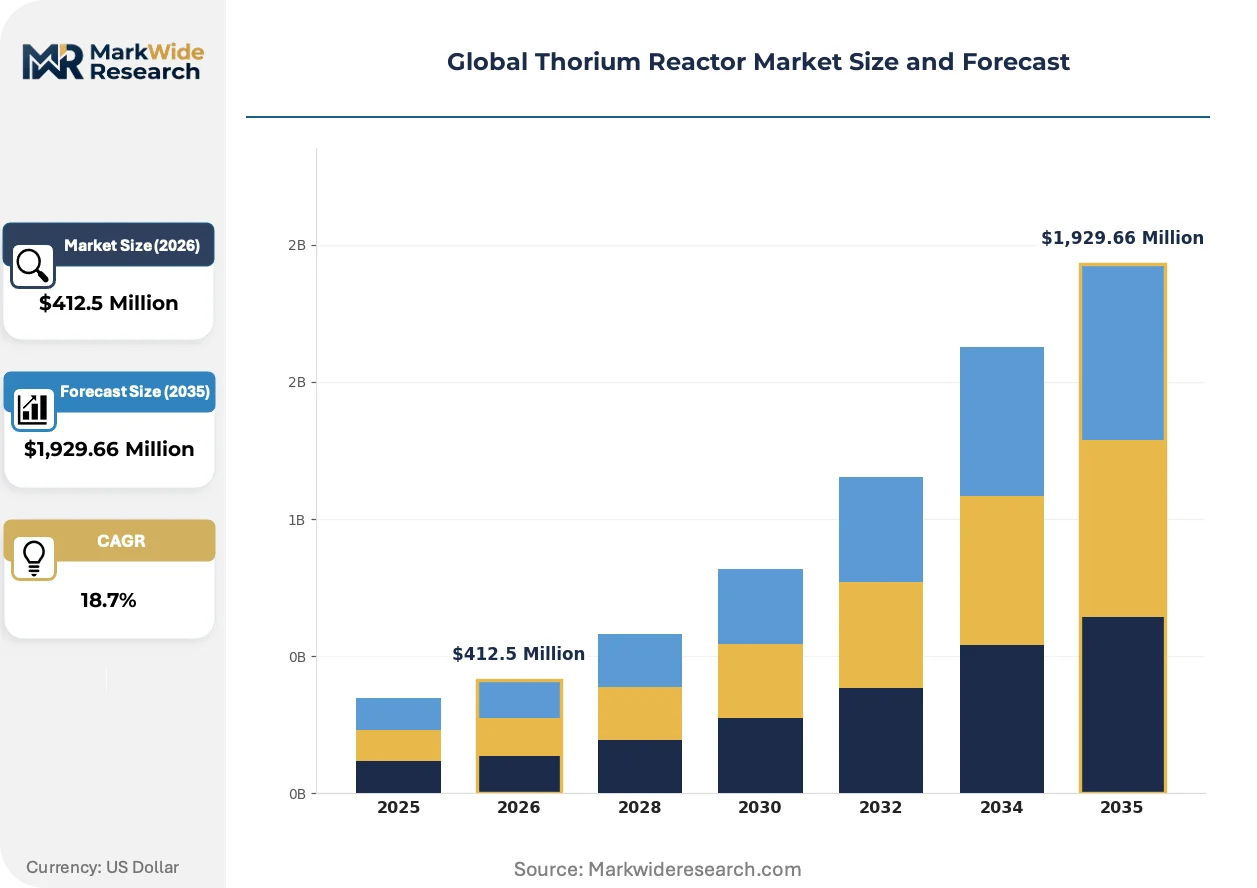
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Reactor Type: Molten Salt Reactor, Heavy Water Reactor, High-Temperature Gas-Cooled Reactor, Fast Breeder Reactor Fuel Form: Solid Fuel, Liquid Fuel, Pebble Bed Fuel, Thorium Oxide Pellets Application: Electricity Generation, Research & Development, Naval Propulsion, Industrial Heat Production End User: Power Utilities, Nuclear Research Institutes, Defense Organizations, Industrial Energy Consumers |
| Companies Covered | TerraPower, Flibe Energy, ThorCon Power, General Atomics, China National Nuclear Corporation, Thor Energy, Westinghouse Electric Company, Copenhagen Atomics, Orano, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thorium Reactor Market Shifts & Advancements
Molten salt reactor engineering is fragmenting along coolant chemistry lines, with distinct technical factions pursuing fluoride versus chloride salt systems. This divergence reshapes supply chain requirements and regulatory engagement strategies across the sector.
Fluoride-based liquid fuel designs dominate private venture capital allocation due to lower neutron spectrum complexity. TerraPower and Flibe Energy anchor United States demonstration timelines around LiF-BeF2 carrier salts, while China's CNNC pursues parallel solid-fuel thorium blankets in heavy water configurations. The technology is fragmenting the vendor landscape into chemistry-specific ecosystems with limited interoperability.
China's National Nuclear Safety Administration and Ministry of Ecology and Environment are enforcing construction permits under evolving GB standards for Generation IV systems. This regulatory momentum compresses domestic deployment schedules and creates precedent pressure on the United States Nuclear Regulatory Commission and India's Atomic Energy Regulatory Board to accelerate their own framework updates. Canadian and Indian regulators are responding with bilateral technical cooperation agreements to avoid standards divergence.
Utility procurement of baseload power is rotating toward sovereign risk mitigation as a primary selection criterion. State-backed developers in China and India capture disproportionate early-mover advantage, while privately financed ventures in the United States face extended capital lockup periods. Saudi Arabia's utility procurement is most visibly adapting, with ACWA Power exploring thorium process heat integration for desalination co-location to reduce grid dependency risks.
Global Thorium Reactor Market Segmentation
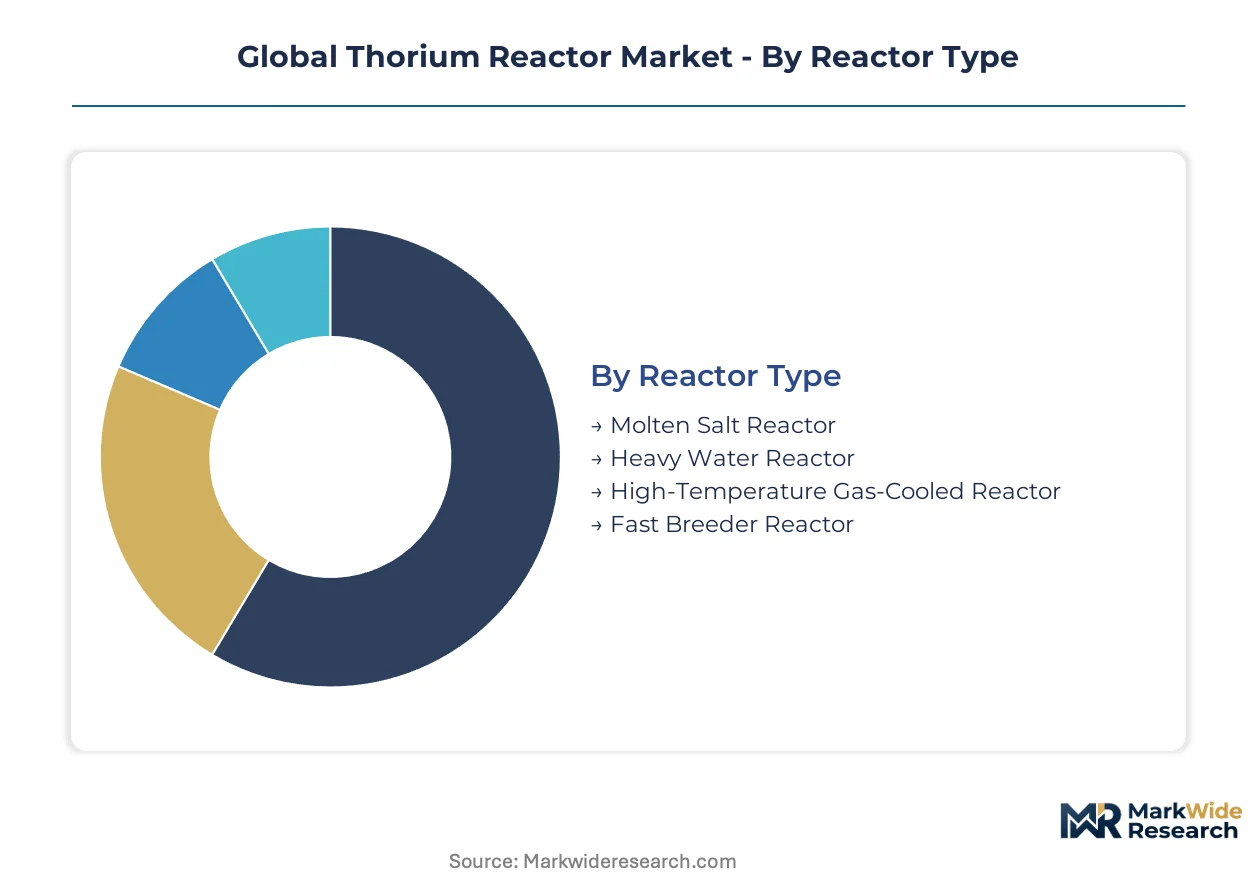
Thorium reactor deployment strategies diverge sharply across reactor configurations, fuel chemistries, and end-use applications. Each segment carries distinct technical barriers, regulatory pathways, and capital intensity profiles that reshape competitive positioning.
Reactor Type:
Molten Salt Reactor designs face the most acute substitution pressure from advanced light-water systems competing for demonstration grants and utility offtake agreements.
- Molten Salt Reactor:Liquid fluoride carrier salts enable passive safety systems and online refueling at operational temperatures between 600°C and 900°C. China's CNNC and private ventures in the United States concentrate demonstration funding here due to reduced meltdown risk profiles and process heat versatility.
- Heavy Water Reactor:CANDU-derived architectures accommodate thorium fuel bundles with minimal core modifications, leveraging existing regulatory familiarity in Canada and India. India's three-stage program anchors dedicated demand through domestic heavy water infrastructure and thorium reserve mandates.
- High-Temperature Gas-Cooled Reactor:Helium-cooled graphite-moderated systems target industrial process heat applications above 750°C. China's Shidao Bay demonstration unit validates TRISO-coated particle fuel performance for thorium breeding blankets.
- Fast Breeder Reactor:Sodium-cooled fast neutron spectrum configurations maximize uranium-233 breeding ratios from thorium-232 fertile feedstock. Russia's BN-series operational experience informs Indian prototype timelines at Kalpakkam.
Molten Salt Reactor retains volume leadership; Fast Breeder Reactor holds the steepest expansion curve tied to closed fuel cycle policy commitments.
Fuel Form:
Cost tier stratification separates chemically complex liquid fuels from commodity-compatible solid geometries.
- Solid Fuel:Thorium-bearing oxide or carbide pellets deploy within existing cladding and assembly frameworks, minimizing licensing novelty. Canada's CANDU operators favor this route for retrofit economics against greenfield construction costs.
- Liquid Fuel:Dissolved thorium and uranium fluorides in molten salt carriers achieve continuous fission product removal and superior burnup. Flibe Energy and TerraPower concentrate intellectual property development here, constrained by high-purity LiF-BeF2 supply bottlenecks.
- Pebble Bed Fuel:TRISO-coated thorium particles in graphite spheres enable continuous refueling and inherent temperature limitation. China's HTR-PM demonstration validates manufacturing scalability for modular deployment.
- Thorium Oxide Pellets:Sintered ThO2 cylinders leverage established ceramic fuel fabrication infrastructure with lower radiotoxicity than uranium equivalents. Indian Nuclear Fuel Complex scales production for pressurized heavy water reactor insertion.
Solid Fuel commands current procurement volumes; Liquid Fuel gains share fastest where process heat applications justify salt chemistry infrastructure investment.
Application:
Customer type concentration varies by revenue model — electricity offtake contracts versus capital grant funding structures.
- Electricity Generation:Baseload power procurement by state-backed utilities in China, India, and Saudi Arabia anchors commercial deployment timelines. ACWA Power explores thorium process heat integration for grid-independent desalination co-location.
- Research & Development:National laboratory validation of fuel cycle performance captures disproportionate public funding share. China's Institute of Modern Physics and India's Bhabha Atomic Research Centre operate dedicated thorium irradiation facilities.
- Naval Propulsion:Compact reactor architectures for submarine and surface vessel applications demand enriched uranium-233 startup inventory. Defense procurement timelines remain classified across operational navies.
- Industrial Heat Production:Cement, chemical, and steel manufacturing facilities in the UAE and Saudi Arabia evaluate thorium process heat for decarbonization compliance. High-temperature output matches hard-to-abate sector requirements.
Electricity Generation retains volume leadership; Industrial Heat Production climbs the fastest as EU carbon border adjustments reshape energy procurement criteria.
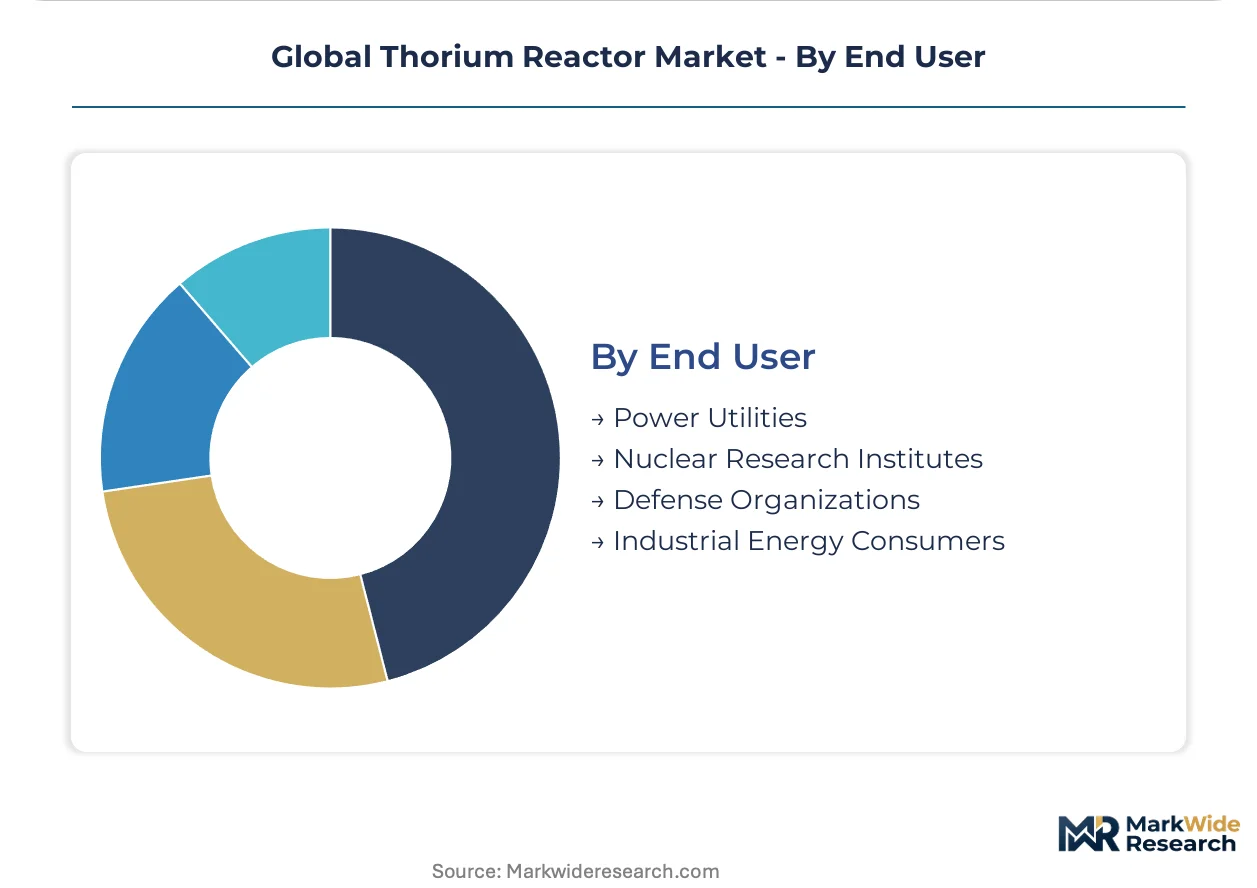
End User:
Supply concentration in fluoride salt production and specialized alloy forging favors vertically integrated state enterprises over fragmented private developers.
- Power Utilities:State Grid Corporation of China and Nuclear Power Corporation of India command procurement scale for multi-reactor deployments. Sovereign risk mitigation criteria increasingly dominate vendor selection.
- Nuclear Research Institutes:China's Institute of Modern Physics, India's Bhabha Atomic Research Centre, and Oak Ridge National Laboratory in the United States operate irradiation facilities and materials test loops. Grant funding flows disproportionately to molten salt chemistry validation.
- Defense Organizations:Naval reactor programs in Russia, the United States, and India maintain classified thorium fuel cycle research. Procurement operates through separate budgetary channels with distinct security clearance requirements.
- Industrial Energy Consumers:Saudi Aramco, SABIC, and Emirates Global Aluminium evaluate thorium process heat for desalination, hydrogen, and high-temperature manufacturing. Direct offtake agreements bypass traditional utility intermediation.
Power Utilities retain volume leadership; Industrial Energy Consumers represent the steepest expansion trajectory as corporate decarbonization targets harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys thorium reactors for breeder-stage electricity generation while China prioritizes molten salt demonstrations for industrial process heat, creating divergent consumption profiles across the two largest national programs.
United States
Advanced reactor licensing preoccupies utility procurement committees at Duke Energy and Southern Company. The Nuclear Regulatory Commission's Part 53 framework revision extends pre-construction approval timelines beyond original estimates. Oak Ridge National Laboratory maintains molten salt chemistry test loops in Tennessee that validate fluoride salt corrosion behavior for private venture designs.
China
Dual carbon goals compress deployment schedules for Generation IV demonstrations beyond electricity applications. The Ministry of Ecology and Environment enforces construction permits under evolving GB standards that accelerate regulatory review for molten salt configurations. Shanghai Institute of Applied Physics operates the TMSR-LF1 liquid fuel prototype in Gansu Province that validates thorium-uranium breeding performance.
India
Domestic thorium reserve mandates anchor the three-stage nuclear program's breeder reactor procurement at Nuclear Power Corporation of India. The Atomic Energy Regulatory Board maintains thorium-specific oversight protocols tied to indigenous fuel cycle requirements. Bhabha Atomic Research Centre in Trombay operates dedicated irradiation facilities that test thorium oxide pellet performance for pressurized heavy water reactor insertion.
Canada
CANDU infrastructure enables thorium fuel bundle retrofits without greenfield construction costs for Ontario Power Generation. Canadian Nuclear Safety Commission regulatory familiarity with heavy water systems reduces licensing novelty barriers. Bruce Power and Candu Energy concentrate engineering expertise in Ontario that supports fuel design adaptation for existing reactor fleets.
Saudi Arabia
Industrial desalination and hydrogen production facilities evaluate thorium process heat for grid-independent operation. King Abdullah City for Atomic and Renewable Energy coordinates feasibility studies for nuclear newcomer program expansion. ACWA Power explores co-location architectures in the Eastern Province that reduce water production dependency on conventional electricity supply.
Global Thorium Reactor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that concentrates intellectual property in specific reactor chemistries. State-backed developers in China and India command procurement scale through sovereign utility relationships, while venture-backed ventures in North America and Europe face extended capital lockup periods. Three strategic archetypes dominate: vertically integrated national laboratories with captive fuel cycle infrastructure, private technology developers with molten salt chemistry specialization, and established nuclear engineering conglomerates with regulatory licensing experience. Competitive moves center on bilateral technical cooperation agreements to avoid standards divergence and strategic partnerships to secure high-purity fluoride salt supply chains.
Within the state-backed tier, China National Nuclear Corporation anchors domestic thorium resource utilization through multiple reactor concept pipelines. TerraPower and Flibe Energy occupy positions in the private venture segment that concentrates liquid fluoride thorium reactor engineering expertise. Copenhagen Atomics represents the European specialist archetype with compact molten salt modular designs. These three entities exemplify the geographic and chemistry-based fragmentation that limits interoperability across vendor ecosystems.
| Leading Market Players |
|---|
| TerraPower |
| Flibe Energy |
| ThorCon Power |
| General Atomics |
| China National Nuclear Corporation |
| Thor Energy |
| Westinghouse Electric Company |
| Copenhagen Atomics |
| Orano |
| Others |
Supply & Pricing Matrix
Capacity utilization at Chinese fluoride salt processors sits below optimal thresholds, compressing price floors for LiF-BeF2 carrier materials while simultaneously concentrating supply-side leverage among state-controlled chemical producers. This scale asymmetry forces private reactor developers in the United States and Europe to accept long-term offtake premiums or absorb inventory risk through strategic stockpiling.
Pricing Analysis
Long-term offtake contracts dominate commercial procurement between state-backed utilities and reactor developers, with spot-market transactions limited to research-quantities of high-purity fluoride salts. Price differentiation rests on certification grade under evolving GB standards versus NRC Part 53 compliance status, and on volume scale for multi-reactor deployment commitments. Cost compression in liquid fuel configurations is intensifying because LiF-BeF2 supply bottlenecks constrain production scaling. Industrial energy consumers in Saudi Arabia and the UAE exhibit highest price sensitivity due to process heat alternative options, while state utilities in China and India demonstrate lowest sensitivity through sovereign budgetary insulation.
Supply Chain Analysis
Strait of Hormuz transit underwrites critical fluoride salt shipments from Chinese processors to Middle Eastern demonstration sites, exposing project timelines to geopolitical disruption. Supply concentrates in China for LiF-BeF2 production, India for thorium oxide pellet fabrication, and Canada for heavy water reactor components. Raw material dependencies center on beryllium feedstock from Kazakh mines, lithium carbonate from South American salares, and high-purity graphite for moderator structures. Single-source vulnerability in Chinese state-controlled chemical processors threatens input security for Western developers. Distribution runs through national laboratory procurement channels and sovereign utility tender processes rather than open commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among state-backed utilities in China, India, and Saudi Arabia, fragmenting procurement leverage for private developers and forcing partnership structures that cede technology control.
For Market Incumbents: Fortify molten salt chemistry expertise through captive recruitment pipelines at Oak Ridge National Laboratory and Shanghai Institute of Applied Physics, locking scarce neutron transport physicists ahead of competitor builds. Deepen backward integration into high-purity fluoride salt production through joint ventures with Chinese state chemical processors, mitigating LiF-BeF2 supply chokepoints that threaten TerraPower and Flibe Energy demonstration timelines. For New Entrants and Emerging Players: NRC Part 53 fast-track certification for molten salt designs offers the most penetrable regulatory pathway for private ventures lacking sovereign utility relationships. Target industrial process heat applications in the UAE and Saudi Arabia where ACWA Power and Emirates Global Aluminium seek grid-independent desalination and hydrogen production solutions, bypassing electricity market intermediation. Lead with modular reactor architectures that reduce capital intensity and accelerate first-mover demonstration milestones. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ventures with validated molten salt corrosion data and established regulatory engagement histories over pre-conceptual design teams. Long-term viability hinges on which jurisdiction achieves full-scale commercial licensing first, reshaping intellectual property migration and supply chain anchoring. Watch for Atomic Energy Regulatory Board licensing precedent in India as the inflection indicator for thorium-specific regulatory pathway maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Fast-Track | NRC Part 53 framework completion would unlock pre-construction approvals for TerraPower and Flibe Energy demonstrations. |
| Fluoride Salt Supply Agreement | Long-term LiF-BeF2 offtake contracts with Chinese state processors reduce input cost volatility for liquid fuel developers. |
| Process Heat Co-Location | ACWA Power's desalination integration in Saudi Arabia validates thorium reactor economics beyond electricity grids. |
| Molten Salt Chemist Recruitment Pipeline | Partnerships with Oak Ridge National Laboratory secure scarce neutron transport physics talent for prototype builds. |
| CANDU Fuel Bundle Retrofit | Ontario Power Generation's heavy water infrastructure enables thorium deployment without greenfield construction costs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers at State Grid Corporation of China and Nuclear Power Corporation of India, reactor engineering leads at TerraPower and CNNC, and molten salt chemists at Oak Ridge National Laboratory and Bhabha Atomic Research Centre. Secondary validation drew from IEA nuclear energy outlooks, NRC advanced reactor licensing dockets, GB standards documentation for Generation IV systems, and national thorium reserve assessments. Bottom-up unit economics for reactor deployment were triangulated against top-down policy commitment trajectories across the three-stage nuclear program and dual carbon goals.
Across the analysis window, the forecasting framework modeled thorium reactor deployment through reactor configuration segmentation, fuel chemistry differentiation, and end-use application splits spanning electricity generation, industrial process heat, and research validation. CAGRs were derived from policy commitment intensity, regulatory pathway velocity, and supply chain readiness indicators. Industry-specific inputs included molten salt corrosion test loop data, heavy water reactor retrofit economics, and uranium-233 breeding ratio validation from irradiation facilities.
Decision-makers should treat outputs as directional under base assumptions of sustained sovereign utility procurement commitment and progressive NRC framework completion; material deviation in licensing timelines or fluoride salt supply access would warrant model refresh. Practitioners should keep alternative scenarios live as regulatory precedent competition between China's GB standards, India's AERB protocols, and United States Part 53 evolution reshapes technology migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Nuclear Decommissioning Services Market
Nuclear Energy
Global Power Plant Uranium Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
Thorium Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Nuclear Power Pump Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Global Nuclear Reactor Construction Market