
 Nuclear Fuels Market | 2026-2036
Nuclear Fuels Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Fuels Market Analysis
Utility buyers are gaining procurement leverage as merchant traders lose contract share, and this rotation is unwinding legacy pricing structures that favored spot-market intermediaries. Cameco Corporation leverages its McArthur River mining complex and conversion assets to sustain vertically integrated supply security across the Western hemisphere. Kazatomprom anchors global uranium concentrate output through its state-controlled mine portfolio in Kazakhstan, while Orano competes on enrichment technology leadership with its Georges Besse II centrifuge plant in France.
Nuclear fuel encompasses fissile and fertile materials—principally uranium dioxide pellets with enrichments between three and five percent U-235, or mixed oxide blends containing plutonium—that undergo controlled fission within reactor cores to generate thermal energy for electricity production. Enriched uranium dominates commercial fuel fabrication due to established supply chains and regulatory familiarity, though advanced reactors are shifting procurement interest toward higher-assay low-enriched uranium and accident-tolerant fuel formulations. Pressurized water reactor fuel assemblies command the largest installed base, while fast breeder reactor technology occupies a niche but strategically significant position for closed fuel cycle programs in France, Russia, and Japan.
The U.S. Nuclear Regulatory Commission governs fuel licensing and reactor operator certification, while the International Atomic Energy Agency safeguards framework and EURATOM supply agreements constrain trade flows and inventory transparency across member states. These overlapping regimes elevate compliance costs for new market entrants and reinforce incumbent supplier relationships. Stakeholders must monitor enrichment capacity expansion timelines and national strategic reserve policies to anticipate supply tightness and contracting windows.
Market Dynamics
Western utilities are accelerating long-term contracting to rebuild domestic enrichment capacity after years of reliance on Russian supply, fundamentally rewiring procurement relationships and pricing power across the fuel cycle.
Growth Catalysts
- Advanced Reactor Demonstrations:The U.S. Department of Energy's Advanced Reactor Demonstration Program is funding first-of-a-kind deployments that require high-assay low-enriched uranium, creating new fuel specification demand.
- EU Taxonomy Recognition:The European Union's classification of nuclear power as a sustainable investment under its sustainable finance taxonomy is unlocking institutional capital for reactor fleet extensions and new build financing.
- Conversion Bottleneck Relief:Cameco Corporation's restart of its Port Hope conversion facility is restoring Western hemisphere UF6 supply security and reducing single-source dependency on Orano's Comurhex plant.
Market Restraints
- Enrichment Capacity Concentration:Four suppliers—Orano, Urenco, Centrus, and Rosatom—control virtually all separative work unit output, creating supply vulnerability if geopolitical sanctions deepen.
- SWU Cost Volatility:Electricity represents 60-70% of enrichment operating costs; European gas price spikes directly compress centrifuge plant margins and lift end-user fuel costs.
- Legacy Liability Burden:Depleted uranium hexafluoride cylinder storage and eventual deconversion obligations impose century-long stewardship costs that deter new market entrants lacking state backing.
Strategic Opportunities
- Domestic U.S. Enrichment Revival:The U.S. Department of Energy's HALEU Availability Program is funding centrifuge technology deployment to rebuild indigenous enrichment infrastructure after the 2013 shutdown of the Paducah Gaseous Diffusion Plant.
- Accident-Tolerant Fuel Commercialization:Westinghouse's EnCore fuel and Framatome's GAIA fuel are advancing chromium-coated zirconium cladding and doped pellet designs that extend burnup and enhance safety margins.
- Closed Fuel Cycle Integration:Fast reactor development in France, Russia, and Japan is creating demand for mixed oxide fuel fabrication services and pyroprocessing technology partnerships.
Industry Challenges
- Specialized Workforce Scarcity:Nuclear fuel engineering requires rare expertise in neutronics, thermal hydraulics, and quality assurance that universities have deprioritized since the 1990s build lull.
- HALEU Certification Timelines:The U.S. Nuclear Regulatory Commission has not yet licensed transport packages for uranium enriched above 5% U-235, delaying advanced reactor fuel logistics.
- Supply Chain Reconfiguration Costs:Shifting from Russian-origin natural uranium and conversion services requires contract renegotiation, assay verification, and inventory blending that strains working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Fuels Market |
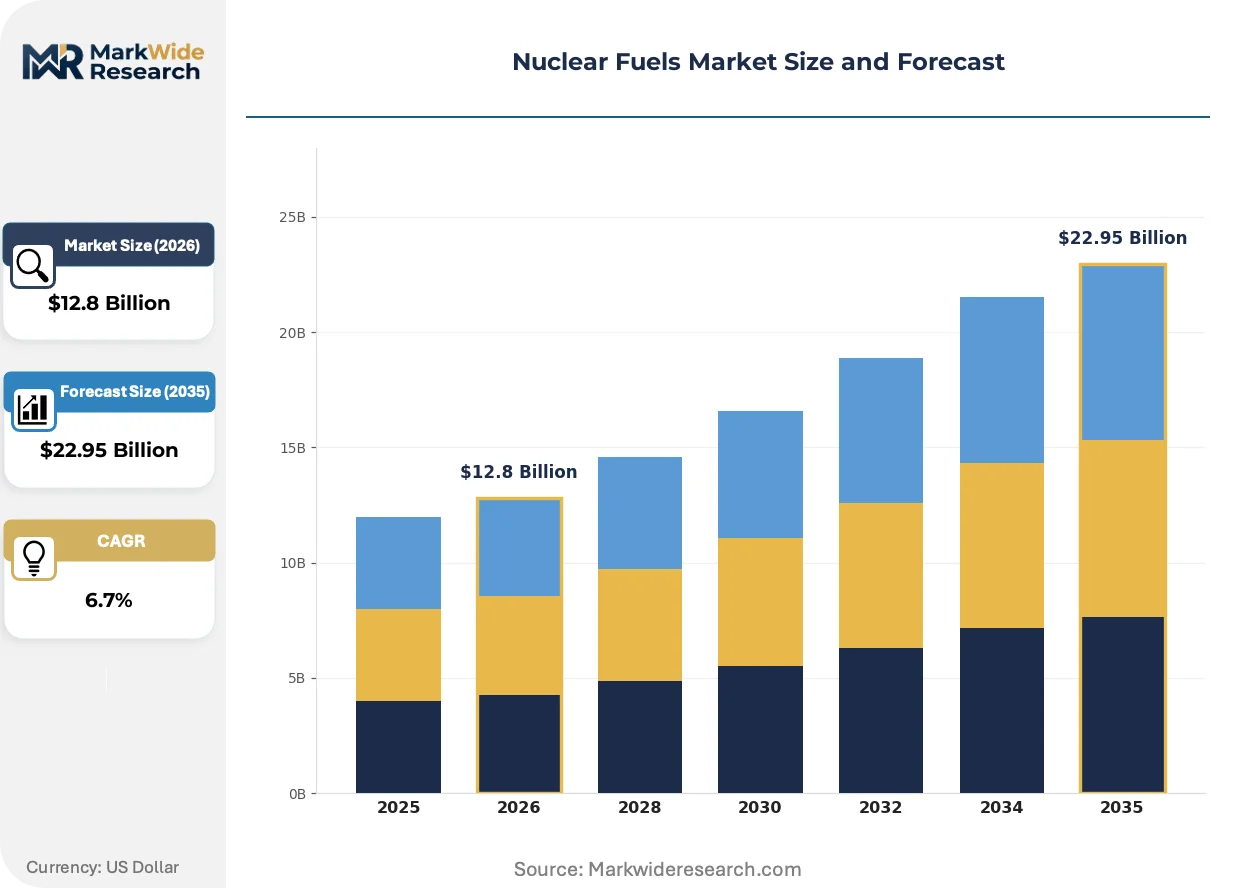
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uranium Oxide, Mixed Oxide Fuel, Enriched Uranium, Thorium Fuel Application: Nuclear Power Generation, Research Reactors, Medical Isotope Production, Defense End User: Utilities, Government, Research Institutions, Defense Agencies Technology: Pressurized Water Reactors, Boiling Water Reactors, Fast Breeder Reactors, Advanced Reactors |
| Companies Covered | Cameco Corporation, Kazatomprom, Orano, China National Nuclear Corporation, Rosatom, Westinghouse Electric Company, Framatome, Centrus Energy Corporation, Urenco Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Fuels Market Emerging Trajectories
Fuel technology pathways are diverging between evolutionary improvements for existing light water reactors and revolutionary formulations for advanced reactor architectures, with regulatory frameworks racing to catch both tracks.
Enrichment technology is bifurcating between established centrifuge designs serving the existing reactor fleet and emerging laser-based and plasma separation methods targeting HALEU production. The U.S. Department of Energy is funding multiple demonstration projects through its Office of Nuclear Energy to validate these alternative technologies. Success would compress the capital intensity and timeline for domestic enrichment capacity expansion.
The U.S. Nuclear Regulatory Commission is streamlining Part 53 licensing frameworks for advanced reactors, creating a parallel regulatory pathway to the decades-old Part 50 and Part 52 structures. This reform is compressing pre-application review periods and enabling staged licensing commitments. Advanced reactor developers in Texas, Wyoming, and Idaho are leveraging these reforms to accelerate construction permits.
Utility fuel buyers are consolidating procurement decisions into centralized sourcing functions that negotiate multi-year, multi-site contracts directly with mine-to-reactor suppliers. This disintermediation is squeezing merchant traders and spot market intermediaries that historically captured margin between producers and end-users. The shift is most visible among U.S. merchant generators and municipal utilities seeking price predictability for rate case filings.
Nuclear Fuels Market Segmentation
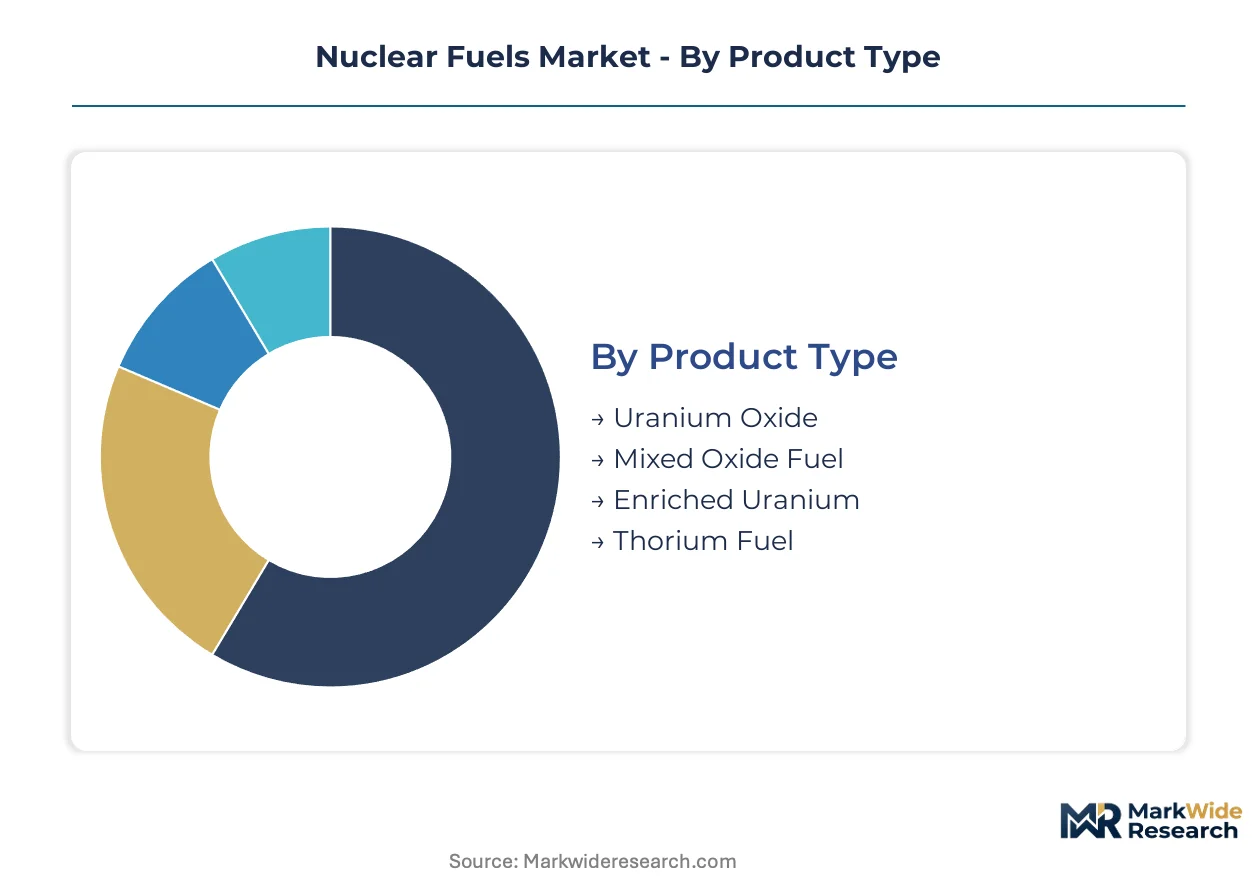
Fuel specification diversity across reactor generations creates distinct procurement pathways, each governed by separate licensing regimes and supply chain configurations. Segmentation clarity enables stakeholders to match enrichment services, fabrication capabilities, and regulatory compliance requirements to specific operational contexts.
Product Type:
U.S. NRC Part 70 licensing distinguishes material categories by enrichment level and chemical form, driving supplier specialization across conversion, enrichment, and fabrication stages.
- Enriched Uranium:Uranium dioxide pellets enriched to 3-5% U-235 constitute the commercial standard for light water reactor fuel assemblies. Procurement concentrates among U.S. utilities rebuilding domestic supply security after Russian import restrictions, with Centrus and Urenco expanding SWU contracting windows to meet renewed demand.
- Mixed Oxide Fuel:Plutonium-uranium blends enable closed fuel cycle operation in fast breeder and some light water reactor configurations. Adoption clusters in France, Russia, and Japan where reprocessing infrastructure supports plutonium recovery from spent fuel, constrained by U.S. nonproliferation policies that limit domestic MOX fabrication.
- Uranium Oxide:Unenriched U3O8 serves conversion feedstock and research reactor fuel.
- Thorium Fuel:Th-232/U-233 formulations remain experimental, pursued by India's three-stage program and select advanced reactor developers.
Established volume favors enriched uranium; emerging adoption favors mixed oxide fuel.
Application:
End-use differentiation determines enrichment assay requirements, delivery schedules, and safeguards intensity.
- Nuclear Power Generation:Commercial electricity production consumes approximately 95% of separative work unit output globally. Procurement cycles align with reactor refueling outages, with U.S. merchant generators and European utilities negotiating multi-year contracts to secure baseload enrichment capacity.
- Medical Isotope Production:High-flux research reactors require specialized low-enriched or high-enriched uranium targets for Mo-99 and other radioisotope generation. Supply security concerns intensified following the NRU reactor shutdown in Canada, redirecting procurement toward European and South African production facilities.
- Research Reactors:Zero-power and training facilities operate on diverse fuel specifications.
- Defense:Naval propulsion and weapons programs require high-assay enrichment under strict national control.
Baseload demand concentrates in power generation; security-sensitive applications impose the tightest supply constraints.
End User:
Customer type shapes contracting structure, risk allocation, and financing mechanisms across the fuel cycle.
- Utilities:Investor-owned and public power entities drive commercial fuel procurement volume, with U.S. utilities accelerating long-term contracting to rebuild inventory positions. Centralized sourcing functions are displacing merchant traders, compressing intermediation margins.
- Government:National programs fund strategic reserve accumulation, enrichment technology demonstration, and HALEU availability initiatives. The U.S. Department of Energy's HALEU program is underwriting centrifuge deployment to restore indigenous enrichment capability.
- Research Institutions:Universities and national laboratories operate under specialized NRC licenses.
- Defense Agencies:Military requirements remain classified and nationally controlled.
Commercial utilities dominate procurement volume; government programs anchor technology development funding.
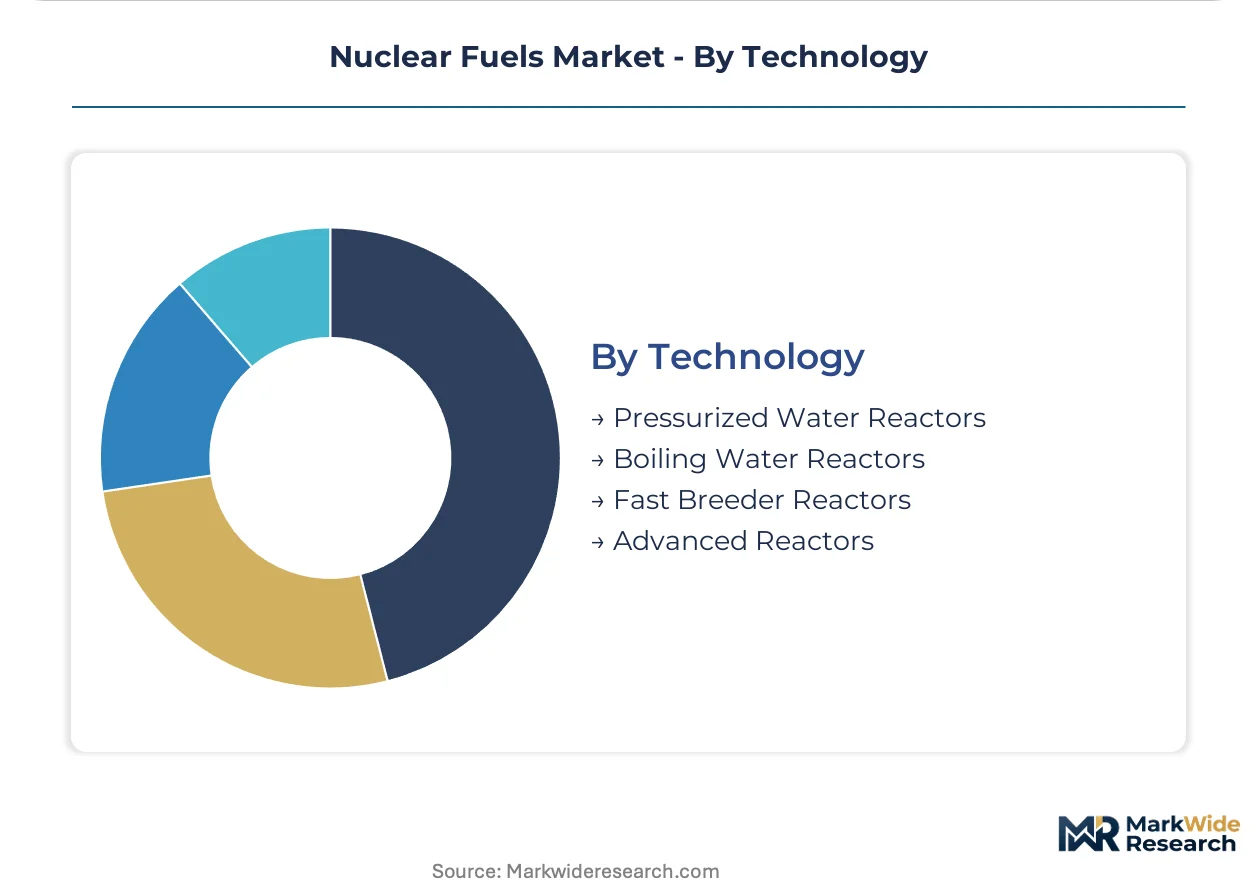
Technology:
Reactor architecture determines fuel form factor, burnup targets, and qualification pathways.
- Pressurized Water Reactors:The dominant installed base commands standardized 17x17 and 16x16 fuel assembly designs. Westinghouse and Framatome compete on fuel performance warranties, with accident-tolerant cladding coatings now entering commercial qualification.
- Advanced Reactors:Molten salt, gas-cooled, and small modular designs require HALEU above 19.75% U-235, driving new enrichment demand. The U.S. NRC has not yet licensed transport packages for these assays, delaying fuel logistics.
- Boiling Water Reactors:GE-Hitachi fuel designs serve a smaller installed base.
- Fast Breeder Reactors:Sodium-cooled configurations enable plutonium breeding and minor actinide transmutation.
Installed capacity favors pressurized water technology; steepest expansion trajectory attaches to advanced reactor categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kazakhstan ships uranium concentrate to conversion facilities across North America and Europe, while Russia's Rosatom historically dominated enrichment services for Western utilities before sanctions rewired these trade corridors.
United States
Reactor fleet extensions at Georgia Power's Vogtle units and Tennessee Valley Authority's Browns Ferry are accelerating fuel procurement cycles. The U.S. Department of Energy's HALEU Availability Program is funding centrifuge technology deployment to rebuild indigenous enrichment infrastructure. Wyoming's Powder River Basin and Texas's Permian Basin host uranium mining operations that are scaling to replace Russian feedstock.
France
Électricité de France is extending reactor lifespans beyond forty years under the EU taxonomy for sustainable finance. The French nuclear safety authority ASN streamlined licensing for advanced fuel formulations. The Georges Besse II centrifuge plant at Tricastin anchors European enrichment capacity, with Orano expanding output to capture post-Russian contract migration.
Japan
Tokyo Electric Power and Kansai Electric are restarting idled reactors after Fukushima-era shutdowns, tightening domestic fuel demand. Japan's nuclear regulatory authority NRA revised safety standards to accommodate accident-tolerant fuel loading. The Rokkasho reprocessing complex in Aomori Prefecture is advancing mixed oxide fuel fabrication for fast breeder reactor programs.
Canada
Ontario Power Generation's Bruce and Darlington refurbishments are sustaining CANDU fuel demand through 2060. The Canadian Nuclear Safety Commission harmonized transport regulations with U.S. DOT standards for cross-border uranium shipments. Saskatchewan's Athabasca Basin hosts Cameco's McArthur River and Cigar Lake mines that supply Western hemisphere utilities.
China
China National Nuclear Corporation and China General Nuclear Power Group are commissioning two reactors annually, expanding enrichment requirements faster than domestic capacity. The National Energy Administration approved pilot programs for high-temperature gas-cooled reactor fuel. Gansu Province's Lanzhou enrichment complex is scaling separative work unit output to reduce import dependency.
Nuclear Fuels Market Vendor Landscape
Listed leaders compete with private specialists across state-backed and commercially driven business models, creating a bifurcated structure where sovereign wealth funds underwrite capacity expansion while publicly traded miners optimize shareholder returns. The market concentrates around vertically integrated fuel cycle operators and pure-play mining specialists. Strategic archetypes include state-controlled national champions, Western integrated suppliers, and enrichment technology pure-plays. Capacity expansion and long-term contracting are displacing spot-market intermediation as dominant competitive moves.
Among state-controlled national champions, Kazatomprom and China National Nuclear Corporation exemplify sovereign-backed production scale that secures supply security for domestic reactor fleets. Cameco Corporation and Orano occupy positions within the Western integrated supplier archetype, combining mining assets with conversion and fabrication capabilities. Centrus Energy Corporation represents the enrichment technology specialist tier, focused on separative work unit output without upstream mining exposure.
| Leading Market Players |
|---|
| Cameco Corporation |
| Kazatomprom |
| Orano |
| China National Nuclear Corporation |
| Rosatom |
| Westinghouse Electric Company |
| Framatome |
| Centrus Energy Corporation |
| Urenco Group |
| Others |
Supply Flow & Price Mechanics
Russian-origin uranium replacement by Kazakh and Canadian feedstock simultaneously redraws supply geography around Astana and Saskatchewan while compressing conversion margins as Western utilities absorb higher assay verification and blending costs.
Pricing Analysis
The technology-generation pricing gap separates legacy centrifuge SWU contracts from HALEU premiums and laser enrichment pilot rates. Pricing stratifies across long-term offtake agreements for baseload utilities, spot-indexed contracts for merchant generators, and government-funded availability programs for advanced reactor developers. Price differentiation hinges on enrichment assay certification tiers and volume scale commitments. Pricing pressure stems from electricity cost volatility at European centrifuge plants, squeezing operator margins and lifting end-user fuel costs. Merchant traders exhibit highest price sensitivity as centralized utility sourcing displaces their intermediary role; government strategic reserve programs show lowest sensitivity due to national security framing.
Supply Chain Analysis
Strategic stockpile preferences dominate utility procurement, with U.S. operators rebuilding inventory positions after Russian import restrictions rather than pursuing just-in-time delivery. Supply concentrates in Kazakhstan, Canada, and Australia for uranium concentrate; France, Germany, and the United Kingdom for enrichment services. The fuel cycle draws from yellowcake mining, UF6 conversion, and separative work unit output as core inputs. Single-source vulnerability around conversion capacity—particularly Orano's Comurhex plant and Cameco's Port Hope facility—creates supply chain risk if operational disruptions coincide. Distribution runs through mine-to-reactor integrated suppliers and long-term contract direct sales, squeezing spot market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nuclear fuels market sits at a platform-economics inflection where HALEU certification and transport licensing interoperability will determine which reactor architectures achieve commercial scale first.
For Market Incumbents: Fortify enrichment capacity positions through backward integration into conversion assets and captive uranium concentrate supply. Cameco's McArthur River-to-Port Hope integration offers a defensive template against Kazakh state-backed volume competition. Invest in HALEU transport package licensing to preempt logistics bottlenecks that could strand advanced reactor fuel deliveries.
For New Entrants and Emerging Players: Lead with laser-based or plasma separation enrichment technologies targeting the HALEU availability gap left by incumbent centrifuge operators. The domestic U.S. enrichment revival under Department of Energy funding represents the most penetrable geography for technology demonstration. Pursue joint development agreements with advanced reactor developers in Texas, Wyoming, and Idaho to secure offtake commitment before commercial qualification.
For Investors and Strategic Acquirers: The market sits at a supply-secure expansion phase that favors vertically integrated Western suppliers over pure-play mining exposure. Long-term viability over the coming decade rests on enrichment technology leadership and regulatory licensing moats rather than commodity price leverage. Watch for U.S. Nuclear Regulatory Commission transport package approvals for uranium enriched above five percent as the signal indicating HALEU logistics readiness and advanced reactor fuel commercialization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Enrichment Capacity Buildout | Restores U.S. separative work unit independence after Paducah shutdown and Russian supply exclusion. |
| HALEU Availability Program Participation | Secures Department of Energy funding for centrifuge deployment and advanced reactor fuel qualification. |
| Long-term Utility Supply Agreement | Locks in baseload contracting windows as merchant traders lose procurement share to centralized sourcing. |
| Accident-Tolerant Fuel Certification | Enables Westinghouse and Framatome to capture premium pricing for chromium-coated cladding formulations. |
| Conversion Facility Restart | Cameco's Port Hope restoration reduces Western hemisphere UF6 dependency on Orano's Comurhex plant. |
Methodological Framework
Desk research of regulatory filings, trade flow databases, and reactor operator procurement disclosures preceded structured interviews with utility fuel buyers, enrichment plant operators, and nuclear regulatory specialists. Primary fieldwork captured contracting cycle timing, inventory policy shifts, and technology qualification timelines. Secondary validation drew from U.S. Nuclear Regulatory Commission licensing records, International Atomic Energy Agency safeguards reports, and European Union taxonomy implementation guidance. Bottom-up segmentation modeling triangulated against top-down macroeconomic scenario analysis.
Variance decomposition across enrichment capacity expansion, reactor fleet extension decisions, and HALEU commercialization timelines shaped the analytical framework. Segmentation dimensions modeled include fuel specification by enrichment level, reactor technology category, end-user utility type, and regional regulatory cluster. CAGRs were derived through exponential smoothing of annual demand projections against supply capacity buildout schedules. Industry-specific forecast inputs incorporated separative work unit electricity cost sensitivity and transport package licensing timelines.
The analysis sits within stated boundaries; outcomes outside sustained government funding for domestic enrichment revival or accelerated advanced reactor deployment would require recalibration. Forecasts reflect assumptions regarding regulatory streamlining continuity and Western utility contracting appetite. Revision becomes warranted when geopolitical sanctions depth or enrichment plant electricity cost volatility crosses thresholds that disrupt supply security planning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Fusion Power Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Nuclear Power Pump Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Steam Generator Market
Nuclear Energy
Global Power Plant Uranium Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market