
 United States Nuclear Power Reactor Decommissioning Market | 2026-2036
United States Nuclear Power Reactor Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
United States Nuclear Power Reactor Decommissioning Market Analytics
Concrete in reactor bioshields is shifting toward advanced demolition robotics and remote tooling as the dominant dismantling approach. Westinghouse Electric Company leverages its reactor design heritage to anchor decommissioning contracts at legacy pressurized water reactor sites. EnergySolutions sustains geographic dominance through its Clive, Utah disposal facility and integrated waste logistics. AECOM competes on engineering scale across multiple simultaneous site closures.
Nuclear power reactor decommissioning encompasses the engineered dismantlement, decontamination, and site restoration of irradiated nuclear facilities following permanent shutdown, requiring remote-handled tooling for components exceeding surface dose rates of 1,000 rem per hour and specialized segmentation of reactor pressure vessels. The primary purpose is to reduce radiological hazards to unrestricted release criteria while managing activated materials through licensed disposal pathways. Immediate Dismantling leads method selection as utilities seek to avoid extended site maintenance burdens, while Deferred Dismantling retains share where spent fuel pool offload delays stretch decades. Low-Level Waste dominates volume throughput but High-Level Waste commands concentrated margin pools due to transport cask certification and deep-geologic repository coordination requirements.
The Nuclear Regulatory Commission governs license termination through its 10 CFR Part 20 and Part 50 frameworks, mandating dose-based release criteria that shape decontamination intensity and final status survey scope. The Department of Transportation partners with the NRC to regulate Type B package certifications for spent fuel transport, directly conditioning project logistics and vendor qualification. The EPA's CERCLA authority overlays at sites with historical groundwater contamination, adding remedial investigation obligations. Stakeholders must monitor NRC rulemaking on emergency planning zone reductions post-fuel removal, as this regulatory inflection determines when local tax burdens shift and community consent frameworks activate.
Market Dynamics
The NRC's 10 CFR Part 50.82 license termination framework is compressing decommissioning timelines as utilities face escalating spent fuel pool maintenance costs and property tax burdens on non-revenue assets.
Growth Catalysts
- Reactor Fleet Age:First-generation commercial reactors installed during the 1960s and 1970s are reaching 60-year license expiration, triggering mandatory decommissioning obligations across the Northeast and Great Lakes states.
- 10 CFR Part 20 Release Criteria:The NRC's dose-based site release standards are clarifying endpoint definitions, reducing regulatory uncertainty that previously delayed contract awards and project mobilization.
- Remote Demolition Robotics:Advanced hydraulic shears and plasma arc cutting systems are penetrating bioshield concrete at dose rates exceeding 1,000 rem per hour, accelerating reactor pressure vessel segmentation.
Market Restraints
- Specialized Labor Pool:The finite supply of Health Physics Technicians certified for remote-handled waste operations concentrates in the Tennessee Valley and Hanford corridor, creating wage inflation and scheduling bottlenecks.
- Type B Package Certification:The Department of Transportation's stringent cask design approval process extends spent fuel transport logistics lead times to 18-24 months, freezing project cash flow.
- Deep Geologic Repository Absence:The lack of licensed high-level waste disposal capacity beyond the Yucca Mountain suspension forces utilities into indefinite on-site dry cask storage, deferring final site release.
Strategic Opportunities
- Texas and Gulf Coast Expansion:Emerging decommissioning demand from South Texas Project and Comanche Peak reactors creates geographic diversification beyond the traditional Northeast concentration.
- Immediate Dismantling Preference:Utilities are abandoning SAFSTOR deferred dismantling to eliminate 60-year monitoring obligations, opening comprehensive single-contract awards.
- Integrated Waste Logistics:Vendors capturing both on-site segmentation and Clive, Utah low-level waste disposal in unified contracts are securing multi-year revenue visibility.
Industry Challenges
- Radiological Characterization Accuracy:Pre-demolition dose rate surveys often underestimate activated steel concentrations in reactor internals, triggering change orders and schedule overruns.
- Spent Fuel Pool Offload Coordination:Dry cask loading campaigns must synchronize with NRC-approved transport cask availability, creating critical path dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Nuclear Power Reactor Decommissioning Market |
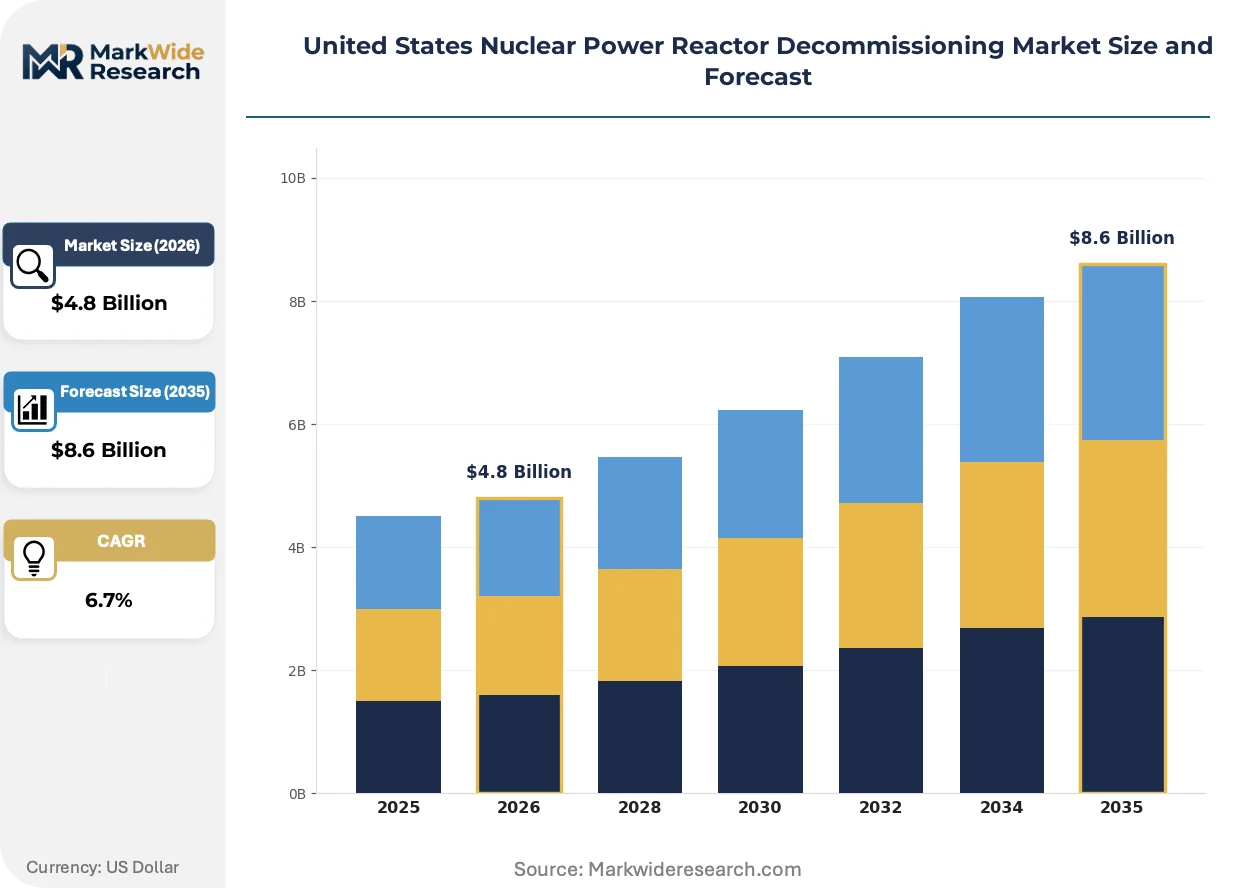
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Decommissioning Method: Deferred Dismantling, Immediate Dismantling, Entombment, Safeguarded Storage End User: Utility Companies, Government Agencies, Environmental Organizations, Contractors Process Phase: Planning Phase, Implementation Phase, Post-Decommissioning Phase, Regulatory Phase Waste Management Type: Low-Level Waste, High-Level Waste, Intermediate-Level Waste, Mixed Waste |
| Companies Covered | Westinghouse Electric Company, Bechtel Corporation, AECOM, Babcock International Group, EnergySolutions, NorthStar Group Services, Orano, Studsvik, Amentum, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Nuclear Power Reactor Decommissioning Market Evolving Landscape
Decommissioning execution is pivoting from manual segmentation toward autonomous remote systems, while regulatory frameworks and utility procurement models simultaneously compress project timelines and expand vendor accountability.
Plasma arc cutting systems equipped with laser-guided positioning are rewriting reactor pressure vessel dismantling economics by reducing segmentation time from months to weeks. Decommissioning contractors at pressurized water reactor sites are deploying these systems for circumferential cuts through 8-inch stainless steel walls. The technology is compressing labor exposure hours and enabling parallel work streams that accelerate site release schedules.
The NRC's proposed emergency planning zone reduction rulemaking following fuel removal is reshaping local tax jurisdiction negotiations. Municipalities dependent on reactor property tax assessments are facing revenue cliffs as EPZ contraction triggers reclassification to industrial rather than nuclear liability rates. Utilities in Illinois and New York are preemptively negotiating community benefit agreements to secure site repurposing consent.
Performance-based decommissioning contracts are displacing unit-rate pricing as the dominant commercial structure. Fixed-price awards with milestone-based payments now dominate procurements above $500 million, transferring cost-overrun risk to contractors. This shift is most pronounced at dual-unit sites where economies of scale justify comprehensive single-vendor awards.
United States Nuclear Power Reactor Decommissioning Market Segmentation
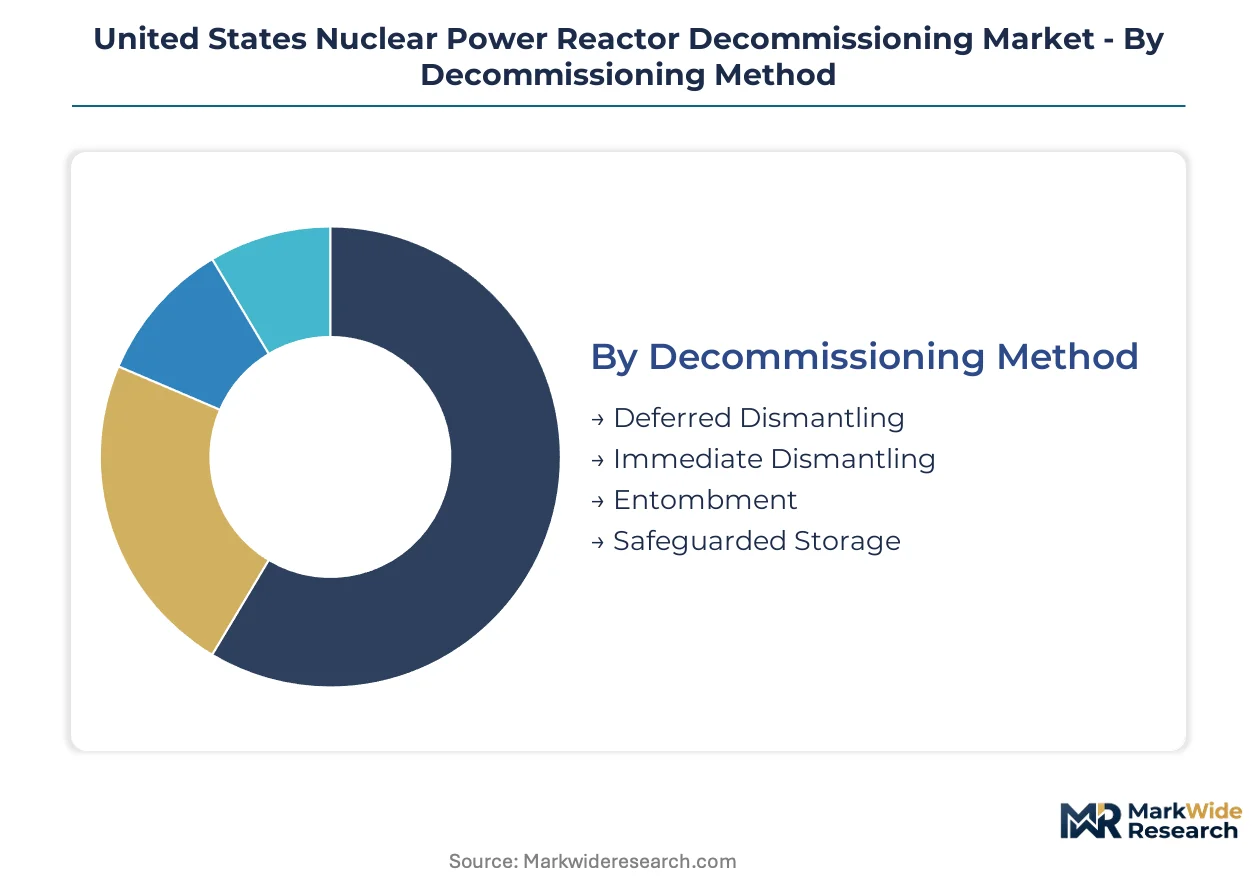
Decommissioning market segmentation reveals how project economics, regulatory pathways, and waste liability distribute across distinct operational modes. Each dimension shapes vendor qualification requirements, contract structures, and capital deployment timelines.
Decommissioning Method:
Volume concentration favors accelerated site release, while premium pricing attaches to extended stewardship obligations requiring multi-decade monitoring infrastructure.
- Immediate Dismantling:Complete reactor segmentation and site restoration commence within months of permanent shutdown, eliminating long-term security and maintenance burdens. Utility procurement in Illinois and New York concentrates here as property tax liabilities on non-revenue assets escalate.
- Deferred Dismantling:Radioactive decay reduces personnel exposure during decades-long dormancy periods before final dismantlement. The SAFSTOR variant dominates where spent fuel pool offload delays stretch timelines, concentrating in reactor sites with constrained dry cask storage capacity.
- Entombment:On-site containment of activated structures within reinforced concrete barriers, restricted to sites with favorable geologic isolation and community consent frameworks.
- Safeguarded Storage:Extended institutional controls maintain physical security and environmental monitoring without active decontamination, preserving license termination flexibility.
Mature deployment sits with Deferred Dismantling. Newer deployment is concentrated in Immediate Dismantling.
End User:
Procurement authority fragments between asset owners retaining liability and specialized contractors absorbing execution risk through fixed-price awards.
- Utility Companies:Investor-owned and public power entities holding NRC operating licenses bear ultimate decommissioning trust fund stewardship and site release liability. Dominion Energy and Duke Energy anchor demand through multi-reactor fleet retirements.
- Government Agencies:Federal ownership of Tennessee Valley Authority reactors and Department of Energy legacy sites creates non-commercial procurement pathways with distinct appropriations cycles.
- Contractors:Turnkey decommissioning specialists assume cost-overrun risk through performance-based contracts, capturing margin from labor productivity and waste volume optimization.
- Environmental Organizations:Stakeholder engagement roles in community benefit negotiations and groundwater monitoring oversight, without direct procurement authority.
Contractor-led execution is displacing utility self-performance. Direct utility management retains concentration at single-unit sites with limited complexity.
Process Phase:
Margin distribution inverts across the project lifecycle, with front-end engineering and back-end characterization commanding premium rates over commodity demolition.
- Planning Phase:License termination plans, dose characterization surveys, and waste pathway approvals establish project scope and regulatory baselines. AECOM and EnergySolutions concentrate here through integrated characterization contracts.
- Implementation Phase:Physical dismantlement, decontamination, and waste packaging absorb the majority of project labor hours and capital deployment.
- Regulatory Phase:NRC license amendment submissions, public hearings, and final status surveys condition site release timing and residual liability.
- Post-Decommissioning Phase:Institutional controls, groundwater monitoring, and restricted-use site maintenance persist where unrestricted release criteria prove unattainable.
Implementation Phase absorbs the dominant share of contract value. Planning Phase represents the fastest-growing trajectory as characterization accuracy demands intensify.
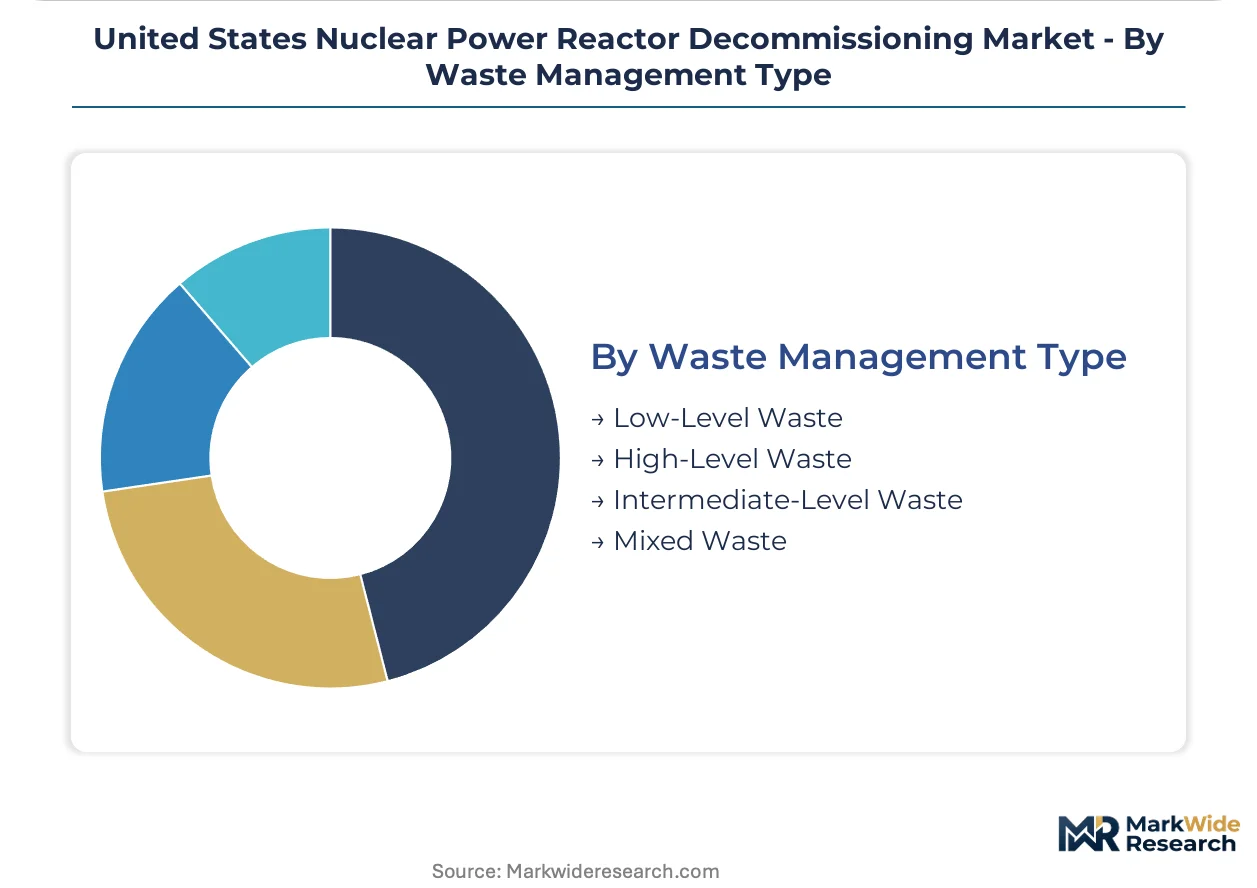
Waste Management Type:
Volume throughput concentrates in lightly contaminated materials, while revenue concentration attaches to cask-certified transport and repository coordination for activated components.
- Low-Level Waste:Contaminated soil, resins, filters, and demolished concrete constitute the majority of shipment volume to licensed disposal facilities. The Clive, Utah site anchors national logistics through its capacity position.
- High-Level Waste:Spent fuel assemblies and vitrified reprocessing residues require NRC-certified transport casks and indefinite on-site dry cask storage pending geologic repository availability.
- Intermediate-Level Waste:Reactor internals, steam generator sections, and activated bioshield concrete exceed Low-Level Waste limits but lack High-Level Waste classification, creating disposal pathway ambiguity.
- Mixed Waste:Radioactive materials combined with hazardous chemical constituents trigger dual EPA and NRC jurisdiction, adding treatment complexity and cost.
Low-Level Waste dominates shipment frequency. High-Level Waste commands concentrated margin pools through specialized handling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in distressed nuclear communities are concentrating decommissioning investment through tax-credit mechanisms and federal grant programs targeting site redevelopment.
Northeast Corridor
Retired reactors at Indian Point, Oyster Creek, and Vermont Yankee drive immediate dismantling demand as property tax burdens on non-revenue assets escalate. The NRC's 10 CFR Part 50.82 framework compresses license termination timelines. Westinghouse Electric Company anchors contractor presence through legacy pressurized water reactor expertise concentrated in Pennsylvania and New York.
Great Lakes States
First-generation boiling water reactors at Palisades, Davis-Besse, and Point Beach reach 60-year license expiration, triggering mandatory decommissioning obligations. State-level spent fuel storage litigation against the Department of Energy accelerates dry cask campaigns. EnergySolutions maintains logistics dominance through integrated waste transport corridors linking Midwest sites to its Clive, Utah disposal facility.
Southeast
Crystal River, Robinson, and Duke Energy's Oconee fleet create emerging decommissioning clusters as utilities abandon license renewal applications. Florida and South Carolina regulators align state environmental permits with NRC release criteria to streamline site restoration. AECOM captures engineering-scale contracts across multiple simultaneous Southeast closures.
Texas and Gulf Coast
South Texas Project and Comanche Peak reactors project end-of-life decommissioning demand within the analysis window. The Texas Commission on Environmental Quality coordinates with the NRC on dual jurisdiction for mixed waste streams. Orano and Studsvik position for spent fuel transport logistics through Gulf Coast port infrastructure.
Pacific Coast
Diablo Canyon's scheduled retirement and Hanford Site legacy obligations sustain contractor demand in California and Washington. California Public Utilities Commission rate-case proceedings determine decommissioning trust fund adequacy thresholds. Bechtel Corporation leverages Department of Energy site management heritage for commercial reactor parallel opportunities.
United States Nuclear Power Reactor Decommissioning Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with reactor-original-equipment heritage commanding premium positioning in pressure vessel segmentation while integrated waste logistics specialists capture recurring revenue streams. The vendor base concentrates around three strategic tiers: design-origin incumbents with reactor-specific tooling libraries, turnkey contractors absorbing fixed-price risk through performance-based awards, and niche radiological characterization firms front-loading project scopes. Consolidation pressures intensify as milestone-based contracts above $500 million favor vendors with simultaneous multi-site capacity.
Within the design-origin tier, Westinghouse Electric Company and Bechtel Corporation exemplify reactor-specific expertise leveraged into decommissioning execution. Among integrated service providers, EnergySolutions and AECOM occupy positions spanning characterization through final status survey. These anchors represent how vendor qualification requirements favor entities with NRC-licensed waste handling infrastructure and Type B package certification track records.
| Leading Market Players |
|---|
| Westinghouse Electric Company |
| Bechtel Corporation |
| AECOM |
| Babcock International Group |
| EnergySolutions |
| NorthStar Group Services |
| Orano |
| Studsvik |
| Amentum |
| Others |
Value Network & Pricing Analysis
Steel price indices from the London Metal Exchange cascade through reactor pressure vessel segmentation contracts, compressing margins for contractors locked into fixed-price awards while amplifying pricing power for vendors with captive fabrication capabilities and NRC-certified cask inventory.
Pricing Analysis
Short-lead-time premiums attach to Type B transport cask availability, with spot-market contractors absorbing 15-20% cost penalties against term-contract holders. Project-based fixed-price awards dominate procurements above $500 million, transferring cost-overrun risk to turnkey vendors. Price differentiation rests on Health Physics Technician certification density and Clive, Utah disposal slot allocation. Cost compression in reactor internals segmentation is intensifying because plasma arc cutting equipment depreciation accelerates with shortened project timelines. Single-unit site owners exhibit highest price sensitivity; dual-unit fleet operators leverage economies of scale for comprehensive vendor consolidation.
Supply Chain Analysis
Regional distribution centers for remote-handled tooling concentrate in Tennessee, Washington, and South Carolina, feeding hub-and-spoke deployment to reactor sites nationwide. Geographic supply concentration draws from Germany, Japan, and domestic US sources for specialized hydraulic shears and laser positioning systems. Raw material dependencies rest on high-grade borated steel for bioshield applications, tungsten-alloy cutting consumables, and lead-shielded transport cask forgings. Single-source vulnerability permeates the Health Physics Technician labor pool, with certification bottlenecks in the Tennessee Valley corridor freezing crew mobilization. Distribution runs through integrated waste logistics specialists capturing both on-site segmentation and disposal facility access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
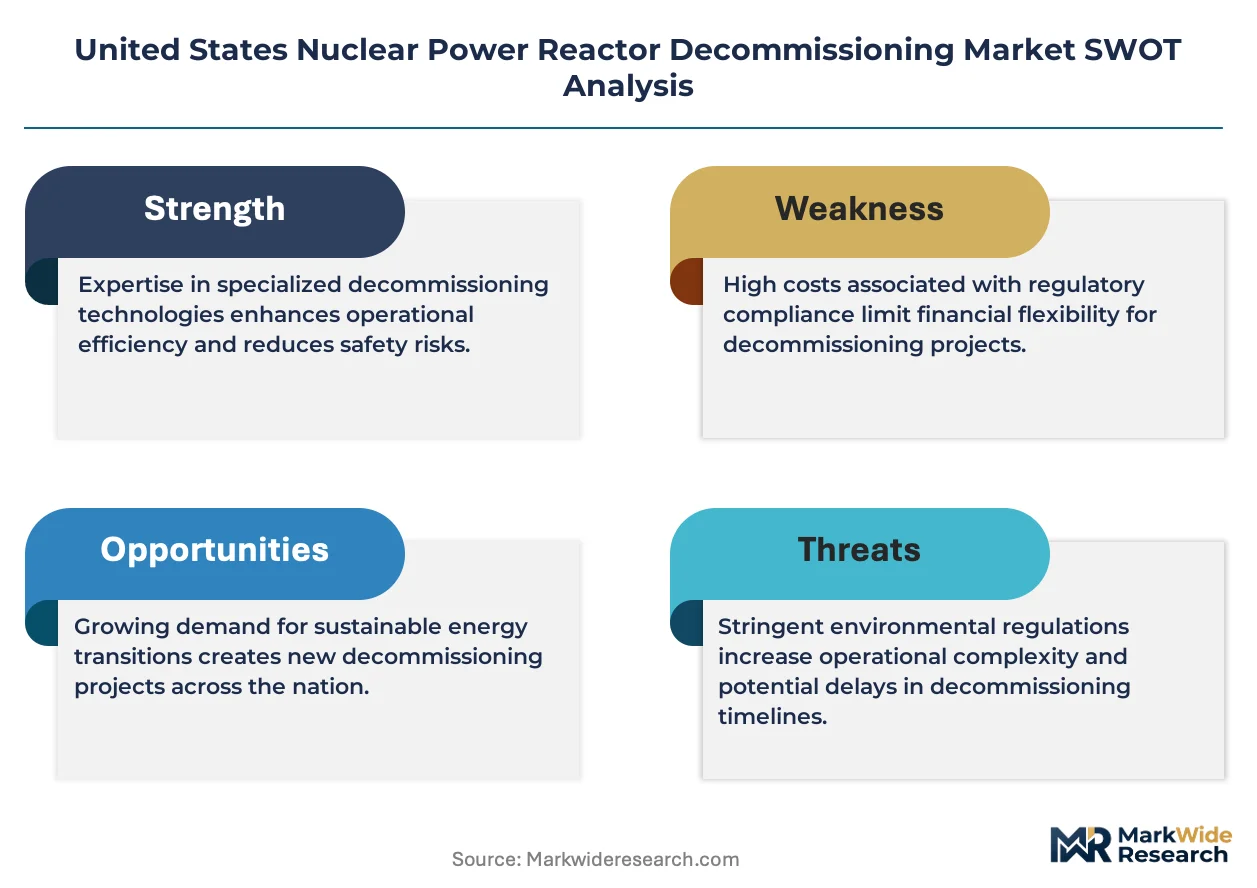
The United States Nuclear Power Reactor Decommissioning Market operates as a cost-of-compliance arena where the NRC's 10 CFR Part 50.82 license termination framework erects formidable barrier-to-entry moats favoring incumbents with established regulatory track records and NRC-licensed infrastructure.
For Market Incumbents: Anticipate margin compression from emerging robotics specialists by deepening captive supply of plasma arc cutting systems and Health Physics Technician training pipelines. Consolidate multi-site capacity positions across Illinois and New York to capture comprehensive fleet retirement contracts. Defensive positioning requires pre-emptive community benefit agreement negotiations before emergency planning zone reductions trigger municipal revenue cliffs. For New Entrants and Emerging Players: Begin with radiological characterization accuracy services, the fastest-growing planning phase segment where incumbent tooling libraries offer limited advantage. Target South Texas Project and Comanche Peak emerging demand corridors where established Northeast contractor relationships remain underdeveloped. Go-to-market positioning centers on fixed-price characterization contracts with performance guarantees against dose survey variance. For Investors and Strategic Acquirers: Distressed-cycle entries favor turnkey contractors with simultaneous multi-site execution capacity in the Great Lakes corridor, where state-level spent fuel litigation accelerates dry cask campaign timelines. Long-term viability hinges on integrated waste logistics positioning through licensed disposal facility access or captive rail transport corridors. The signal to watch is NRC rulemaking on emergency planning zone reduction timing, which determines when local tax burden shifts activate community consent frameworks and site repurposing velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Type B Package Certification Investment | NRC-DOT dual jurisdiction unlocks spent fuel transport revenue pools beyond commodity demolition. |
| Plasma Arc Cutting Capability Buildout | Reactor pressure vessel segmentation timelines compress from months to weeks at pressurized water reactor sites. |
| Clive Disposal Facility Slot Securement | Integrated waste logistics contracts capture multi-year revenue visibility through low-level waste volume commitments. |
| Health Physics Technician Pipeline Development | Tennessee Valley certification density addresses labor bottlenecks constraining project mobilization. |
| Community Benefit Agreement Pre-negotiation | Illinois and New York municipal consent frameworks secure site repurposing before EPZ reduction triggers. |
Research Methodology
Document review covered NRC license termination filings, decommissioning trust fund financial disclosures, and Department of Transportation Type B package certification records, complemented by interviews with decommissioning project directors, Health Physics Technician certification bodies, utility trust fund administrators, and Clive disposal facility logistics coordinators. Secondary validation drew from FERC rate-case proceedings, EPA CERCLA remedial investigation databases, and state-level public utility commission dockets. Bottom-up project pipeline enumeration triangulated against top-down utility fleet retirement announcements.
Historical decommissioning cost actuals cross-referenced against expert panel input on robotics productivity gains shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass decommissioning method, end-user procurement authority, process phase, and waste management classification. CAGRs derived from license expiration schedules, trust fund adequacy thresholds, and regulatory timeline compression assumptions. Industry-specific forecast inputs include spent fuel pool offload coordination constraints and plasma arc cutting penetration rates.
Underlying measurement precision varies by segment; Implementation Phase labor hours carry tighter precision than Planning Phase characterization variance. Forecasts reflect documented assumptions regarding NRC rulemaking velocity and geologic repository policy continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Thorium Market
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
Nuclear Power Pump Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Small Modular Reactor (SMR) Market
Nuclear Energy
North America Nuclear Reactor Construction Market