
 Global Power Plant Uranium Market | 2026-2036
Global Power Plant Uranium Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Plant Uranium Market Foresight
The EU Green Deal taxonomy is repositioning nuclear energy within sustainable finance frameworks, compelling European utilities to secure long-term uranium offtake. Cameco Corporation leverages its McArthur River and Cigar Lake assets to sustain supply reliability for Western reactor operators. NAC Kazatomprom JSC anchors global production volume through its in-situ recovery dominance in Kazakhstan. Orano SA differentiates via integrated conversion and enrichment capabilities across the French nuclear fuel cycle.
Power plant uranium encompasses uranium-bearing materials processed to fuel commercial nuclear reactors, typically requiring enrichment to three-to-five percent uranium-235 for light-water reactor compatibility and fabricated into ceramic fuel pellets within zirconium alloy cladding. Uranium hexafluoride dominates conversion-stage trade flows due to its volatility suitability for gaseous centrifuge enrichment, while uranium fuel assemblies command concentrated margin pools at the fabrication terminus. Low enriched uranium grades lead procurement volumes for civilian power generation, whereas highly enriched material occupies specialized defense and research reactor niches with stringent access controls.
The U.S. Nuclear Regulatory Commission enforces fuel qualification standards that shape enrichment specifications and reactor operator procurement criteria, while the International Atomic Energy Agency safeguards framework governs material accountancy and non-proliferation compliance across bilateral supply agreements. China's National Nuclear Safety Administration and Ministry of Ecology Environment impose domestic conversion and fabrication licensing requirements that condition market access for imported uranium feedstock. Stakeholders must monitor enrichment capacity buildout timelines and safeguard protocol negotiations as supply chain restructuring accelerates.
Market Dynamics
Western reactor operators are accelerating long-term offtake contracting as geopolitical fragmentation forces supply chain restructuring away from concentrated sources. This structural pressure is compressing procurement timelines and redirecting capital toward fuel security investments across multiple jurisdictions.
Growth Catalysts
- EU Green Deal Taxonomy:The inclusion of nuclear energy within sustainable finance frameworks compels European utilities to secure certified uranium supplies through long-term purchase agreements.
- Baseload Power Reliability:Grid operators facing renewable intermittency constraints are prioritizing nuclear capacity factors, expanding demand for high-assay low-enriched uranium reload cycles.
- Kazakhstan Production Scale:In-situ recovery operations in Kazakh deposits maintain cost advantages that sustain global supply availability despite Western diversification efforts.
Market Restraints
- Enrichment Capacity Bottlenecks:Conversion facility limitations in North America and Europe constrain the ability to process raw uranium into reactor-ready fuel forms.
- Secondary Supply Depletion:Former weapons stockpiles from Cold War-era disarmament agreements are approaching exhaustion, removing a price-dampening supply buffer.
- Project Development Timelines:Greenfield mine permitting under Canada's federal environmental assessment process extends from discovery to production beyond typical utility contracting horizons.
Strategic Opportunities
- SMR Fuel Fabrication:Small modular reactor developers in the United States require specialized fuel forms with higher burnup potential, creating demand for advanced ceramic matrix technologies.
- Australian Uranium Development:Untapped deposits in South Australia and the Northern Territory offer Western-aligned supply alternatives as utilities reduce Russian and Chinese dependencies.
- Domestic Enrichment Revival:The U.S. Department of Energy's HALEU availability program is subsidizing domestic centrifuge capacity expansion for advanced reactor fuel cycles.
Industry Challenges
- Geoscientist Workforce Scarcity:Specialized expertise in uranium deposit characterization has atrophied during two decades of price depression, constraining exploration program execution.
- Safeguards Integration Complexity:The International Atomic Energy Agency's material accountancy protocols require costly infrastructure at each conversion and enrichment stage, complicating supply chain reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Plant Uranium Market |
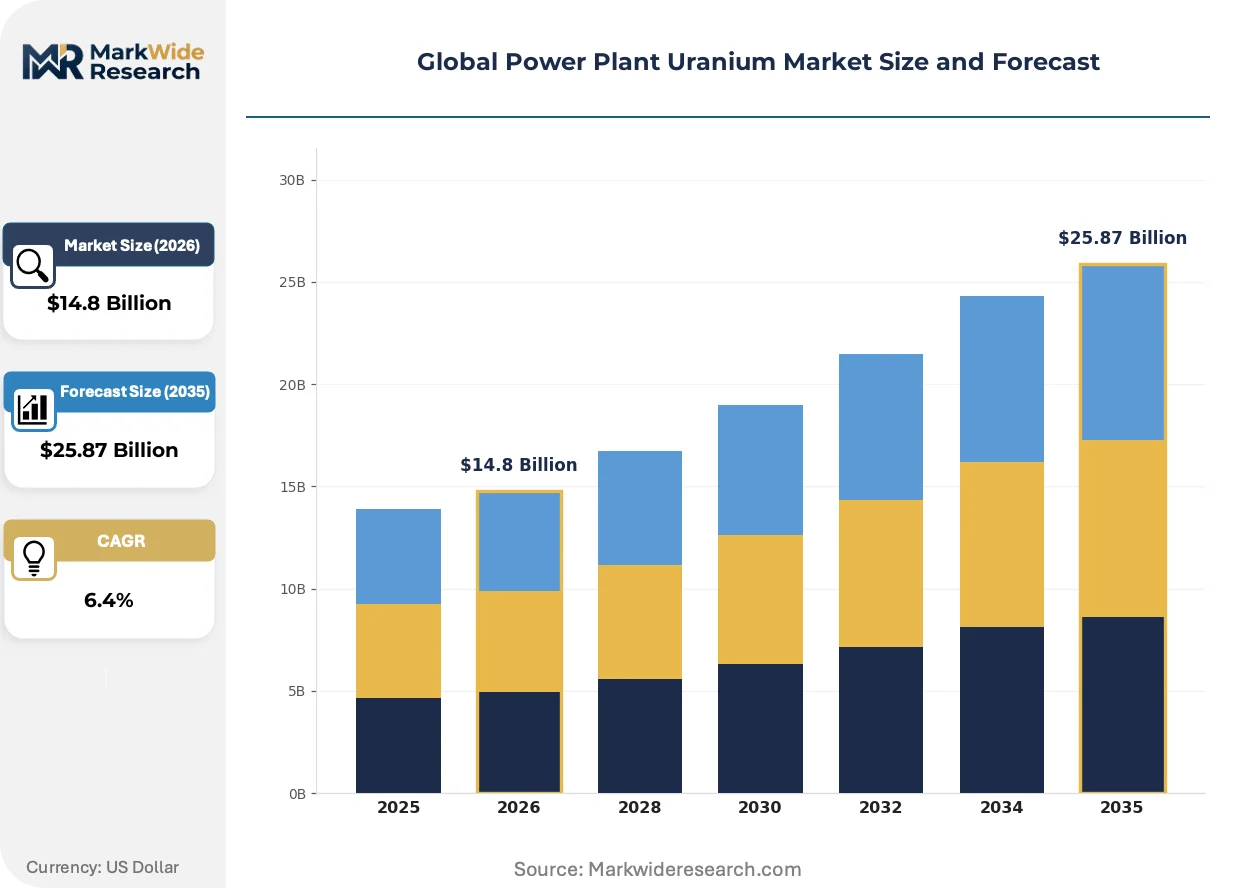
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uranium Oxide, Uranium Hexafluoride, Uranium Enrichment, Uranium Fuel Assemblies End User: Nuclear Power Plants, Research Reactors, Industrial Applications, Defense Supply Chain Stage: Extraction, Milling, Conversion, Fabrication Quality Grade: Low Enriched, Highly Enriched, Fuel Standard, Others |
| Companies Covered | Cameco Corporation, NAC Kazatomprom JSC, Orano SA, Uranium One Inc, China General Nuclear Power Group, Navoi Mining and Metallurgy Combinat, China National Nuclear Corporation, BHP Group Ltd, ARMZ Uranium Holding Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Plant Uranium Market Shifts & Advancements
Reactor technology diversification is fragmenting fuel specifications and demanding new enrichment and fabrication capabilities. This evolution is compressing traditional supply chain structures while opening specialized service niches.
Advanced centrifuge technology is modularizing enrichment plant deployment, allowing incremental capacity additions rather than massive centralized facilities. Utilities in Poland and the Czech Republic are evaluating these smaller-scale configurations for national fuel security. The technology is modularizing investment risk, enabling state-backed entities to enter enrichment without the capital intensity of previous generations.
The EU Green Deal taxonomy is reclassifying nuclear investments as sustainable, triggering capital reallocation under the CSRD disclosure framework. European banks previously restricted from nuclear lending are reactivating project finance desks for fuel cycle infrastructure. French and Finnish utilities are responding by extending contracting horizons beyond the typical five-year windows.
Buyer consortium structures are displacing bilateral utility-supplier relationships in uranium procurement. Japanese and South Korean reactor operators are pooling demand through collective purchasing agreements to secure volume discounts and supply diversification. This pattern is most visible in Asia-Pacific markets where import dependence exceeds ninety percent for all participants.
Global Power Plant Uranium Market Segmentation
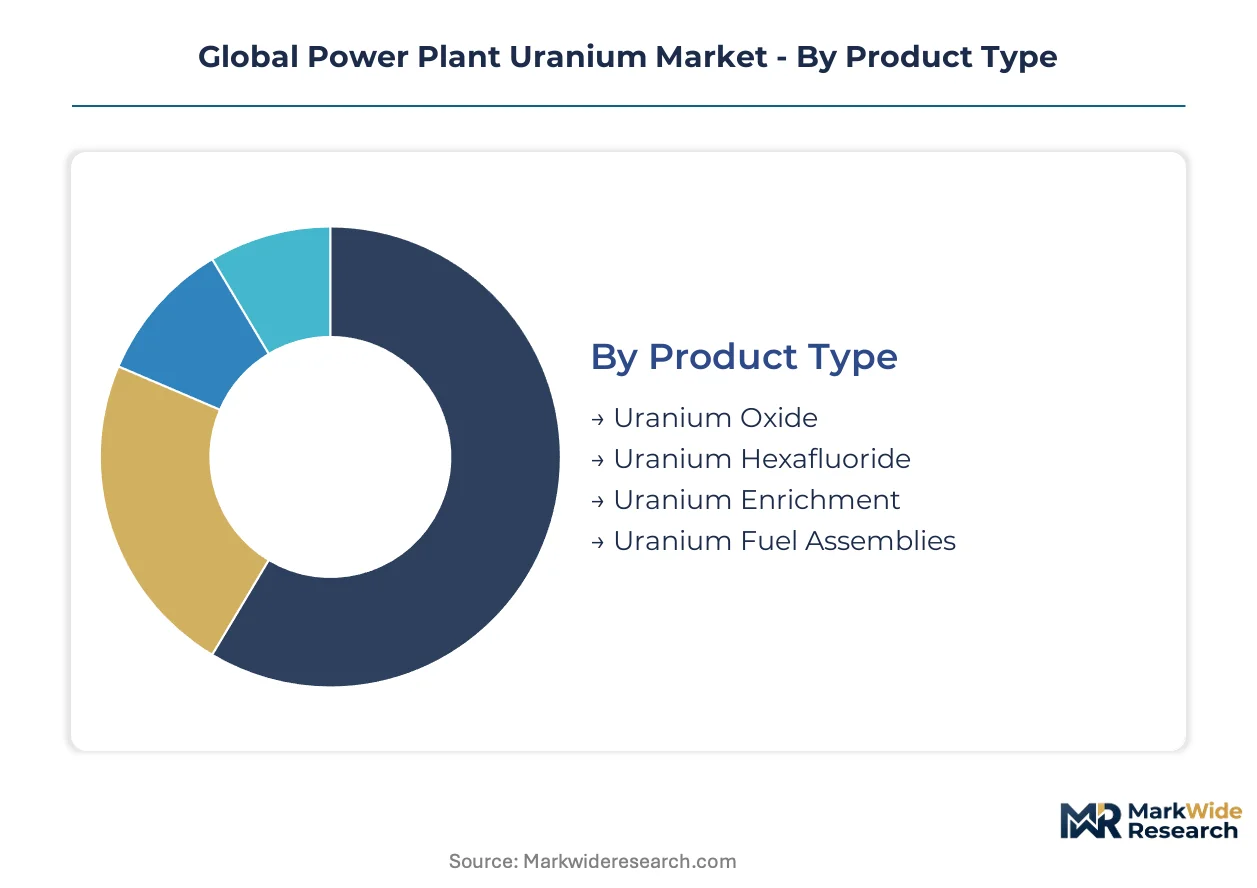
Uranium procurement decisions split across fuel form specifications, reactor operator requirements, and safeguard compliance tiers. Each segmentation dimension carries distinct contracting timelines, pricing mechanisms, and regulatory qualification burdens that reshape supplier relationships.
Product Type:
Reactor operators select fuel forms based on enrichment infrastructure access and reload cycle economics, with conversion-ready intermediates commanding premium logistics.
- Uranium Hexafluoride:Volatile compound suited to gaseous centrifuge enrichment dominates inter-regional trade flows. Western utilities in France and the United States prioritize UF6 procurement under long-term tolling agreements to secure conversion capacity ahead of enrichment bottlenecks.
- Uranium Fuel Assemblies:Ceramic pellets sealed in zirconium alloy cladding represent the terminal fabrication stage with concentrated margin capture. Japanese and South Korean reactor operators source finished assemblies from domestic fabrication facilities to minimize safeguard handoff complexity.
- Uranium Oxide:Yellowcake concentrate from milling operations serves as the foundational feedstock for all downstream processing.
- Uranium Enrichment:Separative work units delivered as enriched uranium product require bilateral safeguard protocols under IAEA material accountancy.
Volume sits with uranium hexafluoride; growth tilts toward finished fuel assemblies as utilities outsource fabrication to specialized providers.
End User:
Demand concentration varies sharply by safeguard intensity, fuel specification tolerance, and contracting horizon length across civilian and non-civilian applications.
- Nuclear Power Plants:Commercial light-water reactors consume standardized low-enriched uranium reloads on 12-18 month cycles. Operators in Finland and the Czech Republic are extending contracting windows to 10-year terms under EU Green Deal taxonomy alignment pressures.
- Research Reactors:Specialized high-flux facilities require highly enriched uranium or high-assay low-enriched alternatives with stringent access controls. Russian-origin fuel supplies to European research installations face accelerating substitution mandates.
- Industrial Applications:Isotope production and materials testing reactors operate on smaller batch procurement with flexible enrichment specifications.
- Defense:Naval propulsion and weapons programs operate outside commercial safeguard frameworks with dedicated enrichment cascades.
Commercial nuclear power plants absorb the dominant procurement volume; research reactor fuel conversion programs are expanding most quickly as highly enriched stockpiles phase down.
Supply Chain Stage:
Capital intensity and regulatory qualification requirements concentrate margin capture at conversion and fabrication stages while extraction faces cost pressures from in-situ recovery competition.
- Conversion:Transformation of yellowcake to uranium hexafluoride occurs at a handful of facilities in Canada, France, and the United States. Capacity constraints here currently throttle the entire fuel cycle, with Western utilities paying premiums for guaranteed queue positions.
- Extraction:In-situ recovery operations in Kazakhstan and open-pit mining in Namibia supply the majority of global yellowcake. Australian deposits in South Australia offer Western-aligned alternatives as supply chain restructuring accelerates.
- Milling:Crushing and chemical processing of ore into yellowcake concentrate operates at mine-adjacent facilities with standardized environmental permitting.
- Fabrication:Final fuel assembly production requires reactor-specific licensing and quality certification from national regulators including the U.S. Nuclear Regulatory Commission.
Extraction commands the volume base; conversion capacity is climbing the fastest as Western governments subsidize domestic infrastructure buildout.
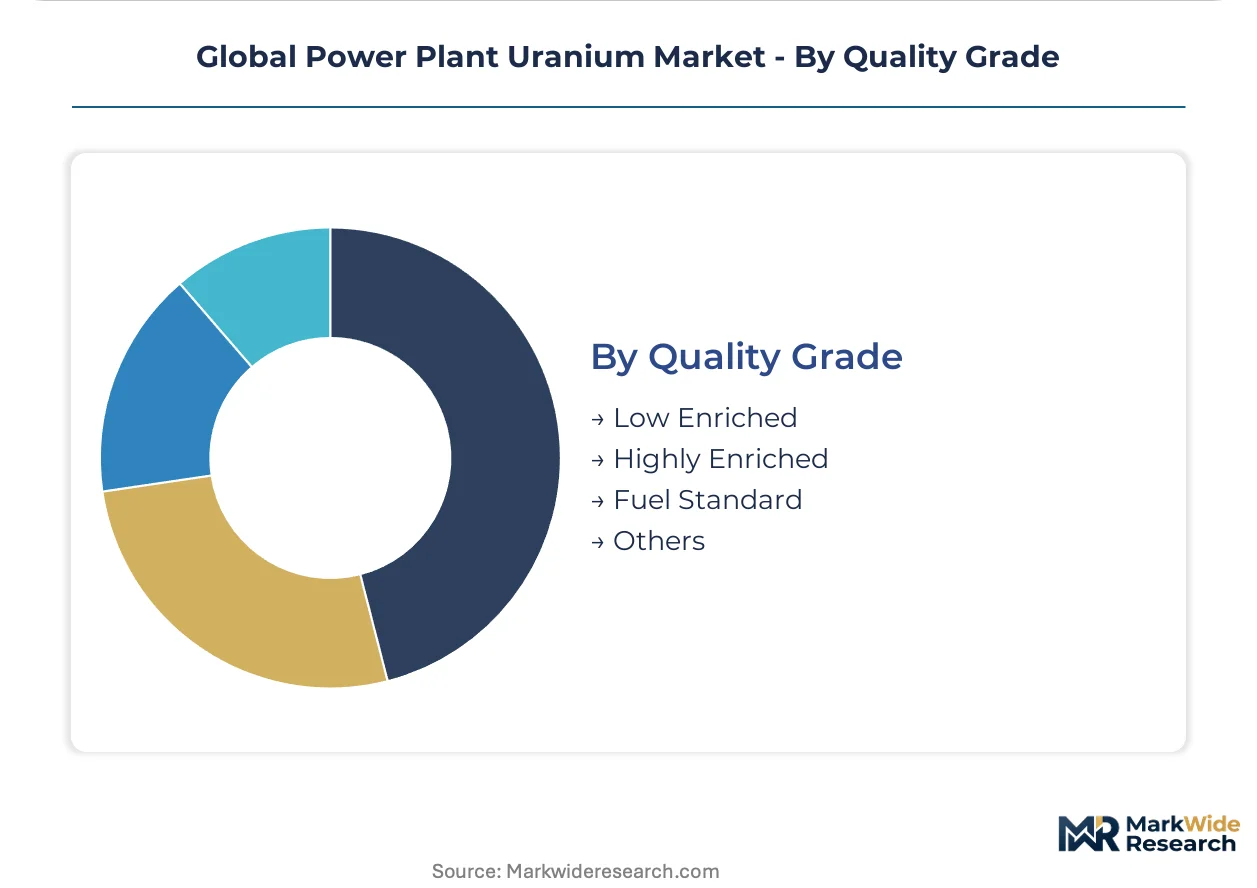
Quality Grade:
Enrichment level determines reactor compatibility, safeguard tier, and pricing structure across civilian and specialized applications.
- Low Enriched:Three-to-five percent uranium-235 content fuels commercial light-water reactors globally. This grade absorbs procurement volumes from utilities in Poland, Romania, and Hungary as reactor construction programs advance.
- Highly Enriched:Twenty percent or greater uranium-235 content serves research reactors and naval propulsion with restricted commercial access. Downblending programs are converting former weapons material for civilian use.
- Fuel Standard:Utility-specific enrichment specifications tailored to individual reactor designs and burnup optimization targets.
- Others:Depleted uranium tails and reprocessed plutonium-uranium mixed oxides occupy niche recycling applications.
Low enriched uranium carries the volume concentration; high-assay low-enriched variants are gaining share fastest as advanced reactor developers specify higher burnup potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saskatoon anchors the Western uranium supply corridor through Cameco Corporation's McArthur River and Cigar Lake operations, with Canadian deposits supplying utilities across multiple continents under long-term offtake frameworks.
United States
Utilities in Texas and the Southeast are extending procurement timelines beyond traditional five-year windows under fuel security mandates from the U.S. Nuclear Regulatory Commission. The Department of Energy's HALEU availability program is subsidizing domestic centrifuge capacity expansion in Ohio and Tennessee. Reactor operators in the Midwest are consolidating demand through buyer consortium structures to secure volume discounts from Kazakh and Canadian suppliers.
Kazakhstan
NAC Kazatomprom JSC maintains production dominance through in-situ recovery operations concentrated in the southern regions near Shymkent and Turkistan. The national atomic company operates outside Western safeguard protocols while supplying utilities in China, India, and Eastern Europe. Local deposits sustain cost advantages that underpin global supply availability despite geopolitical pressures for diversification.
France
Orano SA integrates conversion and enrichment capabilities across the La Hague and Tricastin nuclear complexes under EU Green Deal taxonomy alignment pressures. EDF is extending contracting horizons to ten-year terms to satisfy sustainable finance disclosure requirements from the European Banking Authority. The Paris-based fuel cycle infrastructure serves reactor operators in Finland, the Czech Republic, and Belgium.
Australia
Untapped deposits in South Australia and the Northern Territory offer Western-aligned supply alternatives as utilities reduce dependencies on concentrated sources. BHP Group Ltd operates the Olympic Dam polymetallic complex near Roxby Downs under federal environmental assessment protocols administered by the Australian Radiation Protection and Nuclear Safety Agency. Western utilities are accelerating exploration licensing in the Gawler Craton region to secure long-term feedstock.
China
China General Nuclear Power Group and China National Nuclear Corporation are consolidating domestic conversion and fabrication licensing under the National Nuclear Safety Administration and Ministry of Ecology and Environment. Reactor construction programs in Guangdong and Fujian provinces are absorbing expanding procurement volumes from Kazakh and African suppliers. The state-backed entities are negotiating bilateral safeguard protocols to secure material accountancy compliance for imported yellowcake.
Global Power Plant Uranium Market Competitive Landscape
The competitive structure tilts toward state-backed and vertically integrated incumbents with captive conversion infrastructure. Production capacity concentrates among five dominant operators controlling in-situ recovery deposits in Central Asia and high-grade unconformity deposits in Canada. Two strategic archetypes define positioning: integrated fuel cycle operators with enrichment tolling capabilities, and pure-play miners dependent on third-party conversion queues. Competitive moves center on long-term offtake contracting acceleration and national fuel security partnerships with utilities facing supply chain restructuring pressures.
Within the integrated fuel cycle tier, Orano SA exemplifies European conversion-enrichment capabilities, while Cameco Corporation anchors Western mining supply reliability. NAC Kazatomprom JSC occupies the production volume leadership position through Kazakh in-situ recovery dominance. These three entities represent distinct geographic and regulatory positioning strategies as utilities diversify procurement across multiple jurisdictions.
| Leading Market Players |
|---|
| Cameco Corporation |
| NAC Kazatomprom JSC |
| Orano SA |
| Uranium One Inc |
| China General Nuclear Power Group |
| Navoi Mining and Metallurgy Combinat |
| China National Nuclear Corporation |
| BHP Group Ltd |
| ARMZ Uranium Holding Co |
| Others |
Supply & Pricing Matrix
Western utility consortiums pooling procurement through collective purchasing agreements are compressing supplier margins and forcing producers to guarantee conversion queue positions ahead of enrichment bottlenecks. This buyer consolidation is redistributing pricing power toward fuel cycle operators with captive infrastructure while squeezing pure-play miners dependent on third-party tolling.
Pricing Analysis
Long-term offtake contracts indexed to separative work unit benchmarks anchor commercial negotiations between reactor operators and fuel suppliers. Pricing stratifies across enrichment service tiers, high-assay low-enriched uranium premiums, and fabrication complexity grades. Cost compression in standard low-enriched uranium is intensifying because Kazakh in-situ recovery operations sustain global supply availability at marginal cost floors. Research reactor operators exhibit the highest price sensitivity due to limited procurement volumes, while baseload utilities securing ten-year terms demonstrate the lowest.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale buyer demand for yellowcake and uranium hexafluoride, bypassing intermediaries to secure material accountancy compliance under bilateral IAEA protocols. Production gravity centers on Kazakhstan, Canada, and Australia as Western diversification accelerates. The fuel cycle draws from sulfuric acid for in-situ recovery leaching, fluorine gas for hexafluoride conversion, and zirconium alloy for cladding fabrication. Single-source vulnerability concentrates at conversion facilities in North America and Europe. Distribution runs through national nuclear fuel companies and state-backed atomic energy corporations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global power plant uranium market is transitioning from legacy light-water reactor fuel cycles toward high-assay low-enriched uranium specifications demanded by advanced reactor developers. Small modular reactor deployment timelines are compressing procurement windows for specialized ceramic matrix fuel forms.
For Market Incumbents: Deepen backward integration into conversion infrastructure to defend margin capture against Kazakh cost advantages and secure queue positions ahead of Western capacity buildout. Invest in HALEU certification pathways under U.S. Nuclear Regulatory Commission fuel qualification standards to anchor supply relationships with advanced reactor developers in Tennessee and Ohio. For New Entrants and Emerging Players: Digital procurement platforms aggregating research reactor demand offer a route to bypass entrenched utility-supplier relationships and capture fragmented high-enriched uranium substitution contracts. Target Australian exploration licensing in the Gawler Craton region where Western-aligned supply alternatives command premium offtake terms. Position around specialized fuel fabrication for small modular reactors as incumbent capacity concentrates on legacy light-water reload cycles. For Investors and Strategic Acquirers: The window for entry favors vertically integrated fuel cycle operators with enrichment tolling capabilities and IAEA safeguard infrastructure already deployed. Long-term viability hinges on exposure to EU Green Deal taxonomy-aligned European utilities extending contracting horizons. Monitor centrifuge capacity utilization rates at Orano's Tricastin complex as the inflection indicator for Western supply security premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Enrichment Capacity Buildout | U.S. Department of Energy HALEU subsidies in Ohio and Tennessee reduce import dependence for advanced reactor fuel. |
| Long-term Supply Agreement | Finnish and Czech utilities extend contracting windows to ten-year terms under EU Green Deal disclosure requirements. |
| Backward Integration into Conversion | Cameco Corporation's tolling agreements secure queue positions ahead of North American capacity constraints. |
| Technology Licensing | Advanced centrifuge modularization enables Polish and Czech national fuel security programs without massive capital deployment. |
| Joint Venture | Japanese and South Korean buyer consortiums pool demand to secure volume discounts from Kazakh and Canadian suppliers. |
Research Methodology
Independent corroboration across fuel cycle executives, utility procurement officers, and conversion facility operators underwrites the qualitative findings on supply chain restructuring pressures. Primary interviews with reactor planning specialists, enrichment plant managers, and IAEA safeguard inspectors combined with secondary validation from EIA uranium marketing reports, IEA nuclear energy outlooks, and FERC fuel cost disclosures. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Comparable-period anchoring to historical procurement cycle data established baseline contracting patterns across the analysis window. The analytical framework modeled product type splits between uranium hexafluoride and finished fuel assemblies, end-user concentration across commercial power plants and research reactors, supply chain stage margin capture, and quality grade differentiation between low-enriched and high-assay variants. CAGRs derived from utility construction timelines, reactor restart schedules, and enrichment capacity expansion trajectories.
The model holds under sustained EU Green Deal taxonomy alignment and continued Kazakh production scale; deviation in safeguard protocol negotiations or conversion facility permitting delays would shift supply availability assumptions. Forecasts reflect documented base conditions around reactor construction programs and secondary supply depletion curves. Periodic stress-testing of base assumptions is recommended against enrichment capacity utilization rates and bilateral supply agreement renegotiation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Power Pump Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
United Kingdom Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Small Modular Reactor (SMR) Market
Nuclear Energy
Nuclear Energy Market
Nuclear Energy
Nuclear Fuels Market