
 Europe Nuclear Power Plant and Equipment Market | 2026-2036
Europe Nuclear Power Plant and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nuclear Power Plant and Equipment Market Foresight
France's reactor construction pipeline is fragmenting procurement across multiple domestic and international suppliers. Framatome leverages its vertically integrated fuel and component manufacturing to anchor French new-build programs. Westinghouse Electric Company competes on AP1000 reactor technology for utilities seeking Generation III+ designs. GE Vernova sustains turbine generator leadership through long-term service contracts with European utilities.
Europe nuclear power plant and equipment encompasses reactor pressure vessels, steam generators, control rod drive mechanisms, and safety-class instrumentation rated for seismic and loss-of-coolant accident conditions, manufactured from low-alloy steel forgings with stainless steel cladding to contain fission reactions and convert thermal energy to electricity. Pressurized Water Reactor technology dominates installed capacity and attracts the majority of replacement component demand. Safety Systems represent a concentrated margin pool as regulatory mandates tighten post-Fukushima upgrade requirements. Fast Breeder Reactor development occupies niche research funding but remains structurally immature for commercial deployment.
EMA, the EU Green Deal taxonomy framework, and national regulators such as ASN in France shape equipment certification timelines and capital allocation across the European supply base. REACH compliance for specialized alloys and the F-Gas Regulation for cooling systems add material qualification burdens that filter vendor eligibility. Stakeholders must monitor final investment decisions for small modular reactor projects in Poland and the Czech Republic to calibrate component demand timing.
Market Dynamics
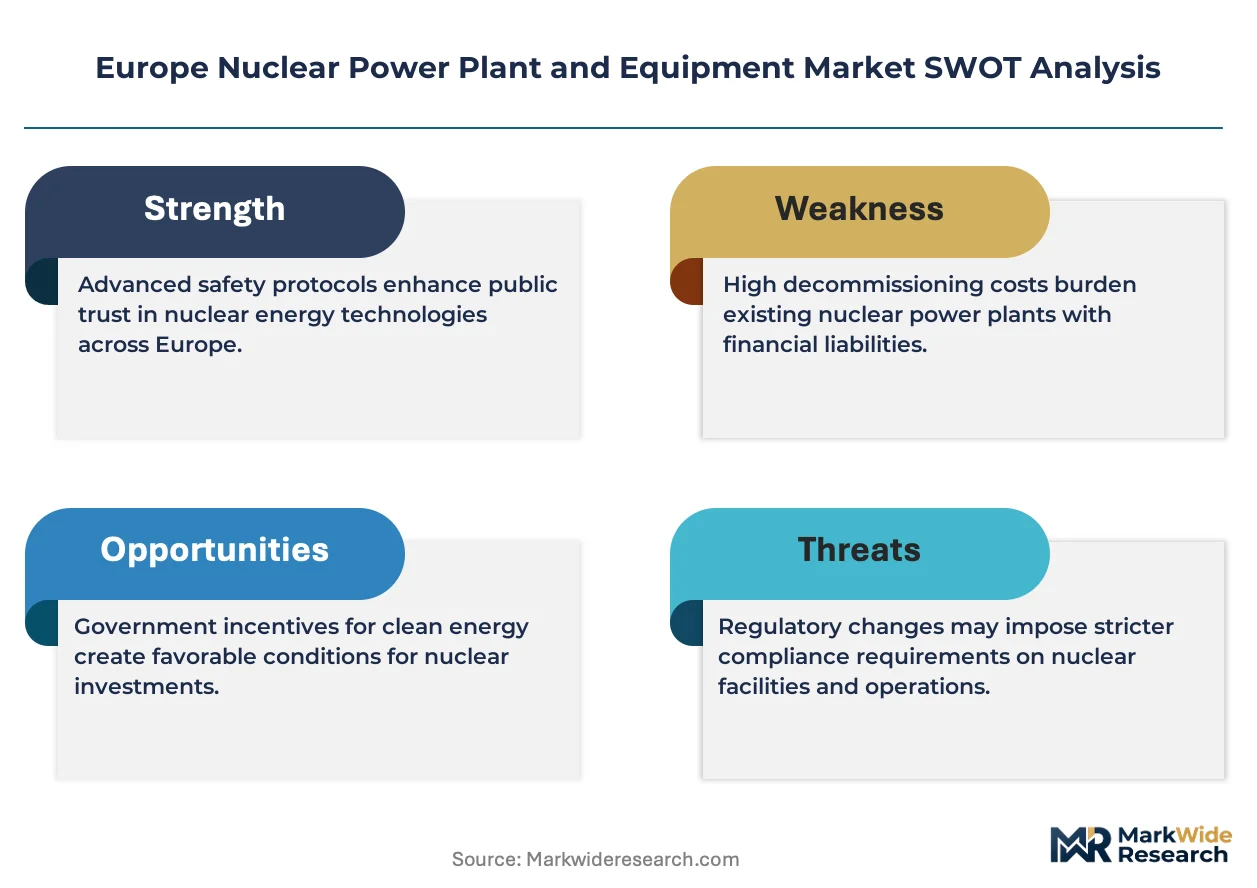
The European nuclear equipment supply base faces a structural squeeze between reactor construction deadlines and the EU Green Deal taxonomy's capital redirection, forcing vendors to qualify components under both ASN safety protocols and REACH alloy standards simultaneously.
Growth Catalysts
- EU Green Deal Taxonomy:The sustainable finance framework reclassifies nuclear investments as environmentally sustainable, unlocking institutional capital for new reactor builds across France and the United Kingdom.
- France:EDF's fleet expansion program generates concentrated demand for replacement steam generators and reactor pressure vessels, anchoring procurement volumes for domestic and international suppliers.
- Small Modular Reactor technology:Poland and the Czech Republic are advancing SMR demonstration projects, creating early-mover equipment qualification opportunities for component manufacturers.
Market Restraints
- Forged component supply:Reactor pressure vessel manufacturing depends on a shrinking pool of qualified steel forges, with capacity concentrated in Japan and South Korea outside European borders.
- REACH compliance burdens:Specialized nickel alloys and cobalt-based materials face extended toxicity testing timelines, delaying component certification for safety-class applications.
- Construction cost escalation:EPR reactor builds at Flamanville and Olkiluoto experienced multi-billion euro overruns, chilling utility appetite for greenfield projects.
Strategic Opportunities
- Poland:The country's first nuclear program offers virgin-market positioning for vendors able to establish local partnerships and meet Polish regulatory qualification requirements.
- Long-term service agreements:Utilities are unbundling turbine generator maintenance from original equipment supply, creating recurring revenue streams for independent service providers.
- Digital instrumentation convergence:Integration of wireless sensor networks with legacy safety systems opens upgrade pathways for cybersecurity-hardened control rod drive mechanisms.
Industry Challenges
- Welding specialist scarcity:ASME Section IX-qualified nuclear welders are retiring faster than training programs replace them, constraining fabrication throughput for safety-class pressure boundary components.
- Multi-jurisdictional licensing:Equipment vendors must secure parallel approvals from ASN in France, ONR in the United Kingdom, and national regulators in emerging nuclear markets, fragmenting compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nuclear Power Plant and Equipment Market |
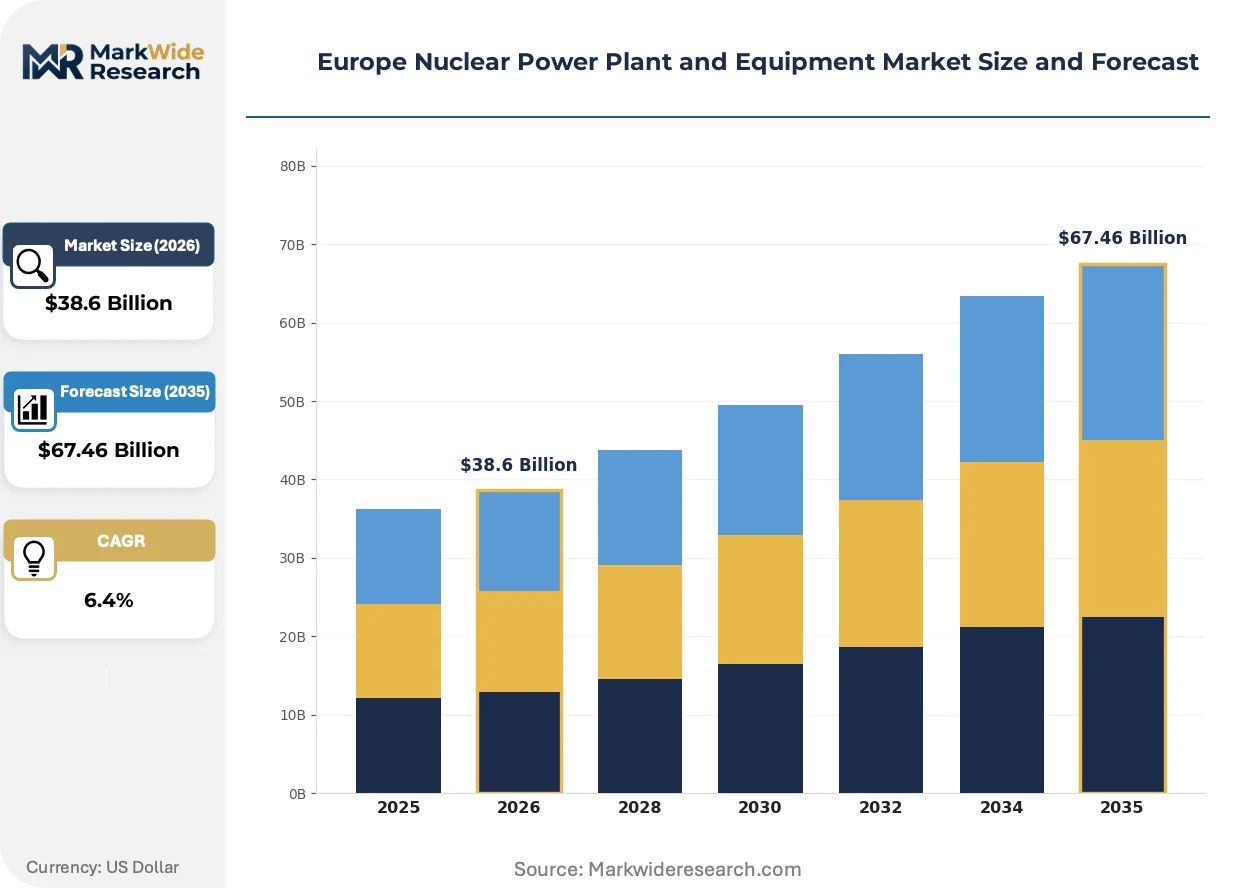
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactor Components, Safety Systems, Control Systems, Turbine Generators Application: Energy Generation, Research Facilities, Safety Management, Maintenance Services End User: Utilities, Government Bodies, Industrial Players, Research Organizations Technology: Pressurized Water Reactor, Boiling Water Reactor, Fast Breeder Reactor, Heavy Water Reactor |
| Companies Covered | Mitsubishi Heavy Industries, Westinghouse Electric Company, Framatome, GE Vernova, BWX Technologies, EDF, Doosan Corporation, Alstom, Rosatom State Atomic Energy Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nuclear Power Plant and Equipment Market Shifts & Advancements
European nuclear equipment markets are pivoting toward modular construction methods and digitally integrated safety systems, compressing traditional engineering-procurement-construction timelines while raising cybersecurity qualification thresholds.
Advanced manufacturing for reactor components is migrating from conventional forging toward additive manufacturing for complex valve bodies and pump impellers. EDF and Framatome are piloting 3D-printed stainless steel parts for non-safety applications. This shift is compressing lead times for replacement components from eighteen months to under six months for qualified geometries.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in reactor cooling systems and auxiliary HVAC equipment. Equipment suppliers must redesign heat exchangers and chillers to accommodate lower-global-warming-potential refrigerants. French and Finnish utilities operating EPR fleets are absorbing the highest retrofit costs due to their sealed cooling system architectures.
Utility procurement teams are consolidating component sourcing through framework agreements spanning multiple reactor sites. EDF's centralized purchasing function now bundles steam generator tube orders across its entire French fleet, displacing site-by-site tendering. This concentration is most visible in France, where single-source contracts for safety-class instrumentation now cover ten-year replacement cycles.
Europe Nuclear Power Plant and Equipment Market Segmentation
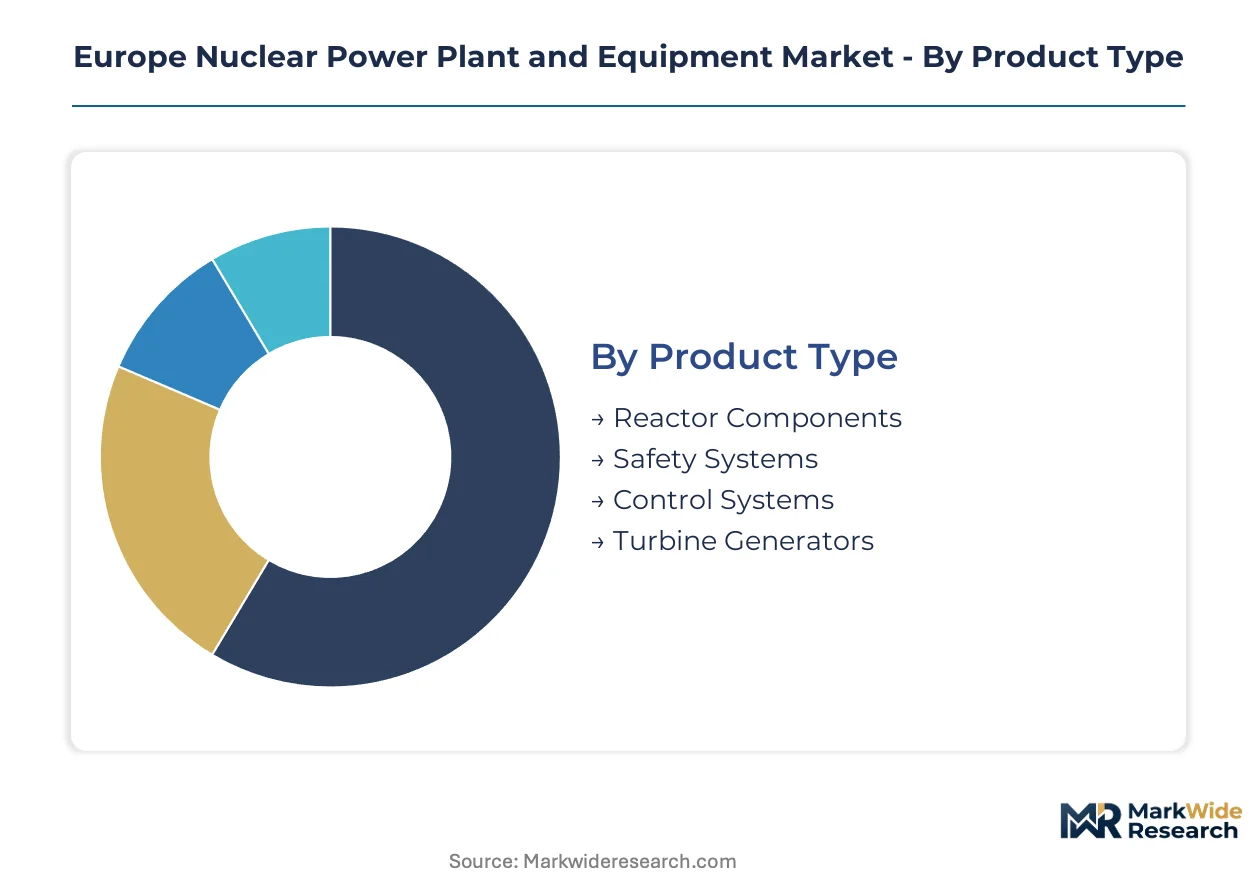
Equipment procurement cycles vary dramatically across nuclear plant systems, with some components requiring decade-long replacement intervals while others face annual upgrade mandates. Understanding these temporal patterns helps suppliers align inventory and qualification investments with actual demand velocity.
Product Type:
Replacement cycles stretch from months for digital instrumentation to decades for reactor pressure boundaries, creating divergent revenue predictability across supplier portfolios.
- Reactor Components:Forged steel pressure vessels and steam generators incorporate low-alloy steel with stainless steel cladding rated for radiation and thermal fatigue. EDF's French fleet replacement program concentrates procurement for steam generator tube bundles, though qualified forging capacity bottlenecks in Japan and South Korea constrain delivery schedules.
- Safety Systems:Emergency core cooling systems and containment spray pumps operate under ASN and ONR seismic qualification protocols with post-Fukushima upgrade mandates accelerating replacement timelines. Regulatory tightening across France and the United Kingdom is compressing procurement cycles for safety-class instrumentation.
- Control Systems:Digital reactor protection systems integrate cyber-hardened architectures with wireless sensor networks.
- Turbine Generators:High-pressure and low-pressure turbine rotors with alloy steel forgings drive baseload conversion efficiency.
Reactor Components anchors the volume base while Safety Systems gains share at the steepest rate.
Application:
Capital intensity and regulatory scrutiny intensify moving from routine maintenance toward greenfield energy generation, fragmenting vendor specialization across the value chain.
- Energy Generation:Commercial power reactors operating above 1,000 MWe dominate installed base economics across France, the United Kingdom, and Finland. EDF's fleet expansion and UK new-build programs at Hinkley Point C concentrate demand for NSSS equipment and long-term fuel supply contracts.
- Safety Management:Post-Fukushima regulatory mandates from ASN and ONR require continuous monitoring system upgrades and severe accident management equipment. French and British utilities face overlapping compliance deadlines for beyond-design-basis event mitigation hardware.
- Research Facilities:Materials test reactors and fusion research installations drive specialized component demand.
- Maintenance Services:Refueling outages and in-service inspection programs sustain recurring revenue for specialized tooling and non-destructive testing equipment.
Energy Generation commands the capital allocation while Safety Management expands most quickly.
End User:
Procurement authority concentrates in entities with fleet-scale purchasing power, marginalizing smaller buyers in qualification-intensive safety-class markets.
- Utilities:EDF, E.ON, and Vattenfall operate centralized procurement functions bundling component orders across multiple reactor sites. Framework agreements now span ten-year replacement cycles for steam generator tubes and control rod drive mechanisms, displacing site-specific tendering.
- Government Bodies:State-backed nuclear programs in Poland and the Czech Republic represent first-mover opportunities for vendors establishing regulatory relationships. Polish nuclear agency PAA qualification requirements differ from established Western European protocols, demanding dedicated compliance investment.
- Industrial Players:Process heat applications and desalination projects drive specialized reactor system demand.
- Research Organizations:CEA in France and national laboratories across Europe sustain niche procurement for experimental reactor components.
Utilities dominate procurement volume while Government Bodies climb the fastest as new nuclear programs advance.
Technology:
Reactor architecture determines equipment specifications, supplier ecosystems, and regulatory approval pathways with limited interchangeability between designs.
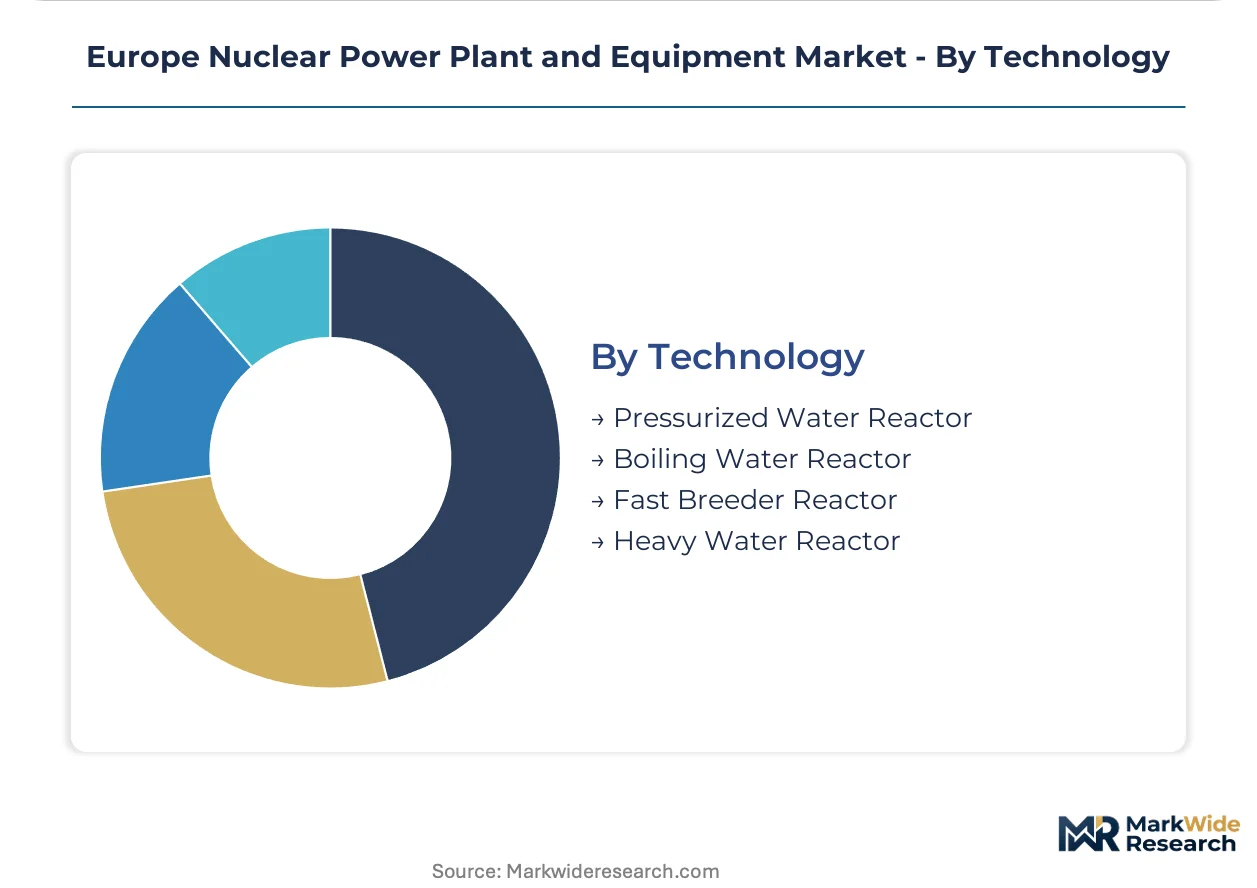
- Pressurized Water Reactor:EPR and AP1000 designs dominate European new-build pipelines with standardized component specifications enabling multi-site procurement economies. EDF's Flamanville and UK Hinkley Point C projects anchor demand for Generation III+ pressure vessels and steam generators.
- Fast Breeder Reactor:Sodium-cooled designs occupy research funding through France's Astrid program and Russian BN-series technology. Commercial deployment remains structurally immature with limited qualified component supply chains outside specialized research consortia.
- Boiling Water Reactor:Mark I and Mark II containment designs persist in limited European installations.
- Heavy Water Reactor:CANDU technology retains niche presence in Romania.
Pressurized Water Reactor anchors the installed base while Fast Breeder Reactor attracts disproportionate R&D investment relative to commercial scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified forging capacity for reactor pressure vessels concentrates in Japan and South Korea, forcing European utilities to source critical components through extended international supply chains despite the EU Green Deal taxonomy redirecting capital toward domestic nuclear investments.
France
EDF operates the continent's largest operational fleet and new-build pipeline, generating concentrated demand for steam generator replacements and Generation III+ reactor components. ASN safety protocols govern equipment certification timelines for Flamanville and future EPR projects. The Le Creusot forge cluster anchors domestic heavy component manufacturing despite capacity constraints.
United Kingdom
Hinkley Point C and Sizewell C projects drive procurement for NSSS equipment and long-term fuel supply contracts. ONR regulatory mandates overlap with post-Fukushima upgrade requirements for existing AGR stations. The Cumbrian nuclear supply chain cluster sustains specialized fabrication and engineering services for new-build programs.
Poland
The country's first nuclear program creates virgin-market positioning for vendors establishing regulatory relationships with PAA. State-backed procurement frameworks differ from established Western European protocols, demanding dedicated compliance investment. The Pomeranian region hosts early site preparation for planned reactor locations.
Czech Republic
ČEZ utility advances SMR demonstration projects alongside Temelín and Dukovany expansion plans. National regulator SÚJB shapes equipment qualification requirements for both large-scale and modular reactor technologies. The South Bohemian region concentrates existing nuclear infrastructure and skilled workforce pools.
Finland
Olkiluoto EPR completion and planned additional units sustain demand for safety-class instrumentation and turbine generator systems. STUK regulatory mandates enforce post-Fukushima compliance deadlines for beyond-design-basis event mitigation hardware. The Eurajoki municipality anchors Nordic nuclear equipment servicing capabilities.
Europe Nuclear Power Plant and Equipment Market Competitive Landscape
Vertically integrated reactor vendors and specialized component fabricators split the market along technology-licensing versus equipment-supply lines. The supply base exhibits tiered concentration, with a handful of forge-capable suppliers controlling pressure vessel manufacturing while digital instrumentation markets fragment across cybersecurity-hardened specialists. Three archetypes dominate: state-backed national champions, independent technology licensors, and captive utility supply arms. Competitive moves center on long-term service agreement capture and SMR qualification partnerships.
Among technology-licensing specialists, Westinghouse Electric Company and GE Vernova occupy positions anchored to Generation III+ reactor designs and turbine generator systems respectively. Framatome exemplifies the vertically integrated national champion archetype, with its corporate structure reflecting French state-backed consolidation of fuel cycle and component manufacturing capabilities. These three entities represent the dominant competitive anchors around which European procurement frameworks organize.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Westinghouse Electric Company |
| Framatome |
| GE Vernova |
| BWX Technologies |
| EDF |
| Doosan Corporation |
| Alstom |
| Rosatom State Atomic Energy Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on Japanese and South Korean forging capacity for reactor pressure vessels determines both the premium commanded by safety-class components and the elongated supply chain architecture European utilities must navigate. The EU Green Deal taxonomy's capital redirection intensifies this structural tension as domestic procurement preferences collide with geographically concentrated manufacturing.
Pricing Analysis
REACH compliance dictates the pricing tier structure across European nuclear equipment markets, with specialized nickel alloys and cobalt-based materials facing extended toxicity testing timelines that compress margins for non-certified suppliers. Three-tier pricing structure across premium certified, standard compliant, and economy non-safety levels separates Framatome and Westinghouse offerings from regional fabricators. Cost compression in the standard tier is intensifying because utilities are consolidating procurement through decade-long framework agreements. State-backed utilities in France and the United Kingdom exhibit the lowest price sensitivity, while emerging nuclear programs in Poland and the Czech Republic drive hardest on total cost of ownership.
Supply Chain Analysis
Japan Steel Works and Doosan Heavy Industries hold dominant forging capacity for reactor pressure vessels, with Le Creusot in France representing the sole European-qualified alternative. Geographic supply concentration centers on Japan, South Korea, and limited French domestic capacity for heavy components. Raw material dependencies rest on low-alloy steel forgings, specialized zirconium alloys for fuel cladding, and cobalt-chromium materials for control rod mechanisms. Single-source vulnerability pervades the pressure vessel supply base, where qualified forging capacity outside Asia remains structurally constrained. Distribution runs through utility-led framework agreements that bundle component orders across multiple reactor sites, displacing traditional site-specific tendering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe nuclear power plant and equipment market sits at an early-cycle expansion story, with the EU Green Deal taxonomy unlocking institutional capital for reactor new-builds and SMR demonstration projects accelerating component qualification timelines.
For Market Incumbents: Insulate forging relationships through long-term capacity reservations with Japan Steel Works and Doosan Heavy Industries before emerging nuclear programs in Poland and the Czech Republic absorb available slots. Deepen backward integration into specialized alloy supply by qualifying alternative European forge sources under ASN protocols. Lock in decade-long service agreements for turbine generator maintenance as utilities unbundle aftermarket from original equipment supply. For New Entrants and Emerging Players: Establish a beachhead in digital instrumentation for safety-class applications, where cybersecurity-hardened control rod drive mechanisms face upgrade mandates from ASN and ONR. Target the Czech SMR demonstration pipeline through partnerships with ČEZ utility and SÚJB regulator pre-qualification. Lead with wireless sensor network integration as the go-to-market angle, compressing installation timelines against legacy hardwired systems. For Investors and Strategic Acquirers: The market sits at a capital-deployment phase that favors component fabricators with existing ASN or ONR certification rather than greenfield technology developers. Long-term viability over the next decade hinges on positioning within SMR supply chains before commercial scale crystallizes. Acquisition target archetype: mid-cap specialists with qualified welding capacity and ASME Section IX certification. The signal to watch is final investment decisions for Polish and Czech reactor projects as inflection indicator for component demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| SMR Qualification Partnership | Early positioning with ČEZ and Polish nuclear agency PAA captures virgin-market procurement frameworks before specifications harden. |
| Long-term Forging Agreement | Capacity reservations with Japan Steel Works secure delivery slots for EDF's fleet replacement program ahead of competing buyers. |
| Digital Instrumentation Certification | ASN and ONR cyber-hardened approvals for wireless sensor networks open upgrade pathways across post-Fukushima compliance deadlines. |
| Backward Integration into Alloys | In-house production of REACH-compliant specialized materials reduces certification delays and filters competitor eligibility. |
| Framework Agreement Capture | Ten-year bundled contracts with EDF's centralized purchasing displace site-by-site tendering and lock out independent suppliers. |
Research Methodology
A standing panel of utility procurement officers, ASN regulatory inspectors, EPC project managers, and forging facility operations directors provided ongoing calibration across primary interview cycles. Secondary validation drew from IEA nuclear development databases, EIA reactor construction tracking, EU Green Deal taxonomy implementation reports, and national regulatory filings with ASN, ONR, and SÚJB. Bottom-up equipment demand modeling triangulated against top-down capital expenditure projections from utility investor disclosures.
Scenario-bracketing framed the analytical approach across the projection horizon, with high-case assumptions incorporating accelerated SMR deployment in Poland and the Czech Republic and low-case assumptions reflecting prolonged EPR construction overruns. Segmentation dimensions modeled include reactor technology type, component safety classification, procurement authority concentration, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and new-build pipeline tracking. Industry-specific forecast inputs incorporated forging capacity utilization rates and welder training program throughput constraints.
Macroeconomic conditions sit as an overlay; deviation in European electricity demand growth, carbon credit pricing, or institutional capital allocation to sustainable finance would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines, forging delivery schedules, and SMR commercialization pace. Quarterly review of EDF final investment decisions, Polish PAA qualification protocols, and Japanese forging capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Global Power Plant Uranium Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
United Kingdom Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Japan Nuclear Power Reactor Decommissioning Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market