
 South America Nuclear Reactor Construction Market | 2026-2036
South America Nuclear Reactor Construction Market Size, Share, and Industry Trends Forecast 2026-2036
South America Nuclear Reactor Construction Market Analytics
Steel-reinforced concrete containment is broadening project economics across the South America Nuclear Reactor Construction Market as composite alternatives face supply bottlenecks. Rosatom State Atomic Energy Corporation leverages its integrated engineering-procurement-construction model to anchor large-scale pressurized water reactor bids in the region. Eletronuclear sustains domestic content requirements through Brazilian supply chain partnerships. Nucleoeléctrica Argentina S.A. specializes in heavy water reactor refurbishment and Atucha site continuity.
South America nuclear reactor construction encompasses the civil works, mechanical installation, and systems integration required to build fission-based electricity generation facilities, typically involving containment structures rated for seismic loads and primary coolant circuits operating at pressures exceeding 15 MPa. Pressurized water reactor and small modular reactor segments command the dominant share of committed capital, while generation III+ technology attracts the fastest-growing engineering procurement flow as vendors seek design certification from national regulators. Utility companies represent the most concentrated end-user pool, though government agencies control licensing timelines and tariff structures that determine project viability.
Brazil's Comissão Nacional de Energia Nuclear and Argentina's Autoridad Regulatoria Nuclear enforce divergent containment standards and operator qualification rules that fragment vendor certification paths across the subcontinent. International Atomic Energy Agency safeguards protocols and ISO 19443 nuclear quality requirements add compliance layers that extend pre-construction timelines. Stakeholders must monitor which regulatory harmonization pathway—Mercosur energy integration or bilateral national agreements—governs cross-border component sourcing and specialist labor mobility.
Market Dynamics
Small modular reactor deployment is compressing project timelines and redirecting capital toward factory-fabricated units rather than site-built gigawatt-scale plants, forcing established engineering-procurement-construction consortia to restructure bid teams and supply chain partnerships.
Growth Catalysts
- Grid reliability mandates:Brazil's national energy regulator has tightened baseload capacity requirements, compelling utilities to commit long-term power purchase agreements to nuclear projects that stabilize transmission networks against intermittent renewable output.
- Pressurized water reactor technology:Generation III+ designs with passive safety systems are attracting engineering procurement flows as vendors pursue design certification from national regulators, reducing licensing risk for utility buyers.
- Argentine nuclear zones:Clustering near Lima and coastal Brazilian regions is concentrating specialist labor pools and component fabrication infrastructure, creating procurement efficiencies for sequential project builds.
Market Restraints
- Steel-reinforced concrete supply:Composite containment alternatives face supply bottlenecks, locking projects into conventional materials with volatile rebar pricing and extended curing schedules that extend critical path timelines.
- Divergent containment standards:Brazil's Comissão Nacional de Energia Nuclear and Argentina's Autoridad Regulatoria Nuclear enforce non-harmonized operator qualification rules, fragmenting vendor certification paths and duplicating compliance costs.
- Extended pre-construction timelines:International Atomic Energy Agency safeguards protocols layered with ISO 19443 nuclear quality requirements add compliance stages that delay first concrete pours.
Strategic Opportunities
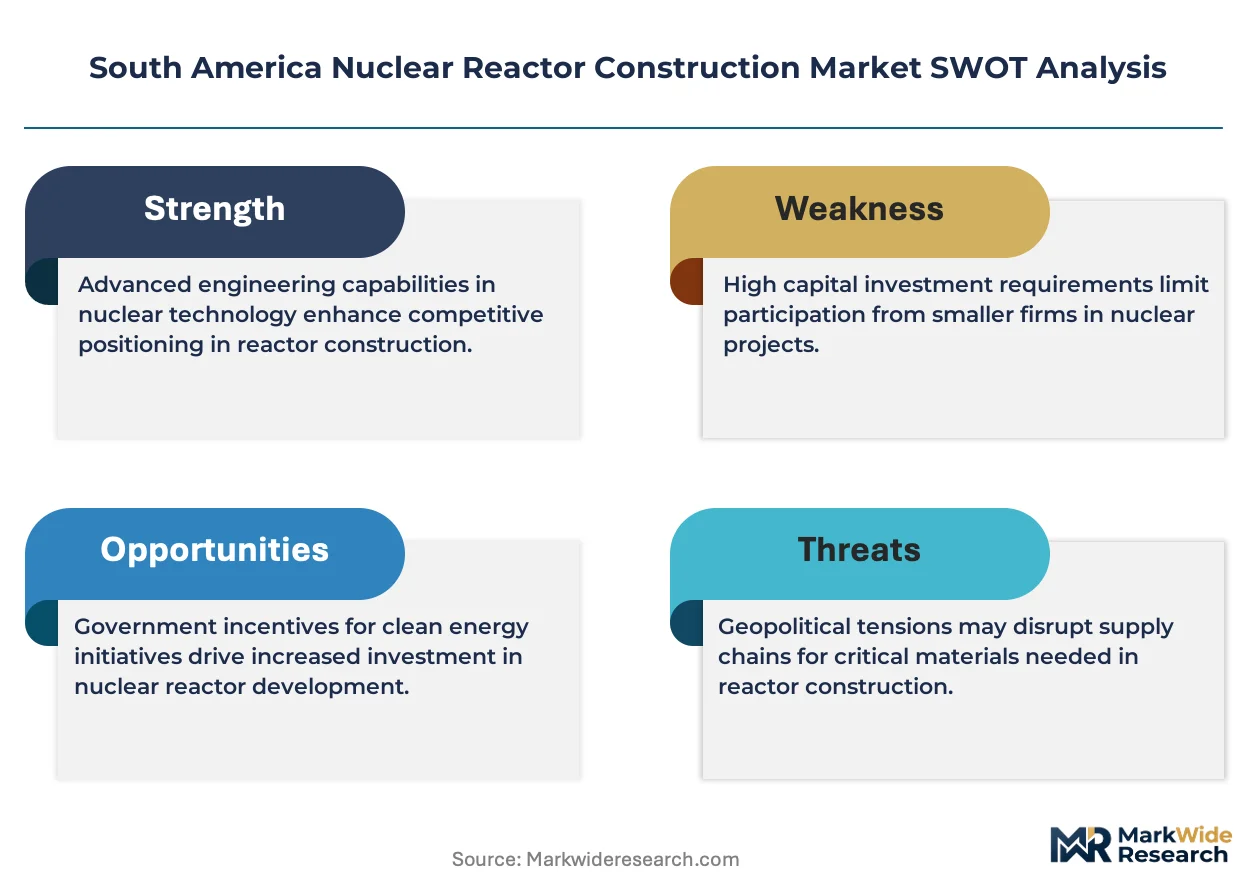
- Heavy water reactor refurbishment:Atucha site continuity programs in Argentina create captive demand for specialized civil works contractors familiar with CANDU architecture and pressure tube replacement protocols.
- Mercosur energy integration:Cross-border component sourcing frameworks could unlock specialist labor mobility between Brazilian and Argentine project sites, reducing per-project staffing costs.
- Seismic-rated containment structures:Engineering firms with proven seismic load certification are expanding into Chilean and Peruvian markets where regulatory frameworks are crystallizing around nuclear new-build scenarios.
Industry Challenges
- Welder certification scarcity:Nuclear-qualified pressure vessel welders require multi-year apprenticeship pipelines that regional technical institutes have not scaled to match committed project backlogs.
- Primary coolant circuit integration:Systems contractors face execution risk when mating reactor pressure vessels to steam generator modules fabricated under different national quality assurance regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Nuclear Reactor Construction Market |
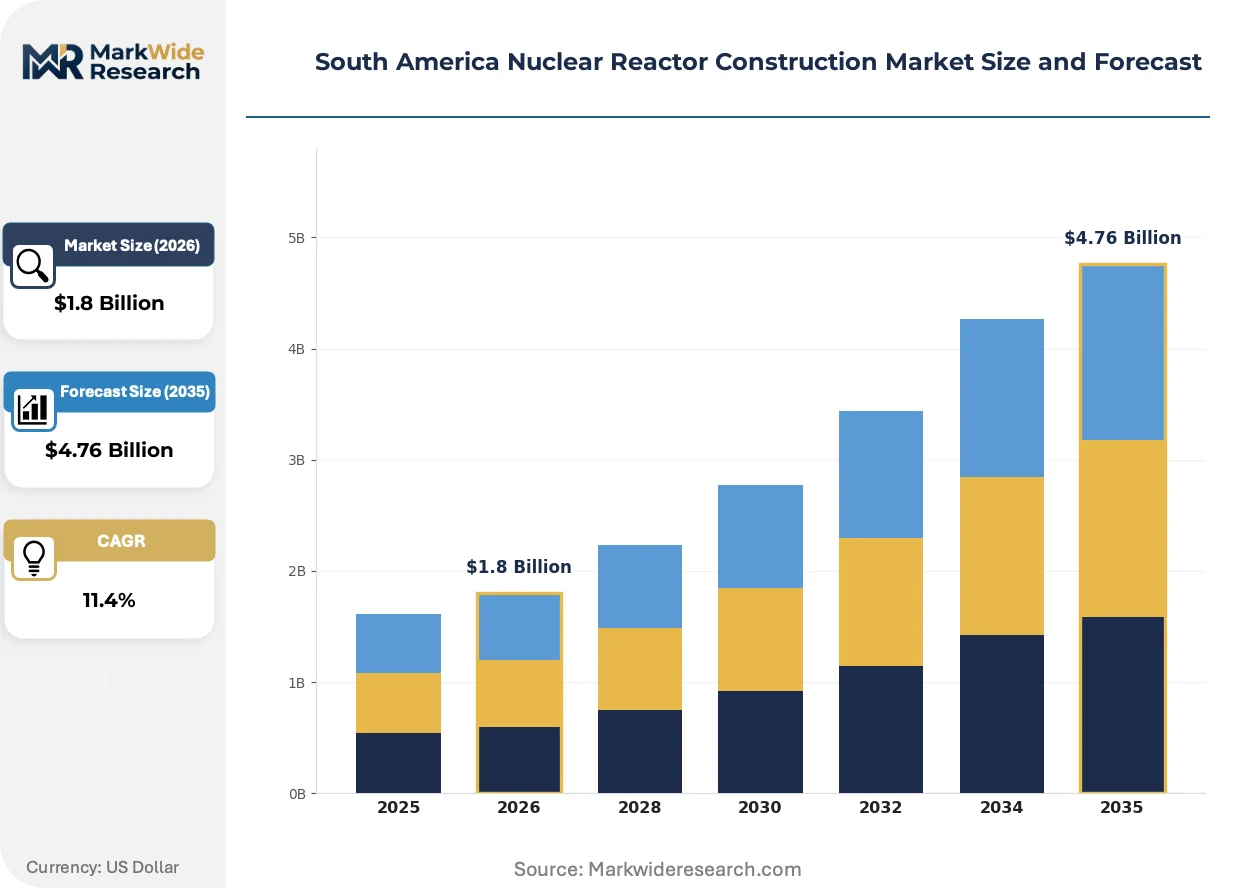
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Pressurized Water Reactor, Boiling Water Reactor, Fast Breeder Reactor, Advanced Gas-Cooled Reactor End User: Utility Companies, Government Agencies, Private Sector Investors, Research Institutions Technology: Generation III, Generation III+, Generation IV, Small Modular Reactors Installation Type: Onshore, Offshore, Greenfield, Brownfield |
| Companies Covered | China National Nuclear Corporation, SNC-Lavalin Inc, Rosatom State Atomic Energy Corporation, Eletronuclear, Argentine National Atomic Energy Commission, Centrais Elétricas Brasileiras SA, Westinghouse Electric Company LLC, Dongfang Electric Corporation Limited, Nucleoeléctrica Argentina S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Nuclear Reactor Construction Market Evolving Landscape
Factory fabrication methods are displacing field construction for reactor pressure vessels and steam generator components, compressing site schedules while demanding new logistics capabilities for oversized module transport.
Small modular reactor designs are expanding into utility procurement portfolios as standardized 300 MWe units enable phased capital deployment and reduced financing risk compared to single large-scale commitments. Brazilian coastal utilities are evaluating these configurations for baseload replacement of aging fossil units. The technology is expanding into previously uneconomic grid locations where transmission infrastructure cannot support gigawatt-scale injection.
Argentina's Autoridad Regulatoria Nuclear is harmonizing operator qualification frameworks with International Atomic Energy Agency standards, reducing certification duplication for multinational engineering teams. This alignment accelerates specialist labor deployment across sequential projects. Heavy water reactor segments face the steepest compliance adjustment as legacy training protocols require restructuring.
Utility procurement committees are consolidating vendor lists to pre-qualified engineering-procurement-construction consortia with demonstrated completion records, displacing open competitive tendering for nuclear island contracts. This concentration shifts negotiation leverage toward integrated bidders with captive fabrication capacity. Argentine and Brazilian state-owned utilities are driving this pattern most aggressively.
South America Nuclear Reactor Construction Market Segmentation
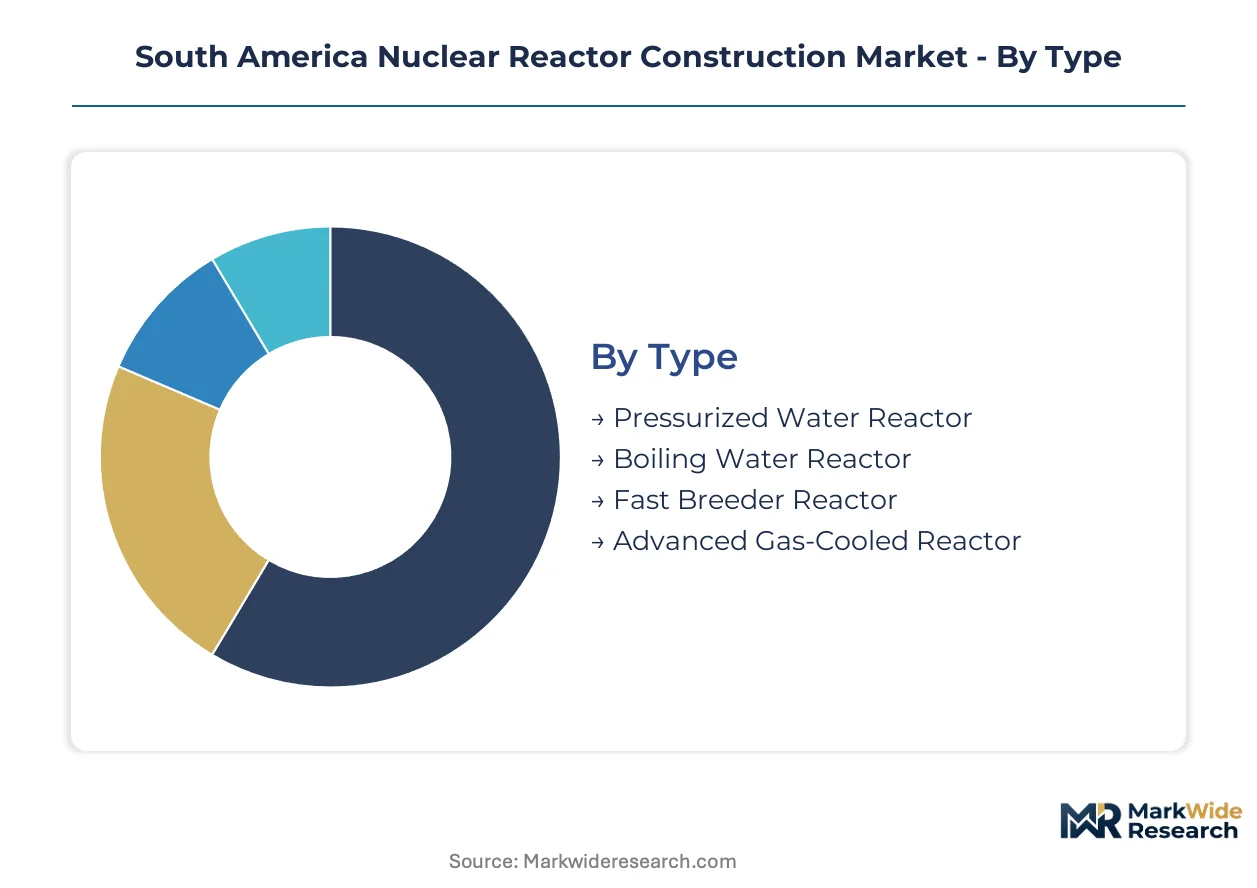
Reactor type determines capital intensity and construction duration across South American projects. End-user concentration shapes financing structures and regulatory engagement models. Technology tier selection drives licensing pathways and supply chain qualification requirements.
Type:
Pressurized water reactor configurations dominate committed megawatt capacity while fast breeder designs concentrate experimental procurement flows.
- Pressurized Water Reactor:Primary coolant circuits operate at pressures exceeding 15 MPa with steel-reinforced concrete containment rated for seismic loads. Brazilian coastal utilities anchor demand as Eletronuclear pursues Angra site expansion under Comissão Nacional de Energia Nuclear oversight.
- Small Modular Reactor:Factory-fabricated 300 MWe units compress project timelines and enable phased capital deployment. Argentine nuclear zones near Lima cluster procurement attention as Nucleoeléctrica Argentina evaluates baseload replacement configurations.
- Boiling Water Reactor:Direct-cycle steam generation reduces component count but demands larger containment volumes for radioactive steam handling.
- Fast Breeder Reactor:Sodium-cooled designs with plutonium breeding blankets attract research institution procurement for closed-fuel-cycle demonstration.
- Advanced Gas-Cooled Reactor:Graphite-moderated helium-cooled configurations remain absent from committed South American project pipelines.
Mature deployment sits with pressurized water reactor construction. Newer deployment is concentrated in small modular reactor evaluation phases.
End User:
State-backed procurement concentrates construction risk while private capital seeks standardized technology platforms.
- Utility Companies:State-owned Eletronuclear and Nucleoeléctrica Argentina commit long-term power purchase agreements to stabilize transmission networks. Brazilian baseload mandates from national energy regulators compel nuclear capacity additions against intermittent renewable output.
- Government Agencies:Direct ownership structures control licensing timelines and tariff frameworks that determine project viability. Argentina's Autoridad Regulatoria Nuclear and Brazil's Comissão Nacional de Energia Nuclear enforce divergent containment standards that fragment vendor certification.
- Private Sector Investors:Independent power producers evaluate small modular reactor deployments where reduced capital exposure matches risk-return thresholds.
- Research Institutions:Experimental reactor construction supports workforce development and fuel cycle research programs.
Construction commitment clusters with utility companies. Government agencies concentrate regulatory gatekeeping functions.
Technology:
Generation III+ designs attract engineering procurement flows as vendors pursue design certification from national regulators.
- Generation III+:Passive safety systems and seismic-rated containment reduce licensing risk for utility buyers. Brazilian coastal clusters concentrate procurement evaluation as Eletronuclear assesses Angra unit replacement options.
- Small Modular Reactors:Standardized factory fabrication enables supply chain replication across sequential Argentine and Brazilian projects. Argentine nuclear zones cluster specialist labor pools for module installation sequences.
- Generation III:Active safety system designs with extensive operating experience anchor refurbishment procurement for existing Atucha and Angra units.
- Generation IV:Supercritical water and molten salt configurations remain pre-commercial with no committed South American construction contracts.
Generation III+ technology commands the steepest expansion trajectory among new-build categories. Generation III concentrates refurbishment and life-extension procurement.
Installation Type:
Site conditions determine civil works scope and seismic foundation requirements across the subcontinent.
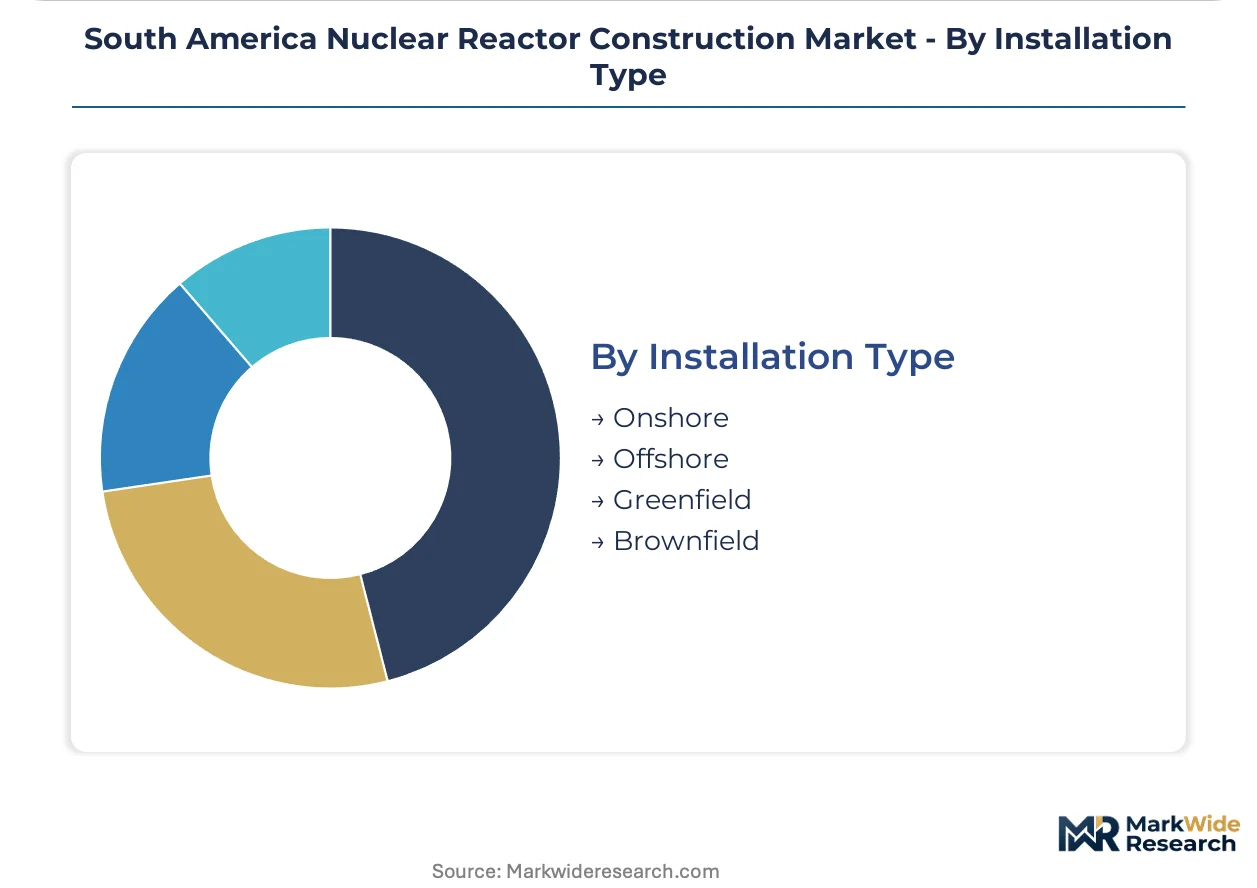
- Greenfield:New site development demands comprehensive environmental licensing and greenfield infrastructure construction. Brazilian coastal locations concentrate evaluation as transmission capacity constraints limit inland siting options.
- Brownfield:Existing nuclear site expansion leverages licensed land buffers and operational infrastructure. Argentina's Atucha complex anchors sequential heavy water reactor refurbishment with captive civil works contractor relationships.
- Onshore:Conventional land-based construction dominates committed project pipelines with established regulatory frameworks.
- Offshore:Floating nuclear power plant configurations remain absent from South American procurement evaluation.
Greenfield development concentrates new capacity evaluation. Brownfield installation anchors life-extension and sequential unit construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement concentrates construction commitment across Brazil and Argentina, with Chile and Peru emerging as evaluation markets for seismic-rated containment technology. National regulators enforce divergent certification standards that shape vendor entry strategies.
Brazil
Eletronuclear drives baseload expansion at the Angra complex under Comissão Nacional de Energia Nuclear oversight. The national energy regulator's tightened grid reliability mandates compel long-term power purchase agreements to nuclear capacity. Coastal clusters near Rio de Janeiro concentrate specialist labor pools for sequential pressurized water reactor construction.
Argentina
Nucleoeléctrica Argentina sustains heavy water reactor refurbishment demand at the Atucha site. Autoridad Regulatoria Nuclear harmonizes operator qualification frameworks with International Atomic Energy Agency standards, reducing certification duplication. Nuclear zones near Lima cluster procurement attention for small modular reactor evaluation.
Chile
Engineering firms with proven seismic load certification are expanding into Chilean markets where regulatory frameworks crystallize around nuclear new-build scenarios. The country's national energy commission evaluates containment standards for high-seismic zones. Santiago-based technical institutes are developing welder apprenticeship pipelines to address regional capability gaps.
Peru
Argentine nuclear zones near the Peruvian border concentrate specialist labor mobility discussions under potential Mercosur energy integration frameworks. The country's national electricity regulator assesses baseload replacement options for aging fossil infrastructure. Coastal grid constraints drive evaluation of small modular reactor configurations for transmission-limited locations.
South America Nuclear Reactor Construction Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated engineering-procurement-construction consortia commanding nuclear island contracts while component fabricators compete for standardized modules. State-owned utilities anchor procurement concentration in Brazil and Argentina, fragmenting vendor access for private capital. Three archetypes dominate: Rosatom-style integrated vendors with captive fabrication capacity, Eletronuclear-type domestic champions leveraging local content requirements, and Westinghouse-class technology licensors pursuing design certification. Competitive moves center on strategic partnerships for supply chain qualification and technology licensing for regulatory pathway acceleration.
Among state-backed energy conglomerates, Eletronuclear and Centrais Elétricas Brasileiras SA exemplify the domestic champion archetype, leveraging Brazilian supply chain partnerships to sustain local content mandates. Rosatom State Atomic Energy Corporation anchors the integrated vendor tier with its engineering-procurement-construction model for large-scale pressurized water reactor bids. Nucleoeléctrica Argentina S.A. occupies a parallel position in Argentina, specializing in heavy water reactor continuity and Atucha site refurbishment protocols.
| Leading Market Players |
|---|
| China National Nuclear Corporation |
| SNC-Lavalin Inc |
| Rosatom State Atomic Energy Corporation |
| Eletronuclear |
| Argentine National Atomic Energy Commission |
| Centrais Elétricas Brasileiras SA |
| Westinghouse Electric Company LLC |
| Dongfang Electric Corporation Limited |
| Nucleoeléctrica Argentina S.A. |
| Others |
Value Network & Pricing Analysis
Factory fabrication of reactor pressure vessels and steam generator modules is compressing site construction schedules while concentrating procurement leverage among integrated engineering-procurement-construction consortia with captive fabrication capacity. This production-method transition simultaneously reduces field labor cost exposure and locks buyers into long-term component supply agreements with Rosatom-style integrated vendors or Eletronuclear-backed domestic champions.
Pricing Analysis
High-volume pressurized water reactor contracts trade margin for market position while small modular reactor deployments command premium pricing for factory-fabricated certainty. Price differentiation rests on certification grade under ISO 19443 nuclear quality requirements and seismic-rated containment design complexity. Cost compression in conventional steel-reinforced concrete containment is intensifying because composite alternative supply bottlenecks eliminate substitution pressure. Private sector independent power producers exhibit highest price sensitivity, whereas state-owned utilities prioritize regulatory pathway certainty over unit cost optimization.
Supply Chain Analysis
Direct-to-utility channels handle sovereign buyer demand while tiered subcontracting feeds component fabrication through Brazilian and Argentine nuclear zones. Geographic supply concentration centers on Russia for integrated reactor island packages, China for forgings and pressure vessel steel, and domestic Brazilian-Argentine partnerships for civil works and local content compliance. Raw material dependencies draw from specialized nuclear-grade steel plate, zirconium alloy tubing, and seismic-rated concrete admixtures. Single-source vulnerability runs through Rosatom's engineering-procurement-construction dominance for large-scale pressurized water reactor bids. Distribution runs through state utility procurement committees with consolidated vendor pre-qualification lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through nuclear-qualified welder scarcity, with apprenticeship pipeline gaps propping pricing power for certified installation contractors across Brazilian coastal clusters and Argentine nuclear zones.
For Market Incumbents: Hedge certification duplication risk by securing dual recognition under Brazil's Comissão Nacional de Energia Nuclear and Argentina's Autoridad Regulatoria Nuclear operator qualification frameworks. Anchor supply chain partnerships with Brazilian steel fabricators to defend local content mandates against Rosatom integrated bids. Capacity addition in Argentine heavy water reactor refurbishment segments captures Atucha site continuity demand.
For New Entrants and Emerging Players: Chilean utility procurement committees represent the most penetrable buyer archetype as seismic-rated containment standards crystallize without incumbent vendor lock-in. Target Peruvian coastal grid locations where transmission constraints favor small modular reactor scale. Pursue technology licensing partnerships with Westinghouse-class design certifiers to accelerate regulatory pathway access.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by state-backed energy conglomerates seeking vertical integration into nuclear island fabrication. Long-term viability favors engineering-procurement-construction consortia with demonstrated completion records under IAEA safeguards protocols. Monitor Mercosur energy integration treaty ratification as inflection indicator for cross-border labor mobility and component sourcing harmonization.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Pressure Vessel Fabrication Partnership | Captive forging capacity under Rosatom or Eletronuclear control secures nuclear island bid eligibility. |
| Small Modular Reactor Design Certification | Autoridad Regulatoria Nuclear approval unlocks Argentine nuclear zone procurement evaluation. |
| Nuclear-Qualified Welder Apprenticeship Pipeline | Santiago and Rio de Janeiro technical institute partnerships address regional capability scarcity. |
| Seismic Containment Structure Certification | Proven seismic load credentials enable Chilean and Peruvian market entry before regulatory frameworks mature. |
| Heavy Water Refurbishment Specialist Acquisition | CANDU architecture expertise captures Atucha site continuity and pressure tube replacement protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs across the South America Nuclear Reactor Construction Market analysis. Primary interviews with utility planning officers, EPC contractors, nuclear regulatory affairs leads, and grid operators combined with International Atomic Energy Agency safeguard reports, national regulator licensing databases, and Comissão Nacional de Energia Nuclear filing records. Bottom-up project pipeline aggregation and top-down energy demand forecasting enabled cross-validation.
Data-stream reconciliation across committed capital announcements, engineering procurement flows, and national energy regulator mandates shaped the analytical framework across reactor type, end user, technology tier, and installation type dimensions. CAGRs were derived from capacity-weighted project timelines and regulatory pathway acceleration assumptions. Nuclear-qualified labor availability curves and steel-reinforced concrete supply elasticity informed construction duration modeling.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Mercosur energy integration treaty progress and small modular reactor design certification timelines. Forecasts reflect documented assumptions regarding regulatory harmonization pathways and apprentice pipeline scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Thorium Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Small Modular Reactor (SMR) Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Nuclear Fuels Market