
 Nuclear Battery Sales Market | 2026-2036
Nuclear Battery Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Battery Sales Market Insights
Defense procurement offices are unwinding legacy chemical battery contracts in favor of multi-decade nuclear power sources for unattended sensors and strategic platforms. Zeno Power leverages its radioisotope sourcing agreements to dominate government satellite power contracts. City Labs Inc. specializes in tritium-based microbatteries for implantable medical devices, sustaining niche leadership through FDA-compliant manufacturing protocols. BetaBatt Inc. competes on semiconductor junction architecture, positioning its betavoltaic designs for extreme-environment industrial telemetry.
Nuclear batteries convert radioactive decay energy into electrical power through semiconductor junctions or thermoelectric materials, typically achieving operational lifespans of 10-50 years without refueling depending on isotope half-life and conversion efficiency. Their primary purpose is delivering continuous microwatt-to-watt scale power where battery replacement is impossible or prohibitively expensive. Betavoltaic batteries lead product type revenue due to tritium availability and established medical device certification pathways, while thermophotovoltaic batteries represent the fastest-growing category as plutonium-238 availability expands for deep-space missions. Radioisotope batteries anchor the mature defense segment, though margin pools are migrating toward medical implants where regulatory barriers protect pricing.
The US FDA governs radiological device safety through 21 CFR standards, while the NRC controls isotope possession and distribution licensing, jointly determining market access timelines for new entrants. ISO 2919 specifies sealed source performance criteria that manufacturers must satisfy for international medical and aerospace shipments. EMA's evolving stance on implantable radiological power sources in Europe is reshaping clinical trial requirements for cardiac and neural applications. Stakeholders must monitor isotope supply chain concentration and regulatory divergence between FDA and EMA pathways when allocating R&D budgets across geographies.
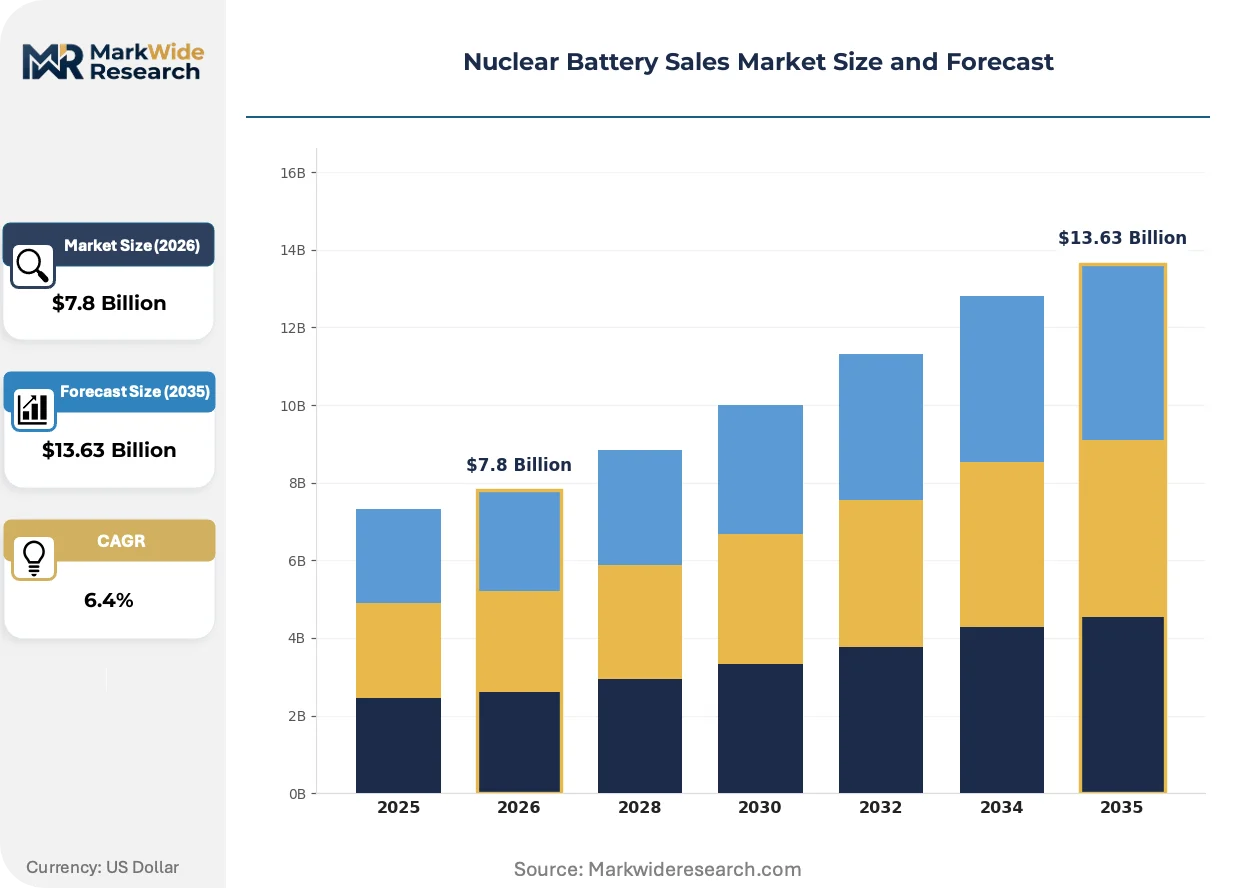
Market Dynamics
Plutonium-238 supply scarcity is compressing thermophotovoltaic battery deployment timelines, forcing defense and aerospace buyers into multi-year forward commitments that reshape vendor-customer contracting structures.
Growth Catalysts
- 21 CFR device classification updates:The US FDA's streamlined premarket pathways for radiological power sources accelerate cardiac implant commercialization timelines.
- Betavoltaic semiconductor junctions:Advances in wide-bandgap materials improve conversion efficiency for neural stimulation devices requiring decade-long operational lifespans.
- NASA deep-space procurement:Multi-mission power contracts for outer-planet probes sustain demand for radioisotope thermoelectric generators.
Market Restraints
- Plutonium-238 supply concentration:US Department of Energy reactor production limits create multi-year order backlogs for deep-space missions.
- Tritium gas handling complexity:Specialized containment infrastructure requirements inflate manufacturing facility capex thresholds.
- Long-life chemical battery substitution:Solid-state lithium-metal cells capture unattended sensor applications below 20-year lifespan requirements.
Strategic Opportunities
- EMA implantable device pathway evolution:Emerging European clinical trial frameworks for radiological cardiac power sources open continental market access.
- Industrial subsea telemetry:Oilfield equipment manufacturers evaluate betavoltaic units for seabed monitoring systems beyond battery replacement reach.
- Direct isotope sourcing agreements:End-users contracting with national laboratories bypass distributor markups and secure supply chain priority.
Industry Challenges
- ISO 2919 sealed source certification timelines:International shipment compliance testing extends product launch schedules by 18-24 months.
- Multiphysics simulation talent scarcity:Coupled radiation transport and semiconductor modeling expertise concentrates in national laboratory alumni pools.
- Legacy sensor integration complexity:Retrofitting existing defense platforms with nuclear power sources requires mechanical and electrical interface redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Battery Sales Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radioisotope Batteries, Thermophotovoltaic Batteries, Betavoltaic Batteries, Photovoltaic Cells End User: Aerospace, Defense, Medical Devices, Remote Sensing Application: Satellite Power Systems, Medical Implants, Undersea Sensors, Emergency Backup Technology: Radioactive Decay, Thermoelectric Effect, Beta Decay, Quantum Dot |
| Companies Covered | Korea Atomic Energy Research Institute, BetaBatt Inc., NDB Inc., Nusano Inc., Widetronix Inc., Zeno Power, City Labs Inc., Qynergy Corporation, Infinity Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Battery Sales Market Trends and Innovations
Material science breakthroughs in semiconductor junction architectures and regulatory pathway rationalization are compressing product development cycles while expanding addressable applications beyond traditional defense and space verticals.
Gallium nitride betavoltaic conversion layers are miniaturizing device footprints for implantable neural stimulators. Medtronic and Boston Scientific procurement teams evaluate sub-millimeter form factors for next-generation deep-brain stimulation systems. The technology is miniaturizing previously volume-constrained applications into subcutaneous deployment envelopes.
REACH authorization requirements for sealed radioactive sources in Europe impose substance restriction compliance costs on medical device exporters. Manufacturers must document containment integrity across product lifecycles under evolving ECHA guidance. Cardiac implant specialists delay EU market entry pending clarity on Article 58 authorization scopes.
Defense procurement offices consolidate multi-decade power source contracts under single-vendor arrangements with radioisotope supply guarantees. Traditional battery distributors lose position to direct prime-contractor relationships. The United States Navy's unmanned underwater vehicle program exemplifies this concentration, with Lockheed Martin and General Dynamics awarding sole-source thermoelectric generator agreements spanning 25-year operational horizons.
Nuclear Battery Sales Market Segmentation
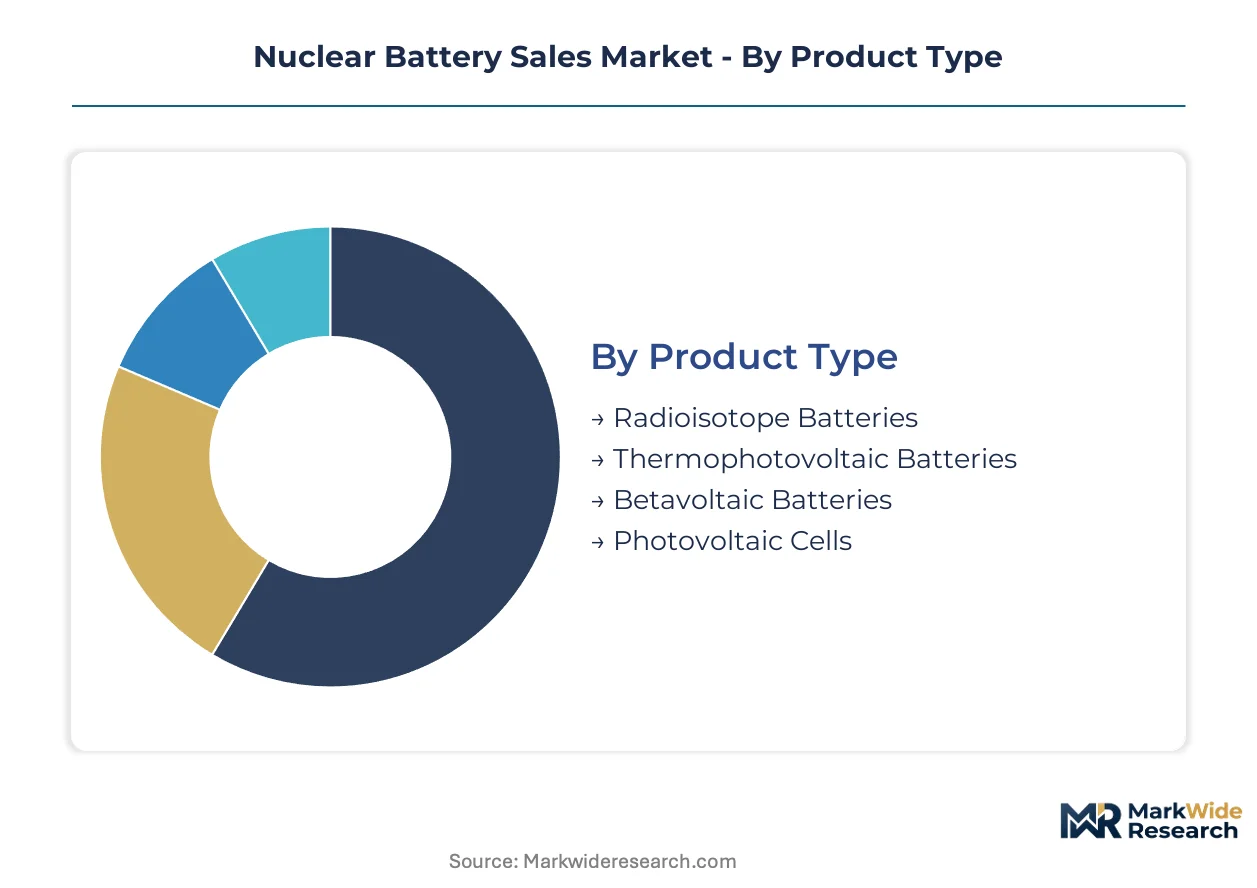
Nuclear battery segmentation reflects divergent isotope supply chains and regulatory pathways that shape commercialization timelines. Each category isolates distinct buyer behaviors, from NASA's multi-decade procurement cycles to cardiac implant manufacturers seeking FDA-compliant tritium sourcing.
Product Type:
Betavoltaic and thermophotovoltaic units dominate domestic US manufacturing, while radioisotope batteries flow through export-controlled channels tied to national laboratory production.
- Betavoltaic Batteries:Semiconductor junctions convert beta particle emissions from tritium or nickel-63 into continuous electrical output. Medical implant manufacturers in the United States concentrate procurement here, drawn by tritium availability and established FDA 21 CFR certification pathways for cardiac and neural devices.
- Thermophotovoltaic Batteries:Plutonium-238 decay heat drives infrared photon emission through specialized emitter surfaces, with photovoltaic cells harvesting converted energy. NASA and Department of Defense buyers anchor demand through multi-year forward commitments, though DOE reactor production limits create order backlogs extending deployment timelines.
- Radioisotope Batteries:Direct energy conversion from alpha or beta emitters serves legacy defense platforms requiring decade-plus unattended operation.
- Photovoltaic Cells:Specialized infrared-tuned junctions pair with radioisotope heat sources in hybrid thermophotovoltaic architectures.
Betavoltaic batteries hold the largest share; momentum sits with thermophotovoltaic designs as plutonium-238 availability expands.
End User:
Defense and aerospace procurement operates on classified contracting timelines, while medical device commercialization follows transparent FDA premarket submission tracks.
- Medical Devices:Cardiac pacemaker and deep-brain stimulation manufacturers drive betavoltaic volume through decade-long device lifespans. Boston Scientific and Medtronic procurement teams specify tritium-based microbatteries for next-generation neural implants, with FDA device classification updates compressing regulatory review periods.
- Defense:Unattended ground sensors and strategic platforms require multi-decade power without maintenance access. The United States Navy's unmanned underwater vehicle program consolidates contracts under sole-source thermoelectric generator agreements spanning twenty-five-year operational horizons.
- Aerospace:Deep-space missions beyond solar range depend on radioisotope thermoelectric generators for continuous watt-scale output.
- Remote Sensing:Arctic and desert environmental monitors evaluate nuclear batteries where chemical cell replacement proves logistically prohibitive.
Defense commands the dominant procurement volume; medical devices are climbing the fastest as cardiac implant pipelines mature.
Application:
Medical and undersea applications demand hermetic sealing certification under ISO 2919, while satellite systems prioritize mass optimization over volume constraints.
- Medical Implants:Sub-millimeter form factors for deep-brain stimulation require gallium nitride betavoltaic conversion layers. Manufacturers target subcutaneous deployment envelopes previously inaccessible to bulkier power sources, with FDA-compliant manufacturing protocols protecting niche pricing.
- Satellite Power Systems:Zeno Power leverages radioisotope sourcing agreements to dominate government satellite contracts, with plutonium-238 scarcity forcing multi-year forward commitments that reshape vendor-customer contracting structures.
- Undersea Sensors:Oilfield equipment manufacturers evaluate betavoltaic units for seabed monitoring systems beyond battery replacement reach.
- Emergency Backup:Critical infrastructure installations specify nuclear batteries for grid-independent operation during extended outages.
Satellite power systems retain the largest installed base; medical implants show the steepest expansion trajectory as neural stimulation indications broaden.
Technology:
Conversion efficiency and isotope half-life determine technology selection, with semiconductor junction advances displacing legacy thermoelectric materials in volume-constrained applications.
- Beta Decay:Tritium and nickel-63 emitters power betavoltaic architectures through continuous electron flux across wide-bandgap semiconductor junctions. City Labs Inc. specializes in tritium-based microbattery manufacturing, sustaining niche leadership through FDA-compliant protocols and sealed source certification.
- Radioactive Decay:Alpha-emitting plutonium-238 and curium-244 fuel thermoelectric and thermophotovoltaic systems for high-reliability aerospace applications.
- Thermoelectric Effect:Legacy Seebeck junction technology serves established defense platforms with proven multi-decade reliability records.
- Quantum Dot:Emerging infrared absorption layers promise enhanced conversion efficiency in next-generation thermophotovoltaic designs.
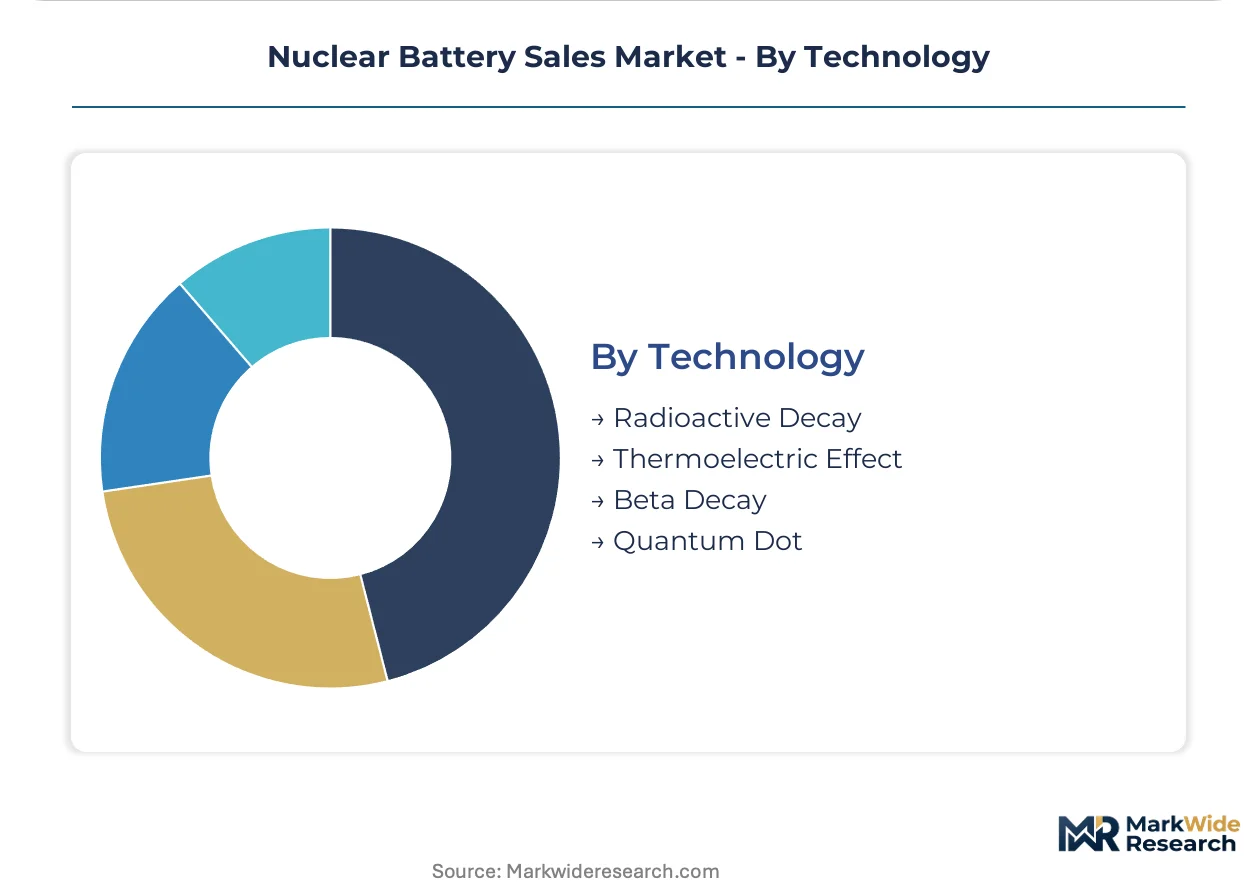
Beta decay conversion dominates commercial shipment volume; quantum dot research programs are expanding most quickly as material science breakthroughs compress development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plutonium-238 production concentrates at the US Department of Energy's Oak Ridge National Laboratory, creating supply bottlenecks that reshape procurement patterns across defense and aerospace verticals worldwide.
United States
NASA and Department of Defense procurement programs anchor global volume commitments for radioisotope thermoelectric generators. The FDA's 21 CFR device classification updates streamline premarket pathways for cardiac implant manufacturers sourcing tritium-based betavoltaic units. Oak Ridge National Laboratory in Tennessee controls plutonium-238 production, constraining thermophotovoltaic battery deployment timelines for deep-space missions.
Germany
Industrial telemetry manufacturers in the Ruhr region evaluate betavoltaic architectures for subsea monitoring systems beyond chemical battery replacement reach. ECHA's evolving REACH authorization requirements for sealed radioactive sources impose substance restriction compliance costs on medical device exporters. The Munich aerospace cluster hosts satellite power system integrators negotiating multi-year forward commitments with isotope suppliers.
Japan
METI funding programs support domestic development of nickel-63 betavoltaic cells for unattended sensor networks in remote island territories. The country's national nuclear regulator maintains strict possession licensing protocols that extend market access timelines for foreign manufacturers. Tokyo-based medical device specialists pursue PMDA premarket consultation for neural stimulation applications requiring decade-long power sources.
France
ANSM oversight of implantable radiological devices creates regulatory divergence from FDA pathways that cardiac manufacturers must navigate for EU market entry. The Provence-Alpes-Côte d'Azur region hosts defense contractors consolidating multi-decade power source contracts under single-vendor arrangements with radioisotope supply guarantees. CEA research programs advance quantum dot infrared absorption layers for next-generation thermophotovoltaic conversion efficiency.
South Korea
Korea Atomic Energy Research Institute production of radioisotope sources supports domestic betavoltaic manufacturing for defense sensor applications. MFDS medical device regulations require localized clinical data for implantable power sources, extending commercialization timelines relative to US pathways. The Daejeon-Sejong corridor concentrates semiconductor junction fabrication facilities serving wide-bandgap material research programs.
Nuclear Battery Sales Market Competitive Landscape
Concentration sits with national laboratory spin-offs and specialized microbattery manufacturers that control isotope sourcing agreements and FDA-compliant production protocols. The vendor base separates into three strategic archetypes: prime contractors with direct Department of Energy relationships, medical device specialists with sealed source certification expertise, and emerging technology developers advancing novel semiconductor junction architectures. Competitive moves center on backward integration into radioisotope supply chains and exclusive licensing of national laboratory conversion technologies.
Among US-based developers, Zeno Power and City Labs Inc. exemplify divergent positioning archetypes—one anchored in government satellite power contracts through direct isotope sourcing agreements, the other specialized in tritium-based microbattery manufacturing for implantable medical devices. BetaBatt Inc. occupies a technology-driven position focused on semiconductor junction architecture advances. Korean Atomic Energy Research Institute represents the national laboratory model with integrated isotope production and device development capabilities.
| Leading Market Players |
|---|
| Korea Atomic Energy Research Institute |
| BetaBatt Inc. |
| NDB Inc. |
| Nusano Inc. |
| Widetronix Inc. |
| Zeno Power |
| City Labs Inc. |
| Qynergy Corporation |
| Infinity Power |
| Others |
Pricing and Supply Chain Analysis
Wide-bandgap semiconductor junctions replacing legacy silicon architectures are redrawing procurement geography toward domestic US fabrication while compressing price premiums for high-efficiency betavoltaic conversion layers. This substitution dynamic simultaneously elevates Oak Ridge National Laboratory's isotope pricing leverage and forces medical device manufacturers into multi-year forward commitments that lock in cost structures.
Pricing Analysis
Volume-discount tiering structures separate NASA mission-grade thermophotovoltaic contracts from small-batch neural implant procurement. Pricing stratifies across FDA-certified medical tiers, defense classified programs, and industrial telemetry volumes. Cost compression in cardiac implant segments is intensifying because City Labs and BetaBatt are expanding tritium microbattery production capacity. Hospital purchasing committees exhibit highest price sensitivity; defense procurement offices prioritize supply security over unit economics.
Supply Chain Analysis
The United States controls plutonium-238 production at Oak Ridge National Laboratory, while Russia and South Korea maintain radioisotope processing capabilities for export-controlled defense applications. The supply chain draws from tritium gas extraction, wide-bandgap semiconductor wafers, and specialized thermoelectric materials. Single-source vulnerability concentrates in DOE reactor production limits that create multi-year order backlogs. Distribution runs through prime contractor direct agreements rather than traditional battery distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in this market accrues to organizations commanding scarce multiphysics simulation talent and sealed source certification expertise that national laboratory alumni pools cannot rapidly replenish.
For Market Incumbents: Compound defensive positioning through backward integration into tritium sourcing agreements and exclusive licensing of gallium nitride junction architectures. Solid-state lithium-metal substitution threatens unattended sensor applications below twenty-year lifespan thresholds. Capacity addition in FDA-compliant manufacturing facilities protects medical implant margin pools from emerging semiconductor specialists. For New Entrants and Emerging Players: Anchor in industrial subsea telemetry white space where oilfield equipment manufacturers evaluate betavoltaic units beyond chemical battery replacement reach. European neural stimulation applications present penetrable regulatory pathways as EMA frameworks evolve. Direct isotope sourcing agreements with national laboratories bypass distributor markups and secure supply chain priority. For Investors and Strategic Acquirers: The market sits at a supply-constrained expansion phase that favors vertically integrated specialists with captive radioisotope production. Long-term viability hinges on five-to-ten-year plutonium-238 availability trajectories and medical device regulatory pathway rationalization. Acquisition targets should demonstrate ISO 2919 certification capabilities and established FDA 21 CFR compliance protocols. Watch DOE reactor production schedule announcements as inflection indicators for thermophotovoltaic deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Isotope Sourcing Agreement | Bypasses distributor markups and secures Oak Ridge National Laboratory supply priority for defense contractors. |
| FDA 21 CFR Certification Investment | Accelerates cardiac implant commercialization timelines and protects premium pricing in medical device segments. |
| Gallium Nitride Junction Development | Miniaturizes device footprints for Medtronic and Boston Scientific neural stimulation procurement specifications. |
| Multi-year Forward Commitment Contracting | Locks in plutonium-238 allocation from DOE reactor production against competing NASA deep-space mission demand. |
| ISO 2919 Sealed Source Certification | Enables international shipment compliance for medical and aerospace applications across EMA-regulated markets. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers at cardiac implant manufacturers, procurement officers at defense prime contractors, isotope supply specialists at national laboratories, and regulatory affairs leads navigating FDA 21 CFR pathways, then refined through secondary validation against NRC licensing databases, NASA procurement disclosures, DOE production reports, and ISO certification registries. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume estimates.
Variance-decomposition across product type, end user, application, technology, and regional regulatory cluster dimensions shaped the analytical framework across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against isotope supply constraints and certification timeline assumptions. Plutonium-238 production schedules and FDA premarket review period trends served as nuclear battery-specific forecast inputs.
Material uncertainties — DOE reactor production delays, EMA authorization scope revisions, and solid-state battery substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about isotope availability trajectories and regulatory pathway stability. Recalibration cycles align with material shifts in national laboratory production announcements and FDA device classification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Tubular GEL Battery Market
Batteries
North America Industrial Battery Market
Batteries
Battery Materials Market
Batteries
N-Type Battery Market
Batteries
West Africa Battery Market
Batteries
North America Battery Market
Batteries
Iron Salt Battery Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
Seawater Battery Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Portable Battery Station Market
Batteries
Lithium-Based Battery Charger Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Mobile Battery Market
Batteries
Battery Wash System Market
Batteries
Lithium Starters Market