
 Global Nuclear Fusion Market | 2026-2036
Global Nuclear Fusion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nuclear Fusion Market Outlook
The capital-intensity divergence between well-funded private developers and leaner academic consortia is redrawing competitive boundaries in nuclear fusion. Commonwealth Fusion Systems leverages its MIT lineage to anchor superconducting magnet capabilities against larger rivals. TAE Technologies sustains its alternative-field-reversed-configuration approach through sustained venture backing. Tokamak Energy competes on compact spherical tokamak geometry, differentiating from the mainstream ITER-scale architecture.
Nuclear fusion denotes the process wherein light atomic nuclei combine under extreme temperature and pressure to release energy, typically requiring plasma temperatures exceeding 100 million degrees Celsius sustained within magnetic or inertial confinement vessels. Its primary purpose centers on delivering baseload electricity without long-lived radioactive waste or carbon emissions. Tokamak technology dominates current investment flows due to decades of operational experience at facilities in the United Kingdom and France. Superconducting magnets represent the critical margin pool, as rare-earth supply chains and cryogenic cooling systems concentrate value capture among specialized component suppliers. Electricity generation applications attract the majority of near-term funding, though industrial process heat offers a secondary demand vector for heavy manufacturing decarbonization.
The US Department of Energy and the UK Atomic Energy Authority shape demand through milestone-based funding tranches tied to plasma performance benchmarks. The EU Green Deal and associated fusion roadmap from the European Commission direct public procurement toward stellarator and tokamak demonstration reactors. Japan's METI coordinates domestic supply chain development through its Broader Approach agreement with the ITER Organization. Stakeholders must monitor which regulatory frameworks first codify fusion-specific licensing distinct from fission precedents, as this determination will unlock private capital deployment at scale.
Market Dynamics
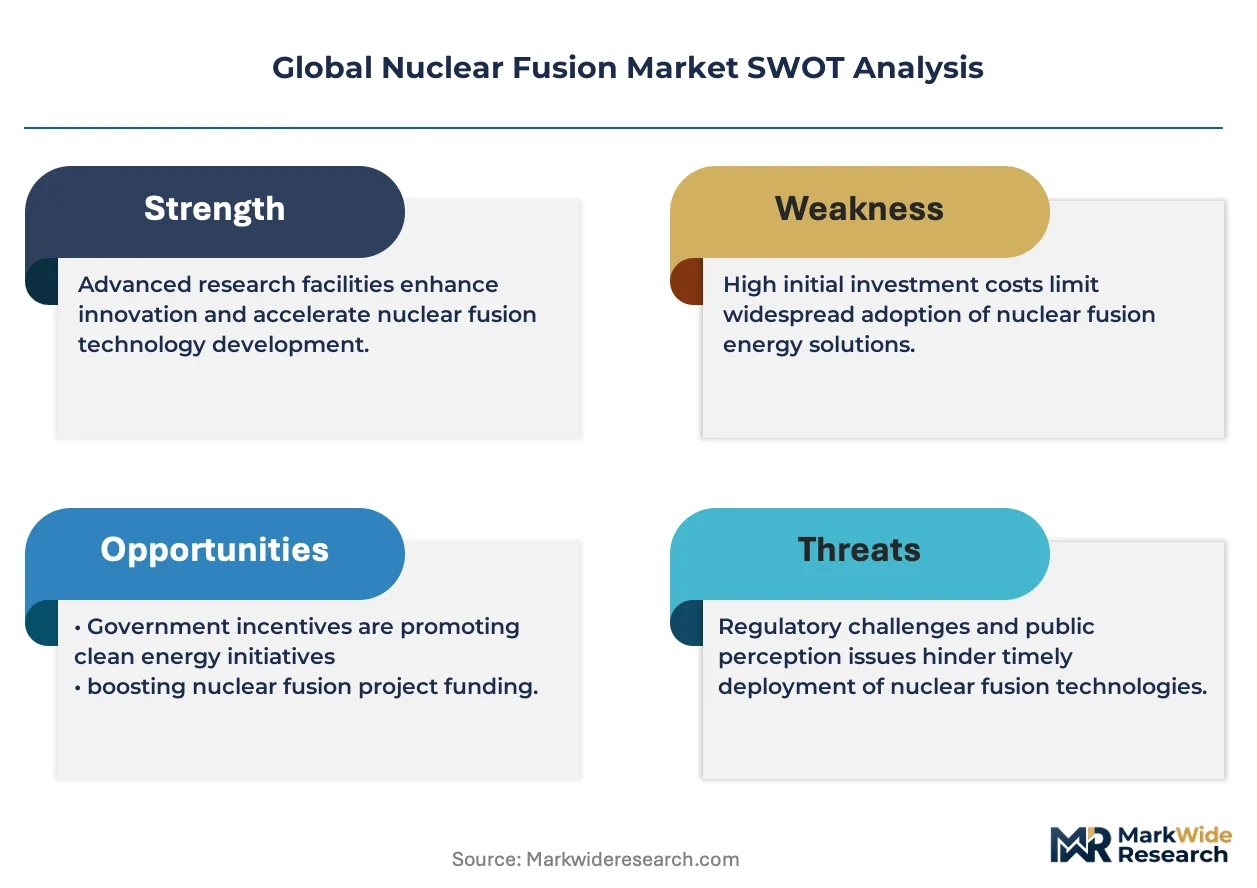
High-temperature superconducting magnet development is compressing reactor construction timelines and redistributing capital requirements across the fusion value chain, forcing developers to secure rare-earth supply partnerships before plasma demonstration milestones.
Growth Catalysts
- EU Green Deal fusion roadmap:The European Commission directs public procurement toward stellarator and tokamak demonstration reactors, creating guaranteed offtake for early-stage developers.
- Industrial process heat demand:Heavy manufacturing decarbonization requirements in Germany and Japan establish secondary revenue streams beyond electricity generation.
- Spherical tokamak geometry:Compact reactor designs reduce capital intensity and site preparation costs compared to ITER-scale architecture.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium processing capacity clusters in China, exposing developers to export restriction risk.
- Cryogenic cooling infrastructure gaps:Helium liquefaction capacity constraints in the United States and Europe limit magnet commissioning schedules.
- Fission-derived licensing frameworks:Regulatory bodies in most jurisdictions apply nuclear fission precedents to fusion, extending permitting timelines by 24-36 months.
Strategic Opportunities
- United Kingdom regulatory sandbox:The UK Atomic Energy Authority develops fusion-specific licensing distinct from fission, positioning Britain as first-mover for private capital deployment.
- AI-enabled plasma control convergence:Machine learning algorithms trained on experimental data from JET and DIII-D compress operational optimization cycles.
- Japan METI supply chain coordination:The Broader Approach agreement domesticizes component manufacturing for Asian reactor deployments.
Industry Challenges
- Plasma physicist talent scarcity:Academic pipeline output lags behind venture-funded developer hiring needs in the United States and United Kingdom.
- Tritium breeding blanket certification:No regulator has established approval pathways for lithium-based fuel cycle systems, blocking integrated reactor demonstrations.
- Superconducting magnet quality assurance:Quench detection and protection system failures destroy months of manufacturing progress and capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nuclear Fusion Market |
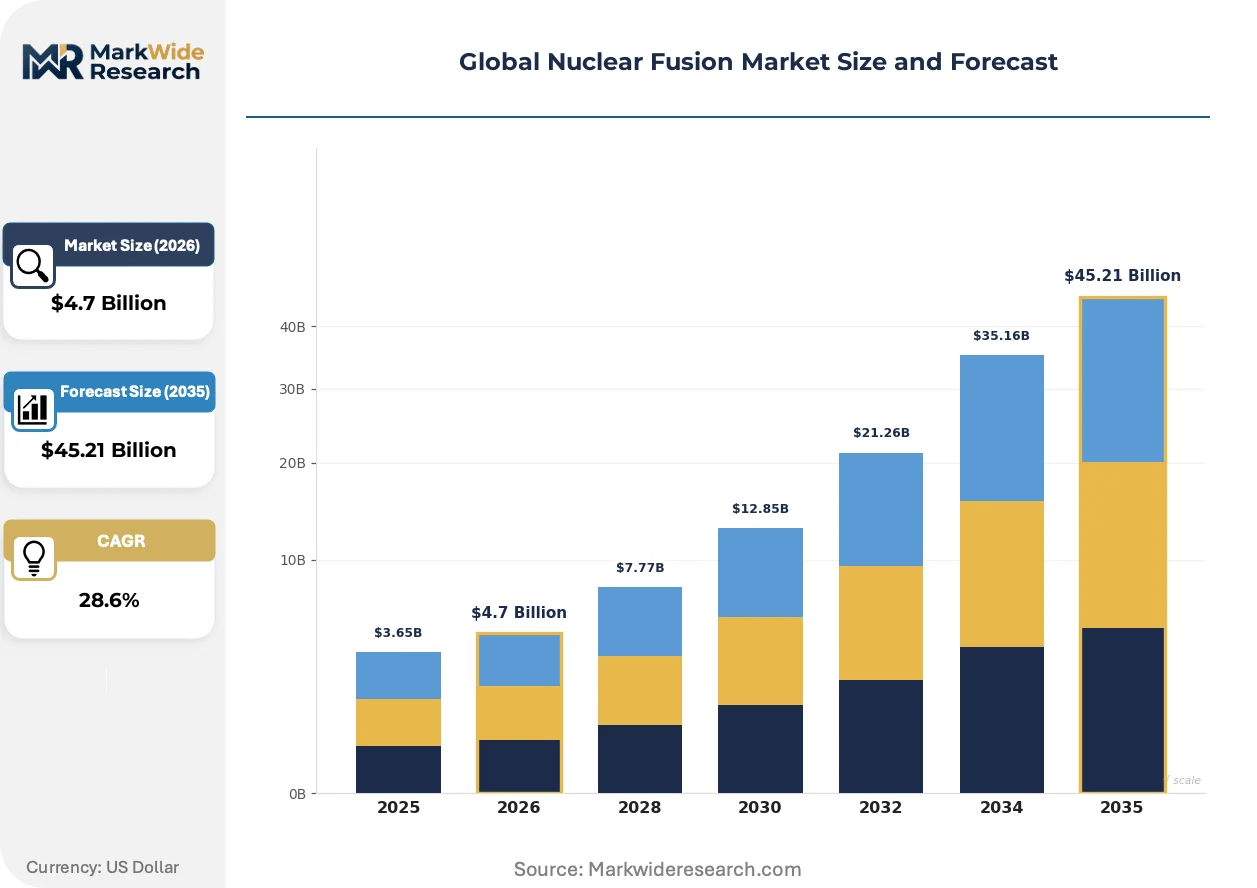
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Tokamak, Stellarator, Inertial Confinement, Magnetic Target Fusion End User: Government Agencies, Research Institutions, Private Corporations, Academic Institutions Component: Superconducting Magnets, Lasers, Diagnostic Equipment, Cooling Systems Application: Electricity Generation, Space Propulsion, Industrial Process Heat, Research and Development |
| Companies Covered | Commonwealth Fusion Systems, TAE Technologies, Helion Energy, Tokamak Energy, General Fusion, Zap Energy, Marvel Fusion, First Light Fusion, HB11 Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nuclear Fusion Market Strategic Shifts
Reactor architecture is fragmenting into competing confinement philosophies while regulatory frameworks struggle to categorize fusion distinct from fission precedents.
High-temperature superconducting tape is bifurcating developer strategies between established low-temperature niobium-titanium systems and emerging rare-earth barium copper oxide conductors. Commonwealth Fusion Systems and Tokamak Energy pursue the latter for stronger magnetic fields and compact footprints. The technology is bifurcating procurement patterns, as magnet suppliers must qualify entirely separate manufacturing lines and quality protocols.
The EU AI Act establishes risk classification for autonomous plasma control systems, requiring algorithmic transparency documentation for reactor safety submissions. European stellarator projects face additional compliance burden compared to US counterparts operating under less prescriptive frameworks. Germany's Wendelstein 7-X facility adapts control architectures to satisfy both physics optimization and regulatory audit trails.
Utility offtake negotiations now precede rather than follow plasma demonstration, with power purchase agreements serving as milestone financing collateral. Developers in the United States secure conditional commitments from regional grids before finalizing magnet specifications. This reverses traditional energy infrastructure sequencing where technology validation preceded commercial contracting.
Global Nuclear Fusion Market Segmentation
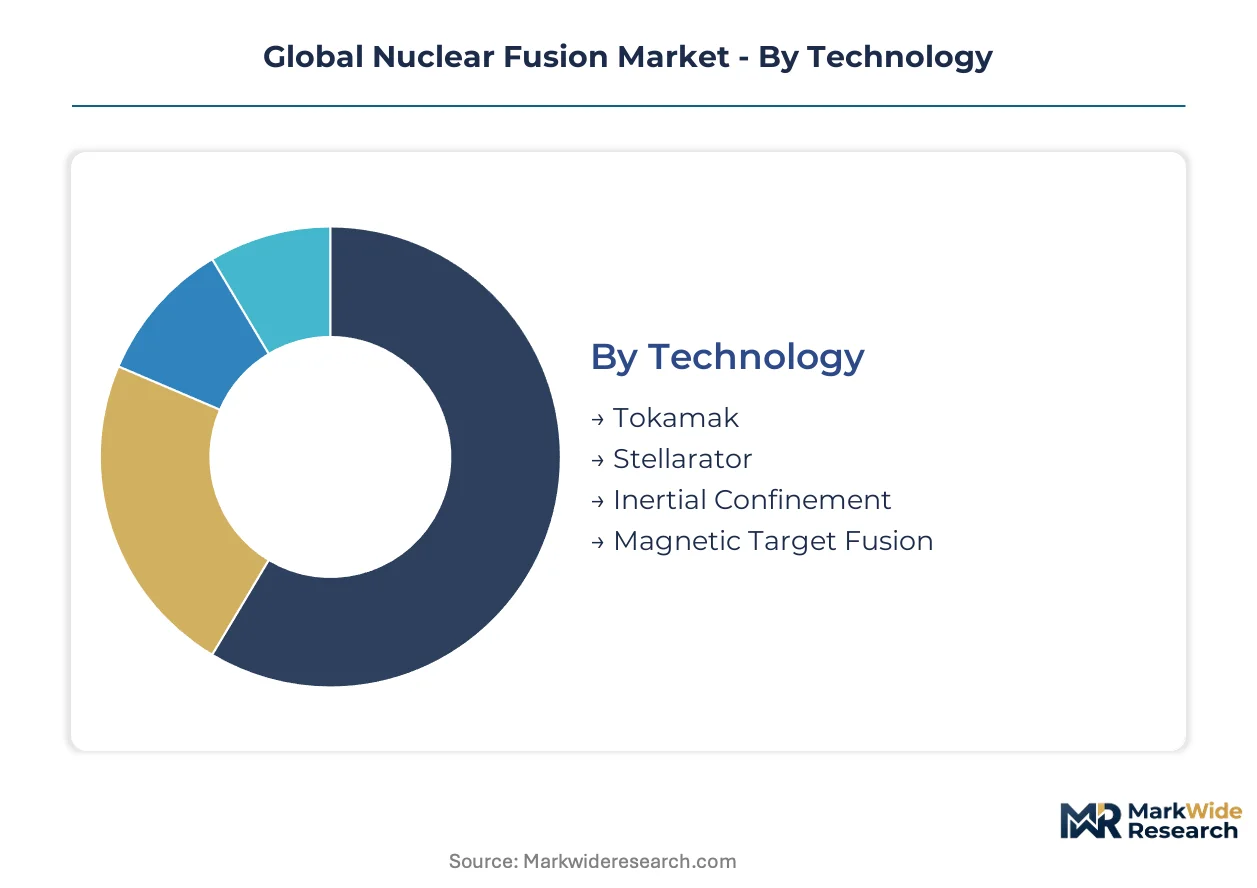
Segmentation reveals how capital flows diverge between demonstration-scale reactors and component supply chains. Technology choices determine magnet procurement patterns, while end-user categories dictate funding mechanisms and regulatory pathways.
Technology:
Tokamak systems dominate procurement channels for government demonstration contracts, while stellarator and alternative confinement approaches attract private venture allocation through different technical milestones.
- Tokamak:Toroidal magnetic confinement vessels using poloidal and toroidal field coils to sustain plasma equilibrium represent the most mature pathway. Demand concentrates in France, the United Kingdom, and the United States where national laboratories anchor procurement for large-scale demonstration facilities, driven by decades of operational data from JET and DIII-D enabling predictable plasma control algorithms.
- Stellarator:Helical magnetic field configurations eliminate the need for plasma current drive through external coil geometry alone. Germany and Japan concentrate development investment, with Wendelstein 7-X and LHD facilities providing experimental baselines that attract EU Green Deal funding streams distinct from tokamak milestone structures.
- Inertial Confinement:Laser-driven compression of fuel pellets achieves fusion conditions without magnetic confinement. The National Ignition Facility in the United States validates physics principles for defense and energy applications.
- Magnetic Target Fusion:Hybrid approaches combining magnetic preheating with inertial compression offer compact reactor footprints. Private developers in Canada and the United States pursue this pathway for modular deployment scenarios.
By volume, tokamak leads. By growth pace, magnetic target fusion is climbing the fastest.
End User:
Cost tier segmentation separates sovereign-funded megaprojects from venture-backed developer timelines, with academic consortia occupying intermediate funding structures.
- Government Agencies:Sovereign entities including the US Department of Energy, UK Atomic Energy Authority, and Japan's METI deploy multi-billion-dollar procurement tranches tied to plasma performance milestones. These fund ITER contributions, national laboratory infrastructure, and milestone-based private developer awards.
- Private Corporations:Venture-backed developers including Commonwealth Fusion Systems and TAE Technologies raise capital through equity financing secured against technical milestones and conditional utility offtake agreements. Their procurement concentrates on superconducting magnets and cryogenic systems.
- Research Institutions:National laboratories and international collaborations operate existing experimental facilities and contribute to ITER construction. Their demand centers on diagnostic equipment and plasma-facing components.
- Academic Institutions:University-based plasma physics programs access smaller-scale funding for theory validation and graduate training pipelines. Their procurement focuses on computational infrastructure and experimental subsystems.
By capital deployed, government agencies dominate. By deal velocity, private corporations are expanding most quickly.
Component:
Supply concentration for rare-earth materials and helium liquefaction capacity creates margin capture asymmetries across component categories.
- Superconducting Magnets:High-temperature rare-earth barium copper oxide and low-temperature niobium-titanium coil systems generate the largest capital expenditure share. Manufacturers in Japan, Germany, and the United States compete for qualification against demanding quench protection specifications.
- Lasers:Solid-state and diode-pumped systems for inertial confinement require precision optical manufacturing. Demand clusters at the National Ignition Facility and comparable defense-energy dual-use programs.
- Diagnostic Equipment:Thomson scattering, interferometry, and neutron detection systems measure plasma parameters. Academic and national laboratory procurement drives this segment.
- Cooling Systems:Helium liquefiers and cryogenic distribution networks enable magnet operation. Capacity constraints in the United States and Europe limit commissioning schedules for new reactor projects.
By revenue concentration, superconducting magnets lead. By supply bottleneck severity, cooling systems face the steepest expansion constraints.
Application:
Customer type segmentation separates baseload electricity offtake negotiations from specialized industrial and aerospace procurement with distinct technical specifications.
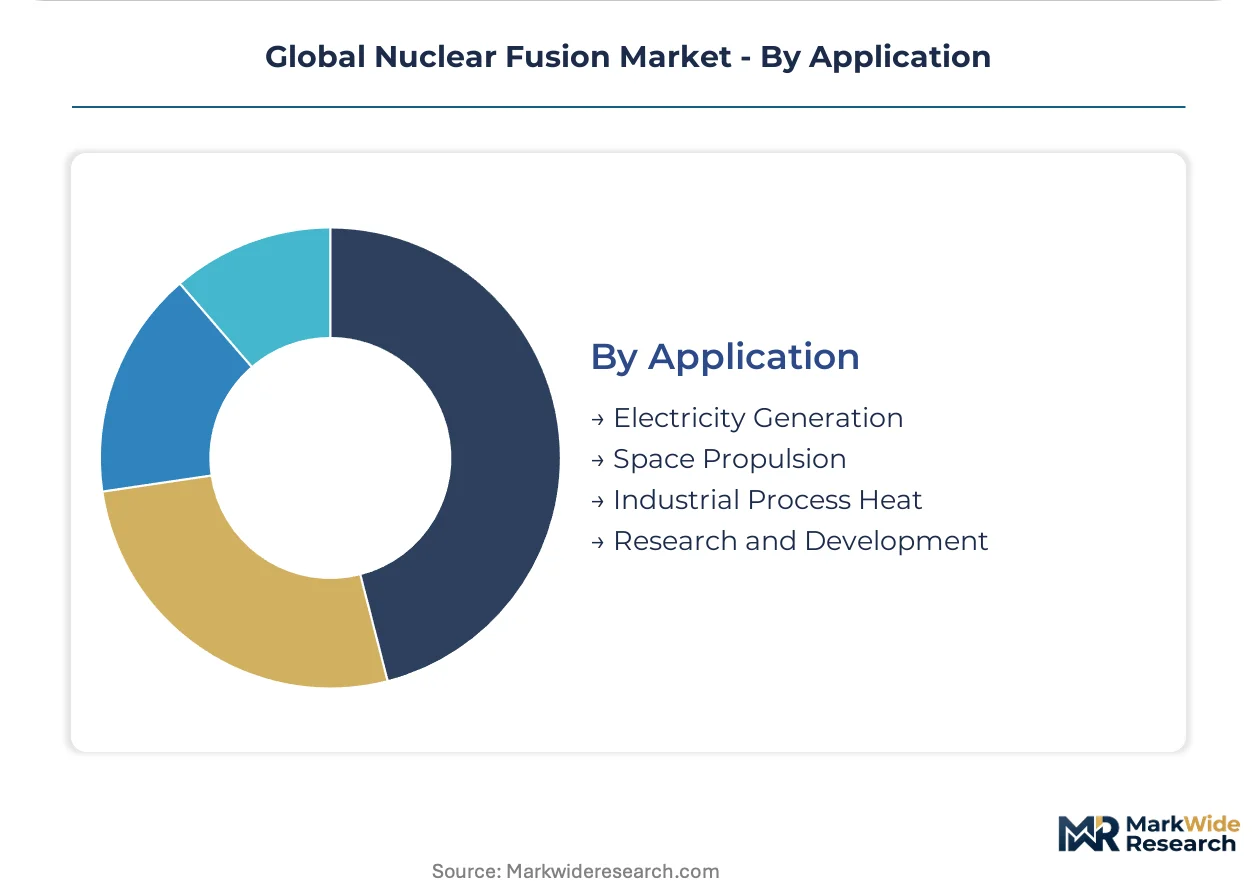
- Electricity Generation:Grid-connected baseload power plants represent the primary commercialization target. Utility offtake negotiations in the United States and United Kingdom now precede plasma demonstration milestones, reversing traditional infrastructure sequencing.
- Industrial Process Heat:High-temperature thermal output for steel, cement, and chemical manufacturing offers decarbonization pathways in Germany and Japan. This secondary demand vector attracts separate regulatory treatment from electricity market frameworks.
- Space Propulsion:Compact fusion systems for deep-space mission profiles drive research at NASA and comparable agencies. Technical requirements prioritize thrust-to-weight ratios over steady-state power output.
- Research and Development:Plasma physics validation, materials testing, and fuel cycle experiments sustain demand from ITER, national laboratories, and university programs. This segment provides the experimental foundation for commercial pathway development.
By near-term funding allocation, electricity generation leads. By technical differentiation potential, industrial process heat is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developers in the United States and United Kingdom demonstrate lowest price sensitivity to magnet procurement costs, while German and Japanese consortia face tighter capital constraints that compress supplier margins.
United States
Commonwealth Fusion Systems and Helion Energy anchor private capital deployment through milestone-based equity financing. The Department of Energy's milestone program directs procurement toward high-temperature superconducting magnet qualification. Massachusetts and California clusters concentrate plasma control algorithm development alongside magnet manufacturing partnerships.
United Kingdom
Tokamak Energy and First Light Fusion leverage the UK Atomic Energy Authority's regulatory sandbox for fusion-specific licensing distinct from fission precedents. The government's fusion strategy commits public procurement tranches to spherical tokamak and inertial confinement demonstrations. Oxfordshire and South Yorkshire house concentrated diagnostic equipment and plasma-facing component supply chains.
Germany
Max Planck Institute operations at Wendelstein 7-X sustain stellarator-focused procurement despite higher capital intensity than tokamak alternatives. The EU Green Deal fusion roadmap channels Commission funding toward helical confinement geometry validation. Bavaria and Brandenburg maintain cryogenic cooling infrastructure and precision coil manufacturing capabilities.
Japan
METI coordinates domestic supply chain development through the Broader Approach agreement with ITER Organization, reducing rare-earth magnet import dependence. National universities and Hitachi-anchored consortia pursue compact reactor designs for industrial process heat applications. Naka and Rokkasho host concentrated tritium handling and superconducting tape qualification facilities.
France
ITER Organization procurement sustains tokamak component demand despite schedule overruns compressing private developer capital availability. The Alternative Energies and Atomic Energy Commission maintains regulatory influence over European fusion safety frameworks. Provence-Alpes-Côte d'Azur hosts the Cadarache research complex and associated magnet supply chain clustering.
Global Nuclear Fusion Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with MIT-originated developers commanding magnet performance specifications while venture-backed alternatives compete on reactor compactness and timeline compression. The market structures around three tiers: sovereign-funded megaprojects with multi-decade horizons, well-capitalized private developers securing utility offtake pre-commitments, and lean academic spinouts dependent on milestone tranches. Dominant competitive moves center on rare-earth supply partnerships upstream and conditional power purchase agreements downstream.
Within the high-temperature superconducting magnet tier, Commonwealth Fusion Systems and Tokamak Energy occupy positions that exemplify the divergence between American and British regulatory first-mover strategies. TAE Technologies anchors the alternative confinement archetype through sustained venture backing distinct from tokamak mainstream architectures.
| Leading Market Players |
|---|
| Commonwealth Fusion Systems |
| TAE Technologies |
| Helion Energy |
| Tokamak Energy |
| General Fusion |
| Zap Energy |
| Marvel Fusion |
| First Light Fusion |
| HB11 Energy |
| Others |
Value Chain & Pricing Dynamics
EU AI Act risk classification for autonomous plasma control systems gates both superconducting magnet supplier qualification and price differentiation between European and American reactor developers. The regulation's algorithmic transparency requirements impose compliance costs that widen the cost gap between stellarator projects in Germany and tokamak alternatives in less prescriptive jurisdictions.
Pricing Analysis
After-sales service contracts for cryogenic cooling system maintenance drive lifetime value for magnet manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by plasma performance requirements and regulatory certification tier. Cost compression in standard-tier niobium-titanium systems is intensifying because Commonwealth Fusion Systems and Tokamak Energy are qualifying competing rare-earth barium copper oxide supply lines. Academic institutions and national laboratories exhibit highest price sensitivity due to milestone-dependent funding tranches, while venture-backed private developers demonstrate lowest sensitivity when securing utility offtake pre-commitments.
Supply Chain Analysis
Extended lead times for helium liquefaction equipment now stretch magnet commissioning schedules by multiple quarters. Rare-earth magnet processing capacity concentrates in China, Japan, and Germany, with neodymium and dysprosium supply chains drawing from concentrated mining operations in Inner Mongolia and Mountain Pass. Single-source vulnerability in high-temperature superconducting tape manufacturing exposes developers to export restriction risk from Beijing's strategic materials policy. Distribution runs through specialized cryogenic logistics networks that link coil manufacturers in Bavaria and Massachusetts directly to reactor construction sites in Oxfordshire and Naka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global nuclear fusion market fragmentation creates entry niches as reactor architecture splinters between tokamak, stellarator, and alternative confinement pathways with divergent component specifications. Industrial process heat demand from German steel and Japanese chemical manufacturers opens specialized procurement channels distinct from electricity generation offtake negotiations.
For Market Incumbents: Secure rare-earth supply partnerships upstream before plasma demonstration milestones compress procurement timelines further. Commonwealth Fusion Systems and Tokamak Energy are anchoring magnet performance specifications that threaten to commoditize niobium-titanium suppliers. Capacity addition in cryogenic cooling infrastructure represents the critical defensive lever against commissioning delays that erode milestone-based financing collateral. For New Entrants and Emerging Players: Anchor in spherical tokamak geometry for compact reactor footprints that reduce capital intensity below ITER-scale alternatives. The United Kingdom regulatory sandbox offers the most penetrable jurisdiction for fusion-specific licensing distinct from fission precedents. Machine learning-enabled plasma control systems provide the go-to-market angle for algorithm-native teams lacking decades of experimental physics heritage. For Investors and Strategic Acquirers: Carve-out targets emerge from national laboratory technology transfer offices holding quench detection and protection system IP. Long-term viability hinges on which developers first secure conditional power purchase agreements before rather than after plasma demonstration. Tritium breeding blanket certification progress at the UK Atomic Energy Authority serves as the critical signal to watch for integrated reactor demonstration feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Supply Partnership | Commonwealth Fusion Systems' MIT lineage anchors superconducting magnet capabilities against larger rivals. |
| Regulatory Sandbox Entry | UK Atomic Energy Authority fusion-specific licensing positions Britain as first-mover for private capital deployment. |
| Utility Offtake Pre-Commitment | Conditional power purchase agreements now serve as milestone financing collateral before plasma demonstration. |
| AI-Enabled Plasma Control | Machine learning algorithms trained on JET and DIII-D data compress operational optimization cycles. |
| Industrial Process Heat Pivot | German steel and Japanese chemical manufacturing decarbonization requirements establish secondary revenue streams. |
Study Parameters
The analysis maps tokamak, stellarator, inertial confinement, and magnetic target fusion pathways, each validated through plasma physicists, superconducting magnet procurement leads, cryogenic system engineers, and utility offtake negotiators. Primary interviews with reactor developers and national laboratory directors combined with secondary validation from ITER Organization procurement disclosures, EU Green Deal funding allocations, and Japan METI Broader Approach agreement documents. Bottom-up reactor deployment timelines and top-down government funding commitments undergo cross-triangulation against magnet manufacturing capacity announcements.
Consistency checks validated volume and value outputs against external benchmarks including sovereign fusion budget appropriations and venture capital flow tracking. The analytical framework segments by technology confinement geometry, end-user funding structure, component supply tier, and application energy output type across the projection horizon. CAGRs derive from reactor commissioning schedules, magnet qualification timelines, and regulatory pathway maturation curves rather than extrapolated historical series. Plasma performance milestone achievement rates and rare-earth magnet supply expansion trajectories feed directly into forecast sensitivity bands.
Decision-makers should treat outputs as directional under assumptions of sustained government procurement commitment and stable rare-earth export policy; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
Nuclear Steam Generator Market
Nuclear Energy
Nuclear Decommissioning Services Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Global Nuclear Reactor Construction Market