
 Asia-Pacific Nuclear Power Plant and Equipment Market | 2026-2036
Asia-Pacific Nuclear Power Plant and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nuclear Power Plant and Equipment Market Outlook
China's reactor construction pipeline is tilting regional supply chains toward heavy forging and reactor pressure vessel manufacturing. Shanghai Electric Group Company Limited leverages domestic capacity in turbine generators and auxiliary systems. Korea Hydro & Nuclear Power Co., Ltd. anchors South Korean export competitiveness through APR1400 technology transfers to the UAE and beyond. Doosan Enerbility competes on large component forging and integrated project delivery across multiple Asia-Pacific markets.
Asia-Pacific nuclear power plant and equipment encompasses reactor pressure vessels, steam generators, coolant pumps, control rod mechanisms, and safety-grade instrumentation operating at pressures exceeding 15.5 MPa and temperatures above 320°C, designed to sustain fission chain reactions while containing radioactive materials for electricity generation. Pressurized Water Reactor technology dominates installed capacity and replacement part demand across the region, while Advanced Modular Reactor designs attract early engineering investment for remote deployment and industrial heat applications. Safety Systems command premium pricing due to seismic qualification requirements and regulatory redundancy mandates, whereas Maintenance Services generate recurring revenue streams tied to operating license renewals.
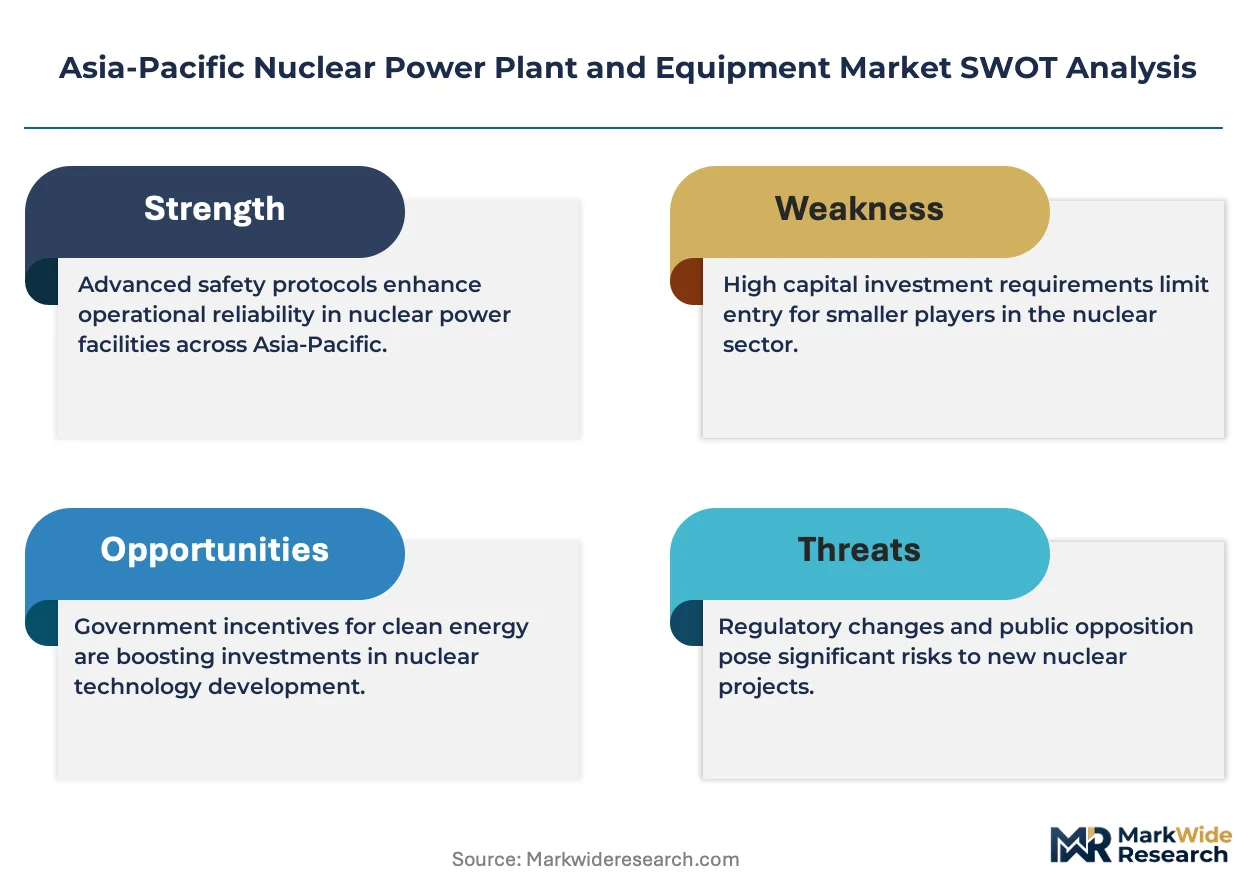
China's National Nuclear Safety Administration enforces construction and operational licensing under GB standards, while South Korea's Nuclear Safety and Security Commission governs post-Fukushima stress test protocols that extend plant life and trigger equipment upgrades. Japan's Nuclear Regulation Authority restart approvals create phased demand for containment venting and seismic isolation systems. Stakeholders must monitor regulatory divergence between national safety frameworks and harmonization pressures from the International Atomic Energy Agency's standards.
Market Dynamics
China's dual carbon goals and Japan's restart protocols are compressing procurement timelines for reactor pressure vessels and safety-grade instrumentation. State-backed reactor programs in China, South Korea, and India dominate equipment procurement, tilting regional supply chains toward heavy forging capacity and seismic qualification expertise.
Growth Catalysts
- Dual Carbon Policy Framework:China's GB standards enforcement accelerates baseload capacity expansion to replace retiring coal fleets. State-owned utilities commission new reactor builds under compressed construction schedules.
- Japan's Restart Protocols:The Nuclear Regulation Authority's phased approvals for containment venting and seismic isolation systems trigger equipment upgrade cycles across existing reactor fleets.
- APR1400 Technology Transfer:Korea Hydro & Nuclear Power Co. exports reactor technology to the UAE and beyond, generating demand for South Korean heavy forging and integrated project delivery capabilities.
Market Restraints
- Heavy Forging Concentration:Reactor pressure vessel manufacturing concentrates among a limited set of qualified forgers in China, South Korea, and Japan, creating supply bottlenecks for large component delivery.
- Extended Certification Timelines:The International Atomic Energy Agency's harmonization pressures clash with national safety frameworks, prolonging equipment qualification periods for cross-border projects.
- Capital Intensity Barriers:Advanced Modular Reactor development requires sustained engineering investment without near-term revenue, constraining private capital participation.
Strategic Opportunities
- Industrial Heat Applications:Advanced Modular Reactor designs attract early engineering investment for remote deployment and process heat supply to steel and chemical plants.
- Maintenance Services Expansion:Operating license renewals in South Korea and Japan generate recurring revenue streams for safety system upgrades and component replacement.
- Southeast Asia Baseload Gap:Utilities in Vietnam, Indonesia, and the Philippines evaluate nuclear options to replace coal capacity, creating greenfield procurement potential.
Industry Challenges
- Seismic Qualification Expertise Shortage:The region lacks sufficient engineers certified to GB standards and Japan's post-Fukushima stress test protocols, constraining project execution capacity.
- Supply Chain Reconfiguration Friction:Reactor manufacturers must dual-source critical components across China, South Korea, and Japan while navigating divergent national safety frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nuclear Power Plant and Equipment Market |
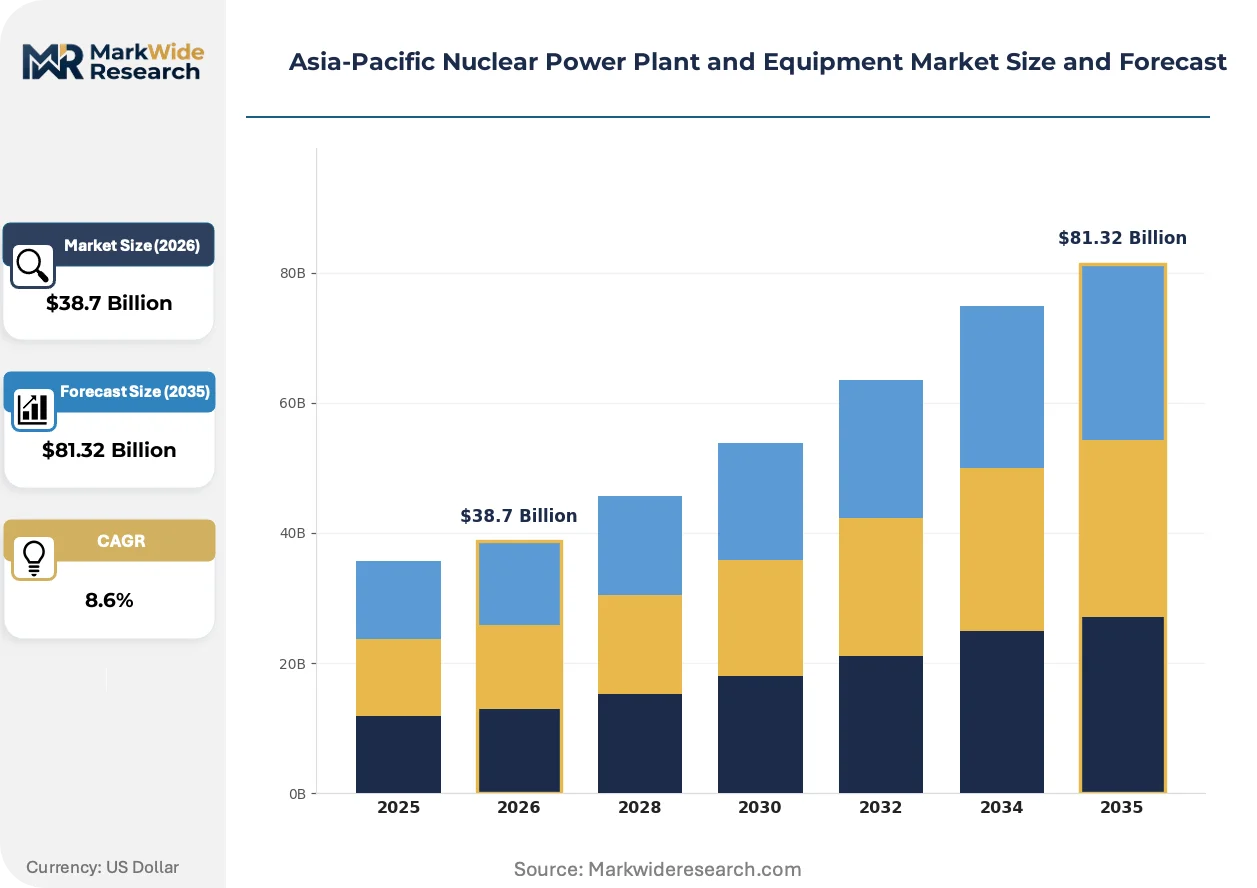
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Reactor Components, Safety Systems, Control Systems, Fuel Handling Systems Technology: Pressurized Water Reactor, Boiling Water Reactor, Fast Breeder Reactor, Advanced Modular Reactor End User: Utilities, Government Agencies, Research Institutions, Contractors Service Type: Maintenance Services, Engineering Services, Consulting Services, Decommissioning Services |
| Companies Covered | China General Nuclear Power Corporation, Shanghai Electric Group Company Limited, Korea Hydro & Nuclear Power Co., Ltd., Doosan Enerbility, Larsen & Toubro Limited, Dongfang Electric Corporation Limited, GE-Hitachi Nuclear Energy, Framatome, Mitsubishi Heavy Industries Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nuclear Power Plant and Equipment Market Strategic Shifts
Digital instrumentation and modular construction methods are compressing reactor build schedules while elevating safety system performance requirements. Equipment suppliers must integrate cyber-physical capabilities with legacy mechanical systems.
Small Modular Reactor designs incorporating factory-fabricated modules and passive safety systems are rendering obsolete site-intensive construction approaches for remote deployment scenarios. Mining operations and island grids in Indonesia and the Philippines evaluate these configurations for baseload independence. The shift compresses project development timelines from decade-scale to half-decade delivery cycles.
South Korea's Nuclear Safety and Security Commission mandates post-Fukushima stress test protocols that extend plant life and trigger equipment upgrades across operating fleets. Reactor operators must replace aging coolant pumps and control rod mechanisms with seismic-qualified alternatives. The regulation drives replacement part demand concentrated in South Korean and Japanese maintenance markets.
Utility procurement departments unbundle long-term service contracts from initial equipment supply, favoring performance-based maintenance agreements with penalty clauses for system availability. Shanghai Electric and Doosan Enerbility restructure offerings to capture recurring revenue through spare parts logistics and predictive analytics. The model shift is most visible in China's state-owned reactor fleet procurement guidelines.
Asia-Pacific Nuclear Power Plant and Equipment Market Segmentation
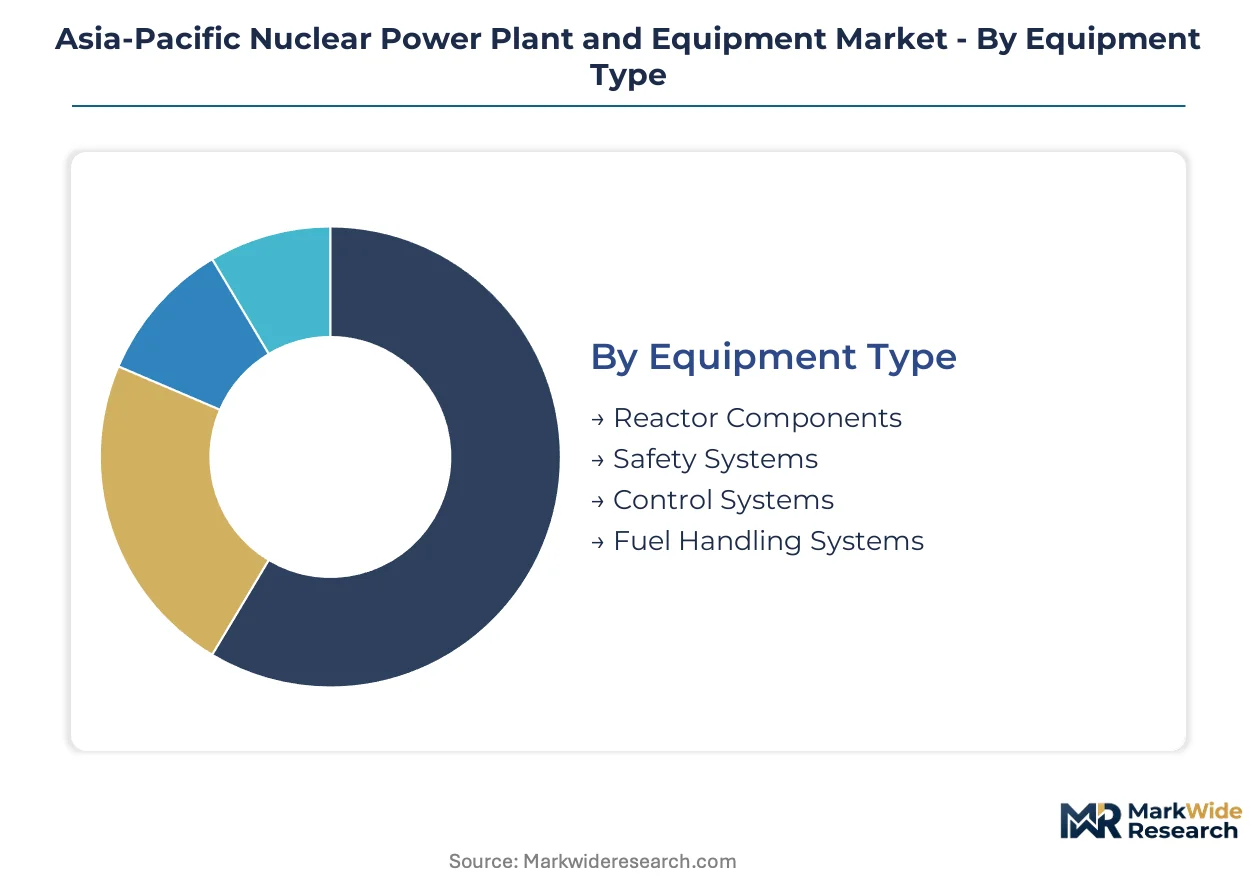
Equipment procurement patterns across Asia-Pacific nuclear markets diverge sharply by reactor lifecycle stage and regulatory maturity. State-backed utilities dominate capital expenditure, while maintenance services concentrate in aging fleets across Japan and South Korea.
Equipment Type:
Cost tier differentiation separates commodity auxiliary components from safety-grade systems requiring seismic qualification and redundant certification.
- Reactor Components:Reactor pressure vessels, steam generators, and coolant pumps operate at pressures exceeding 15.5 MPa and temperatures above 320°C. Procurement concentrates in China's state-owned reactor builds under compressed construction schedules mandated by dual carbon targets.
- Safety Systems:Containment venting, seismic isolation, and emergency core cooling systems command premium pricing due to GB standards enforcement and Japan's post-Fukushima stress test protocols. Demand clusters in Japan's restart approvals and South Korea's plant life extensions.
- Control Systems:Digital instrumentation with cyber-physical integration requirements.
- Fuel Handling Systems:Spent fuel storage and transfer equipment for operating and decommissioning reactors.
Reactor Components commands the established base. The steepest expansion runs through Safety Systems.
Technology:
Application maturity spans from proven baseload designs to early-stage modular configurations targeting industrial heat and remote deployment.
- Pressurized Water Reactor:Dominant installed base across China, South Korea, and Japan with established supply chains for replacement parts. Korea Hydro & Nuclear Power's APR1400 exports to the UAE extend regional manufacturing capacity for large forged components.
- Advanced Modular Reactor:Factory-fabricated modules with passive safety systems compress project timelines from decade-scale to half-decade delivery. Mining operations and island grids in Indonesia and the Philippines evaluate these configurations for baseload independence without grid interconnect.
- Boiling Water Reactor:Concentrated in Japan's existing fleet requiring seismic upgrade cycles.
- Fast Breeder Reactor:Experimental and prototype deployments with limited commercial procurement.
Pressurized Water Reactor anchors current revenue. Advanced Modular Reactor claims the most aggressive development trajectory.
End User:
Customer type determines procurement scale, with state entities commanding multi-reactor programs versus fragmented contractor demand.
- Utilities:State-owned power companies in China, South Korea, and India commission new reactor builds and life extension projects. China's National Nuclear Safety Administration licensing timelines compress equipment delivery windows.
- Contractors:Engineering, procurement, and construction firms source specialized components for cross-border projects.
- Government Agencies:Regulatory and policy-driven procurement for strategic reserves.
- Research Institutions:Limited-volume orders for experimental reactor configurations.
Utilities dominate capital deployment. Contractors represent the most volatile demand segment tied to project financing cycles.
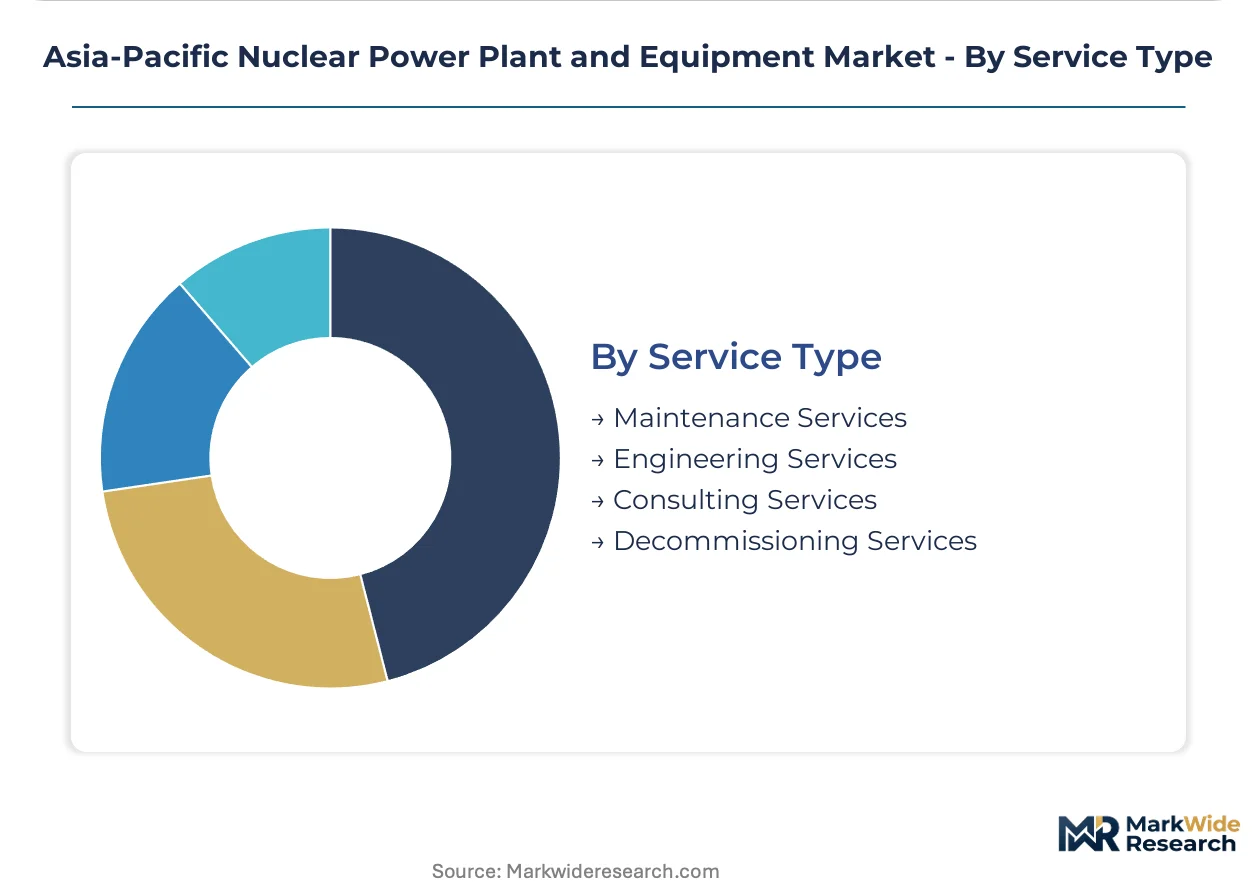
Service Type:
Revenue stability separates recurring maintenance from one-time engineering and decommissioning engagements.
- Maintenance Services:Recurring revenue streams tied to operating license renewals in South Korea and Japan. South Korea's Nuclear Safety and Security Commission mandates replacement of aging coolant pumps and control rod mechanisms with seismic-qualified alternatives.
- Decommissioning Services:Emerging demand from Japan's reactor retirements and early Chinese plant closures. Specialized waste handling and site remediation require distinct contractor capabilities from construction-phase suppliers.
- Engineering Services:Front-end design and licensing support for greenfield projects.
- Consulting Services:Regulatory compliance and safety analysis for operating fleets.
Maintenance Services provides the predictable revenue base. Decommissioning Services is climbing the fastest as fleet aging accelerates across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heavy forging capacity for reactor pressure vessels clusters among qualified facilities in China, South Korea, and Japan, with each national program driving distinct procurement rhythms and safety qualification requirements.
China
State-owned utilities commission new reactor builds under compressed construction schedules mandated by dual carbon targets. The National Nuclear Safety Administration enforces GB standards for construction and operational licensing. Shanghai Electric Group and Dongfang Electric anchor manufacturing clusters in the Yangtze River Delta and Sichuan-Chongqing corridor, supplying turbine generators and auxiliary systems to domestic reactor programs.
South Korea
Korea Hydro & Nuclear Power Co. exports APR1400 technology to the UAE and beyond, generating demand for heavy forging and integrated project delivery capabilities. The Nuclear Safety and Security Commission mandates post-Fukushima stress test protocols that extend plant life and trigger equipment upgrades. Doosan Enerbility anchors large component manufacturing in the Busan-Ulsan industrial belt, serving both domestic and export reactor contracts.
Japan
The Nuclear Regulation Authority's phased restart approvals create demand for containment venting and seismic isolation systems across existing reactor fleets. METI oversees safety framework implementation that drives replacement part procurement. Mitsubishi Heavy Industries maintains engineering and manufacturing presence in the Kansai and Chubu regions, focusing on seismic-qualified component upgrades for restarted units.
India
State-backed reactor programs under the Department of Atomic Energy drive procurement for pressurized heavy water reactors and future light water designs. The Atomic Energy Regulatory Board governs licensing timelines that compress equipment delivery windows. Larsen & Toubro Limited anchors domestic fabrication capacity in Gujarat and Maharashtra, supplying heavy engineering components for indigenous reactor builds.
Vietnam
Utilities evaluate nuclear options to replace retiring coal capacity, creating greenfield procurement potential for first-mover equipment suppliers. The Ministry of Industry and Trade coordinates energy planning that includes nuclear feasibility assessments. Engineering consultancies in Hanoi and Ho Chi Minh City develop preliminary site studies and workforce training programs for potential reactor deployment.
Asia-Pacific Nuclear Power Plant and Equipment Market Competitive Environment
State-affiliated heavy engineering groups and specialized nuclear fabricators split the market between turnkey reactor delivery and component supply. The vendor base concentrates among entities with forged nuclear qualification credentials and seismic certification capabilities. Two archetypes dominate: integrated reactor vendors controlling technology licensing and export protocols, and component specialists capturing replacement part cycles and maintenance services. Competitive positioning hinges on securing national regulator qualifications and anchoring long-term service contracts with state utilities.
Within the integrated vendor tier, China General Nuclear Power Corporation and Korea Hydro & Nuclear Power Co., Ltd. occupy positions as state-backed reactor exporters with captive technology platforms. Shanghai Electric Group Company Limited represents the component-specialist archetype, anchoring domestic supply chains for turbine generators and auxiliary systems. These three entities exemplify the geographic bifurcation between Chinese state-owned consolidation and South Korean technology-transfer competitiveness.
| Leading Market Players |
|---|
| China General Nuclear Power Corporation |
| Shanghai Electric Group Company Limited |
| Korea Hydro & Nuclear Power Co., Ltd. |
| Doosan Enerbility |
| Larsen & Toubro Limited |
| Dongfang Electric Corporation Limited |
| GE-Hitachi Nuclear Energy |
| Framatome |
| Mitsubishi Heavy Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta heavy forging cluster concentrates reactor pressure vessel capacity, granting its operators substantial leverage over equipment pricing for state-backed utilities across China and export markets. This geographic concentration compresses procurement timelines while elevating premiums for seismic-qualified components that meet Japan's post-Fukushima stress test protocols.
Pricing Analysis
GB standards enforcement dictates the pricing tier structure across the Asia-Pacific nuclear equipment market. Three-tier pricing structure across premium, standard, and economy levels separates safety-grade seismic-qualified systems from commodity auxiliary components, with certification grade and volume scale serving as primary price differentiation drivers. Cost compression in standard-tier auxiliary equipment is intensifying because Chinese state-owned utilities consolidate procurement under compressed construction schedules. State-owned power companies demonstrate lowest price sensitivity due to policy-mandated capacity targets, while independent contractors in Southeast Asia exhibit highest sensitivity to total installed cost.
Supply Chain Analysis
Export control regimes limiting nuclear technology flows constrain cross-border equipment transfers and fragment supplier relationships across national boundaries. Manufacturing concentrates in China, South Korea, and Japan, with heavy forging capacity drawing from specialized steel alloys, precision casting capabilities, and seismic certification expertise. Single-source vulnerability runs through qualified reactor pressure vessel forgers capable of meeting GB standards and Japan's Nuclear Regulation Authority requirements. Distribution runs through state utility procurement departments that unbundle long-term service contracts from initial equipment supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against accelerating renewable energy plus storage combinations that threaten baseload nuclear economics. Incumbents must demonstrate cost and reliability advantages against these emerging alternatives.
For Market Incumbents: Insulate core revenue streams by anchoring long-term service contracts with predictive analytics and spare parts logistics for operating license renewals in South Korea and Japan. Deepen backward integration into heavy forging capacity to reduce exposure to supply bottlenecks for reactor pressure vessels. Secure dual certification under GB standards and Japan's post-Fukushima protocols to maintain cross-border competitiveness.
For New Entrants and Emerging Players: Industrial heat applications in remote mining operations and island grids across Indonesia and the Philippines represent the most penetrable entry point for Advanced Modular Reactor component suppliers. Maintenance services for aging coolant pumps and control rod mechanisms in Japan's restarted fleet offer recurring revenue without competing on initial reactor construction. Partner with established heavy engineering groups to access forged nuclear qualification credentials.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with captive maintenance service relationships and seismic certification capabilities over pure-play reactor vendors exposed to construction cycle volatility. Long-term viability rests on recurring revenue streams from plant life extensions rather than greenfield project dependence. Watch for regulatory divergence between national safety frameworks and International Atomic Energy Agency harmonization pressures as an inflection indicator for cross-border equipment qualification costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Certification Investment | Dual qualification under GB standards and Japan's Nuclear Regulation Authority protocols opens cross-border procurement. |
| Predictive Maintenance Platform | Digital instrumentation integration with legacy mechanical systems captures recurring revenue from state-owned utilities. |
| Heavy Forging Capacity Expansion | Domestic reactor pressure vessel manufacturing reduces supply bottlenecks for compressed construction schedules. |
| APR1400 Technology Licensing | Korea Hydro & Nuclear Power's export protocol generates demand for South Korean heavy forging and project delivery. |
| Industrial Heat Partnership | Advanced Modular Reactor deployment for steel and chemical plants creates remote baseload demand outside grid interconnect. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, EPC contractors, nuclear safety regulators, and heavy engineering procurement leads; and secondary validation against International Atomic Energy Agency safety standards documentation, national regulatory filings with China's National Nuclear Safety Administration and Japan's Nuclear Regulation Authority, reactor construction databases, and customs trade records for heavy forged components. Bottom-up equipment procurement tracking and top-down energy capacity modeling were triangulated to ensure consistency.
Forecast inputs considered reactor lifecycle stage, technology type, regulatory maturity tier, and end-user procurement scale across the projection horizon. Segmentation dimensions modeled include equipment type, reactor technology, service category, and national regulatory framework. CAGRs were derived from equipment delivery schedules tied to state-backed reactor programs and operating license renewal timelines. Industry-specific inputs encompass seismic qualification requirements, heavy forging capacity utilization, and technology transfer protocol activation.
Practitioners should monitor regulatory divergence between national safety frameworks and International Atomic Energy Agency harmonization pressures for early signals of equipment qualification cost shifts. Forecasts reflect assumptions regarding state utility procurement continuity, heavy forging capacity expansion, and restart approval pacing in Japan. Material shifts in renewable energy cost competitiveness or nuclear regulatory suspension would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Nuclear Decommissioning Services Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Energy Market
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
North America Nuclear Reactor Construction Market