
 Nuclear Powered Merchant Vessel Market | 2026-2036
Nuclear Powered Merchant Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Powered Merchant Vessel Market Analytics
Small modular reactor fuel systems are repositioning vessel economics away from conventional marine diesel architectures. China State Shipbuilding Corporation leverages its state-backed R&D pipeline to anchor prototype development timelines. Mitsubishi Heavy Industries sustains decades of naval reactor experience to differentiate its commercial offerings. Babcock & Wilcox competes through specialized pressure vessel fabrication capabilities.
A nuclear powered merchant vessel integrates a contained fission reactor—typically pressurized water or small modular designs generating 50–300 MW thermal—into a hull structure to produce shaft power or electrical propulsion without hydrocarbon combustion. The primary purpose is eliminating carbon dioxide and sulfur oxide emissions from transoceanic cargo movement while extending refueling intervals to 10–25 years. Container ships dominate current engineering studies due to route predictability and high-value cargo profiles, while tankers represent a growing segment as crude carriers face mounting decarbonization deadlines. Small modular reactor configurations attract the most design investment because their factory fabrication and modular installation reduce yard time and radiation exposure risks.
The International Maritime Organization's Energy Efficiency Existing Ship Index shapes newbuild specifications and retrofit timelines for nuclear alternatives. The International Atomic Energy Agency's safety standards govern reactor licensing for maritime deployment, while flag state regulators like Lloyd's Register and the American Bureau of Shipping develop classification rules for floating nuclear systems. Classification societies must resolve liability frameworks before commercial orders accelerate beyond demonstration projects.
Market Dynamics
The International Maritime Organization's carbon intensity regulations are compressing vessel design cycles and forcing shipowners toward zero-emission propulsion architectures that eliminate hydrocarbon combustion entirely.
Growth Catalysts
- IMO Carbon Intensity Regulations:The Energy Efficiency Existing Ship Index mandates emission reductions that nuclear propulsion satisfies without fuel switching or exhaust treatment systems.
- Small Modular Reactor Maturation:Factory-fabricated reactor units reduce construction radiation exposure and compress yard installation schedules compared to bespoke naval designs.
- East Asian Shipbuilding Clusters:Concentrated engineering talent in South Korea's Ulsan and Geoje districts enables integrated reactor-hull design workflows.
Market Restraints
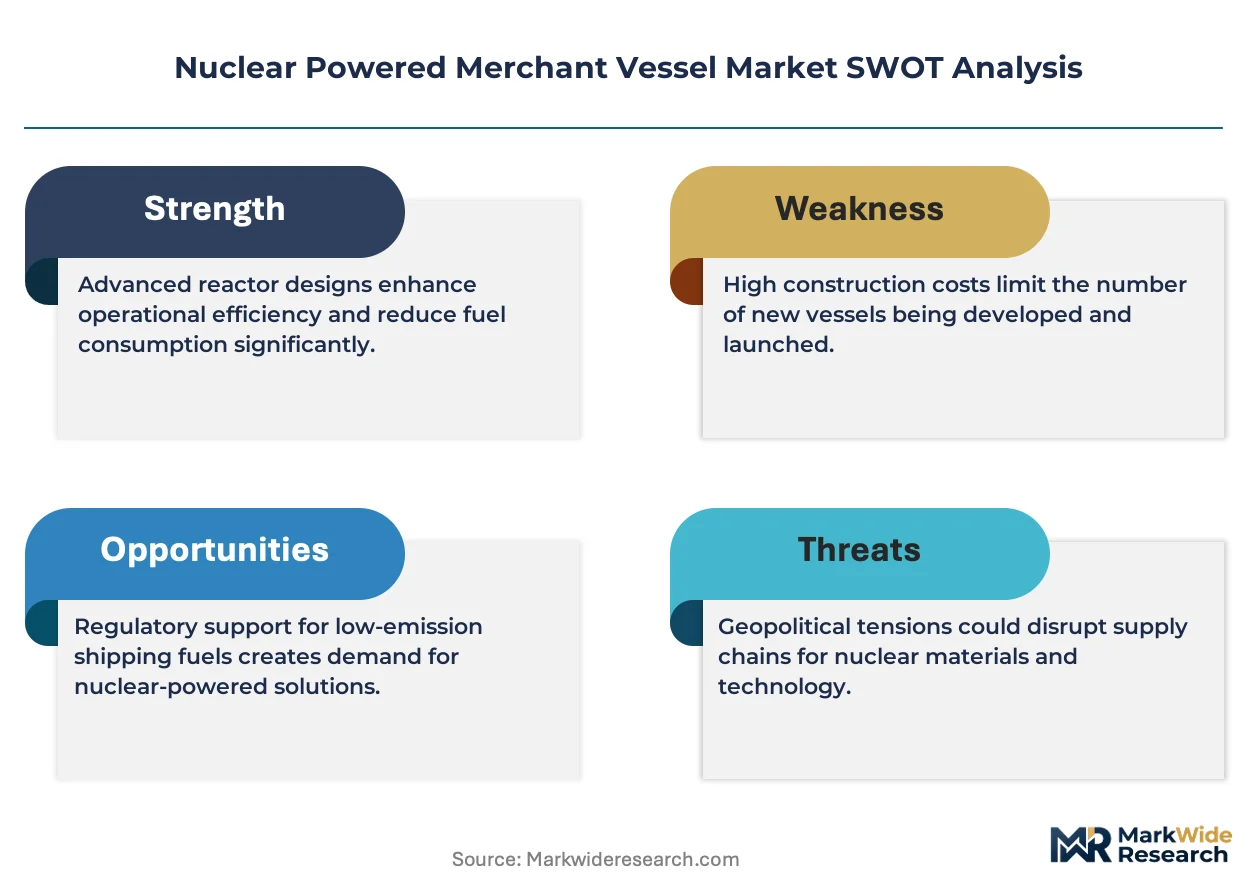
- Classification Liability Gaps:Lloyd's Register and American Bureau of Shipping have not finalized insurance frameworks for floating nuclear systems, freezing commercial financing.
- Reactor Fuel Supply Concentration:High-assay low-enriched uranium fabrication depends on a handful of certified suppliers, creating single-source vulnerability.
- Port Access Restrictions:Multiple coastal jurisdictions prohibit nuclear vessel entry under environmental statutes, constraining route flexibility.
Strategic Opportunities
- Arctic Route Containerization:Russia's Northern Sea Lane and Canada's Northwest Passage offer year-round navigation for ice-class nuclear vessels with minimal refueling infrastructure.
- Green Corridor Mandates:The Clydebank Declaration signatories are designating zero-emission shipping lanes where nuclear propulsion qualifies for preferential port fees.
- Reactor-Electric Hybrid Architectures:Coupling small modular reactors with battery buffers enables peak shaving and redundant propulsion for high-value cargo segments.
Industry Challenges
- Maritime Nuclear Licensing Expertise:Flag state regulators lack sufficient surveyors trained in pressurized water reactor inspection protocols, extending certification timelines.
- Crew Radiation Safety Training:International Convention on Standards of Training, Certification and Watchkeeping for Seafarers does not yet mandate nuclear-specific competencies.
- Decommissioning Liability Allocation:Shipowners and reactor vendors dispute end-of-life core removal responsibilities and radioactive waste custody chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Powered Merchant Vessel Market |
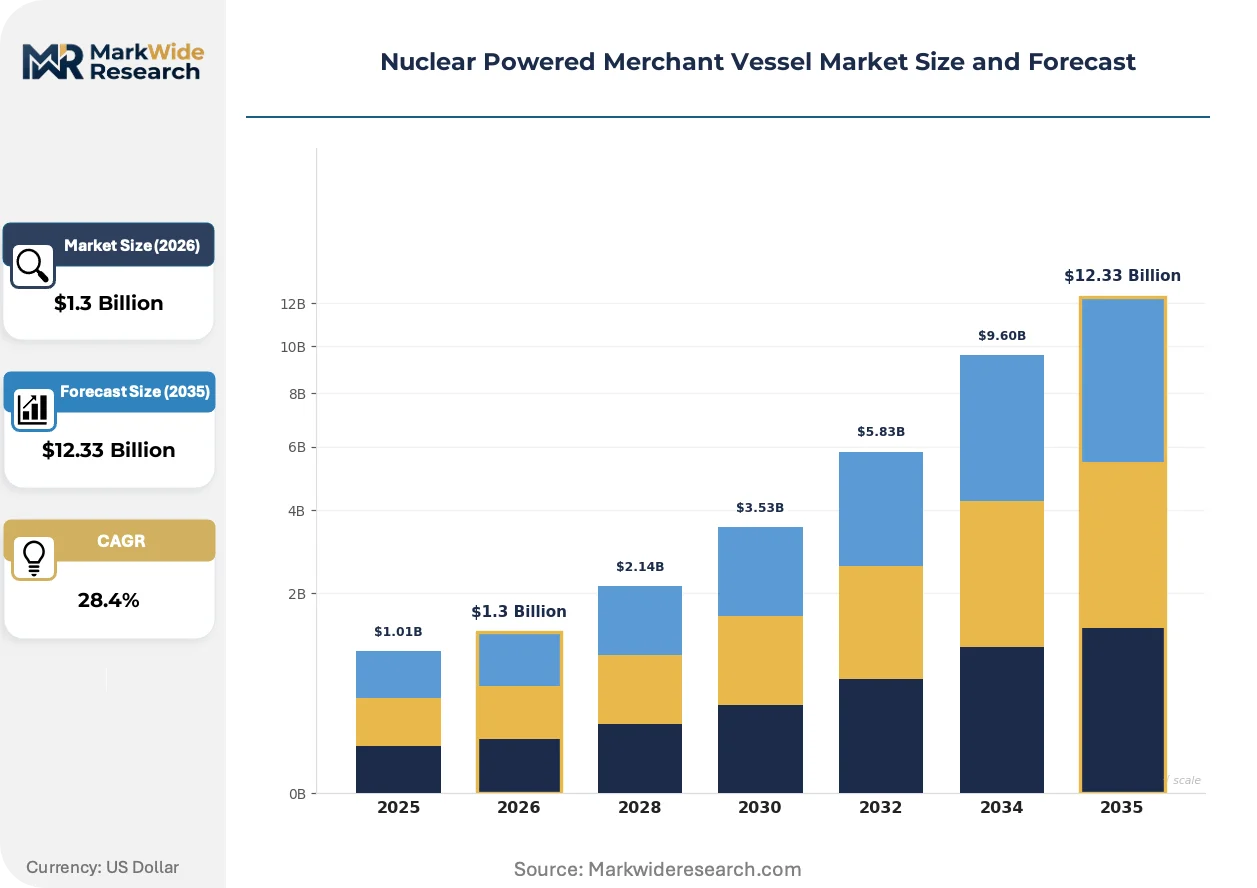
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $12.33 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Container Ships, Bulk Carriers, Tankers, Research Vessels Power Source: Pressurized Water Reactor, Boiling Water Reactor, Small Modular Reactor, High-Temperature Gas Reactor Operational Application: Commercial Shipping, Research Missions, Cargo Transport, Offshore Operations End User: Shipping Companies, Government Agencies, Research Institutions, Energy Corporations |
| Companies Covered | Adams Atomic Engines, Babcock & Wilcox, Howaldtswerke Deutsche Werft AG, Yokosuka Naval Arsenal, United Shipbuilding Corporation, Austal, China State Shipbuilding Corporation, Kawasaki Heavy Industries, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Powered Merchant Vessel Market Evolving Landscape
Reactor miniaturization and modular construction methods are collapsing the capital cost gap between nuclear and conventional marine propulsion while accelerating regulatory acceptance timelines.
Lead-cooled fast reactor designs are absorbing thermal management requirements for high-power density propulsion without the pressure vessel mass of light-water alternatives. Container lines evaluating long-haul Pacific routes favor these configurations for their compact footprint and passive safety characteristics. The technology is absorbing risk capital from naval engineering firms seeking commercial diversification.
The European Union's inclusion of maritime transport within its emissions trading system creates direct carbon cost exposure for conventional fuel consumers. Shipowners now face incremental compliance expenses that nuclear alternatives eliminate entirely. Mediterranean and Baltic operators are restructuring fleet renewal schedules to align with EU Green Deal implementation phases.
Charter contracts are incorporating emission performance clauses that penalize sulfur oxide and carbon dioxide exceedances. Container shippers with science-based targets are specifying zero-emission vessel requirements in procurement tenders. This specification pressure concentrates among East Asian electronics manufacturers moving high-value components across transoceanic lanes.
Nuclear Powered Merchant Vessel Market Segmentation
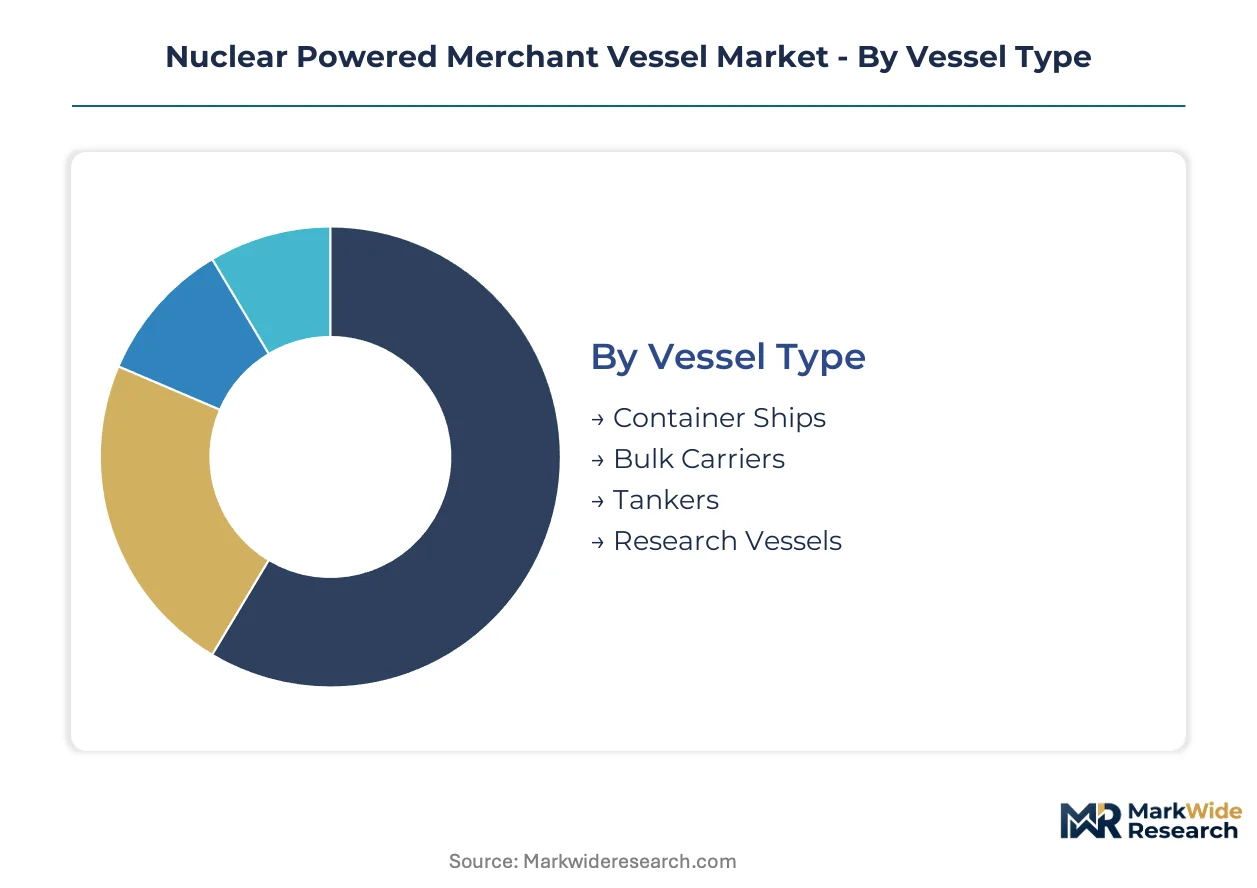
Vessel architecture and reactor configuration determine capital deployment, regulatory pathway, and operational economics for nuclear merchant fleets. Segment boundaries reflect engineering maturity, fuel supply constraints, and port access permissions that shape procurement decisions.
Vessel Type:
Upgrade cycles for existing hull designs are accelerating as IMO carbon intensity deadlines approach, with shipowners evaluating nuclear retrofits against newbuild alternatives.
- Container Ships:Standardized cargo holds and predictable route schedules accommodate reactor shielding requirements and fixed refueling intervals. East Asian electronics manufacturers moving high-value components across Pacific lanes are concentrating procurement specifications here.
- Tankers:Crude carriers face mounting decarbonization deadlines with fewer technical alternatives than container lines. Arctic crude transport routes favor ice-class nuclear tankers with minimal refueling infrastructure.
- Bulk Carriers:Lower cargo value per ton constrains capital allocation for reactor installation.
- Research Vessels:Government-funded scientific missions absorb demonstration reactor risks for unproven designs.
Container ships sit at the top of the volume ranking, with tankers climbing the fastest as crude carriers exhaust conventional compliance pathways.
Power Source:
Reactor cost tiers separate factory-fabricated modular units from bespoke naval-derived systems with extended certification timelines.
- Small Modular Reactor:Factory fabrication reduces yard radiation exposure and compresses installation schedules. South Korea's Ulsan shipbuilding cluster anchors prototype deployment for this configuration.
- Pressurized Water Reactor:Decades of naval operational data de-risk licensing for commercial adaptation. Mitsubishi Heavy Industries leverages this heritage for commercial offerings.
- Boiling Water Reactor:Simplified steam cycle reduces auxiliary system mass for weight-constrained hulls.
- High-Temperature Gas Reactor:Helium coolant enables higher thermal efficiency for long-haul routes with minimal refueling.
Small modular reactors dominate capital deployment, with high-temperature gas designs gaining share fastest among next-generation demonstration projects.
Operational Application:
Application-specific duty cycles determine reactor sizing, with continuous-operation profiles justifying higher capital intensity than intermittent deployment.
- Commercial Shipping:Container lines and bulk operators evaluate nuclear propulsion for transoceanic lanes with minimal port calls. EU emissions trading system inclusion creates direct carbon cost exposure that nuclear alternatives eliminate.
- Cargo Transport:Charter contracts incorporating emission performance clauses penalize sulfur oxide and carbon dioxide exceedances, shifting specification pressure toward zero-emission architectures.
- Research Missions:Extended autonomous operations in remote ocean regions absorb higher reactor complexity for self-sufficiency.
- Offshore Operations:Stationary power generation for drilling platforms competes with floating nuclear alternatives.
Commercial shipping commands the largest addressable base, with cargo transport expanding most quickly as charter contract clauses harden.
End User:
Customer type dictates risk tolerance, procurement timeline, and access to sovereign liability guarantees that commercial financiers require.
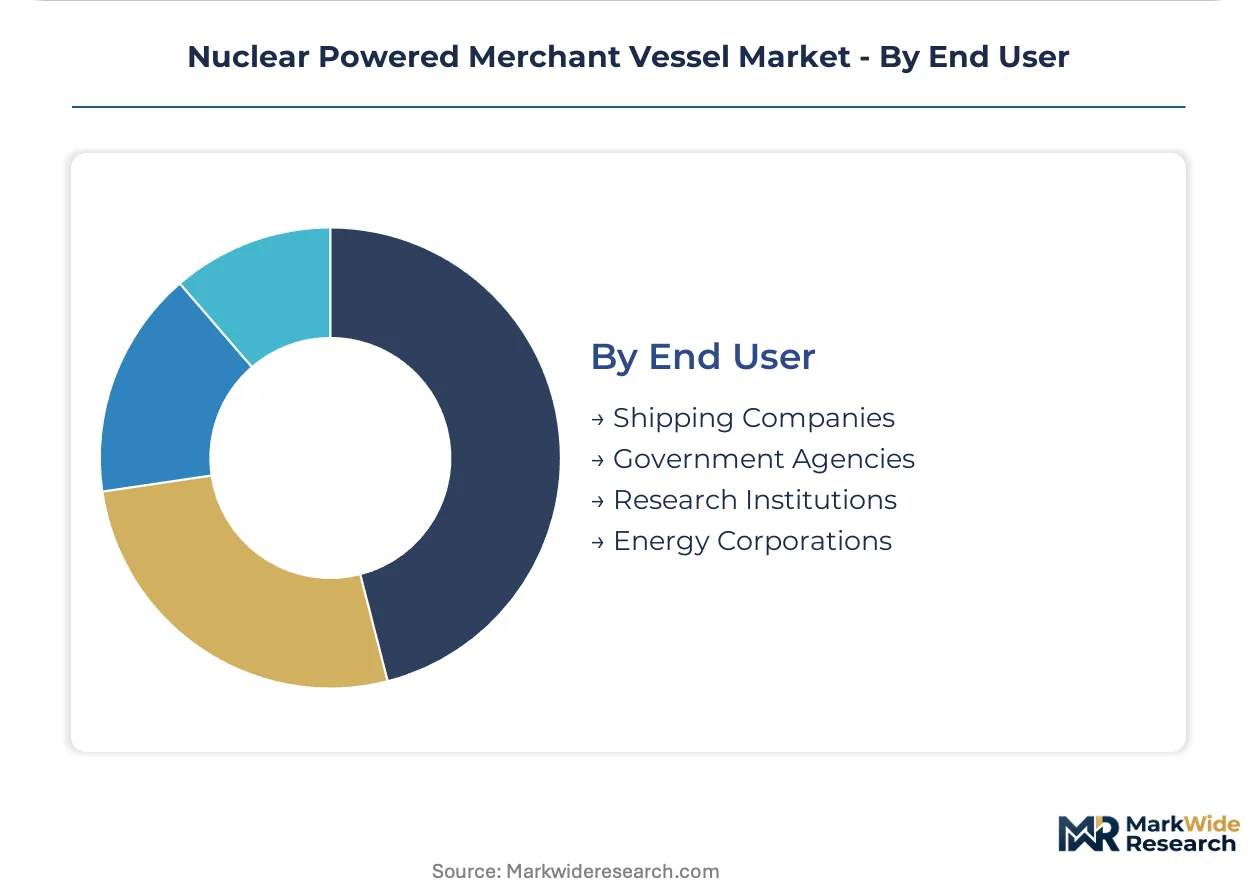
- Shipping Companies:Container lines in East Asia evaluate nuclear propulsion for long-haul Pacific routes with science-based emission targets. Procurement tenders increasingly specify zero-emission vessel requirements.
- Government Agencies:Naval engineering firms seek commercial diversification through state-backed demonstration projects with de-risked licensing pathways.
- Research Institutions:Oceanographic organizations absorb prototype reactor risks for extended autonomous mission profiles.
- Energy Corporations:Integrated oil and gas majors evaluate floating nuclear for offshore platform power with captive demand.
Shipping companies anchor current engineering studies, with government agencies climbing fastest as sovereign liability frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ulsan and Geoje anchor South Korea's nuclear vessel engineering concentration, with China's state-backed shipbuilders and Japan's heavy industrial conglomerates forming the tripartite East Asian cluster driving prototype development.
South Korea
Container lines evaluating Pacific routes drive reactor-hull integration demand. The Ministry of Oceans and Fisheries supports demonstration projects through sovereign liability frameworks. Ulsan and Geoje districts concentrate integrated design workflows for small modular reactor installation.
China
State-backed R&D pipelines accelerate prototype timelines for commercial deployment. The Ministry of Industry and Information Technology governs nuclear equipment certification under national standards. Shanghai and Dalian shipyards coordinate reactor vendor partnerships for export-oriented construction.
Japan
Mitsubishi Heavy Industries leverages naval reactor heritage for commercial differentiation. The Ministry of Economy, Trade and Industry oversees maritime nuclear licensing alignment with IAEA protocols. Nagasaki and Kobe industrial zones sustain pressure vessel fabrication capabilities for next-generation designs.
United States
Babcock & Wilcox competes through specialized pressure vessel fabrication for modular units. The Nuclear Regulatory Commission and Coast Guard coordinate floating reactor oversight with classification societies. Virginia and Ohio manufacturing corridors supply high-assay low-enriched uranium handling infrastructure.
Russia
Arctic route containerization creates captive demand for ice-class nuclear propulsion. Rosatom's nuclear icebreaker program provides operational data for commercial adaptation. Saint Petersburg and Murmansk ports develop refueling infrastructure for year-round Northern Sea Lane navigation.
Nuclear Powered Merchant Vessel Market Competitive Landscape
Global majors compete with regional champions across reactor-hull integration capabilities, with consolidated engineering expertise concentrated among naval-derived industrial conglomerates and emerging modular specialists. The vendor base stratifies between state-backed shipbuilders with sovereign R&D pipelines and private fabricators with classification society partnerships. Three archetypes dominate: naval heritage converters, modular reactor pure-plays, and diversified heavy industrial groups. Capacity expansion and strategic technology licensing represent the primary competitive vectors as yard schedules compress.
Within the naval heritage converter tier, Mitsubishi Heavy Industries and Babcock & Wilcox exemplify the pressure vessel fabrication and reactor operational data advantages that accelerate commercial licensing timelines. China State Shipbuilding Corporation occupies a distinct position as a state-backed integrator with captive demand from domestic container lines. Howaldtswerke Deutsche Werft AG represents European submarine-builder adaptation toward commercial surface vessel applications.
| Leading Market Players |
|---|
| Adams Atomic Engines |
| Babcock & Wilcox |
| Howaldtswerke Deutsche Werft AG |
| Yokosuka Naval Arsenal |
| United Shipbuilding Corporation |
| Austal |
| China State Shipbuilding Corporation |
| Kawasaki Heavy Industries |
| Mitsubishi Heavy Industries |
| Others |
Value Network & Pricing Analysis
Captive integration of reactor fuel fabrication with shipyard assembly sequences anchors both procurement positioning and contract pricing power for nuclear vessel builders. South Korea's Ulsan cluster and China's state-backed yards leverage this vertical control to compress installation timelines and capture premium positioning on long-haul container specifications.
Pricing Analysis
High-assay low-enriched uranium fabrication costs pass through directly to vessel procurement contracts, compressing margins for shipyards without captive fuel partnerships. Pricing stratifies across naval heritage premium, modular standard, and demonstration economy tiers based on certification maturity and operational data depth. Cost compression in the standard tier is intensifying as Chinese state-backed yards absorb R&D subsidies into export pricing. Container lines with science-based emission targets demonstrate lowest price sensitivity, while bulk operators remain most responsive to capital cost differentials.
Supply Chain Analysis
Reverse-logistics for spent fuel removal and reactor vessel decommissioning constrains route planning and terminal partnerships for nuclear merchant fleets. Primary fabrication concentrates in South Korea, China, and Japan, with secondary module assembly emerging in the United States. The supply chain draws from specialized pressure vessel steel, certified uranium enrichment services, and cryogenic coolant systems. Single-source vulnerability in HALEU fabrication creates structural risk for delivery schedules. Distribution runs through sovereign liability frameworks rather than conventional commercial financing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nuclear powered merchant vessel market compounds steadily as the International Maritime Organization's carbon intensity regulations eliminate hydrocarbon alternatives for transoceanic routes. This regulatory ratchet provides durable demand visibility across vessel replacement cycles.
For Market Incumbents: To counter emerging modular reactor pure-plays, Mitsubishi Heavy Industries and Babcock & Wilcox should deepen naval operational data moats through classification society partnerships that accelerate commercial licensing timelines. Capacity addition in South Korea's Geoje district preserves yard slot access for integrated reactor-hull contracts. Certification investment in International Atomic Energy Agency safety standards reinforces differentiation against state-backed competitors. For New Entrants and Emerging Players: Launch via sovereign-backed demonstration projects that absorb first-of-kind licensing risk through government liability guarantees. Arctic route containerization offers the most penetrable white-space as Russia's Northern Sea Lane infrastructure matures. Target research vessel applications where government funders tolerate extended certification timelines and prototype reactor complexity. For Investors and Strategic Acquirers: Roll-up economics work for naval heritage engineering firms because reactor operational data scarcity creates durable competitive moats that compound across certification cycles. Five-to-ten year viability hinges on classification society liability framework resolution rather than technology maturation. Monitor Lloyd's Register and American Bureau of Shipping rule finalization as the critical inflection signal for commercial financing unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Small Modular Reactor Certification | International Atomic Energy Agency safety standard alignment accelerates flag state licensing timelines for commercial deployment. |
| Arctic Route Infrastructure Partnership | Rosatom icebreaker operational data transfer enables ice-class nuclear vessel adaptation for year-round Northern Sea Lane navigation. |
| Reactor-Electric Hybrid Architecture | Coupling small modular reactors with battery buffers addresses peak shaving requirements for high-value cargo segments. |
| Sovereign Liability Framework Development | South Korea's Ministry of Oceans and Fisheries demonstration projects de-risk commercial financing for private shipowners. |
| High-Assay Low-Enriched Uranium Supply Agreement | Long-term fuel fabrication contracts with certified suppliers mitigate single-source vulnerability in reactor deployment schedules. |
Research Methodology
Multiple input streams — classification society technical filings, shipyard order book tracking, and reactor vendor partnership announcements — were reconciled against primary interviews with naval engineering directors, maritime regulatory affairs leads, shipowner fleet planning officers, and port authority infrastructure planners. Secondary validation drew from International Maritime Organization circulars, International Atomic Energy Agency safety standards, Lloyd's Register classification rules, and flag state licensing databases. Bottom-up vessel deployment modeling and top-down carbon intensity compliance demand estimates were triangulated to anchor market sizing.
Historical deployment patterns for naval nuclear propulsion were cross-referenced against expert panel assessments of commercial adaptation timelines. Segmentation modeling spanned vessel architecture, reactor configuration, operational application, and end-user risk tolerance across the projection horizon. CAGRs were derived from installation schedule compression assumptions and regulatory deadline alignment. Forecast inputs included small modular reactor factory fabrication capacity expansion, port access restriction evolution, and sovereign liability framework maturation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under classification society rule delays or HALEU supply disruptions. Practitioners should monitor International Atomic Energy Agency maritime safety standard revisions and Lloyd's Register floating nuclear system certification progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Fusion Power Market
Nuclear Energy
Nuclear Energy Market
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Small Modular Reactor (SMR) Market
Nuclear Energy
Thorium Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Global Power Plant Uranium Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Nuclear Power Market