
 Asia-Pacific Nuclear Power Reactor Decommissioning Market | 2026-2036
Asia-Pacific Nuclear Power Reactor Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nuclear Power Reactor Decommissioning Market Outlook
Project finance structures with long-dated government-backed repayment guarantees is reconfiguring competitive entry in Asia-Pacific reactor decommissioning. Hitachi-GE Nuclear Energy leverages its integrated engineering heritage to anchor large-scale dismantling contracts in Japan. Korea Hydro & Nuclear Power Co. dominates domestic decommissioning planning through its captive utility relationship with state regulators. Orano competes on specialized waste conditioning technology, extending its European expertise into Asian markets through joint venture structures.
Asia-Pacific nuclear power reactor decommissioning encompasses the engineered dismantling, radioactive waste processing, and site restoration of retired fission reactors, typically involving concrete biological shield segmentation, reactor vessel segmentation using thermal or mechanical cutting, and spent fuel pool drainage over multi-decade timelines. The primary purpose is to return licensed nuclear sites to brownfield or greenfield status for unrestricted future use. Waste management services currently command the largest revenue share given the decades-long stewardship burden for intermediate and high-level waste streams, while robotics technology represents the fastest-expanding segment as operators deploy remotely operated platforms to reduce worker radiation exposure in confined reactor containment zones. Site rehabilitation remains comparatively mature, with margin pools concentrated in regulatory compliance advisory services where specialist consultants navigate multi-jurisdictional licensing.
Japan's Nuclear Regulation Authority, South Korea's Nuclear Safety and Security Commission, and Australia's ARPANSA collectively shape decommissioning demand through divergent spent fuel custody rules, worker dose limits, and site release criteria that dictate project scope and duration. Japan's post-Fukushima regulatory tightening has extended mandatory cooling periods before dismantling commencement, directly inflating project management and waste storage service requirements. Stakeholders must monitor how bilateral agreements on cross-border radioactive waste transfer evolve, as domestic storage capacity constraints in Japan and South Korea may force fundamental decisions on international repository access or advanced reprocessing investments.
Market Dynamics
Japan's post-Fukushima regulatory tightening has extended mandatory cooling periods before dismantling commencement, directly inflating project management and waste storage service requirements across the Asia-Pacific reactor decommissioning pipeline.
Growth Catalysts
- Japan's Nuclear Regulation Authority oversight:Extended cooling period mandates create sustained demand for interim waste storage and site monitoring services throughout multi-decade decommissioning timelines.
- Spent fuel reprocessing investments:South Korea's pursuit of domestic pyroprocessing capabilities is generating ancillary decommissioning engineering demand as reactor fleets age in parallel.
- Robotics deployment in confined containment zones:Remotely operated platforms for reactor vessel segmentation reduce worker dose exposure and accelerate dismantling schedules in high-radiation environments.
Market Restraints
- Specialized workforce scarcity:Japan and South Korea face acute shortages of certified radiation protection technicians and reactor segmentation engineers, constraining project throughput.
- Domestic intermediate-level waste storage saturation:Site capacity limitations in Fukushima and Tsuruga prefectures force costly on-site construction of additional engineered barrier facilities.
- Cross-border waste transfer prohibitions:Bilateral agreement gaps block access to international geological repositories, trapping high-level waste in expensive interim custody arrangements.
Strategic Opportunities
- Australian nuclear medicine reactor conversion:ANSTO's aging OPAL facility and legacy HIFAR site rehabilitation create first-mover openings for Asia-Pacific decommissioning consortia.
- Digital twin integration with robotics:Convergence of 3D laser scanning and predictive containment modeling enables pre-segmentation planning that compresses reactor vessel dismantling schedules.
- Extended producer responsibility frameworks:South Korea's emerging waste generator liability statutes will mandate utility-funded decommissioning reserves, locking in long-dated service contracts.
Industry Challenges
- Multi-jurisdictional licensing complexity:Decommissioning contractors must navigate divergent site release criteria between Japan's Nuclear Regulation Authority and South Korea's Nuclear Safety and Security Commission, fragmenting project execution protocols.
- Legacy spent fuel pool integrity:Corrosion assessment and seismic retrofitting of 1970s-era storage infrastructure at Tsuruga and Fukushima Daiichi sites demands unbudgeted engineering interventions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nuclear Power Reactor Decommissioning Market |
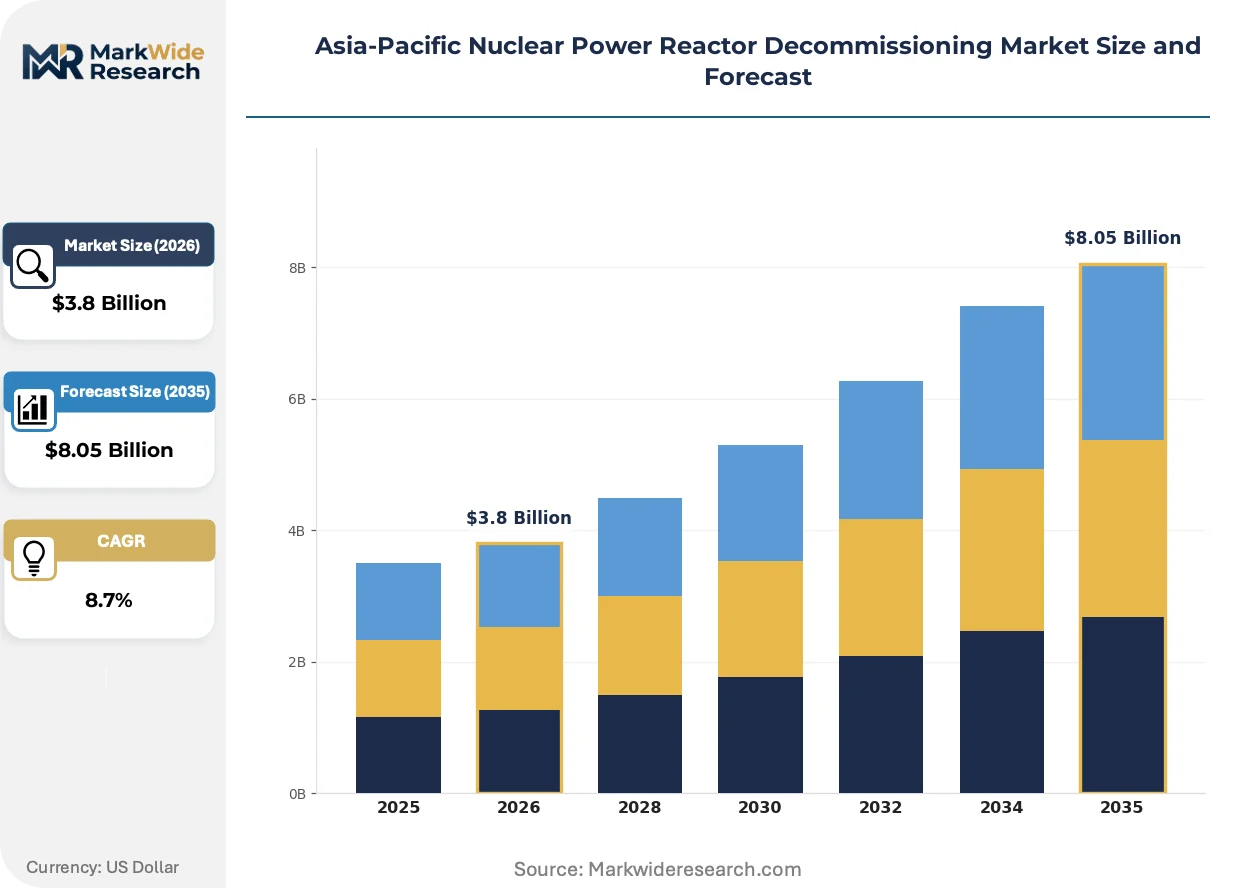
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Project Management, Waste Management, Site Rehabilitation, Regulatory Compliance Technology: Robotics, Segmentation, Dismantling, Remote Handling End User: Government Agencies, Utility Companies, Environmental Organizations, Contractors Waste Type: Low-Level Waste, Intermediate-Level Waste, High-Level Waste, Spent Fuel |
| Companies Covered | Hitachi-GE Nuclear Energy, Japan Atomic Power Co., Tokyo Electric Power Company Holdings, Korea Hydro & Nuclear Power Co., Babcock International Group PLC, GE Hitachi Nuclear Energy, Fluor Corporation, AECOM, Orano, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nuclear Power Reactor Decommissioning Market Strategic Shifts
Remote operations technology is compressing human exposure windows while regulatory digitization is accelerating compliance verification cycles across Asia-Pacific decommissioning programs.
Digital twin technology is virtualizing reactor containment modeling by creating real-time 3D representations of biological shield degradation and vessel segmentation progress. Japan's decommissioning contractors are deploying these platforms at Fukushima Daiichi to coordinate multi-vessel dismantling sequences. This virtualization is compressing pre-work planning cycles from months to weeks while enabling predictive maintenance of cutting equipment in high-radiation zones.
South Korea's Nuclear Safety and Security Commission has mandated real-time radiation monitoring data submission through centralized digital portals, eliminating paper-based dose recordkeeping for decommissioning workers. This regulatory digitization is forcing utility operators to retrofit legacy monitoring infrastructure at Kori and Wolsong sites. Waste management service providers are responding by integrating blockchain-verified custody chains for intermediate-level waste drum tracking.
Utility procurement departments are unbundling decommissioning service contracts into discrete work packages spanning segmentation, waste conditioning, and site restoration rather than awarding integrated turnkey agreements. This disintermediation of traditional engineering-procurement-construction arrangements is fragmenting vendor relationships at Japan's Tokyo Electric and Korea Hydro & Nuclear Power. South Korea's state utility is most visibly advancing this model, creating openings for specialized robotics firms and waste conditioning specialists to compete outside established consortium structures.
Asia-Pacific Nuclear Power Reactor Decommissioning Market Segmentation
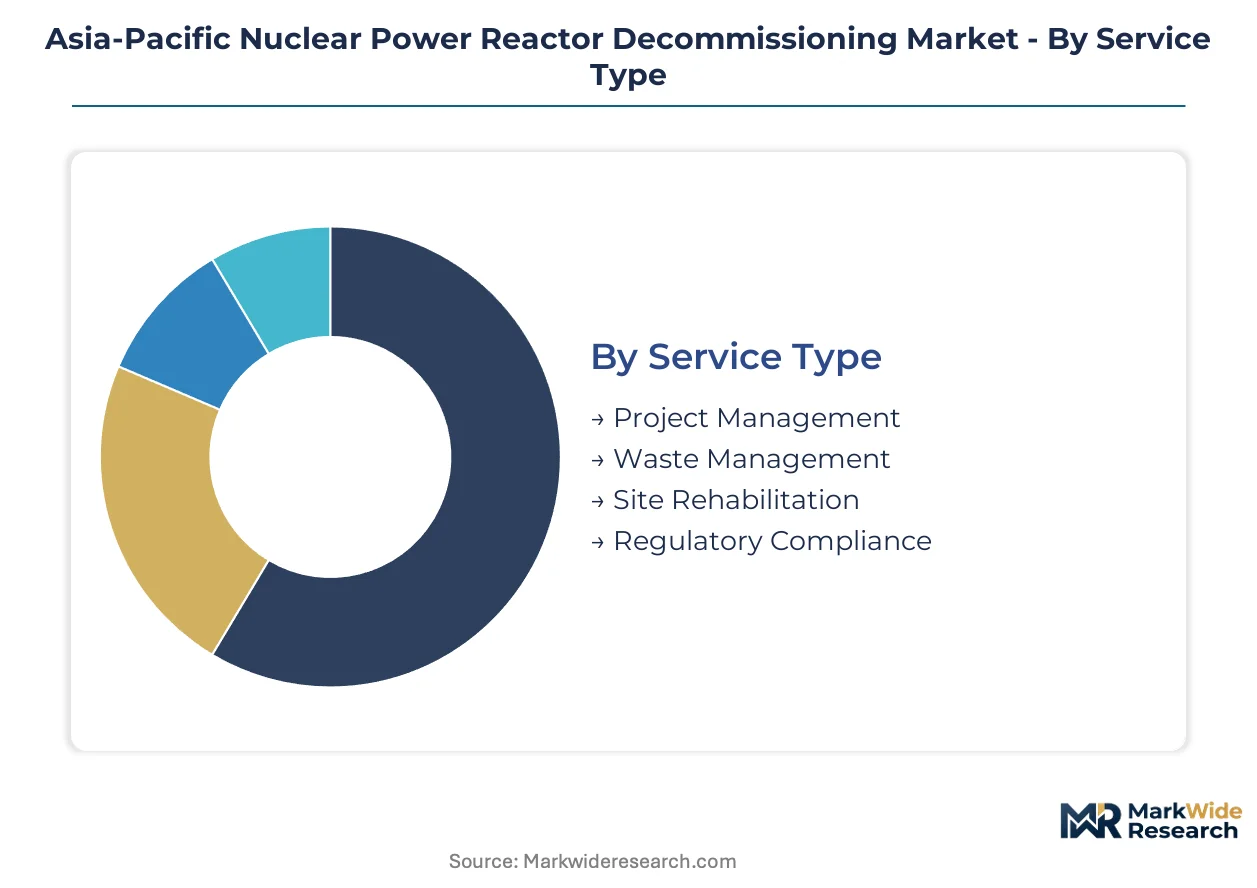
Decommissioning procurement in the Asia-Pacific region fragments across service specializations, technology platforms, waste classifications, and stakeholder types. Each segmentation dimension carries distinct margin profiles and regulatory exposure that shape vendor selection criteria.
Service Type:
Maturity varies sharply across the service spectrum, with legacy disciplines commanding established revenue pools while emerging specializations reshape competitive entry.
- Waste Management:Decades-long stewardship obligations for intermediate and high-level waste streams generate recurring revenue through engineered barrier construction, spent fuel pool drainage, and dry cask storage operations. Demand concentrates in Japan's Fukushima and Tsuruga prefectures where domestic storage capacity constraints force costly on-site facility expansion.
- Project Management:Multi-decade decommissioning timelines require integrated scheduling, contractor coordination, and regulatory interface management across segmented work packages. South Korea's Korea Hydro & Nuclear Power Co. is unbundling traditional turnkey contracts into discrete procurement lots, fragmenting vendor relationships and creating openings for specialized project controls firms.
- Site Rehabilitation:Brownfield and greenfield restoration encompasses soil remediation, groundwater monitoring, and license termination support. Japan's Nuclear Regulation Authority mandates extended cooling periods before site release, inflating long-term monitoring service requirements.
- Regulatory Compliance:Multi-jurisdictional licensing advisory spans dose limit documentation, environmental impact assessments, and cross-border waste transfer permitting.
Waste Management retains volume leadership; Project Management holds the steepest expansion curve as unbundled procurement accelerates.
Technology:
Technology selection maps directly to radiation exposure reduction imperatives and containment geometry constraints.
- Robotics:Remotely operated platforms for reactor vessel segmentation and biological shield dismantling compress human exposure windows in high-radiation zones. Deployment concentrates at Fukushima Daiichi where multi-vessel sequences demand predictive equipment maintenance.
- Segmentation:Thermal and mechanical cutting systems for concrete biological shields and reactor pressure vessels require pre-work planning cycles now compressed through digital twin integration.
- Dismantling:Large-component removal and structural demolition operations employ conventional heavy equipment modified for radiological environments.
- Remote Handling:Master-slave manipulators and teleoperated tooling extend human reach into confined containment geometries without breaching radiological barriers.
Robotics commands premium pricing; Remote Handling is climbing fastest as containment access challenges intensify.
End User:
Procurement authority concentrates with utility operators while regulatory oversight shapes specification requirements.
- Utility Companies:Tokyo Electric and Korea Hydro & Nuclear Power Co. anchor decommissioning demand as captive owners of aging reactor fleets approaching end-of-life. South Korea's emerging extended producer responsibility frameworks will mandate utility-funded decommissioning reserves.
- Government Agencies:Japan's Nuclear Regulation Authority and South Korea's Nuclear Safety and Security Commission dictate compliance timelines, worker dose limits, and site release criteria that directly inflate project scope.
- Contractors:Specialized segmentation engineers, waste conditioning technicians, and robotics operators compete for unbundled work packages outside traditional consortium structures.
- Environmental Organizations:Stakeholder monitoring and public transparency requirements influence site restoration standards and interim waste storage siting decisions.
Utility Companies dominate procurement volume; Contractors are expanding most quickly as disintermediation progresses.
Waste Type:
Radiological classification determines handling protocols, storage duration, and ultimate disposition pathways.
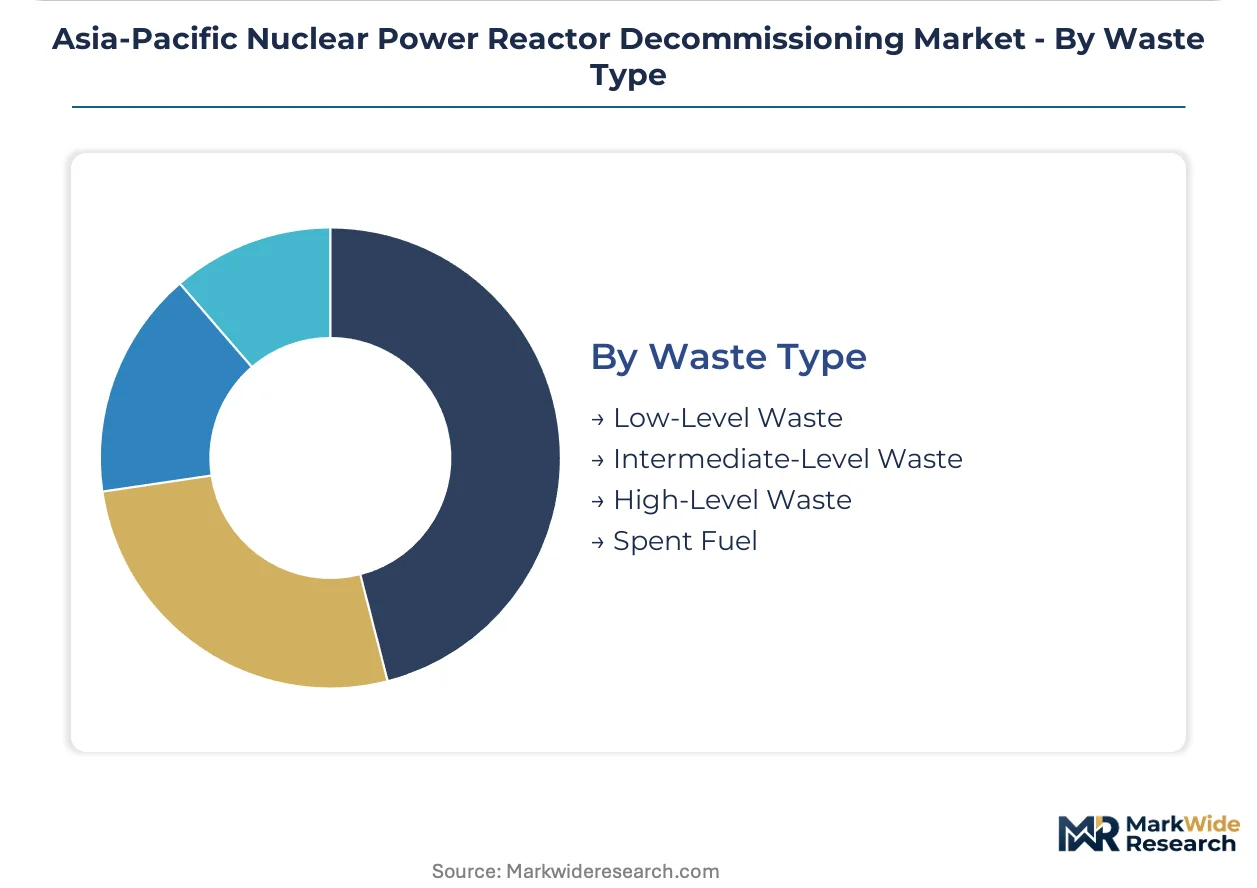
- Intermediate-Level Waste:Resins, filters, and reactor components with elevated activity levels require engineered barrier facilities and decades-long custody. Site capacity saturation in Fukushima and Tsuruga prefectures forces costly on-site construction expansion.
- High-Level Waste:Spent fuel assemblies and vitrified reprocessing products demand dry cask storage or geological repository access. Bilateral agreement gaps block international transfer options, trapping material in expensive interim arrangements.
- Low-Level Waste:Contaminated protective equipment, demolition debris, and operational consumables qualify for near-surface disposal or clearance from regulatory control.
- Spent Fuel:Reactor-removed assemblies pending reprocessing or direct disposal require pool cooling, dry cask transfer, and eventual repository emplacement.
Intermediate-Level Waste retains volume leadership; High-Level Waste holds the steepest cost escalation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in nuclear decommissioning services remain heavily constrained by radioactive material transfer prohibitions, forcing Asia-Pacific markets toward self-sufficient domestic capabilities rather than cross-border service flows.
Japan
Fukushima Daiichi and Tsuruga prefectures concentrate decommissioning demand as multiple reactor fleets reach end-of-life simultaneously. Japan's Nuclear Regulation Authority mandates extended cooling periods before dismantling commencement, inflating interim waste storage requirements. Tokyo Electric Power Company Holdings anchors procurement volume across the Tohoku and Kansai industrial corridors.
South Korea
Korea Hydro & Nuclear Power Co. dominates domestic decommissioning planning through its captive utility relationship with state regulators. The Nuclear Safety and Security Commission enforces real-time radiation monitoring data submission through centralized digital portals. The Busan-Ulsan and Daejeon-Sejong regions host concentrated engineering capacity for reactor segmentation and waste conditioning operations.
China
State-owned nuclear operators are building indigenous decommissioning capabilities as first-generation reactors approach retirement. The National Nuclear Safety Administration establishes licensing frameworks for site release and waste custody. The Yangtze River Delta and Shandong Peninsula regions concentrate emerging decommissioning engineering clusters.
Australia
ANSTO's aging OPAL facility and legacy HIFAR site rehabilitation create first-mover openings for Asia-Pacific decommissioning consortia. ARPANSA governs spent fuel custody rules and site release criteria for nuclear medicine reactors. Lucas Heights in New South Wales anchors the nation's sole significant nuclear infrastructure decommissioning pipeline.
Taiwan
Taipower's reactor fleet decommissioning timeline accelerates as units reach design life without license renewal pathways. The Atomic Energy Council regulates worker dose limits and site restoration standards. The southern industrial zone around Kaohsiung concentrates emerging waste management and site rehabilitation service demand.
Asia-Pacific Nuclear Power Reactor Decommissioning Market Competitive Environment
On the supply side, the industry is consolidating around integrated engineering conglomerates with captive utility relationships, while specialized robotics and waste conditioning firms fragment the unbundled procurement segments. Three strategic archetypes dominate: vertically integrated nuclear engineering heritage players, state-affiliated utility operators with captive decommissioning units, and European technology specialists entering through joint venture structures. Competitive moves concentrate on consortium restructuring to capture unbundled work packages and robotics technology licensing to reduce worker dose exposure.
Within the integrated engineering tier, Hitachi-GE Nuclear Energy exemplifies the heritage conglomerate archetype leveraging decades of reactor construction experience into dismantling contracts. Korea Hydro & Nuclear Power Co. occupies a singular position as a state-utility with captive decommissioning planning authority. Among European specialists, Orano represents the technology licensing model extending waste conditioning expertise into Asian markets through partnership structures rather than direct operational presence.
| Leading Market Players |
|---|
| Hitachi-GE Nuclear Energy |
| Japan Atomic Power Co. |
| Tokyo Electric Power Company Holdings |
| Korea Hydro & Nuclear Power Co. |
| Babcock International Group PLC |
| GE Hitachi Nuclear Energy |
| Fluor Corporation |
| AECOM |
| Orano |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Japan's certified radiation protection technician pool is compressing project throughput and amplifying pricing power for qualified segmentation engineering consortia. This labor scarcity feeds directly into elevated project management fees and extended interim waste storage costs across Fukushima and Tsuruga prefectures.
Pricing Analysis
Utility procurement officers anchor contract valuation through unbundled work-package tendering rather than integrated turnkey awards. Three-tier pricing structure across premium robotics-enabled segmentation, standard mechanical dismantling, and economy-grade site monitoring services reflects certification depth and dose-exposure guarantees. Cost compression in standard-tier mechanical cutting is intensifying as Korean and Chinese engineering firms enter vessel segmentation procurement. State-affiliated utilities exhibit lowest price sensitivity given regulatory-mandated reserve requirements, while specialized robotics subcontractors face acute margin pressure from equipment amortization timelines.
Supply Chain Analysis
Extended payment terms from Korea Hydro & Nuclear Power Co. are forcing mid-tier waste conditioning vendors toward supply-chain finance facilities backed by state development banks. Component sourcing draws from Japan for precision cutting systems, France for vitrification technology, and South Korea for remote handling platforms. Single-source vulnerability concentrates in European-sourced high-integrity containment vessels for spent fuel storage. Distribution runs through direct utility procurement channels with minimal intermediary presence, reflecting the project-specific nature of decommissioning deliverables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates formidable defensive moats in Asia-Pacific reactor decommissioning, as licensing familiarity with Japan's Nuclear Regulation Authority and South Korea's Nuclear Safety and Security Commission accumulates over multi-decade project horizons.
For Market Incumbents: Build regulatory relationship moats by embedding compliance advisory capabilities within utility planning departments before contract award phases. Deepen backward integration into robotics maintenance infrastructure to capture recurring service revenue from digital twin-enabled segmentation platforms. Threaten emerging Korean engineering consortia seeking vessel dismantling contracts through preemptive certification of proprietary cutting methodologies with Japan's regulator. For New Entrants and Emerging Players: Build out specialized waste conditioning capabilities targeting Australia's ANSTO OPAL facility conversion, where first-mover positioning remains unclaimed and ARPANSA licensing pathways lack entrenched incumbent relationships. Pursue joint venture structures with European technology licensors rather than direct operational presence to bypass capital intensity barriers. Go-to-market execution should emphasize digital twin integration credentials to differentiate from established mechanical segmentation providers. For Investors and Strategic Acquirers: Long-term, this sits as a contracted-utility-revenue play because decommissioning reserves under South Korea's emerging extended producer responsibility frameworks lock in service demand regardless of power market pricing cycles. Acquisition screening should prioritize robotics-enabled segmentation specialists with proven Fukushima Daiichi deployment records. Monitor bilateral radioactive waste transfer agreement negotiations as the critical inflection signal for high-level waste storage cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Technology Licensing | Orano's waste conditioning expertise transfer to Korean joint ventures reduces European direct operational exposure. |
| Digital Twin Platform Integration | Hitachi-GE's 3D laser scanning deployment at Fukushima Daiichi compresses pre-segmentation planning cycles. |
| Regulatory Compliance Advisory Embedding | Specialist consultants navigating multi-jurisdictional licensing capture margin pools in site release certification. |
| Joint Venture Structure Formation | European technology specialists partner with domestic utilities to bypass capital intensity and local content requirements. |
| Extended Producer Responsibility Reserve Capture | South Korea's utility-funded decommissioning mandates lock in long-dated service contract revenue visibility. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, utility procurement disclosures, and nuclear safety commission licensing databases. Primary engagement encompassed decommissioning project directors at Tokyo Electric and Korea Hydro & Nuclear Power, radiation protection officers at Fukushima Daiichi, robotics engineering leads, and waste conditioning specialists. Secondary validation drew from Japan Nuclear Regulation Authority safety review documentation, South Korea Nuclear Safety and Security Commission digital portal mandates, ANSTO facility planning disclosures, and IAEA decommissioning cost benchmark studies. Bottom-up service demand modeling triangulates against top-down utility capital expenditure projections.
Forecast inputs incorporate reactor fleet age profiles, regulatory cooling period mandates, and robotics deployment penetration curves across the analysis window. Segmentation dimensions span service type, technology platform, waste classification tier, and end-user procurement authority. CAGRs derive from utility reserve accumulation trajectories under extended producer responsibility frameworks and project management intensity per reactor unit. Industry-specific inputs include spent fuel pool integrity assessment frequencies and bilateral waste transfer agreement negotiation status.
Practitioners should monitor regulatory cooling period extensions, cross-border repository access agreements, and robotics platform reliability maturation for early signals of demand trajectory revision. Forecasts reflect assumptions of continued domestic storage capacity constraints and stable bilateral waste transfer prohibitions. Macroeconomic utility rate case pressures, seismic retrofitting cost overruns, or breakthroughs in advanced reprocessing commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
Nuclear Steam Generator Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
Japan Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market