
 Nuclear Decommissioning Services Market | 2026-2036
Nuclear Decommissioning Services Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Decommissioning Services Market Intelligence
The OECD Nuclear Energy Agency's updated guidance on decommissioning liabilities is rebalancing the cost-of-entry calculus for new service providers. This framework pressures operators to secure long-term, technically proficient partners. Orano Group specializes in the back-end of the fuel cycle, including waste management. Bechtel Group Inc. leverages its extensive engineering and construction management for large-scale reactor dismantling projects.
Nuclear decommissioning services encompass the administrative and technical activities required to safely remove a nuclear facility from service and reduce residual radioactivity to a level that permits release of the property. This process involves detailed site characterization to map contamination hotspots and ensure compliance with regulatory clearance levels. Within service types, reactor dismantling and waste management constitute the most significant project phases. The adoption of advanced robotic systems and new decontamination techniques is critical for reducing worker exposure and accelerating project timelines.
Regulatory oversight from bodies like the U.S. Nuclear Regulatory Commission (NRC), the IAEA, and national agencies in France and Japan dictates project methodologies and timelines. These frameworks mandate strict safety protocols and long-term waste management strategies, defining market access. Service providers must now decide whether to invest in proprietary robotic technologies or rely on specialized subcontractors to manage long-tail project risks.
Market Dynamics
Intensifying regulatory frameworks are the central force shaping the market. These rules compel nuclear operators to secure long-term partners for managing complex decommissioning liabilities, shifting the focus from simple cost-out to risk transfer and technical proficiency.
Growth Catalysts
- Scheduled Shutdowns:A pipeline of first-generation reactor retirements in the United States and France creates predictable project flow for service providers.
- Robotics for Safety:Adopting robotics for dismantling reduces worker radiation exposure and accelerates project timelines, a key value proposition for operators.
- EU Green Deal:This framework's stringent waste management rules compel operators to adopt more sophisticated services, expanding the market for specialists.
Market Restraints
- High Capital Costs:Investment in specialized equipment like remote handling systems and waste vitrification plants creates a significant barrier to entry for new firms.
- Regulatory Delays:Lengthy licensing processes from bodies like the U.S. Nuclear Regulatory Commission can delay project timelines and increase overall costs.
- Waste Disposal Uncertainty:The lack of permanent repositories for high-level radioactive waste creates long-term liability and storage challenges for decommissioning projects.
Strategic Opportunities
- Digital Twin Services:Offering digital twin modeling for site simulation improves planning accuracy and reduces execution risks, creating a new value-added service.
- Eastern Europe Expansion:Decommissioning Soviet-era reactors under EU standards represents a key geographic growth market for experienced service providers.
- Integrated Liability Contracts:Service models that bundle dismantling with long-term waste stewardship meet operator demand for total risk transfer, per OECD guidance.
Industry Challenges
- Workforce Scarcity:A shortage of nuclear engineers and health physicists creates project staffing risks and increases labor costs for service providers.
- Subcontractor Management:Projects rely on a fragmented supply chain for key tasks like waste transport, creating complex coordination and liability challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Decommissioning Services Market |
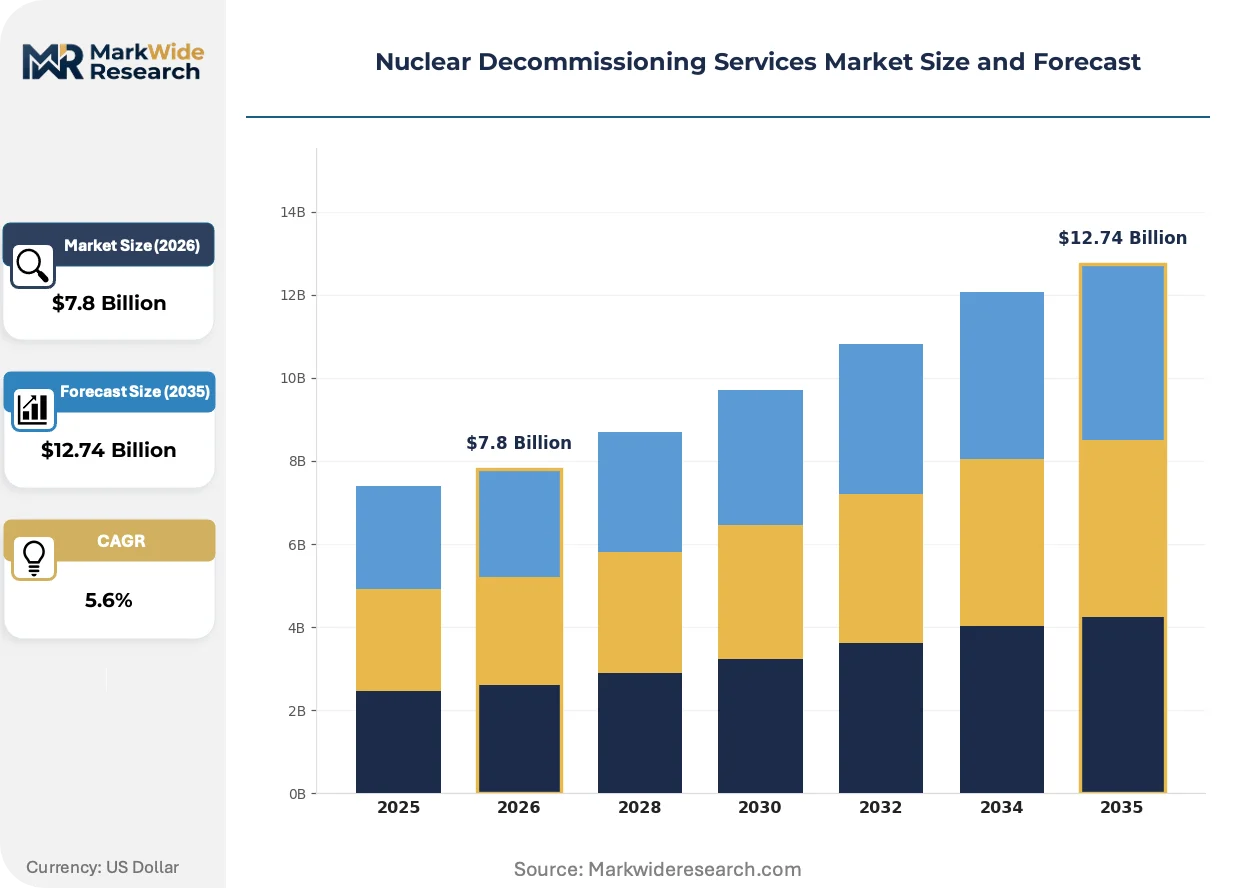
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.74 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Site Characterization, Waste Management, Reactor Dismantling, Site Remediation, License Termination Application: Power Plant Shutdown, Research Reactor Decommissioning, Fuel Fabrication Facility, Storage Facility Clearance End User: Government Agencies, Nuclear Operators, Environmental Consultancies, Engineering Contractors Technology: Robotic Systems, Remote Sensing, Radiation Shielding, Waste Processing, Decontamination Techniques |
| Companies Covered | AECOM, Babcock International Group PLC, Westinghouse Electric Company LLC, Orano Group, Studsvik AB, Bechtel Group Inc., EnergySolutions, NUVIA Group, Onet Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Decommissioning Services Market Strategic Shifts & Innovations
The market is being reshaped by the deployment of digital technologies and new contracting models designed to accelerate project timelines and reduce human intervention. These innovations focus on improving safety, managing long-tail risks, and ensuring compliance with evolving international standards.
Robotics and Digital Twin Convergence
Digital twin technology creates detailed virtual models of nuclear facilities, enabling precise planning and simulation of dismantling activities. Decommissioning operators in mature markets like Japan and the United States are adopting this for scenario analysis and training. This digital modeling capability is converging with advanced robotics to enable remote-controlled, high-precision dismantling, significantly reducing worker radiation exposure.
Harmonization of Waste Management Standards
The IAEA is actively promoting harmonized international standards for radioactive waste characterization, processing, and disposal. This encourages cross-border collaboration and the adoption of best practices, especially for countries with smaller nuclear programs or less-developed regulatory frameworks. Service providers targeting markets in Eastern Europe must align their methodologies with these global benchmarks to secure contracts.
Shift to Long-Term Stewardship Contracts
Facility operators are moving away from fragmented, project-based procurement toward single, long-term stewardship agreements. This shift bundles site characterization, dismantling, and waste management into one integrated package, transferring long-tail project and regulatory risks to the service provider. This model is most prominent in the United States and France, where utilities seek to fix liabilities and ensure compliance through a single partner.
Nuclear Decommissioning Services Market Segmentation
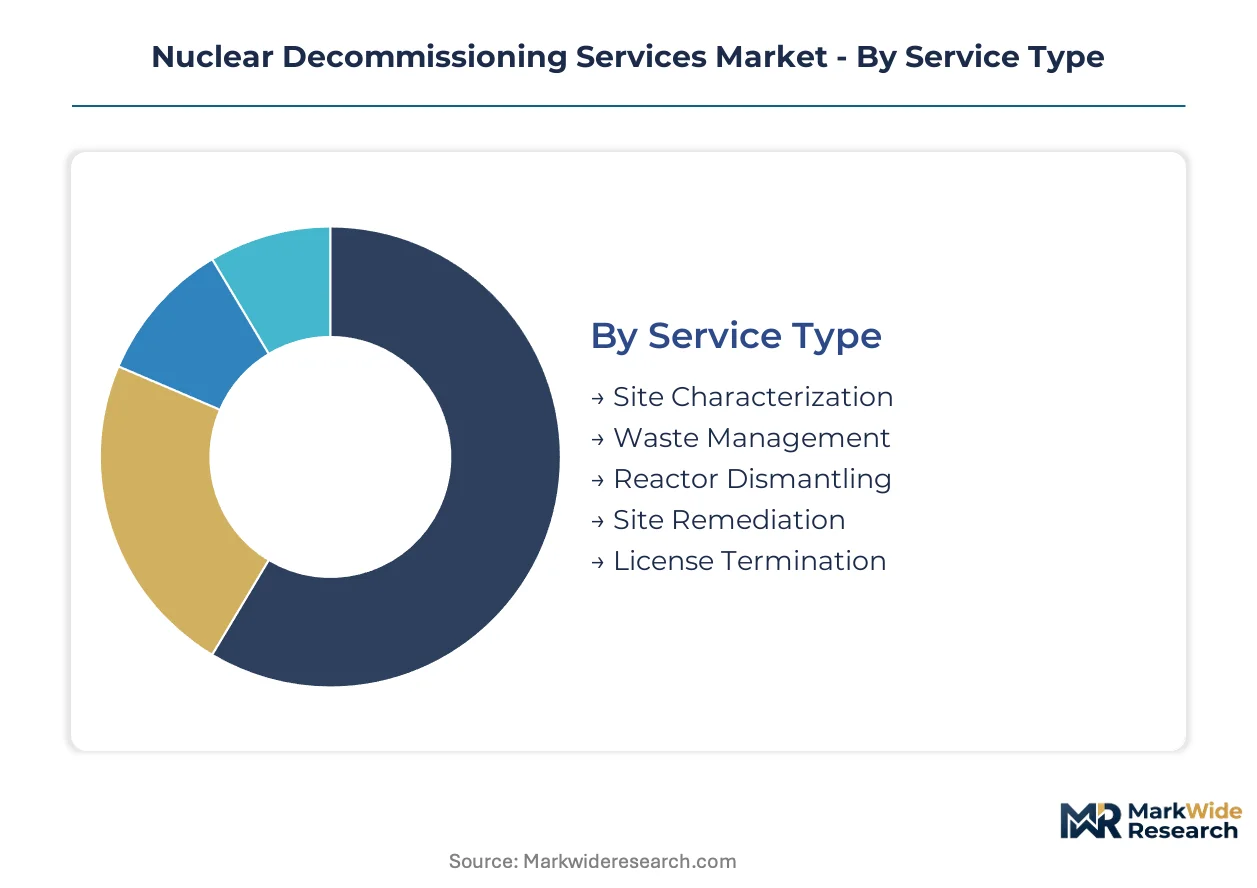
The nuclear decommissioning services market requires granular segmentation to understand its complex operational landscape. This breakdown reveals where technical expertise is most concentrated and where regulatory pressures are shaping service delivery. Analyzing these categories helps identify critical investment areas and emerging demand patterns for specialized providers.
Service Type:
The supply of nuclear decommissioning services is highly concentrated in specialized technical areas that address the most hazardous and complex aspects of facility retirement.
- Reactor Dismantling:This service involves the physical removal and processing of the reactor vessel and associated components, often requiring remote handling and specialized cutting. Demand concentrates in mature nuclear markets like France and the United States due to aging first-generation reactors.
- Waste Management:This encompasses the classification, processing, packaging, and interim storage of radioactive waste generated during decommissioning, adhering to strict international guidelines. This segment sees significant demand from operators in Japan and Germany, driven by stringent waste management regulations under frameworks like the EU Green Deal.
- Site Characterization:This involves detailed surveys to map contamination hotspots and assess radiological conditions, crucial for planning and compliance.
- Site Remediation:This focuses on cleaning contaminated land and structures to meet regulatory clearance levels, preparing the site for reuse.
- License Termination:This administrative and technical process ensures all regulatory requirements are met for final site release from nuclear oversight.
Reactor Dismantling absorbs the bulk of installed capacity; Waste Management is expanding most quickly.
Application:
The scope of decommissioning applications dictates the specific technical challenges and regulatory pathways service providers must navigate.
- Power Plant Shutdown:This application involves the decommissioning of commercial nuclear power reactors, representing the largest volume of projects due to the planned retirement of aging facilities. Demand is concentrating in the United States and Western Europe, where many first-generation reactors are reaching end-of-life.
- Research Reactor Decommissioning:This segment addresses the safe dismantling of smaller, often university-based or experimental reactors, which present unique radiological and logistical challenges. This application sees increased activity in countries with established research programs, such as Canada and the United Kingdom, as older facilities are retired.
- Fuel Fabrication Facility:This involves decommissioning nuclear fuel manufacturing facilities, requiring specialized actinide decontamination.
- Storage Facility Clearance:This covers remediation and clearance of sites used for radioactive material storage, ensuring residual radioactivity limits are met.
Decommissioning Power Plant Shutdowns represents the largest project pipeline; Storage Facility Clearance projects are growing due to increased regulatory scrutiny.
End User:
Different end-user types approach nuclear decommissioning with varying procurement strategies and risk appetites, influencing service provider engagement models.
- Nuclear Operators:These are the primary owners and licensees of nuclear facilities, responsible for funding and overseeing the entire decommissioning process. They often seek long-term, integrated liability contracts to transfer risk.
- Government Agencies:These entities often own or regulate nuclear facilities, particularly in defense or research sectors, and play a significant role in funding and setting policy for decommissioning projects. Agencies like the U.S. Department of Energy are major clients.
- Environmental Consultancies:These firms provide specialized environmental impact assessments, regulatory compliance, and waste characterization services to operators.
- Engineering Contractors:These companies offer project management, design, and construction for specific dismantling or remediation tasks, often as subcontractors.
Nuclear Operators drive the majority of project demand; Environmental Consultancies are seeing increased engagement due to evolving regulatory frameworks.
Technology:
The maturity level of decommissioning technologies ranges from established methods to cutting-edge innovations, each offering distinct advantages for safety and project efficiency.
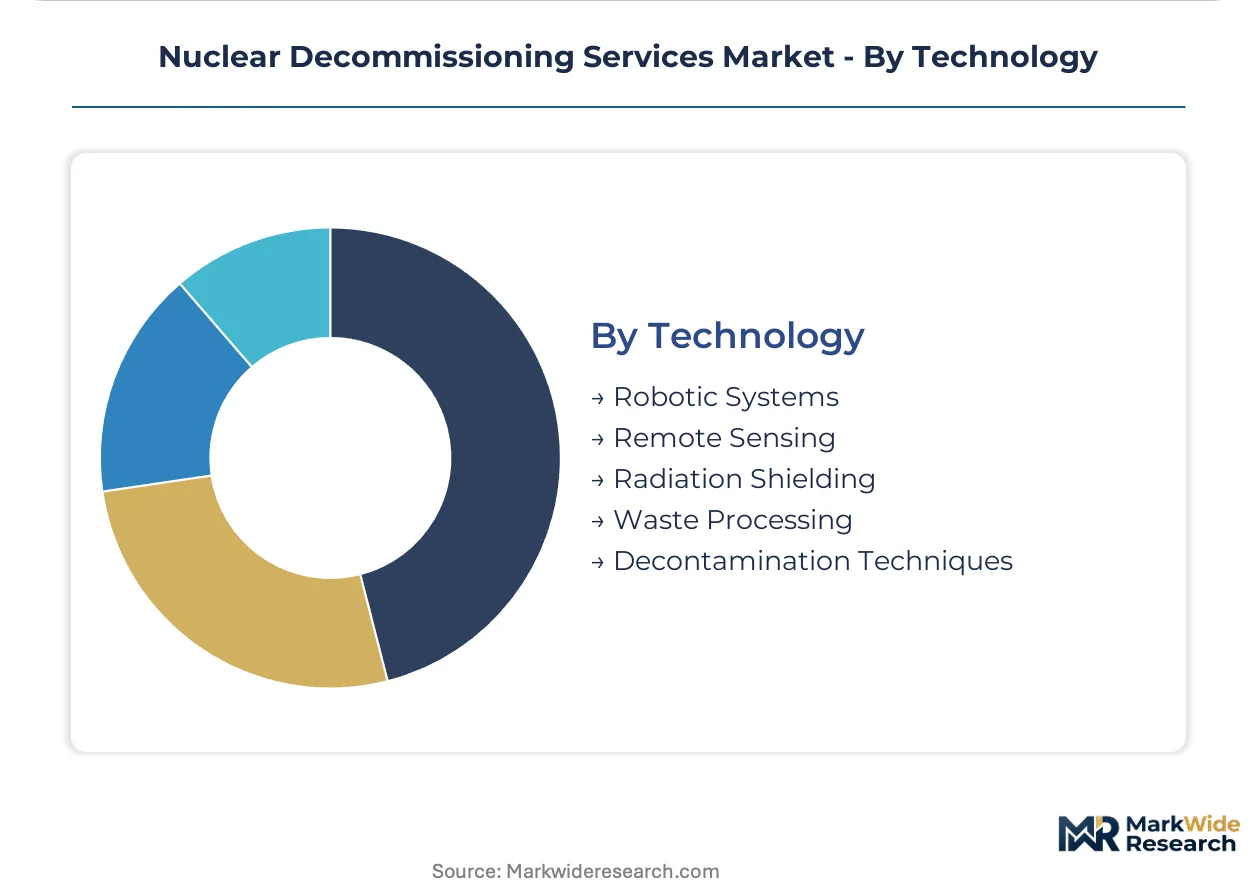
- Robotic Systems:These advanced systems enable remote handling, cutting, and inspection in high-radiation environments, significantly reducing worker exposure and accelerating hazardous tasks. Adoption is accelerating in Japan and the United States for complex reactor internals dismantling.
- Waste Processing:This technology includes vitrification, compaction, and encapsulation methods for reducing the volume and stabilizing radioactive waste for safe long-term storage. This technology is critical for compliance with the EU Green Deal's stringent waste management rules.
- Remote Sensing:This involves using drones and advanced sensors for detailed radiological mapping and structural assessments, improving planning accuracy.
- Radiation Shielding:This technology provides protective barriers to minimize radiation exposure for personnel during dismantling and waste handling.
- Decontamination Techniques:These methods, including chemical flushing and abrasive blasting, remove radioactive contaminants from surfaces to reduce waste volume and enable material recycling.
Robotic Systems are transforming operational safety and efficiency; Decontamination Techniques are gaining traction for waste volume reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's stringent waste management regulations drive significant concentration in specific regions. This comprehensive framework compels nuclear operators to adopt sophisticated decommissioning services. Consequently, project pipelines are concentrating in mature nuclear markets such as France, the United States, and Japan.
United States
Scheduled shutdowns of first-generation reactors create predictable project flow for service providers. The U.S. Nuclear Regulatory Commission (NRC) dictates project methodologies and timelines. Washington State's Hanford Site demonstrates large-scale remediation and waste management efforts.
France
Aging first-generation reactors and a focus on integrated liability contracts drive demand. National agencies dictate strict safety protocols and long-term waste management strategies. The Marcoule site in Southern France focuses on advanced waste processing and decommissioning.
Japan
Stringent waste management regulations and the adoption of robotic systems shape market demand. National agencies define market access and long-term strategies for decommissioning. Fukushima Prefecture exhibits complex remediation and dismantling projects following the 2011 incident.
Germany
A policy-driven nuclear phase-out creates a substantial decommissioning pipeline. The EU Green Deal's stringent waste management rules compel operators to adopt sophisticated services. The Greifswald site in Mecklenburg-Vorpommern undergoes extensive decommissioning and remediation.
United Kingdom
The retirement of older research reactors and commercial power plants fuels project activity. National agencies mandate strict safety protocols and long-term waste management. Sellafield in Cumbria manages complex waste and decommissioning programs for a variety of facilities.
Nuclear Decommissioning Services Market Key Industry Players
Western European producers anchor one tier, offering integrated solutions for complex decommissioning projects. North American specialists hold another, focusing on large-scale reactor dismantling and waste management. The market structure is tiered, with large engineering firms, specialized waste management providers, and technology developers forming distinct archetypes. Strategic partnerships and technology licensing are dominant competitive moves among these players.
Within the specialized services tier, Orano Group exemplifies expertise in the back-end of the fuel cycle, including waste management. Bechtel Group Inc. occupies a position as a leading engineering and construction management firm, often involved in large-scale reactor dismantling projects. These firms anchor the market by providing technically proficient solutions and managing complex liabilities for nuclear operators.
| Leading Market Players |
|---|
| AECOM |
| Babcock International Group PLC |
| Westinghouse Electric Company LLC |
| Orano Group |
| Studsvik AB |
| Bechtel Group Inc. |
| EnergySolutions |
| NUVIA Group |
| Onet Technologies |
| Others |
Cost & Logistics Intelligence
Specialized equipment costs, particularly for remote handling systems, flow from a concentrated vendor base, influencing project-based pricing for complex reactor dismantling services. This upstream concentration shapes downstream service delivery contracts.
Pricing Analysis
Premium pricing for expedited project timelines reflects the scarcity of specialized technical teams and advanced robotic systems. The dominant project-based pricing model accounts for the unique scope of each decommissioning site. Price differentiation stems from the technical complexity of reactor dismantling and the stringent regulatory compliance required by bodies like the U.S. Nuclear Regulatory Commission. Cost compression in initial project phases stems from intense competition for predictable reactor shutdown pipelines. Government agencies are generally less price-sensitive than nuclear operators seeking fixed-liability contracts for total risk transfer.
Supply Chain Analysis
Single-source vulnerability sits with a limited pool of highly specialized nuclear engineers and health physicists, creating project staffing risks. Geographic supply concentration for advanced decommissioning technologies centers on mature nuclear markets like France, the United States, and Japan. The supply chain relies on specialized robotic components and waste processing chemicals. Workforce scarcity represents a significant structural risk for project execution. Distribution runs through direct contracting models, often involving integrated service providers managing complex, long-term liabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nuclear decommissioning market is fundamentally a cost-of-compliance story, where stringent frameworks like the EU Green Deal create significant barriers to entry for non-compliant service providers. This regulatory moat favors technically proficient and financially stable partners.
For Market Incumbents: Acquire specialized robotic technology firms to deepen remote handling capabilities and reduce worker exposure risks. Integrate advanced waste management processing capabilities to meet evolving regulatory standards, mitigating long-term liability transfer. Invest in R&D for new decontamination techniques to counter rising labor costs and workforce scarcity. This defends against emerging entrants leveraging niche technological advantages.
For New Entrants and Emerging Players: Capture niche opportunities in Eastern Europe by offering specialized services for Soviet-era reactor decommissioning under EU standards. Target the site characterization segment in countries with less developed regulatory frameworks, leveraging digital twin modeling for enhanced planning accuracy. Focus on research reactor decommissioning, which presents unique radiological challenges and a distinct project pipeline. This provides a clear go-to-market angle with lower capital intensity.
For Investors and Strategic Acquirers: Increased adoption of integrated liability contracts by major utilities is the leading indicator that operators prioritize risk transfer over fragmented project procurement. This market offers stable, long-term demand over the next decade, driven by predictable reactor retirements. Target vertically integrated service providers with proprietary robotic systems and strong waste management expertise. Watch for regulatory shifts from bodies like the IAEA that accelerate international harmonization of decommissioning standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire Robotic Technology Firms | This secures proprietary remote handling capabilities, reducing worker exposure and accelerating hazardous tasks. |
| Expand Digital Twin Service Offerings | Digital twin modeling improves planning accuracy for complex dismantling projects in mature markets like Japan. |
| Form Integrated Liability Partnerships | Bundling dismantling and waste stewardship transfers long-tail project and regulatory risks from nuclear operators. |
| Invest in Advanced Waste Processing | This ensures compliance with stringent waste management regulations, particularly those under the EU Green Deal. |
| Target Eastern European Decommissioning | This provides geographic growth by addressing Soviet-era reactor retirements under evolving EU standards. |
Research Approach
Multi-period observation of reactor shutdown schedules and regulatory compliance trends anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with nuclear operators, regulatory affairs specialists, decommissioning project managers, and specialized engineering contractors. Secondary validation drew from IAEA reports, U.S. Nuclear Regulatory Commission filings, OECD Nuclear Energy Agency guidance, and company annual reports. This approach ensured bottom-up data collection was triangulated with top-down market perspectives.
Market size and growth forecasts utilized a segment-weighting approach, applying specific growth rates to each identified market segment across the analysis window. The quantitative model integrated segmentation dimensions including service type, application, end-user, technology, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth patterns and projected market accelerators, including scheduled reactor retirement dates. National nuclear phase-out policies served as a critical forecast input.
The model holds under current regulatory stability and projected reactor retirement schedules; deviation in geopolitical events affecting energy policy or unforeseen technological breakthroughs would shift outcomes. Forecasts reflect assumptions regarding long-term waste disposal solutions and workforce availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
United Kingdom Nuclear Power Reactor Decommissioning Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
Small Modular Reactor (SMR) Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market