
 Small Modular Reactor (SMR) Market | 2026-2036
Small Modular Reactor (SMR) Market Size, Share, and Industry Trends Forecast 2026-2036
Small Modular Reactor (SMR) Market Analytics
Long-term fuel supply and maintenance subscription packages is consolidating the commercial model for SMR vendors. NuScale Power leverages its first-mover certification advantage to anchor utility partnerships in the American West. TerraPower sustains technology leadership through its sodium-cooled fast reactor design integrated with molten salt energy storage. Rolls-Royce SMR dominates the British supply chain with a vertically integrated manufacturing approach centered in Derbyshire.
Small modular reactors are factory-fabricated nuclear units with electrical outputs below 300 MWe per module, designed for serial production and transportable assembly. Their primary purpose is delivering dispatchable zero-carbon baseload power to grids, industrial complexes, and remote installations that cannot accommodate gigawatt-scale plants. Pressurized water reactor technology occupies the dominant position due to its proven operational pedigree and regulatory familiarity, while high-temperature gas reactor designs attract hydrogen production applications where process heat above 700°C unlocks thermochemical water splitting. Electricity generation anchors current demand, though hydrogen production represents the fastest-growing application segment as steel and chemical producers seek carbon-free feedstock alternatives.
The US Nuclear Regulatory Commission, the UK's Office for Nuclear Regulation, and Canada's Canadian Nuclear Safety Commission each maintain distinct certification pathways that determine market access timelines and design acceptance criteria. These frameworks shape vendor strategies by rewarding standardized designs with multi-jurisdictional approval potential. Stakeholders must monitor which regulatory precedents achieve reciprocity agreements, as harmonized standards will determine the first export-ready SMR platforms.
Market Dynamics
The US Nuclear Regulatory Commission's Part 53 licensing framework is compressing certification timelines for advanced reactor designs, triggering a race among vendors to lock in site permits and long-term power purchase agreements before 2030 capacity windows close.
Growth Catalysts
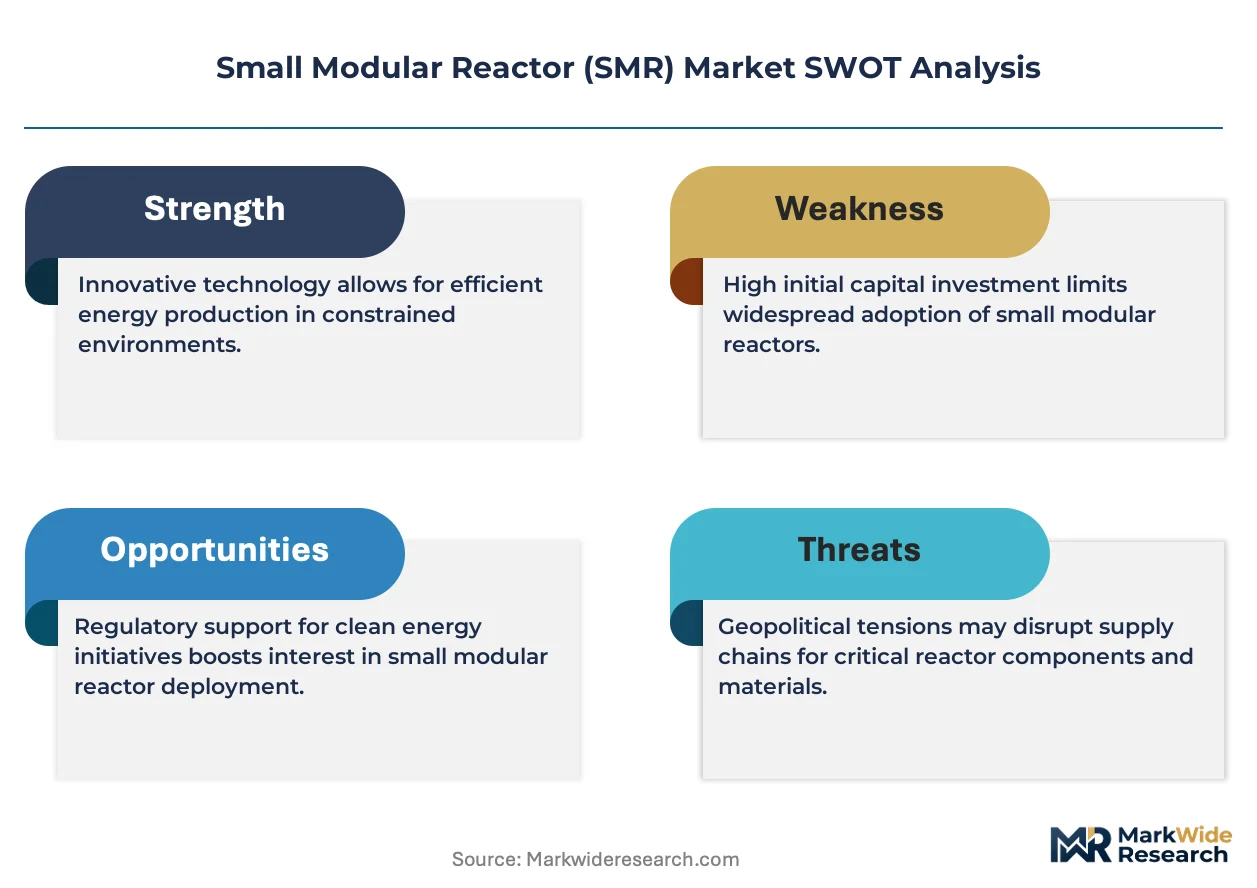
- Inflation Reduction Act tax credits:The IRA's production tax credits for clean electricity generation slash levelized cost of energy for SMR deployments, drawing utility capital away from gas peaker plants.
- Data center load growth:Hyperscale computing clusters in Virginia and Texas are signing 24/7 carbon-free power contracts that only nuclear baseload can fulfill.
- High-assay low-enriched uranium (HALEU) supply chains:Domestic enrichment capacity expansion through the Department of Energy's HALEU program secures fuel pathways for advanced reactor designs.
Market Restraints
- First-of-a-kind engineering costs:Initial SMR builds carry 40-60% capital premiums over nth-of-a-kind projections, chilling utility board approvals.
- Enrichment supply concentration:Commercial HALEU production concentrates at a single US enrichment facility, creating single-point-of-failure vulnerability for advanced reactor fuel loading.
- Grid interconnection queues:Regional transmission organization backlogs in PJM and ERCOT delay commercial operation dates regardless of reactor construction pace.
Strategic Opportunities
- Industrial process heat:Chemical producers in the US Gulf Coast are evaluating SMR steam supply for ammonia and methanol synthesis, opening non-electric revenue streams.
- Remote mining installations:Off-grid mineral extraction operations in northern Canada seek transportable reactor units to displace diesel generation.
- State clean energy mandates:California's SB 100 and New York's CLCPA create regulatory pull for firm zero-carbon capacity that intermittent renewables cannot satisfy.
Industry Challenges
- Welding and quality assurance specialist shortage:Nuclear-grade fabrication requires ASME N-stamp certified welders, a credential held by fewer than 5,000 US workers.
- Design certification sequencing:Reactor vendors must complete NRC design certification before site-specific licensing, forcing parallel capital commitments without revenue certainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Modular Reactor (SMR) Market |
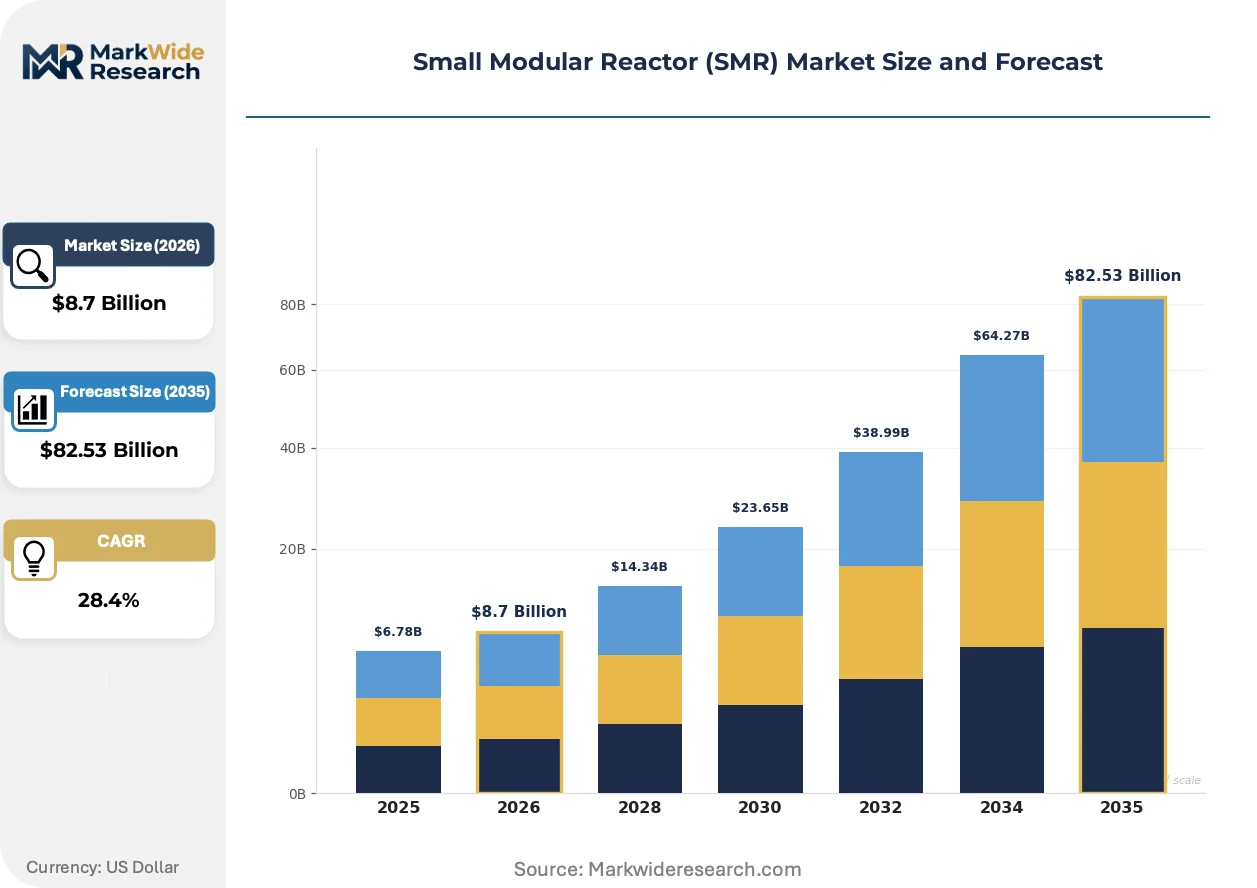
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pressurized Water Reactor, Boiling Water Reactor, High-Temperature Gas Reactor, Liquid Metal Reactor End User: Utilities, Industrial Plants, Remote Locations, Military Bases Deployment: Onsite, Offsite, Modular, Distributed Application: Electricity Generation, Desalination, Hydrogen Production, District Heating |
| Companies Covered | Westinghouse Electric Company, X-energy, NuScale Power, BWX Technologies, Holtec International, TerraPower, GE Hitachi Nuclear Energy, Oklo Inc., Rolls-Royce SMR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Modular Reactor (SMR) Market Evolving Landscape
Reactor vendors are compressing construction schedules through factory fabrication and standardized module designs, shifting competitive advantage from field execution to manufacturing scale and supply chain control.
Advanced manufacturing techniques including robotic welding and automated non-destructive testing are modularizing pressure vessel production, cutting fabrication time from 36 months to 18 months for integral pressurized water reactor components. Equipment suppliers in Ohio and Pennsylvania are retooling automotive and aerospace production lines for nuclear-grade steel forging. This acceleration is collapsing the traditional gap between reactor order and commercial operation, enabling utilities to contract capacity with delivery certainty previously impossible in nuclear construction.
The US Nuclear Regulatory Commission's deployment of the Part 53 risk-informed licensing pathway is compressing review timelines for non-light-water reactor designs. Sodium-cooled fast reactors and high-temperature gas reactors gain regulatory clarity through this framework, while pressurized water SMRs continue under Part 52. Developers with mature Part 53 dockets secure competitive positioning for post-2030 deployment tranches, particularly for industrial heat applications requiring outlet temperatures above 500°C.
Utility procurement teams are unbundling engineering-procurement-construction contracts into separate equipment supply and construction management agreements, transferring construction risk to specialized nuclear EPC firms. This shift fragments vendor economics but accelerates project finance closure by aligning risk allocation with insurer and lender requirements. The practice is most advanced in Texas and the Southeast, where merchant power developers pioneered the model for combined-cycle gas plants and now apply it to SMR fleets.
Small Modular Reactor (SMR) Market Segmentation
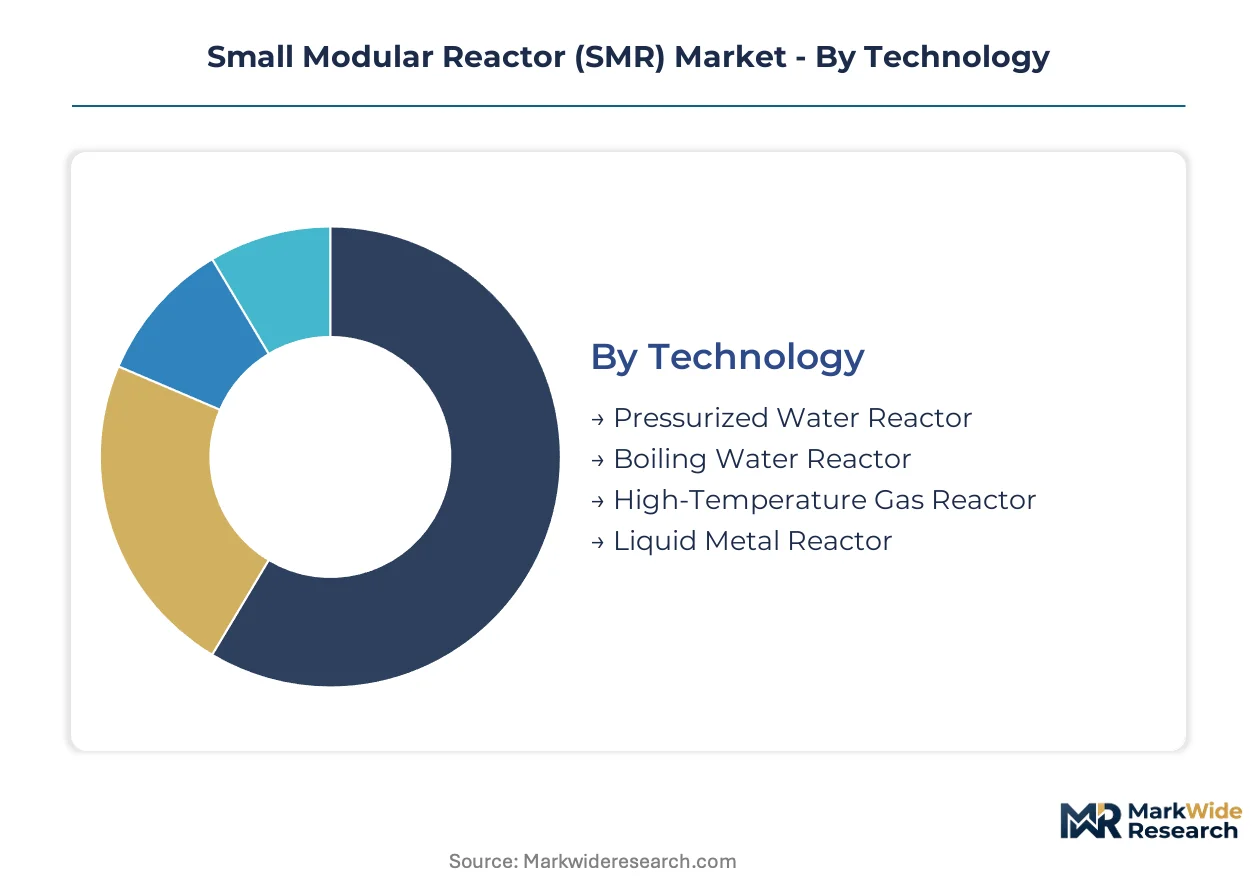
SMR market segmentation reveals how reactor vendors align certification strategies with distinct customer risk profiles and deployment constraints. Each category carries divergent regulatory burdens that determine go-to-market economics and partnership structures.
Technology:
Pressurized water reactor designs carry the lightest certification burden through NRC Part 52 familiarity, while advanced non-light-water variants navigate the newer Part 53 pathway with extended review timelines.
- Pressurized Water Reactor:Light-water designs leverage decades of operational data and established ASME code compliance. Utility procurement teams in the United States and United Kingdom prioritize this technology for baseload contracts due to lower licensing uncertainty.
- High-Temperature Gas Reactor:Helium-cooled graphite-moderated units achieve outlet temperatures exceeding 750°C. Chemical producers in the US Gulf Coast evaluate these systems for thermochemical hydrogen production where process heat quality determines project economics.
- Boiling Water Reactor:Natural circulation designs eliminate recirculation pumps, reducing maintenance overhead for remote installations.
- Liquid Metal Reactor:Sodium-cooled fast neutron systems enable closed fuel cycles with higher burnup rates.
Pressurized Water Reactor sits at the top of the volume ranking, with High-Temperature Gas Reactor climbing the fastest.
End User:
Customer type determines financing structures, with utility offtakers accessing rate-base recovery mechanisms unavailable to industrial or defense customers.
- Utilities:Regulated and merchant power generators deploy SMR fleets under long-term power purchase agreements. PJM and ERCOT interconnection queues in the United States shape deployment sequencing for these customers.
- Industrial Plants:Steel and ammonia producers seek firm thermal supply for process decarbonization. Gulf Coast chemical complexes evaluate steam purchase agreements that displace natural gas-fired boilers.
- Remote Locations:Mining and extraction operations in northern Canada require transportable units with minimal grid infrastructure.
- Military Bases:Defense installations prioritize energy security and islanding capability over levelized cost metrics.
Utilities command the dominant revenue share, while Industrial Plants are expanding most quickly as carbon border adjustments reshape feedstock economics.
Deployment:
Construction modality dictates supply chain geography, with factory-fabricated options concentrating manufacturing investment in regions with nuclear-qualified welding capacity.
- Modular:Factory-fabricated pressure vessels and steam generators enable parallel manufacturing workflows. Ohio and Pennsylvania forging facilities are retooling automotive lines for nuclear-grade component production.
- Onsite:Traditional stick-built approaches persist where transport corridors cannot accommodate oversized modules.
- Offsite:Centralized manufacturing hubs ship complete reactor units to installation locations.
- Distributed:Multiple smaller units networked across a grid zone provide resilience against single-point failures.
Modular deployment leads current investment flows, with Distributed configurations gaining policy support under state clean energy mandates.
Application:
Revenue per megawatt-hour varies dramatically across applications, with non-electric uses commanding premium pricing where carbon intensity regulations bite hardest.
- Hydrogen Production:High-temperature process heat enables thermochemical water splitting without electrolyzer electricity losses. European steel producers under EU carbon border adjustment mechanism pressure are evaluating offtake contracts for nuclear-derived hydrogen.
- Electricity Generation:Baseload power contracts with data center operators in Virginia and Texas anchor near-term demand. These customers require 24/7 carbon-free supply that intermittent renewables cannot fulfill.
- Desalination:Thermal distillation and reverse osmosis preheating applications concentrate in water-stressed coastal regions.
- District Heating:Combined heat and power configurations serve urban heating networks in colder climates.
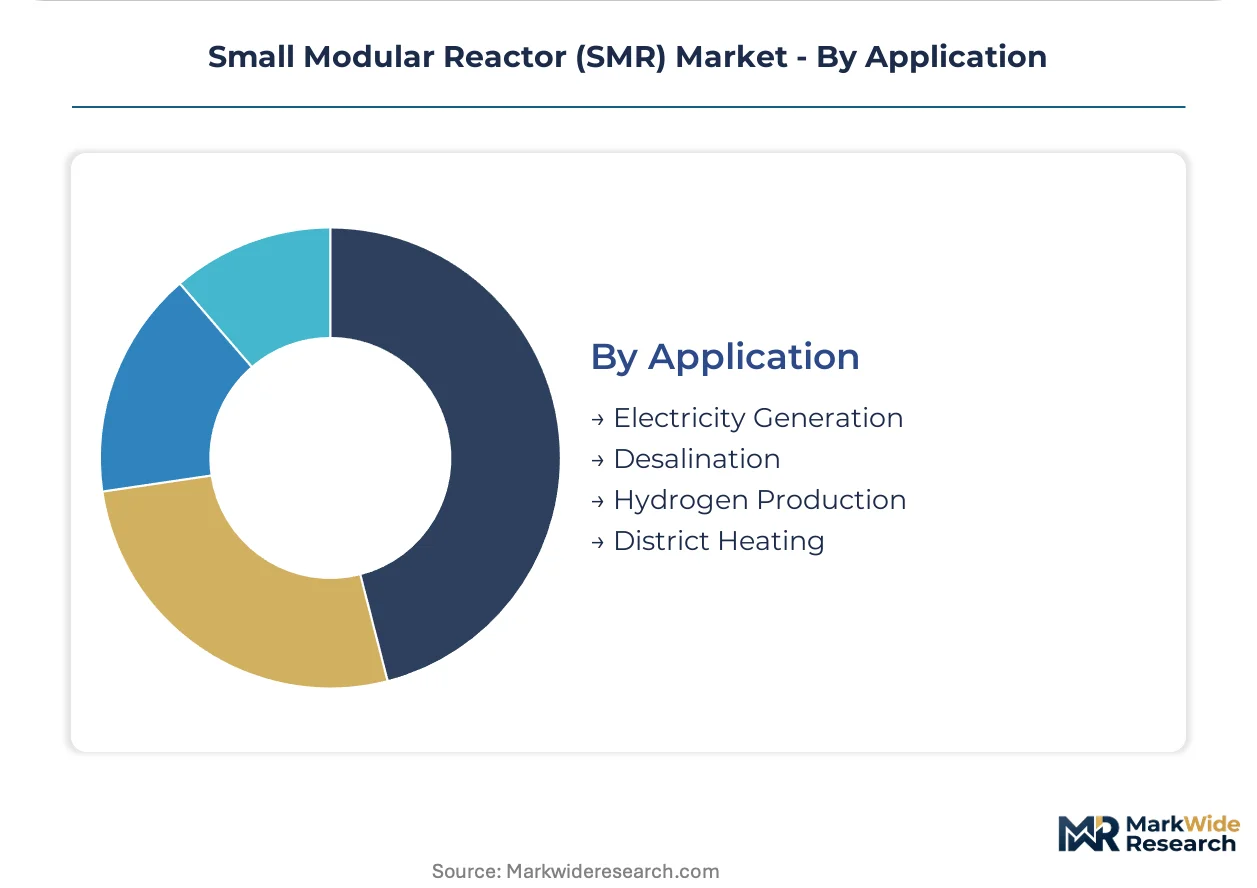
Electricity Generation retains the largest installed base, though Hydrogen Production shows the steepest expansion trajectory as industrial decarbonization deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping SMR deployment geography as vendors chase jurisdictions with compressed licensing timelines and production tax credit density. Factory fabrication capacity migrates toward regions with nuclear-qualified welding labor pools and forgings infrastructure.
United States
Data center load growth in Virginia and Texas anchors utility procurement for 24/7 carbon-free baseload. The Inflation Reduction Act's production tax credits slash levelized costs for SMR fleets, drawing capital away from gas peaker alternatives. Ohio and Pennsylvania forging facilities are retooling automotive lines for nuclear-grade pressure vessel production.
Canada
Remote mining installations in northern provinces seek transportable reactor units to displace diesel generation at extraction sites. The Canadian Nuclear Safety Commission maintains distinct certification pathways that reward standardized designs with multi-jurisdictional approval potential. Ontario's manufacturing base is adapting aerospace fabrication capacity for SMR module assembly.
United Kingdom
Industrial process heat demand from steel and chemical producers drives evaluation of high-temperature reactor designs for hydrogen feedstock production. The Office for Nuclear Regulation's licensing framework shapes vendor strategies through design acceptance criteria that favor proven operational pedigrees. Derbyshire anchors Rolls-Royce SMR's vertically integrated manufacturing approach for British supply chain control.
China
State-backed deployment programs accelerate commercialization timelines for domestic reactor designs targeting industrial decarbonization clusters. MIIT oversight of nuclear equipment manufacturing standards compresses factory fabrication schedules through regulatory coordination with state-owned construction enterprises. The Yangtze River Delta concentration of heavy industry creates concentrated demand for process heat applications above 500°C outlet temperatures.
Japan
Restart approvals for existing nuclear capacity are creating regulatory momentum for advanced reactor demonstrations at industrial coastal sites. METI's technology roadmap prioritizes high-temperature gas reactors for hydrogen export competitiveness under regional decarbonization commitments. The Chubu region around Nagoya maintains forging and precision manufacturing capabilities applicable to pressure vessel module production.
Small Modular Reactor (SMR) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology-origin companies commanding design certification premiums while fabrication partners absorb construction execution risk. The vendor base concentrates around three strategic archetypes: established nuclear engineering houses with regulatory relationships, advanced reactor startups with non-light-water designs, and diversified industrial conglomerates with captive supply chain assets. Competitive positioning hardens through M&A activity targeting ASME N-stamp certified fabrication capacity, and through strategic partnerships locking in long-term power purchase agreements before 2030 interconnection windows close.
Within the established engineering tier, Westinghouse Electric Company and GE Hitachi Nuclear Energy occupy positions anchored by decades of light-water reactor operational data and NRC relationship infrastructure. NuScale Power exemplifies the first-mover certification advantage through its Part 52 design approval, while TerraPower sits within the advanced non-light-water category navigating the Part 53 risk-informed pathway. These three represent divergent strategic bets on regulatory timeline compression versus technology differentiation.
| Leading Market Players |
|---|
| Westinghouse Electric Company |
| X-energy |
| NuScale Power |
| BWX Technologies |
| Holtec International |
| TerraPower |
| GE Hitachi Nuclear Energy |
| Oklo Inc. |
| Rolls-Royce SMR |
| Others |
Value Network & Pricing Analysis
Factory fabrication of pressure vessel modules is compressing capital costs while concentrating manufacturing investment in regions with nuclear-qualified welding labor pools. This production-method transition simultaneously reduces field construction premiums and reshapes supplier pricing power toward forge shops capable of ASME N-stamp certification.
Pricing Analysis
Direct-to-utility procurement discounts dominate reactor vendor pricing, bypassing traditional EPC markups through unbundled equipment supply contracts. Project-based long-term offtake agreements stratify across certification tiers, with NRC Part 52 approved designs commanding premiums over Part 53 pathway alternatives. Cost compression in first-of-a-kind builds is intensifying because utilities demand fixed-price commitments before design certification completion. Merchant power developers in Texas exhibit highest price sensitivity, while data center operators in Virginia prioritize delivery certainty over capital cost minimization.
Supply Chain Analysis
Domestic-content mandates in the Inflation Reduction Act are reshaping sourcing patterns for pressure vessel forgings and specialized welding services. Manufacturing concentration centers on the United States, Canada, and the United Kingdom, with feedstock dependencies on high-assay low-enriched uranium, zirconium alloy tubing, and nuclear-grade steel forgings. Single-source vulnerability runs through commercial HALEU enrichment capacity. Distribution feeds from centralized forging facilities in Ohio and Pennsylvania through specialized heavy-haul logistics to installation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Small Modular Reactor market functions as a regulatory compounder where NRC Part 53 framework deployment creates accelerating certification velocity for advanced designs. This licensing milestone compresses timelines sufficiently to unlock utility capital commitments before interconnection windows close.
For Market Incumbents: Hedge first-mover certification advantage through parallel Part 53 docket investments before sodium-cooled fast reactor designs achieve regulatory parity. Secure captive supply of ASME N-stamp certified welding capacity to defend against fabrication bottlenecks. Anchor utility partnerships through long-term power purchase agreements that transfer construction risk to specialized nuclear EPC firms. For New Entrants and Emerging Players: Enter via industrial process heat applications in the US Gulf Coast where chemical producers seek steam purchase agreements displacing natural gas-fired boilers. Target remote mining installations in northern Canada requiring transportable units with minimal grid infrastructure. Pursue technology licensing partnerships with established forge shops rather than greenfield manufacturing investments. For Investors and Strategic Acquirers: Valuations sit cheapest among advanced reactor startups navigating Part 53 risk-informed pathways before regulatory clarity arrives. Five-to-ten year viability hinges on successful design certification completion rather than commercial operation date achievement. Monitor HALEU supply chain expansion signals as inflection indicator for advanced reactor fuel loading viability.| Strategic Initiative | Industry Significance |
|---|---|
| Design Certification Completion | NRC Part 52 or Part 53 approval unlocks utility procurement and project finance closure. |
| Power Purchase Agreement Execution | Data center operators in Virginia and Texas anchor baseload offtake for SMR fleets. |
| HALEU Supply Agreement | Department of Energy enrichment program secures fuel pathways for advanced reactor designs. |
| Forge Shop Partnership | Ohio and Pennsylvania retooling agreements compress pressure vessel fabrication schedules. |
| Industrial Heat Contracting | Gulf Coast chemical producers evaluate steam purchase agreements for ammonia synthesis decarbonization. |
Research Methodology
Coverage spans the United States, Canada, the United Kingdom, China, and Japan, with primary inputs from each jurisdiction's regulatory and deployment landscape. The analysis combines structured interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists alongside secondary validation through NRC docket filings, EIA project databases, IEA technology roadmaps, and FERC interconnection queue records. Bottom-up project pipeline aggregation triangulates against top-down regulatory capacity forecasts.
Granularity-level modeling extends to reactor technology type, end-user segment, deployment modality, and application across the projection horizon. The analytical framework derives expansion trajectories through installed base evolution and replacement demand cycles. Segmentation dimensions include pressurized water versus non-light-water designs, utility versus industrial offtake structures, and electricity generation versus hydrogen production applications. Forecast inputs incorporate licensing timeline assumptions and production tax credit eligibility thresholds.
The model holds under sustained regulatory streamlining and HALEU supply expansion; deviation in certification delays or enrichment bottlenecks would shift commercial operation timelines. Forecasts reflect documented assumptions regarding interconnection queue clearance and forge shop capacity scaling. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
Global Power Plant Uranium Market
Nuclear Energy
Thorium Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Japan Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Reactor Construction Market