
 Kazakhstan Oil and Gas Midstream Market | 2026-2036
Kazakhstan Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Kazakhstan Oil and Gas Midstream Market Foresight
Tengizchevroil's expanded sour crude processing complex is pivoting Kazakhstan's midstream capacity toward higher-throughput, corrosion-resistant pipeline specifications. KazTransOil leverages its monopoly over the domestic trunk pipeline network to sustain throughput allocation leverage across western producing basins. Caspian Pipeline Consortium anchors export route reliability with its dedicated CPC-R pipeline system to Novorossiysk. Karachaganak Petroleum Operating competes for alternative export channel access through the Atyrau-Samara corridor.
Kazakhstan oil and gas midstream encompasses the transportation, storage, and terminal handling of hydrocarbons between wellheads and downstream processing facilities, operating pipeline systems rated for high-sulfur crude metallurgy and extreme continental temperature swings from minus forty to plus forty degrees Celsius. Its primary commercial purpose is to bridge extraction sites in the Caspian and Pre-Caspian basins with domestic refineries and Black Sea export terminals while maintaining flow assurance. Pipeline infrastructure dominates capital deployment given the thousand-kilometer distances between western fields and consumption or export points, while SCADA and leak detection technology represents the fastest-growing technology category as operators digitize aging Soviet-era control systems. Tank farms near Atyrau and Aktau handle seasonal demand fluctuations and transit storage obligations.
Kazakhstan's Committee for Industrial Development and Industrial Safety enforces technical regulations harmonized with Eurasian Economic Union standards, mandating pipeline pressure testing intervals and corrosion monitoring protocols that shape maintenance spending cycles. The country's environmental regulator, operating under the Ministry of Ecology and Natural Resources, imposes emissions controls on compressor stations and vapor recovery requirements at loading terminals that influence equipment procurement specifications. Stakeholders must monitor how Caspian transit corridor negotiations and evolving EAEU tariff harmonization rules reshape route economics for new production streams.
Market Dynamics
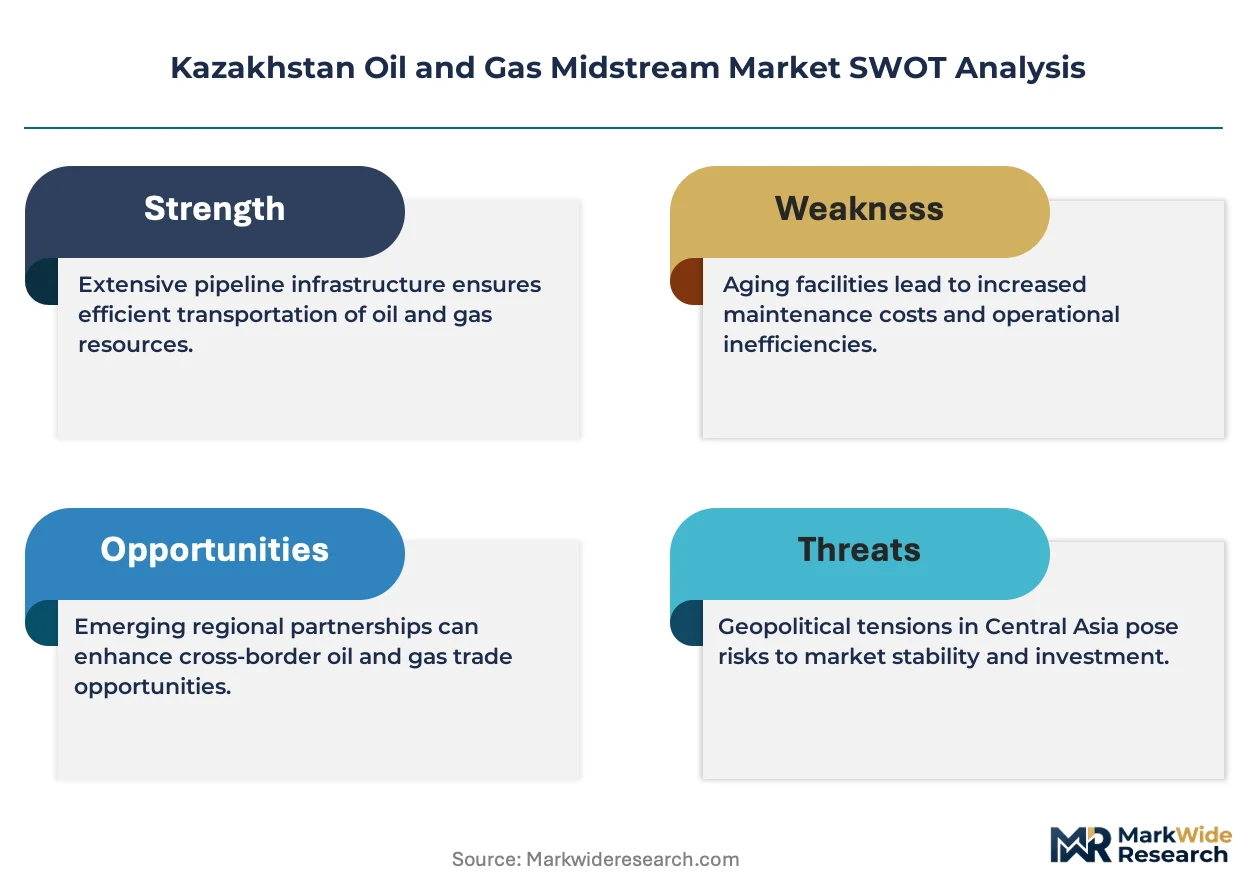
KazTransOil's monopoly over domestic trunk pipelines concentrates throughput allocation power in a single state entity, while Eurasian Economic Union technical regulations force corrosion-resistant metallurgy upgrades across aging Soviet-era infrastructure. This dual pressure—commercial leverage plus regulatory compliance—drives capital deployment toward digitized flow assurance systems.
Growth Catalysts
- Tengiz-Chevron western cluster expansion:High-sulfur crude processing requirements mandate specialized pipeline specifications, pulling investment toward sour-service metallurgy and hydrogen sulfide monitoring systems.
- EAEU technical regulation harmonization:Unified pressure testing intervals and corrosion protocols reduce cross-border certification friction for equipment suppliers serving Kazakh-Russian transit corridors.
- CPC-R dedicated export route:The Novorossiysk pipeline system anchors volume commitments from Karachaganak and Kashagan operators, locking in throughput visibility for midstream tariff planning.
Market Restraints
- Specialized alloy cost volatility:Nickel and molybdenum price swings directly impact corrosion-resistant pipeline procurement budgets, compressing margin visibility for trunk line construction projects.
- Single-operator pipeline concentration:KazTransOil's exclusive control over domestic trunk infrastructure creates bottleneck risk for western basin producers seeking alternative transport options.
- Extreme temperature metallurgy:Pipeline steel must withstand minus forty to plus forty degrees Celsius thermal cycling, limiting supplier qualification to a narrow tier of certified mills.
Strategic Opportunities
- SCADA digitization gap:Soviet-era control systems across Atyrau and Aktau tank farms create retrofit demand for integrated leak detection and predictive maintenance platforms.
- Kashagan offshore tie-in potential:Underdeveloped eastern Caspian infrastructure offers greenfield pipeline routing options bypassing congested western corridor bottlenecks.
- Compressor station emissions standards:Ministry of Ecology vapor recovery mandates open procurement windows for vapor combustion units and carbon capture pilots at loading terminals.
Industry Challenges
- Soviet-era SCADA integration complexity:Legacy analog control systems at Pavlodar and Atyrau refineries resist seamless interfacing with digital flow metering required by EAEU regulations.
- Specialized welding certification timelines:X80 and X100 sour-service pipeline grades demand qualified crews whose certification scarcity extends construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kazakhstan Oil and Gas Midstream Market |
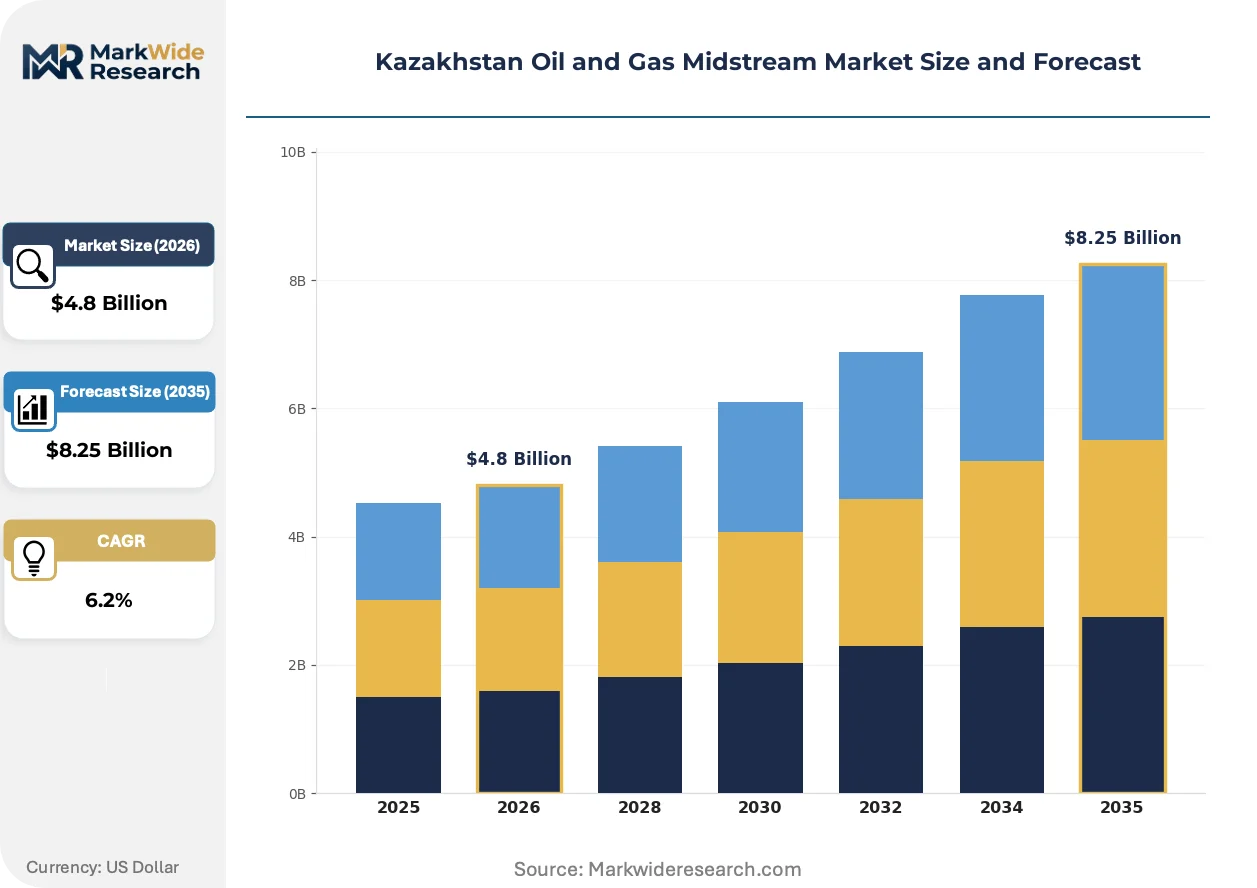
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Terminals, Handling Infrastructure Type: Pipelines, Tank Farms, Compressor Stations, Metering Stations End User: Refineries, Petrochemical Plants, Distributors, Industrial Consumers Technology: SCADA, GIS, Metering Systems, Leak Detection |
| Companies Covered | Transneft, Lukoil, KazTransOil, Karachaganak Petroleum Operating, Caspian Pipeline Consortium, KazMunayGas, China National Petroleum Corporation, North Caspian Operating Company, Tengizchevroil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kazakhstan Oil and Gas Midstream Market Shifts & Advancements
Pipeline digitization is compressing inspection cycles from annual manual surveys to continuous fiber-optic monitoring, while metallurgy advances enable thinner-wall designs for high-pressure sour service. These shifts are rewriting capital efficiency benchmarks across Kazakhstan's thousand-kilometer transport corridors.
Machine learning-driven predictive corrosion modeling is rewriting maintenance scheduling for trunk pipelines carrying Tengiz and Karachaganak high-sulfur crude. Kazakh operators are piloting these platforms at western compressor stations to anticipate wall-thinning before scheduled shutdowns. The technology is rewriting the trade-off between preventive replacement costs and unplanned outage penalties.
Eurasian Economic Union technical regulations now mandate ultrasonic flow meter calibration intervals and pressure-test documentation standards that exceed prior Kazakh national requirements. Pipeline operators must retrofit custody-transfer points along the Atyrau-Samara corridor to comply. Western basin export terminals face the steepest compliance costs given their higher throughput volumes.
Buyers now unbundle construction contracts from decade-long maintenance agreements, forcing equipment vendors to compete on standalone SCADA upgrade pricing. This procurement fragmentation is most visible at Aktau marine terminal expansions, where separate tenders for leak detection hardware and integration services have replaced single-source awards. Kazakh national operators are driving this shift to sharpen supplier accountability.
Kazakhstan Oil and Gas Midstream Market Segmentation
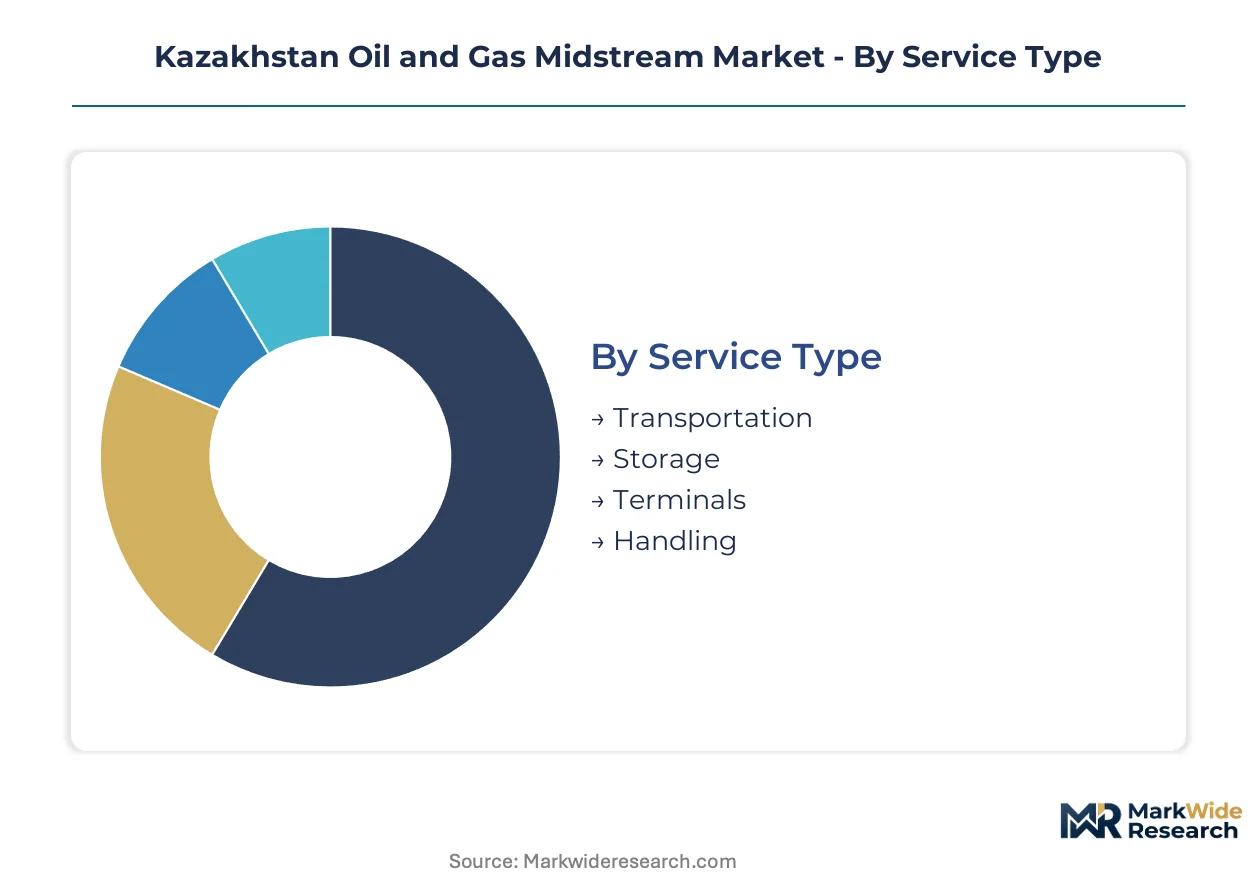
Kazakhstan's midstream infrastructure spans thousand-kilometer corridors where service specialization and technology integration determine tariff economics. Segment boundaries reflect metallurgical requirements for high-sulfur crude handling and Eurasian Economic Union compliance mandates that reshape procurement priorities.
Service Type:
Eurasian Economic Union technical regulations impose distinct certification burdens across service categories, with pressure-testing documentation requirements varying by hydrocarbon handling intensity.
- Transportation:Trunk pipeline operations dominate capital deployment, requiring X80 and X100 sour-service metallurgy certified for minus forty to plus forty degrees Celsius thermal cycling. Tengiz-Chevron western cluster volumes anchor throughput demand, with hydrogen sulfide monitoring systems now mandatory under EAEU harmonized standards.
- Storage:Tank farms at Atyrau and Aktau manage seasonal demand fluctuations and transit storage obligations for Caspian Pipeline Consortium commitments. The country's environmental regulator mandates vapor recovery systems at loading terminals, reshaping equipment procurement specifications.
- Terminals:Marine loading facilities at Aktau handle CPC-R export volumes to Novorossiysk, with custody-transfer metering retrofits required for EAEU ultrasonic flow meter calibration intervals.
- Handling:Pump station and valve maintenance services support continuous flow assurance across the KazTransOil monopoly network.
Leading the category by volume: Transportation. Expanding most quickly: Storage.
Infrastructure Type:
Cost tiers stratify sharply, with pipeline construction consuming seventy percent of sector capital against tank farm expansion at fifteen percent.
- Pipelines:Thousand-kilometer trunk systems linking western Caspian basins to Black Sea terminals demand corrosion-resistant alloys where nickel and molybdenum price volatility compresses procurement margins. Karachaganak Petroleum Operating competes for Atyrau-Samara corridor access against CPC-R dedicated routing.
- Tank Farms:Seasonal buffer capacity at Atyrau and Pavlodar refinery clusters absorbs production swings from Tengiz and Kashagan fields. EAEU pressure-testing intervals force shorter maintenance cycles than prior Kazakh national standards allowed.
- Compressor Stations:Ministry of Ecology emissions controls on turbine exhaust and vapor combustion units reshape equipment specifications at western basin facilities.
- Metering Stations:Custody-transfer points along export corridors require ultrasonic flow meter retrofits to satisfy EAEU documentation standards.
Highest capital intensity: Pipelines. Steepest compliance cost escalation: Metering Stations.
End User:
Application requirements diverge between domestic processing and export-bound streams, with refineries demanding sulfur tolerance that petrochemical plants rarely match.
- Refineries:Atyrau and Pavlodar facilities expand crude intake capacity, driving pipeline flow allocation negotiations with KazTransOil. High-sulfur crude processing requirements from Tengizchevroil expansion mandate specialized metallurgy on inbound trunk lines.
- Petrochemical Plants:Naphtha and feedstock supply chains from western fields require dedicated pipeline laterals with lower sulfur tolerance specifications.
- Distributors:Wholesale product offtake from domestic refineries depends on tank farm seasonal storage availability.
- Industrial Consumers:Regional fuel oil and diesel demand concentrates in Pavlodar industrial zones.
Dominant volume offtake: Refineries. Fastest infrastructure connection growth: Petrochemical Plants.
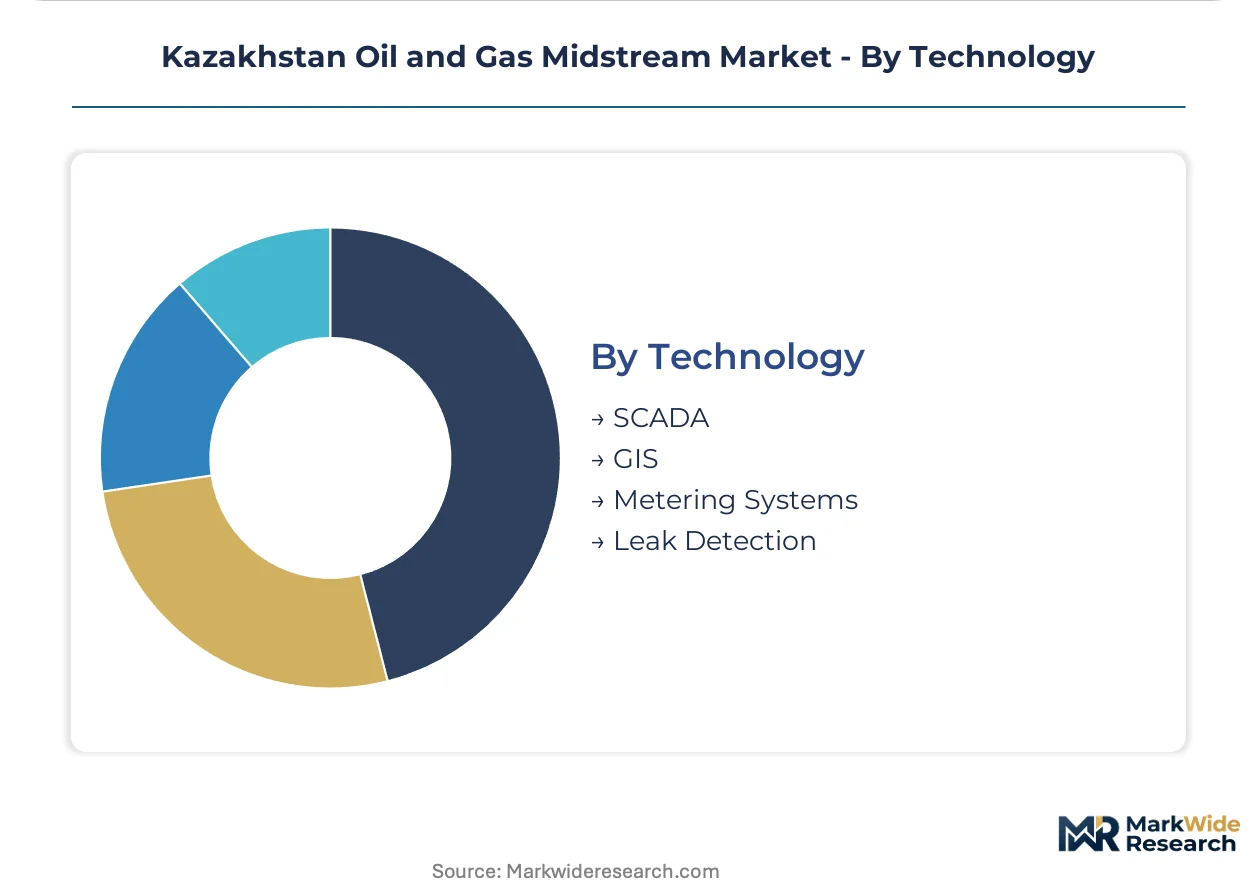
Technology:
Customer procurement patterns unbundle hardware from integration services, with SCADA vendors now competing on standalone upgrade pricing rather than decade-long maintenance bundling.
- SCADA:Digitization of Soviet-era analog control systems at Pavlodar and Atyrau refineries creates retrofit demand for integrated platforms. Machine learning-driven predictive maintenance pilots at western compressor stations anticipate wall-thinning before scheduled shutdowns.
- GIS:Pipeline route optimization and asset mapping supports thousand-kilometer corridor management across extreme continental terrain.
- Metering Systems:Ultrasonic flow meter calibration intervals mandated by Eurasian Economic Union technical regulations exceed prior Kazakh national requirements, forcing retrofit investment at custody-transfer points.
- Leak Detection:Fiber-optic continuous monitoring replaces annual manual surveys, compressing inspection cycles across aging Soviet-era infrastructure.
Widest installed base: SCADA. Steepest procurement growth trajectory: Leak Detection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tengiz and Karachaganak crude deposits anchor Kazakhstan's midstream geography, with pipeline corridors stretching across extreme continental terrain to reach Black Sea export terminals and domestic refining clusters.
Atyrau Region
Tengizchevroil's sour crude expansion and Karachaganak Petroleum Operating's field development drive trunk line demand through this western basin hub. The Committee for Industrial Development enforces Eurasian Economic Union pressure-testing intervals that reshape maintenance cycles. Atyrau city hosts the country's largest tank farm complex, where vapor recovery retrofits respond to Ministry of Ecology mandates.
Mangystau Region
Caspian Pipeline Consortium throughput commitments and Kashagan offshore tie-in potential concentrate infrastructure investment along this corridor. EAEU technical regulations mandate ultrasonic flow meter calibration at custody-transfer points. Aktau marine terminal handles CPC-R export volumes, with separate procurement tenders for leak detection hardware now replacing bundled awards.
Pavlodar Region
Domestic refinery expansion absorbs pipeline flow allocations from KazTransOil's monopoly network. Soviet-era SCADA systems at local refineries resist seamless interfacing with digital metering required by harmonized standards. The industrial zone processes high-sulfur inbound streams from western fields, demanding specialized metallurgy on connecting trunk lines.
Aktobe Region
Kenkiyak and Zhanazhol field production feeds into the Atyrau-Samara corridor, where Karachaganak Petroleum Operating competes for alternative export access against CPC-R routing. The region's compressor stations face emissions control upgrades under environmental regulator directives. Local pipeline laterals require X80 sour-service grades certified for extreme thermal cycling.
Almaty Region
Administrative and financial coordination for national pipeline projects concentrates in this southern commercial center. The Ministry of Ecology's national emissions framework originates here, shaping equipment specifications for western basin facilities. Logistics and procurement functions for KazMunayGas midstream subsidiaries operate from this urban hub.
Kazakhstan Oil and Gas Midstream Market Competitive Landscape
Global majors compete with regional champions across export corridor control, with trunk pipeline access determining competitive leverage. State monopoly structures concentrate throughput allocation power, while international consortium arrangements fragment operational control across Caspian transit routes. Two archetypes dominate: vertically integrated national oil companies and field-specific operating consortia. Capacity expansion and strategic partnerships represent the primary competitive moves, as operators secure dedicated export routes and digitize aging infrastructure.
Among Russia-based pipeline operators, Transneft occupies a position exemplifying cross-border transit leverage through the Atyrau-Samara corridor. Lukoil represents the integrated oil company archetype, with its presence reflecting broader Caspian basin engagement. KazTransOil anchors the state monopoly tier, its exclusive domestic trunk network control shaping competitive dynamics for western basin producers seeking flow allocation.
| Leading Market Players |
|---|
| Transneft |
| Lukoil |
| KazTransOil |
| Karachaganak Petroleum Operating |
| Caspian Pipeline Consortium |
| KazMunayGas |
| China National Petroleum Corporation |
| North Caspian Operating Company |
| Tengizchevroil |
| Others |
Supply & Pricing Matrix
SCADA digitization retrofits at Soviet-era control facilities simultaneously compress procurement timelines and concentrate supplier qualification among certified systems integrators. This technology transition reshapes both upfront capital allocation and long-term maintenance contracting across Kazakhstan's thousand-kilometer pipeline corridors.
Pricing Analysis
Decade-long maintenance bundling has given way to unbundled hardware and service procurement, with Kazakh national operators now tendering SCADA upgrades separately from integration contracts. Three-tier pricing structure across premium certified systems, standard EAEU-compliant packages, and economy analog retrofits reflects certification depth and vendor track record. Cost compression in standard-tier packages is intensifying because qualified integrator scarcity limits competitive pressure at the premium end. Domestic refinery operators exhibit highest price sensitivity given budget constraints, while export corridor joint ventures prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Atyrau and Aktau anchor hub-and-spoke patterns for corrosion-resistant alloy procurement, with inventory positioning critical given thousand-kilometer field-to-terminal distances. Manufacturing concentration rests on Germany, Japan, and South Korea for X80 and X100 sour-service steel grades certified to Eurasian Economic Union standards. Nickel and molybdenum price volatility creates margin unpredictability for trunk line construction budgets. Distribution runs through KazTransOil's centralized procurement function, which aggregates demand across western basin infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kazakhstan's midstream capacity expansion runs ahead of qualified welding crew availability, with X80 and X100 certification scarcity propping contractor pricing power across the western basin.
For Market Incumbents: Lock in exclusive maintenance contracts with Tengizchevroil and Karachaganak Petroleum Operating before alternative service providers achieve EAEU certification. Secure backward integration into specialized alloy stockpiling to buffer nickel and molybdenum price swings. Threat: emerging Russian and Chinese pipeline service entrants leveraging lower labor cost structures. For New Entrants and Emerging Players: Launch via SCADA integration partnerships with established European automation vendors lacking Kazakh field presence. Target the Atyrau tank farm complex, where Soviet-era analog systems resist seamless digital retrofit and incumbent integrators face capacity constraints. Go-to-market angle: predictive corrosion modeling platforms piloted at western compressor stations. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to national oil companies seeking captive midstream capability. Five-to-ten year viability hinges on Eurasian Economic Union tariff harmonization sustaining route economics for Caspian export volumes. Acquisition target archetype: certified welding contractors with X100 sour-service qualifications. Signal to watch: Kashagan eastern Caspian tie-in approvals triggering greenfield pipeline routing demand.| Strategic Initiative | Industry Significance |
|---|---|
| SCADA Platform Integration | Machine learning-driven predictive maintenance at Tengizchevroil compressor stations reduces unplanned outage penalties. |
| Corrosion-Resistant Alloy Stockpiling | Strategic nickel and molybdenum inventory buffers procurement margin compression from commodity price volatility. |
| EAEU Certification Investment | Ultrasonic flow meter calibration capabilities unlock custody-transfer retrofit contracts along Atyrau-Samara corridor. |
| Specialized Welding Crew Expansion | X80 and X100 sour-service certification programs address construction schedule extensions from qualified labor scarcity. |
| Leak Detection Technology Deployment | Fiber-optic continuous monitoring replaces annual manual surveys across aging Soviet-era trunk pipelines. |
Research Methodology
Multi-period observation of throughput allocation patterns, EAEU regulatory implementation timelines, and western basin production expansion anchored the trend analysis, supplemented by interviews with pipeline operations directors, SCADA systems integrators, corrosion engineering specialists, and procurement managers at KazMunayGas subsidiaries. Secondary validation drew from KazTransOil tariff filings, Eurasian Economic Union technical regulation databases, Caspian Pipeline Consortium throughput disclosures, and customs records for corrosion-resistant alloy imports. Bottom-up project pipeline assessment triangulated against top-down sector expenditure estimates.
Segment-weighting across service type, infrastructure category, end-user application, and technology deployment model shaped volume and value distribution. CAGRs were derived from installed base expansion rates, replacement cycle analysis, and regulatory compliance-driven retrofit demand. Forecast inputs incorporated Tengizchevroil expansion schedules, Kashagan offshore tie-in feasibility, and EAEU harmonization implementation phases across the projection horizon.
Commodity price volatility in nickel and molybdenum markets, regulatory enforcement variance across Kazakh regions, and Caspian transit corridor negotiation outcomes are the dominant revision risks to throughput and expenditure assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
United Kingdom LNG Market
Oil & Gas
Wellhead System Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
Tight Gas Market
Oil & Gas
Oil and Gas Gasket Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Connected Oil and Gas Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Enhanced Gas Recovery (EGR) Market