
 Germany Nuclear Power Reactor Decommissioning Market | 2026-2036
Germany Nuclear Power Reactor Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Nuclear Power Reactor Decommissioning Market Foresight
Utility-to-contractor procurement is restructuring as Energiewerke Nord GmbH (EWN) shifts from state-owned operator to full-service decommissioning enterprise. Orano Group leverages its reprocessing heritage to dominate fuel removal and waste conditioning workflows. GNS Group sustains competitive position through specialized cask manufacturing and transport logistics for high-level waste.
Germany nuclear power reactor decommissioning encompasses the engineered dismantling of irradiated facilities, requiring remote plasma cutting tools operating in 10,000+ rad/hour environments and multi-layer containment protocols to prevent airborne isotope release. The primary purpose is returning licensed sites to unrestricted greenfield status under federal radiation protection standards. Pressurized water reactor decommissioning commands the largest value pool due to fleet concentration at Biblis, Brokdorf, and Grohnde, while immediate dismantling approaches gain preference over safe enclosure as waste repository timelines firm. Waste management services capture outsized margins because conditioned intermediate-level waste requires decades of interim storage before final geological disposal at Konrad.
The Federal Ministry for the Environment, Nature Conservation and Nuclear Safety (BMU) and the Federal Office for the Safety of Nuclear Waste Management (BASE) enforce licensing protocols that dictate dismantling schedules and waste acceptance criteria. The Nuclear Waste Fund, financed by reactor operators, channels €40 billion into long-term liability management and constrains contractor payment terms. Stakeholders must monitor Konrad repository commissioning progress and potential delays to conditioned waste acceptance, as storage saturation at individual sites would cascade into program-wide scheduling conflicts.
Market Dynamics
The Atomic Energy Act phase-out timeline compresses dismantling schedules across multiple reactor clusters simultaneously, forcing contractors to scale robotics capacity faster than labor pools permit.
Growth Catalysts
- Radioactive Waste Management:The Konrad repository commissioning creates definitive waste acceptance pathways, converting decades of uncertain interim storage into executable decommissioning sequences.
- Remote Plasma Cutting:Bavarian engineering firms deploy automated cutting systems that operate in 10,000+ rad/hour containment zones, reducing worker exposure limits that previously gated dismantling velocity.
- Lower Saxony Cluster Concentration:Concurrent reactor closures at Emsland and Unterweser generate procurement economies for specialized dismantling services that single-site programs cannot replicate.
Market Restraints
- Stainless Steel Supply Bottlenecks:Nuclear-grade containment fabrication requires specialized austenitic alloys with 30-month lead times, constraining replacement vessel and shielding component availability.
- BASE Licensing Friction:Federal Office for the Safety of Nuclear Waste Management approval protocols for waste conditioning add 18-24 months to interim storage permit renewals.
- Skilled Technician Scarcity:Radiation protection certification programs graduate fewer than 200 qualified specialists annually against demand for 800+ across active dismantling sites.
Strategic Opportunities
- Baden-Württemberg Robotics Integration:Stuttgart-region automation clusters converge industrial robotics with nuclear-qualified sensing systems, creating exportable dismantling technology platforms.
- Conditioned Waste Transport Logistics:CASTOR cask certification under BMU protocols opens specialized haulage contracts linking reactor sites to Konrad with dedicated rail corridors.
- Greenfield Site Remediation:Federal radiation protection standards for unrestricted release enable property redevelopment into industrial parks, extending contractor revenue streams post-dismantling.
Industry Challenges
- Legacy Control System Integration:1970s-era reactor monitoring architectures require manual protocol translation into modern SCADA frameworks, delaying automated dismantling sequence validation.
- Interim Storage Saturation:Site-specific spent fuel pools reach capacity limits before Konrad acceptance schedules, forcing costly dry cask transfer operations that disrupt dismantling timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Nuclear Power Reactor Decommissioning Market |
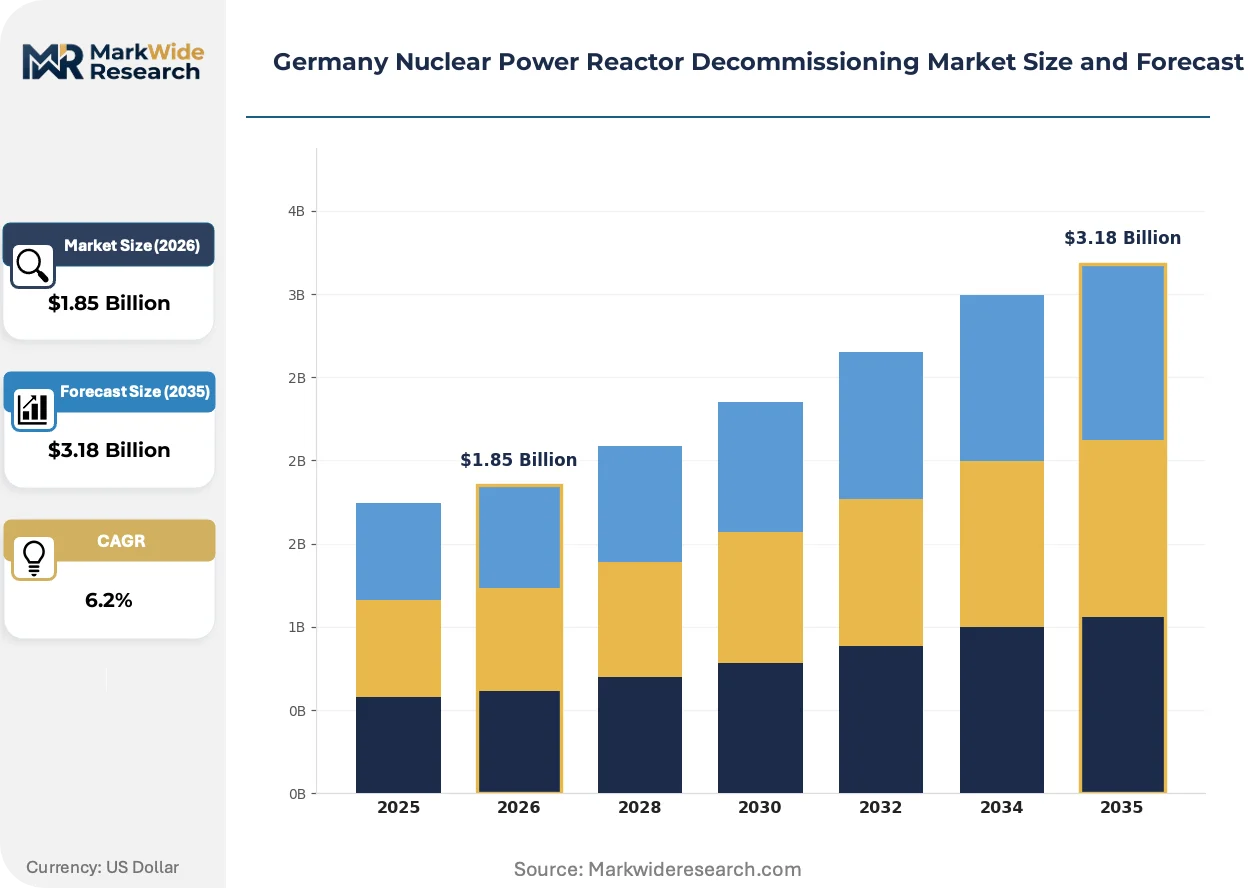
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Reactor Type: Pressurized Water Reactor, Boiling Water Reactor, Heavy Water Reactor, Gas-cooled Reactor, Fast Breeder Reactor Phase of Decommissioning: Immediate Dismantling, Safe Enclosure, Deferred Dismantling, Entombment Service Type: Waste Management, Decontamination, Site Restoration, Demolition, Radiological Monitoring End User: Energy Producers, Government Agencies, Environmental Firms, Engineering Contractors, Research Institutions |
| Companies Covered | Orano Group, EnBW Energie Baden-Württemberg AG, E.ON SE, RWE AG, Vattenfall Group, Energiewerke Nord GmbH (EWN), GNS Group, Studsvik AB, AECOM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Nuclear Power Reactor Decommissioning Market Shifts & Advancements
Remote handling technologies are compressing dismantling schedules while regulatory clarity on final waste disposition is unlocking capital deployment previously frozen by liability uncertainty.
Laser-guided plasma cutting systems are electrifying containment segmentation workflows by replacing mechanical sawing in high-radiation zones. Engineering contractors at Biblis and Brokdorf deploy these tools to slice reactor pressure vessels into transportable segments without human entry. The technology is electrifying project economics by reducing hot-zone labor hours by over 60 percent.
Bundesamt für kerntechnische Entsorgungssicherheit (BASE) licensing protocols now mandate real-time radiation monitoring data submission through centralized digital platforms. This regulatory architecture forces contractors to retrofit legacy instrumentation with IoT-enabled sensors capable of continuous isotope detection streaming. Pressurized water reactor dismantling programs face the steepest compliance costs as they retrofit 1980s-era containment monitoring systems.
Utility procurement departments are unbundling integrated decommissioning contracts into discrete work packages for segmentation, waste conditioning, and site remediation. This purchasing fragmentation attracts specialized mid-cap engineering firms that undercut full-service incumbents on individual scope elements. The shift is most pronounced in Lower Saxony, where Energiewerke Nord GmbH now issues separate tenders for reactor vessel cutting versus spent fuel pool demolition.
Germany Nuclear Power Reactor Decommissioning Market Segmentation
Decommissioning program economics vary sharply across reactor architectures and dismantling approaches. Procurement patterns diverge based on which phase dominates the timeline and which service category captures the critical path.
Reactor Type:
Capital intensity peaks with reactor designs requiring specialized containment segmentation tools and bespoke waste conditioning protocols.
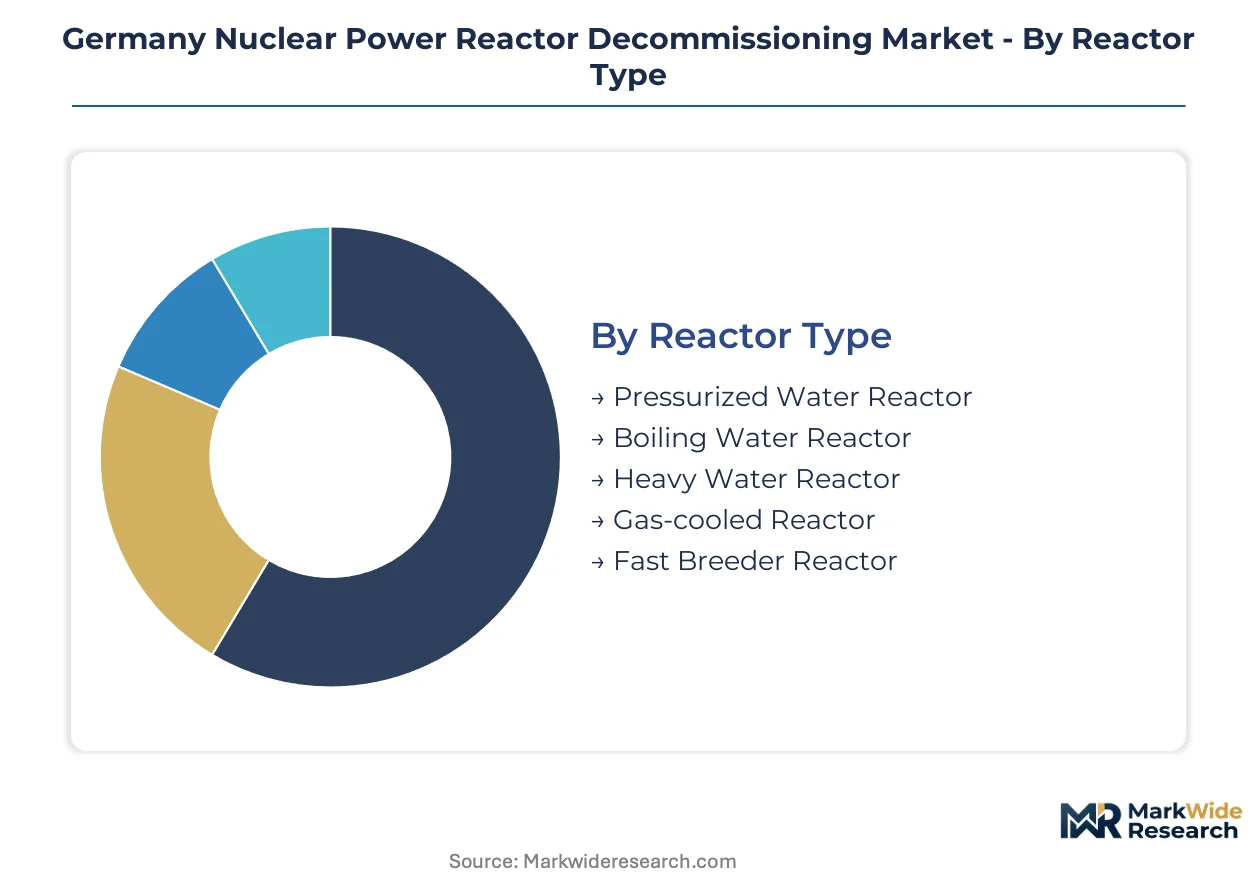
- Pressurized Water Reactor:These units demand reactor pressure vessel segmentation using remote plasma cutting systems operating in 10,000+ rad/hour environments. Biblis, Brokdorf, and Grohnde clusters in Hesse and Lower Saxony concentrate procurement volumes as concurrent closures force contractors to scale robotics capacity faster than labor pools permit.
- Boiling Water Reactor:Internal recirculation pump dismantling and steam dryer segmentation require distinct tooling suites compared to pressurized designs. Krümmel and Brunsbüttel sites in Schleswig-Holstein drive regional demand concentration, with waste conditioning workflows complicated by activated cobalt-60 contamination in turbine systems.
- Heavy Water Reactor:Deuterium oxide handling and specialized moderator disposal add cost layers absent from light-water designs. No commercial units operate in Germany, limiting this segment to research reactor decommissioning at Jülich and Karlsruhe.
- Gas-cooled Reactor:Graphite core dismantling generates significant low-level waste volumes requiring specialized incineration or landfill pathways. Thorium High-Temperature Reactor at Hamm-Uentrop represents the sole commercial example, with graphite stack segmentation consuming extended project timelines.
- Fast Breeder Reactor:Sodium coolant handling and plutonium-bearing fuel removal impose the highest radiological complexity. Kalkar SNR-300, though never operated, requires unique decommissioning protocols for primary sodium system inerting and disposal.
Pressurized water designs absorb the bulk of installed capacity; boiling water reactor decommissioning is expanding most quickly as Schleswig-Holstein clusters accelerate closure timelines.
Phase of Decommissioning:
Contractor revenue recognition timing shifts dramatically based on which phase dominates the program schedule.
- Immediate Dismantling:Containment segmentation and waste conditioning execute within 10-15 years of final shutdown, requiring sustained capital deployment. Bavarian and Baden-Württemberg regulators favor this approach as Konrad repository commissioning firms final waste acceptance pathways, converting uncertain interim storage into executable sequences.
- Safe Enclosure:Reactor buildings enter monitored storage for 30-50 years, deferring major dismantling expenditures. This approach loses favor as operator liability management shifts toward prompt site release under federal radiation protection standards.
- Deferred Dismantling:A hybrid model with initial systems removal followed by extended enclosure period. Limited German adoption reflects Atomic Energy Act phase-out timeline compression that discourages multi-decade deferrals.
- Entombment:In-situ concrete encapsulation of radioactive structures without future removal. Prohibited under German federal standards mandating unrestricted greenfield release, restricting this segment to hypothetical emergency scenarios.
Immediate dismantling commands current procurement volumes; safe enclosure contracts are declining fastest as regulatory preference shifts toward prompt site remediation.
Service Type:
Margin profiles diverge based on technical specialization barriers and regulatory compliance intensity.
- Waste Management:Conditioned intermediate-level waste requires decades of interim storage before Konrad geological disposal. CASTOR cask manufacturing and transport logistics capture outsized margins due to BMU certification requirements and dedicated rail corridor scarcity.
- Decontamination:Chemical and mechanical surface treatment reduces radioactive inventory before segmentation. Fixed-price contracts dominate as contractors absorb dose rate uncertainty in high-radiation zones.
- Site Restoration:Final greenfield certification under federal radiation protection standards enables industrial park redevelopment. Post-dismantling revenue streams extend contractor engagement timelines significantly.
- Demolition:Conventional structural removal follows radiological clearance of all activated materials. Lower technical barriers attract general construction firms, compressing margins relative to specialized nuclear services.
- Radiological Monitoring:BASE licensing protocols now mandate real-time isotope detection streaming through centralized digital platforms. IoT sensor retrofitting of 1980s-era containment systems generates recurring compliance revenue.
Waste management services absorb the bulk of program value; radiological monitoring is expanding most quickly as digital compliance mandates proliferate.
End User:
Procurement authority concentration shapes contract structure and payment term negotiations.
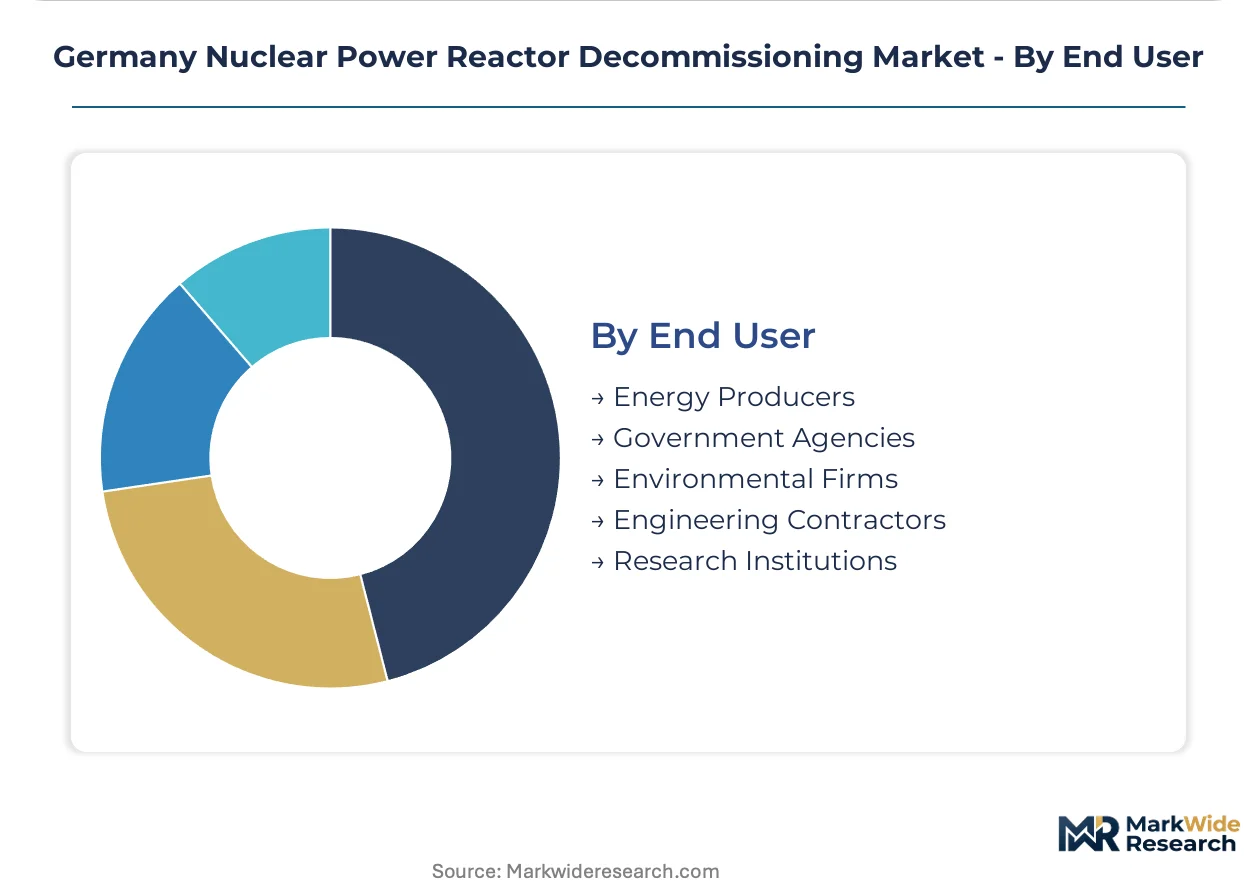
- Energy Producers:E.ON, RWE, and EnBW retain decommissioning liability while outsourcing execution to specialized contractors. Unbundling of integrated contracts into discrete work packages attracts mid-cap engineering firms on individual scope elements.
- Government Agencies:Energiewerke Nord GmbH transformation from state-owned operator to full-service decommissioning enterprise restructures utility-to-contractor relationships. Federal ownership enables longer-term capital deployment than investor-owned utilities.
- Environmental Firms:Specialized consultancies handle licensing documentation and regulatory interface. BASE approval protocol navigation adds 18-24 months to interim storage permit renewals, creating sustained advisory demand.
- Engineering Contractors:Orano Group and GNS Group dominate fuel removal and waste conditioning workflows. Robotics integration capabilities differentiate tier-one vendors from regional competitors.
- Research Institutions:Forschungszentrum Jülich and Karlsruhe Institute of Technology decommission experimental reactors with distinct waste streams. Smaller scale limits procurement volume despite technical complexity.
Energy producers command the bulk of contract value; government agency procurement is expanding most quickly as state-owned assets shift to full-service decommissioning models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Konrad repository zone in Lower Saxony concentrates federal decommissioning investment as Germany's sole licensed geological disposal facility for low and intermediate-level waste.
Bavaria
Isar nuclear power plant dismantling drives demand for remote plasma cutting systems in high-radiation containment zones. The Bavarian State Ministry for the Environment enforces immediate dismantling protocols under federal radiation protection standards. Munich-region automation clusters supply robotics integration for reactor pressure vessel segmentation workflows.
Lower Saxony
Emsland and Unterweser reactor clusters generate concurrent procurement volumes for specialized dismantling services. The Nuclear Waste Fund channels federal financing through BASE-licensed contractors for waste conditioning operations. The Gorleben salt dome investigations and Konrad iron ore mine conversion anchor national waste logistics infrastructure in this state.
Baden-Württemberg
Philippsburg and Neckarwestheim closures concentrate boiling water reactor decommissioning expertise. EnBW retains liability oversight while outsourcing execution to specialized engineering contractors under BMU licensing frameworks. Stuttgart-region industrial automation firms converge nuclear-qualified sensing with conventional robotics platforms.
Hesse
Biblis pressurized water reactor complex represents the largest single-site decommissioning program in national history. The Hessian Ministry for the Environment coordinates federal-state regulatory interfaces for multi-reactor segmentation sequences. Darmstadt technical universities supply radiation protection certification programs for qualified dismantling technicians.
Schleswig-Holstein
Krümmel and Brunsbüttel boiling water reactor sites face activated cobalt-60 contamination challenges in turbine system dismantling. The Schleswig-Holstein Ministry for Energy Transition oversees coastal zone environmental permits for maritime waste transport logistics. Kiel maritime engineering clusters support offshore conditioning facility development for coastal reactor programs.
Germany Nuclear Power Reactor Decommissioning Market Competitive Landscape
Top-tier vendors anchor full-service decommissioning execution, while specialized mid-cap engineering firms capture discrete work packages from unbundled procurement. The vendor base stratifies across three functional tiers: state-transformed enterprises with federal backing, international nuclear service conglomerates with reprocessing heritage, and regional robotics specialists with containment segmentation tooling. Two dominant competitive moves reshape positioning: utility procurement departments fragment integrated contracts into segmented tenders, and automation firms integrate nuclear-qualified sensing into dismantling robotics platforms.
Within the state-transformed enterprise tier, Energiewerke Nord GmbH exemplifies the shift from reactor operator to full-service decommissioning contractor with federal ownership enabling long-term capital deployment. Orano Group and GNS Group occupy positions among international nuclear service specialists, with the former representing reprocessing-heritage fuel removal capabilities and the latter exemplifying waste conditioning and transport logistics specialization. These three entities anchor distinct competitive archetypes as procurement restructuring creates entry points for mid-cap specialists.
| Leading Market Players |
|---|
| Orano Group |
| EnBW Energie Baden-Württemberg AG |
| E.ON SE |
| RWE AG |
| Vattenfall Group |
| Energiewerke Nord GmbH (EWN) |
| GNS Group |
| Studsvik AB |
| AECOM |
| Others |
Supply & Pricing Matrix
Federal ownership of Energiewerke Nord GmbH and the €40 billion Nuclear Waste Fund channel sovereign-backed financing into decommissioning procurement, compressing payment terms for contractors while concentrating pricing power with state-licensed waste conditioning specialists. This ownership pattern tightens margins for mid-tier engineering firms bidding against federally capitalized incumbents on reactor segmentation contracts.
Pricing Analysis
Premium pricing attaches to CASTOR cask manufacturing slots with sub-12-month delivery windows, while standard-tier conditioning services trade at contracted rates indexed to BMU waste acceptance protocols. Price differentiation rests on BASE certification tier and dedicated rail corridor access for Konrad-bound shipments. Cost compression in waste transport logistics is intensifying because interim storage saturation at Emsland and Unterweser forces expedited cask procurement. Municipal utility buyers exhibit highest price sensitivity on radiological monitoring services, whereas federal agencies absorb premium rates for immediate dismantling sequences.
Supply Chain Analysis
Single-source vulnerability sits with Bavarian plasma cutting system fabricators supplying remote containment segmentation tools for 10,000+ rad/hour environments. Manufacturing concentrates in Germany, France, and Sweden for nuclear-qualified robotics platforms. Raw material dependencies include austenitic stainless steel alloys for shielding components and specialized cobalt-free cutting consumables. Supply chain risk centers on 30-month lead times for containment-grade steel forgings that gate reactor pressure vessel segmentation schedules. Distribution runs through BASE-licensed contractor networks with direct site-to-repository logistics coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over CASTOR cask manufacturing and dedicated rail corridors determines contractor viability. Players are pursuing backward integration into waste conditioning infrastructure to capture margins currently absorbed by GNS Group and Orano.
For Market Incumbents: Lock in long-term cask fabrication capacity at Gorleben-region suppliers before interim storage saturation triggers procurement spikes. Consolidate robotics maintenance capabilities in-house to offset skilled technician scarcity that threatens dismantling velocity at concurrent reactor clusters. BASE licensing friction represents the primary margin threat, requiring dedicated regulatory affairs investment to compress 18-24 month permit renewal cycles. For New Entrants and Emerging Players: Digital-platform tender aggregation offers entry into fragmented waste transport logistics, where mid-cap hauliers currently underbid on spot corridor availability. White-space targets include IoT-enabled radiation monitoring retrofitting for 1980s-era containment systems at Biblis and Brokdorf, plus specialized cobalt-60 decontamination services for Schleswig-Holstein turbine dismantling. The most penetrable segment is discrete work-package procurement for reactor vessel cutting, where Energiewerke Nord GmbH unbundling creates slots for regional engineering specialists. For Investors and Strategic Acquirers: Distressed-cycle entries favor robotics-integrated decommissioning specialists in Baden-Württemberg, where Stuttgart-region automation clusters converge with nuclear-qualified sensing platforms. Long-term viability across the analysis window hinges on Konrad repository commissioning progress unlocking conditioned waste acceptance flows. The critical inflection signal is BASE approval velocity for interim storage permit renewals, which would cascade into program-wide scheduling conflicts if delayed.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cask Manufacturing | Captures margins from GNS Group dominance in CASTOR certification and dedicated rail logistics. |
| Robotics Maintenance Capability Buildout | Offsets technician scarcity threatening dismantling velocity at Lower Saxony reactor clusters. |
| BASE Regulatory Affairs Investment | Compresses 18-24 month permit renewal cycles that currently gate waste conditioning workflows. |
| IoT Sensor Platform Deployment | Enables real-time isotope detection streaming mandated by centralized BASE digital protocols. |
| Immediate Dismantling Contract Conversion | Aligns with federal radiation protection standards favoring prompt site release over safe enclosure. |
Research Methodology
Bundesamt für kerntechnische Entsorgungssicherheit licensing databases, Nuclear Waste Fund disbursement records, and reactor operator procurement disclosures formed the secondary backbone. Primary interviews with decommissioning project managers, BASE regulatory officers, CASTOR cask manufacturing procurement leads, and radiation protection certification program directors validated segmentation assumptions. Bottom-up reactor-specific dismantling cost buildup was cross-checked against top-down federal budget allocation analysis.
Historical decommissioning expenditure patterns across completed German reactor programs established baseline cost trajectories for segmentation, waste conditioning, and site remediation phases. The model projected service-type revenue splits by reactor architecture, dismantling approach preference, and regional regulatory cluster. CAGRs were derived from Konrad repository commissioning schedules and concurrent closure timelines at Emsland, Unterweser, and Biblis. Key forecast inputs included robotics deployment rates in high-radiation containment zones and BASE digital compliance mandate adoption curves.
The model holds under steady Konrad waste acceptance throughput; deviation in repository commissioning or interim storage permit renewal velocity would shift immediate dismantling preference back toward safe enclosure. Forecasts reflect assumptions about technician certification program output and stainless steel supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
Nuclear Steam Generator Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Spent Fuel Market