
 North America Nuclear Power Reactor Decommissioning Market | 2026-2036
North America Nuclear Power Reactor Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nuclear Power Reactor Decommissioning Market Analytics
Long-term stewardship service contracts is consolidating as the dominant commercial model in North America nuclear decommissioning, shifting revenue from discrete project awards to multi-decade liability management agreements. Fluor Corporation leverages its integrated engineering-procurement-construction capabilities to capture full-cycle decommissioning programs. EnergySolutions anchors its position through specialized low-level radioactive waste logistics and disposal infrastructure. Westinghouse Electric Company differentiates via proprietary segmentation and packaging technologies for spent fuel management.
Nuclear power reactor decommissioning encompasses the engineered dismantlement, decontamination, and site remediation of irradiated nuclear facilities to achieve unrestricted or restricted release status, typically requiring remote-handled robotic systems capable of operating in dose rates exceeding 1,000 rem per hour. The primary industrial purpose centers on eliminating radiological hazards while recovering reusable materials and restoring land for alternate commercial use. Dismantling services command the largest value share given the labor-intensive structural segmentation of reactor pressure vessels and biological shields. Robotic systems represent the fastest-expanding technology category as operators deploy autonomous platforms to minimize human exposure in high-radiation zones. Waste management functions as the most margin-protected segment due to the scarcity of licensed disposal pathways and extended liability horizons.
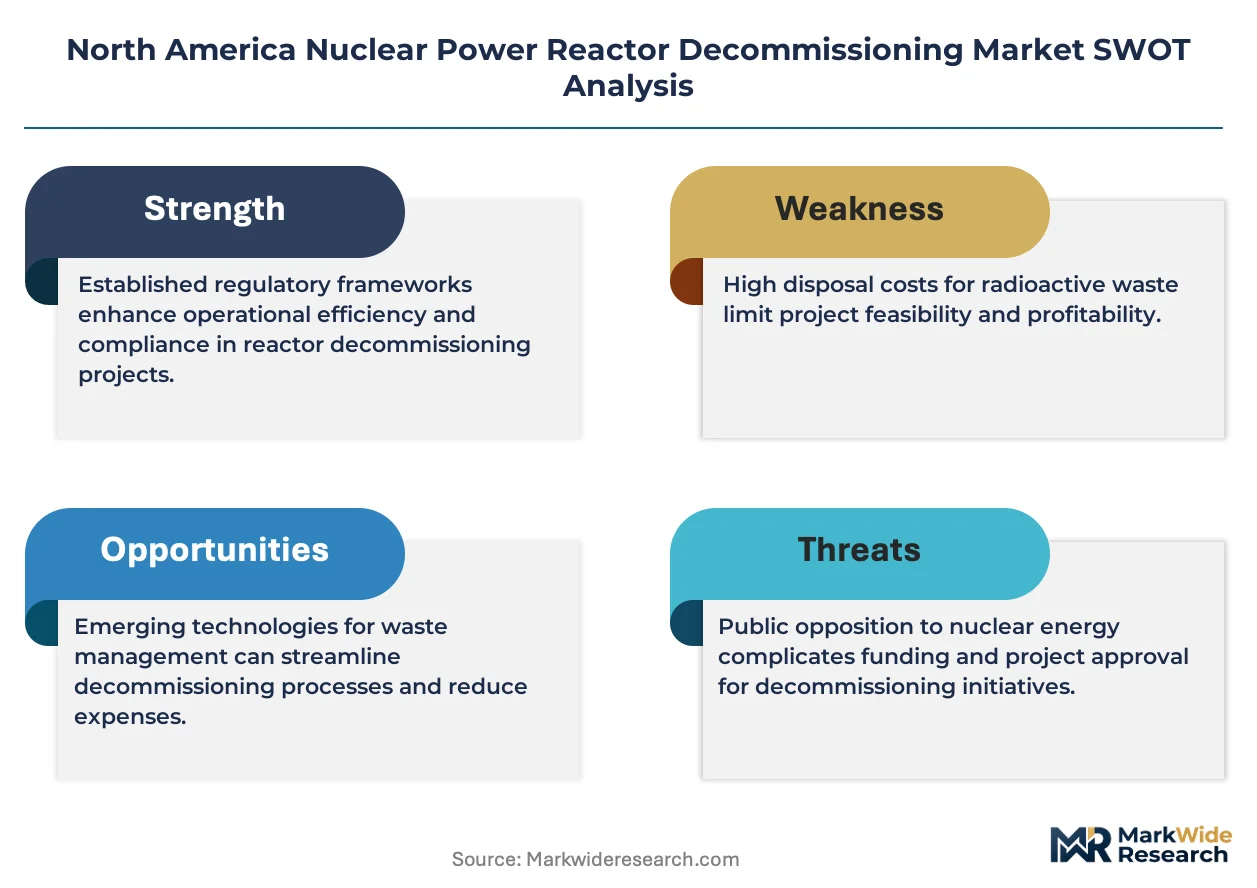
The U.S. Nuclear Regulatory Commission maintains prescriptive decommissioning fund adequacy standards that directly shape project financing structures and contractor qualification thresholds. Canada's Canadian Nuclear Safety Commission enforces parallel financial guarantee requirements under the Nuclear Safety and Control Act, creating harmonized compliance obligations across the bilateral market. State-level public utility commissions in Illinois, Pennsylvania, and California add supplementary oversight layers that extend approval timelines but strengthen contractor credential barriers. Stakeholders must monitor emerging robotics qualification protocols and waste stream characterization standards that will determine competitive access to the next wave of reactor closure portfolios.
Market Dynamics
The North America nuclear decommissioning market pivots on the accelerating closure of pressurized water reactors and boiling water reactors commissioned during the 1970s construction wave, forcing utilities to activate dormant decommissioning trust funds and engage specialized contractors decades ahead of original license expiration dates.
Growth Catalysts
- License Renewal Denials:The U.S. Nuclear Regulatory Commission's heightened scrutiny of aging reactor vessel embrittlement and steam generator tube degradation is compressing operational extensions and triggering premature decommissioning schedules.
- State Clean Energy Mandates:Illinois, New York, and California have enacted statutes requiring carbon-free generation replacements that exclude nuclear license extensions, redirecting utility capital toward decommissioning execution.
- Robotic Segmentation Systems:Autonomous plasma arc cutting and abrasive waterjet platforms are penetrating reactor pressure vessel dismantlement, reducing labor exposure and accelerating project timelines.
Market Restraints
- Disposal Pathway Scarcity:The Waste Isolation Pilot Plant's limited transuranic capacity and the absence of a consolidated interim storage facility force contractors to maintain on-site dry cask storage for indefinite periods.
- Specialized Labor Concentration:Certified health physicists and ALARA planning engineers concentrate in the U.S. Southeast and Great Lakes regions, creating geographic hiring bottlenecks for coastal decommissioning projects.
- Trust Fund Volatility:Decommissioning trust assets held in equity-heavy portfolios face NRC-mandated adequacy tests that trigger supplemental funding obligations during market downturns.
Strategic Opportunities
- Canadian CANDU Decommissioning:Ontario Power Generation's Darlington and Pickering station closures create first-mover opportunities for contractors with heavy-water reactor segmentation experience.
- Integrated Project Delivery:Engineering-procurement-construction firms are bundling site characterization, dismantlement, and license termination into single-accountability contracts that capture full lifecycle value.
- Spent Fuel Consolidation:Private interim storage licensing under the U.S. Nuclear Regulatory Commission's 10 CFR Part 72 is enabling merchant storage solutions that decouple decommissioning from federal repository timelines.
Industry Challenges
- Radiological Characterization Gaps:Legacy dose records and activation calculations for 1960s-era reactors contain uncertainties that delay waste stream classification and disposal contracting.
- Robotics Qualification Protocols:The U.S. Nuclear Regulatory Commission has not established standardized performance criteria for autonomous systems in high-radiation environments, forcing case-by-case safety reviews.
- Stakeholder Alignment Complexity:State public utility commissions, local emergency planning zones, and tribal nations require parallel consultation processes that extend approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nuclear Power Reactor Decommissioning Market |
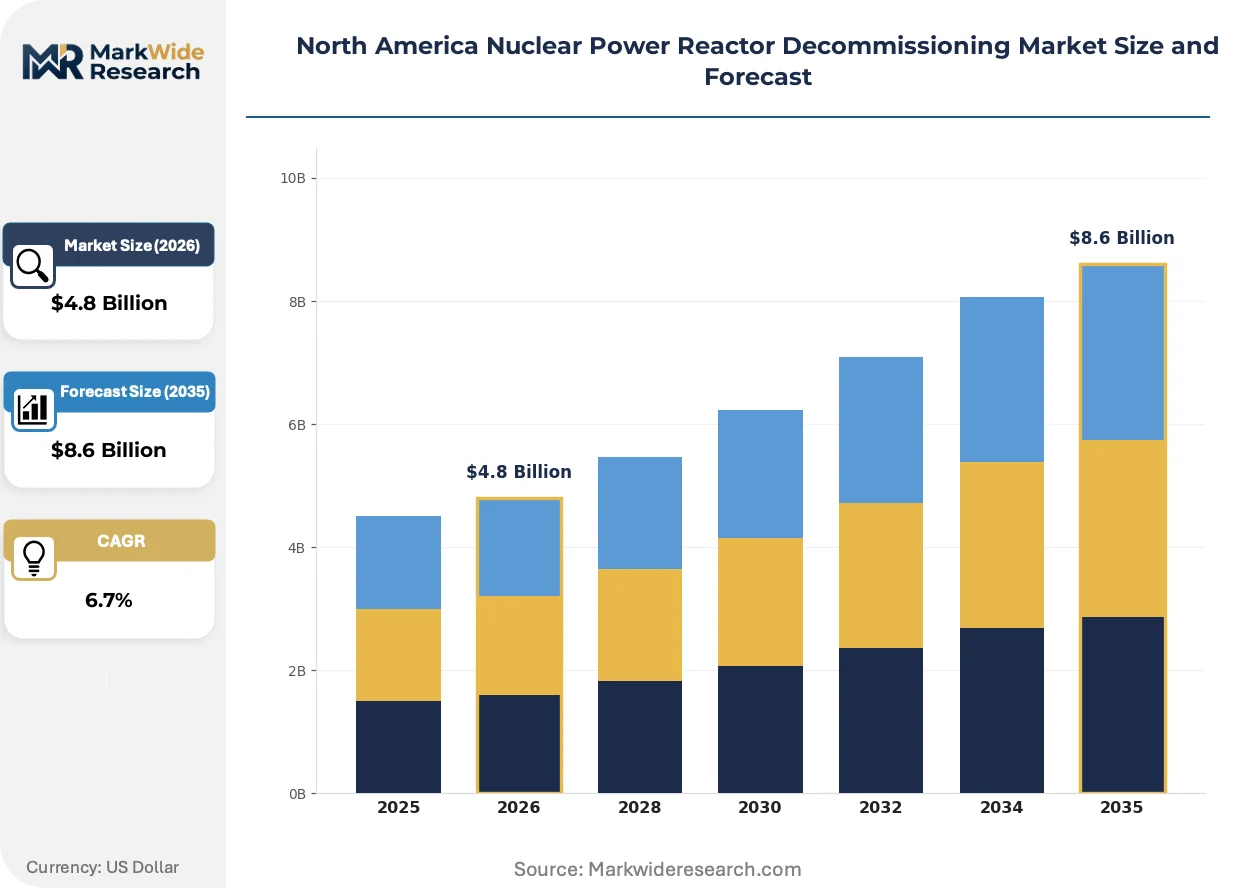
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Decontamination, Dismantling, Waste Management, Site Restoration Technology: Robotic Systems, Cutting Technologies, Monitoring Systems, Waste Treatment End User: Utility Companies, Government Agencies, Environmental Consultants, Contractors Phase: Pre-Decommissioning, Active Decommissioning, Post-Decommissioning, Regulatory Compliance |
| Companies Covered | Babcock International Group, Fluor Corporation, Bechtel Group, NorthStar Group Services, AECOM, Westinghouse Electric Company, Orano Group, James Fisher & Sons, EnergySolutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nuclear Power Reactor Decommissioning Market Evolving Landscape
Decommissioning execution is digitizing through building information modeling and radiation mapping integration, collapsing the traditional sequential phases of characterization, planning, and dismantlement into overlapping workflows that compress project duration.
Autonomous robotic platforms equipped with LiDAR and gamma spectroscopy are expanding into reactor cavity segmentation and biological shield demolition. Decommissioning contractors in the U.S. Midwest are deploying these systems for reactor pressure vessel internals removal, replacing manual remote-handled tooling. This capability compression is enabling fixed-price contracting for high-dose work packages previously billed on time-and-materials bases.
The U.S. Nuclear Regulatory Commission's 2024 updates to 10 CFR Part 50.75 financial assurance rules are tightening decommissioning fund adequacy testing intervals from five years to three. Licensees must now submit probabilistic cost analyses incorporating technology-specific productivity assumptions. Small modular reactor developers and legacy reactor operators alike are responding by pre-positioning dedicated decommissioning subsidiaries with ring-fenced balance sheets.
Utility procurement departments are consolidating decommissioning vendor panels from fragmented regional pools to national pre-qualified rosters. This buyer concentration is displacing local demolition contractors who lack radioactive materials handling licenses. The shift is most visible in the U.S. Northeast, where Exelon and Entergy have implemented master service agreements with tiered contractor qualification levels.
North America Nuclear Power Reactor Decommissioning Market Segmentation
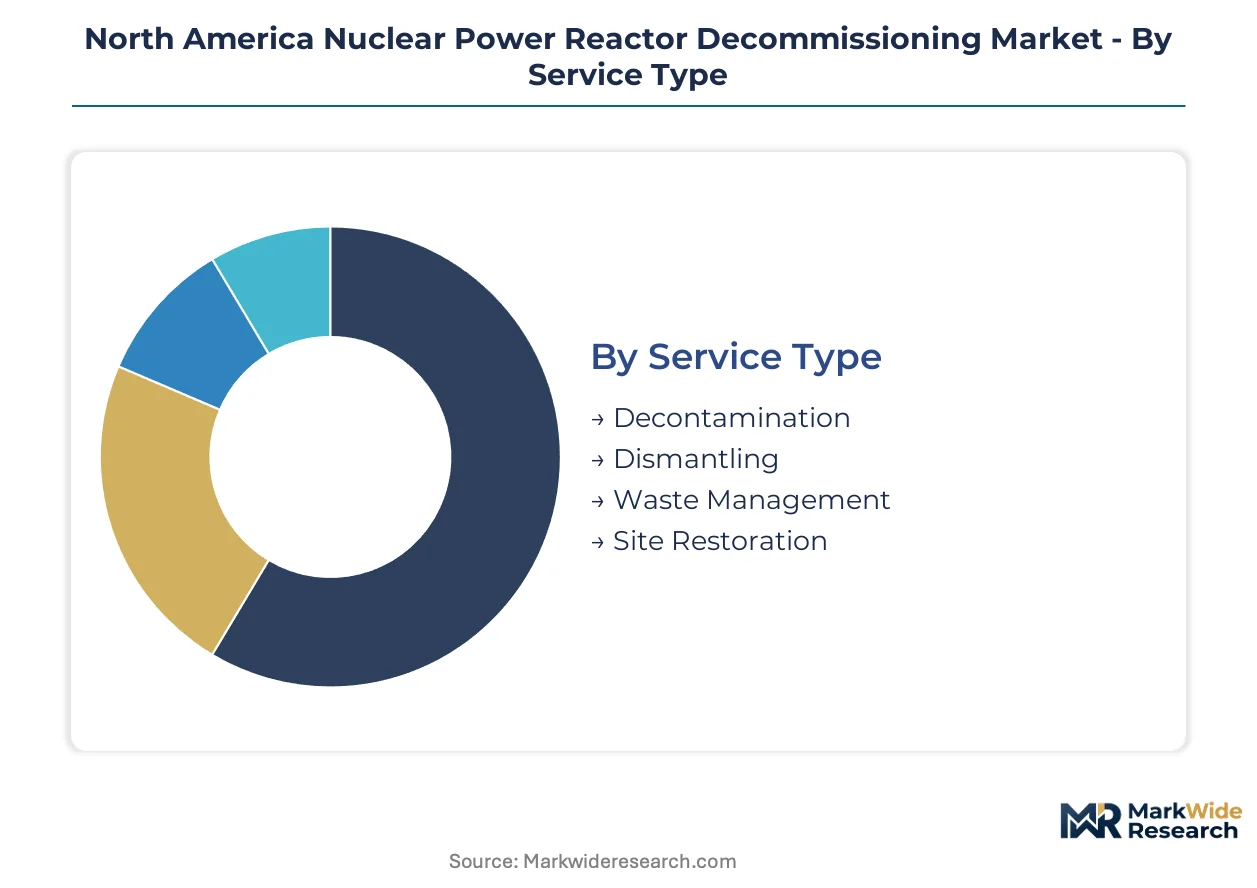
Decommissioning contracts diverge sharply by technical complexity and liability duration, with service providers specializing across discrete capability clusters rather than competing as generalists. Segmentation reveals where capital concentrates and which technology investments unlock premium pricing tiers.
Service Type:
Cost tier separates episodic project work from multi-decade stewardship obligations, with fund adequacy rules favoring integrated service bundling.
- Dismantling:Structural segmentation of reactor pressure vessels and biological shields demands remote-handled tooling in dose rates exceeding 1,000 rem per hour. Labor intensity and specialized equipment requirements concentrate revenue in the U.S. Northeast and Midwest where early-generation plants face accelerated closure timelines.
- Waste Management:Low-level radioactive waste logistics and disposal infrastructure face scarcity of licensed pathways, extending liability horizons and protecting margins through captive volume commitments. Ontario Power Generation's CANDU closures and U.S. utility trust fund activations are concentrating demand for consolidated waste services.
- Decontamination:Surface and subsurface radionuclide removal precedes dismantlement and determines final status survey outcomes.
- Site Restoration:Landform reconstruction and groundwater remediation achieve unrestricted or restricted release status for alternate commercial use.
Volume sits with Dismantling; growth tilts toward Waste Management.
Technology:
Application specificity determines robotics qualification barriers and cutting technology selection for vessel segmentation versus biological shield demolition.
- Robotic Systems:Autonomous platforms equipped with LiDAR and gamma spectroscopy operate in high-radiation zones to minimize human exposure. U.S. Midwest contractors deploy these for reactor pressure vessel internals removal, enabling fixed-price contracting previously billed on time-and-materials bases.
- Cutting Technologies:Plasma arc cutting and abrasive waterjet platforms penetrate thick-walled reactor components with precision control over secondary waste generation. Productivity assumptions for these systems now factor into U.S. Nuclear Regulatory Commission probabilistic cost analyses under updated 10 CFR Part 50.75 rules.
- Monitoring Systems:Real-time dosimetry and contamination tracking support ALARA planning and regulatory documentation.
- Waste Treatment:Volume reduction and stabilization technologies condition materials for licensed disposal or interim storage.
Deployment concentrates in Cutting Technologies; capability investment flows fastest into Robotic Systems.
End User:
Customer type dictates procurement sophistication, with utility trust fund governance imposing contractor qualification tiers that exclude regional demolition specialists.
- Utility Companies:License holders activate dormant decommissioning trust funds decades ahead of original license expiration, consolidating vendor panels from fragmented regional pools to national pre-qualified rosters. Exelon and Entergy master service agreements in the U.S. Northeast exemplify this buyer concentration.
- Government Agencies:Federal and state entities oversee fund adequacy testing and site release certification, with the U.S. Nuclear Regulatory Commission tightening financial assurance intervals from five years to three.
- Environmental Consultants:Third-party characterization and dose reconstruction support waste stream classification and regulatory submittals.
- Contractors:Tiered engineering-procurement-construction firms bundle full-cycle accountability under single-contractor structures.
Contract value aggregates with Utility Companies; procurement influence is expanding fastest among Government Agencies.
Phase:
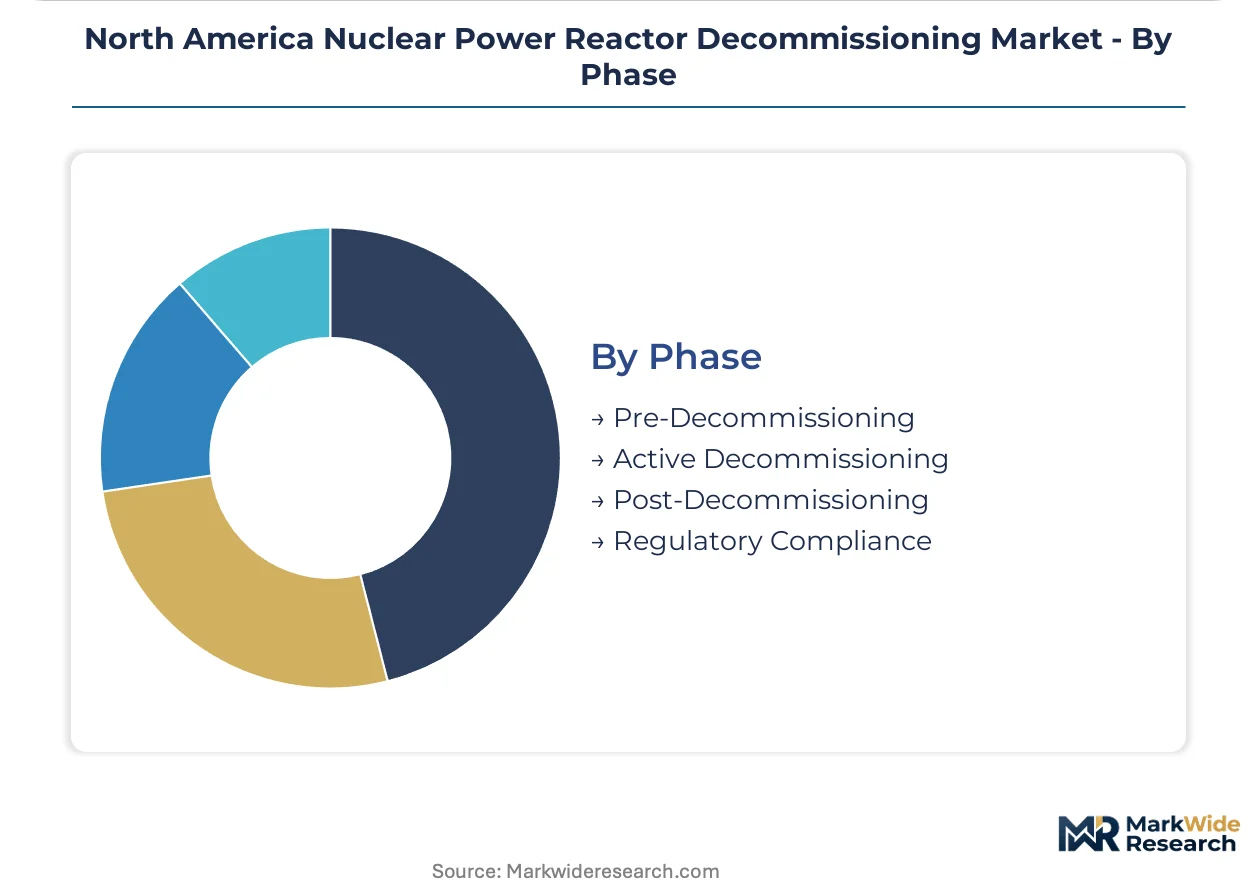
Maturity stage determines revenue recognition patterns, with pre-decommissioning characterization and active dismantlement commanding distinct capability requirements.
- Active Decommissioning:Engineered dismantlement, decontamination, and demolition execute the physical transformation of irradiated facilities. Building information modeling and radiation mapping integration compress traditional sequential phases into overlapping workflows that reduce project duration.
- Pre-Decommissioning:Characterization, planning, and trust fund adequacy testing establish the technical and financial baseline for execution. Updated U.S. Nuclear Regulatory Commission rules now require probabilistic cost analyses with technology-specific productivity assumptions.
- Post-Decommissioning:Long-term stewardship and site monitoring extend liability management for institutional control periods.
- Regulatory Compliance:License termination and release surveys achieve final status for property transfer.
Revenue weight rests in Active Decommissioning; planning intensity is climbing fastest in Pre-Decommissioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Decommissioning execution concentrates where aging reactor fleets meet stringent fund adequacy regimes. The United States generates the majority of contract value, while Canada opens adjacent opportunities through CANDU station closures.
United States
Utility trust fund activations are accelerating across the Northeast and Midwest as pressurized water reactors and boiling water reactors from the 1970s construction wave reach end-of-life. The U.S. Nuclear Regulatory Commission's tightened 10 CFR Part 50.75 rules now mandate three-year adequacy testing intervals with probabilistic cost analyses. Exelon and Entergy procurement departments in the Northeast Corridor have implemented master service agreements with tiered contractor qualification levels.
Canada
Ontario Power Generation's Darlington and Pickering station closures are creating first-mover demand for heavy-water reactor segmentation capabilities unavailable in the U.S. market. The Canadian Nuclear Safety Commission enforces parallel financial guarantee requirements under the Nuclear Safety and Control Act. Toronto-based engineering clusters are positioning for integrated project delivery contracts spanning characterization through license termination.
Illinois
State-level clean energy mandates have redirected utility capital away from license extensions toward accelerated decommissioning execution. The Illinois Commerce Commission adds supplementary oversight layers that extend approval timelines but strengthen contractor credential barriers. Chicago-area decommissioning contractors are deploying robotic systems for reactor pressure vessel internals removal under fixed-price structures.
Pennsylvania
Legacy reactor vessel embrittlement concerns have compressed operational extensions for multiple units in the Commonwealth. The Pennsylvania Public Utility Commission oversees trust fund governance with requirements that exceed federal baselines. Pittsburgh and Philadelphia industrial corridors concentrate certified health physicists and ALARA planning engineers for high-dose dismantlement operations.
California
Statutory carbon-free generation replacement requirements exclude nuclear license extensions, forcing premature decommissioning schedules for coastal units. The California Public Utilities Commission imposes stakeholder consultation mandates involving tribal nations and local emergency planning zones. San Diego and Los Angeles engineering markets face hiring bottlenecks as specialized labor concentrates in the Great Lakes and Southeast regions.
North America Nuclear Power Reactor Decommissioning Market Competitive Landscape
Capital-heavy engineering-procurement-construction firms compete with specialized asset-light waste logistics providers for decommissioning program control. The market structure consolidates around integrated service bundling as utility procurement departments narrow vendor panels to national pre-qualified rosters. Three archetypes dominate: full-cycle EPC contractors capturing single-accountability structures, radioactive waste specialists leveraging captive disposal infrastructure, and robotics-integrated dismantlement firms enabling fixed-price high-dose work. Competitive positioning hinges on M&A-driven capability stacking and pre-positioning of dedicated decommissioning subsidiaries with ring-fenced balance sheets.
Among integrated EPC contractors, Fluor Corporation and Bechtel Group exemplify the capital-heavy archetype bundling site characterization through license termination. EnergySolutions occupies a distinct position within the waste logistics tier through specialized low-level radioactive waste infrastructure. Westinghouse Electric Company anchors the technology-integrated segment via proprietary segmentation capabilities for spent fuel management. These three patterns represent the dominant competitive configurations as trust fund governance tightens and buyer concentration accelerates.
| Leading Market Players |
|---|
| Babcock International Group |
| Fluor Corporation |
| Bechtel Group |
| NorthStar Group Services |
| AECOM |
| Westinghouse Electric Company |
| Orano Group |
| James Fisher & Sons |
| EnergySolutions |
| Others |
Value Network & Pricing Analysis
Utility procurement departments consolidating vendor panels from fragmented regional pools to national pre-qualified rosters command fixed-price contracting for high-dose dismantlement work, displacing time-and-materials billing and compressing margins for contractors lacking radioactive materials handling licenses.
Pricing Analysis
Cost-down pressure on dismantling services accelerates because robotic segmentation platforms enable predictable productivity assumptions that utility trust fund governance now mandates under tightened U.S. Nuclear Regulatory Commission adequacy rules. Project-based fixed-price structures dominate high-dose work packages, with price differentiation resting on ALARA planning certification tier and captive waste disposal infrastructure ownership. Buyers with ring-fenced decommissioning subsidiaries exhibit lowest price sensitivity; regional demolition contractors lacking NRC licenses face extreme price compression.
Supply Chain Analysis
Direct-to-utility channels handle decommissioning program demand, bypassing intermediaries given the specialized liability and regulatory compliance requirements. Equipment manufacturing concentrates in the United States, Germany, and Japan for remote-handled tooling and robotic platforms. The supply chain draws from specialized steel alloys, radiation-hardened electronics, and certified health physicist labor pools. Single-source vulnerability sits with licensed low-level radioactive waste disposal pathways, particularly the scarcity of alternatives to the Waste Isolation Pilot Plant.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decommissioning service providers are racing to integrate captive waste logistics and robotic dismantlement capabilities under single-accountability structures, with downstream control over disposal infrastructure emerging as the decisive margin-protection lever.
For Market Incumbents: Anchor market position through pre-positioning dedicated decommissioning subsidiaries with ring-fenced balance sheets that satisfy tightened U.S. Nuclear Regulatory Commission fund adequacy testing. Pursue backward integration into low-level radioactive waste disposal infrastructure to defend margins against specialized waste logistics entrants. M&A-driven capability stacking in heavy-water reactor segmentation protects against Ontario Power Generation's CANDU closure demand migrating to first-mover contractors. For New Entrants and Emerging Players: Canadian CANDU decommissioning programs represent the most penetrable buyer archetype, with heavy-water reactor segmentation capabilities scarce in the incumbent base. Target Ontario Power Generation's Darlington and Pickering station closures through Toronto-based engineering partnerships that shortcut qualification timelines. Lead with integrated project delivery proposals bundling characterization through license termination to bypass tiered vendor panel barriers. For Investors and Strategic Acquirers: The window for entry favors asset-light robotics-integrated dismantlement firms with proprietary plasma arc cutting and abrasive waterjet platforms. Long-term viability hinges on technology-specific productivity assumptions now required in probabilistic cost analyses. Monitor U.S. Nuclear Regulatory Commission robotics qualification protocol developments as the inflection signal determining competitive access to reactor closure portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Qualification Investment | Proprietary autonomous platforms unlock fixed-price contracting for reactor pressure vessel segmentation previously billed on time-and-materials bases. |
| Waste Infrastructure Acquisition | Captive low-level radioactive waste disposal pathways protect margins through volume commitments amid licensed pathway scarcity. |
| CANDU Capability Development | Heavy-water reactor segmentation expertise positions firms for Ontario Power Generation's first-mover decommissioning contracts. |
| Decommissioning Subsidiary Structuring | Ring-fenced balance sheets satisfy tightened U.S. Nuclear Regulatory Commission fund adequacy testing intervals. |
| Integrated Project Delivery Bundling | Single-accountability contracts spanning site characterization through license termination capture full lifecycle value. |
Research Methodology
Independent corroboration across decommissioning trust fund administrators, U.S. Nuclear Regulatory Commission licensing staff, and utility procurement officers underwrites the qualitative findings. Primary interviews with engineering-procurement-construction program managers, certified health physicists, and ALARA planning specialists combined with secondary validation from NRC 10 CFR Part 50.75 filings, EPA waste manifest databases, and Ontario Power Generation procurement disclosures. Bottom-up project pipeline aggregation and top-down trust fund activation modeling triangulate market sizing.
Rate-of-change decomposition across service type, technology, end user, and phase dimensions structures the analytical framework over the projection horizon. CAGRs derive from technology-specific productivity assumptions now mandated in probabilistic cost analyses, segmented by dismantling versus waste management versus site restoration revenue recognition patterns. Modeled inputs include reactor closure announcement timelines, robotic platform deployment rates, and licensed disposal pathway capacity constraints.
Revisions become necessary when U.S. Nuclear Regulatory Commission robotics qualification protocols crystallize, consolidated interim storage facility licensing advances, or state clean energy mandates accelerate beyond baseline reactor vessel embrittlement schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Nuclear Power Pump Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Steam Generator Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market