
 Nuclear Power Pump Market | 2026-2036
Nuclear Power Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Power Pump Market Insights
Aftermarket service revenue is narrowing toward original equipment manufacturers with certified nuclear repair capabilities. Flowserve leverages its global service network to capture recurring maintenance contracts on installed reactor pump bases. KSB anchors its position through backward integration into precision casting and specialized metallurgy for primary loop applications. Sulzer competes by sustaining R&D intensity in hydraulics tailored to high-radiation environments.
Nuclear power pumps are precision-engineered fluid-handling machines designed to circulate coolant, transfer chemicals, and manage radioactive waste in reactor systems, typically constructed from austenitic stainless steels or nickel alloys to withstand neutron embrittlement and thermal cycling exceeding 300°C. Their primary purpose is maintaining continuous coolant flow to prevent fuel assembly overheating and ensure containment integrity. Centrifugal pumps dominate installed capacity across primary and secondary cooling loops due to their reliability in continuous-duty service. Multistage pumps represent the fastest-growing product category as utilities demand higher discharge pressures for next-generation reactor designs with compact steam generators. Control systems technology is capturing expanding margin pools as digital instrumentation and remote monitoring become mandatory for operational safety.
The US Nuclear Regulatory Commission enforces 10 CFR Part 50 quality standards that govern pump design certification and material traceability for domestic reactor operators. The ASME Boiler and Pressure Vessel Code Section III mandates third-party inspection protocols that shape supplier qualification timelines and capital deployment schedules. The International Atomic Energy Agency's safety standards influence procurement specifications across emerging nuclear programs in the Middle East and Southeast Asia. Stakeholders must monitor regulatory divergence between established nuclear jurisdictions and newcomer countries as dual certification requirements reshape supplier economics and market access thresholds.
Market Dynamics
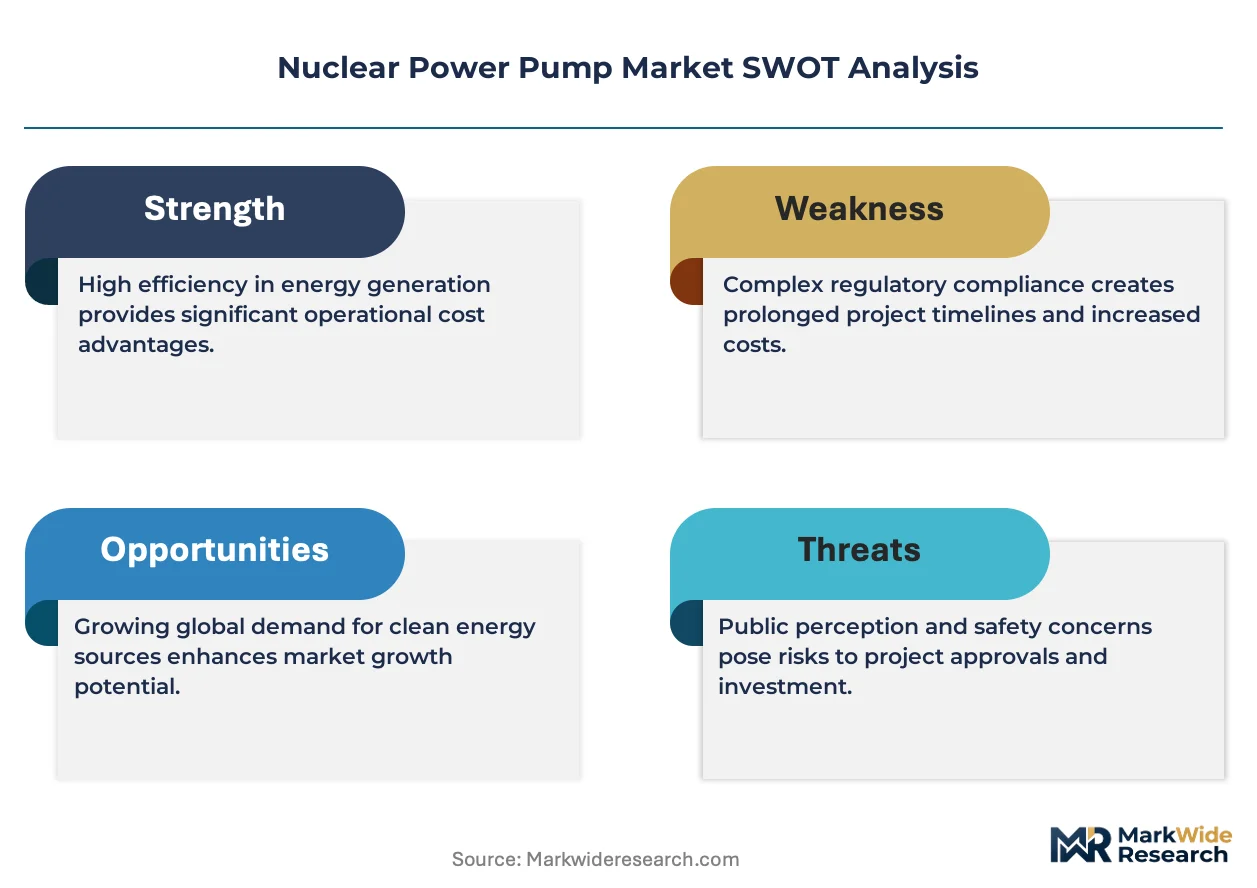
ASME Boiler and Pressure Vessel Code Section III updates are compressing supplier qualification timelines while tightening material traceability requirements for primary loop components. This regulatory tightening is redistributing contract awards toward manufacturers with captive metallurgy capabilities and pre-certified casting facilities.
Growth Catalysts
- China reactor construction:State-owned utilities are procuring primary cooling pumps for 24 new units under construction, creating concentrated demand for forged stainless steel casings and cobalt-free alloys.
- IAEA safety standards:Emerging nuclear programs in the Middle East and Southeast Asia are adopting these procurement specifications, opening qualification pathways for certified suppliers.
- Digital instrumentation mandates:Remote monitoring systems for pump vibration and seal integrity are becoming mandatory for operational safety, expanding addressable market for control system integrators.
Market Restraints
- Nickel alloy supply concentration:Specialty forgings for reactor-grade pumps depend on a limited base of certified foundries in France, Japan, and the United States, creating input bottlenecks.
- 10 CFR Part 50 compliance friction:The US Nuclear Regulatory Commission's quality standards extend certification timelines, freezing out smaller suppliers lacking dedicated regulatory affairs teams.
- Small modular reactor substitution:Next-generation SMR designs with passive cooling systems threaten to displace conventional pumped circulation in specific baseload applications.
Strategic Opportunities
- India capacity expansion:Nuclear Power Corporation of India is tendering for 10 new pressurized heavy water reactors, creating entry points for pump suppliers establishing local joint ventures.
- EU Green Deal taxonomy:Nuclear power's inclusion as sustainable finance-eligible is unlocking green bond financing for utility pump replacement cycles.
- Additive manufacturing convergence:Powder bed fusion for complex impeller geometries is converging with conventional precision casting, enabling rapid prototyping for custom reactor designs.
Industry Challenges
- Welding inspector scarcity:ASME Section IX certified welders and radiographic testing technicians are in short supply, delaying fabrication schedules for primary loop pump casings.
- Dual certification complexity:Suppliers seeking access to both established and newcomer nuclear markets must maintain parallel quality systems, inflating overhead without guaranteed contract flow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Power Pump Market |
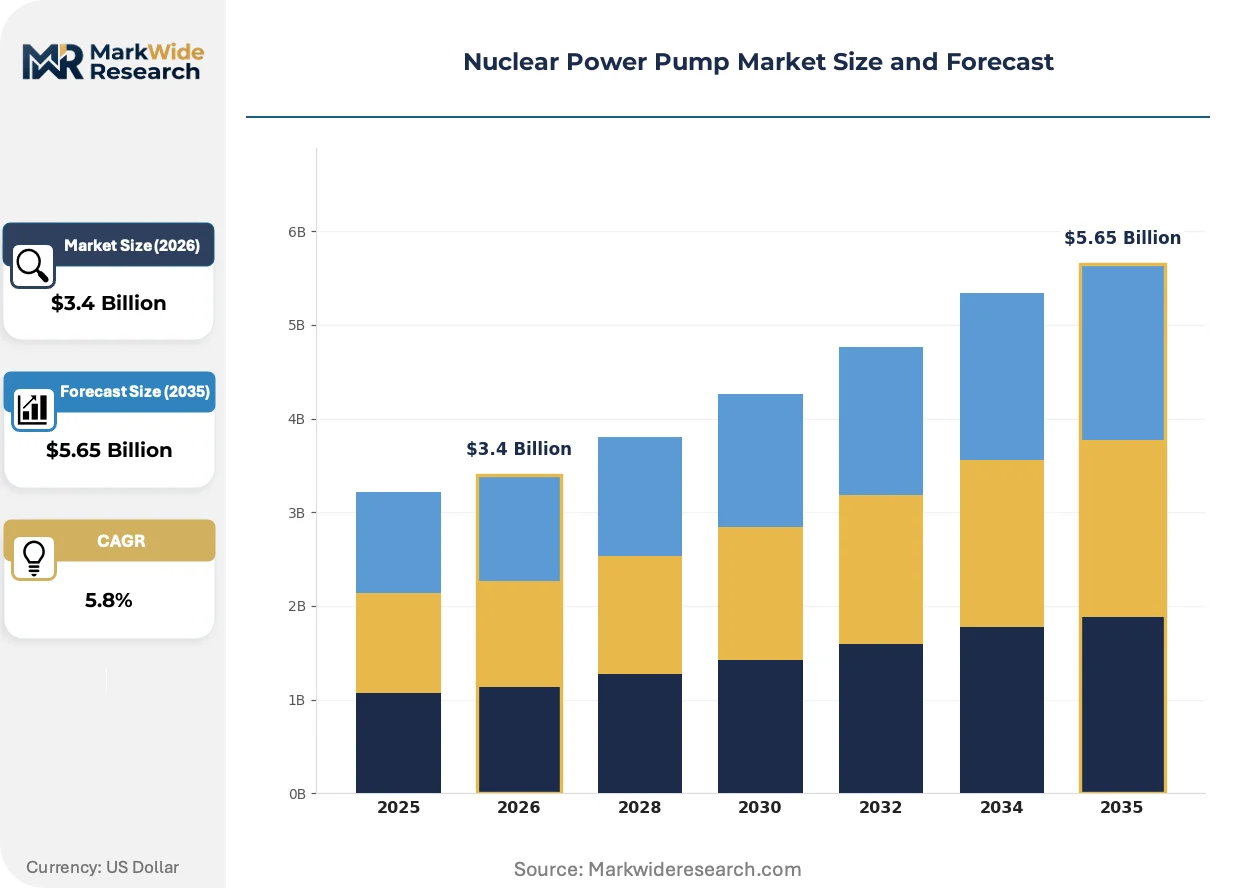
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Reciprocating Pumps, Multistage Pumps, Gear Pumps Application: Primary Cooling, Secondary Cooling, Chemical Transfer, Waste Management End User: Nuclear Power Plants, Research Facilities, Government Agencies, Utility Providers Technology: Hydraulic, Mechanical, Electrical, Control Systems |
| Companies Covered | Flowserve, KSB, Sulzer, General Electric, Curtiss-Wright, Grundfos, Weir Group, Mitsubishi Heavy Industries, Ebara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Power Pump Market Trends and Innovations
Digital instrumentation and predictive maintenance architectures are displacing scheduled overhaul cycles. Three converging developments are restructuring how reactor operators specify, procure, and sustain pump assets over multi-decade service lives.
Sealless canned motor pump technology is migrating from chemical processing into primary cooling applications. European utilities operating aging pressurized water reactors are retrofitting these units to eliminate mechanical seal leakage paths. The technology is migrating from secondary systems to primary loops, compressing maintenance intervals and reducing personnel radiation exposure during seal replacement.
REACH regulation amendments are restricting cobalt content in hardfacing alloys used for pump bearings and wear rings. Manufacturers are reformulating Stellite alternatives using nickel-iron matrices to maintain galling resistance. European suppliers are absorbing reformulation costs fastest, while Asian foundries face extended requalification timelines with notified bodies.
Lifecycle service contracting is displacing transactional spare parts procurement. Reactor operators in China and India are bundling 20-year maintenance agreements with initial pump purchases, transferring inventory risk to OEMs. This pattern is most visible in state-owned utilities with centralized procurement authority and long-term fuel supply contracts.
Nuclear Power Pump Market Segmentation
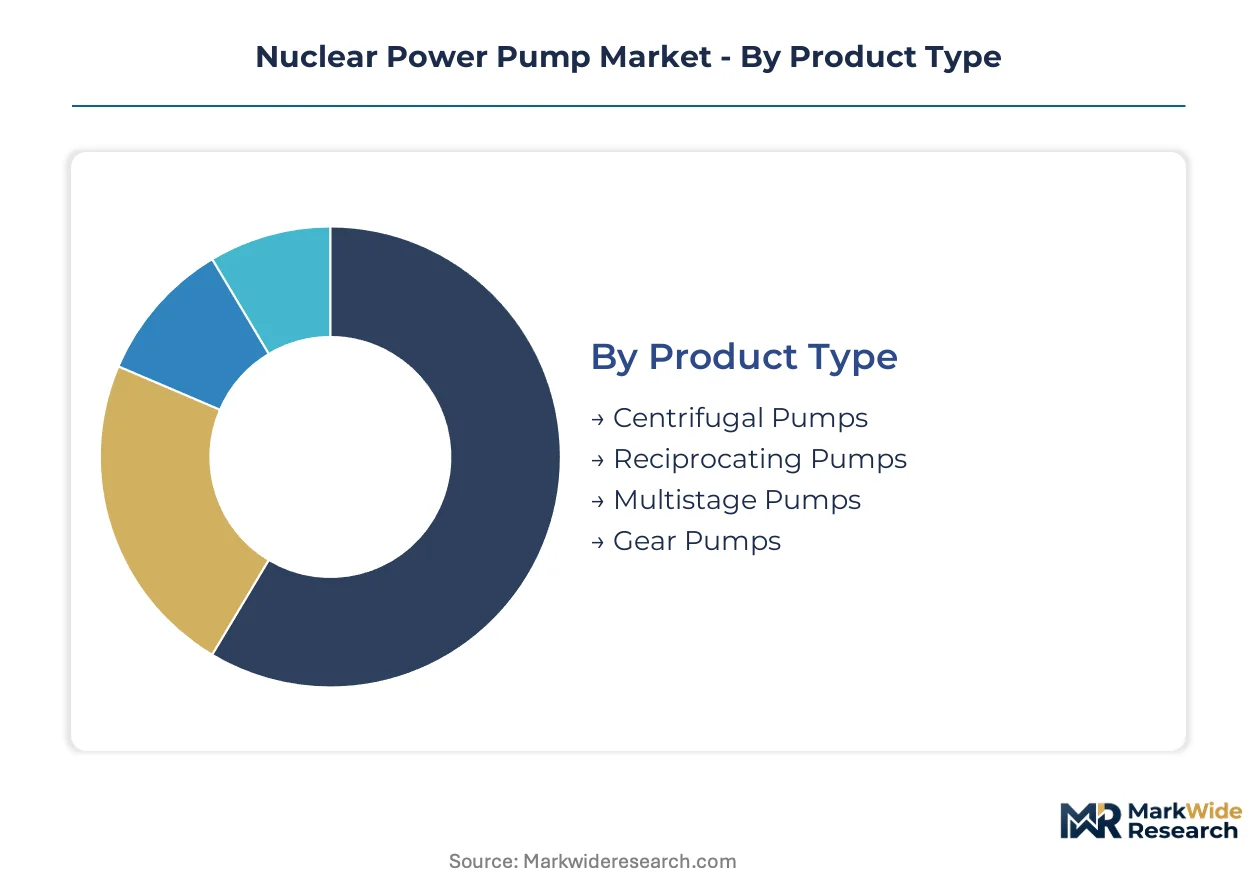
Nuclear power pump procurement cycles vary dramatically by segment, with primary cooling systems operating on 40-year replacement horizons while control system retrofits refresh every 7-10 years. Understanding these temporal patterns enables suppliers to balance long-cycle engineering contracts against recurring service revenue streams.
Product Type:
Replacement velocity separates these categories, with multistage pumps turning over fastest as utilities pursue higher discharge pressures for compact steam generator designs.
- Centrifugal Pumps:Single-suction or double-suction impeller designs handle high-volume coolant circulation across primary and secondary loops. Demand concentrates in China's 24-unit reactor construction program, where state-owned utilities specify forged stainless steel casings for 60-year design life. ASME Section III qualification requirements extend supplier lead times to 18-24 months for these critical components.
- Multistage Pumps:Axially split or barrel-type configurations generate discharge pressures exceeding 15 MPa for next-generation reactor designs with compact steam generators. Procurement is accelerating in India, where Nuclear Power Corporation tenders specify these units for 10 new pressurized heavy water reactors demanding higher head characteristics than single-stage alternatives.
- Reciprocating Pumps:Positive displacement mechanisms deliver precise chemical injection for water chemistry control systems. Research facilities and small modular reactor developers specify these for auxiliary feedwater and boric acid transfer duties.
- Gear Pumps:External or internal gear configurations handle viscous resin wastes and lubricating oil transfer in secondary systems. Limited deployment in primary loops restricts addressable market to maintenance, repair, and operations procurement channels.
Centrifugal pumps dominate installed base. Multistage pumps are where expansion concentrates.
Application:
Margin structure varies by radiation exposure classification, with primary loop applications commanding 3-4x the engineering margin of secondary systems due to cobalt-free alloy requirements and ASME N-stamp certification overhead.
- Primary Cooling:Reactor coolant pumps circulate borated water through reactor vessels and steam generators at temperatures exceeding 300°C. Specifications demand nickel-based superalloys resistant to neutron embrittlement, with India's Department of Atomic Energy mandating indigenous content minimums for these strategic components.
- Secondary Cooling:Condensate and feedwater pumps operate at lower radiation levels, permitting austenitic stainless steels without specialized hardfacing. European utilities retrofitting aging pressurized water reactors are driving demand for sealless canned motor configurations to eliminate mechanical seal leakage paths.
- Chemical Transfer:Boric acid, hydrogen, and lithium hydroxide injection pumps maintain reactor water chemistry within narrow specification bands. These systems experience highest replacement frequency due to corrosive service conditions.
- Waste Management:Resin slurry, evaporator concentrate, and solid waste handling pumps manage radioactive effluent streams. Regulatory classification as safety-related equipment imposes qualification burdens disproportionate to unit value.
Primary cooling commands premium positioning. Secondary cooling offers volume accessibility.
End User:
Procurement sophistication creates distinct customer tiers, with nuclear power plants demanding turnkey lifecycle contracts while research facilities purchase on transactional spot markets.
- Nuclear Power Plants:Commercial reactor operators bundle 20-year maintenance agreements with initial pump purchases, transferring inventory risk to OEMs. State-owned utilities in China and India with centralized procurement authority are pioneering this contracting pattern.
- Utility Providers:Diversified generation companies with nuclear assets specify pumps through consolidated engineering-procurement-construction contracts, privileging suppliers with multi-technology portfolios spanning thermal and renewable generation.
- Research Facilities:National laboratories and university reactors purchase lower volumes with higher specification variance, tolerating longer lead times for custom engineered solutions.
- Government Agencies:Naval propulsion and weapons complex procurement operates through classified channels with security clearance requirements that filter supplier participation.
Nuclear power plants anchor contract value. Utility providers drive standardization.
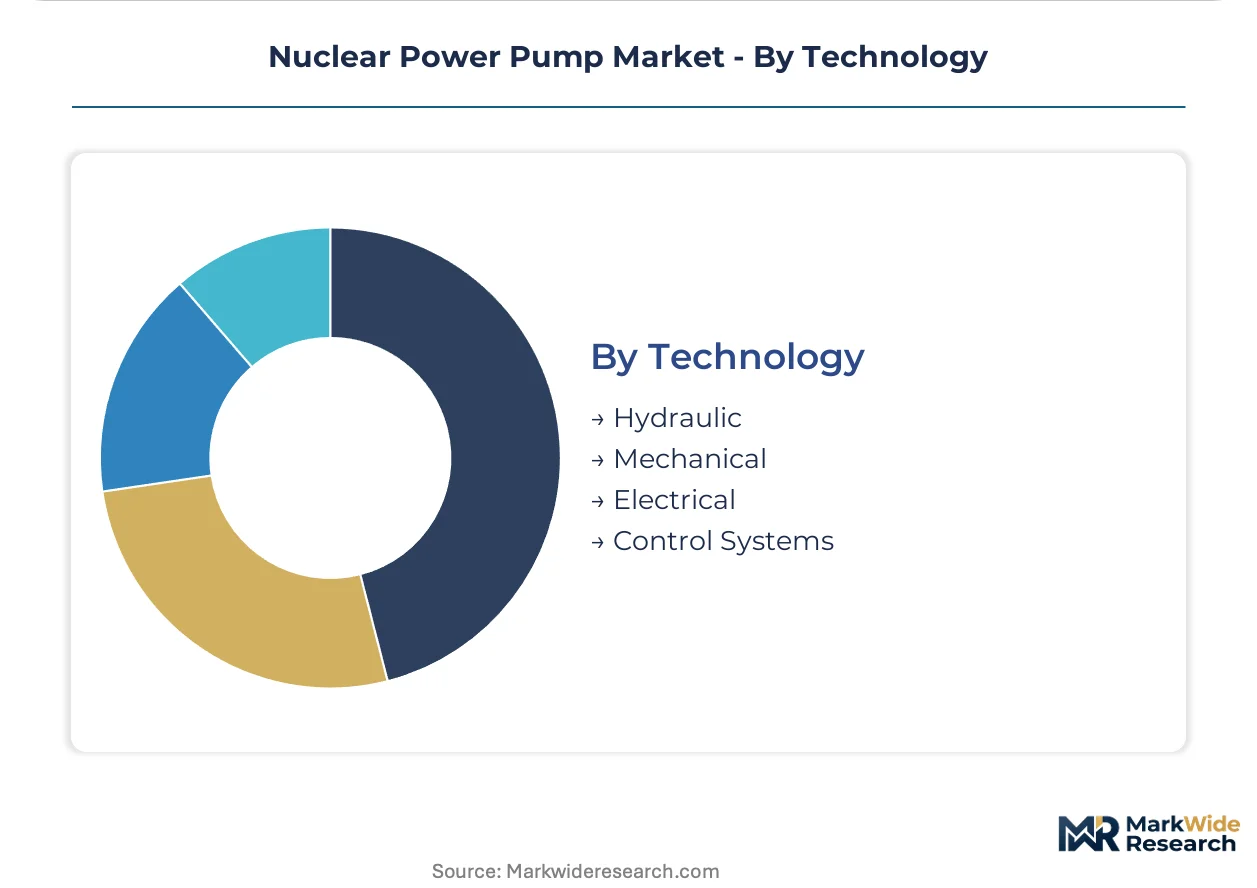
Technology:
Value capture is migrating from hydraulic hardware toward digital layers, with control systems expanding margin pools fastest as remote monitoring becomes mandatory for operational safety.
- Control Systems:Digital instrumentation for pump vibration analysis, seal integrity monitoring, and predictive maintenance architectures displace scheduled overhaul cycles. IAEA safety standards adoption across Middle East and Southeast Asian newcomer programs is mandating these capabilities.
- Hydraulic:Impeller hydrodynamics, volute geometry optimization, and cavitation suppression remain core differentiators for primary loop applications where NPSH margins are constrained by compact containment designs.
- Mechanical:Bearing systems, seal configurations, and structural integrity under thermal cycling define physical service life. REACH regulation amendments restricting cobalt content in hardfacing alloys are forcing Stellite reformulation using nickel-iron matrices.
- Electrical:Canned motor and variable frequency drive integration enables sealless operation and flow modulation. European utilities lead retrofit adoption for personnel radiation exposure reduction.
Hydraulic technology dominates physical installed base. Control systems capture expanding margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and India demonstrate the lowest price elasticity as state-owned utilities prioritize indigenous content mandates and 60-year design life specifications over procurement cost. European utilities exhibit moderate sensitivity, balancing REACH compliance costs against radiation exposure reduction benefits. North American operators face the highest effective cost pressure from extended NRC certification timelines that inflate total cost of ownership regardless of unit pricing.
China
State-owned utilities are procuring primary cooling pumps for 24 new reactor units under construction, creating concentrated demand for forged stainless steel casings. The National Energy Administration enforces indigenous content minimums for strategic nuclear components under domestic technology promotion policies. Shanghai and Sichuan host precision forging clusters where captive foundries supply certified castings to qualified pump manufacturers.
India
Nuclear Power Corporation of India is tendering for 10 new pressurized heavy water reactors requiring higher head characteristics than existing installed base. The Department of Atomic Energy mandates local content thresholds for primary loop equipment through phased manufacturing programs. Kalpakkam and Mumbai anchor the indigenous supply chain where joint venture partnerships transfer metallurgical qualifications to domestic fabricators.
United States
Commercial reactor operators are executing pump replacement cycles on aging pressurized water reactors with 40-year license extensions. The Nuclear Regulatory Commission enforces 10 CFR Part 50 quality standards that extend supplier qualification timelines to 24-36 months. Pittsburgh and Houston host engineering-procurement-construction contractors that consolidate multi-technology procurement across nuclear and thermal generation assets.
France
Electricite de France is retrofitting sealless canned motor pumps into primary cooling loops to eliminate mechanical seal leakage paths on aging reactors. ASN regulatory guidance implements IAEA safety standards for operational safety and radiation protection. Le Creusot and Saint-Etienne maintain specialized foundry capacity for nickel-based superalloys resistant to neutron embrittlement.
Japan
Utilities are restarting idled reactor capacity under post-Fukushima regulatory reforms, triggering inspection-driven pump replacement demand. METI administers safety standards that incorporate IAEA guidelines for equipment qualification and quality assurance. Kobe and Nagoya harbor precision manufacturing clusters where pump OEMs maintain captive metallurgy capabilities for primary loop applications.
Nuclear Power Pump Market Competitive Landscape
Capability concentration sits with full-service OEMs possessing captive foundry capacity and ASME N-stamp certification; scale advantage sits with diversified industrial conglomerates with multi-technology portfolios spanning adjacent energy sectors. The market structure tiers into three archetypes: integrated pump specialists with backward integration into precision casting, diversified flow control platforms with nuclear as one vertical, and regional fabricators serving maintenance-repair-operations channels. Dominant competitive moves include capacity expansion into certified foundry capacity and strategic partnerships with state-owned utilities for localized joint ventures.
Within the integrated specialist tier, Flowserve, KSB, and Sulzer occupy positions defined by metallurgical self-sufficiency and pre-certified manufacturing infrastructure. Flowserve exemplifies the service-network archetype through its global maintenance footprint on installed reactor bases. KSB anchors the backward-integrated model with captive supply of precision castings and specialized alloys. Sulzer represents sustained R&D positioning in application-specific hydraulics. These three firms collectively illustrate how qualification barriers redistribute contract awards toward manufacturers with verified supply chain control.
| Leading Market Players |
|---|
| Flowserve |
| KSB |
| Sulzer |
| General Electric |
| Curtiss-Wright |
| Grundfos |
| Weir Group |
| Mitsubishi Heavy Industries |
| Ebara |
| Others |
Pricing and Supply Chain Analysis
Undercapacity at certified nickel-alloy foundries in France, Japan, and the United States is compressing supplier margins while inflating procurement costs for primary loop pump casings. State-owned utilities in China and India absorb these premiums through indigenous content mandates that prioritize design life over unit economics, whereas European and North American operators face sharper trade-offs between qualification timelines and total cost of ownership.
Pricing Analysis
Long-term offtake contracts dominate primary cooling pump procurement, with Chinese and Indian state-owned utilities bundling 20-year maintenance agreements into initial purchases to lock in lifecycle service capacity. Price differentiation rests on ASME N-stamp certification grade and cobalt-free alloy specification, with certified suppliers commanding substantial premiums over uncertified competitors. Cost compression in secondary cooling systems is intensifying because European utilities are retrofitting sealless canned motor configurations to eliminate mechanical seal leakage paths. Nuclear power plants demonstrate the lowest price sensitivity as centralized procurement authorities prioritize 60-year design life specifications, while research facilities purchasing on transactional spot markets exhibit the highest elasticity.
Supply Chain Analysis
Specialized foundry capacity concentrates at Le Creusot in France, Kobe and Nagoya in Japan, and Pittsburgh in the United States, where captive metallurgy capabilities anchor qualified supplier networks. Raw material dependencies draw from nickel-based superalloys, forged stainless steel casings, and cobalt-free hardfacing alloys reformulated under REACH amendments. Single-source vulnerability at certified forging facilities creates structural risk, as ASME Section IX welding inspector scarcity delays fabrication schedules regardless of material availability. Distribution runs through engineering-procurement-construction contractors that consolidate multi-technology procurement across nuclear and thermal generation assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from small modular reactor designs with passive cooling systems that threaten to displace conventional pumped circulation in specific baseload applications.
For Market Incumbents: Build regulatory certification moats by deepening backward integration into precision casting and specialized metallurgy for primary loop applications. Secure captive foundry capacity to compress ASME qualification timelines while competitors face input bottlenecks. Prioritize joint venture partnerships with Nuclear Power Corporation of India and Chinese state-owned utilities to localize production and satisfy indigenous content mandates. For New Entrants and Emerging Players: Establish a beachhead in secondary cooling system retrofits where sealless canned motor pump migration from chemical processing creates qualification pathways with lower certification barriers. Target European utilities retrofitting aging pressurized water reactors, as ASN regulatory guidance implementing IAEA safety standards mandates equipment upgrades without requiring full primary loop certification. Pursue additive manufacturing convergence for complex impeller geometries to enable rapid prototyping for custom reactor designs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across certified foundry capacity expansion as ASME Boiler and Pressure Vessel Code updates tighten material traceability requirements. Favor acquisition targets with pre-certified casting facilities and established service networks on installed reactor bases. Monitor IAEA safety standards adoption across Middle East and Southeast Asian newcomer programs as the signal for contract flow inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Foundry Capacity Expansion | Captive metallurgy capabilities compress ASME qualification timelines for primary loop components. |
| Lifecycle Service Contracting | 20-year maintenance agreements with Chinese and Indian utilities transfer inventory risk to OEMs. |
| Joint Venture Localization | Partnerships with Nuclear Power Corporation of India satisfy Department of Atomic Energy indigenous content mandates. |
| Digital Instrumentment Integration | Remote monitoring systems for pump vibration analysis address IAEA safety standards mandates. |
| Additive Manufacturing Adoption | Powder bed fusion for complex impeller geometries enables rapid prototyping for custom reactor designs. |
Research Methodology
The analysis maps primary cooling systems, secondary cooling retrofits, chemical transfer applications, and waste management equipment, each validated through utility procurement officers, nuclear engineering consultants, ASME-certified welding inspectors, and foundry operations managers. Primary interviews with plant managers at precision forging clusters, regulatory affairs leads at pump OEMs, and aftermarket service heads at reactor operators combined with secondary validation from ASME Boiler and Pressure Vessel Code filings, NRC 10 CFR Part 50 quality standard documentation, IAEA safety standards publications, and customs trade data for nickel-alloy forgings. Bottom-up unit economics and top-down utility capex trajectories were triangulated to anchor market sizing.
Assumptions held fixed across the modeling period include continued enforcement of ASME Section III qualification protocols, sustained indigenous content minimums in China and India, and stable nickel-alloy supply concentration at certified foundries. Variables allowed to inflect encompass SMR deployment rates, REACH amendment enforcement stringency, and IAEA standards adoption timelines across newcomer nuclear programs. Segmentation dimensions modeled span product type, application radiation classification, end-user procurement sophistication, and technology layer. CAGRs were derived from installed base replacement velocities and new reactor construction pipelines, with inputs from utility long-term maintenance contract disclosures and precision forging capacity utilization signals.
Stress conditions across SMR substitution rates, nickel-alloy price volatility, and welding inspector supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and supply chain configuration stability. Specific risk factors that could revise projections include abrupt SMR regulatory approval acceleration, cobalt-free alloy requalification delays with European notified bodies, or geopolitical disruption to French-Japanese foundry supply corridors. Cross-checking against IEA nuclear capacity expansion forecasts and utility EPC contractor order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Global Power Plant Uranium Market
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Nuclear Power Plant Equipment Market