
 China Nuclear Power Plant Equipment Market | 2026-2036
China Nuclear Power Plant Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
China Nuclear Power Plant Equipment Market Outlook
HAF 604 certification for foreign nuclear safety equipment suppliers is rotating the competitive landscape toward domestic qualification holders. China National Nuclear Corporation leverages its captive reactor design portfolio to anchor procurement pipelines for indigenous Hualong One deployments. Dongfang Electric Corporation Limited sustains manufacturing scale across turbine generator sets, while Harbin Electric Corporation competes on heavy forging capacity for reactor pressure vessels. Shanghai Electric Power Generation Equipment Co., Ltd specializes in auxiliary systems integration for coastal plant complexes.
China nuclear power plant equipment encompasses engineered systems and components designed to contain, control, and convert nuclear fission energy into electrical output, with reactor pressure vessels forged from SA-508 Grade 3 steel to withstand internal pressures exceeding 17 MPa and temperatures above 320°C. Pressurized Water Reactor technology dominates installed capacity and commands the deepest domestic supply chain, while Modular Reactor designs attract accelerated development funding for remote industrial applications. Steam Generator fabrication remains the most margin-concentrated segment due to limited qualified tube sheet suppliers and extensive non-destructive testing protocols.
National Nuclear Safety Administration licensing under the HAF series standards gates market access, with Ministry of Ecology and Environment oversight enforcing construction supervision and environmental release protocols. National Energy Administration planning directives set annual approval quotas that directly shape equipment procurement cycles and vendor order backlogs. Stakeholders must monitor regulatory shifts around small modular reactor certification pathways and localization mandates that will redefine supplier qualification requirements.
Market Dynamics
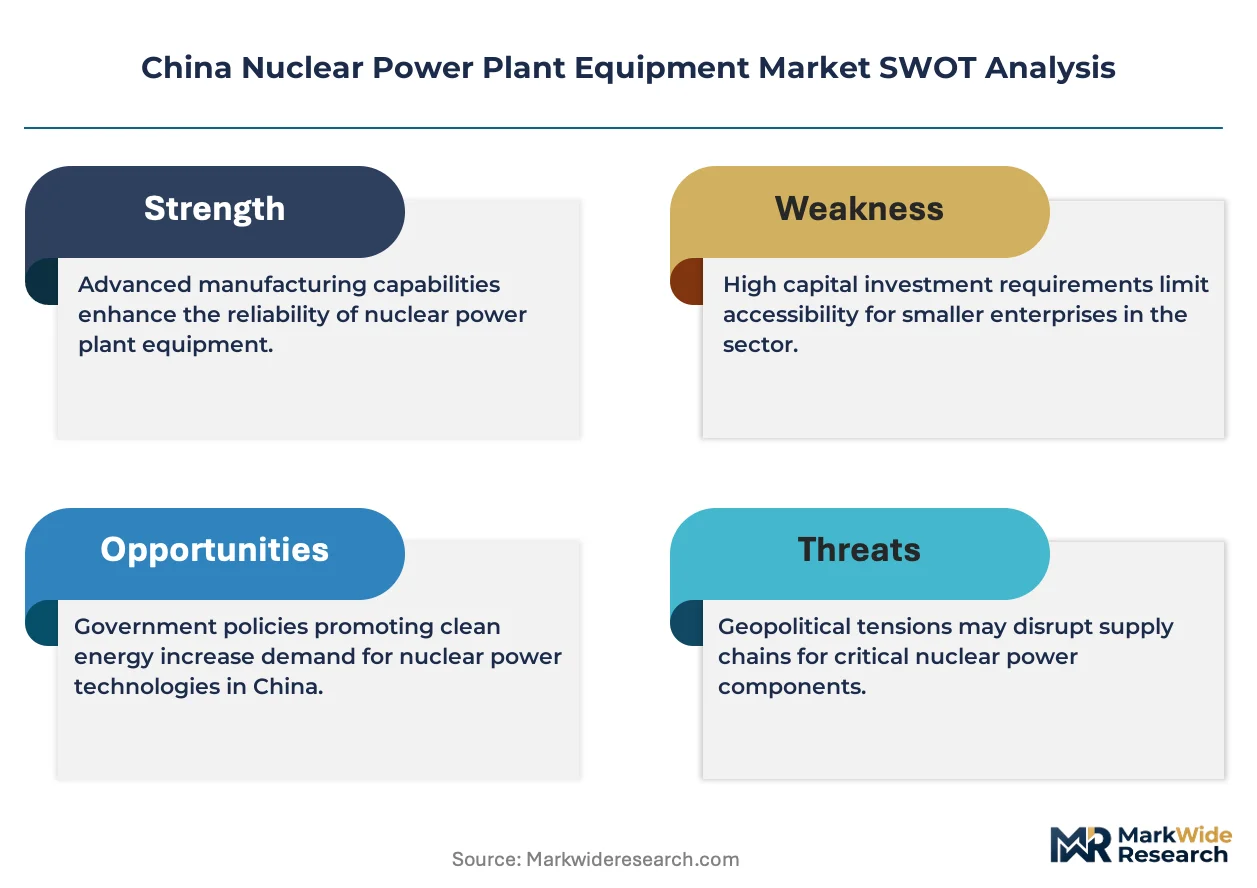
State-owned utility procurement of Generation III reactor systems is accelerating as domestic vendors qualify under China's nuclear safety equipment licensing regime, compressing foreign supplier participation while concentrating order backlogs among HAF 604-certified domestic manufacturers.
Growth Catalysts
- Dual Carbon Policy Mandate:China's national carbon neutrality targets under the 14th Five-Year Plan are channeling state investment into nuclear baseload capacity expansion along the eastern coastal corridor.
- Hualong One Deployment Pipeline:Indigenous reactor design standardization is creating predictable procurement cycles for reactor pressure vessels, steam generators, and turbine generator sets.
- Shandong-Zhejiang-Fujian Construction Cluster:Concentrated new plant construction in these three provinces is generating localized demand spikes for auxiliary systems and containment equipment.
Market Restraints
- SA-508 Grade 3 Steel Supply Concentration:Domestic heavy forging capacity for reactor pressure vessels remains concentrated among state-owned metallurgical groups, creating single-source vulnerability.
- HAF 604 Certification Timeline:Foreign equipment suppliers face extended qualification periods under National Nuclear Safety Administration licensing, delaying market entry by multiple approval cycles.
- Modular Reactor Regulatory Uncertainty:Small modular reactor certification pathways remain undefined under current GB standards, freezing private capital deployment.
Strategic Opportunities
- Remote Industrial Applications:Modular reactor designs for mining and desalination in western provinces offer first-mover positioning outside coastal nuclear corridors.
- Steam Generator Aftermarket Services:Limited qualified tube sheet suppliers create captive service revenue potential for incumbent fabricators with existing NNSA approvals.
- Localization Mandate Acceleration:Ministry of Ecology and Environment directives on domestic content thresholds are reshaping qualification requirements for foreign joint ventures.
Industry Challenges
- Welding Inspector Certification Scarcity:Qualified ASME Section IX and HAF 603 certified welders for reactor pressure vessel fabrication remain critically undersupplied relative to construction timelines.
- Non-Destructive Testing Bottlenecks:Extensive ultrasonic and radiographic testing protocols for steam generator tube sheets are extending fabrication cycles beyond original equipment manufacturer capacity.
- Legacy System Integration Complexity:Generation II plant upgrades require custom engineering to interface indigenous Hualong One components with existing balance-of-plant infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Nuclear Power Plant Equipment Market |
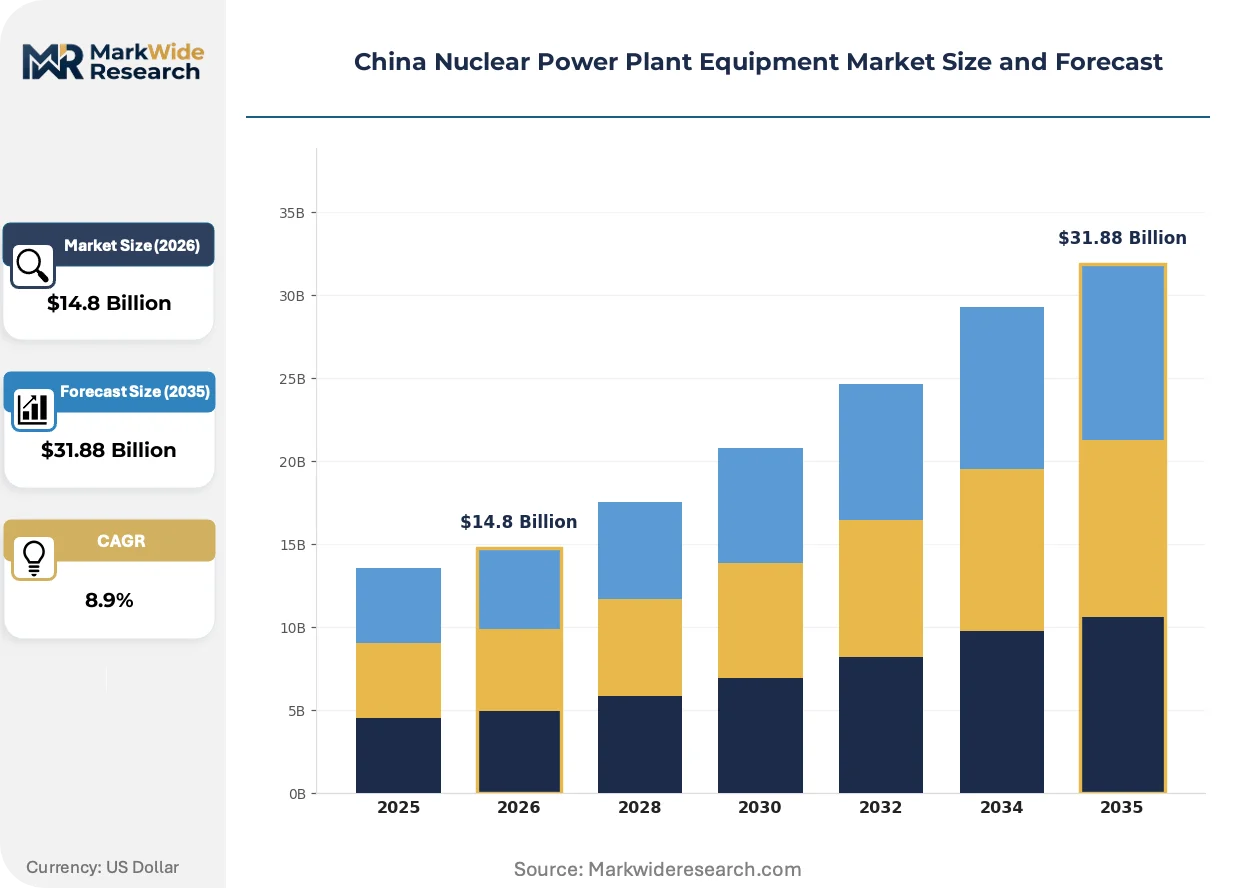
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.88 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactor Pressure Vessel, Steam Generator, Turbine Generator, Containment Structure Technology: Pressurized Water Reactor, Boiling Water Reactor, Fast Breeder Reactor, Modular Reactor End User: Government Utility, Private Utility, Industrial End User, Research Institution Maintenance Type: Preventive Maintenance, Corrective Maintenance, Predictive Maintenance, Emergency Maintenance |
| Companies Covered | China National Nuclear Corporation, China General Nuclear Power Group, Shanghai Electric Power Generation Equipment Co., Ltd, Dongfang Electric Corporation Limited, Mitsubishi Heavy Industries Ltd, Doosan Enerbility, China Nuclear Engineering Corporation, China Nuclear Industry Construction Co., Ltd, Harbin Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Nuclear Power Plant Equipment Market Strategic Shifts
Equipment qualification protocols and procurement patterns are diverging between large-scale Generation III deployments and emerging small modular reactor architectures, creating parallel supply chain development tracks with incompatible technical standards.
Digital twin technology for predictive maintenance of reactor pressure vessels is bifurcating vendor capabilities between traditional equipment fabricators and industrial software specialists. State-owned nuclear operators are mandating digital twin integration in new procurement specifications. This capability split is compressing margins for pure-play mechanical suppliers while elevating system integrators with embedded analytics platforms.
Ministry of Ecology and Environment oversight is tightening construction supervision protocols for environmental release containment, extending commissioning timelines for coastal plant complexes. Equipment suppliers now face parallel approval tracks for mechanical performance and environmental compliance documentation. Steam generator fabricators bear the heaviest documentation burden under these dual-track requirements.
Buyer concentration among China National Nuclear Corporation and State Power Investment Corporation subsidiaries is consolidating procurement decision-making into centralized technical specification committees. Long-term framework agreements are displacing project-by-project tendering for reactor island equipment. This shift is most visible in Zhejiang province where Fangjiashan and Sanmen plant complexes operate under unified procurement umbrellas.
China Nuclear Power Plant Equipment Market Segmentation
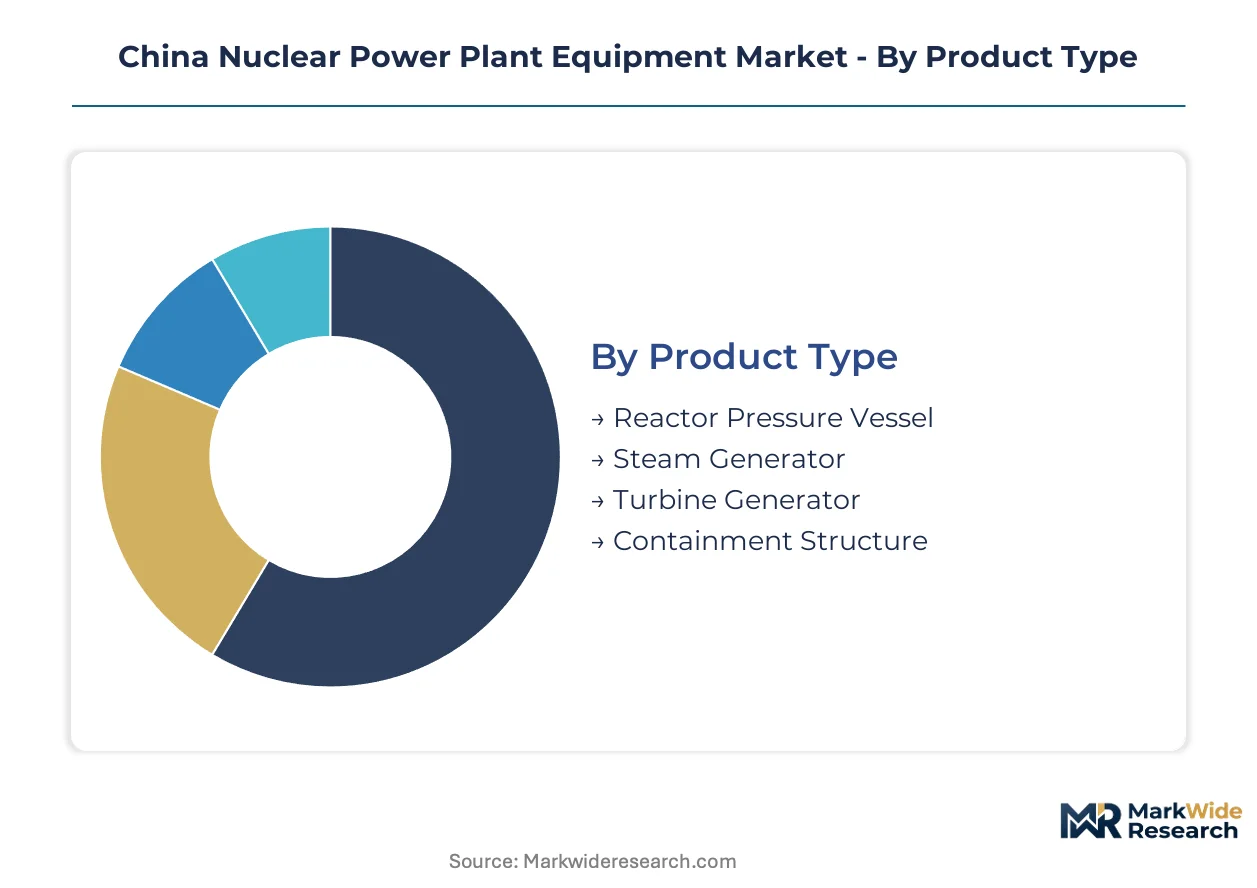
Equipment segmentation in China's nuclear power sector reflects the layered regulatory architecture governing market access. National Nuclear Safety Administration licensing under HAF series standards creates distinct qualification pathways for each product category, while technology choices align with coastal deployment corridors versus western industrial applications.
Product Type:
Regulatory stringency varies dramatically across equipment classes, with reactor island components facing multi-year HAF 604 certification timelines that foreign suppliers rarely complete.
- Reactor Pressure Vessel:Forged from SA-508 Grade 3 steel to withstand internal pressures exceeding 17 MPa and temperatures above 320°C. Demand concentrates among state-owned metallurgical groups in Shandong and Sichuan provinces where heavy forging capacity anchors the Hualong One deployment pipeline.
- Steam Generator:Tube sheet fabrication requires extensive ultrasonic and radiographic testing protocols that extend manufacturing cycles. Procurement clusters along the Zhejiang-Fujian coastal corridor where containment specifications for new plant construction are most stringent.
- Turbine Generator:Dongfang Electric and Harbin Electric dominate manufacturing scale for 1000 MW-class units.
- Containment Structure:Prestressed concrete and steel liner systems integrate with auxiliary cooling networks.
Reactor pressure vessels handle the majority of procurement value concentration; steam generators are climbing the fastest on margin capture due to limited qualified suppliers.
Technology:
Cost tiers separate mature Generation III deployments from emerging architectures attracting development funding for non-coastal applications.
- Pressurized Water Reactor:Installed capacity dominance commands the deepest domestic supply chain with qualified vendors across all major equipment categories. Procurement pipelines align with National Energy Administration approval quotas concentrated in eastern coastal provinces.
- Modular Reactor:Small modular designs for remote mining and desalination applications in western provinces operate outside established certification pathways. Ministry of Ecology and Environment oversight for environmental release protocols remains undefined, freezing private capital deployment.
- Boiling Water Reactor:Limited domestic deployment following technology import restrictions.
- Fast Breeder Reactor:Experimental installations at China Institute of Atomic Energy facilities.
Pressurized water reactor technology anchors current procurement volume; modular reactor designs show steepest expansion trajectory contingent on regulatory pathway clarification.
End User:
Customer type determines procurement centralization versus fragmentation, with state-owned utilities operating under unified technical specification committees.
- Government Utility:China National Nuclear Corporation and State Power Investment Corporation subsidiaries consolidate decision-making through centralized committees. Long-term framework agreements in Zhejiang province displace project-by-project tendering for reactor island equipment.
- Industrial End User:Remote mining operations in Xinjiang and Inner Mongolia explore captive nuclear power for energy-intensive processing. Modular reactor procurement operates outside coastal utility structures with distinct technical specifications.
- Private Utility:Minimal participation due to capital intensity and licensing barriers.
- Research Institution:China Institute of Atomic Energy and Tsinghua University reactors drive specialized component demand.
Government utilities control the dominant procurement channel; industrial end users are gaining share fastest as modular applications advance.
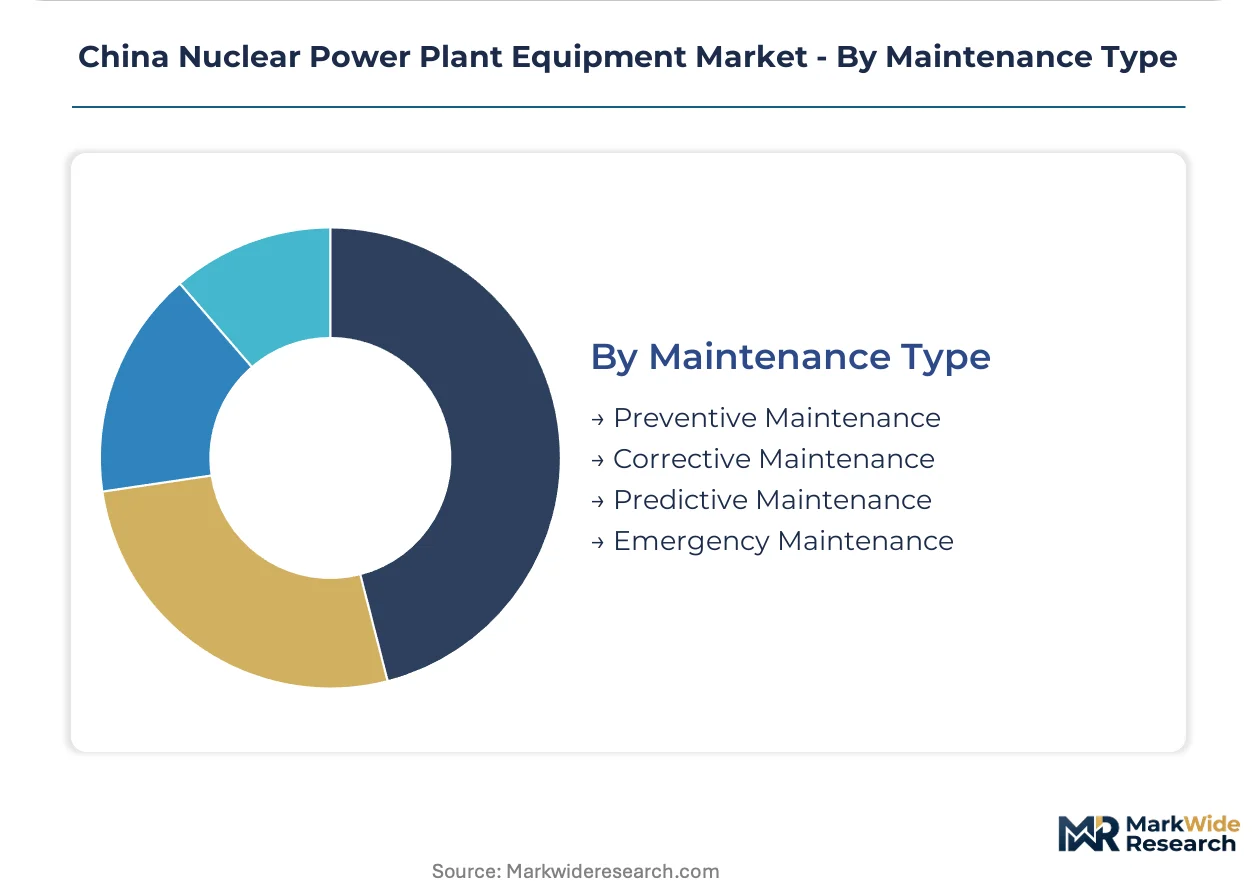
Maintenance Type:
Service revenue concentration follows equipment criticality, with steam generator tube sheet maintenance generating captive aftermarket flows.
- Predictive Maintenance:Digital twin integration for reactor pressure vessels now mandated in new procurement specifications. State-owned operators require embedded analytics platforms, compressing margins for pure-play mechanical suppliers while elevating system integrators.
- Preventive Maintenance:Scheduled outages for turbine generator sets align with National Energy Administration planning directives. Dongfang Electric and Shanghai Electric capture recurring service revenue through long-term operational support contracts.
- Corrective Maintenance:Unplanned repairs for auxiliary systems and balance-of-plant infrastructure.
- Emergency Maintenance:Regulatory-mandated response protocols under National Nuclear Safety Administration oversight.
Predictive maintenance commands expanding procurement specification requirements; preventive maintenance retains the largest installed base service volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-owned utility procurement concentrates equipment demand along three coastal provinces where Generation III reactor construction clusters. National Energy Administration approval quotas direct investment toward Shandong, Zhejiang, and Fujian, creating localized supply chain bottlenecks for reactor pressure vessels and steam generators.
Shandong Province
Shandong anchors the northern coastal construction corridor with multiple Hualong One deployments under active development. Provincial industrial policy channels metallurgical investment toward SA-508 Grade 3 steel forging capacity for reactor pressure vessels. Yantai and Weihai host heavy manufacturing clusters where state-owned fabricators expand forging press capacity to meet National Nuclear Safety Administration licensing requirements.
Zhejiang Province
Zhejiang concentrates the densest cluster of new plant construction along the eastern seaboard with Fangjiashan and Sanmen complexes driving unified procurement. Ministry of Ecology and Environment oversight tightens environmental release containment protocols for coastal installations. Ningbo and Taizhou manufacturing zones specialize in auxiliary systems integration and containment structure fabrication for pressurized water reactor deployments.
Fujian Province
Fujian extends the southern coastal corridor with substantial new capacity additions targeting Taiwan Strait energy security objectives. Provincial development commissions accelerate land-use approvals for nuclear island construction. Fuzhou and Xiamen industrial zones attract turbine generator set manufacturers establishing regional service hubs for preventive maintenance contracts.
Sichuan Province
Sichuan houses critical heavy forging infrastructure for reactor pressure vessel production despite distance from coastal demand centers. Chengdu metallurgical clusters supply SA-508 Grade 3 steel forgings to eastern fabricators under long-term supply agreements. Provincial technology parks host welding inspector training programs addressing ASME Section IX certification scarcity.
Guangdong Province
Guangdong maintains operational heritage from early Generation II deployments while hosting new Hualong One construction. China General Nuclear Power Group headquarters in Shenzhen coordinates procurement across multiple plant complexes. Pearl River Delta manufacturing bases supply balance-of-plant equipment and digital twin integration platforms for predictive maintenance specifications.
China Nuclear Power Plant Equipment Market Competitive Environment
Player mix skews toward state-owned integrated utilities with captive engineering subsidiaries. Market structure consolidates around three dominant domestic conglomerates controlling reactor design licensing and equipment procurement channels. Strategic archetypes separate reactor island specialists, turbine generator fabricators, and auxiliary systems integrators. Competitive dynamics center on HAF 604 certification acquisition and long-term framework agreement negotiation with centralized utility procurement committees.
Among state-owned integrated operators, China National Nuclear Corporation and China General Nuclear Power Group anchor the utility tier with captive reactor design portfolios and unified procurement umbrellas. Dongfang Electric Corporation Limited exemplifies the equipment fabricator archetype with manufacturing scale across conventional island components. Shanghai Electric Power Generation Equipment Co., Ltd occupies a specialist position in auxiliary systems integration for coastal plant complexes. These three entities represent distinct competitive positions: integrated utility operator, scale-driven mechanical fabricator, and systems integration specialist.
| Leading Market Players |
|---|
| China National Nuclear Corporation |
| China General Nuclear Power Group |
| Shanghai Electric Power Generation Equipment Co., Ltd |
| Dongfang Electric Corporation Limited |
| Mitsubishi Heavy Industries Ltd |
| Doosan Enerbility |
| China Nuclear Engineering Corporation |
| China Nuclear Industry Construction Co., Ltd |
| Harbin Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
HAF 604 certification gates both supplier qualification and price differentiation in China's nuclear equipment sector, compressing foreign participation while elevating margin capture for domestic certificate holders. State-owned utilities exploit this dual gating mechanism to enforce cost-plus contracts with SA-508 Grade 3 steel indexation, transferring commodity volatility risk upstream while locking in long-term equipment availability.
Pricing Analysis
Cost-plus contracts with SA-508 Grade 3 steel indexation dominate procurement between state-owned utilities and reactor pressure vessel fabricators. Price differentiation separates HAF 604-certified domestic suppliers from foreign joint ventures facing extended qualification timelines and from uncertified local competitors barred from reactor island work. Cost compression in turbine generator sets is intensifying because Dongfang Electric and Harbin Electric are absorbing steel price volatility through captive metallurgical supply. Industrial end users pursuing modular reactor deployments exhibit highest price sensitivity due to undefined regulatory pathways, while coastal government utilities show lowest sensitivity given baseload energy security mandates.
Supply Chain Analysis
Port congestion at Ningbo and Qingdao is extending inbound logistics cycles for Inconel 690 tubing and specialized welding consumables sourced from France and Japan. Heavy forging capacity concentrates in China, France, and Japan, with SA-508 Grade 3 steel forgings drawing from Sichuan and Shandong metallurgical clusters. Single-source vulnerability pervades reactor pressure vessel fabrication where qualified forging presses number fewer than five globally. Distribution runs through state-owned utility procurement committees operating under National Energy Administration approval quotas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's nuclear equipment market reads as a service-attach opportunity where predictive maintenance contracts and steam generator aftermarket services expand faster than reactor island hardware sales. Digital twin integration mandates from state-owned operators are elevating recurring revenue streams above one-time equipment margins.
For Market Incumbents: Consolidate welding inspector certification pipelines by expanding Chengdu training programs to address ASME Section IX and HAF 603 scarcity threatening fabrication timelines. Deepen captive supply of SA-508 Grade 3 steel forgings through backward integration into Shandong metallurgical assets to defend against single-source vulnerability. Lock in long-term framework agreements with China National Nuclear Corporation procurement committees before modular reactor regulatory clarity attracts new competitors. For New Entrants and Emerging Players: Anchor in western provincial industrial applications where modular reactor deployments for Xinjiang mining and Inner Mongolia desalination operate outside coastal utility procurement structures. Target environmental compliance documentation services where Ministry of Ecology and Environment dual-track approval requirements burden incumbent steam generator fabricators. Enter through joint venture structures with existing HAF 604 certificate holders to bypass multi-year National Nuclear Safety Administration licensing timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned heavy industrial groups divesting non-core nuclear forging assets under localization mandate acceleration. Long-term viability hinges on positioning within Hualong One deployment pipelines rather than speculative modular reactor exposure. Monitor National Nuclear Safety Administration small modular reactor certification pathway announcements as the critical inflection signal separating investable from stranded asset positions.| Strategic Initiative | Industry Significance |
|---|---|
| HAF 604 Certification Acquisition | Domestic qualification under National Nuclear Safety Administration standards gates reactor island procurement participation. |
| SA-508 Grade 3 Steel Backward Integration | Captive metallurgical supply insulates reactor pressure vessel margins from commodity volatility. |
| Digital Twin Platform Development | State-owned operator mandates for predictive maintenance elevate system integrators above pure-play fabricators. |
| Western Provincial Modular Reactor Positioning | Remote mining and desalination applications in Xinjiang and Inner Mongolia escape coastal procurement concentration. |
| Steam Generator Aftermarket Service Contracts | Limited qualified tube sheet suppliers create captive recurring revenue from existing NNSA approvals. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of National Energy Administration planning directives, Ministry of Ecology and Environment licensing records, and state-owned utility procurement disclosures. Primary interviews engaged nuclear safety equipment procurement officers, heavy forging plant managers, welding inspector training program directors, and digital twin platform engineers at state-owned operators. Secondary validation drew from National Nuclear Safety Administration HAF certification registries, reactor construction permit filings, and metallurgical trade flow data. Bottom-up equipment shipment tracking triangulates against top-down utility capex commitment analysis.
Segmentation dimensions modeled span reactor island versus conventional island equipment categories, Generation III pressurized water reactor versus modular reactor technology pathways, and government utility versus industrial end user procurement channels. Forecast derivation across the analysis window incorporates National Energy Administration annual approval quota trajectories, Hualong One deployment pipeline visibility, and welding inspector certification supply constraints. Industry-specific inputs include SA-508 Grade 3 steel forging capacity utilization rates and steam generator tube sheet fabrication cycle extensions from non-destructive testing bottlenecks.
Material uncertainties — regulatory pathway clarification for small modular reactors, welding inspector certification supply response, and Ministry of Ecology and Environment environmental release protocol evolution — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding state-owned utility procurement centralization and localization mandate enforcement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
United Kingdom Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
Thorium Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market