
 Oxy-Hydrogen Generators Market | 2026-2036
Oxy-Hydrogen Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Oxy-Hydrogen Generators Market Insights
Automotive retrofit workshops are reorganizing their equipment procurement priorities around oxy-hydrogen carbon cleaning systems, displacing traditional chemical-based engine decarbonization services. Nel ASA anchors its position through captive electrolyzer technology that feeds directly into generator production. Hydroxy Gas India competes on localized manufacturing scale for the South Asian workshop segment. Air Liquide leverages its industrial gas distribution infrastructure to control channel access for large-format stationary installations.
Oxy-hydrogen generators produce a stoichiometric mixture of hydrogen and oxygen gases—typically via alkaline or proton exchange membrane electrolysis of demineralized water—to deliver flame temperatures exceeding 2800°C for precision thermal processing applications. The primary commercial purpose centers on metalworking operations where the gas mixture eliminates oxidative scaling compared to acetylene or propane alternatives. Stationary generators dominate current revenue pools due to permanent industrial installation contracts, while portable units represent the fastest-expanding category as mobile service providers adopt field-deployable carbon cleaning rigs. Electrolysis technology leads the technology dimension on installed base, though hybrid systems incorporating gas separation membranes are capturing margin concentration from customers seeking higher purity output streams.
EPA enforcement under the Clean Air Act shapes product certification requirements for combustion-related maintenance equipment sold in the United States, while EU F-Gas Regulation and REACH compliance frameworks govern material selection and emission profiles for generators deployed across European member states. OSHA workplace exposure limits for hydrogen storage influence generator enclosure design and safety interlock specifications. Stakeholders must monitor evolving electrolyzer efficiency standards and regional hydrogen infrastructure buildouts to align product roadmaps with shifting industrial energy policies.
Market Dynamics
Automotive service chains in Germany are restructuring capital allocation around EPA-aligned carbon cleaning equipment as tightening emissions enforcement rewrites maintenance technology procurement criteria across commercial garages.
Growth Catalysts
- Clean Air Act Enforcement:EPA emissions scrutiny on combustion engine pollutants compels US commercial garages to replace chemical decarbonization with oxy-hydrogen systems.
- EU F-Gas Regulation:REACH compliance mandates across European member states accelerate material selection upgrades in generator manufacturing.
- Alkaline Electrolysis:Mature electrolyzer technology delivers cost-competitive hydrogen-oxygen mixtures for metalworking operations seeking acetylene alternatives.
Market Restraints
- Platinum Group Metal Costs:Proton exchange membrane electrolyzer stacks depend on iridium and platinum catalysts subject to volatile commodity pricing.
- Electrolyzer Supply Concentration:Captive electrolyzer production anchors with Nel ASA and select Nordic suppliers, constraining independent generator manufacturers.
- Acetylene Infrastructure Entrenchment:Established gas distribution networks and technician familiarity slow displacement in legacy metalworking shops.
Strategic Opportunities
- Mobile Service Expansion:Field-deployable portable generator rigs enable carbon cleaning services at fleet depots and roadside locations.
- Hydrogen Infrastructure Buildouts:Regional industrial hydrogen policies in Germany and the Netherlands create captive demand for on-site generation systems.
- Hybrid Membrane Systems:Converging gas separation membranes with alkaline electrolysis captures margin from purity-sensitive precision thermal processing customers.
Industry Challenges
- Electrolyzer Technician Scarcity:Specialized maintenance skills for membrane and alkaline cell stacks outpace vocational training program output.
- OSHA Hydrogen Storage Compliance:Workplace exposure limits mandate complex safety interlock engineering and enclosure redesign cycles.
- Legacy Equipment Integration:Retrofitting oxy-hydrogen torches into established acetylene piping systems requires custom adapter fabrication and pressure testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxy-Hydrogen Generators Market |
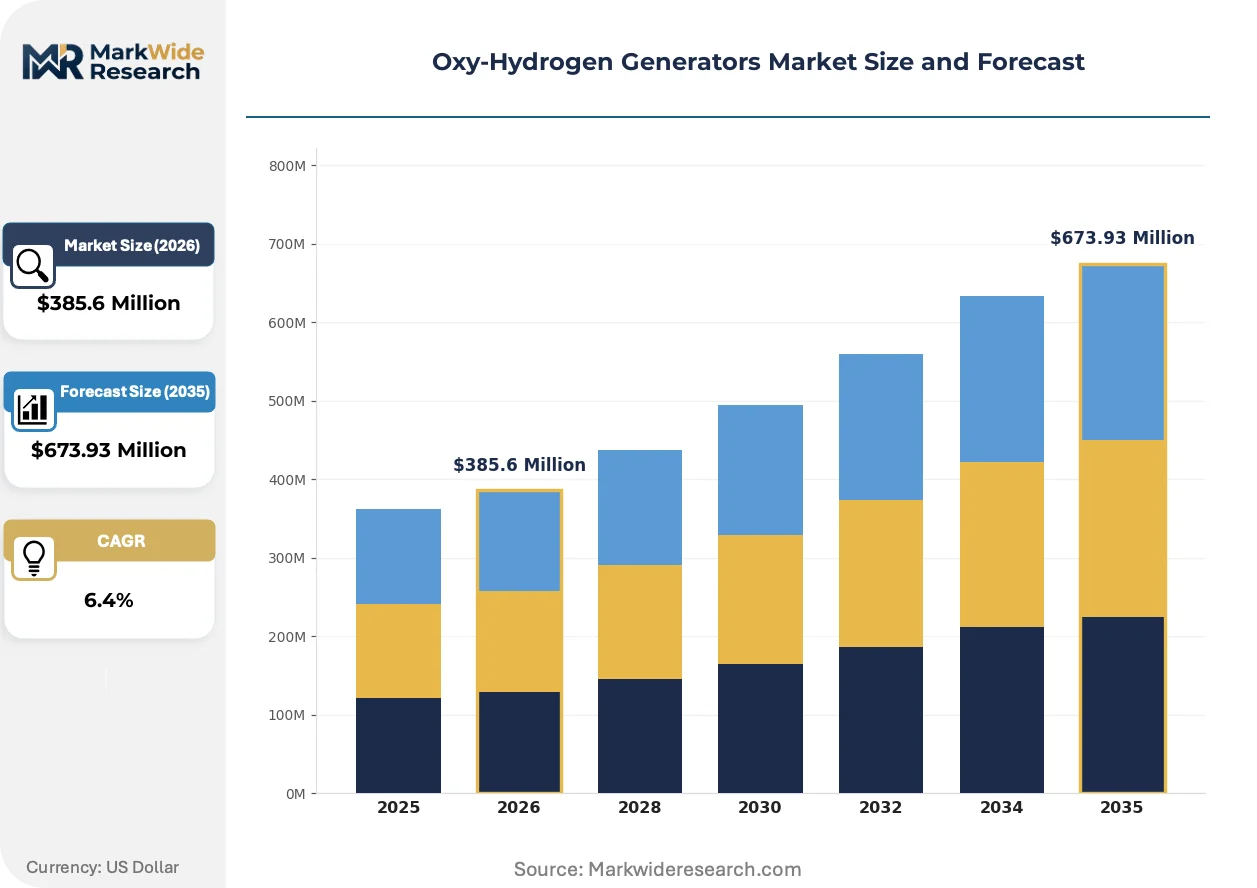
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Stationary Generators, Industrial Generators, Mini Generators End User: Manufacturing, Energy, Automotive, Residential Application: Welding, Fuel Cells, Heating, Cutting Technology: Electrolysis, Gas Separation, Water Hydrolysis, Hybrid Systems |
| Companies Covered | HHO Plus, HHO Bulgaria, Hydroxy Gas India, HHO Kits Direct, Hydrotech India, OxyHydrogen Systems, Nel ASA, Air Liquide, Linde, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxy-Hydrogen Generators Market Trends and Innovations
Electrolyzer efficiency benchmarks and hydrogen purity standards are rewriting product roadmaps as generator manufacturers align with industrial energy policy trajectories.
Proton exchange membrane electrolysis is supplanting alkaline systems in premium generator configurations. Precision metalworking shops in Germany and Japan are adopting PEM-based units for sub-99.999% purity requirements. This technology compression is enabling smaller footprint installations and faster response times in automated cutting operations.
REACH substance restrictions are forcing reformulation of gasket and seal materials in European-sold generators. Manufacturers must validate fluoropolymer alternatives against F-Gas Regulation phase-down schedules. The stationary generator segment bears the heaviest compliance burden due to permanent installation liability exposure.
Service unbundling is fragmenting traditional equipment-plus-gas supply contracts. German automotive chains now procure generators separately from maintenance subscriptions, compressing vendor switching cycles. This behavioral shift is most pronounced in Bavaria and Baden-Württemberg where independent workshop networks dominate fleet service markets.
Oxy-Hydrogen Generators Market Segmentation
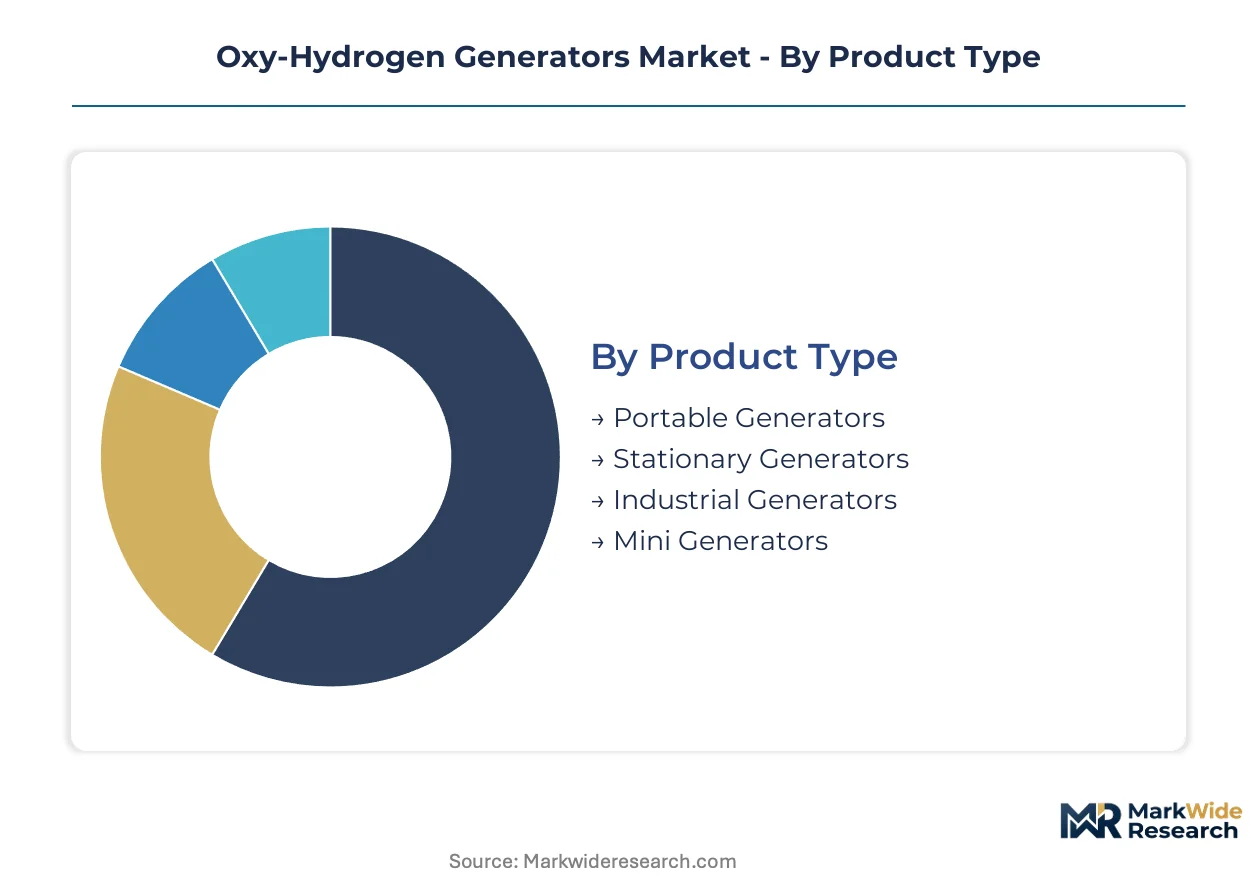
Segmentation in oxy-hydrogen generators reveals how technology choices, mobility requirements, and end-use thermal specifications fragment procurement patterns across metalworking shops, automotive service chains, and distributed energy installations.
Product Type:
Stationary and portable configurations command the deepest margin pools, with industrial-scale permanent installations locking in long-term service contracts and mobile units capturing premium pricing from fleet operators seeking field-deployable carbon cleaning.
- Portable Generators:Compact electrolyzer units mounted on service vehicle platforms deliver 50-200 liter-per-hour gas output for mobile engine decarbonization. Automotive retrofit chains in Germany are standardizing these rigs for depot-to-depot fleet servicing under federal environmental compliance mandates.
- Stationary Generators:Permanent alkaline or PEM electrolyzer installations producing 500+ L/hr for continuous metalworking operations. Welding shops in Japan and precision manufacturers in Baden-Württemberg favor these for sub-99.999% purity thermal processing without oxidative scaling.
- Industrial Generators:Megawatt-scale systems for centralized hydrogen-oxygen production at heavy fabrication facilities.
- Mini Generators:Benchtop units for laboratory prototyping and small-scale jewelry soldering applications.
Stationary generators hold installed capacity. Portable units are rotating up the share rankings.
End User:
Volume concentration sits with manufacturing and automotive segments, where regulatory pressure on combustion emissions and thermal process quality standards drive replacement cycles faster than energy or residential applications.
- Manufacturing:Metal fabrication shops, precision cutting operations, and thermal processing facilities deploy oxy-hydrogen for flame temperatures exceeding 2800°C. German industrial clusters around Stuttgart and Munich are displacing acetylene infrastructure as REACH compliance tightens chemical handling protocols.
- Automotive:Service chains and independent garages utilize generators for hydrogen-based engine carbon cleaning, eliminating chemical decarbonization. EPA Clean Air Act enforcement is compelling US commercial garages to adopt these systems for emissions-compliant maintenance.
- Energy:On-site hydrogen generation for fuel cell backup power and renewable energy storage integration.
- Residential:Hobbyist metalworking and small-scale heating applications with limited commercial penetration.
Manufacturing anchors current revenue. Automotive is climbing the fastest.
Application:
Welding and cutting applications concentrate margin capture due to technical specification requirements and established technician training infrastructure, while fuel cells and heating remain nascent with fragmented standards.
- Welding:Oxy-hydrogen flame welding of copper, aluminum, and stainless steel components where oxide-free joints are critical. Japanese precision manufacturers specify PEM-based generators for sub-99.999% purity requirements in automated production lines.
- Cutting:High-temperature thermal cutting of thick steel plate and specialized alloys. German shipyards and heavy equipment fabricators are retrofitting oxy-hydrogen torches into legacy acetylene piping systems under custom adapter protocols.
- Fuel Cells:On-site hydrogen supply for stationary fuel cell installations and vehicle refueling demonstrations.
- Heating:Direct flame heating for brazing, annealing, and localized thermal treatment operations.
Welding commands the largest installed base. Cutting is gaining share fastest.
Technology:
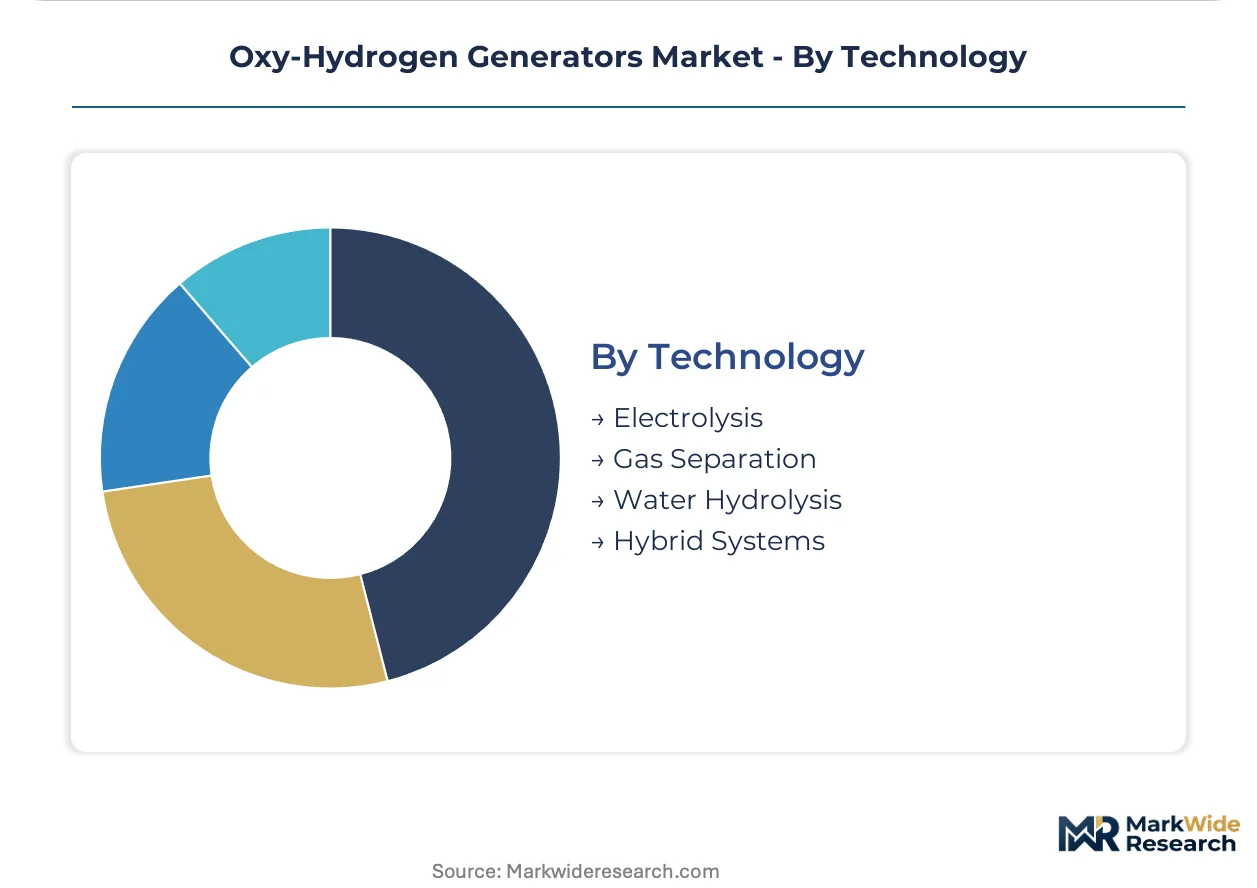
Electrolysis-based systems dominate current revenue pools through mature alkaline technology, while hybrid configurations are capturing expanding margin from purity-sensitive precision applications.
- Electrolysis:Alkaline and proton exchange membrane cells splitting demineralized water into stoichiometric hydrogen-oxygen mixtures. Alkaline systems lead on cost-competitive installed base; PEM units are supplanting them in premium configurations where footprint and response time matter.
- Hybrid Systems:Converged alkaline electrolysis with gas separation membranes for enhanced purity output. Precision metalworking shops in Germany and Japan are adopting these for automated cutting operations requiring sub-99.999% gas specifications.
- Gas Separation:Membrane and pressure swing adsorption units for purifying electrolyzer output streams.
- Water Hydrolysis:Alternative electrochemical approaches with limited commercial deployment relative to standard electrolysis architectures.
Electrolysis holds installed capacity. Hybrid systems are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive retrofit workshops and precision metalworking facilities concentrate procurement in jurisdictions with stringent emissions enforcement and REACH-mandated chemical handling protocols.
United States
Commercial garages facing EPA Clean Air Act enforcement are displacing chemical decarbonization with oxy-hydrogen engine cleaning systems. OSHA workplace exposure limits for hydrogen storage reshape generator enclosure specifications. Industrial clusters around Detroit and Houston retrofit legacy acetylene infrastructure for emissions-compliant maintenance.
Germany
Federal environmental compliance mandates drive automotive service chains toward carbon cleaning equipment. EU F-Gas Regulation and REACH substance restrictions force gasket material reformulation in stationary generator manufacturing. Stuttgart and Munich industrial corridors anchor demand from precision manufacturers seeking sub-99.999% purity thermal processing.
Japan
Precision cutting operations and automated welding lines specify proton exchange membrane generators for oxide-free joint requirements. METI industrial hydrogen policies support on-site generation adoption. Nagoya and Osaka manufacturing belts displace acetylene torches in heavy fabrication facilities.
India
Localized manufacturing scale serves South Asian workshop segments with cost-competitive alkaline electrolyzer systems. BIS standards and state-level pollution control mandates accelerate chemical decarbonization replacement. Maharashtra and Gujarat automotive hubs expand mobile service provider networks for depot-based fleet cleaning.
Netherlands
Regional industrial hydrogen policies create captive demand for megawatt-scale stationary installations. EU Green Deal alignment pressures metalworking shops toward acetylene alternatives. Rotterdam and Eindhoven industrial zones integrate oxy-hydrogen systems into renewable energy storage demonstrations.
Oxy-Hydrogen Generators Market Competitive Landscape
Player mix skews toward electrolyzer-integrated manufacturers and industrial gas distributors with channel control over large-format installations. The competitive structure fragments across captive technology holders, regional fabricators, and gas infrastructure incumbents. Two archetypes dominate: Nordic electrolyzer specialists with backward integration into generator production, and diversified industrial gas majors leveraging distribution scale. Consolidation pressure concentrates through strategic partnerships for membrane technology access and geographic expansion into automotive service chain procurement.
Among Nordic specialists, Nel ASA exemplifies captive electrolyzer integration that feeds directly into generator manufacturing. Hydroxy Gas India occupies a position within the regional fabricator tier serving South Asian workshop demand. Air Liquide sits within the industrial gas distributor archetype, controlling channel access for stationary installations through existing infrastructure relationships.
| Leading Market Players |
|---|
| HHO Plus |
| HHO Bulgaria |
| Hydroxy Gas India |
| HHO Kits Direct |
| Hydrotech India |
| OxyHydrogen Systems |
| Nel ASA |
| Air Liquide |
| Linde |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between German automotive service chains and Nordic electrolyzer suppliers lock in five-year supply access while capping price volatility through iridium and platinum indexation clauses. These arrangements insulate procurement teams from spot market swings in precious metal catalyst costs while committing volume thresholds that shape generator manufacturers' capacity planning cycles.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation for platinum group metals dominate procurement between automotive retrofit chains and electrolyzer-integrated manufacturers. Price differentiation rests on membrane purity grades and REACH certification tiers, with F-Gas-compliant units commanding substantial premiums over standard alkaline configurations. Cost compression in the portable generator tier is intensifying because Indian regional fabricators are flooding South Asian workshop segments with localized alkaline systems. Fleet operators and independent garages exhibit the sharpest price sensitivity, while precision metalworking shops in Stuttgart and Nagoya prioritize purity specifications over unit economics.
Supply Chain Analysis
Inventory lead times for proton exchange membrane stacks now stretch fourteen to twenty weeks as Nordic suppliers throttle output amid iridium sourcing constraints. Supply concentrates in Norway, Germany, and India, with captive electrolyzer production anchoring in Scandinavian industrial corridors while regional fabrication scales in South Asian workshop markets. The supply chain draws from iridium and platinum catalysts, fluoropolymer membranes, and precision-machined titanium cell components. Single-source vulnerability around Nordic electrolyzer technology creates systemic exposure for independent generator manufacturers lacking backward integration. Distribution runs through industrial gas distributors for stationary installations and direct OEM relationships for portable service vehicle platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough as EPA Clean Air Act enforcement reactivates replacement demand across US commercial garage networks. The recovery trajectory hinges on emissions compliance deadlines rather than discretionary capital expenditure cycles.
For Market Incumbents: Consolidate membrane technology access through strategic partnerships with Nordic electrolyzer specialists before iridium supply constraints tighten further. Nel ASA's captive production model demonstrates how upstream control over PEM stack manufacturing defends margin position against commodity volatility. Incumbents should simultaneously lock in long-term offtake contracts with German automotive chains to secure volume visibility through the compliance-driven replacement wave. For New Entrants and Emerging Players: Anchor in the mobile service provider segment across India's Maharashtra and Gujarat automotive corridors, where localized alkaline manufacturing scale meets underpenetrated depot-based fleet cleaning demand. The most penetrable white-space sits with independent workshop networks in Bavaria and Baden-Württemberg seeking F-Gas-compliant portable rigs without incumbent switching costs. A direct sales model targeting fleet maintenance supervisors bypasses established industrial gas distributor relationships that gate stationary installation access. For Investors and Strategic Acquirers: Capital is best deployed toward electrolyzer-integrated mid-cap specialists with demonstrated REACH certification pathways and existing automotive service chain relationships. Long-term viability across a five-to-ten-year horizon rests on membrane technology differentiation rather than pure manufacturing scale. The critical inflection signal to monitor is EPA enforcement intensity on chemical decarbonization penalties, which would accelerate replacement cycles beyond current compliance-driven baselines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyzer Manufacturing | Nel ASA's captive PEM production insulates margin from iridium price volatility. |
| REACH Certification Investment | F-Gas-compliant gasket materials unlock German automotive service chain procurement. |
| Mobile Service Platform Expansion | Field-deployable portable rigs capture fleet depot cleaning demand in India. |
| Hybrid Membrane System Development | Converged alkaline-separation architectures serve precision cutting shops in Japan. |
| Long-term Supply Agreement with Automotive Chains | Five-year offtake contracts lock in volume visibility through EPA compliance cycles. |
Research Methodology
Cross-validation between primary interviews with electrolyzer R&D directors and automotive fleet maintenance supervisors anchors the qualitative findings against secondary validation from EPA enforcement databases and EU F-Gas Regulation implementation reports. Plant managers at German precision metalworking facilities, procurement leads at Indian automotive retrofit chains, aftermarket service heads at Nordic generator manufacturers, and channel partners in industrial gas distribution provided operational perspective. Secondary sources include SEC filings from electrolyzer-integrated manufacturers, ECHA substance restriction updates, BIS standards documentation, and customs records tracking iridium and platinum catalyst imports. Bottom-up generator shipment tallies triangulate against top-down industrial hydrogen demand projections.
Sensitivity analysis across electrolyzer efficiency assumptions and platinum group metal price scenarios stress-tests volume and value outputs over the projection horizon. The analytical framework segments by technology architecture, mobility configuration, end-use thermal specification, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, fleet penetration rates for mobile carbon cleaning services, and purity-grade upgrade trajectories in precision manufacturing. Key inputs include EPA enforcement intensity indices, REACH compliance cost curves, and METI hydrogen infrastructure buildout schedules.
Decision-makers should treat outputs as directional under assumptions of sustained emissions enforcement and stable precious metal supply; material deviation in regulatory intensity or catalyst availability would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Middle-East and Africa Power Rental Market
Power
Digital Power Utility Market
Power
Power Purchase Agreement Market
Power
Qatar Power Market
Power
Controllable Shunt Reactor for UHV Market
Power
Direct Current Power System Market
Power
Electric Arc Furnaces Market
Power
Malaysia Power EPC Market
Power
Europe Frequency Converter Market
Power
Mexico Power Market
Power
Sudan Power Market
Power
Global UPS Market
Power
Norway Power Market
Power
Asia-Pacific Power Market
Power
Europe Solar Inverter Market
Power
Global Ancillary Services Power Market