
 Nuclear Energy Market | 2026-2036
Nuclear Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Energy Market Outlook
France's state-backed reactor fleet operator is pivoting toward extended plant lifespans and new-build commitments. Cameco Corp anchors North American uranium supply through its Saskatchewan mining operations and fuel services division. Constellation Energy Corp leverages its merchant nuclear fleet to capture rising capacity prices in PJM and ERCOT markets. Exelon Corporation sustains the largest regulated nuclear footprint in the United States across multiple state jurisdictions.
Nuclear energy harnesses controlled fission of uranium-235 or plutonium-239 isotopes within pressurized or boiling water reactor vessels to generate thermal energy for electricity production, with modern designs achieving thermal efficiencies exceeding 33 percent and operational lifespans of 60 to 80 years. Pressurized Water Reactor installations dominate existing global capacity due to their proven safety record and naval propulsion heritage, while Advanced Reactors within the technology segment attract the fastest-growing investment flows as developers pursue passive safety systems and higher burnup rates. Electricity Generation remains the foundational application, though Medical Isotope Production commands premium margins as supply chain security concerns intensify for molybdenum-99 and related diagnostic radioisotopes.
The U.S. Nuclear Regulatory Commission and the International Atomic Energy Agency enforce divergent but increasingly harmonized safety standards that shape reactor design certification timelines and cross-border technology transfer protocols. The European Union's taxonomy for sustainable finance, supplemented by national regulators such as ASN in France and ONR in the United Kingdom, determines which nuclear investments qualify for green capital allocation. Stakeholders must monitor regulatory convergence between Western and Chinese licensing regimes as reactor vendors seek multi-jurisdictional project approvals.
Market Dynamics
Small modular reactor licensing acceleration by the U.S. Nuclear Regulatory Commission is compressing project development cycles and redrawing competitive boundaries between established fleet operators and advanced reactor developers.
Growth Catalysts
- Grid Reliability Mandates:PJM and ERCOT capacity market reforms reward baseload nuclear with scarcity pricing during peak demand events.
- China's State-Led Buildout:Central government energy security directives commission multiple gigawatt-scale pressurized water reactor units annually.
- Medical Isotope Security:Supply chain vulnerabilities for molybdenum-99 production incentivize dedicated reactor investments for diagnostic radioisotope manufacturing.
Market Restraints
- Uranium Concentration Risk:Kazakhstan and Canada supply over half of global uranium concentrate, creating geopolitical exposure for Western utilities.
- Capital Intensity Barrier:Large light-water reactors require multi-billion dollar upfront commitments with decade-long construction timelines.
- Regulatory Divergence:The U.S. Nuclear Regulatory Commission and China's National Nuclear Safety Administration maintain incompatible certification standards that fragment vendor strategies.
Strategic Opportunities
- Data Center Load Growth:Hyperscale cloud operators in Virginia and Texas seek dedicated nuclear power purchase agreements for 24/7 carbon-free computing.
- EU Taxonomy Alignment:The European Union's sustainable finance classification unlocks green bond issuance for life extension investments at French and Swedish plants.
- Advanced Reactor Export:Bilateral agreements with Poland, Romania, and Indonesia create first-mover advantages for Western SMR vendors.
Industry Challenges
- Welding and Inspection Expertise Gap:Aging specialist workforces in pressure vessel manufacturing constrain new-build timelines.
- Digital Instrumentation Certification:Migration from analog to digital control systems triggers extensive safety case revalidation with national regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Energy Market |
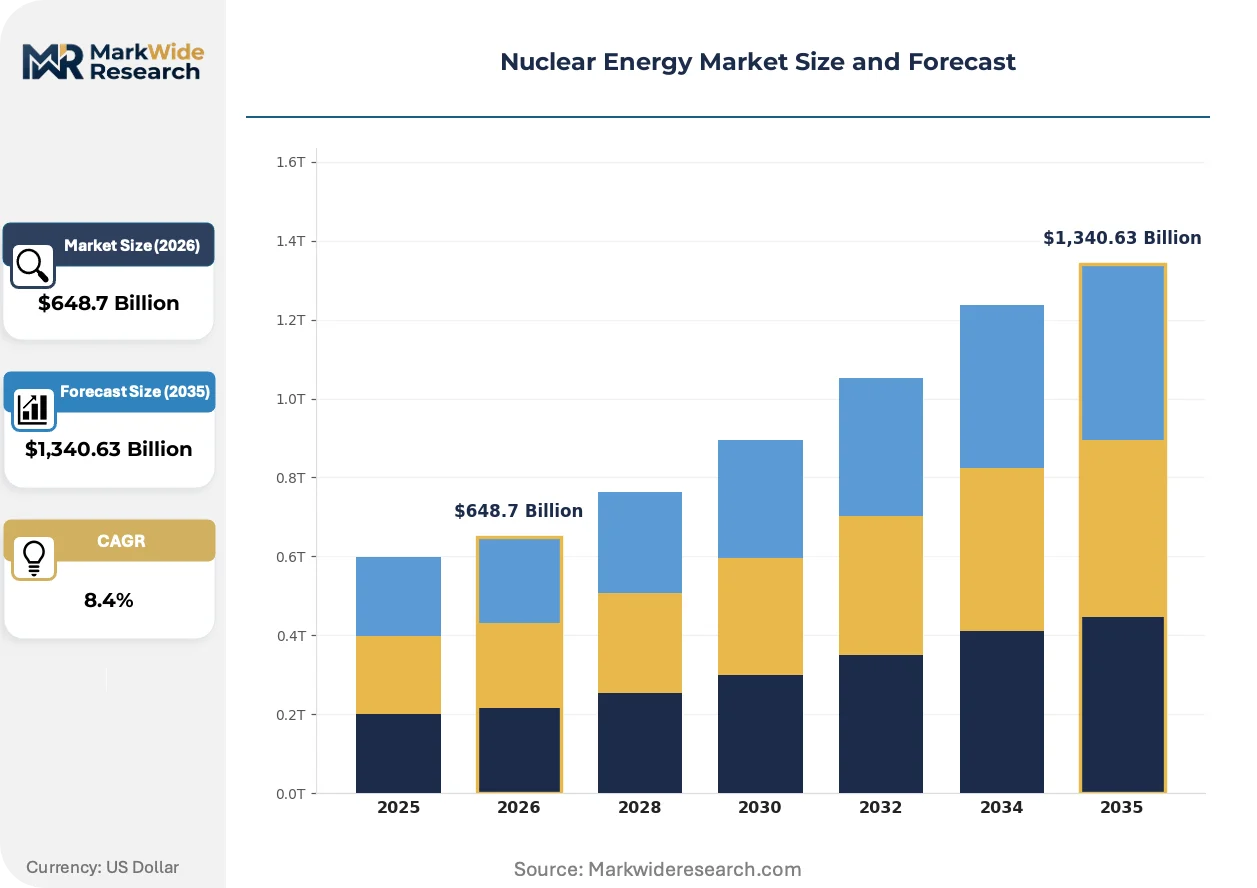
| Market Size in 2026 | $648.7 Billion |
| Market Size in 2035 | $1,340.63 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Pressurized Water Reactor, Boiling Water Reactor, Fast Breeder Reactor, Heavy Water Reactor Technology: Uranium Enrichment, Spent Fuel Management, Nuclear Waste Processing, Advanced Reactors End User: Electric Utilities, Government Agencies, Research Institutions, Industrial Facilities Application: Electricity Generation, Desalination, Medical Isotope Production, District Heating |
| Companies Covered | Cameco Corp, Constellation Energy Corp, Exelon Corporation, Duke Energy Corporation, Dominion Energy, FirstEnergy, Centrus Energy Corp, Denison Mines Corp, BWX Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Energy Market Strategic Shifts
Reactor design philosophy is pivoting from economies of scale toward factory fabrication and serial production, compressing delivery schedules and altering supplier relationships across the fuel cycle.
Small modular reactor technology is modularizing nuclear construction by enabling off-site manufacturing of standardized pressure vessel modules. Data center operators and industrial hydrogen producers are advancing power purchase negotiations for first-of-a-kind deployments. This shift is compressing the traditional engineering-procurement-construction model into repeatable assembly sequences that reduce site labor requirements.
The U.S. Nuclear Regulatory Commission's Part 53 licensing framework streamlines certification for non-light-water designs including molten salt and high-temperature gas reactors. Developers gain conditional design approval before completing full construction applications. Advanced reactor startups are restructuring regulatory submissions to exploit this phased pathway, while established vendors face sunk-cost disadvantages in legacy light-water platforms.
Corporate offtake contracting is displacing traditional utility-centric procurement as direct power purchase agreements emerge between reactor developers and industrial loads. Technology companies with 24/7 clean energy commitments are negotiating dedicated nuclear supply outside regulated utility structures. This pattern concentrates initially in deregulated U.S. markets where merchant generators can contract directly with large electricity consumers.
Nuclear Energy Market Segmentation
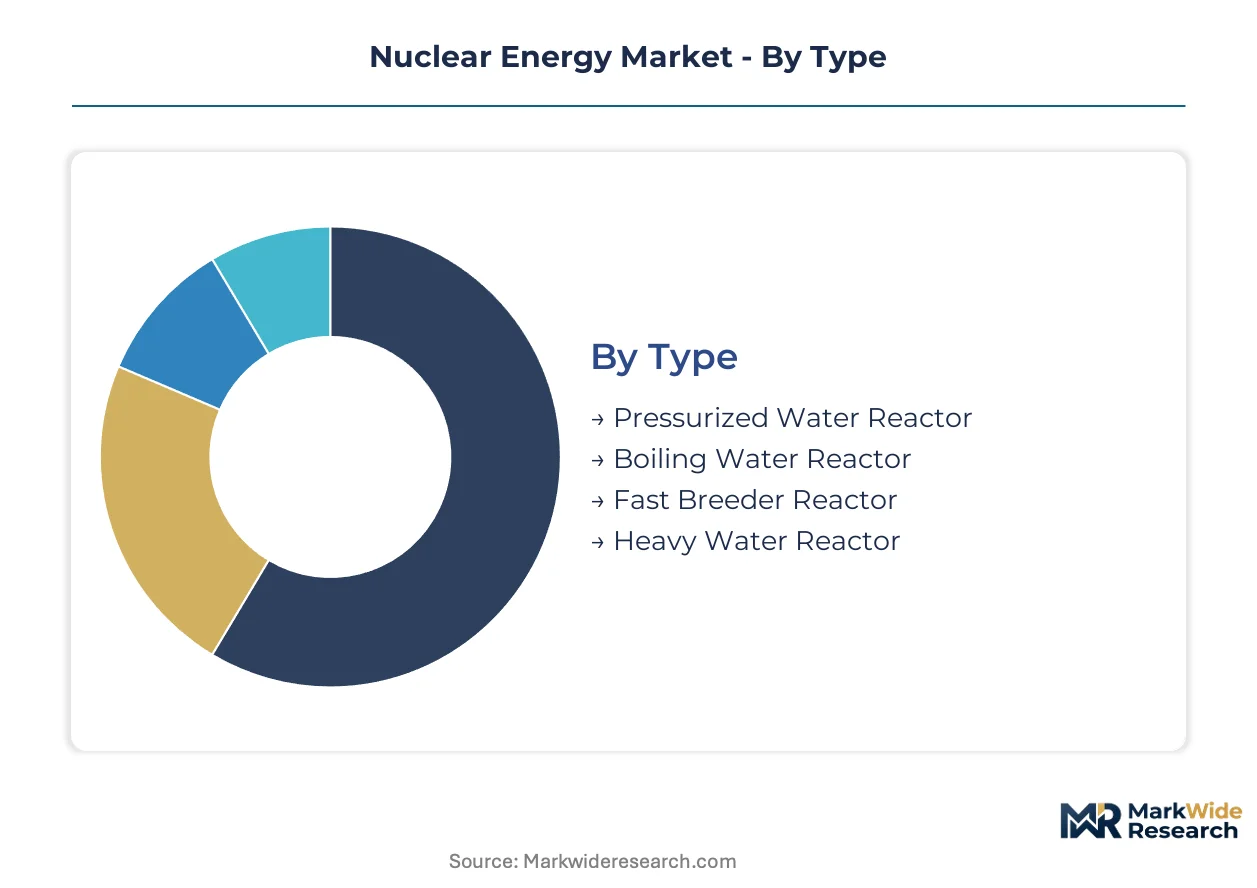
Reactor design philosophy and fuel cycle services fragment into distinct competitive arenas with divergent capital requirements and regulatory pathways. Technology suppliers and project developers must align capabilities against specific segment characteristics to capture value across the nuclear value chain.
Type:
Supply concentration in pressure vessel manufacturing and specialist welding expertise favors reactor types with established supply chains and proven construction methodologies.
- Pressurized Water Reactor:These systems circulate pressurized light water through the reactor core to a steam generator, transferring heat to a secondary loop for turbine operation. Demand concentrates in China and France, where state-backed utilities commission multiple units annually under centralized procurement frameworks.
- Boiling Water Reactor:Direct steam generation within the reactor vessel eliminates the intermediate heat exchanger, reducing capital costs but requiring more stringent containment designs. Japan's Tokyo Electric and US utilities in the Southeast favor this technology for its operational simplicity and lower staffing requirements.
- Fast Breeder Reactor:Sodium-cooled designs achieve higher fuel utilization through plutonium breeding. Russia's BN-800 unit at Beloyarsk demonstrates commercial viability.
- Heavy Water Reactor:CANDU technology uses natural uranium fuel and enables on-power refueling. Canada and India maintain active fleets.
Pressurized Water Reactor units absorb the bulk of installed capacity; Advanced Reactors within the technology segment are expanding most quickly.
Technology:
Cost tier differentiation separates commoditized fuel services from high-margin advanced reactor development programs with multi-decade revenue horizons.
- Uranium Enrichment:Centrifuge technology dominates, with Urenco and Orano operating Western capacity. Demand clusters in European and US utilities seeking to diversify from Russian supply.
- Spent Fuel Management:Interim storage in dry cask systems prevails where permanent geological repositories remain stalled. Finland's Onkalo facility advances deep disposal.
- Nuclear Waste Processing:Reprocessing recovers plutonium and uranium from spent fuel. France's La Hague facility processes domestic and foreign material.
- Advanced Reactors:Non-light-water designs including molten salt and high-temperature gas configurations pursue passive safety and industrial heat applications. X-energy and Kairos Power advance demonstration projects in Texas and Tennessee.
Uranium Enrichment commands the largest revenue pool; Advanced Reactors gain share fastest as developers secure corporate offtake agreements.
End User:
Customer type determines procurement structure, with regulated utilities favoring rate-base treatment and merchant generators pursuing bilateral contracts.
- Electric Utilities:Vertically integrated and independent power producers operate the majority of commercial reactors. US utilities in PJM and ERCOT capture scarcity pricing through capacity market reforms.
- Government Agencies:National laboratories and defense programs sustain specialized reactor operations. The US Department of Energy funds advanced reactor demonstrations at Idaho National Laboratory.
- Research Institutions:University reactors support materials science and neutron scattering research. MIT and Oak Ridge maintain operational units.
- Industrial Facilities:Chemical and hydrogen producers evaluate dedicated nuclear heat and power. Nucor and Dow explore advanced reactor partnerships for steel and petrochemical operations.
Electric Utilities anchor capacity deployment; Industrial Facilities represent the steepest expansion trajectory for first-of-a-kind advanced reactor deployments.
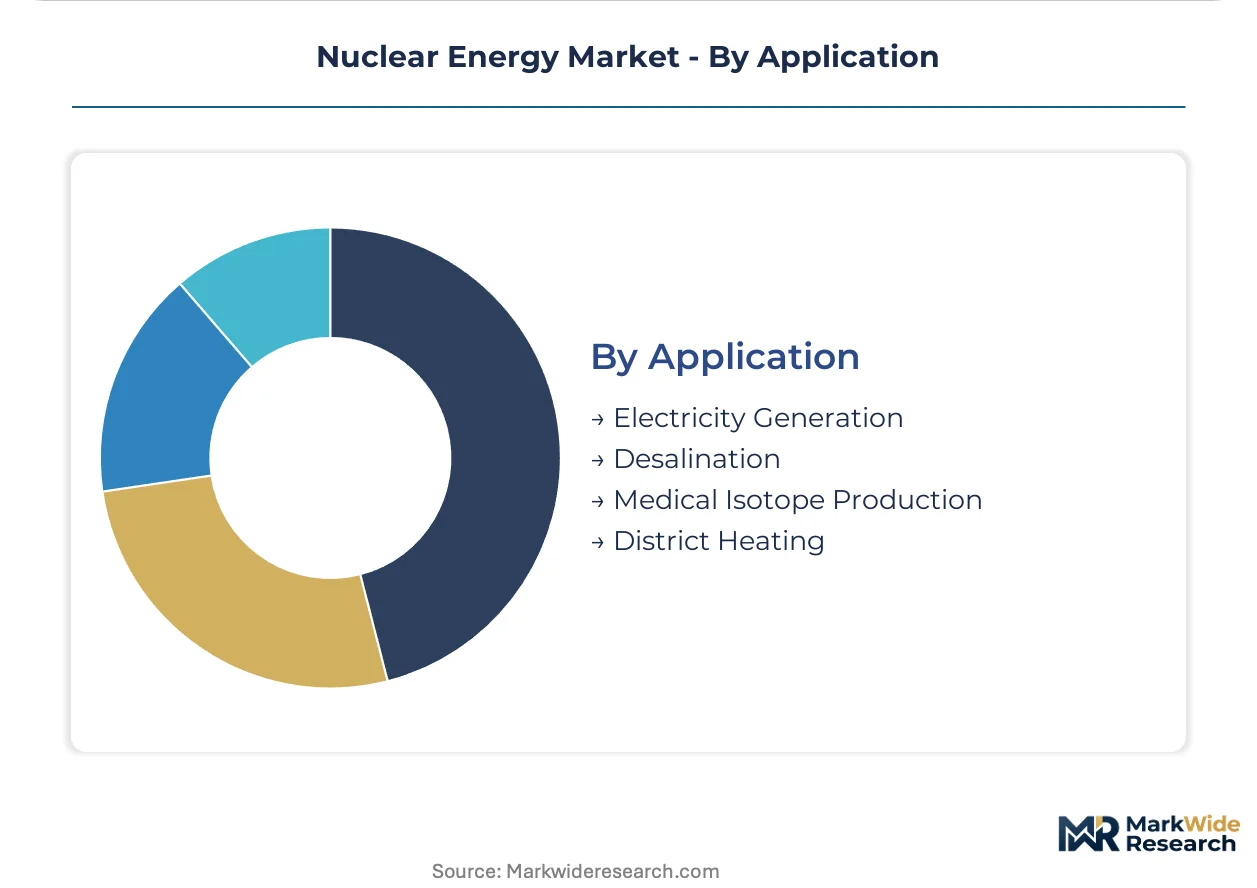
Application:
Application maturity varies dramatically, with electricity production enjoying century-scale operational history while non-electric applications remain commercially nascent.
- Electricity Generation:Baseload power supply dominates nuclear deployment, with fleet operators in France, the US, and China sustaining high capacity factors. Grid reliability mandates and carbon-free commitments reinforce nuclear's role in decarbonization strategies.
- Desalination:Cogeneration configurations produce potable water alongside electricity. Saudi Arabia and the UAE evaluate nuclear desalination for water security.
- Medical Isotope Production:Molybdenum-99 and related diagnostic radioisotopes command premium pricing. Canada's Chalk River legacy and European reactors face supply constraints.
- District Heating:Nuclear cogeneration supplies residential and industrial heat. Russia's floating nuclear plant at Pevek demonstrates Arctic applications.
Electricity Generation retains dominant deployment share; Medical Isotope Production climbs the fastest as supply chain security concerns intensify diagnostic radioisotope investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Uranium deposits in Saskatchewan's Athabasca Basin anchor North American supply security for Western reactor fleets. State-backed utilities in China and France commission multiple gigawatt-scale units annually under centralized procurement frameworks.
United States
Merchant generators in PJM and ERCOT capture scarcity pricing through capacity market reforms that reward baseload reliability. The U.S. Nuclear Regulatory Commission's Part 53 framework accelerates small modular reactor licensing timelines. Data center clusters in Northern Virginia and Texas negotiate dedicated nuclear power purchase agreements for carbon-free computing loads.
China
Central government energy security directives commission multiple pressurized water reactor units annually through state-backed developers. The National Nuclear Safety Administration maintains certification standards that diverge from Western regulatory regimes. Coastal provinces in Guangdong and Fujian concentrate new-build activity near manufacturing hubs and load centers.
France
Électricité de France pursues extended plant lifespans and new-build commitments under state-backed recapitalization. The Autorité de Sûreté Nucléaire enforces safety standards aligned with EU taxonomy requirements for green finance eligibility. The Grand Carénage refurbishment program concentrates engineering resources at Tricastin and Gravelines sites.
Canada
Cameco's Saskatchewan mining operations supply uranium concentrate to Western utilities diversifying from Russian sources. The Canadian Nuclear Safety Commission regulates CANDU technology deployments domestically and for export markets. Ontario's Bruce Power and Darlington sites anchor the provincial baseload generation fleet.
Japan
Tokyo Electric and Kansai Electric restart idled boiling water reactor units under post-Fukushima regulatory protocols. The Nuclear Regulation Authority enforces stricter safety standards than pre-2011 frameworks. Western Japan's industrial corridor from Osaka to Hiroshima drives demand for restored nuclear capacity.
Nuclear Energy Market Competitive Environment
Global majors compete with regional champions across fuel cycle services and reactor operations. The market structures around vertically integrated uranium miners, regulated utility operators, and specialized fuel fabricators. Three archetypes dominate: state-backed fleet operators with rate-base protections, merchant generators capturing wholesale price volatility, and upstream uranium suppliers controlling concentrate production. Competitive moves center on long-term offtake contracting and regulatory licensing advantages for advanced reactor designs.
Within the upstream supply tier, Cameco Corp and Centrus Energy Corp exemplify divergent strategies for Western uranium security. Among regulated utility operators, Constellation Energy Corp and Exelon Corporation occupy positions as fleet-scale generators with exposure to capacity market reforms. Duke Energy Corporation and Dominion Energy represent vertically integrated utilities with rate-base treatment for nuclear assets across multiple state jurisdictions.
| Leading Market Players |
|---|
| Cameco Corp |
| Constellation Energy Corp |
| Exelon Corporation |
| Duke Energy Corporation |
| Dominion Energy |
| FirstEnergy |
| Centrus Energy Corp |
| Denison Mines Corp |
| BWX Technologies |
| Others |
Value Chain & Pricing Dynamics
Specialist welding and pressure vessel fabrication workforces in South Korea and Japan concentrate in shipyard-adjacent industrial zones, creating labor-cost differentials that widen pricing spreads between premium certified reactor components and economy-tier modular assemblies.
Pricing Analysis
Extended warranty and fuel-supply bundling separates premium reactor vendor offerings from unbundled equipment-only transactions. Pricing stratifies across three tiers: full-wrap engineering-procurement-construction contracts, technology licensing with local content requirements, and component-only supply without construction support. Price differentiation hinges on NRC certification tier and domestic content percentage thresholds. Cost compression in the economy tier intensifies as Chinese reactor vendors expand export financing. Merchant utilities in deregulated markets exhibit highest price sensitivity; state-backed fleet operators prioritize total lifecycle cost over upfront capital.
Supply Chain Analysis
Heavy-lift vessel charter rates and specialized nuclear cargo insurance premiums elevate logistics costs for oversized pressure vessel shipments from forging facilities to coastal assembly sites. Uranium concentrate supply concentrates in Kazakhstan, Canada, and Namibia; enrichment services draw from Urenco's European and US centrifuge plants. Zirconium alloy tubing and control rod assemblies rest on Japanese and French specialty metal suppliers. Single-source vulnerability persists in ultra-large forging presses capable of reactor pressure vessel manufacture. Distribution runs through long-term offtake contracts between miners, converters, and utility fuel buyers rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where the U.S. Nuclear Regulatory Commission's Part 53 certification timeline creates a decade-long barrier-to-entry moat protecting first-mover advanced reactor developers from fast-follower competition.
For Market Incumbents: Anchor market position through exclusive fuel services contracting with utilities facing uranium supply diversification mandates. Pursue backward integration into Saskatchewan uranium mining to capture margin from concentrate through fabrication. Defend against emerging SMR developers by accelerating digital instrumentation upgrades at legacy pressurized water reactor fleets before regulatory mandates force compliance spending. For New Entrants and Emerging Players: The premium-to-economy pricing gap in medical isotope production offers accessible entry without gigawatt-scale capital requirements. Target diagnostic radioisotope supply agreements with North American hospital networks currently dependent on aging Canadian and European reactor sources. Pursue partnership structures with national laboratories for irradiation services rather than greenfield reactor construction. For Investors and Strategic Acquirers: Re-rating potential sits with advanced reactor developers holding conditional NRC design approval given corporate offtake momentum from hyperscale data center operators. Long-term viability favors platforms with demonstrated passive safety systems and industrial heat applications beyond electricity generation. Monitor Poland and Romania SMR deployment timelines as inflection signals for Western vendor export competitiveness against Chinese state-backed offerings.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Uranium Offtake Contracting | Western utilities securing Kazakh and Canadian concentrate volumes reduce exposure to Russian supply disruption under sanctions regimes. |
| SMR Design Certification Investment | Developers advancing through NRC Part 53 phases gain regulatory precedence that compresses competitor approval timelines. |
| Corporate Power Purchase Agreements | Direct contracts with Virginia and Texas data center operators bypass traditional utility procurement structures and rate-base constraints. |
| Fuel Cycle Backward Integration | Upstream control over Saskatchewan mining and conversion assets captures margin through enrichment and fabrication stages. |
| Medical Isotope Reactor Deployment | Dedicated molybdenum-99 production facilities address supply chain vulnerabilities from aging Chalk River infrastructure. |
Study Parameters
Multi-period observation of reactor construction timelines, licensing submission milestones, and capacity factor performance anchored the trend analysis, supplemented by interviews with utility fuel procurement officers, reactor vendor project managers, enrichment facility operators, and national laboratory research directors. Secondary validation drew from U.S. Nuclear Regulatory Commission docket filings, International Atomic Energy Agency reactor databases, World Nuclear Association fuel cycle reports, and utility SEC 10-K disclosures. Bottom-up unit economics and top-down market sizing were triangulated against disclosed power purchase agreement terms and announced project capital commitments.
Input-output matrices mapped uranium supply volumes through conversion, enrichment, and fabrication stages against reactor demand by technology type and geographic deployment. Segmentation modeling spanned reactor design category, fuel cycle service tier, end-user regulatory structure, and application across electricity generation and non-electric uses. CAGRs were derived from regression analysis of historical capacity additions correlated with policy incentive intensity and grid reliability mandate implementation. Forecast inputs included announced reactor construction schedules, corporate offtake letter-of-intent volumes, and national energy security directive timelines.
Inputs from regulatory filing databases and utility disclosure documents were available through the study window; gaps in privately held reactor vendor financials and undisclosed power purchase agreement pricing introduce uncertainty bands around revenue projections. Forecasts reflect documented assumptions regarding licensing timeline acceleration, uranium supply diversification trajectories, and capacity market reform implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
Nuclear Power Pump Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Thorium Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market