
 North America Nuclear Reactor Construction Market | 2026-2036
North America Nuclear Reactor Construction Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nuclear Reactor Construction Market Analytics
Multi-source procurement for reactor components and engineering services is broadening across North American utilities. Westinghouse Electric Company LLC leverages its AP1000 design certification to sustain technology leadership in large-scale pressurized water reactor deployments. Bechtel anchors major infrastructure delivery through its project management capabilities at complex nuclear sites. BWX Technologies specializes in nuclear components and fuel manufacturing, differentiating its position in the supply chain for both new builds and operating fleet support.
North America nuclear reactor construction encompasses the engineering, procurement, and construction of fission-based power generation facilities, typically requiring steel reactor pressure vessels exceeding 15 inches in wall thickness, specialized welding procedures, and seismic qualification to site-specific ground motion criteria. The primary purpose is to deliver grid-connected baseload electricity with capacity factors above 90 percent. Small modular reactor and advanced reactor technology segments are attracting capital commitments ahead of traditional pressurized water reactor categories, while greenfield project type activity generates the largest absolute contract values despite longer development cycles. Refurbishment segments offer shorter payback periods and lower regulatory risk profiles.
The U.S. Nuclear Regulatory Commission's Part 52 licensing framework and Canada's Canadian Nuclear Safety Commission vendor design review process govern reactor certification and site permitting across the continent. EPA emissions standards and state-level renewable portfolio standards indirectly shape demand by constraining fossil alternatives. The Canadian Environmental Assessment Act and provincial utility planning processes in Ontario and New Brunswick add jurisdictional complexity. Stakeholders must monitor regulatory readiness for advanced reactor designs and assess supply chain capacity against announced project pipelines.
Market Dynamics
The U.S. Department of Energy's loan guarantee programs and Canada's vendor design review process are compressing development timelines for advanced reactor designs, while utility procurement teams restructure supplier relationships around small modular reactor delivery models.
Growth Catalysts
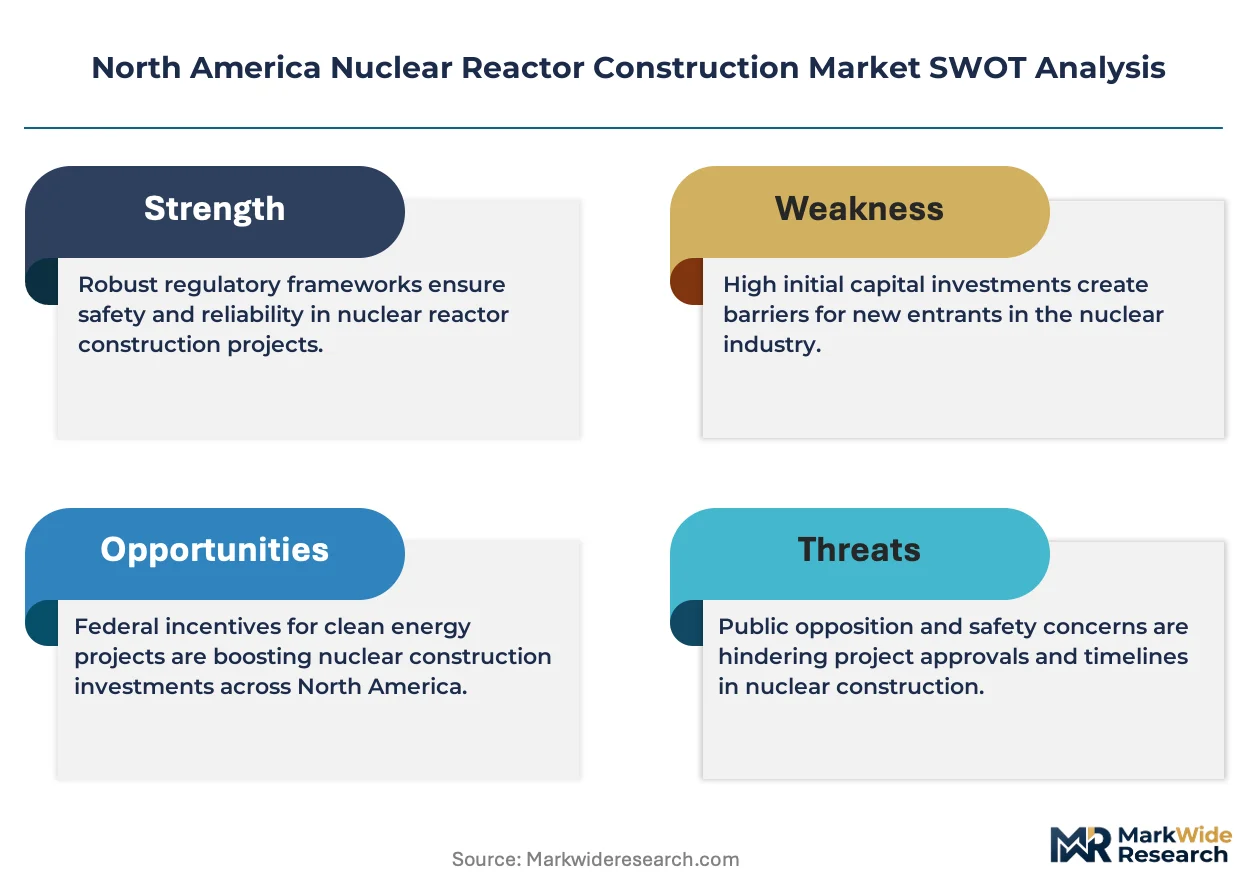
- IRA Production Tax Credits:The Inflation Reduction Act's clean energy incentives are improving project economics for utilities evaluating new nuclear capacity against renewable alternatives.
- Southeastern State Mandates:Clean energy portfolio standards in Georgia, South Carolina, and Virginia are preserving nuclear baseload as a compliance pathway alongside intermittent renewables.
- Advanced Manufacturing:Additive fabrication techniques for reactor pressure vessel components are reducing lead times and enabling domestic sourcing of previously imported forgings.
Market Restraints
- Heavy Forging Concentration:Steel reactor pressure vessels exceeding 15 inches wall thickness rely on a limited supplier base concentrated in Japan and France, creating single-source vulnerability.
- NRC Part 52 Licensing Duration:The certification framework for new reactor designs requires multi-year review cycles that extend capital commitment periods beyond utility planning horizons.
- Natural Gas Price Volatility:Competing baseload capacity from combined-cycle gas turbines creates dispatch economics pressure during periods of suppressed Henry Hub pricing.
Strategic Opportunities
- Ontario Refurbishment Pipeline:Bruce Power and Ontario Power Generation's multi-unit life extension programs offer near-term contract visibility absent greenfield permitting risk.
- SMR Export Positioning:Canadian and U.S. vendor design certifications are creating licensing reciprocity pathways for reactor deployment in Central and Eastern European markets.
- Data Center Colocation:Hyperscale computing facilities in Texas and Arizona are negotiating behind-the-meter power purchase agreements for dedicated nuclear generation.
Industry Challenges
- ASME Section III Welder Certification:Specialized nuclear welding qualifications require multi-year apprenticeship pipelines that lag announced construction schedules.
- Seismic Qualification Testing:Site-specific ground motion criteria for new western U.S. projects demand extended shake-table validation of safety-related electrical equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nuclear Reactor Construction Market |
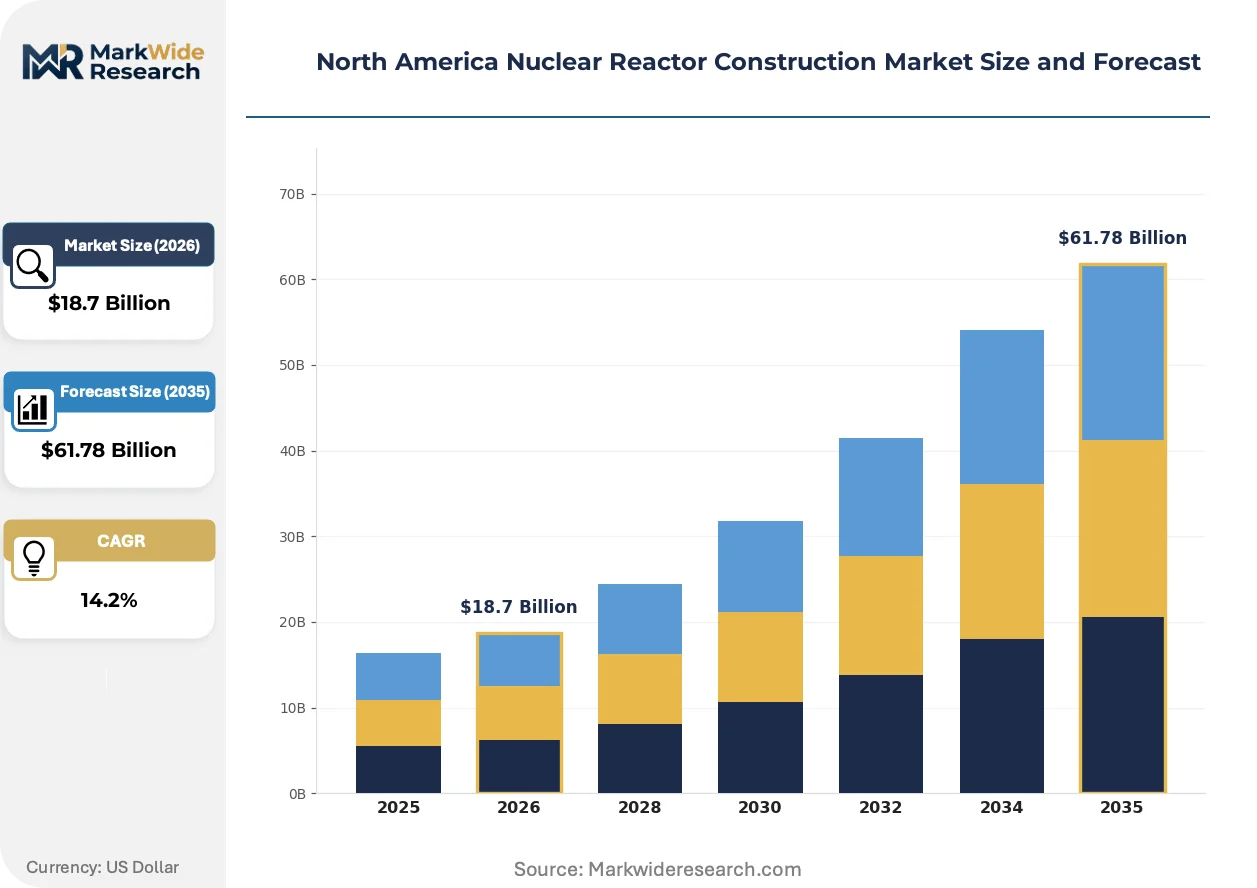
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Greenfield, Refurbishment, Expansion, Decommissioning Technology: PWR, BWR, SMR, Advanced Reactors Contractor Type: EPC Contractors, Subcontractors, Consultants, Design Firms Regulatory Framework: Licensing, Safety Standards, Compliance, Environmental Impact |
| Companies Covered | Rosatom State Nuclear Energy Corporation, Westinghouse Electric Company LLC, GE-Hitachi Nuclear Energy Inc., Mitsubishi Heavy Industries Ltd, Electricite de France SA, Framatome, AECOM, Bechtel, BWX Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nuclear Reactor Construction Market Evolving Landscape
Digital engineering tools and modular construction methods are restructuring how reactor projects move from design certification to concrete pour, compressing field execution timelines while elevating precision requirements for component interfaces.
Small modular reactor technology is absorbing engineering talent and capital commitments previously directed toward large-scale pressurized water reactor designs. Utilities in the southeastern United States are prioritizing SMR vendor engagement for mid-2030s deployment targets. This technology shift is absorbing licensing resources at the Nuclear Regulatory Commission and compressing the addressable market for traditional gigawatt-scale construction.
Canada's Canadian Nuclear Safety Commission has streamlined its vendor design review process to enable concurrent U.S. NRC certification efforts, reducing redundant engineering submissions for cross-border reactor deployment. This regulatory alignment is accelerating project development timelines for utilities with assets in both jurisdictions. The Ontario and New Brunswick provincial planning processes are incorporating these dual-certification pathways into integrated resource planning.
Utility procurement teams are consolidating component specifications across multiple reactor projects to achieve volume pricing from heavy forging suppliers. This specification standardization is displacing project-specific engineering approaches that historically fragmented order books. The concentration of demand is most visible at Tennessee Valley Authority and Duke Energy, where multi-unit procurement strategies are reshaping supplier negotiation dynamics.
North America Nuclear Reactor Construction Market Segmentation
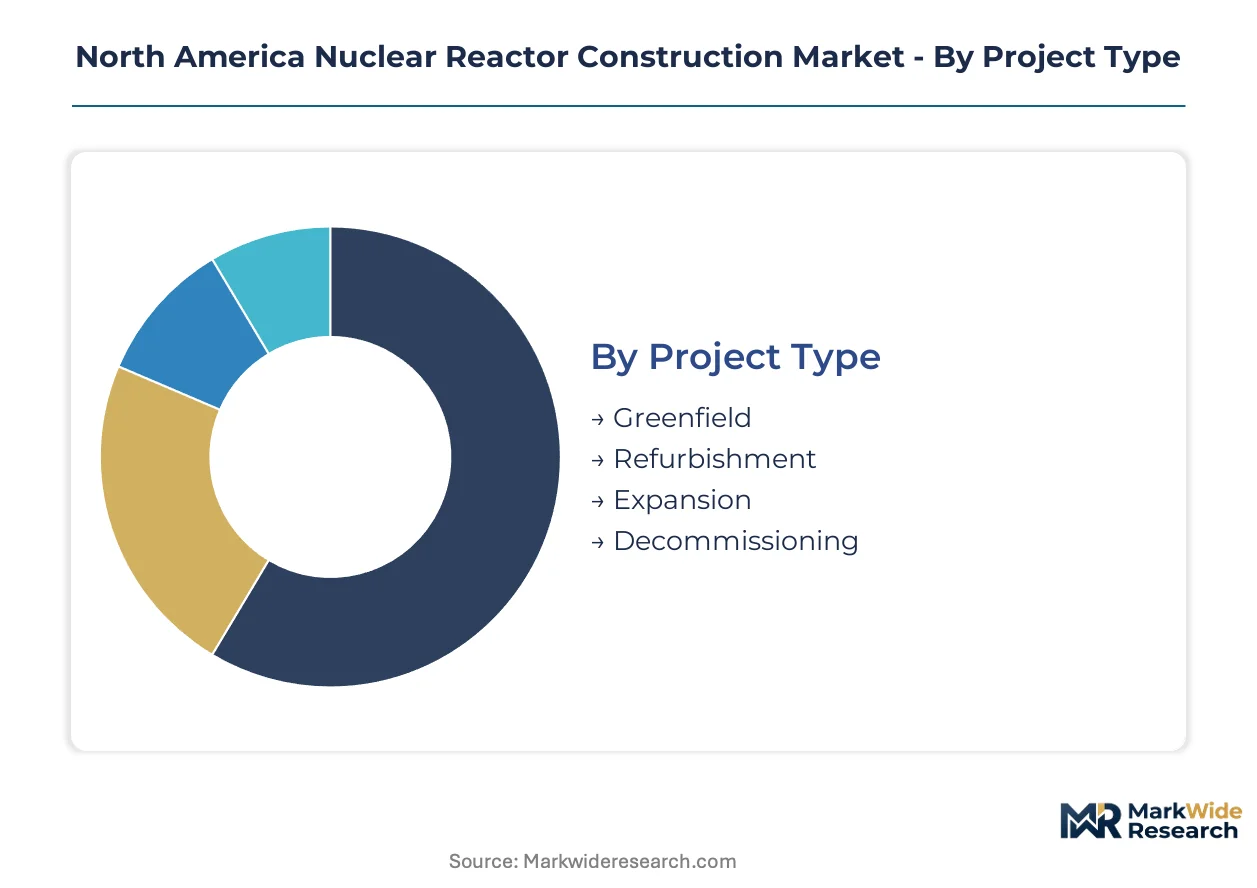
Reactor construction segmentation in North America reveals how capital allocation shifts between life extension and new build commitments. Project sponsors structure procurement differently across greenfield, refurbishment, and emerging technology categories, with each segment demanding distinct contractor capabilities and regulatory pathways.
Project Type:
Greenfield and refurbishment cycles operate on fundamentally different capital deployment timelines, with refurbishment compressing payback periods while greenfield delivers multi-decade capacity additions.
- Greenfield:New reactor construction on previously undeveloped sites requires NRC Part 52 certification and multi-year capital commitment periods. Demand concentrates in Georgia, South Carolina, and Virginia where state clean energy mandates preserve nuclear baseload alongside intermittent renewables.
- Refurbishment:Life extension programs for operating reactors involve pressure tube replacement and steam generator upgrades with shorter regulatory review cycles. Ontario Power Generation and Bruce Power in Canada anchor near-term contract visibility through multi-unit refurbishment pipelines absent greenfield permitting risk.
- Expansion:Additional reactor units at existing licensed sites leverage established infrastructure and workforce pools.
- Decommissioning:Permanent reactor shutdown and site restoration activities governed by NRC and CNSC waste management protocols.
Volume placements concentrate in Refurbishment; the faster expansion belongs to Greenfield.
Technology:
Technology selection determines forging specifications, licensing pathways, and the addressable supplier base for critical components.
- PWR:Pressurized water reactor designs dominate the installed base and supply chain maturity. Westinghouse AP1000 certification sustains technology leadership for large-scale deployments in the southeastern United States.
- SMR:Small modular reactors below 300 MWe are absorbing engineering talent and NRC licensing resources previously directed toward gigawatt-scale projects. NuScale Power and Ontario Power Generation are prioritizing SMR engagement for mid-2030s deployment targets.
- BWR:Boiling water reactor technology retains presence in the existing fleet with specialized maintenance and component replacement demand.
- Advanced Reactors:Non-light water designs including sodium-cooled and high-temperature gas reactors require novel licensing frameworks and manufacturing qualification.
Technology commitments are shifting most rapidly toward SMR platforms; PWR retains the largest installed base for component replacement demand.
Contractor Type:
Procurement structures are consolidating around integrated delivery models that compress interface risk between engineering and field execution.
- EPC Contractors:Engineering-procurement-construction integrators assume single-point accountability for schedule and cost performance. Bechtel anchors major infrastructure delivery through project management capabilities at complex nuclear sites.
- Subcontractors:Specialized mechanical, electrical, and civil trades execute scope packages under EPC direction. ASME Section III welder certification requirements create multi-year apprenticeship pipelines that lag announced construction schedules.
- Consultants:Independent engineering and regulatory advisory services support owner oversight and licensing strategy.
- Design Firms:Reactor vendor engineering organizations and architect-engineers develop certified design packages for NRC and CNSC review.
Contractor selection is concentrating in EPC-led structures; design firm engagement is climbing fastest with SMR certification demand.
Regulatory Framework:
Compliance architecture shapes project sequencing, with dual-certification pathways emerging for cross-border reactor deployment.
- Licensing:NRC Part 52 design certification and CNSC vendor design review govern reactor approval timelines. The Canadian regulator has streamlined its process to enable concurrent U.S. certification efforts, reducing redundant engineering submissions.
- Safety Standards:Seismic qualification to site-specific ground motion criteria demands extended shake-table validation for western U.S. projects.
- Compliance:Quality assurance programs under 10 CFR 50 Appendix B and CSA N285.0 govern component manufacturing and installation.
- Environmental Impact:National Environmental Policy Act reviews in the United States and Canadian Environmental Assessment Act processes add jurisdictional complexity to project timelines.
Regulatory resource allocation concentrates in Licensing; Environmental Impact review duration is expanding most quickly with advanced reactor novelty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel reactor pressure vessel forging capacity in Japan and France supplies North American project pipelines, creating geographic interdependence that shapes procurement timelines across the continent.
United States
Georgia, South Carolina, and Virginia host the most active greenfield development pipelines, with state clean energy mandates preserving nuclear baseload alongside intermittent renewables. The U.S. Department of Energy's loan guarantee programs compress capital commitment periods for utilities evaluating new capacity. Tennessee Valley Authority and Duke Energy anchor multi-unit procurement strategies that reshape supplier negotiation dynamics across the southeastern cluster.
Canada
Ontario Power Generation and Bruce Power drive near-term contract visibility through multi-unit refurbishment pipelines absent greenfield permitting risk. The Canadian Nuclear Safety Commission's streamlined vendor design review process enables concurrent U.S. NRC certification efforts, reducing redundant engineering submissions. Provincial utility planning processes in Ontario and New Brunswick incorporate dual-certification pathways into integrated resource planning.
Mexico
CFE's existing Laguna Verde facility represents the sole operational nuclear capacity, with limited near-term expansion activity compared to northern neighbors. The national utility's capital allocation prioritizes grid modernization and renewable integration over new nuclear baseload. Industrial clusters in Veracruz and Mexico City concentrate engineering talent for potential future vendor engagement if policy shifts occur.
North America Nuclear Reactor Construction Market Competitive Landscape
Technology licensing dominates the current landscape, with reactor vendors leveraging design certifications to secure long-term fuel and service revenue streams. The vendor base concentrates around a handful of integrated technology providers with NRC and CNSC approvals, supplemented by specialized component fabricators and construction integrators. Two strategic archetypes define positioning: full-scope reactor vendors controlling design intellectual property, and EPC-led consortia assuming single-point accountability for field execution. Competitive intensity centers on SMR certification races and multi-unit procurement bundling.
Among U.S.-based technology providers, Westinghouse Electric Company LLC exemplifies the full-scope reactor vendor archetype through its AP1000 design certification. Bechtel anchors major infrastructure delivery capabilities at complex nuclear sites. BWX Technologies occupies a specialized position in nuclear components and fuel manufacturing for both new builds and operating fleet support.
| Leading Market Players |
|---|
| Rosatom State Nuclear Energy Corporation |
| Westinghouse Electric Company LLC |
| GE-Hitachi Nuclear Energy Inc. |
| Mitsubishi Heavy Industries Ltd |
| Electricite de France SA |
| Framatome |
| AECOM |
| Bechtel |
| BWX Technologies |
| Others |
Value Network & Pricing Analysis
Sovereign-backed utilities and federally guaranteed project finance structures dominate North American nuclear reactor construction, concentrating procurement leverage among a handful of state-supported buyers while compressing margins for private EPC contractors competing on fixed-price delivery.
Pricing Analysis
Warranty and long-term service bundling separates reactor vendor proposals, with Westinghouse and GE-Hitachi competing on guaranteed fuel supply and outage management against unbundled equipment-only bids from component specialists. Project-based lump-sum contracting dominates greenfield construction, while refurbishment segments favor cost-plus structures with shared risk pools. Price differentiation rests on ASME Section III certification grade and domestic content ratios mandated by IRA domestic manufacturing bonuses. Cost compression in EPC margins is intensifying because utilities consolidate multi-unit procurement to extract volume concessions. Municipal utilities and rural electric cooperatives exhibit highest price sensitivity; investor-owned utilities in regulated southeastern states demonstrate lowest sensitivity due to rate-base recovery mechanisms.
Supply Chain Analysis
Domestic content rules under the Inflation Reduction Act and Buy American provisions are reshaping sourcing patterns, pressuring EPCs to qualify North American fabricators for pressure vessel and steam generator components previously imported from Japan and France. Heavy forging capacity concentrates in Japan, France, and South Korea; specialized welding consumables and reactor-grade zirconium alloys draw from limited qualified supplier pools. Single-source vulnerability in steel reactor pressure vessels exceeding 15 inches wall thickness creates critical path risk for announced construction schedules. Distribution runs through prime contractor-led consortia with tiered subcontractor networks for mechanical, electrical, and civil scope packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American nuclear reactor construction has become a vertical-integration race, with reactor vendors acquiring fuel fabrication capabilities and EPCs bringing heavy forging relationships in-house to secure capacity against competing project pipelines.
For Market Incumbents: Anticipate SMR certification races by pre-positioning engineering resources at the NRC and CNSC for concurrent design reviews, while locking multi-year heavy forging commitments before competitor utilities consolidate procurement. Defend against emerging technology disruption from sodium-cooled and high-temperature gas designs by accelerating AP1000 construction timelines to capture rate-base approvals ahead of advanced reactor commercialization. For New Entrants and Emerging Players: Begin with specialized component fabrication for refurbishment segments, where shorter qualification cycles and lower regulatory barriers enable revenue generation ahead of greenfield certification. Ontario's Bruce Power and OPG refurbishment pipelines offer the most penetrable near-term contract visibility, with entry through ASME Section III welding qualifications and steam generator tube supply agreements rather than full-scope reactor delivery. For Investors and Strategic Acquirers: NRC Part 52 design certification completion for SMR platforms is the leading indicator that commercial deployment capital will flow, signaling the transition from technology development to executable project finance. Target acquisition profiles should emphasize heavy forging and specialized welding contractors with existing ASME certifications, as capability scarcity in these segments will intensify across the analysis window. Long-term viability favors vertically integrated positions spanning design IP, component manufacturing, and construction execution.| Strategic Initiative | Industry Significance |
|---|---|
| SMR Design Certification | NRC Part 52 approval unlocks project finance for NuScale and Ontario Power Generation deployment pipelines. |
| Heavy Forging Capacity Lock | Multi-year vessel supply agreements with Japan Steel Works secure critical path components for TVA and Duke Energy projects. |
| Domestic Content Qualification | IRA manufacturing bonuses reward EPCs qualifying U.S. and Canadian fabricators for pressure vessel production. |
| Refurbishment Contract Capture | Bruce Power and OPG life extension programs offer near-term revenue absent greenfield permitting risk. |
| Dual-Certification Pathway | Concurrent CNSC and NRC vendor design reviews accelerate cross-border deployment for utilities with assets in both jurisdictions. |
Research Methodology
Document review covered NRC licensing dockets, CNSC vendor design review records, and utility integrated resource plans, complemented by interviews with utility planning officers, EPC project directors, nuclear component procurement leads, and regulatory affairs specialists at the NRC and CNSC. Secondary validation drew from EIA power plant databases, FERC filings, IEA nuclear development reports, and project finance tracking databases. Bottom-up project pipeline aggregation was cross-checked against top-down utility capital expenditure forecasts to establish analytical consistency.
Market size and growth projections were developed through multi-dimensional segmentation modeling across reactor technology type, project category, contractor delivery structure, and regulatory framework, with value outputs calibrated against announced contract values and historical construction cost benchmarks. CAGRs were derived from regression analysis of capital deployment timelines and capacity addition schedules. Key forecast inputs included NRC staffing capacity for design certification reviews, heavy forging order backlogs at qualified suppliers, and state-level clean energy mandate compliance trajectories.
Underlying measurement precision varies by segment; refurbishment pipelines with executed contracts carry tighter precision than greenfield projects contingent on pending license approvals. Forecasts reflect assumptions regarding regulatory review durations, commodity price stability for steel and specialty alloys, and sustained federal loan guarantee program authorization. Supply chain disruption, seismic qualification delays for western U.S. sites, or natural gas price collapse could materially revise deployment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Power Pump Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
Nuclear Decommissioning Services Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Global Power Plant Uranium Market