
 North America Pulses Market | 2026-2036
North America Pulses Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pulses Market Intelligence
Food manufacturers is rotating toward pulse proteins as a core ingredient class, displacing traditional soy and wheat gluten in clean-label formulations. AGT Food and Ingredients leverages its vertical integration from farm to fractionation to secure supply security for North American buyers. Cargill, Inc. competes through its extensive origination network across the northern Plains and Prairie provinces. The Scoular Company specializes in identity-preserved handling and traceability systems that premium buyers require.
Pulses comprise the dried, edible seeds of leguminous crops—lentils, chickpeas, peas, and beans—typically containing 20-30% protein by dry weight, with starch and fiber constituting the remaining mass fraction. These crops fix atmospheric nitrogen through rhizobial symbiosis, reducing synthetic fertilizer dependency in rotational cropping systems. Peas currently lead volume throughput due to their functional protein isolate applications, while chickpeas command premium positioning in the nutraceuticals segment where protein digestibility scores drive formulation decisions. Bulk packaging dominates farm-gate and processor-to-processor flows, though pouches are gaining share in direct-to-consumer channels.
USDA grading standards and the FDA's Food Safety Modernization Act govern handling protocols and traceability requirements across the North American supply chain. Canada's Canadian Grain Commission establishes protein content and admixture tolerances that directly determine export eligibility and price premiums. Stakeholders must monitor evolving EPA biofuel policy intersections with pulse starch diversion, as renewable diesel feedstock competition could reshape domestic availability.
Market Dynamics
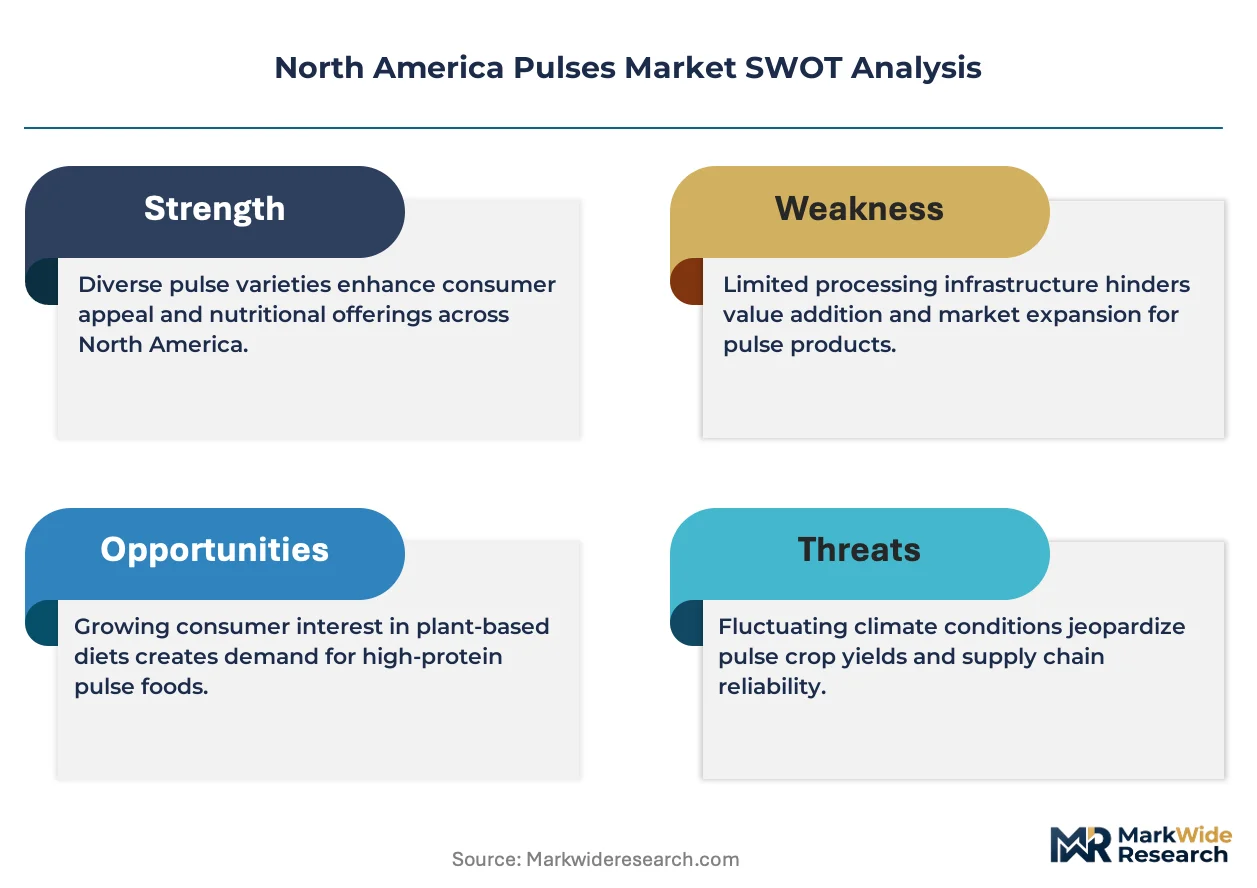
Plant-based protein substitution is compressing traditional commodity margins while fractionation technology upgrades concentrate value capture among processors with captive pea and lentil isolate capacity.
Growth Catalysts
- USDA Dietary Guidelines:Federal nutrition policy now explicitly recommends pulse consumption twice weekly, creating institutional procurement mandates across K-12 cafeterias and military commissaries.
- Renewable diesel feedstock competition:EPA biofuel policy is diverting pulse starch toward fuel applications, tightening domestic food-grade supply and elevating price premiums for identity-preserved varieties.
- Clean-label formulation:Food manufacturers are reformulating meat analogues and bakery applications around pulse proteins to displace soy and wheat gluten in allergen-sensitive product lines.
Market Restraints
- Input cost volatility:Synthetic fertilizer price swings directly affect rotational economics for pulse growers, compressing planted acreage during nitrogen cost spikes.
- Supply concentration risk:Northern Plains states and Prairie provinces host over 80% of North American lentil and dry pea production, exposing buyers to single-region weather events.
- Technical limitation:Pulse protein isolates retain beany off-flavors that limit inclusion rates in neutral-tasting applications without expensive masking systems.
Strategic Opportunities
- Underpenetrated geography:Southeastern United States lacks regional pulse processing infrastructure, creating first-mover advantages for fractionation facilities near Atlanta or Charlotte logistics hubs.
- Regulatory tailwind:Canadian Grain Commission protein premiums incentivize growers to adopt enhanced grading protocols, opening export channels into Asian nutraceutical markets.
- Technology convergence:Precision fermentation paired with pulse protein hydrolysates is enabling novel texturizing agents that replicate animal muscle fiber structures.
Industry Challenges
- Skill gap in fractionation engineering:Commercial-scale protein isolate production requires specialized expertise in membrane filtration and spray-drying that remains scarce outside legacy soy processing regions.
- Capex intensity for identity-preserved handling:Segregated storage, cleaning, and traceability systems demand capital outlays that mid-tier elevators cannot finance without cooperative structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pulses Market |
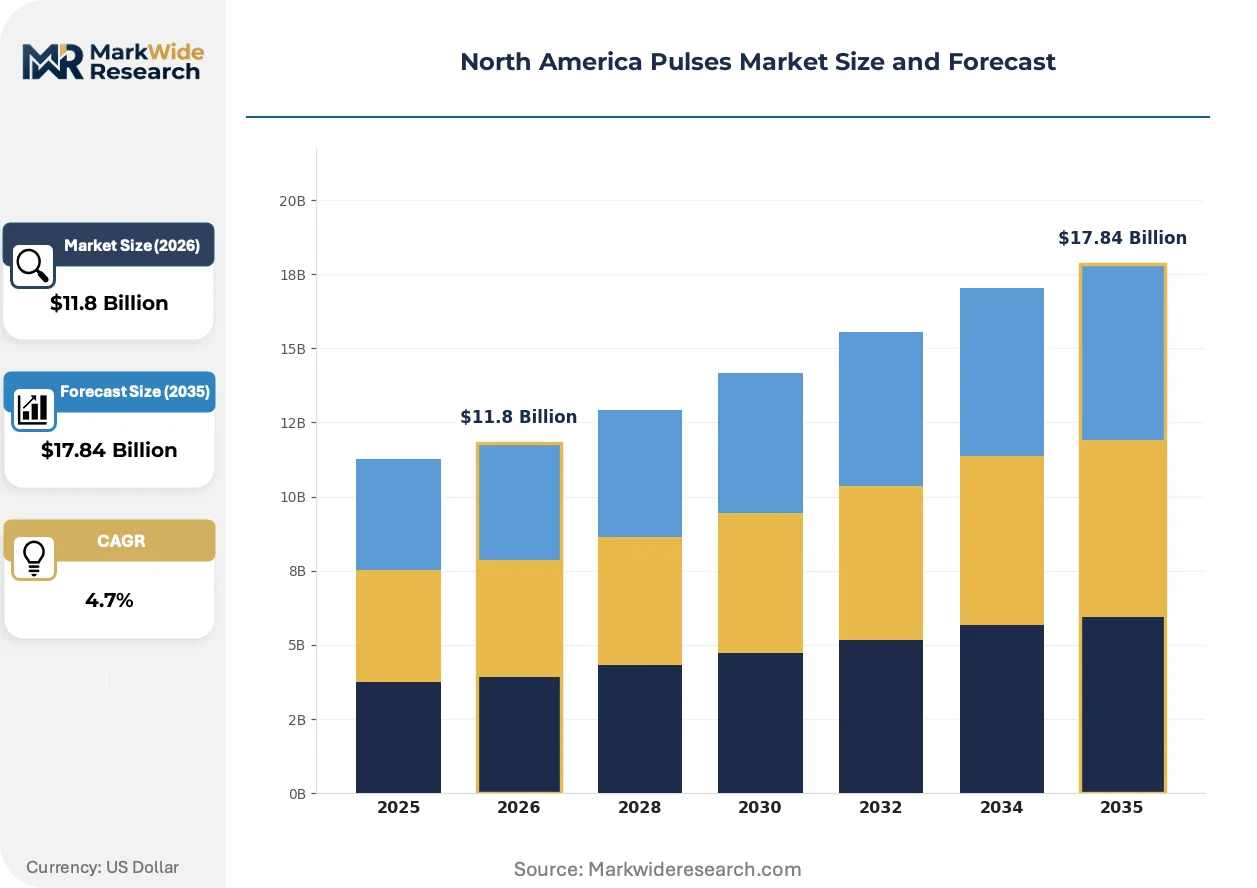
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.84 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lentils, Chickpeas, Peas, Beans End User: Food Industry, Animal Feed, Snacks, Nutraceuticals Packaging Type: Bags, Cans, Pouches, Bulk Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | AGT Food and Ingredients, CanMar Grain Products, Ingredion Incorporated, Roquette Frères, Great Western Grain, Cargill, Inc., The Scoular Company, BroadGrain Commodities Inc., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pulses Market Strategic Shifts & Innovations
Downstream ingredient customization is overtaking commodity trading as the primary value-creation mechanism, with processors investing in application-specific functionality rather than bulk volume throughput.
Dry fractionation technology is miniaturizing. Mobile processing units now deploy directly to farm clusters in Montana and Saskatchewan, reducing transportation costs for high-moisture green peas. Small-scale equipment manufacturers are leasing these systems to producer cooperatives under output-sharing agreements. This distributed model is compressing the historical advantage of centralized mega-facilities.
Canada's Canadian Grain Commission revised protein measurement protocols in 2023, tightening tolerances for export-grade lentils. This regulatory shift forces domestic elevators to upgrade near-infrared spectroscopy equipment. Premium buyers in Japan and South Korea now require third-party verification against the new standards, reshaping procurement contracts across Prairie province aggregators.
Food service distributors are consolidating pulse ingredient specifications into master purchasing agreements. Large contract manufacturers now dictate functional protein content, particle size distribution, and water-holding capacity rather than accepting standard commodity grades. This specification-driven procurement is most visible in California and Texas, where plant-based meat startups cluster near co-packing infrastructure.
North America Pulses Market Segmentation
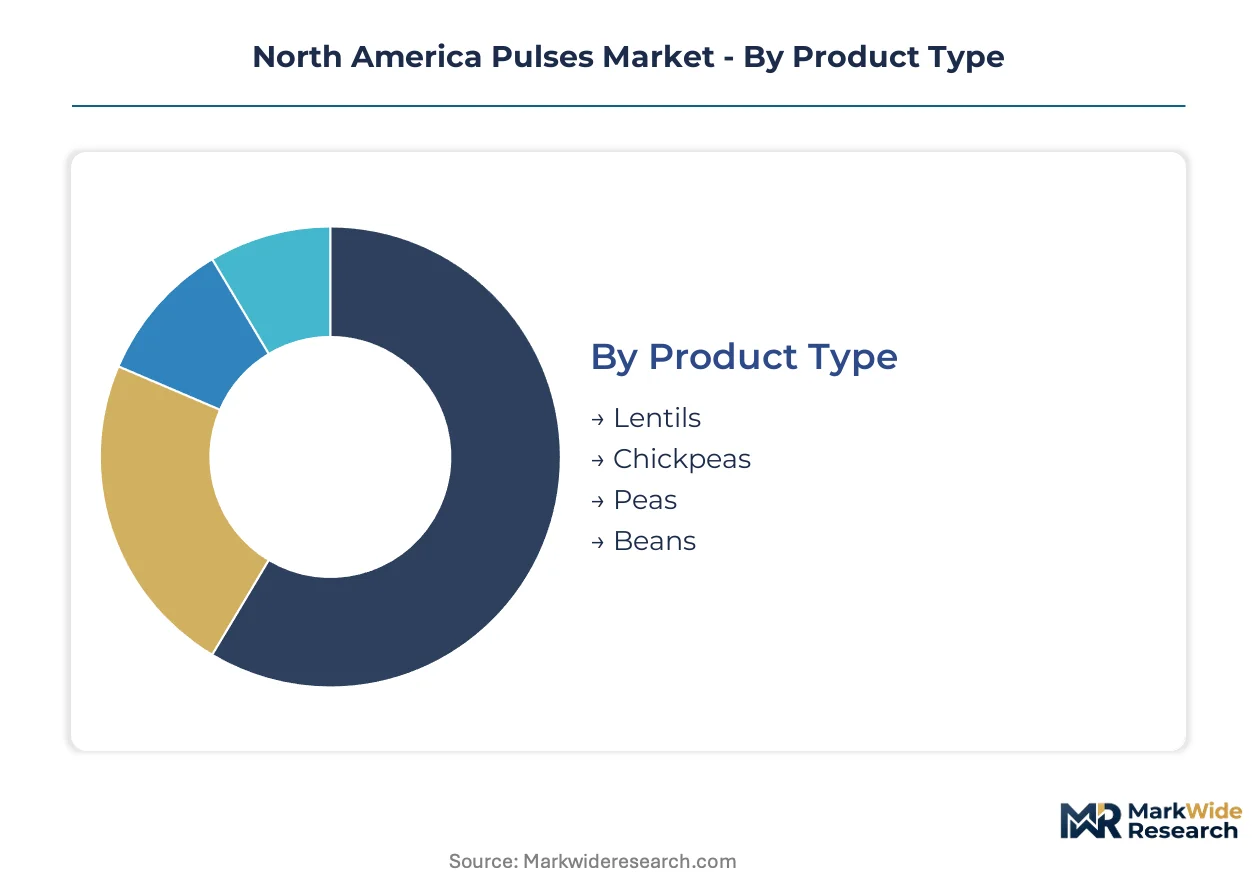
Pulse processors capture value through differential positioning across product grades, end-use specifications, and channel structures. Segmentation reveals where identity-preserved premiums concentrate versus commodity throughput economics.
Product Type:
Margin pools concentrate in protein isolate feedstocks where functional specifications command premiums over commodity grain flows.
- Peas:Yellow and green pea varieties contain 23-25% protein with favorable amino acid profiles for fractionation. Food manufacturers in California and Texas plant-based meat clusters specify pea protein isolate for meat analogues requiring neutral flavor and high water-binding capacity. EPA biofuel policy diverts pea starch toward renewable diesel, tightening food-grade supply.
- Lentils:Red and green lentil segments split between food-grade exports to South Asian diaspora markets and dehulled split processing for North American retail. Canadian Grain Commission protein premiums now require upgraded near-infrared spectroscopy at Prairie elevators serving Japanese and South Korean nutraceutical buyers.
- Chickpeas:Kabuli varieties dominate premium positioning for protein concentrate applications.
- Beans:Navy, black, and pinto varieties serve traditional canned goods and emerging bean flour applications.
The dominant share belongs to peas, while chickpeas are closing the gap fastest through nutraceutical protein concentrate demand.
End User:
Application-driven procurement now dictates functional specifications rather than accepting standard commodity grades.
- Food Industry:Meat analogue manufacturers specify protein content, particle size distribution, and water-holding capacity in master purchasing agreements. Clean-label reformulation is displacing soy and wheat gluten in allergen-sensitive bakery and pasta applications. USDA dietary guidelines mandating twice-weekly pulse consumption drive institutional procurement across K-12 cafeterias and military commissaries.
- Nutraceuticals:Protein digestibility-corrected amino acid scores determine formulation decisions for sports nutrition and senior nutrition products. Canadian protein premiums open export channels into Asian markets with third-party verification requirements.
- Animal Feed:Pulse byproducts from fractionation supply pet food protein fortification.
- Snacks:Roasted and extruded pulse snacks target direct-to-consumer channels with pouched packaging.
Food Industry holds the largest volume position, though Nutraceuticals is expanding most quickly on protein premium capture.
Packaging Type:
Cost tier separation runs from farm-gate bulk through premium unit-dose formats.
- Bulk:Farm-gate and processor-to-processor flows move via railcar and truckload with identity-preserved segregation. Northern Plains elevators invest in segregated storage and cleaning systems for premium varieties. Capital intensity for traceability infrastructure excludes mid-tier handlers without cooperative financing structures.
- Pouches:Direct-to-consumer channels gain share with resealable formats targeting plant-based protein convenience positioning. Small-scale mobile processing units in Montana and Saskatchewan reduce transportation costs for high-moisture green peas through distributed farm-cluster deployment.
- Bags:Multi-wall paper and woven polypropylene serve traditional retail and food service.
- Cans:Canned bean formats retain shelf-stable positioning in conventional grocery.
Bulk commands the volume base, while pouches are gaining share fastest in e-commerce and specialty retail.
Distribution Channel:
Channel selection determines margin capture versus volume throughput tradeoffs.
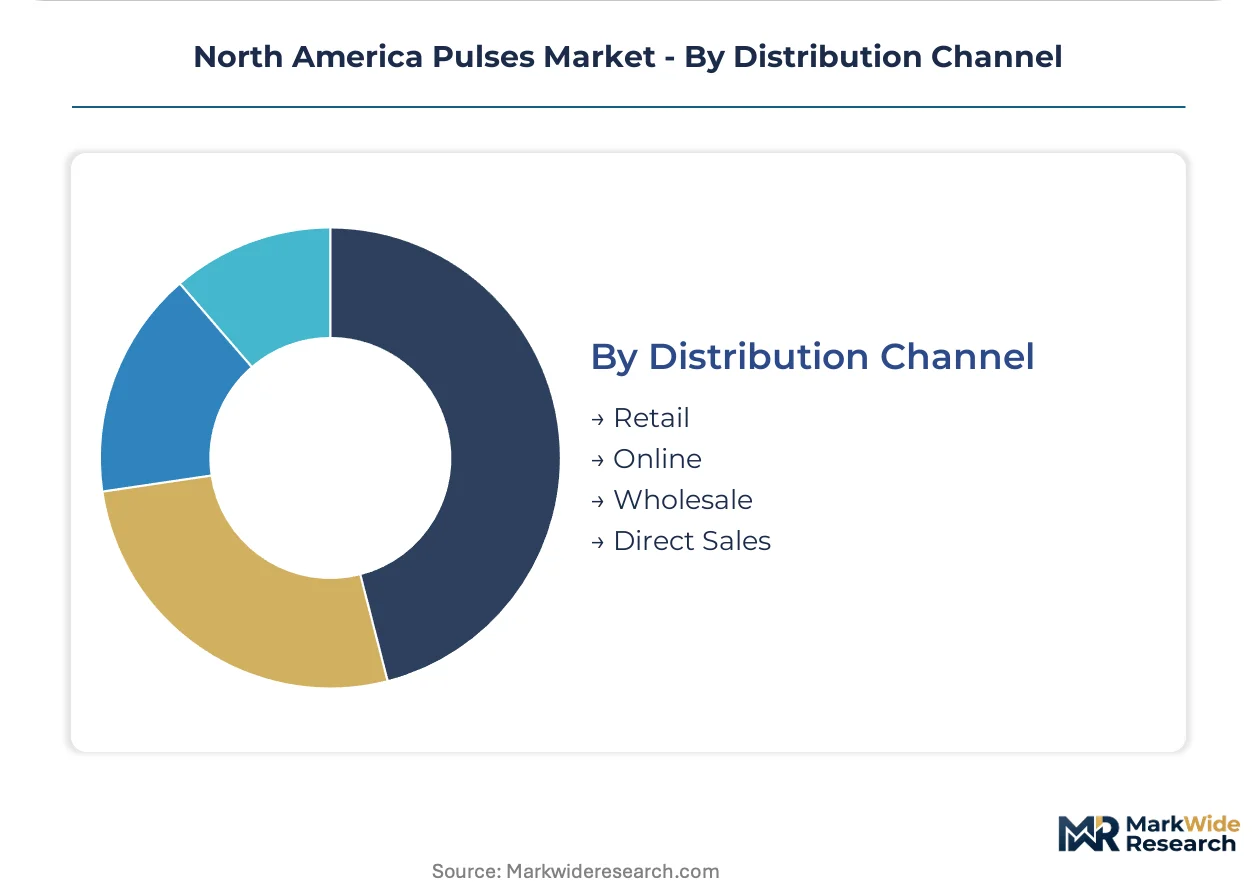
- Wholesale:Food service distributors consolidate pulse ingredient specifications into master purchasing agreements with contract manufacturers. Large buyers now dictate functional parameters rather than accepting standard grades. This specification-driven procurement concentrates in California and Texas plant-based meat startup clusters near co-packing infrastructure.
- Direct Sales:Identity-preserved handling with full traceability from farm to fractionator secures supply security for premium buyers. AGT Food and Ingredients leverages farm-to-fractionation control for North American buyer relationships.
- Retail:Conventional grocery and natural specialty channels carry packaged dry pulses and value-added ingredients.
- Online:Direct-to-consumer growth supports specialty and subscription formats.
Wholesale maintains the dominant position, with Direct Sales climbing fastest on traceability premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over 80% of North American lentil and dry pea production clusters in the northern Plains states and Prairie provinces. This geographic concentration exposes buyers to single-region weather events while creating infrastructure advantages for fractionation facilities. The analysis examines production and processing dynamics across the three North American countries.
United States
Plant-based meat manufacturers in California and Texas specify pea protein isolate for meat analogues requiring neutral flavor profiles. USDA dietary guidelines mandating twice-weekly pulse consumption drive institutional procurement across K-12 cafeterias and military commissaries. Northern Plains states host expanded lentil and pea production clusters with growing fractionation capacity.
Canada
Canadian Grain Commission protein premiums incentivize growers to adopt enhanced grading protocols for export eligibility. The 2023 revision to protein measurement protocols forces Prairie elevators to upgrade near-infrared spectroscopy equipment. Saskatchewan and Manitoba farm clusters supply Japanese and South Korean nutraceutical buyers requiring third-party verification.
Mexico
Traditional bean consumption patterns support domestic processing infrastructure for navy, black, and pinto varieties. The country's national agricultural regulator establishes quality standards for cross-border trade with US food manufacturers. Northern border states concentrate drying and cleaning facilities serving Texas and California plant-based protein clusters.
North America Pulses Market Key Industry Players
Concentration sits with vertically integrated processors and diversified agricultural conglomerates. The market structure tiers between global trading houses with origination networks and specialized fractionators with captive isolate capacity. Strategic archetypes include farm-to-fractionation integrators, identity-preserved handlers, and commodity-scale traders. Dominant competitive moves encompass backward integration into farm-gate origination and capacity expansion in protein isolate production.
Among vertically integrated processors, AGT Food and Ingredients exemplifies farm-to-fractionation control, while Cargill, Inc. occupies a position as a diversified agricultural conglomerate with extensive origination networks. The Scoular Company represents the identity-preserved handling archetype with specialized traceability systems for premium buyers.
| Leading Market Players |
|---|
| AGT Food and Ingredients |
| CanMar Grain Products |
| Ingredion Incorporated |
| Roquette Frères |
| Great Western Grain |
| Cargill, Inc. |
| The Scoular Company |
| BroadGrain Commodities Inc. |
| Archer Daniels Midland Company |
| Others |
Cost & Logistics Intelligence
Canadian Grain Commission protein measurement protocols gate both export eligibility and price tier placement for Prairie province elevators serving Asian nutraceutical buyers. USDA grading standards and FDA food labeling requirements create parallel qualification thresholds that segment domestic supply into identity-preserved premiums versus commodity throughput pools.
Pricing Analysis
USDA dietary guidelines mandating twice-weekly pulse consumption dictate the pricing tier structure across institutional procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates identity-preserved varieties with full traceability from commodity grades and feed-quality diversion streams. Pricing pressure stems from EPA biofuel policy diverting pea starch toward renewable diesel applications, tightening food-grade supply. K-12 cafeteria procurement managers demonstrate highest price sensitivity, while Japanese and South Korean nutraceutical buyers absorb premiums for verified protein content.
Supply Chain Analysis
Strait of Hormuz transit risk parallels the chokepoint concentration across northern Plains states and Prairie provinces, where over 80% of North American lentil and dry pea production clusters within a single weather-vulnerable corridor. Rhizobial inoculant supplies and nitrogen fertilizer inputs rest on agricultural chemical distribution networks anchored in the Mississippi River corridor. Single-region weather exposure constitutes the dominant structural risk. Distribution runs through railcar and truckload flows from farm-gate elevators to fractionation facilities, with mobile processing units now deploying directly to Montana and Saskatchewan farm clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based protein substitution is accelerating market disruption as precision fermentation technology converges with pulse protein hydrolysates to enable novel texturizing applications. USDA institutional procurement mandates and Canadian export protocol revisions create regulatory tailwinds for qualified suppliers.
For Market Incumbents: Shield fractionation margins by securing captive pea and lentil isolate capacity before renewable diesel feedstock competition intensifies. Invest in membrane filtration engineering talent pools concentrated in legacy soy processing regions. Expand identity-preserved handling infrastructure across northern Plains elevator networks to capture Canadian Grain Commission protein premiums. For New Entrants and Emerging Players: Canadian Grain Commission third-party verification fast-tracks entry into Japanese and South Korean nutraceutical export channels with premium pricing. Target southeastern United States fractionation infrastructure gaps near Atlanta or Charlotte logistics hubs. Deploy mobile dry fractionation units under output-sharing agreements with Montana and Saskatchewan producer cooperatives. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across protein isolate production as membrane filtration and spray-drying equipment costs escalate. Five-to-ten-year viability favors processors with demonstrated farm-to-fractionation control and established Asian export verification relationships. Monitor EPA biofuel policy rulings as the critical inflection signal for domestic food-grade supply availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Gate Origination | AGT Food and Ingredients leverages upstream control to secure supply security for North American buyers. |
| Protein Isolate Capacity Expansion | Fractionation technology upgrades concentrate value capture among processors with captive pea isolate production. |
| Identity-Preserved Handling Infrastructure | The Scoular Company's traceability systems meet premium buyer requirements for segregated storage and cleaning. |
| Mobile Processing Unit Deployment | Distributed farm-cluster models in Montana and Saskatchewan compress transportation costs for high-moisture green peas. |
| Asian Export Certification Investment | Prairie province elevators upgrade near-infrared spectroscopy to access Japanese and South Korean nutraceutical markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with pulse processors, food manufacturer procurement leads, agricultural cooperative managers, and fractionation engineering specialists. Secondary validation drew from USDA crop production reports, Canadian Grain Commission grading bulletins, FDA food labeling guidance documents, and EPA biofuel policy filings. Bottom-up volume modeling triangulated against top-down value estimates across product type, end-use application, and distribution channel dimensions.
Across the analysis window, forecasts reflect segmented growth trajectories for peas, lentils, chickpeas, and beans by protein isolate, concentrate, and commodity grain applications. CAGRs were derived from historical production trends, planted acreage elasticity to input costs, and fractionation capacity expansion pipelines. Modeling incorporated EPA renewable diesel feedstock diversion scenarios and Canadian export protocol revision impacts on premium grade availability.
The analysis sits within stated boundaries; outcomes outside sustained plant-based meat formulation demand or stable biofuel policy regimes would require recalibration. Practitioners should keep alternative scenarios live as EPA ruling timelines and precision fermentation cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Organic Cereals Market
Grains
Spelt Wheat Market
Grains
Whole-Wheat Flour Market
Grains
Organic Rice Flour Market
Grains
Africa Wheat Flour Market
Grains
United States Rice Market
Grains
Cultured Wheat Market
Grains
Sorghum Market
Grains
Heritage Grain Market
Grains
Oat Bran Market
Grains
Global Cassava Flour Market
Grains
Grain and Cereal Crop Market
Grains
Green Banana Flour Market
Grains
Grain Silos and Storage System Market
Grains
Wheat Bran Market
Grains
North America Wheat Protein Market