
 North America Peas Market | 2026-2036
North America Peas Market Size, Share, and Industry Trends Forecast 2026-2036
North America Peas Market Analytics
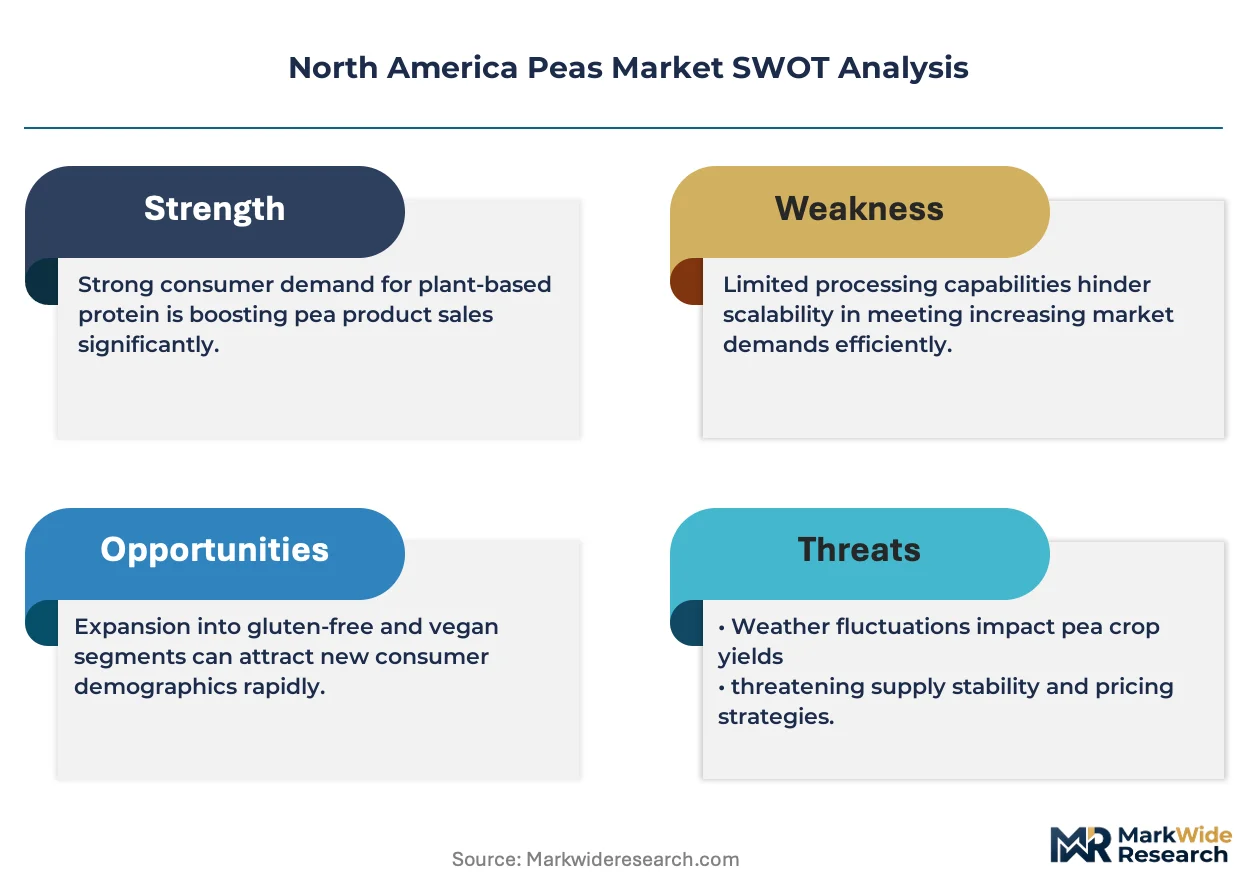
The North America peas market is consolidating around a widening gap between premium protein isolate tiers and commodity whole-pea trading. Roquette Frères leverages its Canadian processing footprint to anchor supply security for food-grade isolates. Puris competes through domestic U.S. sourcing networks that sustain shorter lead times to plant-based meat manufacturers. AGT Food and Ingredients dominates bulk export channels while extending its origination reach across Saskatchewan and North Dakota growing belts.
Peas are leguminous seeds of Pisum sativum containing approximately 20-25% protein by dry weight, with yellow peas typically yielding higher starch content and more neutral flavor profiles suited to extraction and texturization. The crop serves as a rotational nitrogen-fixing alternative to cereal monocultures while supplying protein, starch, and fiber fractions to food and feed formulators. Yellow peas lead volume throughput across Prairie processing facilities, while the food industry end-use segment captures the deepest margin pools through fractionation into isolates and concentrates. Online retail and foodservice distribution channels are expanding fastest as direct-to-ingredient-buyer platforms and specialized plant-based supply chains mature.
The U.S. FDA oversees pea protein GRAS determinations and labeling standards, while USDA administers crop insurance and conservation programs that influence planting decisions across the Northern Plains. Canada's CFIA enforces seed purity and varietal registration rules that shape which pea cultivars enter commercial production. Protein Industries Canada coordinates domestic fractionation R&D investments that redirect prairie-grown pulses toward higher-value food ingredients. Stakeholders must monitor how evolving FDA guidance on plant protein nutrient content claims and potential U.S.-Canada trade friction around pulse tariffs reshape margin allocation between growers, processors, and branded food customers.
Market Dynamics
Plant-based protein extraction technology is compressing the cost gap between pea isolates and commodity soy concentrates, forcing Prairie processors to upgrade fractionation capacity or retreat to bulk export channels.
Growth Catalysts
- Canada's Protein Industries Supercluster:Federal R&D coordination redirects Saskatchewan-grown yellow peas toward food-grade isolate production, displacing lower-margin feed channels.
- FDA GRAS pathway streamlining:Novel plant protein guidance accelerates ingredient approval timelines for U.S.-based meat alternative formulators seeking domestic sourcing.
- Midwest processing cluster density:North Dakota and Manitoba milling corridors concentrate dehulling and air-classification assets within 200 miles of primary growing belts.
Market Restraints
- Natural gas input cost volatility:Prairie fractionation facilities depend on thermal drying; Alberta and Saskatchewan gas price spikes compress processor margins during winter contracting windows.
- Single-region supply concentration:Over 70% of North American yellow pea origination flows through Saskatchewan-registered elevators, creating weather-correlated volume risk.
- Flavor masking technical limitations:Pea protein's residual grassy and beany off-notes require expensive enzymatic or fermentation interventions that soy isolates avoid.
Strategic Opportunities
- Pacific Northwest ingredient manufacturing:Underdeveloped fractionation infrastructure in Oregon and Washington offers first-mover positioning for coastal plant-based seafood formulators.
- Pet food protein fortification:Premium companion animal nutrition brands are adopting pulse concentrates as novel protein sources beyond traditional chicken and fish meals.
- USDA Climate-Smart Commodities initiative:Conservation program payments incentivize cover-crop pea rotations that qualify processors for carbon-intensity scoring advantages in biofuel-adjacent markets.
Industry Challenges
- Food-grade certification timelines:BRC and SQF audits for Prairie greenfield fractionation plants average 14-18 months, delaying commercial offtake agreements with multinational CPG buyers.
- Legacy ERP integration friction:Seed-to-protein traceability requirements from CFIA and major retailers force mid-scale processors to replace commodity grain accounting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Peas Market |
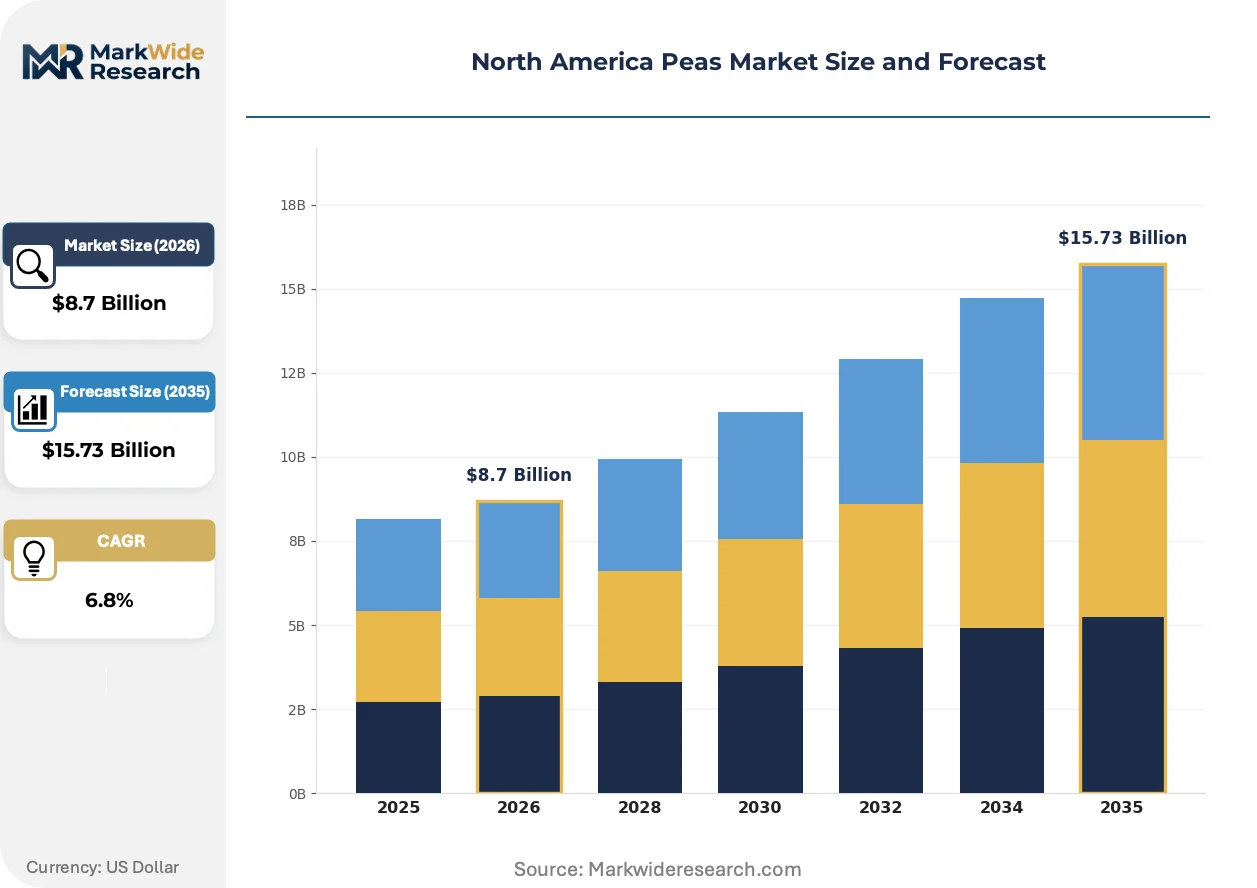
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Peas, Split Peas, Green Peas, Yellow Peas End Use: Food Industry, Animal Feed, Snacks, Flour Production Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Foodservice Processing Method: Frozen, Canned, Dehydrated, Fresh |
| Companies Covered | Roquette Frères, Ingredion, AGT Food and Ingredients, Puris, Cargill, Archer Daniels Midland Company, The Scoular Company, Burcon NutraScience Corporation, Emsland Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Peas Market Evolving Landscape
Extrusion and fermentation technologies are converging to transform pea protein from a commodity ingredient into a functional texturizing platform that mimics muscle fiber structures.
Dry-fractionation coupled with enzymatic hydrolysis is modularizing protein concentration workflows across Prairie processing facilities. Plant-based meat manufacturers in Minneapolis and Toronto are adopting these hybrid systems to reduce water usage by half versus wet-extraction alternatives. The technology is modularizing capital deployment decisions, allowing processors to stage capacity expansion in 5,000-ton increments rather than committing to integrated wet mills.
The U.S. FDA's draft guidance on plant protein nutrient content claims is tightening amino acid scoring requirements for "complete protein" labeling. Formulators must now document lysine and methionine ratios through third-party testing, adding $15,000-$25,000 per SKU in analytical costs. Sports nutrition and infant formula segments are responding by sourcing specifically from high-lysine pea cultivars registered with Canada's CFIA varietal purity system.
Direct-to-ingredient-buyer platforms are compressing traditional elevator-processor-brand procurement hierarchies. Specialized pulse brokers in Fargo and Saskatoon now offer real-time protein content and moisture data via blockchain-verified certificates, displacing long-term fixed-price contracts. This pattern is most visible in the plant-based dairy vertical, where oat milk and pea milk blenders require lot-level consistency that commodity channels cannot guarantee.
North America Peas Market Segmentation
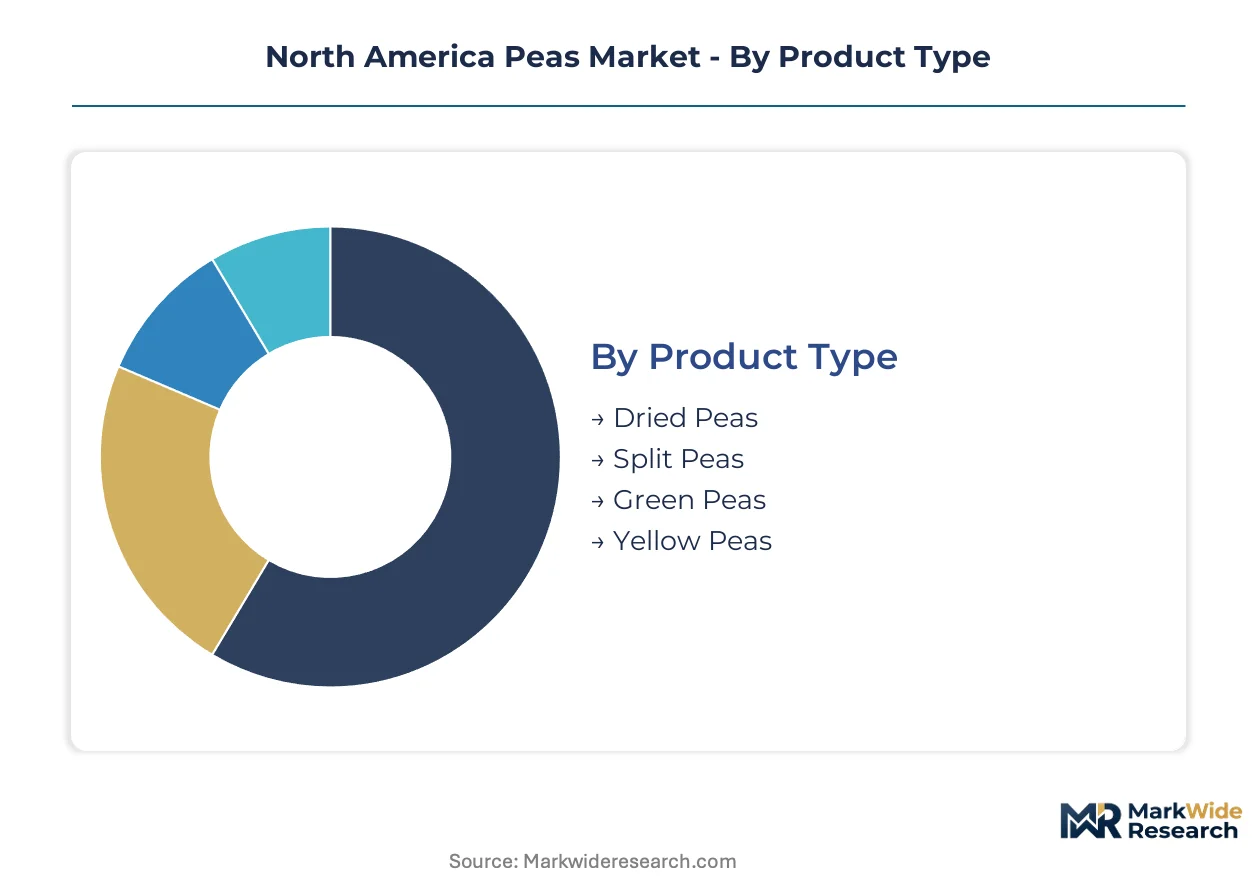
Pea market segmentation reveals divergent margin profiles across product forms and processing intensities. Buyers in Minneapolis and Toronto food manufacturing corridors prioritize protein content consistency over commodity price arbitrage, reshaping procurement patterns across Prairie supply chains.
Product Type:
Buyers select pea varieties based on starch-protein ratios and flavor neutrality for downstream fractionation.
- Yellow Peas:Higher starch content and neutral flavor profiles suit protein isolate extraction and texturization for plant-based meat applications. Prairie processing infrastructure clusters around Saskatchewan-registered yellow pea elevators, with Roquette Frères and AGT Food anchoring dehulling and air-classification capacity within 200 miles of primary growing belts.
- Dried Peas:Whole seed preservation enables extended storage and flexible milling schedules for flour and concentrate production. Bulk export channels through Vancouver and Thunder Bay terminals serve Asian noodle manufacturers seeking consistent hydration properties.
- Split Peas:Dehulled and cotyledon-separated for accelerated cooking in soup and side-dish applications.
- Green Peas:Higher chlorophyll content and sweeter taste profile targets premium frozen vegetable and fresh-pack channels.
Yellow peas lead on scale; green peas lead on momentum in premium fresh-pack channels.
End Use:
Application selection drives ingredient specification tiers from commodity feed to pharmaceutical-grade isolates.
- Food Industry:Protein concentrates, starches, and fibers fractionated for plant-based meat, dairy alternatives, and gluten-free baking. Minneapolis and Toronto formulators demand lot-level protein content consistency that commodity channels cannot guarantee, compressing traditional elevator-processor-brand procurement hierarchies.
- Animal Feed:Pelleted pea protein and starch fractions replace soybean meal in aquaculture and poultry rations. Prairie feed mills blend pea co-products from fractionation facilities to reduce import dependence on South American soy.
- Snacks:Roasted, puffed, and extruded whole pea applications for health-positioned retail positioning.
- Flour Production:Stone-ground and roller-milled pea flour for gluten-free bakery and pasta formulations.
Food industry applications command the steepest expansion trajectory; animal feed maintains volume anchoring.
Distribution Channel:
Channel selection determines traceability depth and contract structure flexibility.
- Online Retail:Direct-to-consumer platforms for specialty organic and heritage pea varieties. Fargo and Saskatoon pulse brokers now offer real-time protein content and moisture data via blockchain-verified certificates, displacing long-term fixed-price contracts for ingredient buyers.
- Wholesale Distributors:Volume aggregation for food manufacturers and institutional foodservice across Midwest and Prairie corridors.
- Supermarkets:Packaged dry peas and frozen green peas for household pantry replenishment cycles.
- Foodservice:Bulk frozen and dehydrated formats for restaurant and institutional kitchen procurement.
Wholesale distributors lead on scale; online retail gains share fastest in ingredient-grade sourcing.
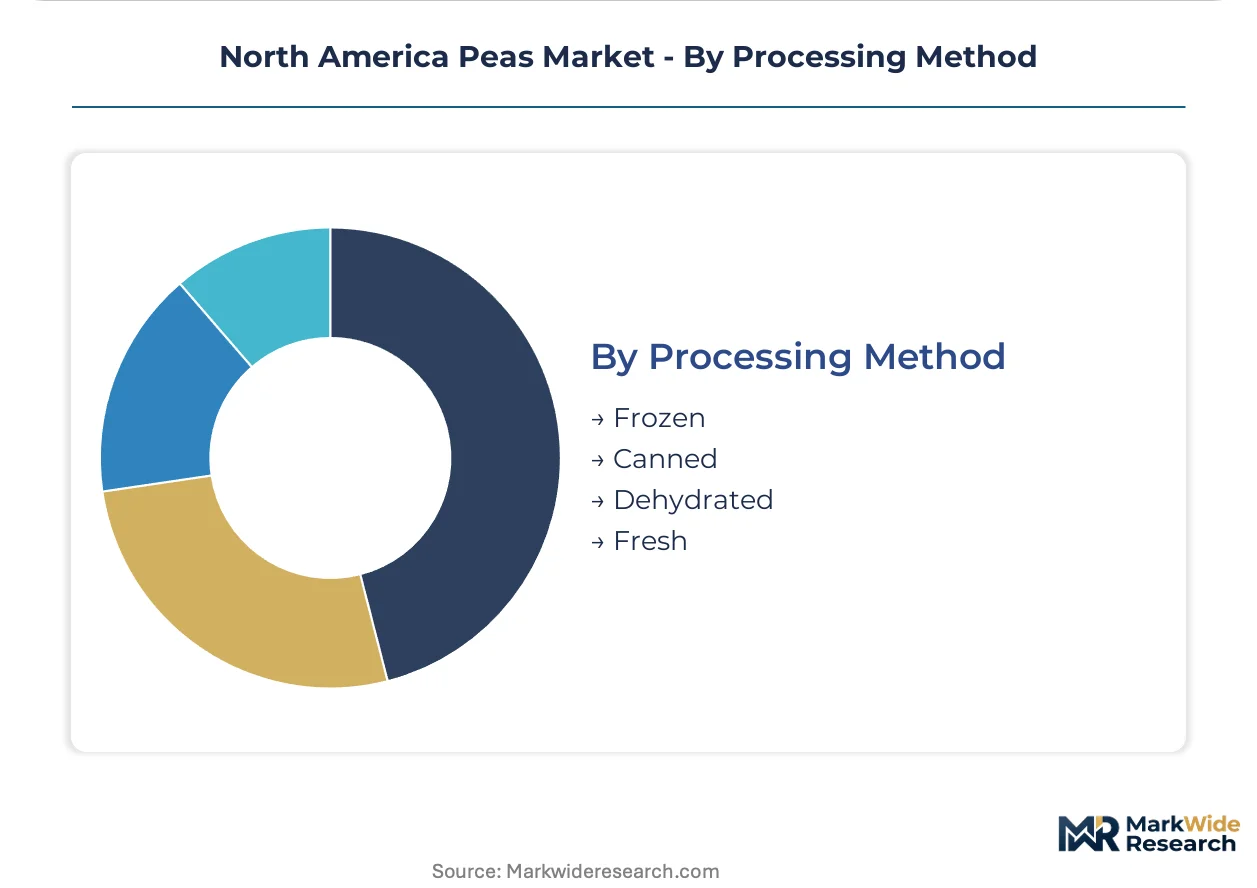
Processing Method:
Preservation technology selection balances shelf stability against nutrient retention and energy inputs.
- Frozen:Rapid blast-freezing of green peas within hours of harvest locks color and vitamin content. Pacific Northwest processing plants in Oregon and Washington offer underdeveloped fractionation infrastructure for coastal plant-based seafood formulators seeking domestic sourcing.
- Dehydrated:Low-moisture whole and split peas for extended ambient storage and international shipping efficiency.
- Canned:Brine-packed green peas for shelf-stable retail and emergency food program distribution.
- Fresh:Limited seasonal availability for farmers' market and premium restaurant channels.
Dehydrated processing leads on scale; frozen applications climb the fastest in ingredient manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing engineers and agronomists cluster across the Prairie provinces and Midwest states, anchoring North America's pea fractionation capacity near primary cultivation zones.
United States
Plant-based meat manufacturers in Minneapolis and Chicago drive food-grade protein isolate demand. The FDA's streamlined GRAS pathway accelerates novel ingredient approvals for domestic formulators. North Dakota's Red River Valley concentrates dehulling assets within 150 miles of primary yellow pea growing belts.
Canada
Saskatchewan-registered elevators handle over 70 percent of North American yellow pea origination. Protein Industries Canada coordinates federal R&D investments that redirect prairie pulses toward higher-value food ingredients. Roquette Frères anchors its North American processing footprint in Manitoba to secure supply security for isolates.
Mexico
Emerging aquaculture feed mills in Sonora and Sinaloa test pea protein concentrates as soybean meal alternatives. The country's national agricultural regulator oversees import phytosanitary standards for pulse ingredients. Guadalajara's food manufacturing corridor attracts pilot fractionation investments targeting Central American export channels.
North America Peas Market Competitive Landscape
Top-tier vendors anchor premium isolate production, while mid-scale processors compete through origination reach and bulk export volume. The market structures around three tiers: multinational ingredient houses with integrated fractionation, regional pulse specialists controlling elevator networks, and emerging domestic sourcing platforms. Dominant competitive moves include Prairie processing capacity expansion and strategic partnerships with plant-based meat formulators seeking shorter lead times.
Among North American specialists, Roquette Frères, Puris, and AGT Food and Ingredients occupy distinct archetype positions. Roquette Frères exemplifies the multinational integrated processor with Canadian footprint anchoring supply security. Puris represents the domestic U.S. sourcing platform competing through proximity to Midwest manufacturers. AGT Food and Ingredients sits within the regional origination specialist tier, dominating bulk export channels while extending elevator control across Saskatchewan and North Dakota growing belts.
| Leading Market Players |
|---|
| Roquette Frères |
| Ingredion |
| AGT Food and Ingredients |
| Puris |
| Cargill |
| Archer Daniels Midland Company |
| The Scoular Company |
| Burcon NutraScience Corporation |
| Emsland Group |
| Others |
Value Network & Pricing Analysis
Natural gas input costs for thermal drying at Prairie fractionation facilities flow directly into contract pricing for protein isolates, with Alberta and Saskatchewan winter price spikes compressing margins across food-grade and feed-grade tiers alike. This energy-cost passthrough creates divergence between processors with long-term pipeline hedges and those exposed to spot market volatility during peak contracting windows.
Pricing Analysis
Commodity spot contracting for whole yellow peas operates alongside long-term offtake agreements for fractionated isolates and concentrates. Price differentiation hinges on protein content certification and CFIA varietal registration status, with food-grade isolates commanding premiums over feed-grade channels. Cost compression in standard-grade concentrates is intensifying because wet-extraction competitors are achieving parity with dry-fractionation economics. Small-scale aquaculture feed mills in Mexico exhibit the highest price sensitivity, while Minneapolis-based plant-based meat manufacturers prioritize lot-level consistency over per-ton arbitrage.
Supply Chain Analysis
Workforce availability constraints in Manitoba and Saskatchewan milling corridors limit expansion velocity for dehulling and air-classification assets. Supply concentrates in the Prairie provinces, with over seventy percent of North American yellow pea origination flowing through Saskatchewan-registered elevators. Raw material dependencies center on nitrogen-fixing crop rotations, seed purity stocks, and natural gas for thermal processing. Single-region weather exposure creates correlated volume risk across the origination belt. Distribution runs through Vancouver and Thunder Bay export terminals for Asian bulk channels, while dedicated rail spurs serve Minneapolis and Toronto food manufacturing corridors directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America peas market reads as a late-cycle quality story, with Minneapolis and Toronto formulators shifting procurement toward high-lysine cultivars and blockchain-verified protein certificates that command premium positioning.
For Market Incumbents: Deepen backward integration into Saskatchewan elevator networks to secure origination control against emerging direct-to-buyer platforms. Expand fractionation capacity in Manitoba within 200 miles of primary growing belts to compress logistics costs. Invest in BRC and SQF certification pipelines to accelerate commercial offtake timelines with multinational CPG buyers. For New Entrants and Emerging Players: Capture the Pacific Northwest white-space opportunity in Oregon and Washington, where coastal plant-based seafood formulators lack domestic fractionation infrastructure. Target pet food protein fortification channels in premium companion animal nutrition, where pulse concentrates displace traditional chicken and fish meals. Deploy direct-to-ingredient-buyer platforms with real-time protein content verification to bypass legacy elevator-processor hierarchies. For Investors and Strategic Acquirers: Roll-up economics work for regional pulse specialists with elevator network control because Saskatchewan-registered origination capacity is consolidating around three to four dominant players. The five-to-ten year viability thesis rests on food-grade isolate demand outrunning Prairie processing capacity expansion. Watch FDA final guidance on plant protein nutrient content claims as the inflection signal for analytical cost pass-through and cultivar specialization premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elevator Networks | Secures origination control against blockchain-verified direct-buyer platforms displacing traditional procurement. |
| FDA GRAS Pathway Investment | Accelerates ingredient approval timelines for domestic U.S. meat alternative formulators seeking shorter lead times. |
| Pacific Northwest Capacity Buildout | Captures coastal plant-based seafood demand currently served by imported isolates with higher carbon intensity. |
| Pet Food Protein Fortification Entry | Opens premium companion animal channels beyond traditional poultry and fish meal protein sources. |
| Climate-Smart Commodity Certification | Qualifies processors for carbon-intensity scoring advantages under USDA conservation program incentives. |
Research Methodology
Multiple input streams — fractionation plant managers, pulse procurement leads at plant-based meat manufacturers, CFIA regulatory affairs specialists, and Prairie elevator operators — were reconciled against secondary validation. Primary interviews covered technical R&D directors at ingredient houses, category buyers at Minneapolis and Toronto food manufacturers, and distribution channel partners across Midwest and Prairie corridors. Secondary sources included USDA crop insurance filings, CFIA varietal registration databases, FDA GRAS determination records, and Protein Industries Canada R&D investment disclosures. Bottom-up volume modeling from processing capacity and origination data was cross-checked against top-down demand aggregation from end-use segments.
Historical price series for yellow pea spot contracts and isolate offtake agreements were cross-referenced against panel input from procurement executives to establish baseline elasticity assumptions. The analytical framework segmented volume and value across product type, end-use application, distribution channel, and processing method, with additional granularity on protein content tiers and certification status. CAGRs were derived from regression against planted acreage trends, fractionation capacity expansion pipelines, and food manufacturer formulation adoption curves. Forecast inputs included natural gas price volatility scenarios and FDA guidance implementation timelines.
Weather-correlated yield shocks, regulatory delays in novel protein approvals, and trade friction around pulse tariffs are the dominant revision risks to modeled outputs. Material deviation in any of these triggers warrants pause and re-evaluation of capacity investment and origination strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Europe Pea Market
Vegetables
Fresh Vegetables Market
Vegetables
North America Sweet Potatoes Market
Vegetables
Dry Onion Market
Vegetables
Saudi Arabia Greenhouse Horticulture Market
Vegetables
Asparagus Market
Vegetables
Fresh Onions and Shallots Market
Vegetables
Butternut Squash Market
Vegetables
Dried Mushroom Market
Vegetables
Garlic Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Global Indoor Plant Market
Vegetables
Acorn Squash Market
Vegetables
Spain Avocado Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Squash Market