
 Whole-Wheat Flour Market | 2026-2036
Whole-Wheat Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Whole-Wheat Flour Market Analytics
USDA Organic certification is unwinding competitive access across the whole-wheat flour value chain, forcing smaller mills to absorb multi-year compliance costs. Ardent Mills leverages vertical integration from regional grain elevators to mill networks, sustaining cost advantages across North American distribution. Cargill anchors global supply through proprietary varietal development programs that control protein content specifications for industrial bakers. Hodgson Mills differentiates via stone-ground heritage positioning, occupying premium shelf space in health food retail channels.
Whole-wheat flour consists of the complete wheat kernel including bran, germ, and endosperm, typically milled to retain fiber content above 10% and protein levels ranging from 11% to 15% depending on hard or soft wheat varietals. Its primary commercial purpose centers on delivering measurable nutritional density to baked goods, pasta, and prepared foods where reformulation demands clean-label fiber enrichment without additive inclusion. Organic whole-wheat commands margin premiums as certification scarcity limits supply expansion, while stone-ground whole-wheat attracts artisan bakery procurement focused on flavor differentiation and minimal processing narratives. Conventional whole-wheat dominates volume throughput in food manufacturing, where cost-sensitive pasta production and snack extrusion applications prioritize standardized extraction rates over provenance claims.
FDA whole-grain labeling standards and USDA National Organic Program rules govern product identity and market access in the United States, while India's FSSAI fortification directives mandate micronutrient enrichment in public distribution channels. These regulatory frameworks elevate compliance costs for cross-border suppliers but simultaneously create protected demand pools for certified domestic producers. Stakeholders must monitor evolving whole-grain definition disputes between FDA and industry petitioners, as revised serving-size thresholds would immediately reformulate product portfolios and reposition competitive advantage across retail and foodservice segments.
Market Dynamics
Stone-ground milling technology is compressing extraction rates across premium whole-wheat segments while India's FSSAI fortification mandates redirect bulk procurement toward micronutrient-enriched supply chains. These dual pressures are fragmenting competitive positioning between artisan heritage mills and industrial fortification specialists.
Growth Catalysts
- FSSAI Fortification Directives:India's mandatory micronutrient enrichment in public distribution channels is locking in institutional demand for fortified whole-wheat flour variants.
- Clean-Label Bakery Reformulation:Industrial bakers are substituting refined flour with whole-wheat alternatives to meet fiber-content claims without additive inclusion.
- Stone-Ground Milling:Heritage milling processes are capturing premium shelf space as health-food retailers prioritize minimal-processing narratives.
Market Restraints
- Protein Content Volatility:Hard wheat varietals face climate-driven yield inconsistency, compressing margin predictability for pasta manufacturers dependent on 13-15% protein specifications.
- Organic Certification Scarcity:USDA National Organic Program compliance timelines stretch 24-36 months, constraining supply expansion for certified whole-wheat flour.
- Refined Flour Substitution:Cost-sensitive snack extrusion operations continue specifying lower-cost refined alternatives where fiber enrichment is not consumer-visible.
Strategic Opportunities
- India Subsidized Distribution Channels:Government procurement integration offers captive volume anchors for mills achieving FSSAI fortification compliance.
- Heritage Grain Varietal Recovery:Regional landrace wheat programs are enabling terroir-based differentiation for artisan bakery supply contracts.
- Direct-to-Bakery Digital Platforms:Specialty mills are bypassing distributor markups through proprietary e-commerce portals targeting independent bakeries.
Industry Challenges
- Milling Technician Shortage:Stone-ground operations require skilled operators capable of adjusting grind parameters for varietal moisture variation, a competency pool that is aging out.
- Legacy Equipment Retrofit Costs:Conventional roller mills face capital-intensive conversion to achieve whole-wheat extraction rates without excessive heat degradation.
- FDA Whole-Grain Definition Uncertainty:Pending serving-size threshold revisions threaten immediate reformulation requirements across retail product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whole-Wheat Flour Market |
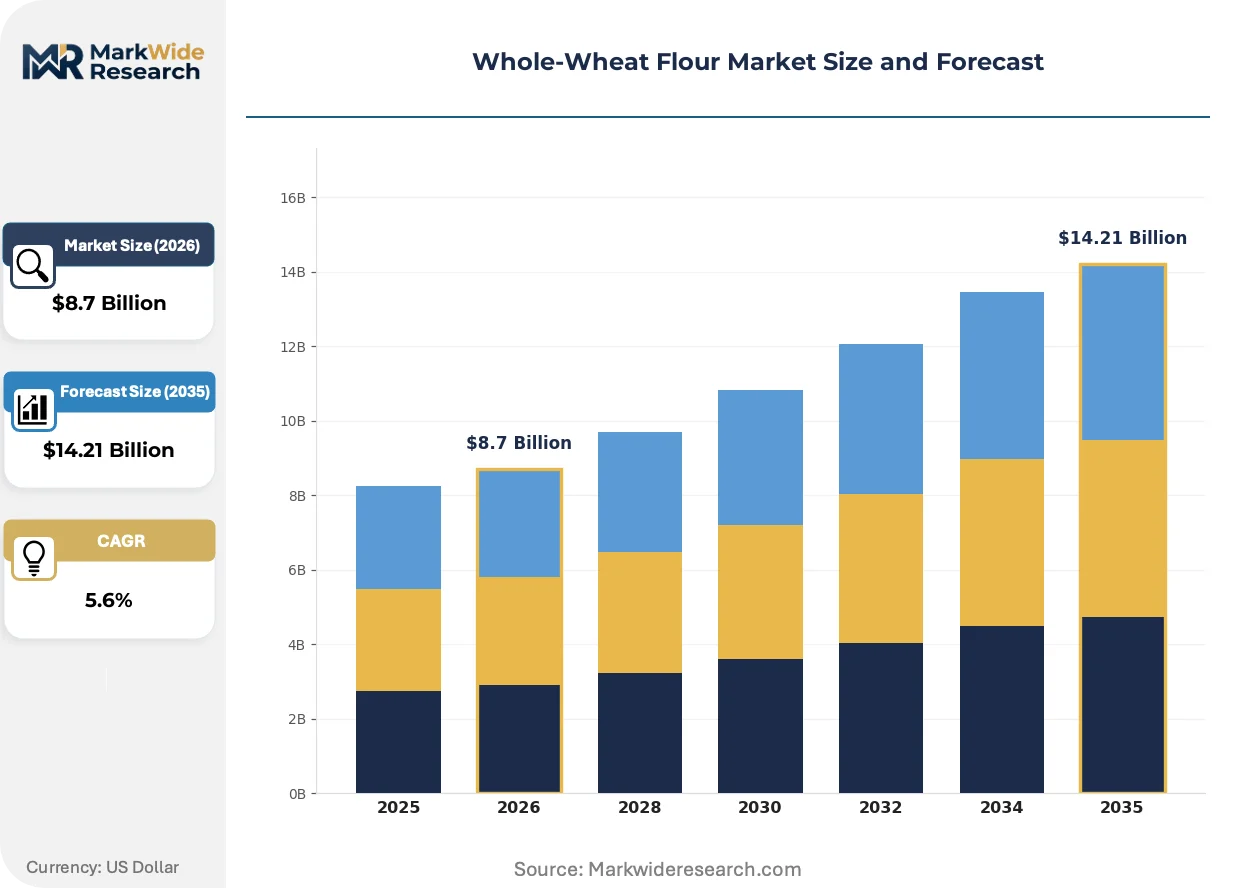
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Whole-Wheat, Conventional Whole-Wheat, Stone-Ground Whole-Wheat, All-Purpose Whole-Wheat Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores End User: Bakers, Food Manufacturers, Home Cooks, Restaurants Application: Baking, Pasta Production, Nutritional Supplements, Snacks |
| Companies Covered | General Mills, Cargill, Conagra Mills, Allied Mills, Archer Daniels Midland Company, Ardent Mills, George Weston Foods, Hodgson Mills, The King Milling Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whole-Wheat Flour Market Evolving Landscape
Whole-wheat flour processing is bifurcating between heritage stone-ground methods and precision-controlled roller milling, with regulatory fortification mandates forcing technology convergence at the industrial tier.
Impact milling with temperature-controlled aspiration is displacing conventional roller systems in premium whole-wheat production. Artisan bakeries in North American urban markets specify sub-40°C flour temperatures to preserve enzyme activity. This thermal specification is displacing high-speed roller configurations that generate excessive frictional heat during bran integration.
REACH-compliant food-contact substance approvals are reshaping European packaging requirements for whole-wheat flour distribution. The European Chemicals Agency's updated migration limits for mineral oil saturated hydrocarbons are forcing kraft paper supplier switches. German and French retail flour brands are accelerating compostable barrier film adoption to preempt enforcement actions.
Restaurant chains are unbundling flour specifications from broadline distributor contracts. Fast-casual bakery concepts now contract directly with regional mills for custom protein-content blends. This disintermediation is most advanced in California and Texas, where independent pizzeria groups source identity-preserved hard red winter wheat through mill-direct arrangements bypassing traditional foodservice distribution.
Whole-Wheat Flour Market Segmentation
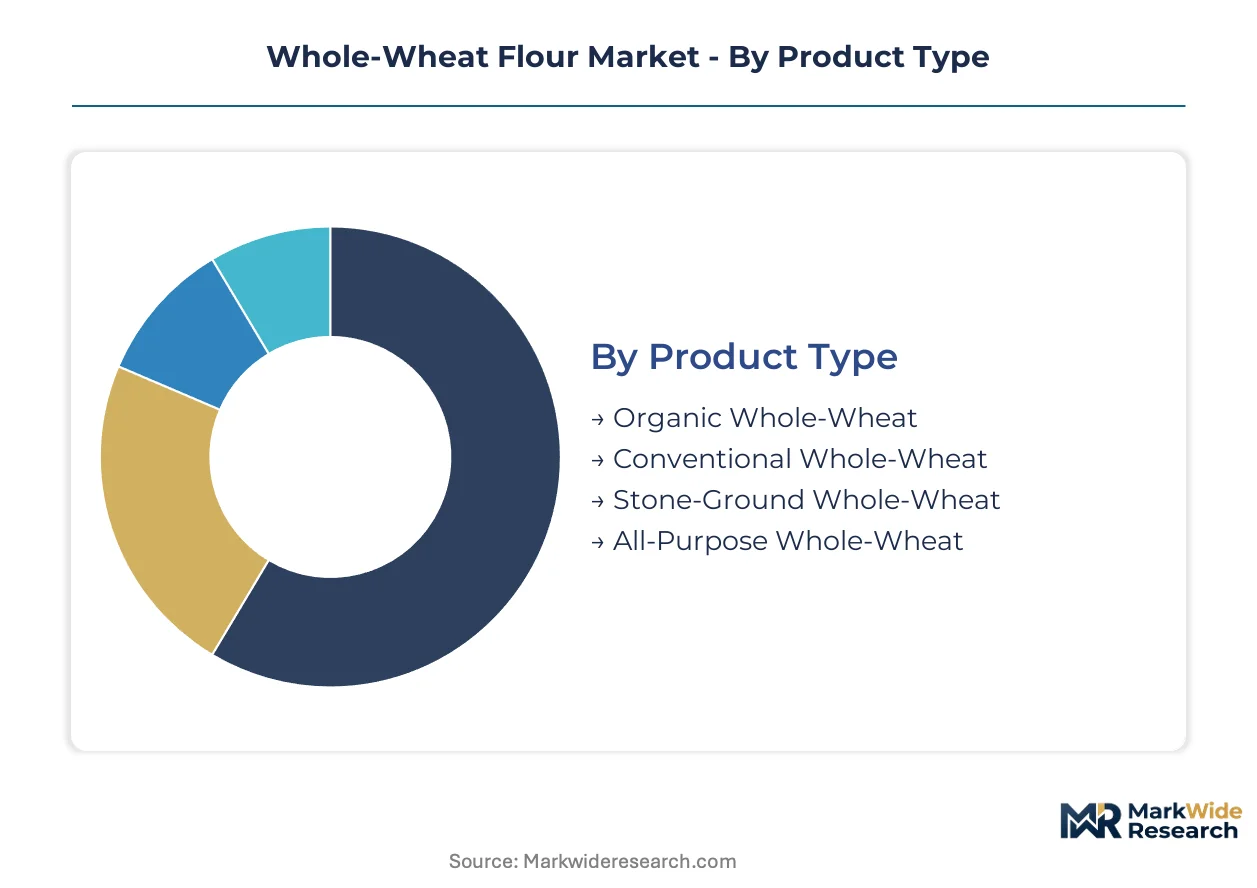
Whole-wheat flour segmentation reveals divergent supply chain architectures across product grades and procurement channels. Understanding these splits exposes where margin pools concentrate and which customer groups drive specification changes.
Product Type:
Domestic milling dominates conventional and all-purpose grades, while organic and stone-ground variants rely heavily on export-certified production from India, Australia, and select North American heritage operations.
- Organic Whole-Wheat:USDA National Organic Program certification mandates 24-36 month transition timelines for grain sourcing and milling operations. Demand clusters in California and Pacific Northwest retail channels where consumers pay premiums for pesticide-free fiber enrichment. Supply scarcity limits volume expansion despite margin advantages.
- Stone-Ground Whole-Wheat:Heritage milling preserves enzyme activity through sub-40°C grind temperatures, attracting artisan bakery procurement in urban North American markets. Hodgson Mills and regional specialists control this premium tier through proprietary stone-burr configurations and minimal-processing narratives.
- Conventional Whole-Wheat:Roller-milled extraction dominates industrial pasta and snack manufacturing, with Ardent Mills and Cargill supplying standardized 11-15% protein specifications to food manufacturers.
- All-Purpose Whole-Wheat:Blended formulations balance fiber content with refined flour performance for home baking applications, distributed primarily through supermarket private-label programs.
Conventional whole-wheat commands the established base. The steepest expansion runs through stone-ground heritage variants.
Distribution Channel:
Channel selection maps directly to customer price sensitivity and specification complexity, with direct procurement bypassing traditional tiers in commercial segments.
- Online Retail:E-commerce portals enable specialty mills to bypass distributor markups and reach independent bakeries with identity-preserved varietals. California and Texas fast-casual concepts source custom protein blends through mill-direct digital platforms.
- Supermarkets:Mass retail moves volume through private-label conventional whole-wheat, with shelf space allocation favoring national brands meeting standardized fortification requirements.
- Health Food Stores:Premium positioning for organic and stone-ground products, with retailers prioritizing USDA certification and minimal-processing claims in assortment decisions.
- Specialty Stores:Ethnic grocers and artisan food shops stock heritage grain varietals for regional baking traditions, particularly Indian and Middle Eastern whole-wheat applications.
Supermarkets anchor volume throughput. Health food stores deliver the fastest margin expansion.
End User:
User sophistication determines specification granularity, with commercial operators driving custom blending while home segments accept standardized grades.
- Bakers:Artisan and industrial operations specify exact protein percentages and extraction rates, with pizza chains in Texas and California contracting directly for hard red winter wheat identity preservation.
- Food Manufacturers:Pasta producers require 13-15% protein hard wheat with climate-dependent yield consistency, while snack extruders prioritize cost over fiber visibility in formulation decisions.
- Home Cooks:All-purpose blends dominate retail purchases, with consumers responding to FDA whole-grain labeling claims in purchase decisions.
- Restaurants:Fast-casual bakery concepts unbundle flour from broadline contracts, sourcing regional mill products for menu differentiation.
Food manufacturers consume the largest volume share. Restaurant direct procurement shows the steepest channel shift.
Application:
Application requirements dictate wheat varietal selection and processing intensity, with thermal specifications varying dramatically across end uses.
- Baking:Bread and pastry applications drive clean-label reformulation, with industrial bakers substituting refined flour to meet fiber-content claims without additive inclusion. Stone-ground preferences dominate artisan segments.
- Pasta Production:Durum and hard red spring wheat specifications demand consistent 13-15% protein content, with climate volatility compressing margin predictability for manufacturers.
- Nutritional Supplements:Bran and germ fractions enter fiber fortification powders, with extraction byproducts finding secondary value streams.
- Snacks:Extruded products prioritize cost-sensitive refined flour where fiber enrichment lacks consumer visibility, limiting whole-wheat penetration.
Baking anchors category demand. Nutritional supplement applications gain share fastest as functional food trends accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government fortification mandates and health-focused procurement policies are redirecting whole-wheat flour demand toward certified supply chains across major consuming economies.
United States
Clean-label bakery reformulation drives industrial adoption as Ardent Mills and Cargill supply standardized protein specifications to pasta manufacturers. FDA whole-grain labeling standards govern retail product identity. Minneapolis-St. Paul anchors North American milling capacity with vertically integrated elevator-to-mill networks.
India
FSSAI fortification directives mandate micronutrient enrichment in public distribution channels, locking institutional demand for fortified variants. Government procurement integration offers captive volume anchors for compliant mills. Punjab and Haryana concentrate bulk wheat processing infrastructure serving subsidized distribution networks.
Germany
REACH-compliant food-contact substance approvals reshape packaging requirements for whole-wheat flour distribution. ECHA migration limits for mineral oil saturated hydrocarbons force kraft paper supplier switches. Bavaria and Baden-Württemberg host heritage grain recovery programs enabling terroir-based differentiation.
Australia
Export-certified organic production supplies North American and Asian health-food retail channels facing USDA National Organic Program compliance scarcity. Climate-driven protein content volatility challenges durum wheat consistency. Victoria and New South Wales concentrate identity-preserved hard wheat programs for artisan bakery contracts.
Canada
Prairie provinces anchor hard red spring wheat production for pasta manufacturers requiring 13-15% protein specifications. Health Canada grain quality standards govern varietal registration for commercial milling. Manitoba and Saskatchewan concentrate elevator infrastructure serving international bulk export markets.
Whole-Wheat Flour Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and milling technology vectors. The vendor base stratifies between industrial-scale roller mills and heritage stone-ground operations. Three archetypes dominate: vertically integrated grain handlers controlling elevator-to-distribution networks, organic certification specialists capturing scarcity premiums, and artisan heritage mills occupying minimal-processing niches. Capacity expansion and direct-to-bakery digital platform development represent the dominant competitive moves reshaping channel access.
Within the heritage milling tier, Hodgson Mills exemplifies stone-ground positioning through minimal-processing narratives. At the industrial scale end, Cargill anchors global supply through proprietary varietal development programs. Ardent Mills occupies the vertically integrated archetype, sustaining cost advantages across North American distribution through regional grain elevator control.
| Leading Market Players |
|---|
| General Mills |
| Cargill |
| Conagra Mills |
| Allied Mills |
| Archer Daniels Midland Company |
| Ardent Mills |
| George Weston Foods |
| Hodgson Mills |
| The King Milling Company |
| Others |
Value Network & Pricing Analysis
Mill-scale economies at Ardent Mills and Cargill compress unit costs below regional competitors, anchoring price floors for conventional grades while organic certification scarcity sustains premiums for USDA-compliant supply. This concentration forces smaller operators toward stone-ground differentiation or FSSAI fortification specialization to escape commodity pricing gravity.
Pricing Analysis
Certification level creates the primary spread across the whole-wheat flour market, with USDA Organic commanding substantial premiums over conventional roller-milled grades due to 24-36 month compliance timelines constraining supply expansion. Three-tier pricing structure across premium stone-ground, standard fortified, and economy conventional levels reflects processing intensity and provenance claims. Pricing pressure stems from climate-driven protein volatility in hard wheat varietals, compressing margin predictability for pasta manufacturers. Food manufacturers exhibit highest price sensitivity due to bulk procurement volumes, while artisan bakeries absorb premiums for identity-preserved heritage grains.
Supply Chain Analysis
Inbound logistics costs through Mumbai and Chennai ports constrain Indian fortification mills serving public distribution channels, elevating landed costs for micronutrient premix inputs. Supply concentrates in the United States, India, and Australia, with Prairie provinces and Punjab anchoring hard wheat production for protein-specified pasta manufacturing. Raw material dependencies center on hard red winter wheat, durum varietals, and iodine-iron premixes for FSSAI compliance. Single-source vulnerability runs through climate-exposed wheat belts where yield inconsistency threatens protein specification adherence. Distribution runs through vertically integrated elevator-to-mill networks for industrial volumes, while specialty mills bypass traditional tiers via direct-to-bakery digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern whole-wheat flour procurement as restaurant chains unbundle specifications from broadline distributors, creating interoperability demands between mill-direct digital portals and independent bakery ERP systems.
For Market Incumbents: Consolidate elevator infrastructure across North American wheat belts to secure identity-preserved varietal streams before heritage grain programs mature. Acquire FSSAI-certified Indian milling capacity to anchor government procurement volumes. Stone-ground technician pipelines represent a critical retention vulnerability as aging operators exit without replacement training pathways. For New Entrants and Emerging Players: Differentiate on thermal specification compliance for artisan bakery segments demanding sub-40°C enzyme preservation. Target Texas and California fast-casual pizza chains with custom protein-content blends bypassing distributor markups. Launch proprietary e-commerce portals featuring identity-preserved hard red winter wheat with batch-traceable provenance documentation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heritage milling equipment manufacturers and digital procurement platform operators over commodity roller-mill expansions. Five-to-ten year viability hinges on fortification mandate proliferation across Asian public distribution systems. Monitor FDA whole-grain serving-size threshold revisions as immediate portfolio reformulation triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Grain Varietal Recovery | Regional landrace programs enable terroir-based differentiation for artisan bakery contracts in Bavaria and Victoria. |
| Direct-to-Bakery Digital Platform | Mill-direct portals bypass distributor markups while capturing specification data from California pizzeria procurement. |
| FSSAI Fortification Compliance | Micronutrient enrichment mandates lock institutional volume anchors for mills serving India's public distribution system. |
| Stone-Ground Equipment Retrofit | Temperature-controlled aspiration systems displace conventional roller mills for premium enzyme-active flour production. |
| Backward Integration into Elevators | Regional grain elevator control secures identity-preserved varietal streams for protein-specified pasta manufacturing. |
Research Methodology
Operator-level perspectives from mill procurement directors, artisan bakery owners, food manufacturing R&D leads, and FSSAI compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through USDA National Organic Program filings, FSSAI fortification directive documentation, FDA whole-grain labeling dockets, and customs trade records for wheat varietal flows. Bottom-up volume modeling triangulated against top-down protein specification demand estimates across pasta, bakery, and snack extrusion applications.
Sensitivity analysis tested forecast robustness across climate volatility scenarios for hard wheat yield consistency and regulatory adoption timelines for fortification mandates. Segmentation dimensions modeled include product certification tier, milling technology type, distribution channel structure, end-user sophistication level, and application thermal specification. CAGRs derived from multivariate regression across protein content demand curves and clean-label reformulation penetration rates, with inputs anchored to grain elevator capacity utilization and heritage grain program enrollment trajectories.
The analysis sits within stated boundaries; outcomes outside sustained FSSAI enforcement, FDA serving-size finalization, or climate adaptation in wheat breeding programs would require recalibration. Forecasts reflect documented assumptions regarding fortification mandate geographic expansion and artisan bakery channel growth. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Masa Corn Products Market
Grains
United States Maize Market
Grains
Oat Bran Market
Grains
South American Maize Market
Grains
Argentina Grains Market
Grains
Egypt Rice Market
Grains
Grain Silos and Storage System Market
Grains
South America Rice Market
Grains
North America Wheat Market
Grains
Asia-Pacific Rice Market
Grains
Organic Rice Flour Market
Grains
Bangladesh Rice Market
Grains
Corn Market
Grains
Global Wheat Market
Grains
Asia-Pacific Wheat Market
Grains
Brown Rice Market