
 North America Wheat Protein Market | 2026-2036
North America Wheat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wheat Protein Market Analytics
Ingredient customization revenue is narrowing as buyers consolidate procurement around fewer qualified suppliers. Archer Daniels Midland Company leverages its origination network across the US grain belt to secure feedstock cost advantages. Cargill competes through backward integration into wheat milling and ethanol co-product streams. Kerry Group differentiates via flavor-masked protein systems tailored for meat alternative applications.
Wheat protein comprises glutenin and gliadin fractions extracted from wheat flour through wet-processing, yielding isolates with protein concentrations exceeding 80% for food fortification and binding applications. Vital wheat gluten dominates commercial volumes due to its viscoelastic properties in bakery and pasta manufacturing, while textured wheat protein records the fastest application growth as extrusion technologies improve fibrous structure simulation for meat alternatives. Wheat protein isolate commands premium positioning in nutraceutical and personal care formulations where allergen management and solubility specifications matter.
USDA grading standards and FDA food additive regulations govern protein content claims and allergen labeling across US interstate commerce, while Health Canada and PMRA requirements shape cross-border product registration for Canadian market access. The FDA's evolving framework for plant-based meat terminology influences how textured wheat protein gets positioned at retail. Stakeholders must monitor how California and New York state-level clean-label legislation propagates into broader procurement specifications requiring ingredient traceability and processing transparency.
Market Dynamics
Plant-based meat manufacturers are consolidating wheat protein procurement around fewer qualified suppliers capable of delivering consistent functional performance and full traceability documentation. This buyer concentration is compressing margins for mid-tier processors while rewarding integrated origination-to-ingredient operators with volume commitments and multi-year contracts.
Growth Catalysts
- USDA BioPreferred Program:Federal procurement preference for biobased ingredients drives institutional foodservice adoption of wheat protein isolates in school nutrition and military ration formulations.
- Extrusion technology advancement:High-moisture extrusion systems now simulate muscle fiber alignment in textured wheat protein, enabling cleaner-label meat alternatives without methylcellulose binders.
- Midwest milling cluster concentration:Proximity to Kansas, Nebraska, and Oklahoma hard red winter wheat production reduces feedstock logistics costs for protein extraction facilities.
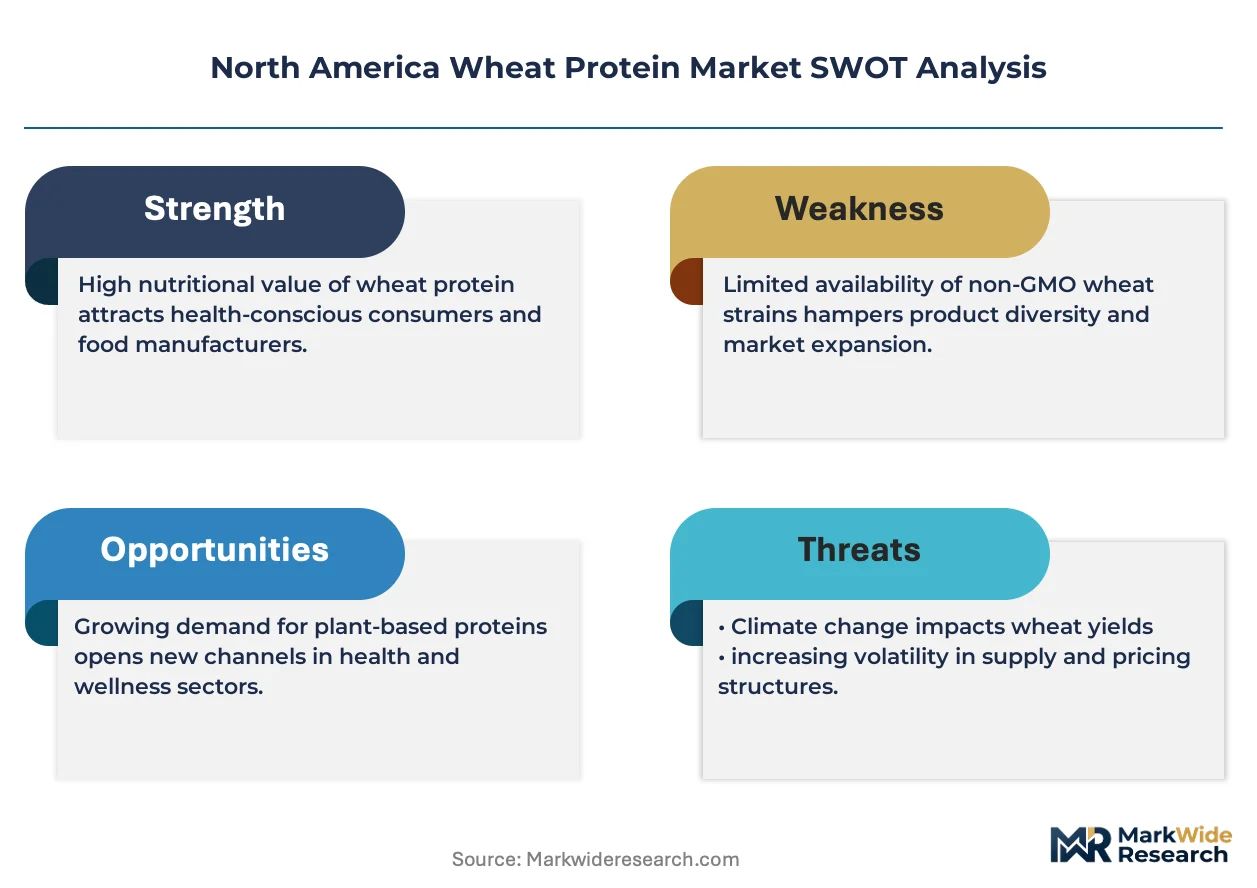
Market Restraints
- Hard red winter wheat price volatility:Drought cycles in the Southern Plains and export competition from Black Sea suppliers create input cost instability for gluten processors.
- Single-source supply risk:Vital wheat gluten production concentrates among four North American millers, creating vulnerability to facility downtime or quality excursions.
- Functional ceiling in high-hydration applications:Wheat protein's water-holding capacity plateaus below soy and pea alternatives, limiting penetration in certain meat analog formats.
Strategic Opportunities
- Canadian prairie wheat expansion:Saskatchewan and Manitoba spring wheat production offers untapped feedstock for protein extraction facilities serving Health Canada-registered clean-label product lines.
- Precise fermentation hybridization:Combining wheat protein substrates with microbial fermentation enables customized amino acid profiles for sports nutrition and clinical nutrition applications.
- Direct-to-manufacturer e-procurement platforms:Digital ingredient marketplaces reduce distributor markups and accelerate specification matching for mid-sized plant-based meat startups.
Industry Challenges
- Extrusion operator skill scarcity:High-moisture extrusion of wheat protein requires specialized rheology expertise that outpaces current technical training program output.
- Dual certification timeline pressure:Simultaneous pursuit of Non-GMO Project verification and USDA Organic certification extends product launch schedules by 14-18 months.
- Legacy bakery equipment incompatibility:Textured wheat protein incorporation demands screw profile and barrel temperature modifications that conflict with existing pasta and baked goods production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wheat Protein Market |
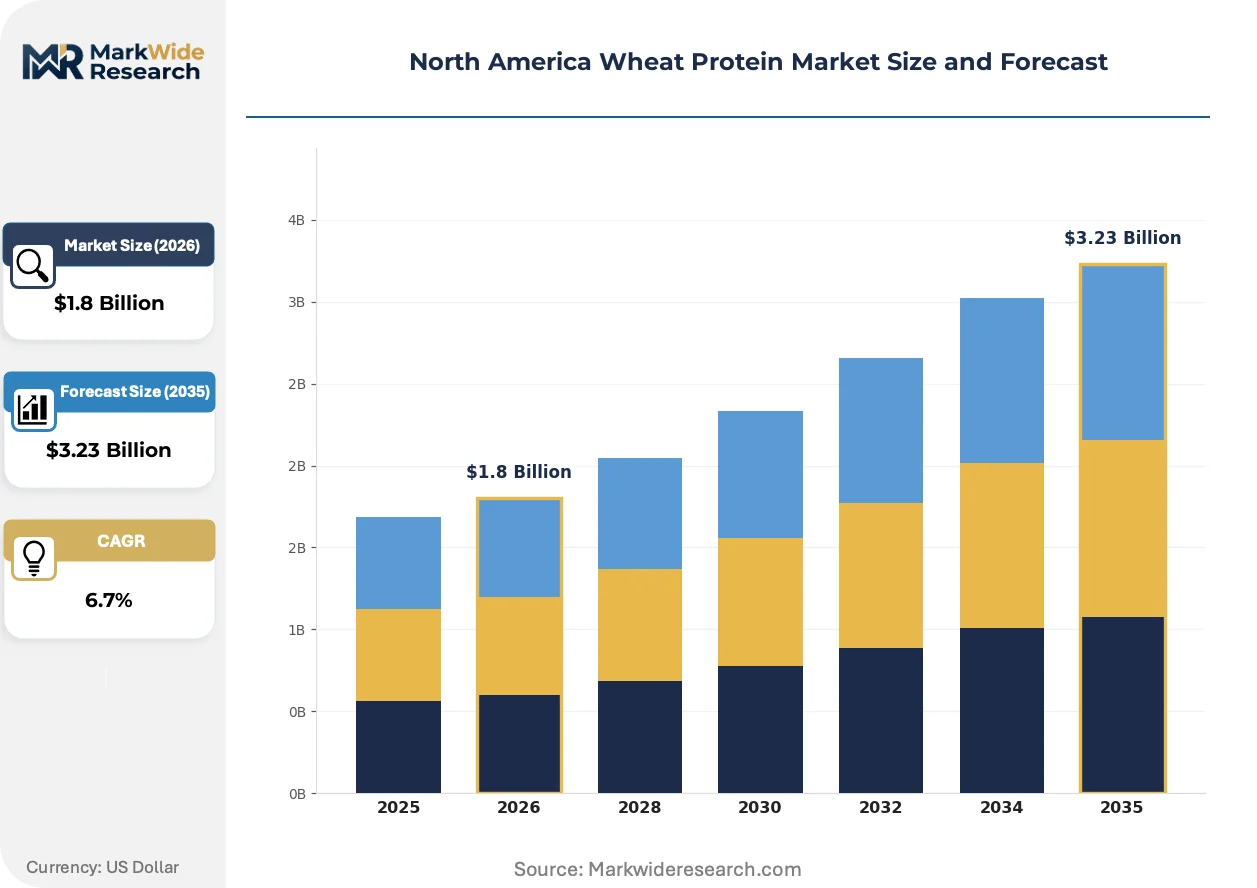
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Wheat Protein, Vital Wheat Gluten, Wheat Protein Isolate, Textured Wheat Protein Application: Beverages, Bakery Products, Snacks, Meat Alternatives End User: Food Industry, Nutraceuticals, Animal Feed, Personal Care Distribution Channel: Direct Sales, Online Retail, Supermarkets, Specialty Stores |
| Companies Covered | Roquette Frères, Manildra Group, Archer Daniels Midland Company, AB Amilina, Agridient, Cargill, Tereos, Kerry Group, MGP Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wheat Protein Market Evolving Landscape
Extrusion science and precision fermentation are converging to expand wheat protein functionality beyond traditional bakery applications into high-performance meat analog systems. These technical advances are reshaping supplier qualification criteria and end-use specification standards simultaneously.
High-moisture extrusion technology is migrating from low-shear, low-hydration configurations toward twin-screw systems operating at moisture levels exceeding 60%. Plant-based meat R&D teams at CPG manufacturers are validating these next-generation textures for whole-muscle chicken and seafood alternatives. The shift is compressing development cycles for clean-label products while raising the technical barrier for ingredient suppliers lacking in-house extrusion pilot capabilities.
Health Canada's updated Food and Drug Regulations for plant-based protein claims now mandate amino acid scoring pattern disclosure on nutrition labels. This regulatory revision forces wheat protein suppliers to invest in compositional testing infrastructure and reformulate blends to achieve PDCAAS scores competitive with animal and soy alternatives. Canadian market entrants must now front-load regulatory affairs resources before product registration.
Food manufacturers are consolidating ingredient sourcing decisions under centralized procurement functions with sustainability scorecard requirements. Mid-sized plant-based meat brands are bypassing traditional distributor networks to contract directly with wheat protein extractors offering mass-balance certified supply chains. This pattern is most pronounced in California and New York state markets where retail buyers enforce Scope 3 emissions disclosure from ingredient tiers.
North America Wheat Protein Market Segmentation
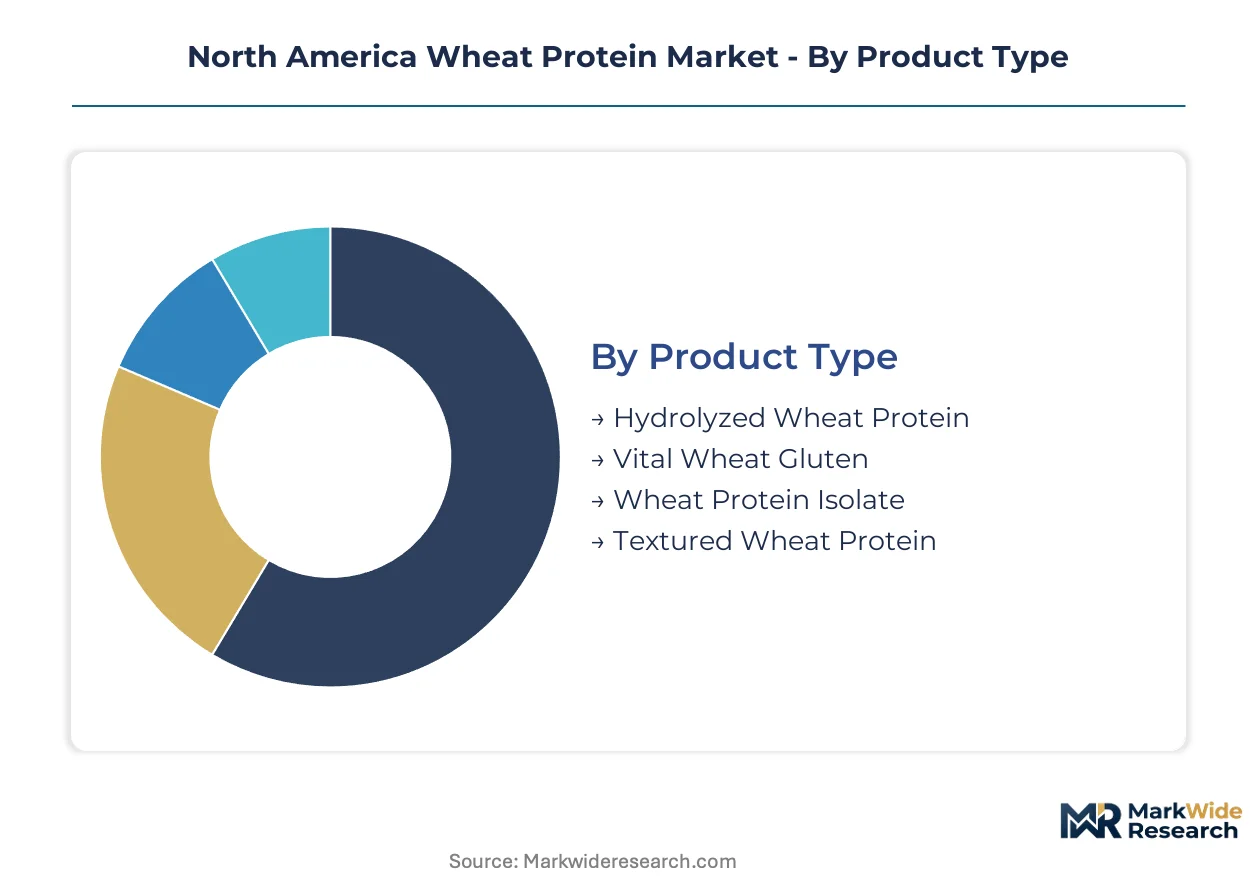
Wheat protein segmentation in North America reflects divergent technical requirements across bakery heritage applications and emerging meat alternative formulations. Product type selection determines functional performance ceilings, while distribution channel choices increasingly hinge on traceability documentation capabilities.
Product Type:
Formulators select wheat protein fractions based on viscoelastic demands, hydration targets, and clean-label positioning requirements across the use-case spectrum.
- Vital Wheat Gluten:Comprising 75-85% protein with intact glutenin-gliadin networks, this fraction delivers the elastic backbone for artisan bread and pasta production. Demand concentrates among Midwest milling operations supplying Kansas and Nebraska hard red winter wheat bases to industrial bakeries, though drought-induced feedstock volatility creates margin pressure for processors lacking origination assets.
- Textured Wheat Protein:Extruded fibrous structures from vital wheat gluten or isolate precursors now achieve moisture levels exceeding 60% through high-shear twin-screw systems. Meat alternative manufacturers in California and New York state procurement networks are validating these textures for whole-muscle chicken analogs, driving fastest-segment expansion as methylcellulose-free clean-label formulations gain retail traction.
- Wheat Protein Isolate:Purified to 90%+ protein with reduced starch and fiber content, this premium fraction serves sports nutrition powders and clinical nutrition applications where solubility and allergen management matter.
- Hydrolyzed Wheat Protein:Enzymatically cleaved peptides with enhanced digestibility and film-forming properties for personal care formulations and specialized beverage fortification.
The dominant share belongs to Vital Wheat Gluten, while Textured Wheat Protein is closing the gap fastest.
Application:
Volume concentration varies sharply between mature bakery channels and nascent meat alternative segments with divergent specification standards.
- Bakery Products:Heritage applications in bread, pizza crust, and laminated doughs consume the largest protein volumes, with vital wheat gluten fortifying flour consistency across variable crop years. Procurement concentrates among national baking conglomerates with captive milling operations in the US grain belt, though legacy equipment retrofit costs slow textured protein adoption.
- Meat Alternatives:High-moisture extrusion and 3D structuring technologies are displacing soy and pea proteins in plant-based chicken, seafood, and whole-cut beef analogs. R&D teams at CPG manufacturers in Chicago and Austin innovation hubs are driving specification evolution toward fibrous bite alignment and neutral flavor profiles that mask wheat protein's characteristic notes.
- Snacks:Extruded puffs and protein-fortified crackers leverage wheat protein's expansion properties and Maillard reactivity for texture and browning control.
- Beverages:Limited penetration due to solubility challenges and suspension stability requirements, with hydrolyzed forms finding niche use in meal replacement formulations.
Bakery Products retains volume leadership, though Meat Alternatives commands the steepest expansion trajectory.
End User:
Customer technical sophistication ranges from commodity procurement functions to specialized formulation teams with pilot-scale extrusion capabilities.
- Food Industry:Industrial bakeries and plant-based meat manufacturers represent the core demand base, with procurement consolidation around fewer qualified suppliers capable of delivering full traceability documentation and consistent functional performance across lot sizes.
- Nutraceuticals:Sports nutrition and clinical nutrition formulators seek customized amino acid profiles and PDCAAS optimization, with Health Canada's scoring pattern disclosure mandate driving compositional testing investments.
- Personal Care:Film-forming and conditioning properties in hydrolyzed wheat protein serve hair care and skin care formulations with clean-label positioning requirements.
- Animal Feed:Feed-grade vital wheat gluten from ethanol co-product streams competes with soy meal in pet food and aquaculture applications.
Food Industry dominates procurement volumes, while Nutraceuticals shows the most rapid specification escalation.
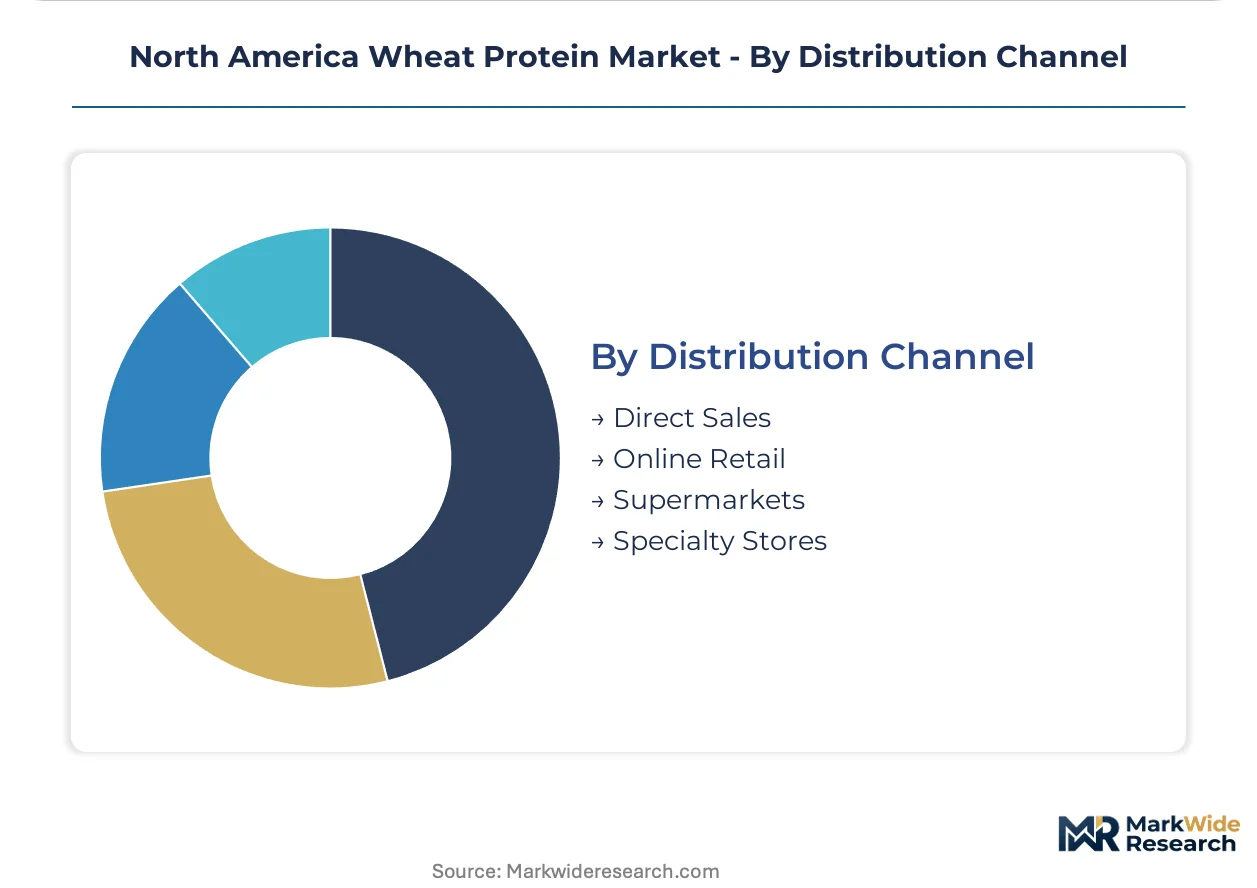
Distribution Channel:
Channel selection increasingly correlates with customer scale and sustainability verification requirements rather than traditional geographic coverage.
- Direct Sales:Large plant-based meat brands and national bakery chains bypass distributor markups to contract directly with wheat protein extractors offering mass-balance certified supply chains, with California and New York state buyers enforcing Scope 3 emissions disclosure.
- Specialty Stores:Ingredient distributors serving mid-sized manufacturers with technical support and smaller minimum order quantities, though margin compression from buyer consolidation limits growth.
- Online Retail:E-procurement platforms accelerate specification matching for startups, reducing search costs and enabling rapid supplier qualification.
- Supermarkets:Limited wheat protein distribution as a standalone ingredient, confined to specialty baking aisles in premium retail formats.
Direct Sales captures the largest revenue share, while Online Retail platforms are gaining transaction velocity fastest among emerging brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across North American procurement networks. Large plant-based meat manufacturers in California and New York enforce strict sustainability scorecards that tolerate premium pricing for mass-balance certified supply chains. Mid-sized industrial bakeries in the US Midwest remain highly elastic, switching suppliers on quarterly feedstock cost movements.
United States
Plant-based meat R&D teams in Chicago and Austin innovation hubs drive specification evolution toward fibrous bite alignment and neutral flavor profiles. The FDA's evolving framework for plant-based meat terminology shapes how textured wheat protein gets positioned at retail. Kansas and Nebraska hard red winter wheat production clusters anchor the nation's largest milling infrastructure, with protein extraction facilities concentrated in proximity to grain origination points.
Canada
Health Canada's updated Food and Drug Regulations for plant-based protein claims now mandate amino acid scoring pattern disclosure on nutrition labels. Saskatchewan and Manitoba spring wheat production offers untapped feedstock for protein extraction facilities serving Health Canada-registered clean-label product lines. Prairie province milling operations are expanding capacity to capture cross-border demand from US manufacturers seeking dual-certified supply chains.
Mexico
Industrial bakery growth in Mexico City and Monterrey metro areas sustains import demand for vital wheat gluten fortification. Mexico's national food safety regulator COFEPRIS shapes import documentation requirements for wheat protein isolates entering pharmaceutical and nutraceutical channels. Bajío Region food processing clusters are attracting toll-manufacturing investments from US-based suppliers seeking NAFTA-advantaged production.
North America Wheat Protein Market Competitive Landscape
Integrated grain processors and specialized ingredient formulators split the market into distinct capability tiers. Four North American millers concentrate vital wheat gluten production, creating single-source supply vulnerability. Strategic archetypes include origination-integrated majors with captive wheat supply, and application-focused specialists with in-house extrusion pilot capabilities. Competitive moves center on backward integration into prairie wheat sourcing and high-moisture extrusion technology licensing.
Within the origination-integrated tier, Archer Daniels Midland Company and Cargill exemplify scale-driven positions anchored across the US grain belt. Kerry Group occupies a specialist position emphasizing flavor-masked protein systems. These three entities represent contrasting strategic postures: ADM and Cargill leverage upstream control over feedstock costs, while Kerry Group differentiates through formulation expertise tailored for meat alternative applications.
| Leading Market Players |
|---|
| Roquette Frères |
| Manildra Group |
| Archer Daniels Midland Company |
| AB Amilina |
| Agridient |
| Cargill |
| Tereos |
| Kerry Group |
| MGP Ingredients |
| Others |
Value Network & Pricing Analysis
Kansas grain belt milling clusters concentrate vital wheat gluten capacity among four North American processors, translating feedstock proximity into pricing power over downstream bakery and meat alternative manufacturers. Hard red winter wheat price volatility from Southern Plains drought cycles feeds directly into contract renegotiation leverage, while California and New York procurement networks absorb premiums for mass-balance certified supply chains.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated millers and national bakery chains, though spot market exposure persists for mid-tier processors lacking origination assets. Price differentiation separates mass-balance certified isolates for plant-based meat manufacturers from commodity-grade vital wheat gluten serving industrial bakeries. Pricing pressure stems from buyer consolidation around fewer qualified suppliers capable of delivering full traceability documentation. Industrial bakeries in the US Midwest exhibit highest price sensitivity, switching suppliers on quarterly feedstock cost movements, while California plant-based meat brands tolerate premium positioning for sustainability-verified supply chains.
Supply Chain Analysis
ADM and Cargill milling operations in Kansas, Nebraska, and Oklahoma hold dominant vital wheat gluten capacity, with Manildra Group and MGP Ingredients occupying specialized extraction positions. Hard red winter wheat from the Southern Plains and spring wheat from Saskatchewan and Manitoba constitute primary feedstock dependencies. Single-source vulnerability concentrates among four North American millers, creating facility downtime risk across bakery and meat alternative channels. Distribution runs through direct sales relationships with large plant-based meat brands and national bakery chains bypassing traditional distributor networks, supplemented by e-procurement platforms accelerating startup supplier qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where extrusion technology licensing and formulation consulting revenue layers expand faster than commodity protein sales. Customized amino acid profiling and clean-label certification support services now command margin premiums exceeding base ingredient transactions.
For Market Incumbents: Entrench origination control through prairie wheat sourcing expansion into Saskatchewan and Manitoba spring wheat production. Secure multi-year contracts with California and New York plant-based meat manufacturers before Health Canada's amino acid scoring disclosure mandate propagates into US procurement specifications. Invest in high-moisture extrusion pilot capabilities to defend against specialist competitors offering turnkey texture solutions.
For New Entrants and Emerging Players: Establish a beachhead in hydrolyzed wheat protein for sports nutrition and clinical nutrition applications where solubility specifications and PDCAAS optimization command premium positioning. Target Canadian market entry ahead of prairie province milling capacity expansion, leveraging Health Canada's updated Food and Drug Regulations as a qualification barrier for incumbent complacency. Pursue direct-to-manufacturer e-procurement platform partnerships to bypass established distributor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a nutrition-as-a-service play because ingredient suppliers are consolidating around formulation expertise and certification infrastructure rather than commodity extraction scale. Acquisition targets should emphasize extrusion technology licensing capabilities and Health Canada-registered product lines. Monitor FDA plant-based meat terminology framework evolution as an inflection signal for textured wheat protein positioning at retail.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prairie Wheat Sourcing | Secures Saskatchewan and Manitoba spring wheat feedstock for Health Canada-registered clean-label product lines. |
| High-Moisture Extrusion Technology Licensing | Enables methylcellulose-free meat analog textures for California and New York procurement networks. |
| Dual Certification Investment | Simultaneous Non-GMO Project and USDA Organic pursuit extends product launch timelines but locks in premium positioning. |
| Direct-to-Manufacturer E-Procurement Platform | Reduces distributor markups and accelerates specification matching for mid-sized plant-based meat startups. |
| Precision Fermentation Hybridization | Combines wheat protein substrates with microbial fermentation for customized amino acid profiles in sports nutrition. |
Research Methodology
A spread of perspectives from wheat protein extraction plant managers, procurement leads at plant-based meat manufacturers, bakery R&D directors, and Health Canada regulatory affairs specialists converged on the working assumptions driving segmentation and growth projections. Primary fieldwork combined structured interviews with secondary validation through USDA crop production reports, FDA food additive regulations, Health Canada Food and Drug Regulations, and SEC filings from publicly traded grain processors. Bottom-up volume modeling across product types and applications triangulated against top-down market sizing from trade flow analysis.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning protein fraction type, application category, end-user technical sophistication, and distribution channel traceability requirements. CAGRs derived from historical volume trajectories adjusted for extrusion technology adoption curves and regulatory disclosure mandate implementation timelines. Forecast inputs incorporated hard red winter wheat price volatility cycles and prairie province milling capacity expansion announcements.
Sensitivities concentrate around FDA plant-based meat terminology framework finalization, Health Canada amino acid scoring pattern enforcement intensity, and Southern Plains drought frequency affecting feedstock costs. Forecasts reflect documented assumptions regarding buyer consolidation velocity and extrusion operator training program output. Quarterly review of USDA crop condition reports, FDA guidance document releases, and California clean-label legislation propagation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Grain Roller Market
Grains
Organic Rice Flour Market
Grains
Global Grain Mill Products Market
Grains
Cultured Wheat Market
Grains
Argentina Maize Market
Grains
United States Rice Market
Grains
Wheat Fiber Market
Grains
Egypt Rice Market
Grains
Africa Maize Market
Grains
North America Pulses Market
Grains
Chickpeas Market
Grains
Sorghum Market
Grains
Corn Flour Market
Grains
Barley Grass Market
Grains
Ancient Grain Market
Grains
Europe Rice Market