
 Grain and Cereal Crop Market | 2026-2036
Grain and Cereal Crop Market Size, Share, and Industry Trends Forecast 2026-2036
Grain and Cereal Crop Market Analytics
Black Sea grain exporters are repositioning trade flows following corridor disruptions. Cargill Incorporated leverages its integrated origination network across North and South American growing belts. Bunge Limited anchors its crushing and export footprint in Brazilian soybean and corn regions. Louis Dreyfus Company competes through ocean freight optimization and port terminal control.
Grain and cereal crops comprise the harvested seeds of cultivated grasses and pseudocereals, typically dried to 12-14% moisture content for storage stability and processed through milling, malting, or fermentation. These crops serve as foundational inputs for human food products, livestock nutrition, and industrial starch extraction. Wheat and rice dominate food processing channels where milling margins concentrate in premium protein grades. Animal feed demand for barley and corn is expanding fastest in integrated poultry and aquaculture systems. The organic variety segment commands price premiums through certified supply chains, though conventional hybrid seed still occupies the volume core.
The USDA and EPA shape US biofuel blending mandates that redirect corn into ethanol channels, while the EU Green Deal and REACH regulate pesticide residues and carbon intensity in imported grain. India's FSSAI and CEA enforce fortification standards and minimum support prices that stabilize domestic cereal availability. Stakeholders must monitor how sustainability certification requirements and carbon border adjustments reshape access to premium import markets.
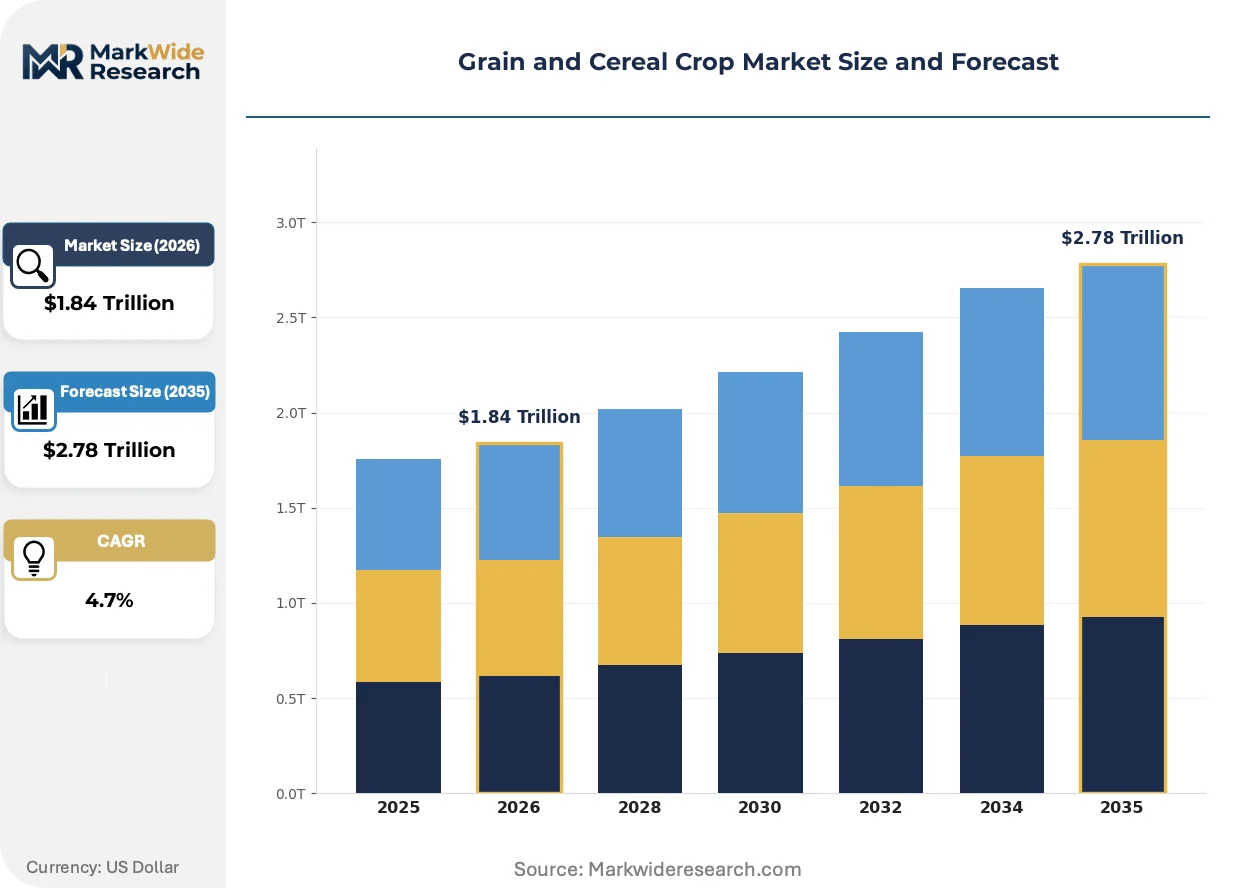
Market Dynamics
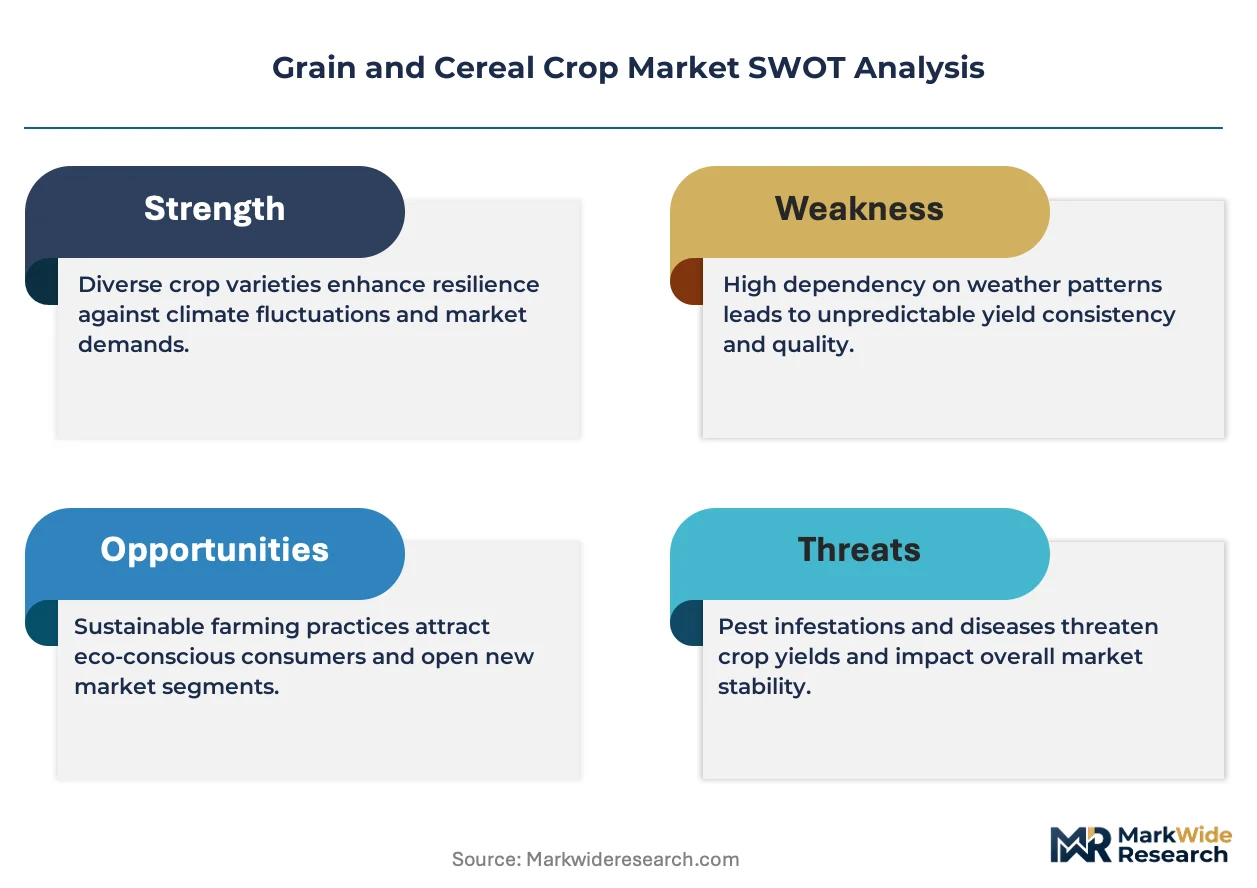
The EU Green Deal and F-Gas Regulation are compressing carbon intensity benchmarks across grain supply chains, forcing input suppliers to certify lower-emission cultivation practices or lose access to premium European procurement channels.
Growth Catalysts
- India's Minimum Support Price regime:The CEA and FSSAI stabilize smallholder output through guaranteed grain procurement, expanding domestic cereal availability and reducing price volatility for millers.
- US biofuel blending mandates:The EPA and USDA redirect corn volumes into ethanol channels, creating structural offtake demand that underpins acreage allocation decisions across the Corn Belt.
- Precision agriculture adoption:Variable-rate nitrogen application and satellite-guided planting are lifting yields per hectare in Brazilian soybean-corn rotation systems, compressing unit production costs.
Market Restraints
- Input cost volatility:Ammonia and phosphate fertilizer prices swing with natural gas benchmarks, compressing margins for growers locked into fixed-price delivery contracts with processors.
- Black Sea supply concentration:Corridor disruptions through Ukrainian ports force rerouting via Romanian Constanta or Baltic terminals, extending lead times and influring ocean freight rates.
- Regulatory friction from REACH:Pesticide residue thresholds for imported grain into the EU are tightening faster than substitution chemistries can achieve registration, blocking some origin shipments.
Strategic Opportunities
- Carbon-certified grain premiums:The EU Carbon Border Adjustment Mechanism creates price differentiation for verified low-emission cereals, rewarding early adopters of regenerative tillage practices.
- Integrated aquaculture feed demand:Barley and wheat middlings are displacing fishmeal in Norwegian and Chilean salmon farming, opening volume contracts with marine protein producers.
- Blockchain traceability channels:Retail and foodservice buyers are mandating immutable origin records, creating subscription revenue streams for data-verified supply chain platforms.
Industry Challenges
- Agronomic data science talent scarcity:Crop modeling and remote sensing expertise concentrates in technology vendors, leaving grain cooperatives dependent on outsourced analytics.
- Certification timeline compression:Organic and regenerative audits require multi-year field history documentation, delaying price premium capture for transitioning growers.
- Legacy storage infrastructure retrofit costs:Aeration and moisture monitoring upgrades for existing silo networks demand capital deployment that smaller elevators cannot self-finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain and Cereal Crop Market |
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $2.78 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat, Barley, Oats, Rice End Use Industry: Food Processing, Animal Feed, Brewing, Biofuel Distribution Channel: Wholesale, Retail, Online, Direct Sales Variety: Hybrid, Heirloom, Organic, Conventional |
| Companies Covered | Cargill Incorporated, Bunge Limited, Louis Dreyfus Company, Archer Daniels Midland, CHS Inc., Wilmar International, Olam International, Seaboard Corporation, Scoular Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain and Cereal Crop Market Evolving Landscape
Digital agronomy platforms and biological input systems are restructuring how yield risk is managed and who captures value from cultivation data across the grain value chain.
Gene-edited drought tolerance traits are overtaking conventional hybrid selection in water-stressed growing regions. Seed companies are stacking these edits into elite germplasm for deployment in Australian and Argentinian wheat belts. The technology is compressing the breeding cycle from eight years to four, enabling faster climate adaptation.
The EU F-Gas Regulation and companion Farm-to-Fork Strategy are banning neonicotinoid seed treatments and compressing allowable synthetic pesticide applications by fifty percent. Milling and malting buyers are now requiring residue testing protocols that exclude non-compliant origins. German and French grain cooperatives are responding by expanding biocontrol and pheromone-based pest management acreage.
Direct contracting between food manufacturers and grower cooperatives is displacing spot market purchases at regional elevators. CPG brands like Unilever and Nestlé are locking multi-year supply agreements with identity-preserved soybean and corn pools. This pattern is most visible in the US Midwest and Brazil's Mato Grosso, where traceability infrastructure supports premium segregation.
Grain and Cereal Crop Market Segmentation
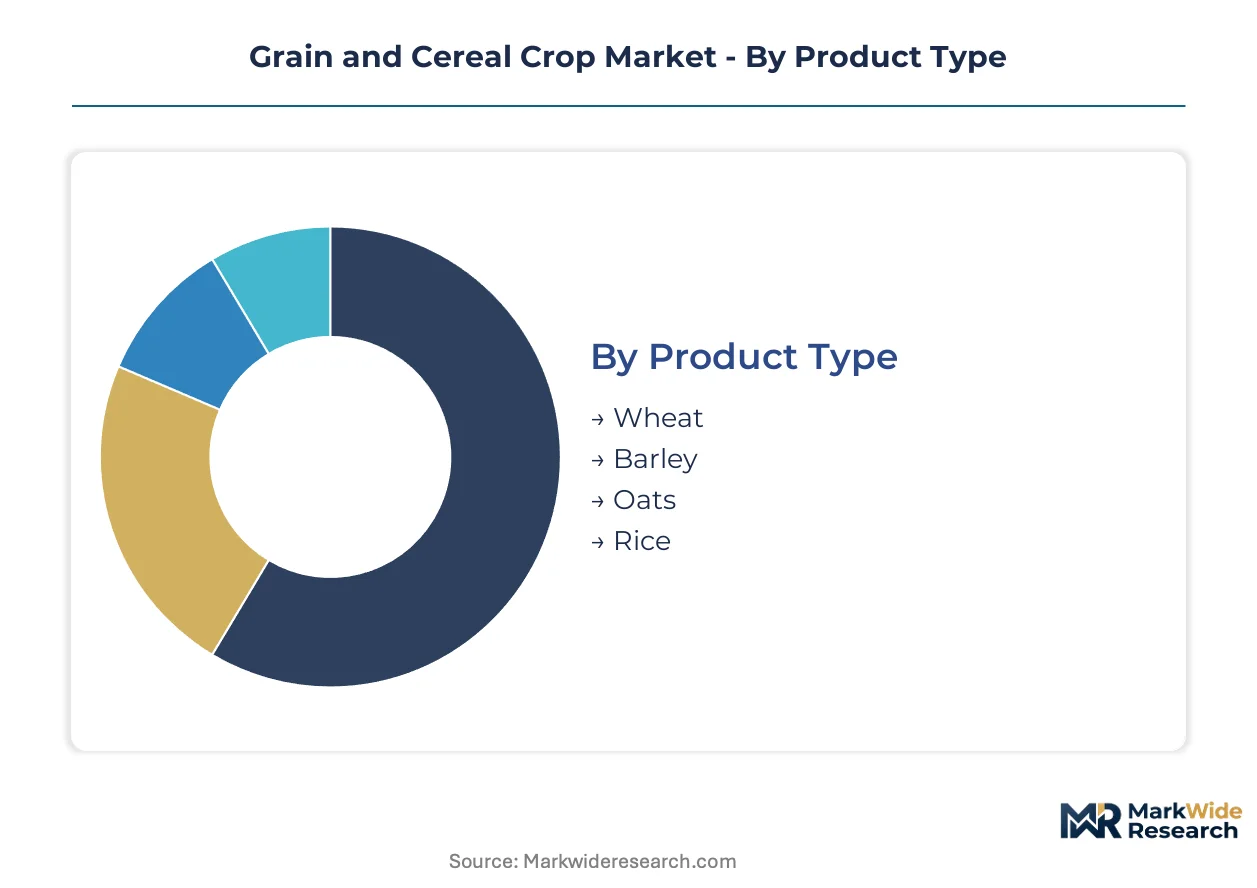
Grain and cereal crop segmentation separates commodity flows by intrinsic quality attributes, downstream processing requirements, and certification status. These divisions determine price formation mechanisms, storage infrastructure investments, and regulatory compliance obligations across the value chain.
Product Type:
Protein content, gluten strength, and starch gelatinization temperatures differentiate milling performance and end-use suitability across grass crop species.
- Wheat:Hard red winter and spring varieties deliver 12-14% protein for bread flour production. Demand concentrates in EU milling corridors where the EFSA enforces mycotoxin thresholds that disqualify lower-grade origins.
- Rice:Long-grain indica and short-grain japonica subspecies exhibit distinct amylose ratios affecting cooking texture. Procurement is accelerating in West African urban centers where import substitution policies favor Asian-origin aromatic varieties.
- Barley:Two-row malting cultivars with low beta-glucan content command brewer premiums.
- Oats:Beta-glucan-rich groats serve functional food and cosmetic ingredient channels.
Mature deployment sits with wheat. Newer deployment is concentrated in specialty barley for craft brewing and aquafeed.
End Use Industry:
Processing intensity and quality specifications vary sharply between human food, animal nutrition, and industrial fermentation applications.
- Animal Feed:Corn and barley deliver metabolizable energy densities of 3,300-3,500 kcal/kg for poultry and swine rations. Demand is climbing fastest in Vietnamese and Indonesian aquaculture systems where extruded feed production expands.
- Food Processing:Durum wheat semolina and parboiled rice require specific hardness and amylose profiles for pasta and instant noodle manufacturing. Milling margins concentrate in premium protein grades destined for CPG brand supply chains.
- Biofuel:Starch-to-ethanol conversion rates favor high-test-weight corn above 56 lb/bushel.
- Brewing:Maltsters specify nitrogen content below 1.65% and germination energy above 95%.
Volume leadership rests with animal feed. Value capture is steepest in brewing and specialty food processing.
Distribution Channel:
Logistics configuration and title transfer timing determine working capital requirements and price risk exposure for growers and buyers.
- Wholesale:Elevator aggregation and barge-rail intermodal shipment dominate bulk commodity movement. The USDA reports weekly cash bids at 1,800+ terminal locations that anchor price discovery.
- Direct Sales:Identity-preserved contracting bypasses spot markets, locking multi-year supply agreements with traceability guarantees. Adoption is expanding most quickly in Brazilian soybean-corn rotation belts where CPG brands mandate deforestation-free sourcing.
- Retail:Packaged flour and breakfast cereals reach consumers through supermarket chains.
- Online:Specialty and organic varieties move through direct-to-consumer platforms.
Wholesale infrastructure commands volume flows. Direct sales channels are capturing margin expansion through sustainability premiums.
Variety:
Genetic provenance and cultivation certification create tiered price structures and market access conditions.
- Conventional:Hybrid seed with stacked trait packages dominates acreage through yield reliability and input compatibility. The EPA regulates refuge requirements for insect-resistant biotech cultivars.
- Organic:Certified supply chains exclude synthetic inputs for three years minimum, capturing 20-40% price premiums in EU and North American retail channels. Transition timelines delay premium capture for converting growers.
- Hybrid:Proprietary genetics protected by plant variety rights concentrate seed market power with multinational breeders.
- Heirloom:Landrace populations preserve genetic diversity for niche food and beverage applications.
Conventional hybrid seed occupies the volume core. Organic certification is climbing fastest where carbon market incentives and retailer procurement policies align.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American Corn Belt and Brazilian Cerrado anchor global supply for corn and soybean rotation systems, while the Indo-Gangetic Plain sustains wheat and rice output for domestic food security programs.
United States
EPA biofuel mandates and USDA crop insurance programs stabilize corn acreage across Iowa, Illinois, and Nebraska. The EPA's Renewable Fuel Standard redirects approximately one-third of national corn output into ethanol channels. Processing clusters in Decatur, Illinois and Cedar Rapids, Iowa concentrate wet milling and fermentation capacity for starch and sweetener derivatives.
Brazil
Mato Grosso and Goiás states expand soybean-corn double-cropping onto former pasturelands, lifting total grain output per hectare annually. The country's national agricultural regulator enforces deforestation-free sourcing protocols for export eligibility to EU markets. Santos port terminals and the Northern Arc grain corridor via Pará state compete for export origination from interior production belts.
India
The CEA-administered Minimum Support Price regime guarantees wheat and rice procurement from Punjab, Haryana, and Uttar Pradesh smallholders. FSSAI fortification mandates for rice and wheat flour channel subsidized grain into public distribution networks. Hyderabad and Bangalore host emerging agritech clusters deploying satellite-guided crop monitoring for yield prediction services.
China
Henan and Shandong provinces maintain wheat self-sufficiency targets through state reserve procurement at floor prices set by the national grain administration. The Ministry of Ecology and Environment enforces soil pollution controls that restrict heavy metal accumulation in rice cultivation zones. Yangtze River Delta milling centers process imported high-protein wheat for premium noodle and bakery applications.
France
The EFSA enforces mycotoxin thresholds that disqualify lower-grade wheat from milling channels, concentrating premium procurement on Beauce and Picardy growing regions. The EU Farm-to-Fork Strategy mandates fifty percent reduction in synthetic pesticide applications by 2030, accelerating biocontrol adoption. Rouen and Dunkirk port elevators anchor export flows to North African and Middle Eastern destinations.
Grain and Cereal Crop Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon-certified and identity-preserved premium channels. The market structure concentrates around integrated traders with origination networks spanning multiple growing belts and proprietary port terminal access. Three archetypes dominate: diversified agricultural conglomerates with crushing and processing assets, specialized grain traders optimizing ocean freight logistics, and regional cooperatives aggregating smallholder output. Competitive moves center on backward integration into fertilizer and seed inputs, plus multi-year direct contracting with food manufacturers seeking traceability guarantees.
Among North American-based integrated traders, Cargill Incorporated and Archer Daniels Midland exemplify the conglomerate archetype with origination-to-processing footprints. Bunge Limited occupies a position within the South American corridor specialist tier. Louis Dreyfus Company represents the ocean freight optimization archetype, anchoring competitive positioning on terminal control and vessel chartering efficiency.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Bunge Limited |
| Louis Dreyfus Company |
| Archer Daniels Midland |
| CHS Inc. |
| Wilmar International |
| Olam International |
| Seaboard Corporation |
| Scoular Company |
| Others |
Value Network & Pricing Analysis
Agronomic data science talent scarcity in Iowa and Illinois widens the spread between premium identity-preserved contracting and spot-market commodity sales, as labor-intensive traceability protocols inflate handling costs for certified grain tiers.
Pricing Analysis
After-sales service bundling separates full-service origination contracts from stripped-down cash-bid transactions at country elevators. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and protein content, with organic and carbon-certified origins capturing the top tier. Cost compression in the standard tier is intensifying because ammonia and phosphate input volatility squeezes elevator margins on fixed-price forward contracts. Smallholder cooperatives in India exhibit the highest price sensitivity, while craft maltsters and CPG brands with traceability mandates show the least.
Supply Chain Analysis
Skilled elevator operations and grain merchandising labor availability in the US Corn Belt, Brazilian Mato Grosso, and French Beauce regions determines origination efficiency and throughput capacity. The network draws from ammonia fertilizer production clusters, proprietary seed genetics, and ocean freight charter markets. Single-source vulnerability concentrates in Ukrainian Black Sea corridor disruptions that force rerouting through Romanian Constanta. Distribution runs through barge-rail intermodal corridors to export terminals, with direct contracting bypassing spot-market elevators for premium segregated flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around traders with captive port terminal access, as EU carbon border adjustments and deforestation-free sourcing mandates force subscale originators into exit or acquisition.
For Market Incumbents: Acquire regional elevator networks and inland storage assets to lock origination capacity before carbon-certified grain premiums widen further. Integrate backward into fertilizer blending and seed distribution to capture input margin and secure supply loyalty. The EPA's evolving biofuel blending calculus and REACH residue tightening threaten traders without multi-continent origination flexibility.
For New Entrants and Emerging Players: Begin with blockchain-verified identity-preserved contracting for craft brewing and aquafeed segments where traceability premiums offset scale disadvantages. Target West African rice import substitution corridors and Norwegian salmon feed barley markets as penetrable white-space geographies. Lead with subscription-based farm management software bundled with certified seed and biological input packages.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale cooperatives possessing deforestation-free certification and Northern Arc port access given EU procurement policy shifts. Long-term viability hinges on five-to-ten-year carbon market incentive durability and CPG brand direct-contracting expansion. Watch for inflection when Brazilian federal prosecutors accelerate environmental enforcement actions against non-compliant clearing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fertilizer Production | Cargill and ADM captive ammonia sourcing hedges against natural gas volatility compressing grower margins. |
| Carbon Certification Program Deployment | EU Carbon Border Adjustment Mechanism rewards early regenerative tillage adopters with premium market access. |
| Identity-Preserved Supply Agreement | Nestlé and Unilever multi-year contracts lock traceable corn and soybean volumes for deforestation-free claims. |
| Port Terminal Capacity Expansion | Santos and Pará Northern Arc investments compete for Brazilian soybean-corn double-crop export origination. |
| Biological Input Manufacturing Scale-Up | German and French cooperatives expand biocontrol acreage to meet EU Farm-to-Fork pesticide reduction mandates. |
Research Methodology
USDA weekly cash bid reports, EFSA mycotoxin threshold documentation, and Brazilian federal environmental enforcement records formed the secondary backbone for supply and regulatory validation. Primary interviews with grain elevator managers, CPG procurement directors, maltsters, and agritech platform engineers combined with customs trade data and SEC processor filings. Bottom-up acreage and yield estimates triangulated against top-down consumption forecasts from biofuel and feed sector demand models.
Historical trendline analysis of minimum support price regimes, ethanol blending mandate trajectories, and organic certification adoption curves anchored projection assumptions. The modeling framework segmented by crop type, end-use industry, distribution channel, and certification status across the analysis window. CAGRs derived from weighted average of demand elasticity estimates for food processing, animal feed, and biofuel applications, with input from satellite-guided yield prediction service adoption rates.
Corridor disruption recurrence, EU pesticide registration timeline compression, and carbon market incentive durability are the dominant revision risks for forecast accuracy. Forecasts reflect documented assumptions on policy continuity and trade flow stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Wheat Market
Grains
Ancient Grain Market
Grains
Grain Storage Silos Market
Grains
Global Precooked Corn Flour Market
Grains
Black Gram Market
Grains
Grain Bins Market
Grains
Europe Wheat Market
Grains
Sorghum Market
Grains
Quinoa Flour Market
Grains
Millet Flour Market
Grains
Italy Rice Market
Grains
Millets Market
Grains
South America Wheat Market
Grains
Grain Storage Systems Market
Grains
North America Rice Market
Grains
Cameroon Grains Market