
 North America Silage Inoculant Market | 2026-2036
North America Silage Inoculant Market Size, Share, and Industry Trends Forecast 2026-2036
North America Silage Inoculant Market Analytics
Agricultural cooperative procurement is narrowing as dairy operations consolidate feed-purchasing decisions. Cargill, Incorporated leverages its grain-handling infrastructure to bundle inoculant sales with commodity contracts. Lallemand Inc. anchors its position through yeast and bacteria strain specialization. Chr. Hansen A/S sustains R&D intensity across lactic acid bacteria portfolios.
Silage inoculants are live microbial cultures or enzyme preparations applied to chopped forage to accelerate lactic acid fermentation, suppress spoilage organisms, and preserve nutritional value in anaerobic storage. Bacterial inoculants dominate volume as homofermentative strains deliver predictable pH drop, while enzymatic inoculants command premium positioning where fiber digestibility gains justify higher input cost. Dairy silage applications generate the deepest margin pools due to milk-production sensitivity to feed quality.
USDA grading standards and FDA feed ingredient regulations shape product registration pathways and label claims across the United States. EPA biopesticide oversight intersects with certain microbial strain introductions, creating dual-compliance requirements for novel formulations. Canadian Food Inspection Agency protocols add cross-border complexity for suppliers serving Ontario and Quebec dairy markets. Stakeholders must monitor strain patent expirations and conservation-program eligibility criteria to time portfolio adjustments.
Market Dynamics
Dairy consolidation across Wisconsin, Iowa, and Minnesota is compressing procurement timelines and forcing inoculant suppliers to restructure distribution around fewer, larger cooperative buyers with centralized feed-purchasing authority.
Growth Catalysts
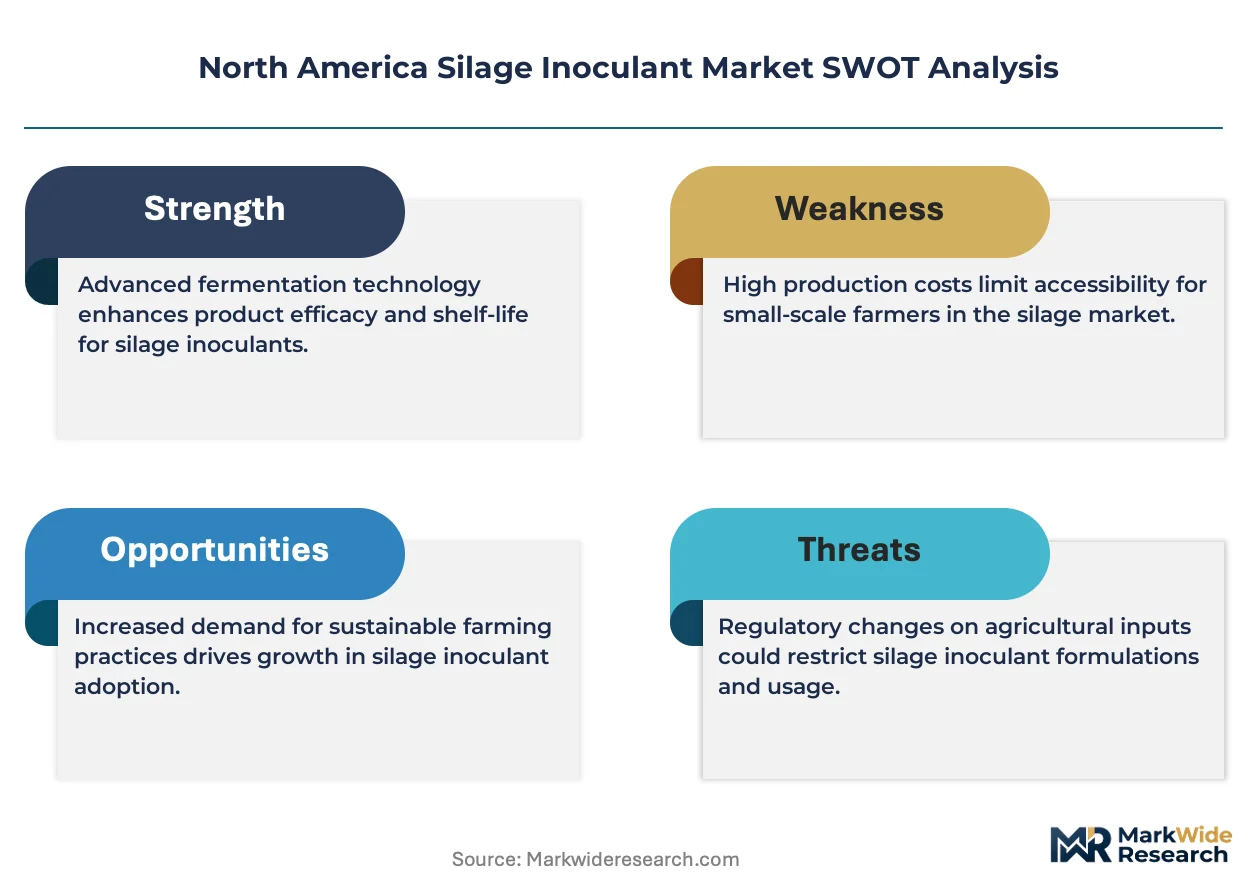
- USDA Conservation Stewardship Program:Cost-share incentives for improved feed management accelerate inoculant adoption among mid-scale dairy operations seeking compliance credits.
- Homofermentative bacterial strains:Predictable pH suppression reduces dry-matter loss and extends bunk life, delivering measurable milk-yield returns that justify input expenditure.
- Great Plains dairy expansion:Greenfield operations in Nebraska and South Dakota specify inoculants in initial facility design, embedding microbial fermentation protocols from startup.
Market Restraints
- Strain development costs:Novel lactic acid bacteria characterization and EPA biopesticide registration impose multi-year R&D cycles that freeze smaller formulators out of premium positioning.
- Canadian cross-border friction:CFIA import protocols and strain-specific approval delays complicate supply coordination for Ontario and Quebec dairy markets served from US production.
- Enzymatic substitute pressure:Fiber-digestibility enzymes from adjacent feed-additive categories compete for the same per-ton forage budget allocation.
Strategic Opportunities
- Underpenetrated Southwest feedlots:Arizona and New Mexico beef operations represent untapped volume as producers there still rely on native fermentation without microbial inoculation.
- Precision agriculture convergence:Integration with chopper-mounted applicators and moisture sensors enables real-time dosing adjustments tied to forage dry-matter content.
- Conservation program stacking:Eligibility for both USDA Environmental Quality Incentives Program and state-level carbon crediting creates compound financial justification for adoption.
Industry Challenges
- Microbiologist talent scarcity:Strain selection and fermentation troubleshooting require specialized expertise that rural feed-supply operations struggle to recruit and retain.
- Dual-registration complexity:EPA biopesticide and FDA feed-ingredient pathways for novel microbial strains extend time-to-market and inflate regulatory compliance headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Silage Inoculant Market |
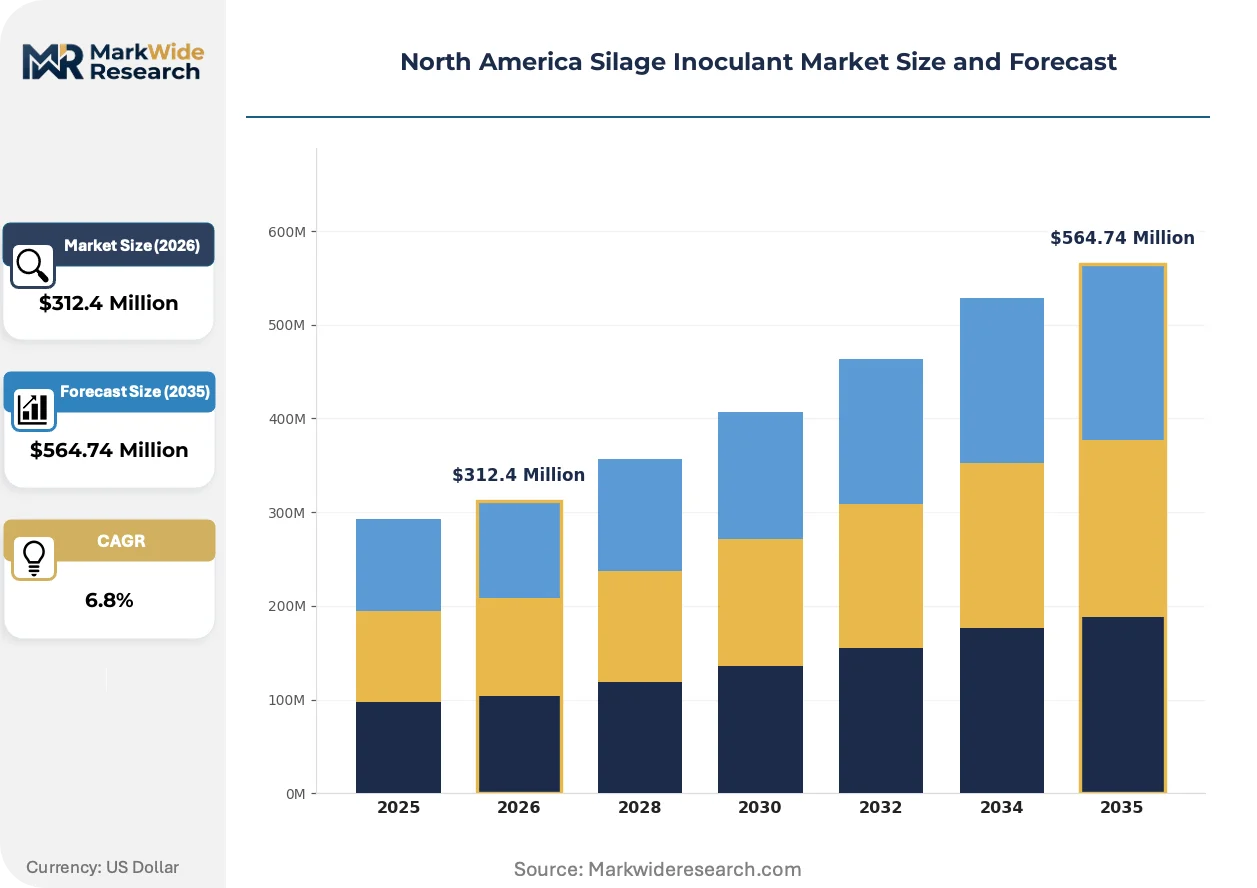
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Inoculants, Enzymatic Inoculants, Chemical Preservatives, Probiotic Cultures Application: Dairy Silage, Beef Silage, Fermented Forages, Environmental Conservation Formulation Type: Liquid Form, Dry Granules, Pelleted Form, Concentrated Solution Distribution Channel: Direct Sales, Distributors, Online Retailers, Agricultural Cooperatives |
| Companies Covered | Chr. Hansen A/S, Kemin Industries, Cargill, Incorporated, Agri-King, Volac International Limited, Archer-Daniels-Midland Company, Lallemand Inc., DuPont, Corteva Agriscience, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Silage Inoculant Market Evolving Landscape
Formulation science and application hardware are converging to enable site-specific inoculation protocols that match bacterial strain selection to real-time forage conditions rather than static crop categories.
Multi-strain bacterial consortia combining homofermentative and heterofermentative species are migrating from research trials to commercial application. Large-scale dairies in Wisconsin and Minnesota are adopting these blends to achieve both rapid pH drop and aerobic stability during feedout. This migration from single-strain to combination products is compressing margins for legacy homofermentative-only suppliers while rewarding R&D-intensive formulators with patent-protected strain combinations.
EPA biopesticide registration requirements for novel microbial strains are tightening labeling and efficacy substantiation standards. The agency now demands field-trial data from multiple growing seasons and geographic zones before approving new strain introductions. Small and mid-sized inoculant suppliers serving the Upper Midwest are responding by licensing existing EPA-registered strains rather than pursuing independent registrations.
Feed-purchasing centralization within consolidated dairy cooperatives is restructuring distribution relationships. Independent nutrition consultants in Iowa and Minnesota are displacing traditional feed-dealer channels as the primary influence point for inoculant specification. This shift concentrates vendor access through fewer professional gatekeepers who bundle inoculant recommendations with total mixed ration formulation services.
North America Silage Inoculant Market Segmentation
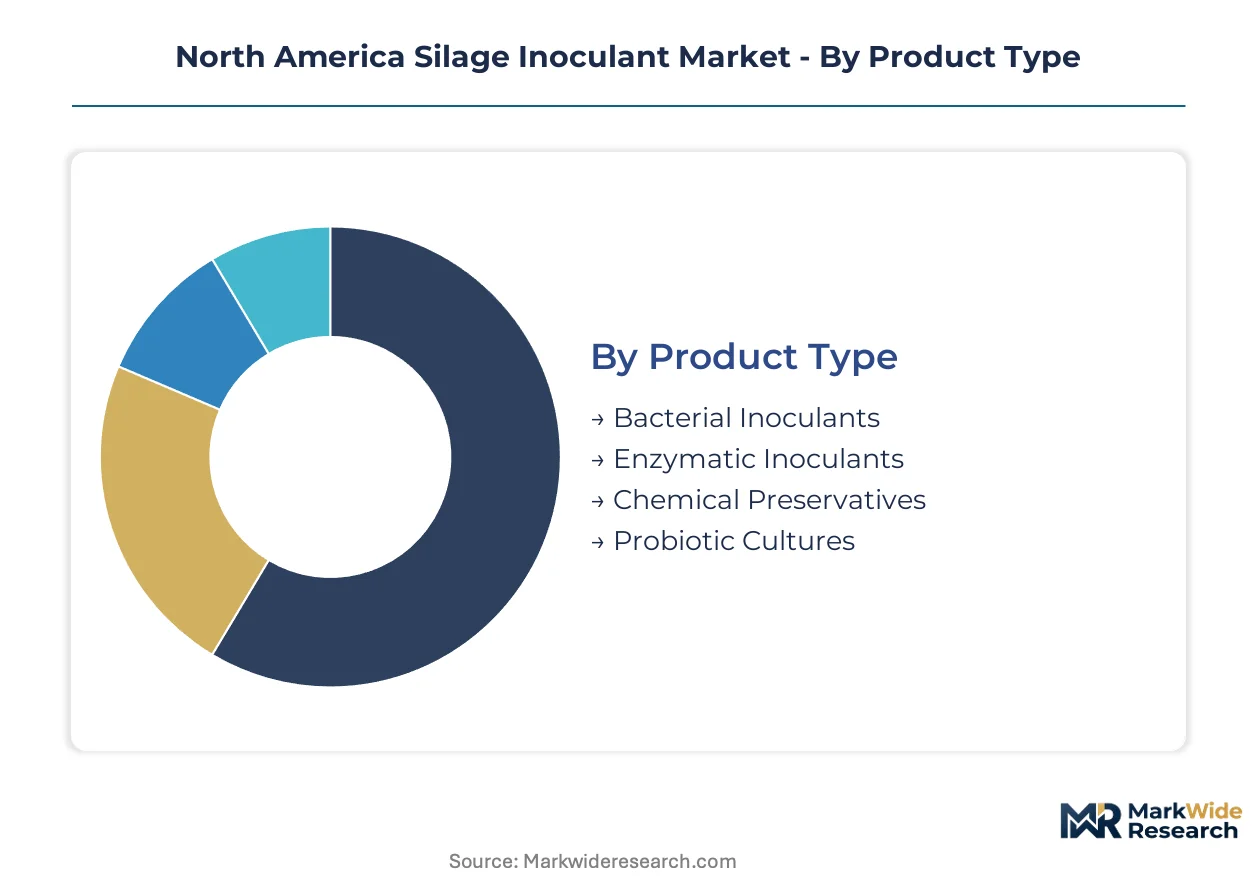
Silage inoculant procurement patterns diverge sharply across product categories, with bacterial formulations demanding intensive fermentation troubleshooting support while enzymatic alternatives require fiber-digestibility validation services. Application context and distribution channel both reshape service intensity requirements and margin structures for suppliers competing across North American dairy regions.
Product Type:
After-sales service intensity varies dramatically by product type, with live bacterial cultures requiring strain-specific technical support for fermentation failure diagnosis and pH optimization protocols.
- Bacterial Inoculants:Live homofermentative and heterofermentative lactic acid bacteria cultures dominate volume due to predictable pH suppression and measurable dry-matter retention. Demand concentrates in Wisconsin and Minnesota large-scale dairies where milk-yield sensitivity to feed quality justifies ongoing technical consultation costs.
- Enzymatic Inoculants:Cellulase and hemicellulase preparations command premium positioning where fiber digestibility gains translate directly to milk production economics. Iowa dairy cooperatives specify these for high-fiber forage blends despite higher per-ton input cost.
- Chemical Preservatives:Organic acid and ammonia-based alternatives serve backup applications when bacterial viability concerns arise during temperature-stressed harvest windows.
- Probiotic Cultures:Direct-fed microbial strains with silage-stage application are gaining traction in Nebraska greenfield operations seeking gut-health continuity from feed to animal.
Bacterial inoculants hold the largest share; momentum sits with enzymatic inoculants as fiber-digestibility premiums justify higher service investment.
Application:
Cost tier differentiation separates commodity beef operations from precision dairy applications, with the latter absorbing three to four times the per-ton inoculant expenditure for measurable production returns.
- Dairy Silage:High-value milk production creates the deepest margin pool for inoculant suppliers, with Wisconsin and Minnesota operations specifying multi-strain consortia for both rapid fermentation and aerobic stability during feedout. USDA Conservation Stewardship Program eligibility accelerates adoption among mid-scale producers seeking compliance credits.
- Beef Silage:Feedlot applications prioritize cost containment over fermentation precision, with Arizona and New Mexico operations representing underpenetrated volume still relying on native fermentation.
- Fermented Forages:Alfalfa and grass silage variants for equine and small ruminant markets occupy niche positioning with specialized moisture-tolerance requirements.
- Environmental Conservation:Manure-management and biogas feedstock applications emerge as regulatory compliance drivers under state-level carbon crediting frameworks.
Dairy silage commands the dominant revenue share; beef silage is expanding most quickly as Great Plains feedlot consolidation creates centralized procurement leverage.
Formulation Type:
Volume concentration favors liquid and dry granular formats that integrate with existing chopper-mounted applicator infrastructure across Midwest harvest operations.
- Liquid Form:Tank-mix compatibility with water-soluble application systems dominates custom harvester specifications. Iowa and Illinois operations favor this format for real-time dosing adjustments tied to forage moisture sensors.
- Dry Granules:Extended shelf stability and ambient storage requirements suit remote cooperative distribution points with limited refrigeration capacity.
- Pelleted Form:Dust-reduced handling characteristics address OSHA respiratory compliance in high-volume mixing facilities.
- Concentrated Solution:Ultra-high potency formats reduce freight cost per active unit for cross-border supply into Ontario and Quebec dairy markets.
Liquid form holds the largest share; concentrated solution is gaining share fastest as Canadian cross-border friction elevates freight efficiency priorities.
Distribution Channel:
Customer-type concentration is restructuring channel economics, with consolidated dairy cooperatives displacing fragmented feed-dealer networks as the primary specification gatekeepers.
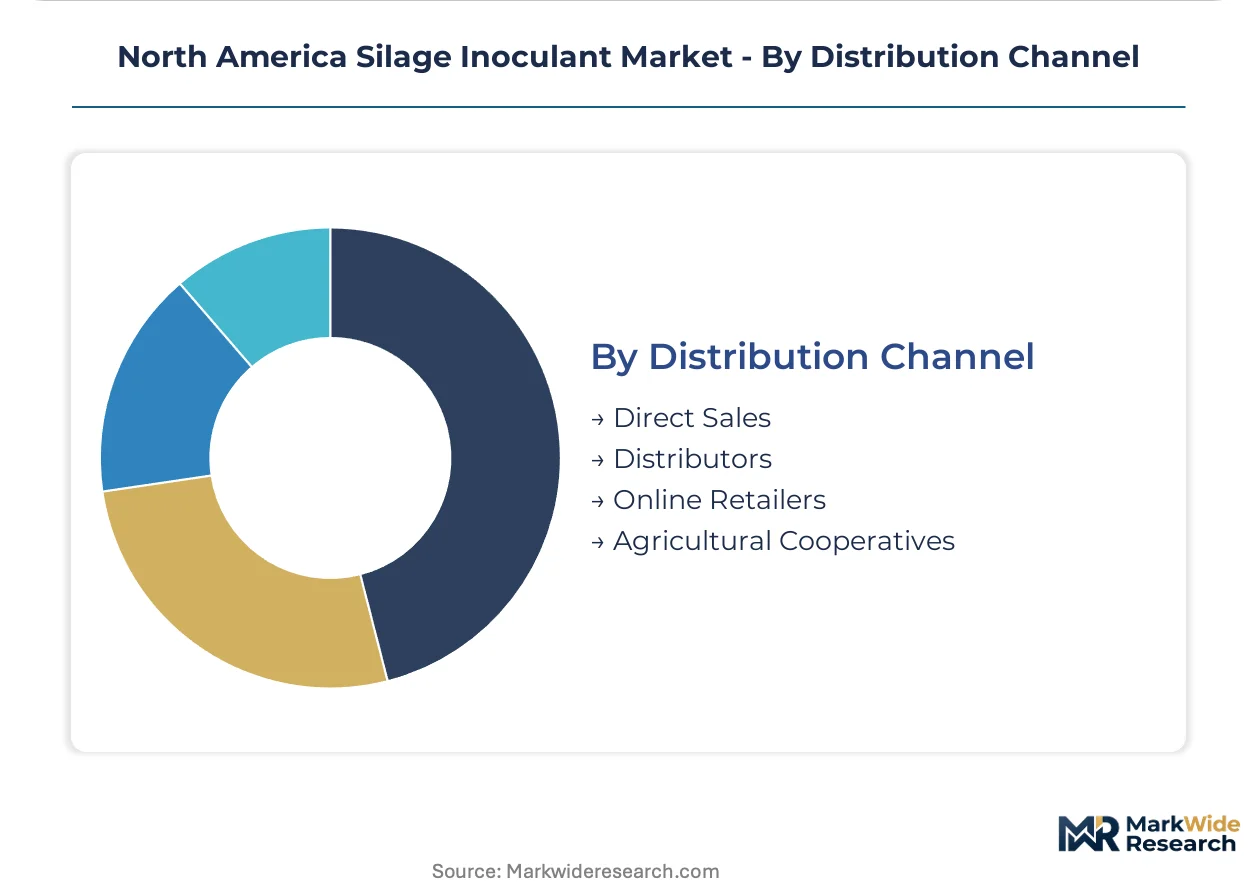
- Direct Sales:Large-scale Wisconsin and Minnesota cooperatives negotiate enterprise contracts bundling inoculant supply with total mixed ration formulation services. Cargill leverages grain-handling infrastructure to integrate microbial products into commodity procurement agreements.
- Distributors:Regional feed-supply operations retain relevance in South Dakota and Nebraska where dairy expansion outpaces cooperative consolidation timelines.
- Online Retailers:E-commerce penetration remains limited by cold-chain requirements for live bacterial products and the technical consultation dependency of effective application.
- Agricultural Cooperatives:Centralized purchasing authority within CHS and Land O'Lakes networks compresses vendor access to fewer professional nutrition consultants who bundle recommendations with herd management services.
Direct sales hold the largest share; agricultural cooperatives are climbing the fastest as dairy consolidation accelerates feed-purchasing centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA conservation programs and FDA feed ingredient regulations anchor market development across the United States, while Canadian Food Inspection Agency protocols create cross-border friction for Ontario and Quebec dairy suppliers. Mexico's expanding feedlot sector introduces emerging demand dynamics distinct from northern dairy concentration.
United States
Midwest dairy consolidation in Wisconsin, Iowa, and Minnesota drives procurement centralization as large-scale cooperatives consolidate feed-purchasing authority. USDA Conservation Stewardship Program cost-share incentives accelerate inoculant adoption among mid-scale producers seeking compliance credits. The Great Lakes dairy corridor anchors technical service infrastructure and strain development activity.
Canada
Ontario and Quebec dairy markets face CFIA import protocol delays and strain-specific approval requirements that complicate supply coordination from US production facilities. Provincial dairy boards maintain strict feed quality standards that favor documented fermentation performance. The St. Lawrence Valley concentration supports specialized distribution networks serving francophone nutrition consultants.
Mexico
Northern feedlot expansion in Chihuahua and Sonora creates emerging volume as beef operations modernize silage storage infrastructure. SENASICA feed safety regulations increasingly align with US FDA frameworks, easing strain registration pathways. Bajío region dairy growth around Guanajuato attracts technical service investment from cross-border suppliers.
North America Silage Inoculant Market Competitive Landscape
Global microbial specialists and integrated grain handlers split the market into distinct capability tiers. Consolidation pressures favor players with captive strain libraries and EPA registration expertise. Three archetypes dominate: R&D-intensive bacterial strain developers, grain-trading conglomerates bundling inoculants with commodity contracts, and regional formulators licensing established microbial platforms. Competitive moves center on conservation program eligibility certification and precision agriculture hardware partnerships.
Within the R&D-intensive tier, Chr. Hansen A/S and Lallemand Inc. exemplify strain specialization strategies, while Cargill, Incorporated represents integrated grain-handler positioning that leverages commodity infrastructure for bundled microbial product distribution. These three anchors illustrate how regulatory compliance depth and distribution scale create divergent competitive moats.
| Leading Market Players |
|---|
| Chr. Hansen A/S |
| Kemin Industries |
| Cargill, Incorporated |
| Agri-King |
| Volac International Limited |
| Archer-Daniels-Midland Company |
| Lallemand Inc. |
| DuPont |
| Corteva Agriscience |
| Others |
Value Network & Pricing Analysis
Overcapacity in liquid bacterial formulation facilities across the Upper Midwest is forcing suppliers to absorb freight costs into delivered pricing, compressing margins for regional distributors serving Iowa and Minnesota dairy cooperatives while rewarding integrated grain handlers with captive logistics networks.
Pricing Analysis
Wisconsin-to-Arizona price spreads for equivalent homofermentative formulations exceed the freight differential alone, reflecting regional service intensity variation. The market operates on a contract-based long-term offtake model where annual volume commitments lock in base pricing, with price differentiation driven by strain patent protection status and bundled technical consultation hours. Cost compression in economy-tier bacterial products is intensifying because licensed generic strains flood the market as original EPA registrations expire. Mid-scale dairy operations in South Dakota exhibit the highest price sensitivity, while large Wisconsin cooperatives prioritize fermentation performance predictability over per-ton input cost.
Supply Chain Analysis
Extended payment terms from consolidated dairy cooperatives are squeezing working capital for independent distributors, forcing reliance on supply-chain finance facilities backed by grain-trading conglomerates. Manufacturing concentrates in the United States, with Canadian production serving Ontario and Quebec markets under CFIA strain approval requirements. Raw material dependencies include specific lactic acid bacteria master cultures, cryoprotectant formulations, and sterile packaging films. Single-source vulnerability around EPA-registered strain licensing creates bottleneck risk for smaller formulators. Distribution runs through agricultural cooperative procurement networks that centralize feed-purchasing authority within fewer professional nutrition consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as dairy herd expansion across the Great Plains restarts silage infrastructure investment paused during consolidation-driven culling periods.
For Market Incumbents: Entrench position by deepening captive strain libraries through exclusive licensing of heterofermentative species combinations, and secure conservation program eligibility certification ahead of USDA Environmental Quality Incentives Program funding cycles. The threat of enzymatic fiber-digestibility substitutes competing for the same per-ton forage budget demands demonstration of measurable milk-yield returns that justify bacterial inoculant expenditure. For New Entrants and Emerging Players: Arizona and New Mexico beef feedlots represent the most penetrable entry point, as these operations still rely on native fermentation without microbial inoculation and lack established supplier relationships. Nebraska greenfield dairy facilities offer secondary white-space opportunity where initial facility design embeds fermentation protocols. The recommended go-to-market angle pairs chopper-mounted applicator hardware partnerships with simplified single-strain formulations that reduce technical support dependency. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EPA biopesticide registration expertise and strain patent portfolios create durable moats that reward scale. Acquisition targets should display captive strain libraries with multi-season field-trial data and existing conservation program eligibility. The signal to watch is CFIA approval timeline compression for US-registered strains, which would unlock cross-border supply efficiency gains and revalue Canadian market access.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Biopesticide Registration Pathway | Multi-season field-trial requirements now demand geographic zone diversity beyond Midwest dairy corridors. |
| Precision Agriculture Hardware Partnership | Chopper-mounted applicator integration enables real-time dosing tied to forage moisture sensors. |
| Conservation Program Eligibility Certification | USDA Environmental Quality Incentives Program stacking creates compound financial justification for adoption. |
| Strain Licensing Agreement | Exclusive heterofermentative species combinations compress margins for generic homofermentative-only competitors. |
| Backward Integration into Master Culture Production | In-house bacterial strain development reduces dependency on third-party EPA-registered platform licenses. |
Research Methodology
Initial hypotheses were tested against primary input from dairy nutrition consultants, cooperative procurement managers, EPA registration specialists, and custom harvester operators and refined through secondary validation against USDA NASS crop reports, FDA feed ingredient filings, CFIA strain approval databases, and state-level carbon crediting program documentation. Bottom-up volume estimates from individual dairy operation specifications were triangulated against top-down segment sizing derived from cooperative purchasing data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application context, formulation format, and distribution channel concentration. CAGRs were computed from normalized baseline values through iterative convergence testing. Industry-specific forecast inputs included dairy herd expansion rates across Great Plains states and conservation program funding allocation trajectories.
Practitioners should monitor EPA biopesticide registration timeline extensions and CFIA cross-border protocol adjustments for early signals of supply constraint or competitive entry acceleration. Forecasts reflect assumptions around dairy consolidation pace and conservation program continuity that could shift with federal appropriation cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
United States Animal Feed Additives Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Forage Inoculants Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
Global Inoculants Market