
 North America Seeds Market | 2026-2036
North America Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
North America Seeds Market Intelligence
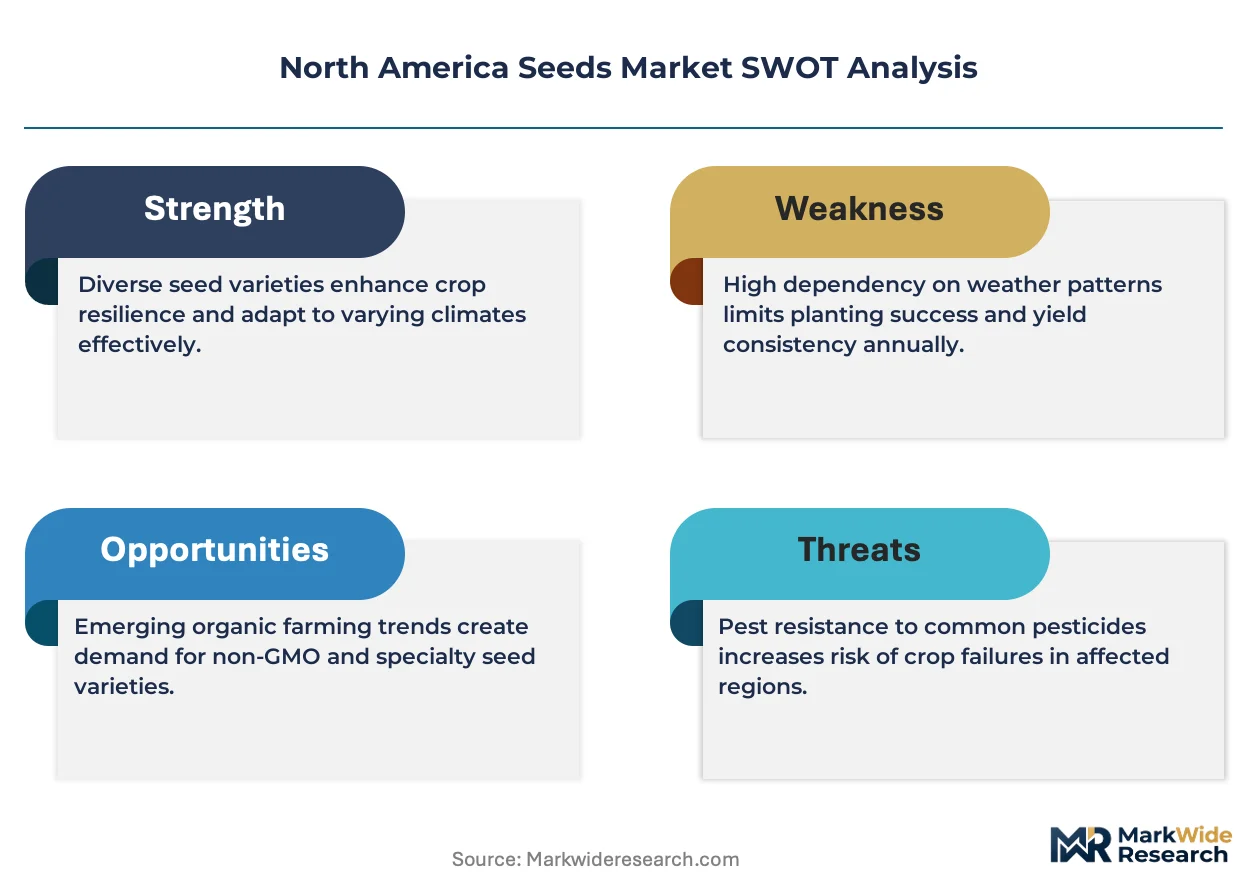
Trait licensing revenue is fragmenting as seed developers diversify beyond single-gene royalty models. Corteva Agriscience leverages its germplasm library to sustain premium positioning in corn and soybean segments. Bayer AG anchors its North American presence through integrated seed-and-crop-protection bundles. Syngenta Group competes on vegetable seed genetics, particularly in protected agriculture systems across Mexico and the southwestern United States.
Seeds are reproductive plant structures containing embryonic tissue, nutrient reserves, and protective coatings engineered for specific germination rates, vigor scores, and trait expression. The North America seeds industry supplies genetically improved planting stock for commercial crop production, with germination percentages and genetic purity standards governed by the Association of Official Seed Certifying Agencies. Oilseeds command substantial margin pools due to crushing demand for protein meal and vegetable oils, while vegetable seeds generate premium pricing through hybrid vigor and disease-resistance stacking. Biological treatment applications are expanding fastest as Canadian and US growers face restrictions on neonicotinoid-based chemical coatings.
The USDA Animal and Plant Health Inspection Service oversees genetically engineered organism release permits, while EPA regulates pesticide-treated articles including chemically coated seeds. Health Canada and the Canadian Food Inspection Agency enforce variety registration requirements that control market access for new cultivars. Stakeholders must monitor evolving state-level pollinator protection statutes and federal biotechnology disclosure rules that could alter seed treatment formulations and labeling obligations.
Market Dynamics
Biological seed treatment formulations are displacing neonicotinoid coatings across US and Canadian row-crop operations, forcing R&D pipeline reallocation and supply chain reconfiguration for major germplasm providers.
Growth Catalysts
- USDA Biotechnology Disclosure Rules:Mandatory labeling for bioengineered food ingredients is accelerating investment in gene-edited cultivars that fall outside regulatory scope, creating faster commercialization pathways for drought-tolerant corn lines.
- Protected Agriculture Expansion:Mexican greenhouse vegetable operations in Sinaloa and Baja California are scaling hybrid tomato and pepper seed purchases, driving demand for climate-adapted genetics with stacked disease resistance.
- Neonicotinoid Restrictions:EPA cancellation orders and Health Canada phase-outs are compelling growers toward biological seed coatings containing Beauveria bassiana and Trichoderma strains, opening premium pricing tiers for treated products.
Market Restraints
- Phosphorus Input Volatility:Fertilizer cost spikes compress operating margins for independent seed dealers who bundle starter fertilizer with treated soybean and corn seed packages.
- Germplasm Concentration:Four proprietary trait platforms control over 85% of North American corn and soybean genetics, limiting price competition and farmer choice in trait licensing negotiations.
- Gene Flow Containment:Pollen drift from genetically engineered crops creates liability exposure for organic operators in the Red River Valley, generating insurance cost inflation and buffer-zone disputes.
Strategic Opportunities
- Canadian Prairie Pulse Expansion:Saskatchewan and Manitoba growers are diversifying from canola into lentils and chickpeas, creating demand for regionally adapted pulse genetics with improved harvestability traits.
- Carbon Credit Integration:USDA Partnerships for Climate-Smart Commodities program creates verified carbon credit pathways for cover crop seed users, embedding seed purchases into sustainability compensation frameworks.
- CRISPR-Native Trait Development:Gene editing convergence with rapid phenotyping platforms is compressing variety development cycles from eight years to four, enabling faster response to emerging pathogen pressures.
Industry Challenges
- Seed Certification Bottlenecks:Canadian Food Inspection Agency variety registration timelines stretch 24-36 months for novel minor crops, delaying market entry for specialty vegetable developers.
- Trait Licensing Complexity:Stacked intellectual property claims across multiple germplasm owners create royalty stacking disputes that fragment breeding program access to foundational genetic tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Seeds Market |
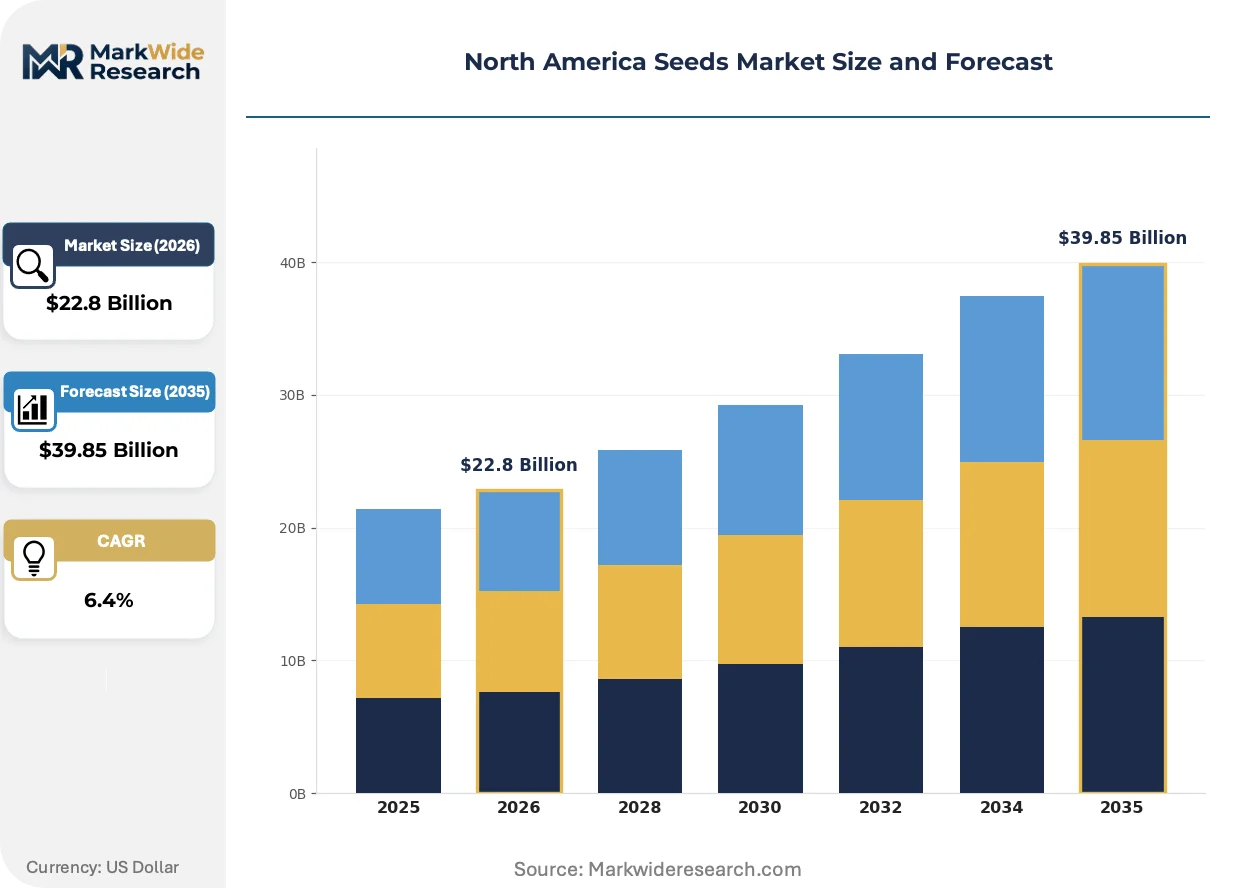
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereal Seeds, Vegetable Seeds, Flower Seeds, Oilseeds Distribution Channel: Wholesale, Retail, Direct Sales, Online Sales End Use Industry: Agriculture, Horticulture, Landscaping, Research Seed Treatment: Chemical Treatment, Biological Treatment, Physical Treatment, Seed Coating |
| Companies Covered | Corteva Agriscience, Bayer AG, Syngenta Group, BASF SE, Land O'Lakes Inc., Advanta Seeds, RiceTec Inc., Florimond Desprez, AgReliant Genetics LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Seeds Market Strategic Shifts & Innovations
Digital phenotyping platforms and biological input integration are restructuring how seed performance is validated, priced, and distributed across North American agricultural supply chains.
Gene editing via CRISPR-Cas9 is virtualizing traditional backcross breeding programs by enabling precise trait insertion without transgenic marker retention. Large-scale corn and soybean operators in Iowa and Illinois are piloting gene-edited drought-tolerance lines at commercial scale. This compression of development timelines is virtualizing the competitive advantage of legacy germplasm libraries built over decades of conventional breeding.
EPA's Endangered Species Act biological opinions for neonicotinoid pesticides are mandating expanded buffer zones and seasonal application restrictions for treated seeds. Seed treatment facilities in Minnesota and North Dakota face capital expenditure requirements for containment infrastructure and runoff mitigation systems. Vegetable seed distributors in California's Central Valley are accelerating transitions to biological alternatives ahead of state pollinator protection mandates.
Direct-to-farm digital platforms are disintermediating traditional cooperative distribution channels for specialty crop genetics. Smaller vegetable growers in the Pacific Northwest are purchasing hybrid pepper and lettuce seeds through manufacturer-branded e-commerce portals with field-specific planting recommendations. This channel compression is most pronounced among organic-certified operations seeking transparent supply chain documentation for certification compliance.
North America Seeds Market Segmentation
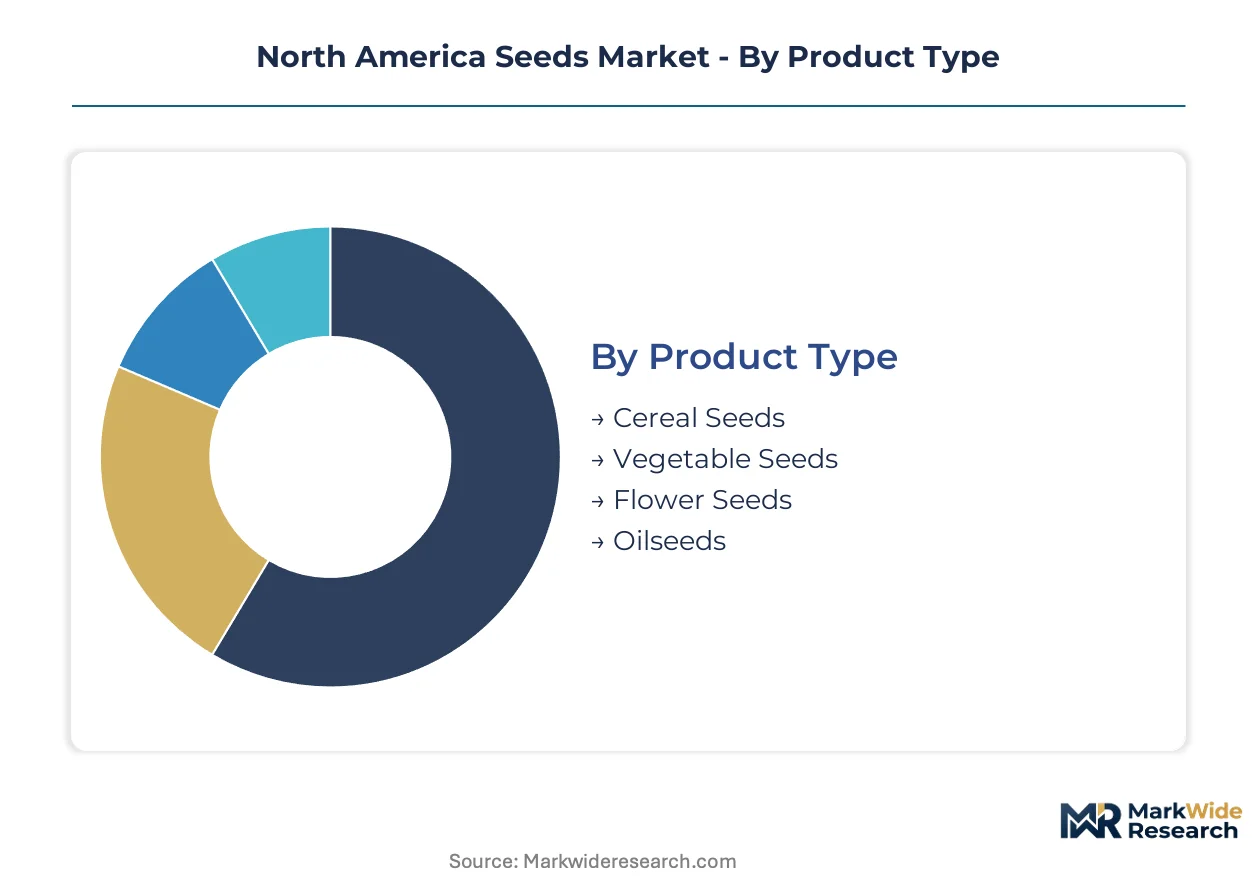
Seed purchasing decisions in North America fragment across crop type, distribution channel, and treatment technology, with each segment demanding distinct technical support and agronomic consultation intensity. Understanding these divisions reveals where margin pools concentrate and which customer relationships require sustained field-service investment.
Product Type:
After-sales agronomic support intensity varies dramatically by crop complexity, with vegetable seed users demanding season-long technical consultation while commodity grain operators prioritize logistics reliability.
- Vegetable Seeds:Hybrid cultivars with stacked disease-resistance traits require intensive grower support through transplanting and harvest windows. Protected agriculture operations in California's Central Valley and Mexican greenhouse clusters in Sinaloa drive demand for climate-adapted pepper and tomato genetics with precision germination specifications.
- Oilseeds:Canola and soybean germplasm with herbicide-tolerance traits dominates acreage in Canadian prairie provinces and the US Corn Belt, where crushing demand for protein meal and vegetable oils sustains premium pricing tiers for certified seed with guaranteed oil content profiles.
- Cereal Seeds:Wheat and corn varieties with drought-tolerance genetics serve large-scale row-crop operations across Iowa, Illinois, and the Dakotas.
- Flower Seeds:Ornamental varieties target commercial landscaping contractors and retail garden centers with lower technical service requirements.
By volume, cereal seeds lead. By growth pace, vegetable seeds are climbing the fastest.
Distribution Channel:
Channel selection in this market tracks farm scale and crop specialization, with commodity producers favoring volume-efficient wholesale routes while specialty growers seek direct breeding-program access.
- Wholesale:Cooperative and independent dealer networks aggregate purchasing power for corn and soybean growers across the Corn Belt, bundling seed with starter fertilizer and crop protection products through seasonal financing programs.
- Direct Sales:Large-scale vegetable operations in the Pacific Northwest and research institutions negotiate proprietary germplasm access and custom trait-stacking agreements directly with breeding companies, bypassing traditional distribution markups.
- Retail:Farm supply stores and garden centers serve hobby farmers and residential landscaping customers with packaged seed and basic agronomic guidance.
- Online Sales:Manufacturer-branded e-commerce portals are gaining traction among organic-certified specialty crop growers seeking transparent supply chain documentation.
Wholesale channels still capture the greatest transaction volume. Direct sales are expanding most quickly as digital platforms compress information asymmetries.
End Use Industry:
Application context determines seed specification rigor, with commercial agriculture demanding certified genetic purity while research applications prioritize experimental trait diversity.
- Agriculture:Commercial crop production consumes the majority of certified seed volume, with germplasm performance validated through Association of Official Seed Certifying Agencies standards and state-level seed law enforcement.
- Horticulture:Nursery operations and greenhouse producers in Florida and British Columbia require vegetable and ornamental varieties with specific maturity windows and post-harvest handling characteristics.
- Landscaping:Turf grass and wildflower seed mixtures serve municipal parks departments and commercial property managers with lower genetic purity requirements than food crop applications.
- Research:University breeding programs and biotechnology firms source foundation seed and genetic stocks for trait development and variety testing under USDA and Canadian Food Inspection Agency permits.
Agriculture dominates absolute consumption. Horticulture is gaining share fastest as protected vegetable production scales.
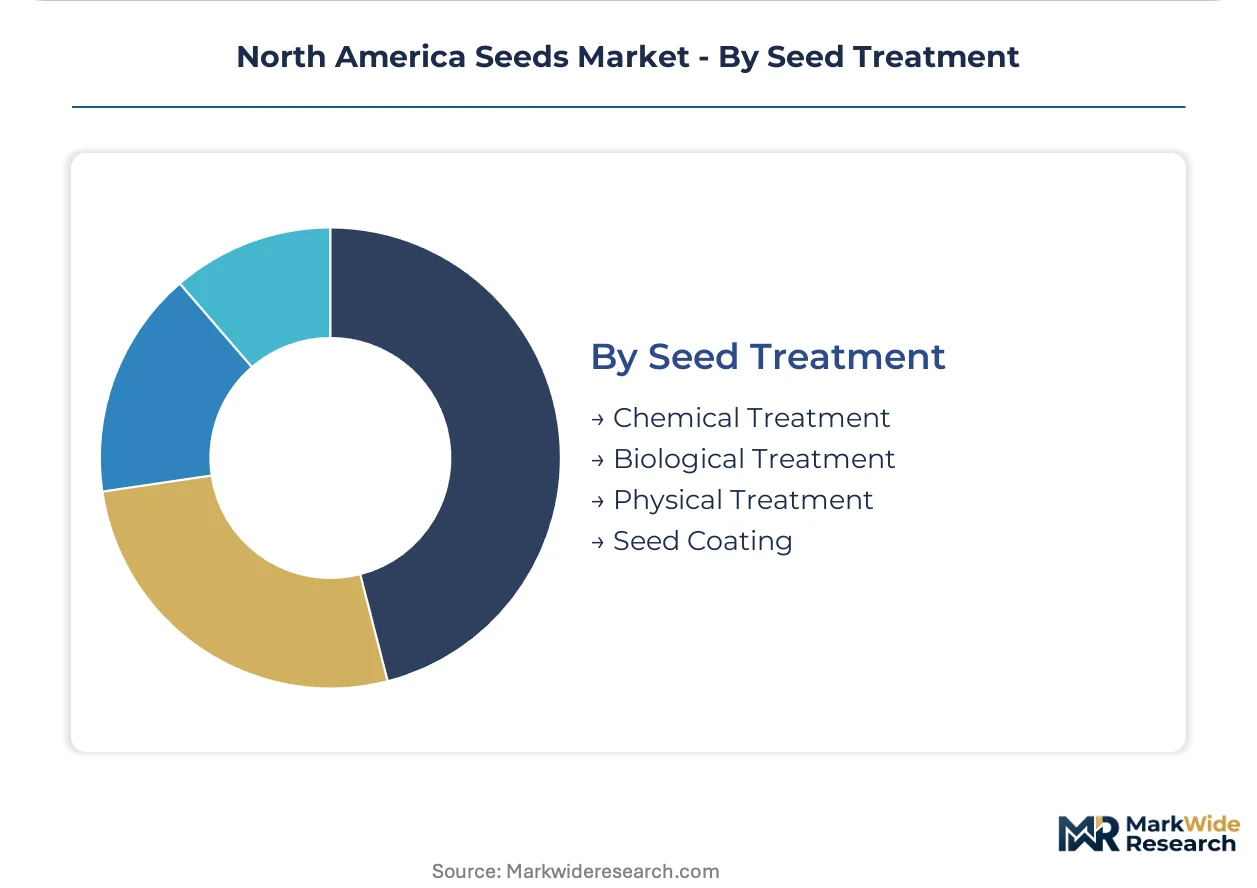
Seed Treatment:
Regulatory pressure on chemistries is restructuring treatment technology adoption, with biological alternatives commanding technical service premiums as growers navigate unfamiliar application protocols.
- Biological Treatment:Formulations containing Beauveria bassiana and Trichoderma strains are displacing neonicotinoid coatings across US and Canadian row-crop operations, requiring grower education on storage conditions and application timing to maintain viable microbial populations.
- Chemical Treatment:Traditional fungicide and insecticide seed coatings face EPA cancellation orders and Health Canada phase-out timelines, compressing remaining market availability for conventional treatment services.
- Physical Treatment:Thermal and plasma processing methods enhance seed vigor without chemical residues, appealing to organic-certified operations.
- Seed Coating:Polymer and nutrient-based coatings improve plantability and early-season nutrition, particularly for small-seeded vegetable crops.
Chemical treatment still handles the greatest volume. Biological treatment is expanding most steeply as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seed buyers in the Canadian prairies exhibit the highest price elasticity, deferring certified seed purchases when commodity prices compress margins. US Corn Belt operators demonstrate lower elasticity, locking in traited genetics regardless of near-term crop receipts. Mexican protected agriculture producers show intermediate sensitivity, trading up for disease-resistant hybrids during favorable growing seasons.
United States
Iowa and Illinois corn operators drive volume demand for drought-tolerance genetics, while California specialty crop growers prioritize disease-stacking traits. EPA cancellation orders on neonicotinoid coatings are accelerating biological treatment adoption across Minnesota and North Dakota seed facilities. The Red River Valley faces escalating buffer-zone disputes as pollen drift from genetically engineered crops generates liability exposure for organic operators.
Canada
Saskatchewan and Manitoba growers are diversifying from canola into lentils and chickpeas, creating demand for regionally adapted pulse genetics. Health Canada and the Canadian Food Inspection Agency enforce variety registration timelines stretching 24-36 months for novel minor crops. Prairie seed dealers face compressed margins as fertilizer cost spikes disrupt traditional bundling of starter inputs with treated soybean packages.
Mexico
Greenhouse vegetable operations in Sinaloa and Baja California are scaling hybrid tomato and pepper seed purchases. The country's national agricultural regulator oversees phytosanitary import requirements that shape cross-border germplasm flows. Protected agriculture clusters in central Mexico are demanding climate-adapted genetics with precision germination specifications for year-round production cycles.
North America Seeds Market Key Industry Players
Integrated agrochemical-seed bundles and germplasm-specialist independents split the market between volume-driven commodity platforms and precision-positioned niche genetics. Four proprietary trait platforms control over 85% of corn and soybean genetics, producing consolidated pricing power in row-crop segments. Strategic archetypes include diversified life-science conglomerates, farmer-owned cooperatives, and regional breeding specialists. Dominant competitive moves center on trait licensing diversification beyond single-gene royalty models and direct-to-farm digital platform deployment.
Among diversified life-science conglomerates, Bayer AG and BASF SE exemplify the integrated bundle archetype, combining germplasm access with crop protection portfolios. Corteva Agriscience occupies a distinct position leveraging germplasm library depth to sustain premium positioning in corn and soybean segments. Syngenta Group represents the specialty crop vector, competing on vegetable seed genetics particularly in protected agriculture systems. These three anchors illustrate how scale, specialization, and integration depth define competitive positioning across commodity and specialty crop segments.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Bayer AG |
| Syngenta Group |
| BASF SE |
| Land O'Lakes Inc. |
| Advanta Seeds |
| RiceTec Inc. |
| Florimond Desprez |
| AgReliant Genetics LLC |
| Others |
Cost & Logistics Intelligence
Proprietary trait platform concentration in Iowa and Illinois germplasm development centers concentrates upstream pricing power among four dominant licensors, compressing margin pools for independent seed dealers who bundle starter fertilizer and crop protection downstream.
Pricing Analysis
After-sales agronomic support revenue drives lifetime value across vegetable seed tiers, where hybrid pepper and tomato genetics command premium positioning through season-long technical consultation. Three-tier pricing structure across premium, standard, and economy levels separates certified disease-stacked cultivars from foundation seed and farm-saved alternatives. Cost compression in commodity grain segments is intensifying because fertilizer input volatility disrupts traditional bundling economics. Canadian prairie growers exhibit highest price elasticity, deferring certified purchases during commodity downturns, while US Corn Belt operators lock in traited genetics regardless of near-term crop receipts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for soybean and corn germplasm flows, particularly for genetic stocks and laboratory equipment inputs. Manufacturing concentration clusters in the United States, Canada, and Mexico, with foundation seed multiplication anchored in Idaho, Oregon, and the Canadian prairies. Raw material dependencies center on phosphorus-based fertilizer coatings, polymer seed treatments, and biological inoculant substrates. Single-source vulnerability persists for CRISPR reagent supplies and specialized phenotyping sensors. Distribution runs through cooperative dealer networks for commodity grains and direct manufacturer portals for specialty vegetable genetics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-farm digital platforms are reconfiguring this market toward platform-economics dynamics, with interoperability between seed performance data and farm management information systems becoming the critical ecosystem battleground.
For Market Incumbents: Insulate germplasm library value through accelerated gene-edited trait pipelines that compress development cycles below competitor reach. Deepen field-service infrastructure in California's Central Valley and Mexican protected agriculture clusters to defend against biological seed treatment specialists. Prioritize backward integration into microbial inoculant production to capture margin migrating from chemical coatings. For New Entrants and Emerging Players: Saskatchewan and Manitoba pulse crop diversification represents the most penetrable white-space opportunity, with lentil and chickpea genetics underserved by established canola-focused incumbents. Target organic-certified vegetable operations in the Pacific Northwest through transparent supply chain documentation and field-specific planting recommendation engines. Deploy manufacturer-branded e-commerce portals with integrated agronomic consultation to bypass cooperative distribution gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional breeding specialists holding regionally adapted pulse and specialty crop germplasm. Long-term viability hinges on gene editing capability convergence with rapid phenotyping infrastructure. Monitor EPA neonicotinoid enforcement actions as the signal indicating acceleration timelines for biological treatment market capture.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Seed Treatment Manufacturing Scale-Up | EPA cancellation orders on neonicotinoids are compressing chemical coating availability windows across Minnesota and North Dakota facilities. |
| Gene-Edited Trait Pipeline Acceleration | CRISPR-native development cycles halve time-to-market for drought-tolerant corn lines in Iowa and Illinois. |
| Direct-to-Farm Digital Platform Deployment | Manufacturer-branded e-commerce portals disintermediate cooperative channels for organic-certified Pacific Northwest vegetable growers. |
| Canadian Prairie Pulse Genetics Expansion | Saskatchewan and Manitoba diversification from canola creates demand for regionally adapted lentil and chickpea cultivars. |
| Carbon Credit Integration Partnership | USDA Climate-Smart Commodities program embeds cover crop seed purchases into verified sustainability compensation frameworks. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with seed company R&D directors, cooperative procurement managers, and specialty crop growers, alongside secondary validation through USDA APHIS permit databases, EPA pesticide registration records, and Canadian Food Inspection Agency variety registration filings. Stakeholder input from biological treatment facility operators and greenhouse producers in Sinaloa supplemented commodity grain perspectives. Bottom-up acreage and pricing estimates triangulated against top-down germplasm licensing revenue assessments.
Forecast inputs considered trait penetration curves, regulatory phase-out timelines, and protected agriculture expansion rates across the projection horizon. Segmentation dimensions modeled include crop type complexity, distribution channel structure, end-use application rigor, and treatment technology regulatory status. CAGRs derived from historical certified seed adoption patterns and projected gene-edited cultivar commercialization velocities. Industry-specific inputs incorporated neonicotinoid restriction implementation schedules and carbon credit program enrollment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by gene-editing specialists or biological input platforms would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Flax Crop Market
Seeds
Americas Seeds Market
Seeds
Russia Seed Market
Seeds
Flax Seed Market
Seeds
South America Seed Market
Seeds
Organic Chia Seeds Market
Seeds
Global Alfalfa Seed Market
Seeds
Commercial Seed Market
Seeds
North America Vegetable Seed Market
Seeds
Africa Vegetable Seed Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
North America Chia Seeds Market
Seeds
Europe Sesame Seed Market
Seeds
Global Rice Seed Market
Seeds
United States Vegetable Seed Market
Seeds
Safflower Seeds Market