
 Organic Rice Flour Market | 2026-2036
Organic Rice Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Rice Flour Market Outlook
Gluten-free bakery demand is restructuring how food manufacturers source starch alternatives across Europe and North America. Bob's Red Mill Natural Foods leverages its vertically integrated milling infrastructure to control organic grain procurement from Pacific Northwest growers. Ingredion Incorporated anchors its ingredient portfolio through specialized rice starch extrusion capabilities serving multinational bakery clients. Archer Daniels Midland Company competes via global origination networks that secure organic paddy from Thai and Indian contract farming collectives.
Organic rice flour consists of finely milled endosperm and bran fractions from Oryza sativa cultivated without synthetic pesticides or petrochemical fertilizers, with particle size distributions typically ranging from 80 to 200 mesh depending on wet-milling or dry-milling process parameters. Its primary commercial purpose centers on providing clean-label viscosity, binding, and browning functionality in gluten-free formulations where wheat starch exclusion is mandatory. Brown rice flour commands structural priority in health-positioned baking segments due to retained aleurone layer fiber and micronutrient density that supports premium shelf placement. White rice flour dominates volume throughput in conventional gluten-free bread and snack manufacturing where neutral flavor and light coloration prove essential. Glutinous rice flour occupies specialized positioning within Asian confectionery and brewing applications where amylopectin-driven gelation creates distinctive textural signatures unavailable from conventional cereal starches.
USDA Organic certification under the National Organic Program governs input restrictions and traceability documentation for United States market access, while EU Organic Regulation 2018/848 mandates equivalent compliance thresholds for European import eligibility. Japan's Agricultural Standards and JAS organic seal requirements impose additional residue testing protocols that filter supplier qualification at the port-of-entry level. Stakeholders must monitor evolving equivalence agreements between major certifying jurisdictions to anticipate supply disruption risks and reposition sourcing relationships accordingly.
Market Dynamics
Clean-label formulation mandates from major retailers are forcing gluten-free manufacturers to abandon modified starches in favor of single-ingredient rice flour solutions, compressing formulation windows and tightening supplier qualification timelines.
Growth Catalysts
- EU Organic Regulation 2018/848:Certification harmonization across member states is streamlining cross-border ingredient procurement for multinational bakery chains, reducing duplicate audit burdens.
- Amylopectin extraction advances:Wet-milling process refinements are expanding glutinous rice flour functionality into Western confectionery applications previously dominated by corn syrup solids.
- Japan's JAS organic seal adoption:Premium packaged food exporters are securing port-of-entry clearance advantages by pre-qualifying mills against residue testing protocols.
Market Restraints
- Organic paddy input volatility:Contract farming collectives in Thailand and India face climate-driven yield fluctuations that transmit directly to flour pricing.
- USDA Organic transition period:Three-year field conversion requirements lock conventional growers out of premium markets regardless of immediate compliance investment.
- Tapioca starch substitution:Cost-sensitive snack manufacturers are reformulating with cassava-derived alternatives where texture tolerance permits.
Strategic Opportunities
- Brazilian bakery expansion:ANVISA's updated gluten-free labeling standards are creating first-mover advantages for certified organic rice flour suppliers.
- Pulse-flour blending:Protein-fortified hybrid formulations combining rice and lentil fractions are penetrating sports nutrition bar segments.
- Direct-to-manufacturer platforms:Digital procurement channels are disintermediating traditional ingredient distributors for mid-scale organic certified buyers.
Industry Challenges
- Cross-contamination protocols:Shared milling infrastructure requires batch segregation systems that extend equipment downtime between conventional and organic runs.
- Equivalence agreement tracking:Millers must monitor bilateral organic recognition pacts between USDA, EU Commission, and Japan's MAFF to anticipate sudden sourcing disqualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Rice Flour Market |
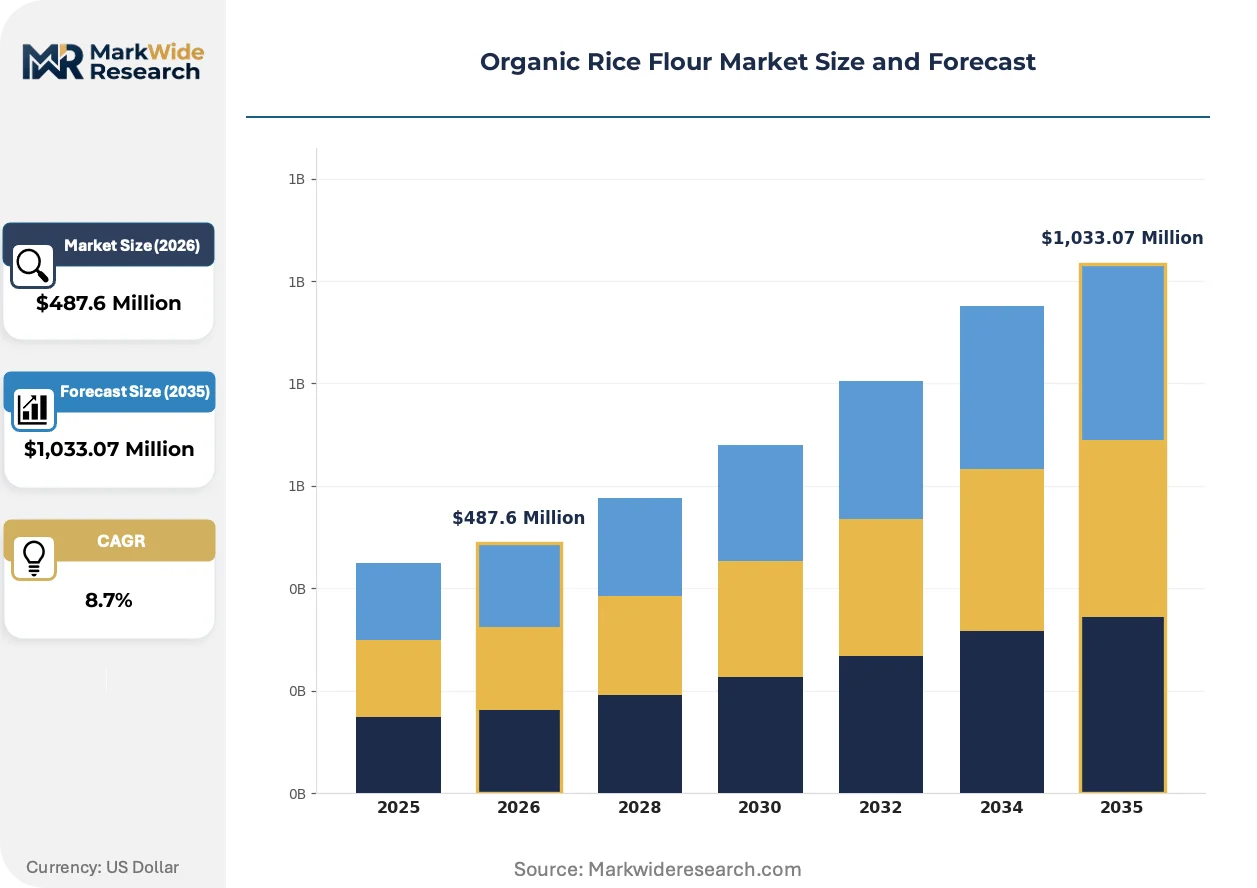
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice Flour, Brown Rice Flour, Glutinous Rice Flour, Wild Rice Flour End Use: Baking, Brewing, Snacks, Baby Food Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales Packaging Type: Bags, Boxes, Bulk Containers, Sachets |
| Companies Covered | Bob's Red Mill Natural Foods, Ingredion Incorporated, Archer Daniels Midland Company, Shipton Mill Ltd, Ebro Foods, Wilmar International Limited, Ardent Mills LLC, BENEO, Nature Bio-Foods Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Rice Flour Market Strategic Shifts
Processing technology convergence and certification digitization are compressing supplier qualification cycles while expanding addressable formulation spaces for rice-derived ingredients.
Extrusion-cooked pregelatinized rice flour is rewriting viscosity control standards in no-bake snack bar manufacturing. Clean-label confectionery developers at mid-scale North American co-manufacturers are adopting the material at pace to eliminate hydration steps. The technology is rewriting production economics by reducing energy inputs and enabling room-temperature processing lines.
REACH chemical registration requirements for imported grain processing aids are tightening documentation burdens on Asian millers serving European buyers. Industrial consequence includes accelerated migration toward EU-based toll processing arrangements. Brown rice flour fractions face heightened scrutiny due to bran oil content triggering substance volume threshold calculations.
Retailer-driven specification consolidation is concentrating buyer power among three North American grocery chains that now mandate dual USDA-EU organic certification for private label placement. Direct supplier relationships are displacing traditional broker networks for volume commitments above container-load thresholds. Germany's discounter channel exhibits the most aggressive consolidation timeline, with reformulation deadlines compressing to eighteen-month windows.
Organic Rice Flour Market Segmentation
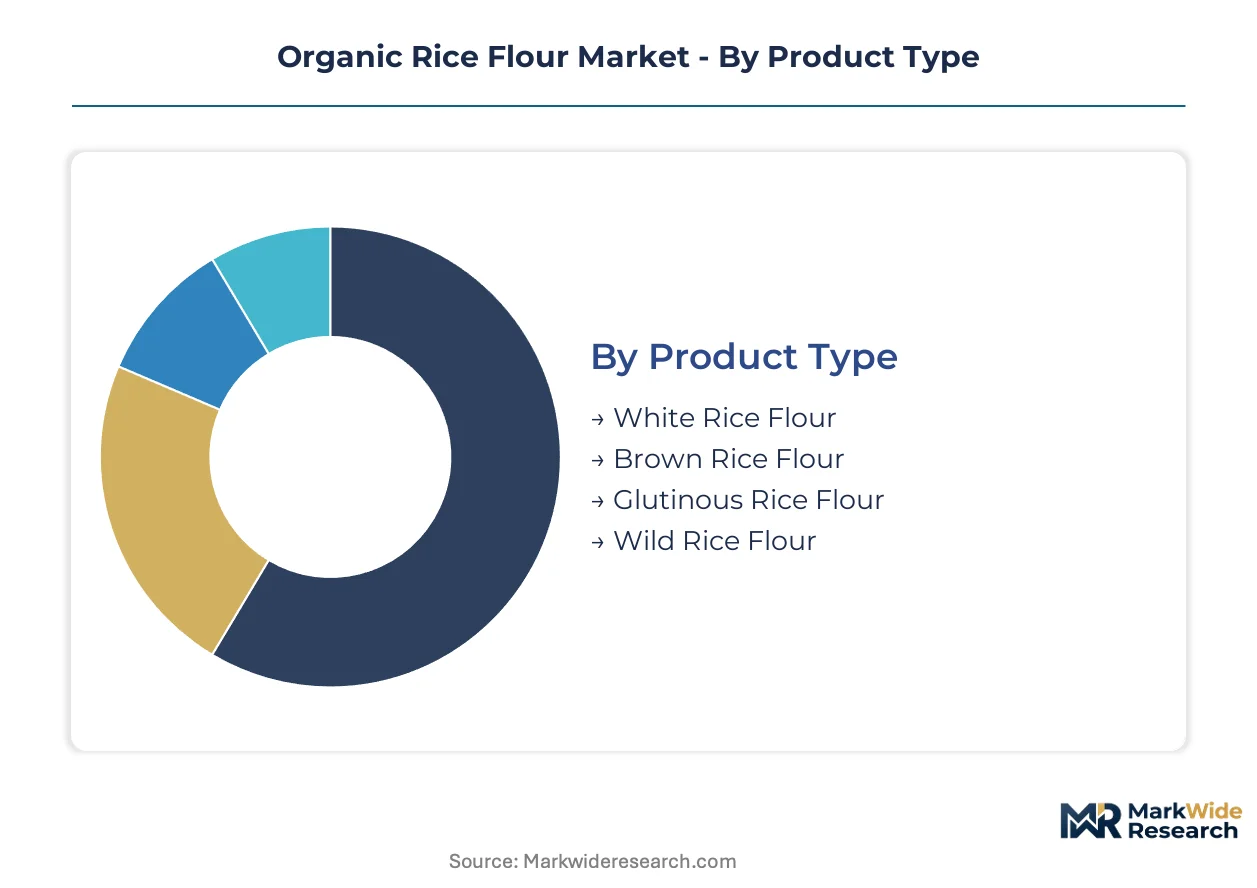
Organic rice flour segmentation reflects divergent buyer priorities across formulation functionality, certification requirements, and procurement scale. Manufacturers configure sourcing strategies around end-use viscosity demands and retail channel compliance thresholds.
Product Type:
Formulation engineers select flour grades based on amylose-amylopectin ratios and particle size distributions that determine hydration behavior.
- White Rice Flour:Milled endosperm with bran and germ removed yields neutral flavor profiles and light coloration. Gluten-free bread manufacturers in the United States specify 100-140 mesh particle sizes for consistent crumb structure in high-volume automated lines.
- Brown Rice Flour:Whole-grain milling retains aleurone layer fiber and lipid fractions. Clean-label bakery positioning in Germany drives specification for stabilized bran content to prevent rancidity during extended shelf life requirements.
- Glutinous Rice Flour:Waxy cultivar starch enables thermoreversible gelation. Asian confectionery applications and Western mochi-style snack innovation create specialized procurement channels.
- Wild Rice Flour:Zizania palustris grain offers distinct nutty flavor and higher protein content. Niche organic positioning supports premium pricing in specialty health food segments.
White rice flour leads on scale; glutinous rice flour leads on momentum.
End Use:
Application-specific functionality requirements determine certification tier and supplier qualification intensity.
- Baking:Viscosity modulation and Maillard browning control dominate formulation specifications. Industrial gluten-free bread operations demand lot-to-lot consistency in water absorption indices.
- Brewing:Saccharification enzyme compatibility and fermentable sugar profiles guide selection. Craft sake producers in Japan specify organic JAS-certified milled rice for traditional koji propagation.
- Snacks:Extrusion stability and oil absorption rates determine flour blend ratios. Puffed and baked snack manufacturers optimize for expansion volume and texture crispness.
- Baby Food:Residue testing protocols and heavy metal screening impose the strictest supplier qualification. Infant nutrition brands require documentary evidence of arsenic mitigation through sourcing region selection.
Baking commands volume concentration; baby food commands margin premium.
Distribution Channel:
Channel selection reflects order scale, certification documentation needs, and buyer technical service requirements.
- Online Retail:E-commerce platforms serve small-batch artisan producers and direct-to-consumer organic brands with fragmented SKU demands.
- Supermarkets:Mass-market grocery chains consolidate procurement through approved supplier lists with dual USDA-EU organic certification mandates.
- Health Food Stores:Independent retailers emphasize local sourcing narratives and specialty grain provenance storytelling for consumer differentiation.
- Direct Sales:Large-scale manufacturers bypass intermediaries for container-load commitments, securing volume pricing and customized milling specifications.
Supermarkets anchor throughput volume; direct sales anchors contract value.
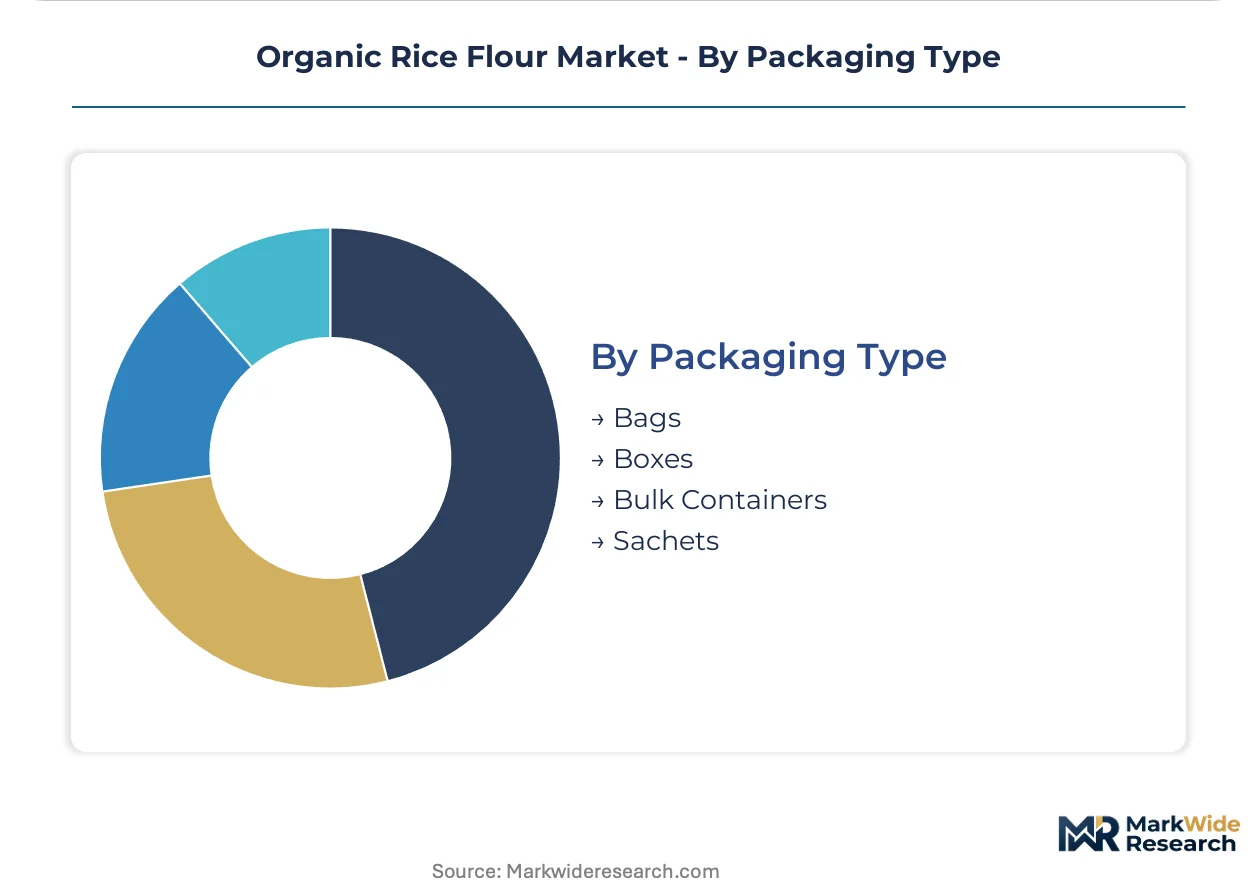
Packaging Type:
Packaging configuration aligns with contamination risk management, inventory velocity, and retail format requirements.
- Bags:Multi-layer paper-plastic laminates dominate mid-scale bakery procurement with 10-25 kg formats balancing handling efficiency and shelf stability.
- Boxes:Corrugated containment with inner liners supports retail-ready presentation for premium organic brands in grocery channels.
- Bulk Containers:Food-grade totes and silo deliveries minimize unit costs for industrial manufacturers with dedicated organic handling infrastructure.
- Sachets:Single-serve portions target foodservice trial sizes and consumer convenience formats in specialty retail.
Bulk containers dominate industrial procurement; bags dominate commercial bakery procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are reshaping organic rice flour sourcing as Thai and Indian millers absorb EU REACH compliance costs while US and Japanese buyers seek dual-certified supply. Production gravity shifts toward jurisdictions with streamlined organic equivalence agreements.
United States
Clean-label bakery demand from gluten-free manufacturers in California and Oregon drives specification tightening. USDA National Organic Program enforcement intensifies traceability audits for Pacific Northwest milling operations. Minneapolis-St. Paul anchors industrial procurement through vertically integrated grain handlers serving national bread brands.
Germany
Discounter channel consolidation forces eighteen-month reformulation deadlines for private-label gluten-free lines. EU Organic Regulation 2018/848 harmonization reduces duplicate certification burdens for mills supplying cross-border bakery chains. Hamburg and Bremen harbor specialized organic grain trading houses that pre-qualify Asian suppliers for port-of-entry compliance.
Japan
Premium packaged food exporters prioritize JAS organic seal pre-qualification to secure customs clearance advantages. Ministry of Agriculture, Forestry and Fisheries residue testing protocols filter supplier qualification at entry ports. Kobe and Osaka concentrate craft sake milling operations demanding traditional koji-compatible organic rice specifications.
Thailand
Contract farming collectives face climate-driven yield volatility that transmits directly to export flour pricing. Organic agriculture promotion programs struggle with three-year field conversion barriers locking conventional growers out of premium markets. Bangkok and surrounding central plains host wet-milling facilities serving EU and US gluten-free manufacturers.
Brazil
ANVISA updated gluten-free labeling standards create first-mover positioning for certified organic rice flour suppliers. Bakery sector expansion in São Paulo and Minas Gerais drives demand for clean-label starch alternatives. Southern rice-growing regions near Rio Grande do Sul develop organic paddy capacity to serve domestic millers and reduce import dependency.
Organic Rice Flour Market Competitive Environment
Capacity expansion dominates the current landscape as specialized millers retrofit conventional lines for organic batch segregation. The vendor base stratifies across three tiers: multinational grain traders with global origination networks, regional organic specialists with captive farm relationships, and commodity millers seeking certification upgrade. Two strategic archetypes predominate: vertically integrated handlers controlling Pacific Northwest organic grain flows, and Asian toll processors leveraging EU-based partnerships to circumvent REACH documentation burdens. Competitive intensity centers on dual USDA-EU certification acquisition and extrusion-cooked pregelatinized product line development.
Within the multinational grain trader archetype, Archer Daniels Midland Company and Wilmar International Limited exemplify scale-driven positioning through contract farming collective networks spanning Thailand and India. Bob's Red Mill Natural Foods anchors the specialist tier with Pacific Northwest vertical integration into organic grain procurement. These three entities represent divergent strategic bets: global origination breadth versus regional supply chain control versus premium brand positioning in clean-label retail channels.
| Leading Market Players |
|---|
| Bob's Red Mill Natural Foods |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Shipton Mill Ltd |
| Ebro Foods |
| Wilmar International Limited |
| Ardent Mills LLC |
| BENEO |
| Nature Bio-Foods Ltd. |
| Others |
Value Chain & Pricing Dynamics
North American grocery chain procurement consolidation concentrates buyer power among three major retailers, forcing contract-based long-term offtake agreements that compress margin flexibility for organic rice flour millers. These volume commitments anchor pricing stability while channel-margin layers absorb compliance cost inflation from dual USDA-EU certification requirements.
Pricing Analysis
Distributor margin compression runs through mid-scale bakery supply tiers as direct-to-manufacturer platforms disintermediate traditional ingredient brokers. Three-tier pricing structure across premium dual-certified, standard single-certified, and economy conventional grades reflects certification investment differentials. Pricing pressure stems from tapioca starch substitution in cost-sensitive snack segments. Industrial gluten-free bread manufacturers exhibit highest price sensitivity; premium clean-label confectionery buyers show lowest.
Supply Chain Analysis
Certification gating through USDA National Organic Program, EU Organic Regulation 2018/848, and Japan's JAS standards fragments supplier qualification timelines. Organic paddy supply draws from Thai contract farming collectives, Indian agricultural zones, and emerging Brazilian southern regions. Wet-milling capacity, dry-milling infrastructure, and extrusion-cooked pregelatinized processing lines constitute critical input dependencies. Single-source vulnerability concentrates in Pacific Northwest organic grain flows controlled by vertically integrated handlers. Distribution runs through Hamburg and Bremen trading houses for European port-of-entry compliance, Minneapolis-St. Paul grain handlers for US industrial procurement, and Bangkok wet-milling facilities for Asian export origination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic rice flour operates as a regulatory compounder where EU Organic Regulation 2018/848 harmonization across member states accelerates demand consolidation among multinational bakery chains seeking streamlined cross-border procurement.
For Market Incumbents: Cement dual USDA-EU certification acquisition as the primary defensive moat against emerging Asian toll processors leveraging EU-based partnerships. Prioritize captive organic paddy supply through backward integration into Pacific Northwest grower contracts to insulate against Thai and Indian climate-driven yield volatility. Batch segregation system investments protect premium positioning from cross-contamination liability. For New Entrants and Emerging Players: The premium-to-economy certification gap creates white-space positioning for mid-tier single-certified suppliers targeting ANVISA-updated Brazilian gluten-free labeling standards. Brazil's bakery sector expansion in São Paulo and Minas Gerais offers the most penetrable geography with first-mover advantages for certified organic positioning. Digital direct-to-manufacturer procurement platforms provide the optimal go-to-market angle for bypassing entrenched distributor networks. For Investors and Strategic Acquirers: Multinational grain traders with global origination networks are the most active acquirer in this space, seeking wet-milling and extrusion capabilities to complete ingredient portfolios. Long-term viability rests on organic equivalence agreement stability across USDA, EU Commission, and Japan's MAFF jurisdictions. Acquisition target archetype: regional organic specialists with captive farm relationships and dual-certification infrastructure. The signal to watch is bilateral organic recognition pact renegotiations that suddenly disqualify established supplier relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | USDA-EU organic alignment secures placement on approved supplier lists for North American grocery chains. |
| Backward Integration into Organic Paddy | Pacific Northwest grower contracts insulate millers from Thai and Indian climate-driven yield fluctuations. |
| Extrusion-Cooked Pregelatinized Line Expansion | No-bake snack bar manufacturing adoption rewrites viscosity control standards and production economics. |
| EU-Based Toll Processing Partnership | REACH compliance circumvention accelerates migration for Asian millers serving European bakery clients. |
| Pulse-Flour Blending R&D | Rice-lentil hybrid formulations penetrate sports nutrition bar segments with protein fortification positioning. |
Study Parameters
Bottom-up bakery and snack formulation modeling reconciled against top-down organic grain origination tracking forms the analytical core. Primary interviews with gluten-free product development executives, organic certification auditors, grain procurement managers at multinational bakery chains, and toll processing facility operators combine with secondary validation. Secondary sources include USDA National Organic Program enforcement data, EU Organic Regulation 2018/848 implementation guidance, Japan's JAS organic seal residue testing protocols, customs and trade flow records, and SEC filings from publicly traded grain handlers.
Input-output matrices map organic paddy supply from Thai and Indian contract farming collectives through wet-milling and dry-milling capacity to end-use demand across baking, brewing, snack, and baby food segments. Segmentation dimensions span product type, end-use application, certification tier, distribution channel, and packaging format across the projection horizon. CAGRs derive from volume trajectory analysis calibrated against price elasticity assumptions and substitution threat intensity from tapioca starch and pulse-flour alternatives.
The model assumes steady-state organic equivalence agreement frameworks between USDA, EU Commission, and Japan's MAFF; sudden recognition withdrawals would alter supplier qualification timelines and sourcing economics. Forecasts reflect assumptions regarding climate stability in Southeast Asian paddy regions and clean-label mandate persistence among North American retailers. A model refresh is warranted upon material change in bilateral organic recognition pacts or ANVISA regulatory enforcement intensity in Brazil.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Europe Wheat Protein Market
Grains
GCC Basmati Rice Market
Grains
Tunisia Grain Market
Grains
Rye Market
Grains
Grain Storage Systems Market
Grains
South Africa Grain Market
Grains
Organic Wheat Flour Market
Grains
Asia Pacific Wheat Protein Market
Grains
Ghana Grain Market
Grains
Wheat Protein Market
Grains
Asia-Pacific Rice Market
Grains
Soybean Market
Grains
North America Wheat Market
Grains
Wheat Flour Market
Grains
Black Gram Market
Grains
Bangladesh Rice Market