
 Oat Bran Market | 2026-2036
Oat Bran Market Size, Share, and Industry Trends Forecast 2026-2036
Oat Bran Market Analysis
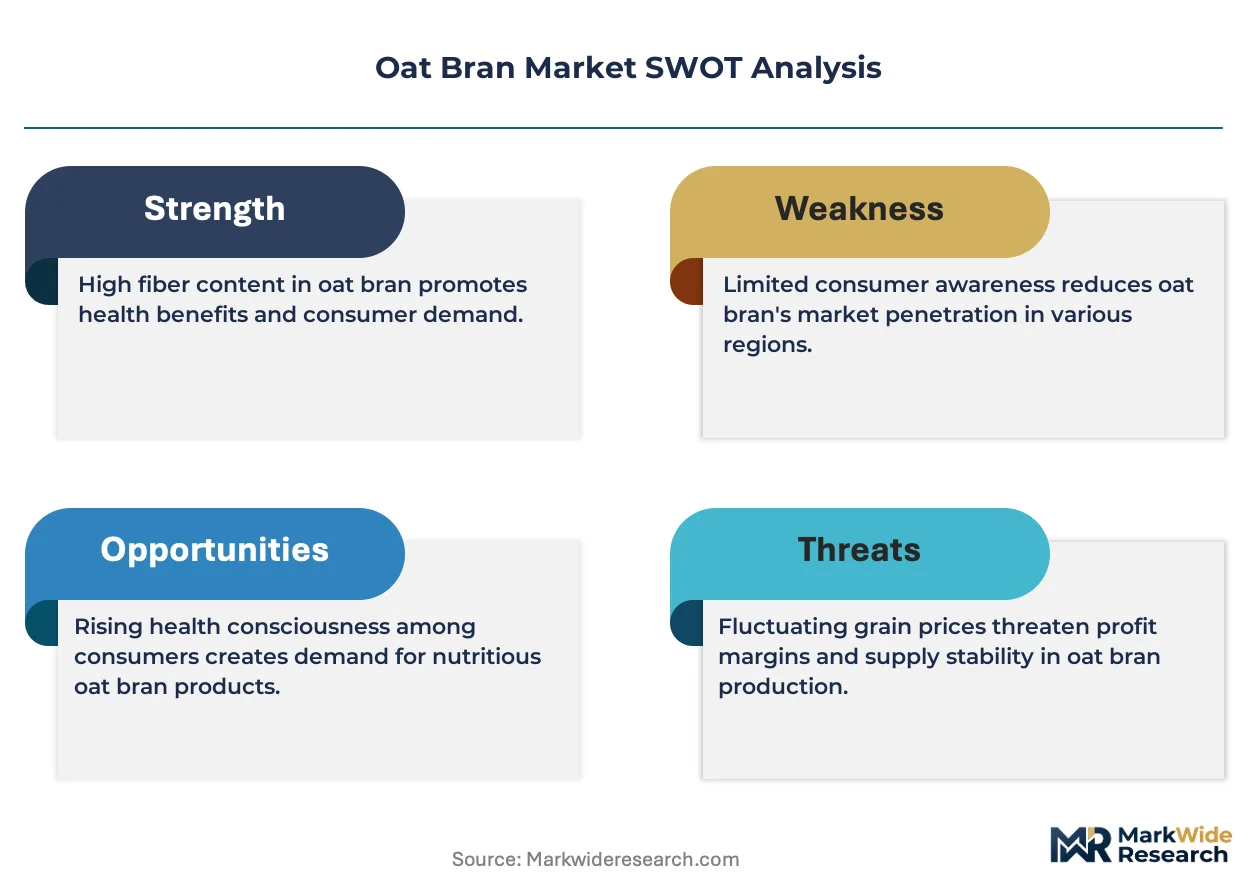
The capital-intensity divergence between integrated millers and specialty brands is redrawing competitive boundaries in oat bran. Grain Millers, Inc. leverages its captive oat processing infrastructure to control supply from field to finished ingredient. Bob's Red Mill differentiates through stone-ground heritage positioning and gluten-free certification programs. Quaker Oats Company anchors the mass-market channel with branded breakfast cereals that incorporate oat bran as a functional ingredient.
Oat bran comprises the outer husk and aleurone layer of the oat kernel, containing approximately 50% more fiber than standard oatmeal with notable beta-glucan concentrations that support cholesterol management claims. Commercial production employs roller milling to separate the bran fraction, followed by heat stabilization to prevent rancidity in storage. Organic oat bran commands premium positioning as consumers prioritize pesticide-free grain sourcing, while gluten-free variants address the expanding celiac and wheat-avoidance population. The baked goods end-use segment generates the deepest margin pools as artisan and industrial bakeries reformulate for fiber enrichment.
The FDA governs oat bran health claims through qualified coronary heart disease labeling rules tied to beta-glucan thresholds, while USDA organic certification shapes premium pricing architecture. EFSA in Europe maintains parallel scrutiny of oat beta-glucan cholesterol claims under EU nutrition and health claims regulation. Stakeholders must monitor evolving fiber definition harmonization between jurisdictions, as divergence in qualifying criteria directly determines which products access preferred shelf positioning and health-claim marketing.
Market Dynamics
The FDA's updated dietary fiber definition has forced reformulation decisions across functional food portfolios, separating qualifying oat beta-glucan ingredients from non-qualifying alternatives and compressing margin structures for non-compliant suppliers.
Growth Catalysts
- Clean-label baked goods reformulation:Industrial bakeries are replacing synthetic fiber additives with oat bran to meet front-of-package claims without ingredient list penalties.
- USDA organic certification expansion:Premium pricing for pesticide-free oat bran is pulling acreage conversion in the upper Midwest and Canadian prairie provinces.
- Celiac disease diagnostic rates:Rising wheat avoidance diagnoses in North America and Western Europe are expanding addressable market for certified gluten-free oat bran variants.
Market Restraints
- Oat futures volatility:Weather-driven supply swings in Canada and Nordic growing regions transmit directly to ingredient cost structures without effective hedging instruments for smaller buyers.
- Roller milling equipment concentration:Capacity for food-grade bran separation concentrates among legacy North American millers, creating supply bottleneck risk during peak harvest windows.
- Psyllium husk substitution:Lower-cost soluble fiber alternatives in supplement and pharmaceutical applications capture price-sensitive volume that oat bran cannot match.
Strategic Opportunities
- Southeast Asian bakery modernization:Industrial bread and biscuit manufacturing in Vietnam and Indonesia remains underpenetrated for functional fiber enrichment, offering first-mover positioning.
- EU Green Deal agricultural incentives:Carbon-sequestering oat cultivation payments in France and Germany could subsidize organic bran production cost premiums.
- Direct-to-ingredient e-commerce:Small-scale artisan bakeries and restaurant chains are bypassing traditional distribution tiers through bulk ingredient platforms.
Industry Challenges
- Heat stabilization technician shortage:Enzyme inactivation expertise for preventing oat bran rancidity is concentrated among retiring mill engineering cohorts without adequate training pipeline replacement.
- Gluten-free certification audit backlog:Third-party verification timelines for oat bran processed in shared wheat facilities are extending 8-14 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat Bran Market |
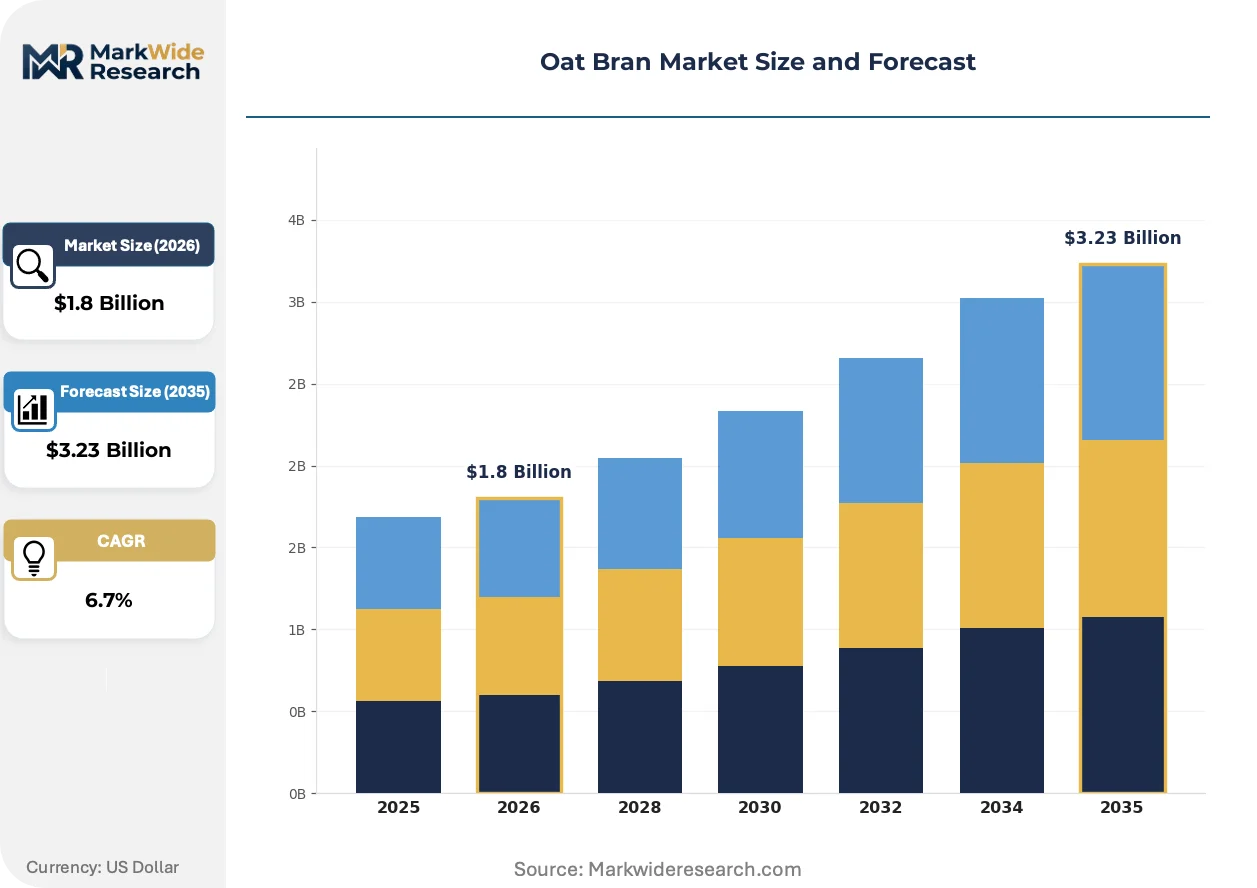
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, Organic, Gluten-Free, Instant End Use: Baked Goods, Breakfast Cereals, Snack Foods, Smoothies Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales Packaging Type: Bags, Boxes, Bulk, Individual Portions |
| Companies Covered | Quaker Oats Company, Kellogg's, Bob's Red Mill, Myprotein, Morning Foods Limited, Grain Millers, Inc., Flahavans, Bulk Barn Foods, Richardson International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat Bran Market Emerging Trajectories
Processing technology and procurement patterns are splitting the oat bran market into parallel tracks serving distinct buyer risk tolerances and clean-label stringency requirements.
Stone-ground heritage milling is bifurcating the premium ingredient tier from commodity roller-milled supply. Artisan bakery chains and specialty food manufacturers specify granite millstone processing for narrative differentiation in direct consumer communication. This mechanical tradition is compressing throughput scalability while enabling 40-60% price premiums over industrial equivalents.
EFSA's 2024 clarification of oat beta-glucan cholesterol claim substantiation requirements is tightening dossier standards for EU market access. Manufacturers must now demonstrate batch-to-batch beta-glucan consistency above 3.0g per serving, forcing investment in in-house analytical laboratories or third-party testing contracts. The baked goods segment is responding with reformulation toward higher bran inclusion rates to guarantee claim compliance.
Ingredient sourcing contracts are shortening from multi-year commitments to 6-12 month rolling agreements with price renegotiation clauses. Mid-sized food manufacturers facing margin pressure are trading volume discounts for flexibility, while integrated millers resist spot market exposure. This tension is most visible in the United States, where 2023-2024 oat harvest quality variability triggered contract renegotiation disputes.
Oat Bran Market Segmentation
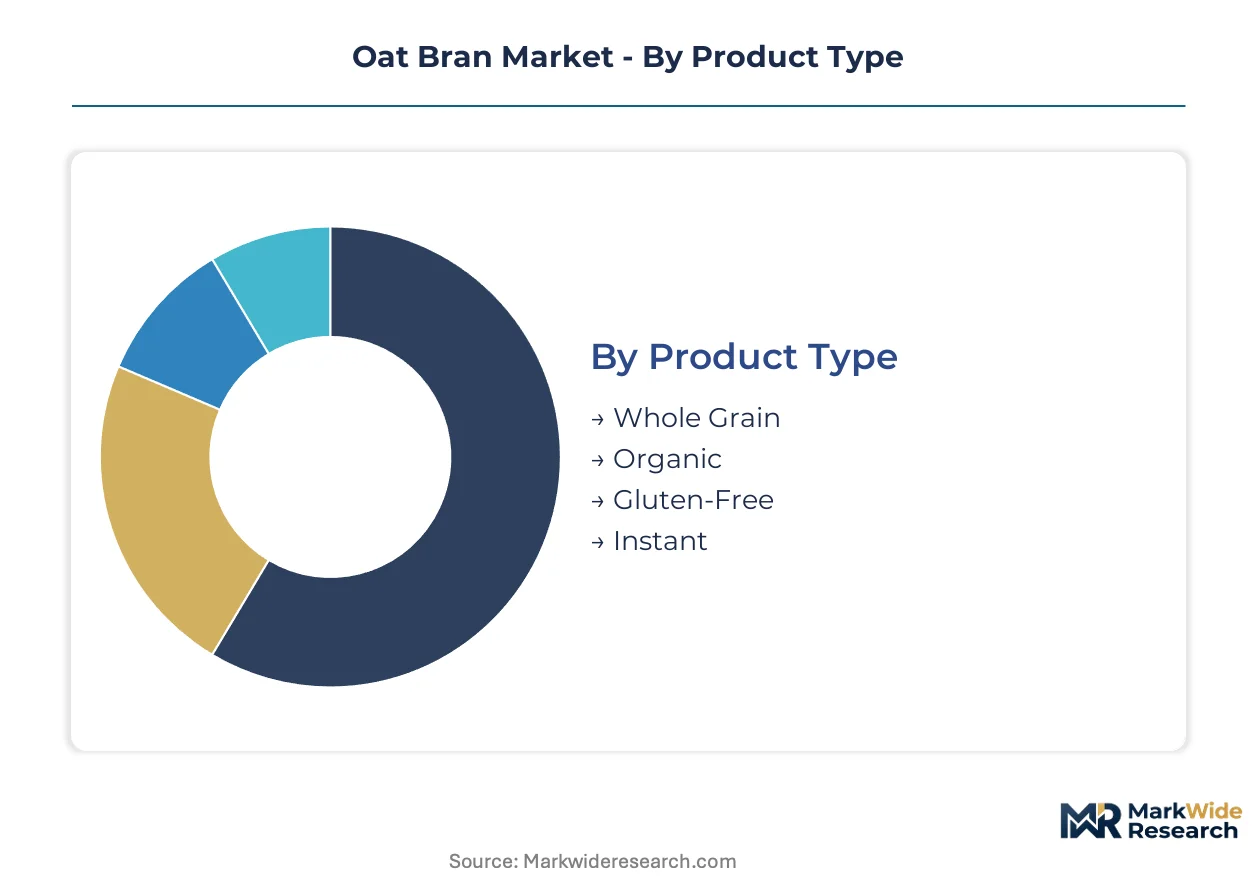
Oat bran segmentation reveals divergent margin structures across product grades and channel strategies. Understanding how organic certification, gluten-free processing, and bulk formats map to distinct buyer workflows enables targeted portfolio positioning without cross-segment cannibalization.
Product Type:
Channel mix varies sharply by processing intensity, with stone-ground and organic variants concentrating in health food stores and direct sales while instant formats dominate supermarket velocity slots.
- Whole Grain:Retains the complete aleurone layer and outer husk with beta-glucan concentrations qualifying for FDA coronary heart disease labeling. Demand concentrates in artisan bakery supply chains across the upper Midwest where heritage milling narratives support premium positioning.
- Organic:USDA-certified pesticide-free sourcing commands shelf price multiples in natural grocery channels. Acreage conversion in Minnesota and Saskatchewan is accelerating as supply contracts shorten to preserve flexibility against conventional price volatility.
- Gluten-Free:Third-party verified absence of wheat cross-contamination addresses celiac and wheat-avoidance populations through dedicated processing facilities.
- Instant:Pre-cooked and finely milled for rapid hydration in hot beverage applications, capturing convenience-oriented breakfast cereal formulations.
By volume, Whole Grain leads. By growth pace, Organic is expanding most quickly.
End Use:
Application-driven cost tiers separate commodity ingredient sales from value-added finished goods, with baked goods commanding formulation premiums and smoothies driving single-serve packaging innovation.
- Baked Goods:Industrial and artisan bakeries incorporate oat bran for fiber enrichment in bread, muffin, and cookie formulations. Clean-label reformulation at commercial bakeries in the United States is displacing synthetic methylcellulose additives.
- Breakfast Cereals:Bran flakes and hot cereal applications leverage cholesterol-health marketing heritage from prior FDA-approved claims. Mass-market penetration through Quaker and private label channels maintains volume concentration.
- Snack Foods:Energy bars and savory crackers utilize oat bran for texture modification and nutritional panel enhancement.
- Smoothies:Fine-milled instant oat bran blends into beverage bases for functional nutrition positioning in direct-to-consumer powder formats.
Baked Goods generates the deepest margin pools. Smoothies are climbing the fastest.
Distribution Channel:
Volume scale inversely correlates with service intensity, with supermarkets moving tonnage through centralized procurement while direct sales capture relationship-driven organic premiums.
- Online Retail:Amazon and specialty ingredient platforms enable small-scale artisan bakeries to bypass traditional distribution tiers. Bulk bag sizes and subscription replenishment models are displacing periodic supermarket stock-ups.
- Supermarkets:Kroger, Safeway, and Walmart shelf placement determines mass-market visibility for branded breakfast cereals and baking aisle bags. Slotting fee structures favor established suppliers with trade marketing budgets.
- Health Food Stores:Whole Foods and regional cooperatives prioritize USDA organic and gluten-free certifications in curated oat bran assortments.
- Direct Sales:Grain Millers and Bob's Red Mill operate proprietary e-commerce and foodservice ingredient channels for institutional bakery accounts.
Supermarkets dominate volume throughput. Online Retail is gaining share fastest.
Packaging Type:
Format selection tracks end-use scale and contamination risk tolerance, with bulk supply serving industrial formulation and portion control addressing foodservice labor cost constraints.
- Bags:Flexible polyethylene or paper stand-up pouches dominate retail shelves with resealability for home baking applications.
- Boxes:Rigid cardboard secondary packaging protects fragile flake structures in breakfast cereal applications.
- Bulk:Food-grade totes and railcar shipments serve industrial bakery and cereal manufacturing with minimal unit packaging cost.
- Individual Portions:Single-serve sachets target foodservice oatmeal pots and airline breakfast programs with precise inventory control.
Bulk leads by tonnage moved. Individual Portions show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Western Europe and North America absorb oat bran premiums for organic certification, while price-sensitive markets in Southeast Asia prioritize conventional grades. Demand elasticity varies most sharply between health-claim-regulated jurisdictions and commodity-importing regions without fiber-labeling frameworks.
United States
FDA-qualified coronary heart disease claims for beta-glucan drive branded breakfast cereal demand. The USDA organic certification program shapes premium pricing in natural grocery channels. Minneapolis-St. Paul anchors North American oat processing infrastructure, with integrated millers controlling supply from prairie cultivation to finished ingredient.
Canada
Prairie province oat acreage expansion responds to organic price premiums under Canadian Organic Regime standards. Health Canada maintains parallel beta-glucan cholesterol claim scrutiny to FDA rules. Saskatchewan's grain handling corridor concentrates food-grade oat separation capacity with direct rail links to US bakery manufacturing clusters.
Germany
EFSA's 2024 beta-glucan claim substantiation tightening forces batch-to-batch consistency investments. EU Green Deal agricultural incentives subsidize carbon-sequestering oat cultivation in Lower Saxony. Hamburg's port infrastructure handles bulk organic oat bran transshipment for European bakery reformulation demand.
United Kingdom
Celiac disease diagnostic rates expand gluten-free oat bran demand through dedicated processing facilities. UK Food Standards Agency enforcement of oat cross-contamination thresholds shapes certification audit timelines. Scottish oat milling heritage supports stone-ground premium positioning in artisan bakery supply chains.
France
Industrial bakery modernization in the Île-de-France region displaces synthetic fiber additives with oat bran enrichment. ANSM oversight of functional food claims intersects with EFSA nutrition and health claims regulation. Auvergne-Rhône-Alpes food manufacturing clusters source organic bran for clean-label reformulation of traditional bread categories.
Oat Bran Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the oat bran supply base. Integrated grain processors with captive oat milling infrastructure control cost structures through backward integration into field supply. Specialty ingredient brands compete on certification density and heritage processing narratives rather than unit economics. The market structure rewards two dominant competitive moves: geographic expansion into underpenetrated bakery markets and portfolio diversification into organic and gluten-free certified variants.
Among North American integrated processors, Grain Millers, Inc. and Richardson International occupy positions defined by captive supply chain control from prairie cultivation to finished ingredient. Bob's Red Mill exemplifies the heritage-milling archetype, competing through stone-ground processing narratives and third-party certification density rather than scale economies. Quaker Oats Company anchors mass-market penetration through branded breakfast cereal formulations that leverage decades of FDA-approved cholesterol-health marketing heritage.
| Leading Market Players |
|---|
| Quaker Oats Company |
| Kellogg's |
| Bob's Red Mill |
| Myprotein |
| Morning Foods Limited |
| Grain Millers, Inc. |
| Flahavans |
| Bulk Barn Foods |
| Richardson International |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between prairie oat millers and industrial bakery buyers lock in both supply access and price visibility across volatile growing seasons. These contracts trade volume discounts for harvest-quality flexibility, compressing margin buffers for non-integrated suppliers when Canadian oat futures swing on weather events.
Pricing Analysis
After-sales service bundling in technical ingredient support drives lifetime value for mid-sized bakery accounts seeking reformulation guidance. Three-tier pricing structure across premium, standard, and economy levels separates stone-ground organic certification from commodity roller-milled supply. Cost compression in the conventional tier is intensifying because psyllium husk substitutes capture price-sensitive supplement volume. Industrial bakeries exhibit highest price sensitivity, while artisan chains absorb premiums for heritage processing narratives.
Supply Chain Analysis
Inventory lead times for food-grade oat bran extend through the post-harvest stabilization window, creating working capital intensity for buyers without elevator storage access. Supply concentrates in Canada, the United States, and Sweden, with prairie provinces anchoring North American food-grade separation capacity. Processing draws from raw oat grain, roller milling equipment, and heat stabilization energy inputs. Single-source vulnerability concentrates in legacy North American millers with specialized bran separation infrastructure. Distribution runs through bulk rail shipments to industrial bakery clusters and bagged retail channels for consumer-facing formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oat bran market functions as a defensive-moat story anchored in regulatory entrenchment. FDA-qualified health claims for beta-glucan create certification barriers that new entrants cannot easily replicate without multi-year substantiation investment.
For Market Incumbents: Compound defensive positioning through backward integration into organic oat acreage in Saskatchewan and Minnesota, securing supply against conventional price volatility. Deepen certification density with simultaneous USDA organic and gluten-free third-party verification to widen shelf-access moats against emerging stone-ground heritage brands. Prioritize heat stabilization engineering talent retention as retiring technician cohorts threaten operational continuity. For New Entrants and Emerging Players: Artisan bakery technical service gaps in Southeast Asia offer first-mover positioning where incumbents under-serve reformulation expertise. Target Vietnam and Indonesia industrial bread modernization with instant oat bran formulations and on-site fiber enrichment consulting. Penetrate through direct-to-ingredient e-commerce platforms that bypass traditional distribution tiers serving small-scale bakery accounts. For Investors and Strategic Acquirers: Capital is best deployed toward integrated millers with captive prairie oat supply chains and established FDA claim substantiation dossiers. Long-term viability over the coming decade rests on regulatory entrenchment durability and organic acreage conversion momentum. Watch EFSA batch-to-batch beta-glucan consistency enforcement as the inflection signal for European market access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acreage | Captive supply from Saskatchewan prairie cultivation locks in premium pricing architecture against conventional volatility. |
| Gluten-Free Certification Investment | Third-party verification addresses celiac population expansion through dedicated processing facility separation protocols. |
| Direct-to-Ingredient E-Commerce Launch | Bulk platform sales bypass traditional distribution tiers serving artisan bakery and restaurant chain procurement workflows. |
| Southeast Asian Bakery Partnership | Technical service relationships with Vietnamese industrial bread manufacturers establish first-mover fiber enrichment positioning. |
| In-House Analytical Laboratory Buildout | Batch-to-batch beta-glucan testing capability ensures EFSA cholesterol claim compliance without third-party contract dependency. |
Methodological Framework
Cross-validation between primary interviews with oat mill engineering directors and secondary validation through USDA acreage reports anchors the qualitative findings in this study. Conversations with industrial bakery procurement managers, gluten-free certification auditors, and prairie grain elevator operators combined with FDA filing records, EFSA health claim registers, and Canadian Grain Commission trade data. Bottom-up volume modeling from end-use segment consumption patterns triangulates against top-down oat processing capacity estimates.
Sensitivity analysis across price elasticity assumptions and harvest yield scenarios tests forecast robustness over the projection horizon. The analytical framework segments by product grade tier, end-use application, certification status, and regional regulatory cluster. CAGRs derive from rolling average consumption trends adjusted for organic conversion rates and clean-label reformulation momentum. Beta-glucan claim substantiation requirements and heat stabilization capacity constraints serve as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA and EFSA health claim regimes; material policy shifts would require re-modeling. Supply disruption from prairie weather events or gluten-free certification audit backlogs could revise volume assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Rice Market
Grains
Grain Bins Market
Grains
Wild Rice Market
Grains
China Rice Market
Grains
Organic Cereals Market
Grains
United States Gluten-Free Oats Market
Grains
Bangladesh Rice Market
Grains
Corn Market
Grains
Global Maize Market
Grains
South Africa Maize Market
Grains
Black Gram Market
Grains
Fortified Rice Market
Grains
Grain-Based Flours Market
Grains
Triticale Market
Grains
Non-Basmati Rice Market
Grains
North America Maize Market