
 Green Banana Flour Market | 2026-2036
Green Banana Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Green Banana Flour Market Outlook
Buyer concentration in the food manufacturing segment is decoupling from traditional bakery supply chains as gluten-free and clean-label portfolios expand. Natural Evolution Pty Ltd. leverages its Australian processing base to supply resistant-starch-rich flour to functional food makers. Symrise AG anchors its ingredient portfolio through flavor-system integration with banana-derived bases. Archer Daniels Midland Company (ADM) competes by extending its global grain and specialty ingredient distribution network into emerging tropical flour categories.
Green banana flour consists of dried and milled unripe banana pulp, typically containing 40-60% resistant starch by dry weight and exhibiting low glycemic response, which makes it suitable for glycemic management products and gluten-free formulations. Organic flour commands premium positioning in health food stores and specialty retail channels, while conventional flour dominates volume through supermarket and food-service distribution. The gluten-free products application leads value generation as celiac-safe and paleo-positioned brands source banana flour for bread, pasta, and snack matrices.
The FDA governs gluten-free labeling thresholds in the United States, while the EU Green Deal and EFSA nutrition claims frameworks shape permissible health-positioning language across European markets. Brazil's ANVISA and Ecuador's national food safety authority enforce processing standards for export-oriented banana flour facilities. Stakeholders must monitor evolving resistant-starch health claim substantiation requirements and origin-certification protocols as procurement criteria tighten across major import markets.
Market Dynamics
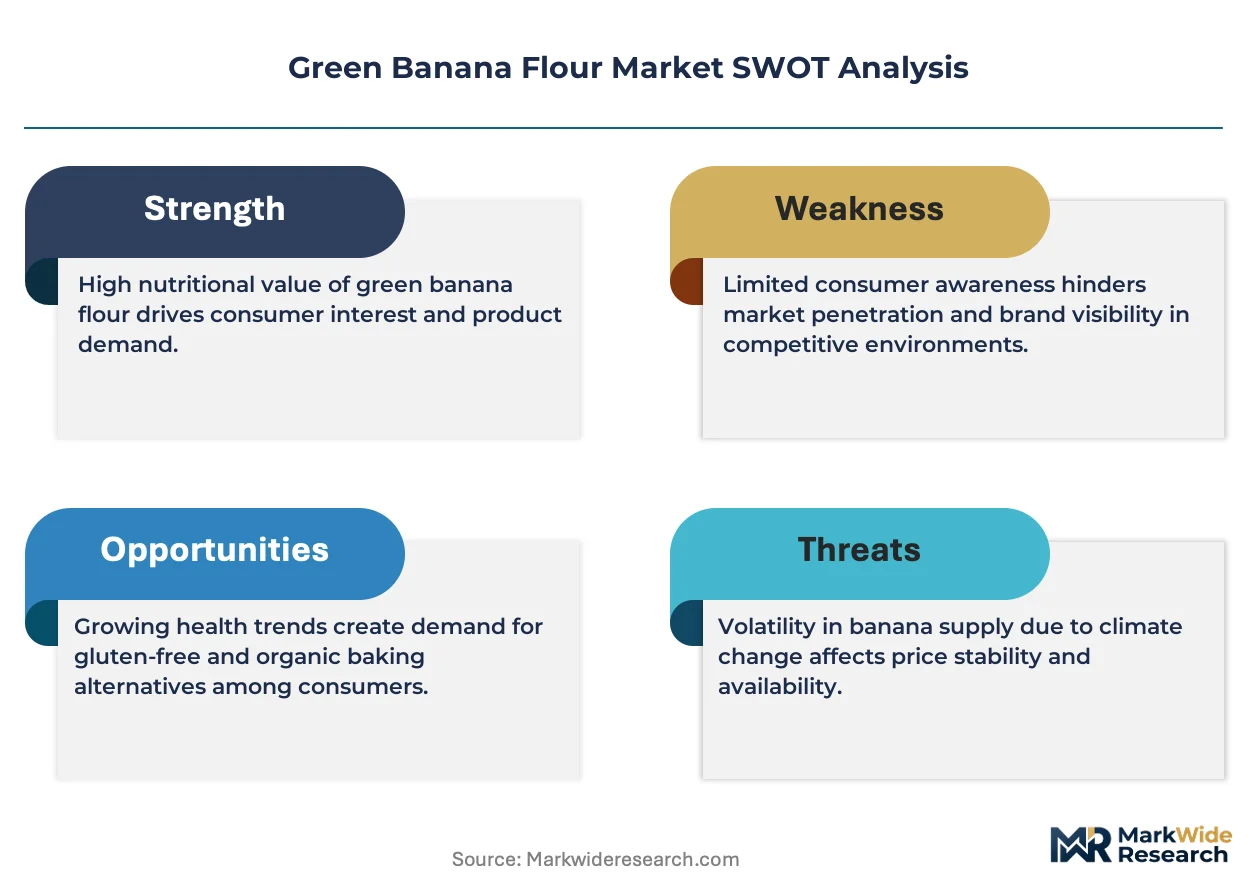
Clean-label mandates in the European Union and United States are forcing food manufacturers to purge synthetic additives from gluten-free formulations, redirecting procurement toward resistant-starch-rich banana flour as a functional replacement for modified starches and hydrocolloids.
Growth Catalysts
- EU Green Deal nutrition claims frameworks:Tightening disclosure requirements for processed foods incentivize reformulation with single-ingredient banana flour to meet clean-label thresholds.
- Brazilian processing infrastructure clustering:Concentrated raw material access around São Paulo and Minas Gerais states enables cost-competitive export supply to North American and European gluten-free manufacturers.
- Resistant starch health positioning:Glycemic management product developers leverage banana flour's 40-60% resistant starch content for paleo and celiac-safe portfolios.
Market Restraints
- Input cost volatility:Unripe banana prices fluctuate with Ecuadorian and Colombian harvest cycles, compressing processor margins during El Niño disruptions.
- Supply concentration risk:Over 70% of commercial green banana flour originates from facilities within 200 kilometers of coastal Ecuadorian plantations, creating single-point vulnerability.
- Substitution threat from cassava and tigernut flours:Alternative resistant-starch sources with established supply chains and lower price volatility capture mid-market gluten-free formulations.
Strategic Opportunities
- Underpenetrated Japanese functional food sector:METI's Foods with Function Claims system permits resistant-starch substantiation for digestive health products, opening premium positioning channels.
- Direct-to-consumer subscription channels:Specialty health brands bypass conventional food-service distribution by offering organic banana flour through personalized nutrition platforms.
- Convergence of spray-drying and enzyme stabilization:Hybrid processing technologies preserve resistant-starch integrity while reducing moisture content below 8%, enabling extended ambient shelf life for export markets.
Industry Challenges
- Certification timeline compression:Organic and gluten-free audits require 18-24 months for new processing facilities, delaying market entry for emerging suppliers in Southeast Asia.
- Specialized drying technician scarcity:Operational expertise in low-temperature dehydration below 60°C to preserve resistant-starch crystallinity concentrates among Brazilian and Ecuadorian trained workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Banana Flour Market |
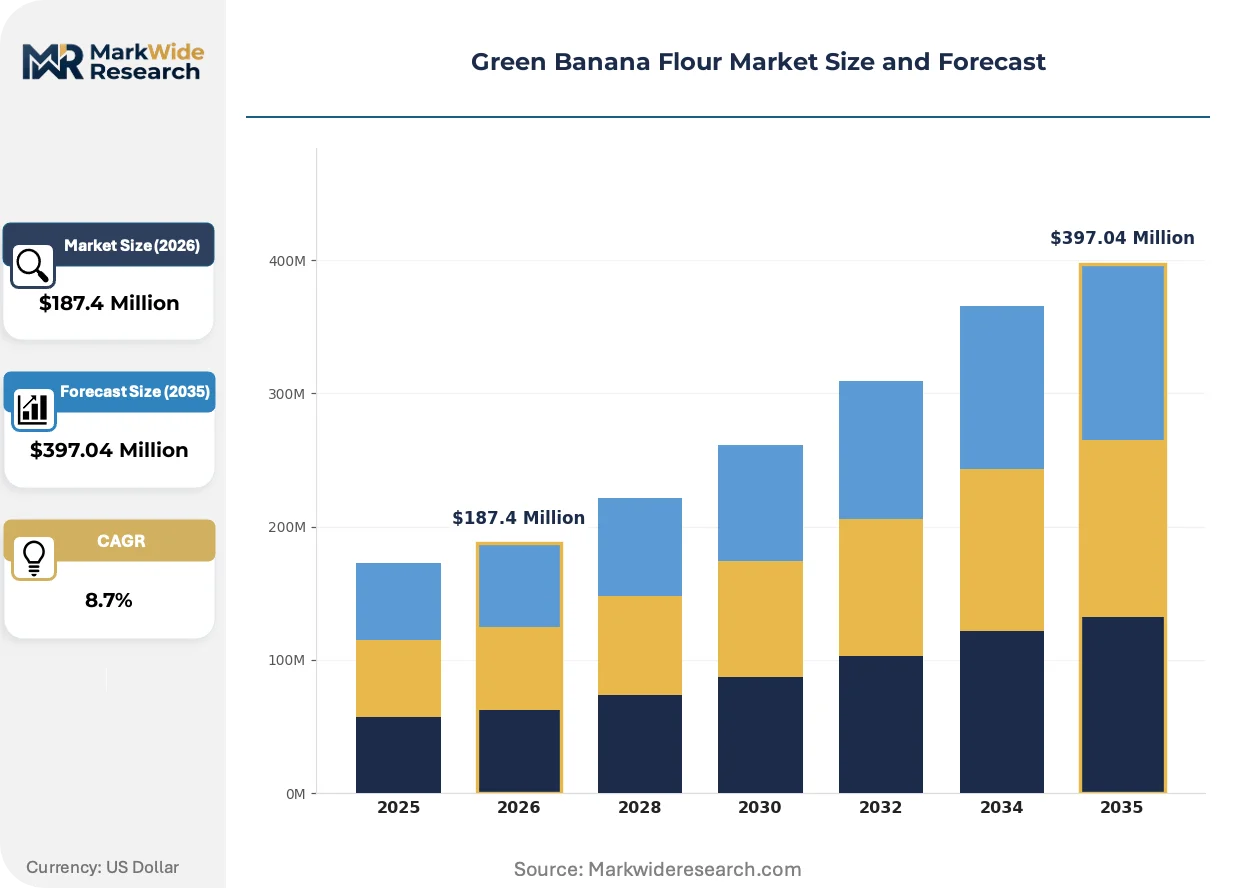
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Flour, Conventional Flour, Instant Flour, All-Purpose Flour Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores End User: Bakers, Restaurants, Home Cooks, Food Manufacturers Application: Baking, Thickening Agent, Gluten-Free Products, Snacks |
| Companies Covered | Natural Evolution Pty Ltd., Symrise AG, Archer Daniels Midland Company (ADM), S K International (Candix), Ceres Organics Pvt. Ltd., Banana Flour Co., APKA Industries, Kanegrade Ltd., Green Banana Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Banana Flour Market Strategic Shifts
Processing technology convergence and procurement model evolution are restructuring how resistant-starch ingredients reach formulation laboratories and commercial kitchens. These shifts compress traditional supply hierarchies while elevating traceability requirements.
Spray-drying combined with enzyme pre-treatment is unifying moisture reduction and starch crystallinity preservation in a single continuous line. Functional food manufacturers in Germany and the Netherlands adopt these integrated systems at pilot scale. This unification eliminates batch-to-batch resistant-starch variation that previously required reformulation adjustments.
The EU Green Deal's Farm to Fork strategy tightens origin-documentation requirements for imported tropical ingredients entering European processing facilities. Banana flour importers must now provide geolocation data for sourcing plantations and water-usage certifications. Small-to-mid-scale Brazilian exporters face compliance cost barriers while larger integrated processors absorb documentation overhead.
Food manufacturers are consolidating supplier relationships from fragmented commodity traders toward contracted direct partnerships with single-origin processors. This consolidation displaces spot-market purchasing in the gluten-free bakery segment. The shift is most visible in California and Pacific Northwest clean-label brands seeking batch-traceability for paleo-positioned product lines.
Green Banana Flour Market Segmentation
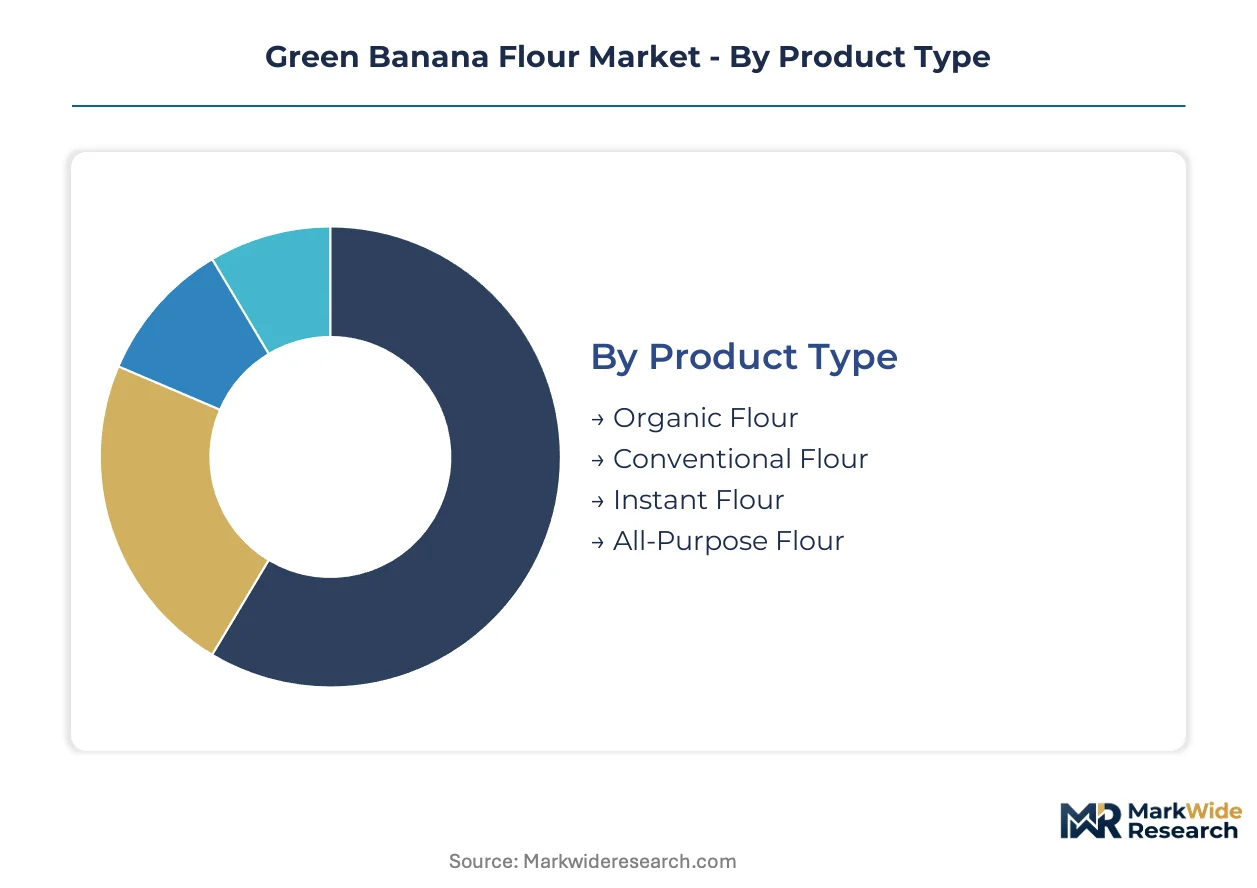
Green banana flour procurement patterns diverge sharply across product grades and buyer types. Processing technology requirements and certification thresholds create distinct investment profiles that reshape competitive positioning within each segment cluster.
Product Type:
Organic flour demands the heaviest upfront capital for certification compliance and segregated processing lines, while conventional operations achieve scale with lower infrastructure barriers.
- Organic Flour:Certified unripe banana pulp processed under USDA Organic or EU Organic protocols, commanding price premiums in paleo and celiac-safe portfolios. Demand concentrates in California and Pacific Northwest clean-label brands seeking batch-traceability for resistant-starch substantiation.
- Conventional Flour:Standard-grade dried banana pulp with 40-60% resistant starch content, serving mainstream gluten-free manufacturers. Brazilian processors around São Paulo and Minas Gerais anchor volume supply to North American supermarket channels.
- Instant Flour:Pre-gelatinized flour for rapid hydration in beverage and instant food matrices. German and Dutch functional food developers adopt pilot-scale spray-drying integration.
- All-Purpose Flour:Blended formulations combining banana flour with alternative starches for texture optimization in home baking applications.
Most installed capacity flows through Conventional Flour. Expansion is steepest in Organic Flour.
Distribution Channel:
Channel selection determines margin capture and customer acquisition cost, with digital platforms requiring minimal physical infrastructure compared to retail shelf placement.
- Supermarkets:Conventional flour dominates volume through centralized distribution to gluten-free bakery sections. Ecuadorian export processors prioritize pallet-scale shipments to US and European retail chains.
- Health Food Stores:Organic flour commands premium positioning through specialty retail with educated staff. Japanese functional food sector demand concentrates here under METI's Foods with Function Claims system.
- Online Retail:Direct-to-consumer subscription channels enable personalized nutrition platforms to bypass conventional food-service hierarchies.
- Specialty Stores:Curated selections for paleo and resistant-starch-focused consumers seeking origin documentation.
Supermarkets absorb the largest volume share. Online Retail is climbing the fastest as subscription models consolidate.
End User:
Food Manufacturers deploy the most sophisticated procurement systems, while Home Cooks represent the lowest barrier to entry for emerging brands.
- Food Manufacturers:Industrial-scale buyers reformulate gluten-free bread, pasta, and snack matrices with resistant-starch-rich banana flour. FDA gluten-free labeling thresholds and EU Green Deal disclosure requirements drive specification tightening.
- Bakers:Artisan and commercial bakery operations source banana flour for celiac-safe product lines, with Brazilian ANVISA-certified facilities preferred for export supply.
- Restaurants:Limited penetration in food-service channels due to moisture sensitivity and specialized storage requirements.
- Home Cooks:Growing direct purchase segment through specialty health brands offering recipe integration support.
Food Manufacturers command the deepest supplier relationships. Home Cooks are gaining share fastest through digital-native brand building.
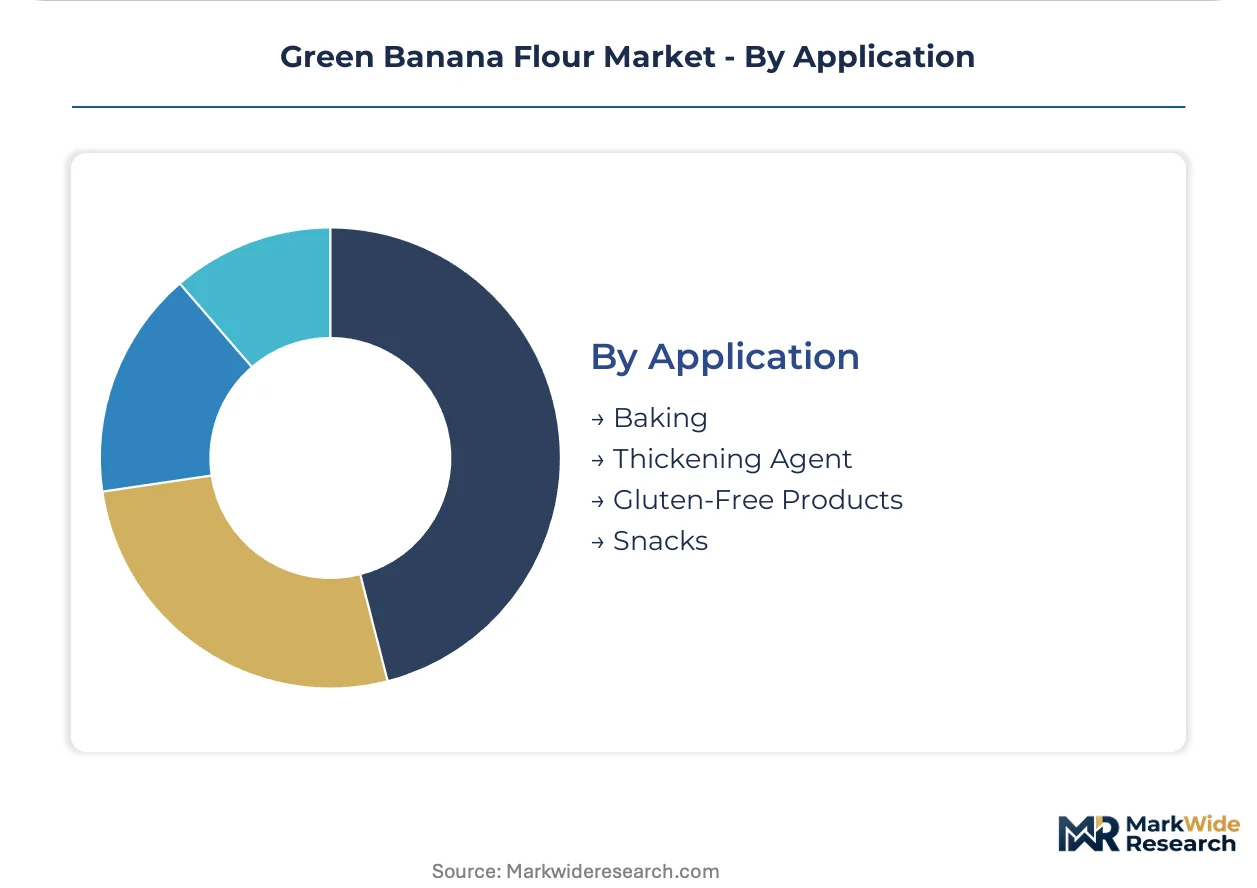
Application:
Gluten-Free Products generate the highest value per kilogram, while Thickening Agent applications compete on cost with modified starches.
- Gluten-Free Products:Core value driver where banana flour replaces wheat in bread, pasta, and snack formulations. Clean-label mandates in the European Union and United States purge synthetic additives, redirecting procurement toward single-ingredient resistant-starch sources.
- Snacks:Extruded and baked applications leverage low glycemic response for paleo-positioned brands. Ecuadorian coastal processing clusters supply North American contract manufacturers.
- Baking:Traditional cake and pastry applications requiring hydration adjustment due to banana flour's moisture-binding properties.
- Thickening Agent:Functional replacement for hydrocolloids in soups and sauces, competing with cassava and tigernut flour alternatives.
Gluten-Free Products absorb the majority of certified organic supply. Snacks represent the steepest expansion trajectory as extrusion technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil generates larger export volumes than Ecuador, yet Ecuadorian processors retain tighter geographic clustering around coastal plantations. This concentration pattern shapes procurement reliability and margin structures across import markets.
Brazil
ANVISA-certified facilities in São Paulo and Minas Gerais anchor supply to North American gluten-free manufacturers. The country's national food safety authority enforces processing standards that align with FDA import requirements. São Paulo-state processors cluster within 150 kilometers of major banana-growing cooperatives, enabling just-in-time raw material sourcing.
Ecuador
Over 70% of commercial green banana flour originates from facilities within 200 kilometers of coastal plantations. The national food safety authority mandates export-oriented processing protocols that satisfy EU Green Farm to Fork documentation requirements. Guayas Province hosts the densest concentration of low-temperature dehydration expertise.
United States
California and Pacific Northwest clean-label brands drive demand for batch-traceable organic flour in paleo-positioned product lines. FDA gluten-free labeling thresholds require substantiation documentation that favors contracted direct partnerships over spot-market purchasing. Los Angeles and Portland metro areas concentrate formulation laboratories sourcing resistant-starch ingredients.
Germany
Functional food developers in the Netherlands and Germany adopt pilot-scale spray-drying integration for instant flour production. EFSA nutrition claims frameworks shape permissible health-positioning language for glycemic management products. Cologne and Düsseldorf processing hubs test hybrid enzyme stabilization technologies.
Japan
METI's Foods with Function Claims system permits resistant-starch substantiation for digestive health products. Health food stores in Tokyo and Osaka concentrate demand for premium organic flour with origin documentation. Japanese importers require geolocation data for sourcing plantations that exceeds EU Green Deal baseline requirements.
Green Banana Flour Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The vendor base organizes around three strategic archetypes: integrated tropical processors with captive raw material access, flavor-system integrators leveraging ingredient portfolio breadth, and regional specialists optimizing resistant-starch preservation protocols. M&A activity concentrates on acquiring low-temperature dehydration expertise, while capacity expansion targets spray-drying and enzyme stabilization convergence.
Within the integrated processing tier, Natural Evolution Pty Ltd. represents Australian-based resistant-starch specialization, while Symrise AG exemplifies flavor-system integration with banana-derived bases. Archer Daniels Midland Company anchors global grain and specialty ingredient distribution network extension into emerging tropical flour categories. These three entities occupy positions that span distinct competitive vectors without overlapping core capabilities.
| Leading Market Players |
|---|
| Natural Evolution Pty Ltd. |
| Symrise AG |
| Archer Daniels Midland Company (ADM) |
| S K International (Candix) |
| Ceres Organics Pvt. Ltd. |
| Banana Flour Co. |
| APKA Industries |
| Kanegrade Ltd. |
| Green Banana Technologies |
| Others |
Value Chain & Pricing Dynamics
Spray-drying and enzyme stabilization convergence in German and Dutch pilot facilities simultaneously compresses processing costs and concentrates supply relationships among technology-advanced processors, reshaping how resistant-starch integrity commands premium positioning across certification tiers.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for conventional flour as São Paulo-state processors expand dehydration lines. Three-tier pricing structure across organic, conventional, and instant flour levels separates certified supply from standard-grade volume. Price differentiation rests on USDA Organic certification and resistant-starch assay consistency. Cost compression in conventional tiers is intensifying because El Niño disruptions in Ecuadorian harvest cycles trigger raw material volatility. Food manufacturers with long-term offtake contracts exhibit lowest price sensitivity; spot-market bakers face highest exposure.
Supply Chain Analysis
Direct-to-manufacturer channels handle industrial-scale demand from gluten-free formulators seeking batch-traceability. Raw material sourcing draws from Ecuadorian coastal plantations, São Paulo-state banana cooperatives, and Minas Gerais processing clusters. Unripe banana pulp, low-temperature dehydration equipment, and ANVISA-certified laboratory capacity anchor upstream dependencies. Single-source vulnerability concentrates in Guayas Province facilities where over 70% of commercial output originates within 200 kilometers. Distribution runs through contracted direct partnerships displacing fragmented commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork strategy operates as a regulatory compounder, tightening origin-documentation requirements that redirect procurement toward traceable single-ingredient suppliers.
For Market Incumbents: Cement backward integration into captive banana plantation access to defend margin position against cassava and tigernut flour substitution. Prioritize ANVISA and FDA certification maintenance as barrier construction against Southeast Asian entrants facing 18-24 month audit timelines. Channel control through direct partnerships with California and Pacific Northwest clean-label brands preserves pricing power. For New Entrants and Emerging Players: METI's Foods with Function Claims system in Japan opens a window for premium organic flour positioning through health food store channels underpenetrated by established Brazilian exporters. Target direct-to-consumer subscription platforms as lowest-barrier entry vector. Leverage spray-drying technology partnerships with German functional food developers as credibility anchor. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Brazilian processors lacking EU Green Deal documentation infrastructure but possessing ANVISA-certified capacity. Long-term viability favors acquisition targets with hybrid dehydration technology and established geolocation data systems for plantation traceability. Watch Japanese importer requirements for water-usage certifications as inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Access | Captive raw material supply insulates processors from Ecuadorian harvest volatility and El Niño disruptions. |
| Hybrid Spray-Drying and Enzyme Stabilization Adoption | German and Dutch pilot facilities demonstrate moisture reduction below 8% while preserving resistant-starch crystallinity. |
| Direct-to-Consumer Subscription Launch | Digital-native brands bypass conventional food-service hierarchies to capture paleo-positioned home cook demand. |
| EU Green Deal Documentation Compliance Investment | Geolocation data and water-usage certification systems satisfy Farm to Fork origin requirements for European import. |
| ANVISA and FDA Dual Certification Pathway | Dual regulatory alignment enables simultaneous access to North American supermarket and Brazilian domestic channels. |
Study Parameters
Direct dialogue with banana flour processors, gluten-free food manufacturer procurement leads, ANVISA regulatory affairs specialists, and low-temperature dehydration equipment suppliers grounded qualitative assessment. Secondary validation drew from FDA gluten-free labeling guidance documents, EU Green Deal Farm to Fork strategy publications, EFSA nutrition claims registers, and Brazilian customs export data. Bottom-up capacity modeling and top-down demand triangulation cross-verified segment outputs.
Market size and growth projections across the analysis window reflect segment-level modeling by product type, distribution channel, end user, and application dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating resistant-starch health claim substantiation timelines and clean-label reformulation adoption rates. Forecast inputs included El Niño cycle probability weighting for Ecuadorian supply disruption scenarios and METI Foods with Function Claims approval velocity for Japanese market penetration.
Revisions become necessary when EU Green Deal documentation requirements tighten beyond current Farm to Fork baselines, when Brazilian or Ecuadorian food safety authorities modify export processing standards, or when spray-drying technology cost curves shift adoption economics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
IQF Rice Market
Grains
Europe Rice Market
Grains
Global Maize Market
Grains
North America Wheat Protein Market
Grains
Africa Wheat Protein Market
Grains
Millet Flour Market
Grains
Wheat Flour Market
Grains
Spain Rice Market
Grains
Grain Storage Silos Market
Grains
Oat Flour Market
Grains
China Wheat Protein Market
Grains
Triticale Market
Grains
South America Rice Market
Grains
Corn Gluten Feed Market
Grains
Spelt Wheat Market
Grains
Sorghum Flour Market