
 Wheat Bran Market | 2026-2036
Wheat Bran Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat Bran Market Analysis
Modular packaging of wheat bran into single-serve sachets and bulk foodservice totes is realigning procurement patterns across nutraceutical and bakery channels. Cargill leverages its grain origination network to secure consistent bran supply from North American elevators. Associated British Foods anchors European demand through its Allied Bakeries and Twinings distribution infrastructure. Wilmar International dominates Southeast Asian supply chains with integrated palm and grain logistics that extend into bran trading.
Wheat bran consists of the outer pericarp, testa, and aleurone layers of the wheat kernel, typically comprising 14.5% protein, 42% dietary fiber, and 4% fat by weight, with particle size ranging from 200 to 2000 microns depending on milling configuration. Its primary commercial purpose centers on intestinal health promotion in human nutrition and rumen fermentation modulation in ruminant livestock diets. Organic wheat bran commands premium positioning through certified supply chains that restrict synthetic pesticide residues, while animal feed applications absorb volume at thinner margins. The health supplements segment is expanding fastest as nutraceutical companies extract arabinoxylan oligosaccharides for prebiotic formulations.
The FDA's Food Safety Modernization Act imposes preventive controls on animal food facilities handling wheat bran, while the EU's Feed Hygiene Regulation mandates hazard analysis and critical control points across milling byproduct streams. India's FSSAI enforces maximum permissible mycotoxin thresholds on bran destined for human consumption, creating divergence in processing standards between feed-grade and food-grade channels. Stakeholders must monitor evolving mycotoxin testing protocols and organic certification reciprocity agreements between major exporting and importing jurisdictions to preserve market access and margin structures.
Market Dynamics
The EU's Feed Hygiene Regulation is tightening mycotoxin thresholds on cereal byproducts, forcing millers to segregate food-grade and feed-grade bran streams through dedicated processing lines and enhanced testing protocols.
Growth Catalysts
- Arabinoxylan extraction:Nutraceutical manufacturers in Germany are isolating prebiotic oligosaccharides from wheat bran for capsule formulations targeting gut microbiome modulation.
- FSSAI mycotoxin standards:India's food safety regulator is enforcing stricter human-consumption thresholds, creating certified supply chain premiums for compliant Indian millers.
- Rumen fermentation science:Livestock nutritionists in Brazil are formulating fiber-enriched dairy rations using wheat bran to optimize volatile fatty acid production.
Market Restraints
- Input cost volatility:Wheat bran pricing tracks underlying grain futures, exposing processors to commodity swings without pass-through mechanisms in long-term feed contracts.
- Supply concentration risk:North American elevator networks controlled by major grain traders create dependency on a limited origination geography for premium-grade bran.
- Soy hull substitution:Dairy operations in the United States are substituting soy hulls for wheat bran during periods of unfavorable price spreads, compressing volume commitments.
Strategic Opportunities
- Organic certification arbitrage:German health supplement brands are sourcing certified organic bran from transitioning Eastern European farms to capture supply before full organic premiums apply.
- Single-serve sachet formats:Nutraceutical distributors are repackaging bran powder into portion-controlled units for direct-to-consumer wellness subscriptions bypassing bulk ingredient channels.
- CSRD supply chain disclosure:The EU's Corporate Sustainability Reporting Directive is rewarding bran suppliers with verified carbon footprint data, creating preferential procurement relationships with ESG-mandated buyers.
Industry Challenges
- Cross-contamination protocols:Millers operating dual food-feed lines face FDA preventive control requirements demanding physical separation infrastructure and documented cleaning validations.
- Organic transition timelines:Farms seeking USDA organic certification must complete three-year conversion periods without synthetic pesticide use, creating supply gaps during qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat Bran Market |
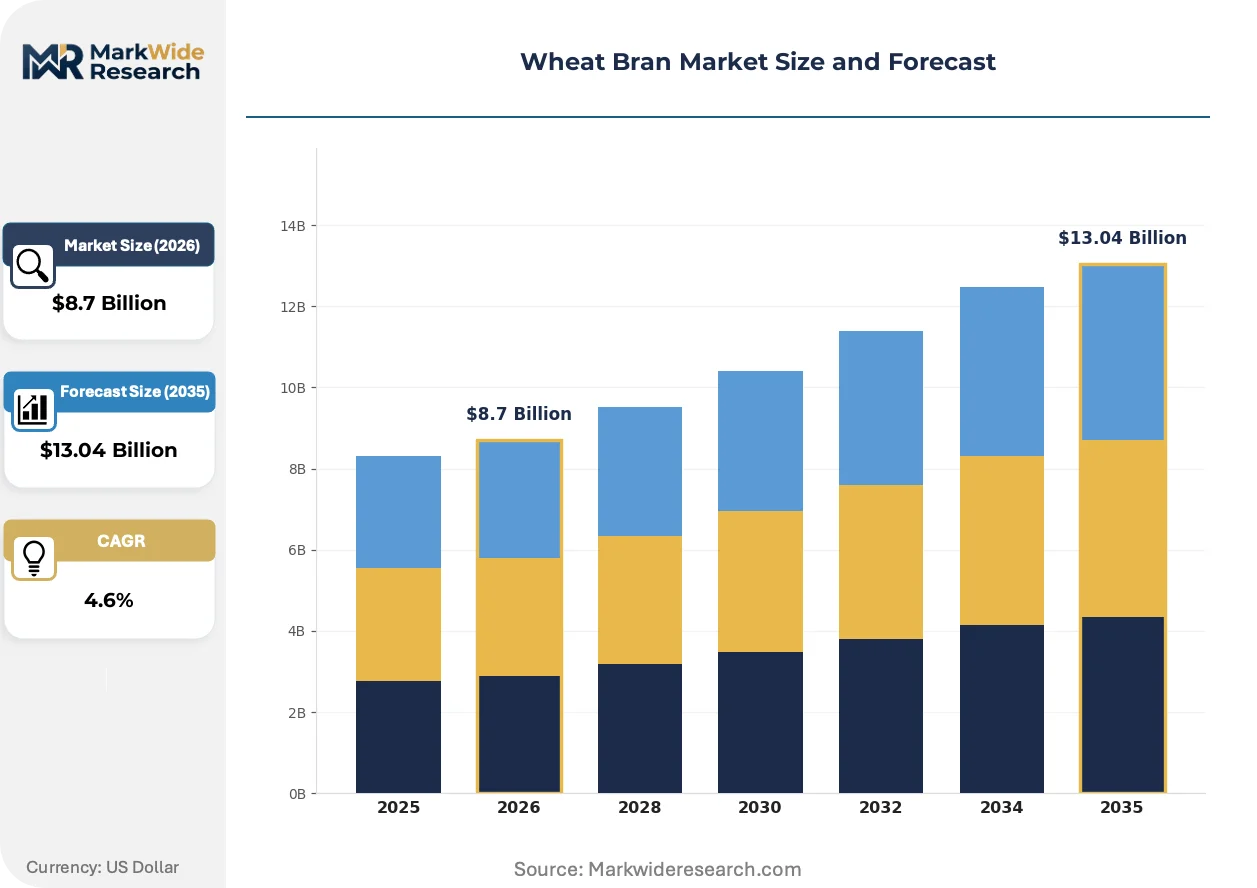
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Wheat Bran, Non-Organic Wheat Bran, High-Fiber Wheat Bran, Toasted Wheat Bran Application: Baking, Breakfast Cereals, Health Supplements, Animal Feed Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Wholesale End User: Bakers, Cereal Manufacturers, Nutraceutical Companies, Livestock Farmers |
| Companies Covered | Wilmar International, Siemer Milling Company, Cargill, ConAgra Foods, Hindustan Animal Feeds, Archer Daniels Midland (ADM), Star of the West Milling, Associated British Foods, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Bran Market Emerging Trajectories
Processing technologies and regulatory frameworks are converging to transform wheat bran from a bulk commodity into a precision ingredient with segmented certification tiers and application-specific formulations.
Ultrafine milling systems are expanding into the 200-500 micron particle range for beverage fortification applications. Nutraceutical blenders in the United States are adopting these systems to achieve suspension stability in ready-to-drink formulations without sensory degradation. This particle size reduction is expanding into premium pricing tiers previously occupied by soluble fiber isolates.
REACH chemical registration requirements are extending to novel extraction solvents used in arabinoxylan isolation processes. European ingredient suppliers must now submit full toxicity dossiers for ethanol-water mixtures and enzymatic processing aids. German contract manufacturers are responding by reverting to GRAS-listed conventional milling to avoid registration timelines.
Buyer consolidation among multinational bakery chains is compressing supplier qualification cycles from annual to quarterly reviews. Procurement teams at Allied Bakeries and similar operators are unbundling ingredient certification from price negotiations, creating separate vendor pools for organic, conventional, and feed-grade bran. This bifurcation is most pronounced in the United Kingdom where retail label requirements exceed baseline EU standards.
Wheat Bran Market Segmentation
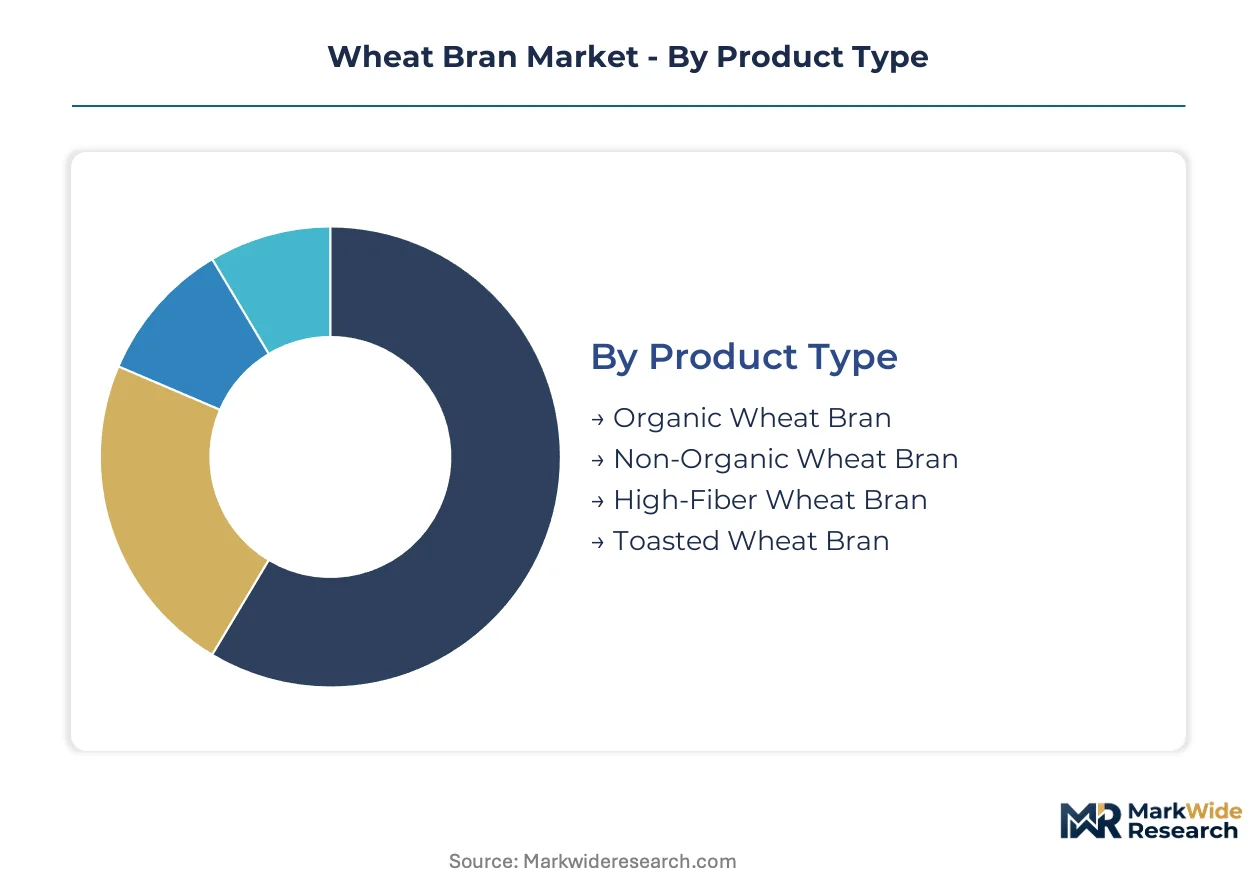
Wheat bran segmentation reflects divergent certification standards, processing intensities, and end-use specifications that command distinct margin structures across human and animal nutrition channels. Procurement teams segment supply chains by mycotoxin thresholds, organic provenance, and particle size distribution to align ingredient grades with regulatory and functional requirements.
Product Type:
Certification premiums drive buyer selection between organic and conventional supply chains, with particle modification and thermal processing creating additional tiering.
- Organic Wheat Bran:Certified supply chains restrict synthetic pesticide residues across three-year farm conversion periods. German nutraceutical brands source from transitioning Eastern European farms to capture supply before full organic premiums apply.
- Non-Organic Wheat Bran:Conventional milling byproduct streams dominate volume throughput in feed and standard bakery applications. North American elevator networks controlled by major grain traders concentrate origination for this grade.
- High-Fiber Wheat Bran:Elevated arabinoxylan content targets prebiotic extraction and digestive health positioning. Nutraceutical manufacturers in Germany isolate oligosaccharides for capsule formulations.
- Toasted Wheat Bran:Thermal treatment reduces moisture and extends shelf stability for beverage fortification. Ultrafine milling systems process toasted material into 200-500 micron particles for suspension stability.
Volume sits with Non-Organic Wheat Bran; growth tilts toward Organic Wheat Bran.
Application:
Functional requirements separate commodity feed rations from precision ingredients demanding validated health claims and sensory neutrality.
- Baking:Fiber enrichment in bread and pastry formulations requires specific particle size distribution to avoid texture degradation. Allied Bakeries unbundles ingredient certification from price negotiations in quarterly supplier reviews.
- Breakfast Cereals:Toasted bran adds crunch and fiber claims to extruded and flaked products. Cereal manufacturers specify moisture content below 12% to prevent rancidity in extended distribution.
- Health Supplements:Arabinoxylan extraction for prebiotic formulations commands the steepest expansion trajectory among all applications. German and United States manufacturers pull premium-grade organic bran into capsule and powder formulations.
- Animal Feed:Rumen fermentation modulation in dairy rations absorbs volume at compressed margins. Livestock nutritionists in Brazil formulate fiber-enriched rations to optimize volatile fatty acid production.
Feed applications hold volume dominance; supplement extraction climbs fastest.
Distribution Channel:
Channel selection reflects order scale, certification documentation requirements, and buyer proximity to processing infrastructure.
- Supermarkets:Packaged retail formats target home bakers and health-conscious consumers. Private label programs in the United Kingdom exceed baseline EU standards for fiber content claims.
- Online Retail:Direct-to-consumer wellness subscriptions bypass bulk ingredient channels through single-serve sachet formats. Nutraceutical distributors repackage bran powder into portion-controlled units.
- Health Food Stores:Specialty retailers emphasize organic certification and non-GMO verification. Staff education requirements favor established brands with documented supply chain transparency.
- Wholesale:Bulk totes and tanker shipments serve industrial bakeries and feed compounders. Cargill leverages its grain origination network to secure consistent supply for this channel.
Wholesale moves the tonnage; online retail expands most quickly.
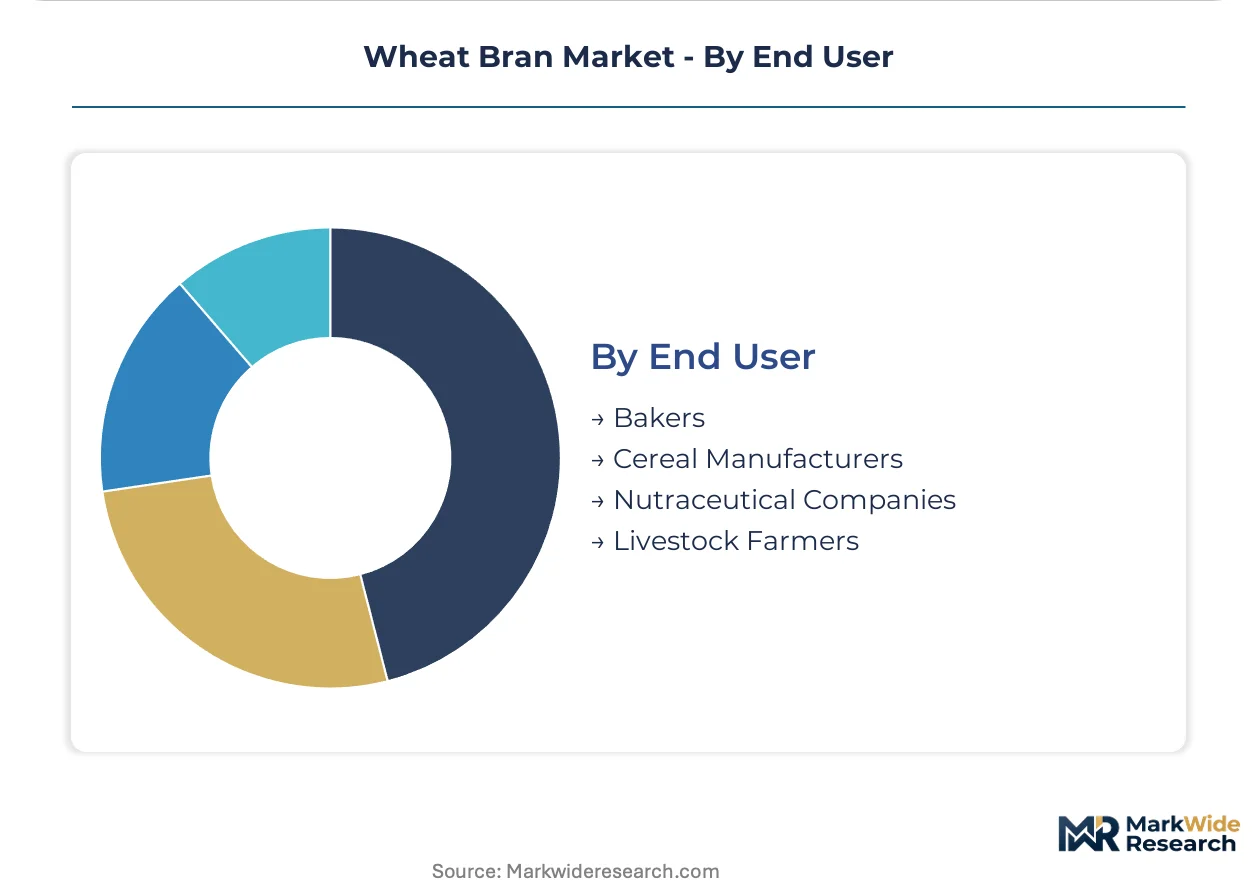
End User:
Technical sophistication and regulatory exposure vary sharply between industrial food manufacturers and agricultural operations.
- Bakers:Industrial operations demand consistent ash content and falling number specifications across production runs. Buyer consolidation among multinational chains compresses supplier qualification cycles.
- Cereal Manufacturers:Extrusion and flaking processes require precise moisture and fat content to prevent equipment fouling. Twinings distribution infrastructure anchors European demand through integrated sourcing.
- Nutraceutical Companies:Prebiotic and digestive health claims require validated arabinoxylan content and mycotoxin documentation. FSSAI enforcement in India creates certified supply chain premiums for compliant millers.
- Livestock Farmers:Dairy operations in the United States substitute soy hulls for wheat bran during unfavorable price spreads. Rumen fermentation science drives formulation decisions rather than ingredient loyalty.
Livestock Farmers consume the volume; Nutraceutical Companies gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Maharashtra and Gujarat concentrate India's wheat bran processing capacity, attracting feed compounders with tax incentives and proximity to grain belt logistics.
United States
Livestock nutritionists in Wisconsin and California formulate fiber-enriched dairy rations using wheat bran to optimize rumen fermentation. The FDA's Food Safety Modernization Act imposes preventive controls on animal food facilities handling wheat bran. Cargill leverages its North American elevator network to secure consistent supply from Midwest grain origination points.
Germany
Nutraceutical manufacturers in Bavaria isolate arabinoxylan oligosaccharides from wheat bran for prebiotic capsule formulations. REACH chemical registration requirements extend to novel extraction solvents used in processing. The EFSA maintains strict mycotoxin thresholds on cereal byproducts entering human food channels.
Brazil
Dairy operations in São Paulo state substitute wheat bran for soy hulls during favorable price spreads to maintain volatile fatty acid production. ANVISA enforces evolving food safety standards on imported milling byproducts. Integrated grain logistics in Paraná and Rio Grande do Sul anchor South American supply chain concentration.
India
FSSAI mycotoxin standards for human consumption create certified supply chain premiums for compliant millers in Punjab and Haryana. The regulator enforces maximum permissible thresholds that diverge processing standards between feed-grade and food-grade channels. Mumbai and Ahmedabad processing clusters handle bulk exports to Southeast Asian feed markets.
China
Health supplement manufacturers in Jiangsu and Zhejiang provinces extract functional fibers for digestive wellness positioning. SAMR oversees food safety registration requirements for novel ingredient applications. Yangtze River Delta milling infrastructure processes substantial volumes for both domestic feed and export nutraceutical channels.
Wheat Bran Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the wheat bran value chain. The market structure exhibits moderate consolidation, with major grain traders controlling origination networks while regional millers retain processing autonomy. Three archetypes dominate: integrated agricultural conglomerates with captive grain supply, independent milling specialists with flexible sourcing, and nutraceutical ingredient extractors with premium positioning. Competitive moves center on backward integration into elevator networks and portfolio diversification into organic certification tiers.
Among integrated agricultural conglomerates, Cargill, Wilmar International, and Associated British Foods exemplify scale-driven positioning. Cargill's North American elevator dominance secures origination access. Wilmar International anchors Southeast Asian supply chains through integrated palm and grain logistics extending into bran trading. Associated British Foods occupies European demand channels through Allied Bakeries and Twinings distribution infrastructure.
| Leading Market Players |
|---|
| Wilmar International |
| Siemer Milling Company |
| Cargill |
| ConAgra Foods |
| Hindustan Animal Feeds |
| Archer Daniels Midland (ADM) |
| Star of the West Milling |
| Associated British Foods |
| Bunge Limited |
| Others |
Supply Flow & Price Mechanics
Ultrafine milling systems capable of 200-500 micron particle reduction are simultaneously compressing processing costs and concentrating supply among capital-equipped millers in Germany and the United States. This technology shift allows beverage fortification applications to capture premium positioning previously reserved for soluble fiber isolates, while elevating barriers for conventional milling operations.
Pricing Analysis
Short lead-time premiums reward certified organic bran sourced from transitioning Eastern European farms before full organic conversion premiums apply. Three-tier pricing structure across premium organic, standard food-grade, and economy feed-grade levels reflects mycotoxin certification thresholds and particle size distribution. Cost compression in feed-grade channels intensifies as dairy operations substitute soy hulls during unfavorable price spreads. Livestock farmers exhibit highest price sensitivity due to formulation flexibility, while German nutraceutical brands absorb premiums for validated arabinoxylan content.
Supply Chain Analysis
Reverse-logistics flows for returned or off-specification bran create secondary feed-grade channels through reprocessing and thermal treatment. North American elevator networks controlled by major grain traders concentrate origination for premium-grade supply, while Indian processing clusters in Maharashtra and Gujarat handle bulk export volumes. Wheat futures volatility, synthetic pesticide residue testing, and mycotoxin segregation infrastructure constitute critical input dependencies. Single-source vulnerability emerges from dependency on Midwest grain origination points for food-grade certification. Distribution runs through Cargill's integrated origination network for wholesale industrial buyers and direct-to-consumer wellness subscriptions for nutraceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's Feed Hygiene Regulation functions as a cost-of-compliance moat, elevating processing infrastructure requirements that filter out sub-scale millers and consolidate margin capture among certified operators.
For Market Incumbents: Cement defensible positioning through backward integration into elevator networks across North American grain belts and parallel investment in dual food-feed line segregation infrastructure. Soy hull substitution threats from dairy operations demand volume commitment mechanisms in long-term feed contracts. Organic certification reciprocity agreements between exporting and importing jurisdictions represent the priority lever for preserving premium channel access. For New Entrants and Emerging Players: Arabinoxylan extraction technology offers a technology-first wedge into nutraceutical supply chains serving German and United States capsule manufacturers. White-space concentrates in certified organic bran from Eastern European farms completing three-year conversion periods, bypassing incumbent origination dominance. Direct-to-consumer wellness subscriptions through single-serve sachet formats enable channel bypass of bulk ingredient gatekeepers. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated agricultural conglomerates with captive grain supply and validated organic certification tiers. Long-term viability hinges on differentiation from commodity feed-grade exposure through precision ingredient positioning in prebiotic extraction. Monitor FSSAI enforcement intensity in India as an inflection indicator for certified supply chain premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elevator Networks | Cargill's origination dominance secures consistent bran supply from Midwest grain points. |
| Organic Certification Investment | Three-year farm conversion periods create supply scarcity premiums for early certifiers. |
| Arabinoxylan Extraction Scale-Up | German nutraceutical manufacturers isolate prebiotic oligosaccharides for capsule formulations. |
| Dual Food-Feed Line Segregation | FDA preventive controls mandate physical separation infrastructure and documented cleaning validations. |
| Direct-to-Consumer Channel Launch | Single-serve sachet formats bypass bulk ingredient channels for wellness subscription revenue. |
Methodological Framework
Independent corroboration across milling operations executives, livestock nutritionists, nutraceutical procurement leads, and grain trading desk managers underwrites the qualitative findings in this study. Primary fieldwork combined with secondary validation from customs and trade data, FSSAI enforcement records, FDA preventive control guidance documents, and EU Feed Hygiene Regulation compliance filings anchors supply chain and pricing intelligence. Bottom-up volume triangulation against top-down market sizing ensures internal consistency across segmentation outputs.
Comparable historical reference periods spanning conventional milling, organic transition, and precision extraction phases anchored the forecast window across the analysis window. Modeled segmentation dimensions include certification tier, particle size distribution, application channel, and geographic regulatory cluster. CAGRs derive from trend extrapolation calibrated against input cost elasticity and substitution dynamics. Wheat futures volatility curves and mycotoxin testing protocol evolution constitute industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including force majeure crop failures, abrupt regulatory reciprocity suspensions, and breakthrough synthetic fiber substitutes. Forecasts reflect documented assumptions regarding organic conversion timeline adherence and feed substitution elasticity. Practitioners should monitor EU CSRD supply chain disclosure requirements and REACH chemical registration timelines for early signals of compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Organic Wheat Flour Market
Grains
Pulses Market
Grains
South America Rice Market
Grains
United States Rice Market
Grains
Organic Oats Market
Grains
Durum Wheat Flour Market
Grains
Rice Flour Market
Grains
Corn Flour Market
Grains
Organic Cereals Market
Grains
Grain Bins Market
Grains
Europe Rice Market
Grains
Whole-Wheat Flour Market
Grains
Colombia Grains Market
Grains
Asia-Pacific Guar Market
Grains
Barley Grass Market
Grains
India Rice Market