
 Cultured Wheat Market | 2026-2036
Cultured Wheat Market Size, Share, and Industry Trends Forecast 2026-2036
Cultured Wheat Market Outlook
Asset-light fermentation-as-a-service models are reshaping competitive entry barriers in cultured wheat production. ADM leverages its existing grain handling infrastructure to secure feedstock cost advantages. Cargill sustains geographic dominance through North American supply chain density. MGP Ingredients specializes in specialty wheat derivatives that command premium positioning among bakeries.
Cultured wheat denotes wheat flour or grain subjected to controlled fermentation with specific bacterial or yeast cultures, yielding enhanced flavor profiles, extended shelf stability, and reduced preservative requirements for commercial food production. The process typically employs Lactobacillus or Propionibacterium strains at monitored pH levels between 4.5 and 5.5 to achieve targeted acidification and enzyme activity. Baked Goods applications lead volume consumption due to widespread clean-label reformulation across commercial bakeries. Pasta segments represent the fastest-growing application as manufacturers replace chemical preservatives with biologically cultured wheat ingredients. Whole Wheat product types anchor the premium tier, where fermentation-derived tang and extended freshness justify higher input costs for health-focused brands.
USDA organic certification requirements and FDA food additive regulations shape ingredient disclosure standards and fermentation process validation for cultured wheat entrants. EFSA novel food assessments govern European market access, while ISO 22000 frameworks establish hazard control benchmarks for international trade. Stakeholders must monitor evolving fermentation labeling thresholds that could bifurcate product positioning between artisan-claim and industrial-grade supply tiers.
Market Dynamics
Fermentation-as-a-service platforms are compressing capital barriers for cultured wheat entrants, allowing regional bakeries to access bioprocessing capabilities without building captive facilities. This structural shift redistributes value capture from equipment manufacturers to contract fermentation operators.
Growth Catalysts
- Clean-label mandates:FDA disclosure requirements for preservatives drive commercial bakeries toward biologically acidified wheat derivatives that reduce synthetic additive counts.
- Pasta reformulation:Italian and German pasta manufacturers accelerate adoption of cultured wheat to replace sorbates and benzoates in extended-shelf-life products.
- EFSA novel food pathways:Streamlined assessment frameworks for fermentation-derived ingredients accelerate European market entry timelines relative to historical biotech approvals.
Market Restraints
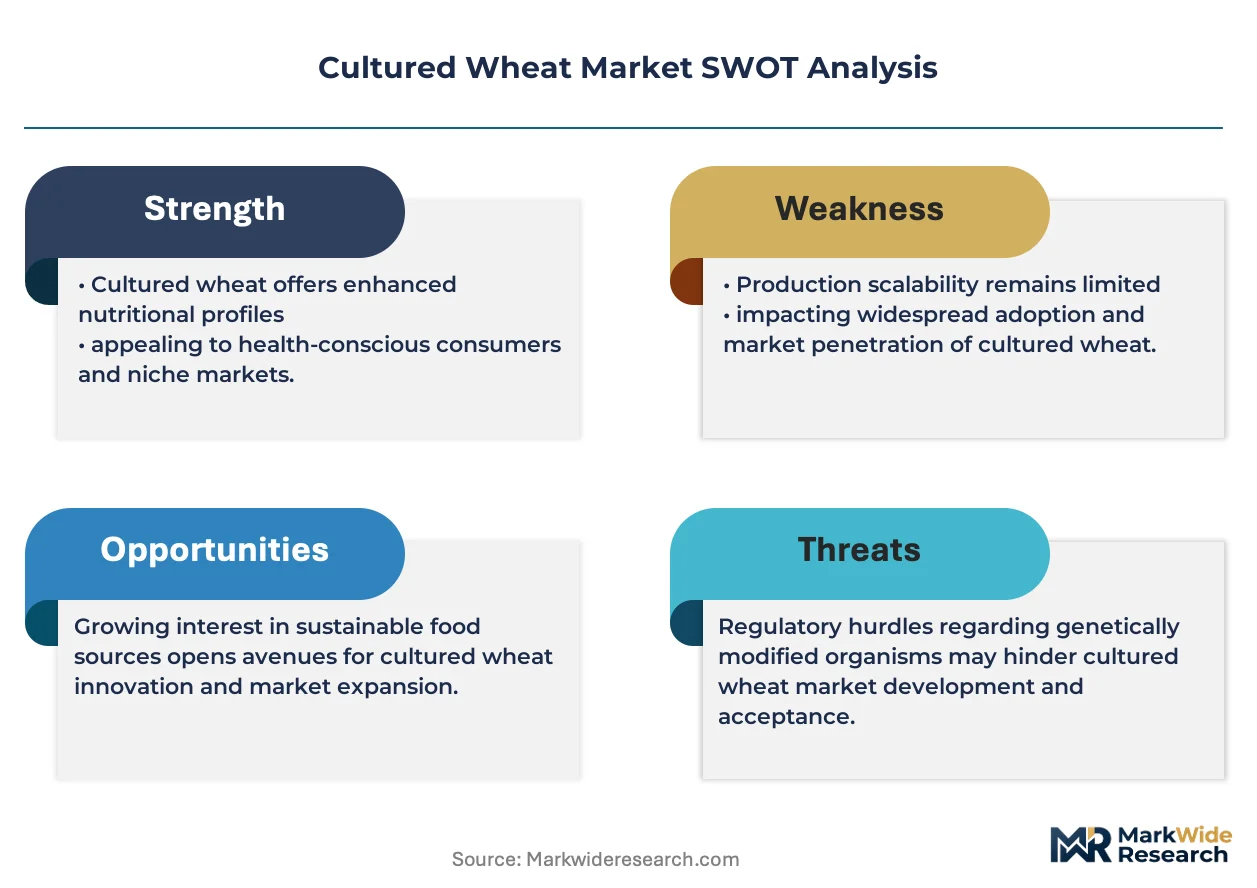
- Feedstock concentration:North American hard red wheat supply tightness creates input cost volatility for fermentation facilities dependent on specific protein grades.
- Propionibacterium strain scarcity:Limited qualified culture suppliers constrain production scaling for manufacturers targeting precise pH acidification profiles.
- USDA organic compliance friction:Certification requirements for fermentation inputs create documentation burdens that disqualify conventional wheat streams from premium positioning.
Strategic Opportunities
- South Korean bakery penetration:Underdeveloped clean-label ingredient supply creates first-mover positioning for cultured wheat exporters meeting MFDS fermentation standards.
- Precision fermentation convergence:Integration of AI-driven bioreactor controls with traditional wheat substrate processing enables real-time pH optimization and yield improvements.
- Direct-to-bakery distribution:Bypassing ingredient distributors through regional fermentation hubs captures margin and accelerates technical service response times.
Industry Challenges
- ISO 22000 implementation timelines:Hazard analysis documentation requirements delay facility certifications by 8-14 months for new fermentation entrants.
- Legacy mixing equipment incompatibility:Existing bakery infrastructure requires retrofitting to handle higher-moisture cultured wheat doughs without process reengineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cultured Wheat Market |
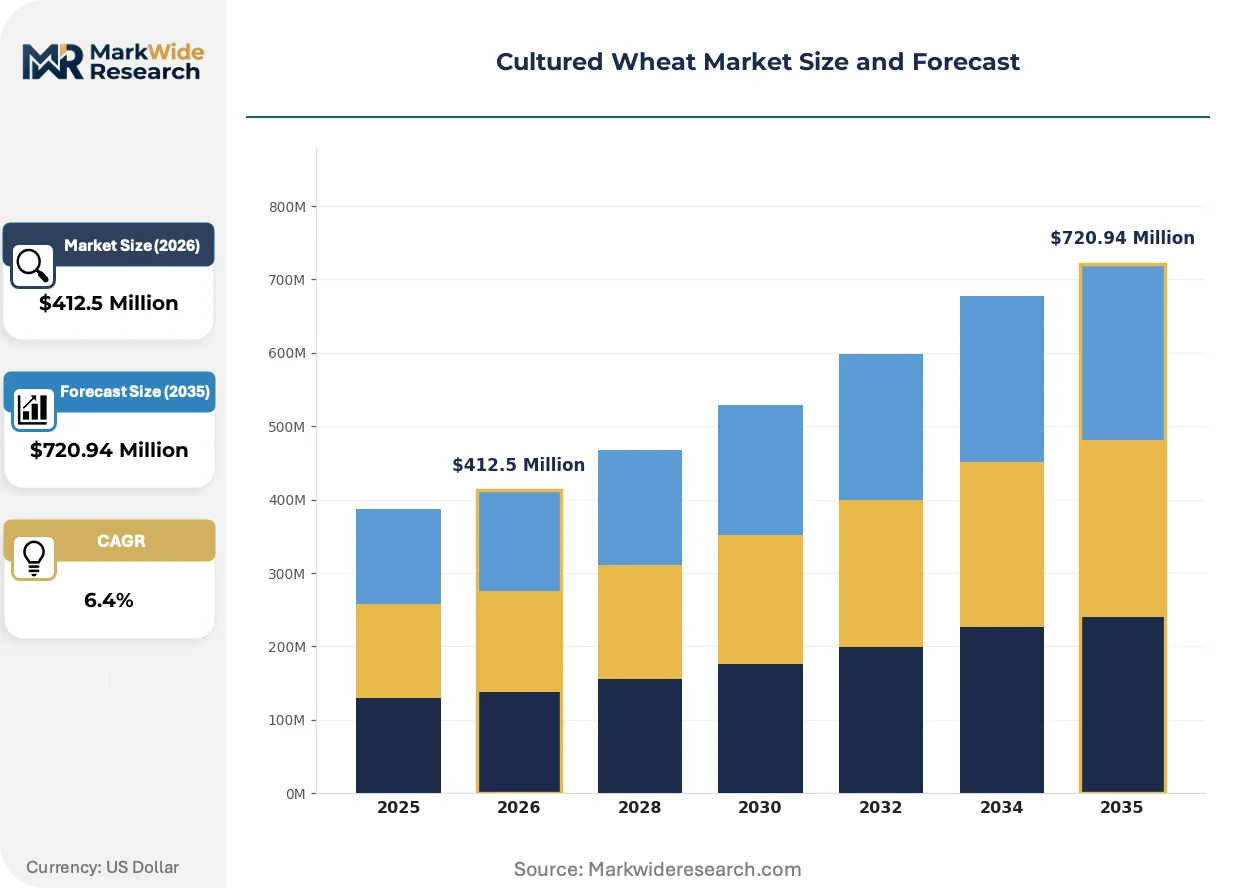
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, White Wheat, Durum Wheat, Soft Wheat End User: Bakeries, Food Manufacturers, Restaurants, Health Stores Application: Baked Goods, Pasta, Cereals, Snacks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | IFF, Perfect Day, ADM, Every Company, Nature's Fynd, Cargill, DuPont Nutrition & Biosciences, Motif FoodWorks, MGP Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cultured Wheat Market Strategic Shifts
Bioprocess control technologies are transforming how fermentation parameters are monitored and adjusted, compressing batch-to-batch variability and enabling consistent acidification outputs. This shift underpins quality standardization across distributed production networks.
Sensor-integrated bioreactor systems is digitizing pH and temperature monitoring in commercial fermentation facilities, replacing manual sampling protocols. Mid-scale bakery ingredient suppliers deploy these systems fastest, driven by contract specifications from national bakery chains. The technology is digitizing quality assurance workflows and reducing laboratory testing overhead for batch release decisions.
EU Green Deal sustainable food system targets are tightening disclosure requirements for processing aids and fermentation-derived ingredients. Manufacturers must now document carbon intensity across wheat cultivation, transport, and bioprocessing stages. German and Dutch bakery brands respond fastest, reformulating around EFSA-registered fermentation processes that qualify for environmental claim substantiation.
Specification-driven procurement now dominates bakery ingredient purchasing, with technical teams mandating acidification curves and enzyme activity ranges rather than accepting generic fermented wheat grades. Ingredient distributors lose influence as buyers contract directly with fermentation operators for customized culture blends. This pattern concentrates in the United States, where national bakery chains centralize R&D and enforce uniform ingredient standards across regional production facilities.
Cultured Wheat Market Segmentation
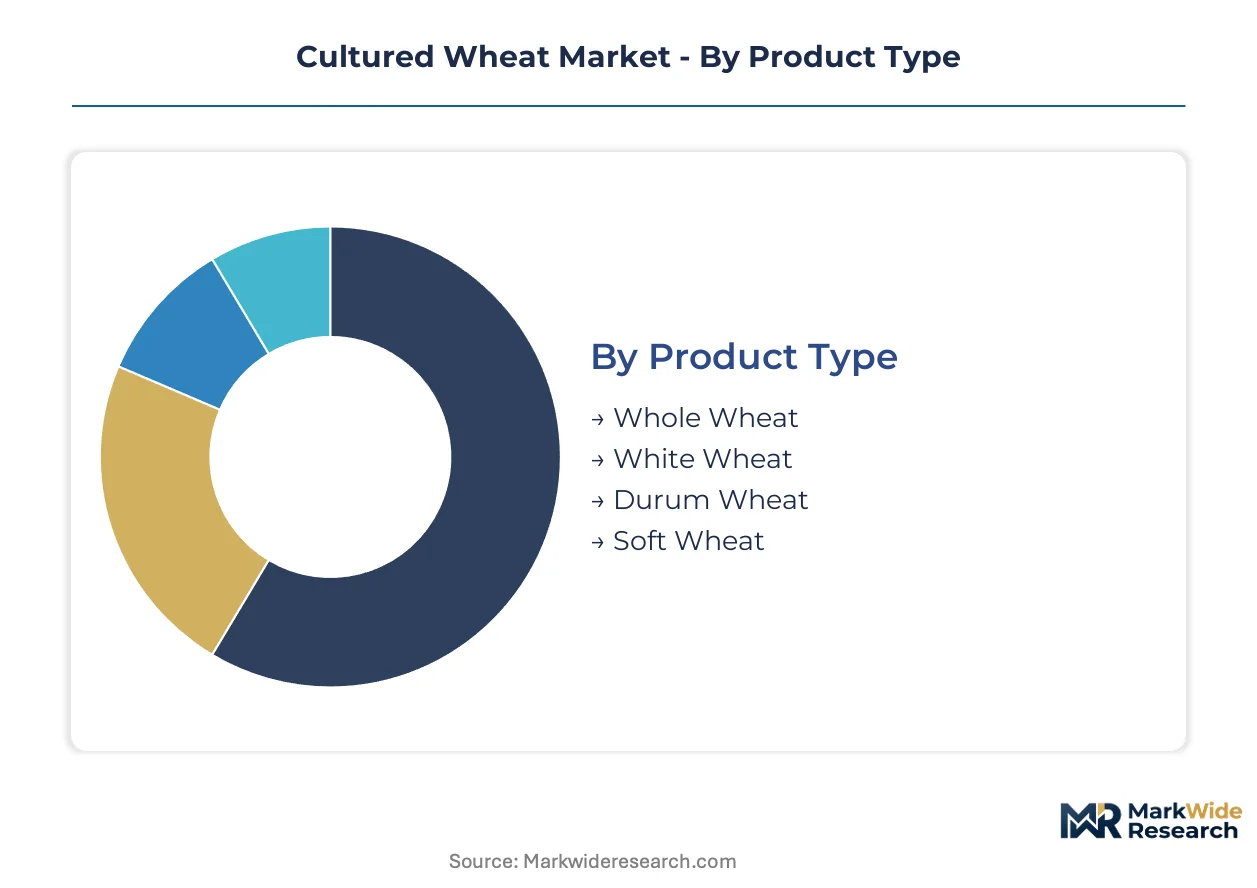
Cultured wheat producers must align fermentation specifications with distinct buyer requirements across wheat varieties, commercial channels, and end-use applications. Segmentation discipline separates commodity-grade suppliers from premium-positioned operators commanding technical service premiums.
Product Type:
Cost tier differentiation separates commodity fermentation feedstocks from premium wheat grades commanding specialized culture protocols and extended processing cycles.
- Whole Wheat:Higher bran content demands extended fermentation cycles to achieve target pH reduction without compromising fiber integrity. German artisan bakeries and US organic brands concentrate demand here, paying premiums for fermentation-derived shelf stability that eliminates chemical preservatives in whole-grain formulations.
- White Wheat:Lower protein interference enables precise acidification control, making this the standard feedstock for industrial-scale fermentation facilities. Italian pasta manufacturers and North American commercial bakeries drive volume procurement, prioritizing batch consistency over terroir claims.
- Durum Wheat:Semolina-focused applications in Mediterranean pasta production require culture strains selected for minimal gluten degradation during acidification.
- Soft Wheat:Low protein grades suit pastry and cake applications where fermentation must enhance flavor without toughening crumb structure.
White Wheat holds installed capacity. Whole Wheat is rotating up the share rankings.
End User:
Application maturity varies sharply across customer types, with industrial bakeries demanding specification-driven procurement while foodservice operators prioritize supply reliability.
- Bakeries:National chains enforce acidification curve specifications and enzyme activity ranges through direct contracts with fermentation operators. Clean-label reformulation mandates from US and German retail channels accelerate adoption, with technical teams rejecting generic grades in favor of culture-blend customization.
- Food Manufacturers:Pasta and cereal producers integrate cultured wheat as a drop-in preservative replacement, requiring documentation for EFSA novel food registrations or FDA GRAS self-determinations. Extended-shelf-life product lines in Italy and Germany represent the steepest expansion trajectory.
- Restaurants:Artisan bakery concepts and farm-to-table operators source small-batch cultured wheat for house-made bread programs, valuing fermentation storytelling over cost optimization.
- Health Stores:Organic certification compliance and non-GMO verification dominate procurement criteria, with USDA organic documentation requirements filtering conventional wheat streams from this channel.
Food Manufacturers hold installed capacity. Bakeries are climbing the fastest.
Application:
Volume concentration and margin structure diverge across food categories, with baked goods anchoring current throughput and pasta applications expanding most quickly.
- Baked Goods:Commercial bread, bun, and roll production consumes the largest fermentation volumes, with pH-controlled acidification replacing calcium propionate and sorbic acid in clean-label reformulations. US national bakery chains centralize R&D and enforce uniform ingredient standards across regional production facilities.
- Pasta:Extended-shelf-life dried pasta and fresh refrigerated lines replace chemical preservatives with biologically acidified wheat, with Italian and German manufacturers leading adoption. EFSA novel food pathway streamlining accelerates European market entry relative to historical biotech approvals.
- Cereals:Breakfast and snack cereal applications leverage fermentation for flavor modulation and moisture management in extruded products.
- Snacks:Cracker and savory biscuit producers utilize cultured wheat for texture optimization and reduced additive counts in premium positioning.
Baked Goods hold installed capacity. Pasta is gaining share fastest.
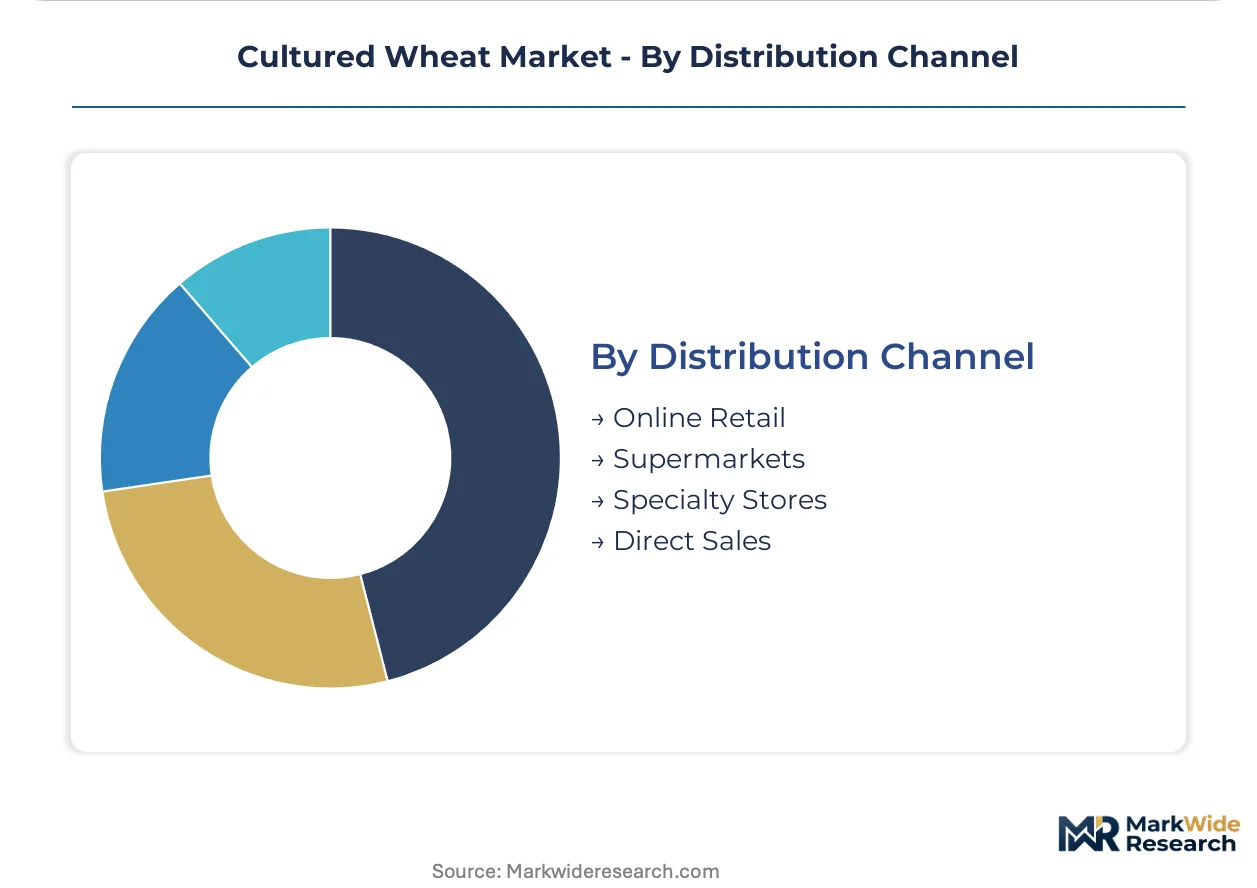
Distribution Channel:
Supply concentration and margin capture shift as direct contracting erodes traditional distributor influence in specification-driven segments.
- Direct Sales:Fermentation-as-a-service platforms and regional fermentation hubs bypass ingredient distributors to capture margin and accelerate technical service response times. National bakery chains and multinational pasta manufacturers concentrate procurement here, mandating customized culture blends and real-time quality documentation.
- Supermarkets:Mass-market retail channels move commodity-grade cultured wheat through established grocery supply chains, with private-label programs driving volume.
- Specialty Stores:Organic and natural food retailers serve health-focused brands and artisan producers requiring small-batch flexibility and certification transparency.
- Online Retail:E-commerce platforms facilitate ingredient access for regional bakeries and restaurants without established distributor relationships, particularly in underdeveloped clean-label markets.
Supermarkets hold installed capacity. Direct Sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bakery chains command 15-20% price premiums for organic cultured wheat formulations, while US commercial bakeries operate on thinner margins constrained by national retail pricing agreements. This asymmetry concentrates premium product development in European fermentation facilities.
United States
National bakery chains drive specification-driven procurement for clean-label reformulation, mandating acidification curves and enzyme activity ranges through direct fermentation operator contracts. FDA disclosure requirements for preservatives accelerate biologically acidified wheat adoption. Chicago and Minneapolis-St. Paul anchor industrial fermentation capacity serving nationwide distribution networks.
Germany
Artisan bakeries and organic brands concentrate demand for whole wheat fermentation-derived shelf stability, paying premiums that eliminate chemical preservatives. EFSA novel food assessments govern market access for fermentation-derived ingredients. The Munich-Stuttgart corridor hosts specialized culture suppliers serving premium bakery segments across German-speaking Europe.
Italy
Pasta manufacturers accelerate adoption of cultured wheat to replace sorbates and benzoates in extended-shelf-life dried and fresh refrigerated lines. EU Green Deal sustainable food system targets tighten processing aid disclosure requirements. Emilia-Romagna's pasta production clusters integrate biologically acidified wheat into reformulated product lines for export markets.
South Korea
Underdeveloped clean-label ingredient supply creates first-mover positioning opportunities for cultured wheat exporters meeting MFDS fermentation standards. Bakery franchise expansion drives demand for shelf-stable clean-label formulations. Seoul's commercial bakery R&D centers pilot imported cultured wheat for domestic reformulation programs.
Netherlands
Dutch bakery brands respond fastest to EU environmental claim substantiation requirements, reformulating around EFSA-registered fermentation processes. Rotterdam's port infrastructure facilitates wheat feedstock import for fermentation facilities serving northwest European markets. Wageningen University partnerships accelerate precision fermentation research for commercial bakery applications.
Cultured Wheat Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying culture strains and fermentation infrastructure. The vendor base distributes across integrated grain processors, dedicated fermentation operators, and specialty ingredient formulators. Three archetypes dominate: captive fermentation divisions of agribusiness conglomerates, independent fermentation-as-a-service platforms, and boutique culture suppliers. Capacity expansion and direct-to-bakery distribution partnerships constitute the primary competitive moves reshaping channel control.
Among agribusiness conglomerates with captive fermentation capabilities, ADM leverages existing grain handling infrastructure while Cargill sustains North American supply chain density. MGP Ingredients exemplifies the specialty wheat derivatives archetype commanding premium positioning among specification-driven bakery buyers. These three entities anchor distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| IFF |
| Perfect Day |
| ADM |
| Every Company |
| Nature's Fynd |
| Cargill |
| DuPont Nutrition & Biosciences |
| Motif FoodWorks |
| MGP Ingredients |
| Others |
Value Chain & Pricing Dynamics
Feedstock concentration in North American hard red wheat creates input cost volatility that compresses margin spreads between premium organic and conventional cultured wheat tiers while forcing fermentation facilities toward multi-source sourcing strategies. This dependency structure simultaneously widens price differentiation across certification grades and reshapes facility location decisions around grain handling infrastructure.
Pricing Analysis
Industrial bakery buyers anchor contract-based long-term offtake structures, with pricing stratifying across USDA organic, EFSA-registered, and conventional fermentation tiers. Price differentiation rests on certification documentation depth and culture strain traceability, with organic commands absorbing 15-20% premiums in German markets. Cost compression in conventional white wheat tiers is intensifying because fermentation-as-a-service platforms commoditize basic acidification capabilities. National bakery chains exhibit lowest price sensitivity due to clean-label mandate compliance costs, while regional food manufacturers face acute margin pressure from feedstock volatility.
Supply Chain Analysis
Tariff exposure between the United States and key wheat-exporting regions dominates supply chain risk calculus for fermentation facilities dependent on specific protein grades. Geographic supply concentration centers on the United States, Germany, and Canada for hard red wheat feedstocks, with Italian durum wheat serving Mediterranean pasta applications. Raw material dependencies draw from qualified Propionibacterium culture suppliers, pH monitoring sensor systems, and organic-certified grain handling infrastructure. Single-source vulnerability in qualified culture strain supply constrains production scaling for precise acidification profiles. Distribution runs through direct fermentation operator contracts for specification-driven buyers, with ingredient distributors retaining commodity-grade volume channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cultured wheat market sits in a cyclical recovery phase driven by clean-label reformulation mandates across commercial bakery and pasta manufacturing, with capital deployment favoring fermentation-as-a-service platforms over captive facility builds.
For Market Incumbents: Build certification moats through EFSA novel food registration depth and USDA organic compliance infrastructure that emerging fermentation-as-a-service platforms cannot replicate quickly. Defensive consolidation should prioritize backward integration into grain handling infrastructure in Minneapolis-St. Paul and Chicago corridors to secure feedstock cost advantages against ADM and Cargill positioning. Channel control through direct-to-bakery technical service contracts protects margin capture from distributor disintermediation. For New Entrants and Emerging Players: Establish a beachhead in South Korean bakery supply chains where MFDS fermentation standards create qualification barriers for incumbent exporters and local clean-label ingredient supply remains underdeveloped. The most penetrable white space sits in precision fermentation convergence for real-time pH optimization, with AI-driven bioreactor controls offering technical differentiation against legacy manual sampling protocols. Go-to-market execution should leverage regional fermentation hub partnerships rather than greenfield facility investment. For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors fermentation-as-a-service platform operators with existing bioreactor capacity and culture strain libraries over de novo technology developers. Long-term viability across the analysis window rests on contract fermentation operators capturing margin from ingredient distributor displacement and specification-driven procurement concentration. Acquisition target archetypes include boutique culture suppliers with Propionibacterium strain qualification and mid-scale bakery ingredient suppliers with sensor-integrated quality systems. The signal to watch is national bakery chain direct contracting velocity as an indicator of channel control shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation-as-a-Service Platform Expansion | Lowers capital barriers for regional bakeries accessing bioprocessing without captive facilities. |
| Direct-to-Bakery Distribution Buildout | Bypasses ingredient distributors to capture margin and accelerate technical service response times. |
| EFSA Novel Food Registration Investment | Secures European market access for fermentation-derived ingredients ahead of competitor filings. |
| Precision Fermentation Technology Integration | Enables AI-driven bioreactor controls for real-time pH optimization and yield improvements. |
| Backward Integration into Grain Handling | Secures feedstock cost advantages through control over North American hard red wheat supply. |
Study Parameters
The analysis maps fermentation technology tiers, wheat variety specifications, and end-user application segments, each validated through fermentation operations directors, bakery chain procurement leads, and specialty ingredient distributors. Primary interviews with plant managers at commercial fermentation facilities, technical R&D directors at national bakery chains, and regulatory affairs specialists navigating EFSA novel food pathways combined with secondary validation from FDA GRAS determination filings, USDA organic certification databases, and customs trade data on wheat feedstock flows. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Assumptions held fixed include EFSA regulatory pathway streamlining continuity and clean-label mandate enforcement intensity across US and German retail channels, while fermentation technology cost curves and culture strain supplier concentration were varied across sensitivity scenarios. Segmentation dimensions modeled encompass wheat variety, end-user archetype, application category, and distribution channel structure. CAGRs were derived from installed capacity buildout timelines and adoption curve penetration rates for preservative replacement applications, with pasta reformulation velocity and bakery chain specification enforcement serving as key forecast inputs.
Stress conditions across feedstock price volatility bands, regulatory approval timeline extensions, and fermentation technology cost compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clean-label mandate durability and fermentation-as-a-service platform scalability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Spelt Wheat Market
Grains
Egypt Rice Market
Grains
Tunisia Grain Market
Grains
Sorghum Market
Grains
Bangladesh Rice Market
Grains
Chickpeas Market
Grains
Green Pea Grits Market
Grains
Uganda Grains Market
Grains
North America Rice Market
Grains
Europe Maize Market
Grains
Basmati Rice Market
Grains
North America Wheat Market
Grains
Soya Flour Market
Grains
Whole-Wheat Flour Market
Grains
Global Maize Market
Grains
Grain Silos and Storage System Market