
 United States Rice Market | 2026-2036
United States Rice Market Size, Share, and Industry Trends Forecast 2026-2036
United States Rice Market Analytics
Food service procurement is shifting toward aromatic and specialty rice varieties as restaurant chains reformulate menus. Riceland Foods leverages its cooperative structure to sustain volume across the mid-South. Riviana Foods competes through branded retail positioning in jasmine and basmati segments. Cargill anchors industrial supply chains with bulk handling infrastructure.
United States rice comprises Oryza sativa grain cultivated across flooded paddy fields, with milling operations producing polished white, whole-grain brown, or aromatic varieties at moisture contents typically below 14 percent for stable storage. The crop serves as a staple carbohydrate source for direct consumption, processed food ingredients, and brewing applications. White rice occupies the largest volume share among product types due to its extended shelf life and broad culinary compatibility, while brown rice captures expanding health-oriented retail shelf space. Food processing end users represent the fastest-growing demand channel as manufacturers incorporate rice flour and syrup into gluten-free and clean-label formulations.
USDA Federal Grain Inspection Service standards govern grade classifications and moisture limits, while EPA Clean Water Act provisions regulate paddy runoff and pesticide discharge in major production counties. California State Water Resources Control Board allocations increasingly constrain planting decisions in the Sacramento Valley. State-level rice check-off programs coordinate research funding across Arkansas, Louisiana, and Texas. Stakeholders must monitor water rights adjudication and evolving FDA guidance on arsenic thresholds in infant rice cereals.
Market Dynamics
Water scarcity in California's Sacramento Valley is forcing acreage contraction while Arkansas-Louisiana-Mississippi Delta growers absorb displaced volume, tightening regional supply concentration and amplifying price volatility for medium-grain varieties.
Growth Catalysts
- Gluten-free food processing:Rice flour and syrup incorporation into clean-label baked goods and snack formulations is accelerating demand from manufacturers seeking wheat alternatives.
- USDA Federal Grain Inspection Service standards:Uniform grade classifications enable transparent commodity trading and reduce quality arbitrage across domestic elevators.
- Arkansas rice check-off programs:State-level research funding coordinates varietal development for drought tolerance and blast resistance across the mid-South production belt.
Market Restraints
- California State Water Resources Control Board allocations:Surface water cuts have eliminated planting on 25,000+ acres since 2022, permanently shifting medium-grain production geography.
- Imported aromatic rice substitution:Thai and Indian jasmine and basmati varieties capture price-sensitive retail segments despite domestic long-grain availability.
- Input cost volatility:Diesel, urea, and glyphosate price spikes compress operating margins for Delta growers lacking forward-contract coverage.
Strategic Opportunities
- Texas Gulf Coast expansion:Underutilized rice acreage in Jefferson and Chambers counties offers irrigation infrastructure for specialty aromatic cultivation.
- Brewing and distilling applications:Craft breweries and rice-spirit producers are sourcing specific amylose-content varieties for fermentation performance.
- FDA arsenic guidance alignment:Infant cereal manufacturers are qualifying low-arsenic California and Arkansas sourcing to preempt regulatory thresholds.
Industry Challenges
- Milling automation retrofit costs:Legacy equipment in small and mid-sized mills requires capital investment to achieve optical sorting precision demanded by export markets.
- Water rights adjudication complexity:Groundwater sustainability agency rulings in the Sacramento Valley create permitting uncertainty for multi-year crop planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Rice Market |
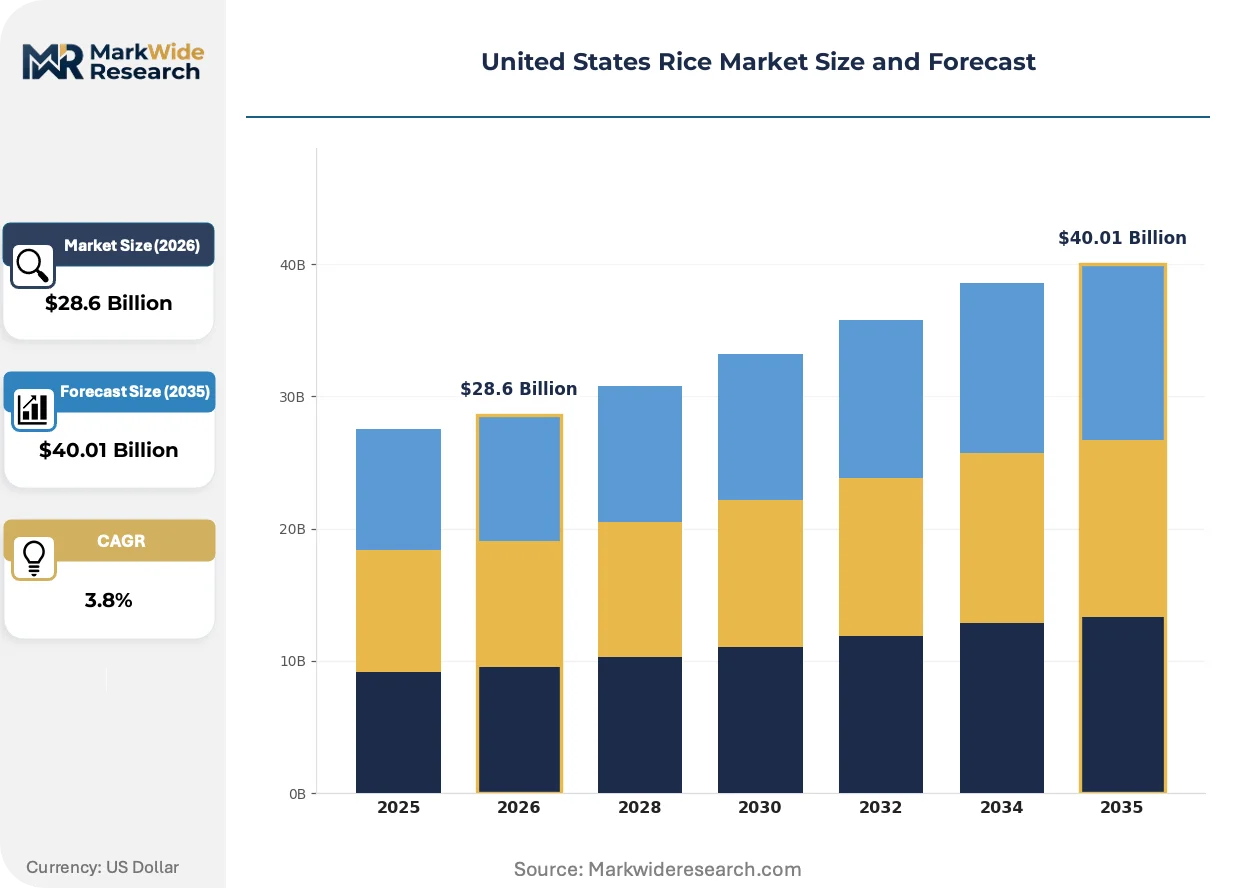
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $40.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice, Brown Rice, Basmati Rice, Jasmine Rice End User: Household, Food Service, Food Processing, Exporters Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores Packaging Type: Bags, Boxes, Bulk, Cans |
| Companies Covered | Riceland Foods, American Rice, Farmers' Rice Cooperative, Riviana Foods, Diversified Ingredients, American Commodity Company, Cargill, USA Rice, Planet Rice, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Rice Market Evolving Landscape
Digital agriculture tools and precision irrigation systems are penetrating rice cultivation at accelerating rates, while regulatory pressure on water use and chemical inputs forces operational redesign across the production base.
Variable-rate irrigation technology is converging with satellite-derived evapotranspiration data to enable field-specific water application. Large Delta operations are deploying these systems to document conservation compliance for state nutrient reduction strategies. The technology is converging with carbon credit verification platforms, allowing growers to monetize methane reduction from alternate wetting and drying protocols.
EPA Clean Water Act provisions governing paddy runoff and pesticide discharge are tightening enforcement in Arkansas and Louisiana production counties. Industrial consequence includes mandatory buffer zones and constructed wetland requirements that add fixed costs per acre. Smallholder operations in the Mississippi Delta are consolidating or exiting as compliance timelines compress, accelerating cooperative and corporate farm expansion.
Restaurant chain procurement teams are reformulating around specific rice varieties with traceable origin credentials. Branded menu claims now specify Arkansas long-grain or California Calrose provenance, displacing anonymous commodity sourcing. Food service distributors in the Southeast and Mid-Atlantic are building direct elevator relationships to secure identity-preserved supply for chain accounts.
United States Rice Market Segmentation
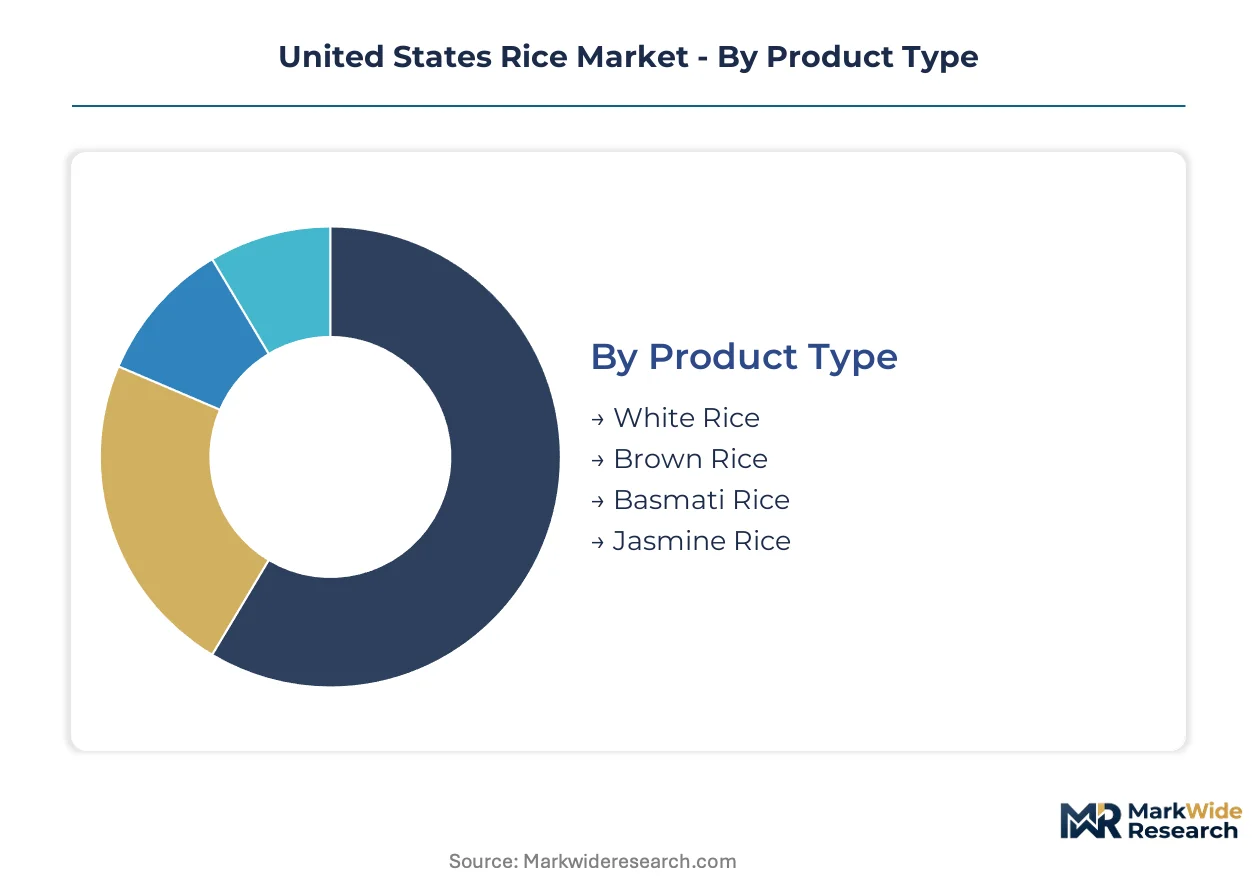
Segmentation in the United States rice market reveals how milling specifications, procurement channels, and packaging formats align with distinct buyer workflows. Each category carries implications for moisture management, identity preservation, and shelf-life extension.
Product Type:
Standardization dominates commodity grades while aromatic varieties command premium customization through varietal specificity and origin documentation.
- White Rice:Milled to remove bran and germ layers, achieving moisture content below 14 percent for extended storage stability. Arkansas-Louisiana-Mississippi Delta elevators move the largest volumes to food service distributors and industrial processors seeking consistent amylose content for texture control.
- Brown Rice:Retains bran layer with higher fiber and oil content, requiring refrigerated supply chains or rapid turnover. California Calrose brown rice captures expanding retail shelf space in health-oriented West Coast markets as FDA arsenic guidance tightens on infant cereal applications.
- Basmati Rice:Aromatic long-grain variety with distinct elongation ratio upon cooking, sourced through identity-preserved supply chains.
- Jasmine Rice:Thai-origin aromatic competing against domestic long-grain in price-sensitive retail segments.
Leading the category by volume: White Rice. Growing fastest: Brown Rice.
End User:
Volume concentration shifts from direct consumption toward ingredient manufacturing as formulation science advances rice-derived applications.
- Food Processing:Manufacturers incorporate rice flour, starch, and syrup into gluten-free baked goods, snack coatings, and clean-label thickeners. Arkansas and Louisiana mills are retrofitting optical sorting lines to meet flour-grade purity specifications demanded by national bakery chains.
- Household:Retail consumers purchase packaged rice through supermarkets and online channels, with purchasing decisions driven by cooking time convenience and nutritional claims.
- Food Service:Restaurant chains specify origin-verified varieties for menu transparency, contracting directly with Delta cooperatives.
- Exporters:Bulk shipments to Caribbean and Central American markets require USDA Federal Grain Inspection Service grading compliance.
Dominant by tonnage: Food Processing. Steepest expansion trajectory: Food Service procurement of traceable-origin varieties.
Distribution Channel:
Channel selection determines margin capture, with direct-to-processor routes bypassing retail markups while requiring volume commitments.
- Supermarkets:Traditional retail channel for branded and private-label packaged rice, controlling the largest consumer-facing volume.
- Wholesale:Food service distributors and institutional buyers source bulk and intermediate packaging through regional elevator networks.
- Online Retail:Direct-to-consumer and subscription models for specialty aromatic varieties, growing fastest in urban coastal markets.
- Specialty Stores:Ethnic grocery channels for imported jasmine and basmati, competing on authenticity claims.
Primary volume route: Supermarkets. Gaining share fastest: Online Retail.
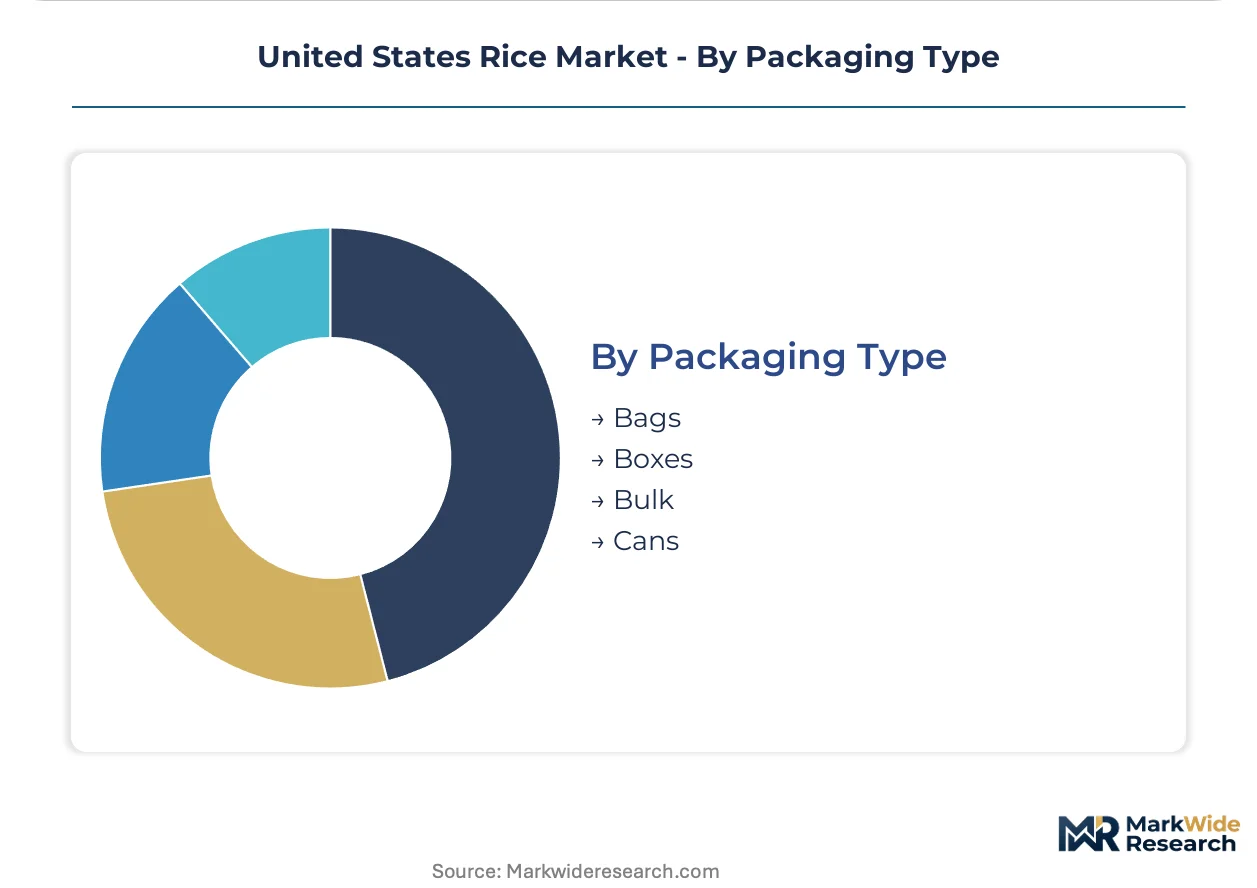
Packaging Type:
Packaging economics reflect handling automation compatibility and shelf-life requirements across supply chain nodes.
- Bulk:Rail and barge shipments to industrial processors and exporters, minimizing per-unit packaging cost at scale.
- Bags:Standard retail and food service format, with multi-layer laminates replacing plain polypropylene for moisture barrier improvement.
- Boxes:Premium retail presentation for aromatic and organic varieties, supporting shelf differentiation.
- Cans:Precooked and ready-to-heat formats for convenience-oriented household segments.
Highest throughput: Bulk. Expanding most quickly: Bags with enhanced barrier properties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arkansas's rice check-off program and cooperative infrastructure anchor production concentration across the mid-South, while California's water allocation constraints force geographic displacement toward the Delta corridor.
Arkansas
Food processing demand for rice flour and syrup drives acreage expansion in the Grand Prairie and Mississippi Delta counties. The Arkansas Natural Resources Commission coordinates groundwater sustainability planning with USDA conservation programs. Stuttgart-based milling clusters process identity-preserved long-grain for restaurant chain contracts.
California
Specialty medium-grain and Calrose brown rice production contracts under State Water Resources Control Board surface water cuts. Sacramento Valley growers face groundwater sustainability agency adjudication threatening multi-year planting certainty. Colusa-Glenn county cooperatives pivot toward low-arsenic certification for infant cereal supply chains.
Louisiana
Cajun food service procurement and export elevator access sustain plantings across the southwestern parishes. The Louisiana Department of Agriculture and Forestry administers state rice promotion assessments alongside federal crop insurance coordination. Crowley-Lake Charles processing infrastructure handles cross-border Caribbean bulk shipments.
Mississippi
Delta region growers absorb displaced California medium-grain volume under forward-contract coverage with Riceland Foods. Mississippi State University Extension Service varietal trials target blast resistance for humid subtropical conditions. Bolivar-Washington county elevator networks consolidate for optical-sorting compliance with export specifications.
Texas
Jefferson and Chambers county rice acreage offers underutilized irrigation capacity for aromatic specialty cultivation. Texas A&M AgriLife Research coordinates drought-tolerant germplasm development with Gulf Coast water district allocations. Beaumont-Port Arthur processing infrastructure serves brewing and distilling end users seeking specific amylose-content varieties.
United States Rice Market Competitive Landscape
Top-tier vendors anchor cooperative and corporate milling infrastructure, while mid-tier processors compete on identity-preserved specialty contracts. The market structure concentrates around vertically integrated handlers with elevator networks and branded retail positioning. Three archetypes dominate: cooperative-owned processors with farmer-member governance, diversified agribusiness trading houses with bulk logistics, and branded consumer goods specialists with aromatic portfolio focus. Competitive moves center on milling automation retrofit investment and direct-to-foodservice contracting bypassing traditional distributor channels.
Within the cooperative archetype, Riceland Foods and Farmers' Rice Cooperative exemplify farmer-owned structures that sustain volume across Arkansas-Louisiana-Mississippi Delta corridors. Riviana Foods occupies a branded retail position in jasmine and basmati segments. Cargill anchors industrial supply chains with bulk handling infrastructure.
| Leading Market Players |
|---|
| Riceland Foods |
| American Rice |
| Farmers' Rice Cooperative |
| Riviana Foods |
| Diversified Ingredients |
| American Commodity Company |
| Cargill |
| USA Rice |
| Planet Rice |
| Others |
Value Network & Pricing Analysis
Chicago Board of Trade rough rice futures cascade through the U.S. rice supply chain, compressing margins at Arkansas-Louisiana-Mississippi Delta elevators while amplifying premium capture for identity-preserved California Calrose contracts. This commodity benchmark transmission shapes three distinct pricing tiers: forward-contracted industrial volume, spot-traded food service lots, and certified low-arsenic retail premiums.
Pricing Analysis
Lead-time contracting structures pricing tiers across the U.S. rice market, with food service distributors paying premiums for 30-day guaranteed delivery while processors capture discounts on 90-day forward commitments. Three-tier pricing stratifies across premium identity-preserved, standard commodity-grade, and economy spot-market levels, differentiated by USDA grade certification and origin documentation. Cost compression in California medium-grain runs through groundwater pumping cost spikes and surface water allocation cuts. Price-sensitive retail consumers in Southeast ethnic grocery channels drive volume, while least-sensitive buyers populate infant cereal manufacturers seeking low-arsenic certification.
Supply Chain Analysis
Water allocation rests on California State Water Resources Control Board surface permits, Arkansas Natural Resources Commission groundwater sustainability plans, and Louisiana Department of Agriculture surface irrigation infrastructure. Diesel fuel, urea nitrogen, and glyphosate herbicide constitute critical input dependencies feeding into Delta production economics. Single-source vulnerability concentrates in Sacramento Valley medium-grain germplasm, where water adjudication threatens varietal continuity. Distribution runs through Riceland Foods cooperative elevator networks, Cargill bulk handling terminals, and direct-to-processor rail contracts bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The U.S. rice market operates as a supply-constrained system where California water allocation cuts have permanently removed 25,000+ acres from production, propping medium-grain pricing premiums through geographic displacement to Arkansas-Louisiana-Mississippi Delta corridors.
For Market Incumbents: Anticipate EPA Clean Water Act buffer zone expansion in Arkansas and Louisiana production counties by accelerating cooperative consolidation to absorb compliance costs across larger acreage bases. Prioritize optical sorting automation investment at Stuttgart and Crowley milling clusters to defend export-grade purity specifications against Thai and Indian aromatic substitution. Vertical integration into food service direct contracting bypasses distributor margin capture. For New Entrants and Emerging Players: Launch via online retail subscription models targeting coastal urban consumers seeking traceable-origin brown rice and aromatic specialty varieties. The most penetrable white-space sits in Texas Gulf Coast Jefferson and Chambers county aromatic cultivation, where underutilized irrigation infrastructure awaits drought-tolerant germplasm deployment. Secondary opportunity resides in craft brewing and rice-spirit distilling channels demanding specific amylose-content sourcing. For Investors and Strategic Acquirers: Distressed-cycle entries favor water-constrained California cooperative assets with existing low-arsenic certification infrastructure and infant cereal supply chain relationships. Long-term viability across the analysis window hinges on groundwater sustainability agency adjudication outcomes in Sacramento Valley and Arkansas Natural Resources Commission pumping allocation rulings. The signal to watch is State Water Resources Control Board permanent crop conversion permit issuance rates.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Automation | Arkansas and Louisiana mills achieve export-grade purity specifications demanded by Caribbean bulk buyers. |
| Identity-Preserved Contracting | Delta cooperatives secure direct food service relationships with restaurant chains specifying provenance claims. |
| Low-Arsenic Certification | California and Arkansas growers qualify for infant cereal supply chains under evolving FDA guidance thresholds. |
| Precision Irrigation Deployment | Large Delta operations document conservation compliance for state nutrient reduction strategies and carbon credit verification. |
| Texas Aromatic Expansion | Jefferson and Chambers county irrigation infrastructure supports specialty germplasm development for brewing applications. |
Research Methodology
USDA National Agricultural Statistics Service crop reports, EPA Clean Water Act enforcement databases, and Arkansas Natural Resources Commission groundwater sustainability filings formed the secondary backbone, cross-referenced with primary interviews involving rice milling operations managers, food service procurement directors at regional distributors, cooperative elevator operators, and infant cereal manufacturer supply chain leads. Bottom-up acreage and yield data triangulated against top-down consumption estimates from food processing ingredient demand surveys.
Bottom-up modeling anchored volume projections in county-level planted acreage, state water allocation rulings, and varietal adoption curves, while top-down validation referenced national food processing demand for rice flour and syrup. Segmentation dimensions included product type (white, brown, aromatic), end user (food processing, household, food service, export), and distribution channel (supermarket, wholesale, online retail, specialty store). CAGRs derived from trend extrapolation of acreage displacement patterns and clean-label formulation adoption rates in gluten-free baked goods.
California groundwater adjudication, EPA paddy runoff enforcement intensity, and Thai-Indian aromatic import price volatility are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around water rights permanence and FDA arsenic threshold timing. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Grain Mill Products Market
Grains
Oat Bran Market
Grains
Basmati Rice Market
Grains
Ancient Grain Market
Grains
Global Oats Market
Grains
Green Pea Grits Market
Grains
Ancient and Specialty Grain Flour Market
Grains
Gluten Feed Market
Grains
Sorghum Flour Market
Grains
Spelt Wheat Market
Grains
North America Maize Market
Grains
Low Fat Rice Market
Grains
Grain Silos Market
Grains
Asia Pacific Wheat Protein Market
Grains
South America Wheat Market
Grains
Organic Oats Market