
 Sorghum Market | 2026-2036
Sorghum Market Size, Share, and Industry Trends Forecast 2026-2036
Sorghum Market Outlook
Market Context
Capital-intensity divergence between integrated seed-chemical giants and regional breeders is collapsing as genomic selection tools democratize trait development. KWS leverages its European breeding infrastructure to distribute heat-tolerant hybrids across Sub-Saharan Africa. Corteva Agriscience sustains North American market presence through stacked-trait sorghum platforms and adjacent crop protection bundling. Bayer CropScience anchors its position in South American markets with glufosinate-tolerant varieties tied to herbicide systems.
Technical Definition and Structural Segments
Sorghum is a C4 cereal grass cultivated for its starchy grain, typically containing 9-12% protein and 3-4% fat by dry weight, with a waxy endosperm variant prized for industrial starch extraction. The grain serves as a dual-purpose input: milled for gluten-free food applications and crushed for high-moisture livestock rations where its tannin content reduces rumen acidosis risk. Sorghum grain commands the largest value pool across product types, though sorghum flour is expanding fastest in North American and European gluten-free retail channels where specialty stores capture premium pricing. Animal feed remains the dominant end-use segment by volume, while biofuel applications in India and Brazil attract policy-linked offtake through ethanol blending mandates.
Regulatory Frame and Outlook
The USDA's Risk Management Agency shapes North American planting decisions through crop insurance actuarial tables that favor sorghum in drought-prone counties, while India's FSSAI and CEA jointly regulate sorghum ethanol pathways under the PLI scheme for biofuel feedstocks. China's SAMR enforces GB standards for grain reserve quality that determine which hybrids qualify for state procurement, directly influencing breeder R&D priorities. Stakeholders must monitor how carbon accounting rules under the EU Green Deal and emerging U.S. IRA biofuel tax credits reallocate margin between food-grade and industrial sorghum streams.
Market Dynamics
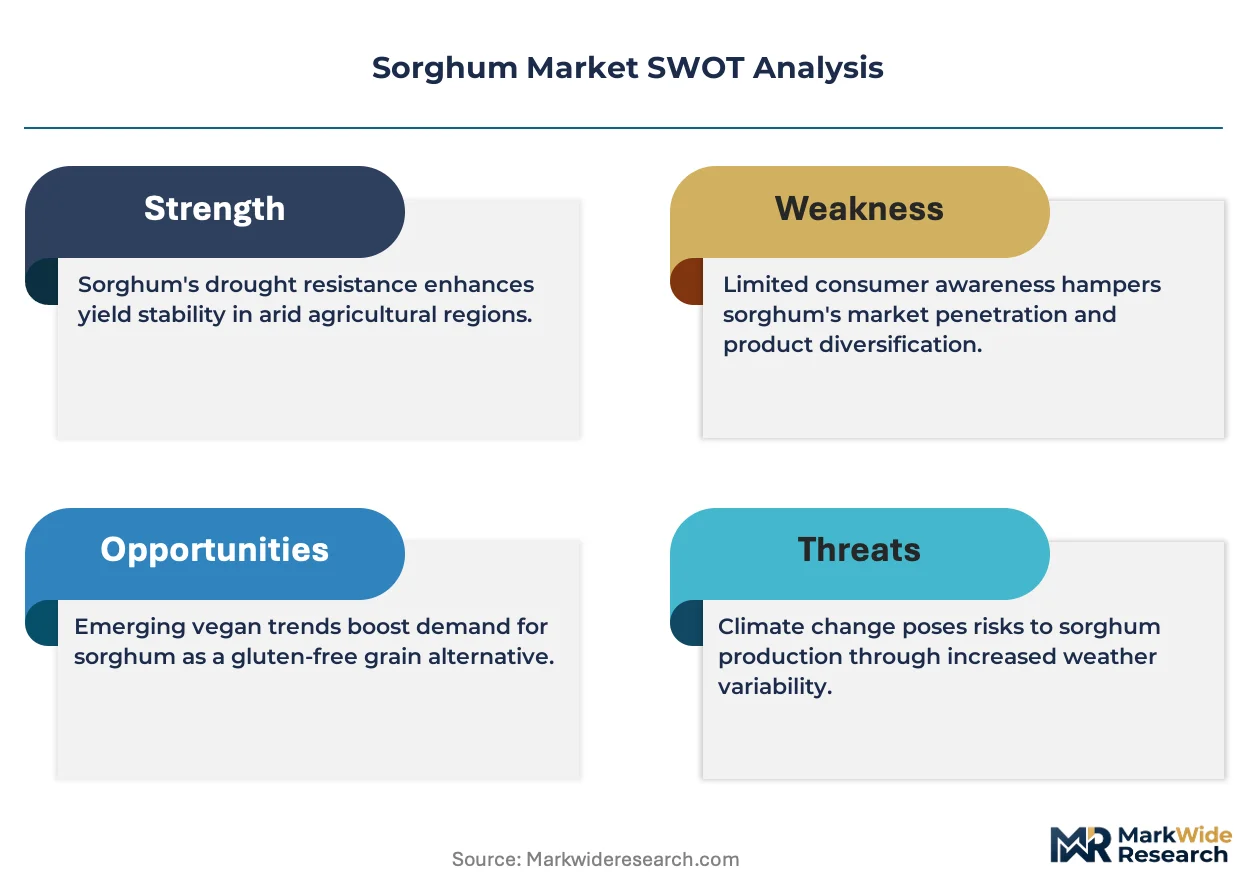
Climate volatility is compressing planting windows across major producing belts, forcing rapid substitution between feed grains as water stress intensifies. The USDA's insurance recalibration and China's state reserve procurement together restructure where breeders deploy drought-tolerant genetics.
Growth Catalysts
- India's Ethanol Blending Mandate:The PLI scheme for biofuel feedstocks creates guaranteed offtake for sorghum ethanol pathways, redirecting acreage from food-grade to industrial varieties. State-run oil marketing companies now contract directly with farmers.
- Brazilian Livestock Ration Reformulation:Beef and poultry integrators in Mato Grosso and Goiás are expanding sorghum inclusion rates as corn logistics tighten. Feed mills prize sorghum's lower mycotoxin risk during humid storage.
- Genomic Selection Platforms:Marker-assisted breeding cycles have collapsed from eight years to four, accelerating heat-tolerant hybrid deployment. Regional breeders now access trait libraries previously locked behind multinational IP walls.
Market Restraints
- Input Cost Volatility:Nitrogen fertilizer prices swing with natural gas benchmarks, squeezing margins on rain-fed sorghum where yield response to nutrient application lags irrigated corn.
- Substitute Grain Competition:Corn's established handling infrastructure and deeper futures liquidity pull procurement contracts away from sorghum in years when water stress moderates.
- Quality Standard Fragmentation:China's GB standards for state reserve acceptance diverge from FDA food-grade specifications, forcing exporters to maintain parallel inventory grades.
Strategic Opportunities
- EU Green Deal Carbon Accounting:The Carbon Border Adjustment Mechanism creates premium pathways for low-carbon sorghum ethanol entering European fuel markets. Brazilian mills are certifying supply chains to capture this spread.
- Gluten-Free Retail Channel Expansion:Specialty grocers in Germany and the United Kingdom are building direct-producer relationships for identity-preserved sorghum flour, bypassing commodity handlers.
- CRISPR Trait Editing Convergence:Gene-edited waxy endosperm varieties with modified amylopectin ratios unlock industrial starch applications previously served by maize or tapioca.
Industry Challenges
- Seed Certification Timeline Compression:National variety release protocols in India and Nigeria lag breeding advances by three to five years, delaying farmer access to improved genetics.
- Integrated Pest Management Skill Gaps:Fall armyworm resistance management requires scouting expertise and rotation discipline that extension services struggle to deliver at scale.
- Post-Harvest Loss Infrastructure:Aflatoxin control during smallholder drying and storage demands capital investment in hermetic bags and solar dryers that microfinance rarely covers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorghum Market |
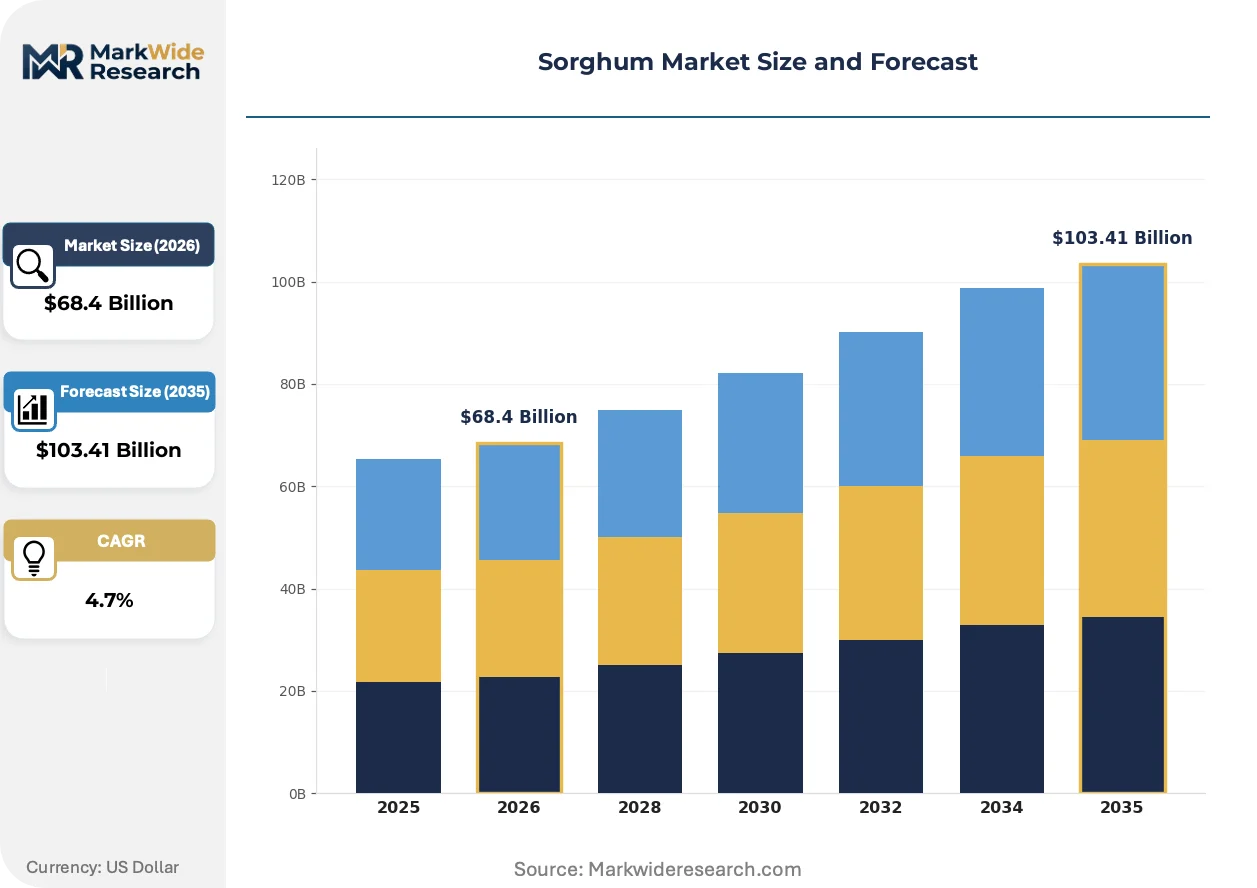
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorghum Grain, Sorghum Flour, Sorghum Syrup, Sorghum-based Snacks End Use: Animal Feed, Food & Beverage, Biofuel, Starch Production Form: Whole Grain, Ground, Flaked, Pelleted Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | KWS, S&W Seed Co, Corteva Agriscience, Proline, Dyna-GroSeed, Bayer CropScience, Nufarm, Seed Co Limited, Advanta Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorghum Market Strategic Shifts
Digital agriculture tools and novel processing technologies are dissolving traditional boundaries between commodity grain and specialty ingredient markets. Breeders, processors, and end-users now share data streams that reshape variety selection and contracting terms.
CRISPR-based gene editing is fragmenting the trait licensing landscape. Public research institutions in Australia and India now release edited sorghum lines with open-source germplasm terms. Seed companies in East Africa are adopting these lines faster than stacked-trait platforms, compressing the premium that multinational patent estates once commanded.
The EU Green Deal's Farm-to-Fork Strategy tightens pesticide residue thresholds for imported feed grains. The regulation forces Brazilian and Argentine exporters to document integrated pest management compliance across contracted acreage. European compound feed manufacturers are now specifying sorghum from certified low-chemical management zones.
Identity-preserved contracting is displacing spot-market procurement for food-grade sorghum. North American gluten-free manufacturers now sign multi-year agreements with specific farm clusters, specifying variety, protein content, and mycotoxin limits. This channel captures price premiums that commodity handlers cannot access.
Sorghum Market Segmentation
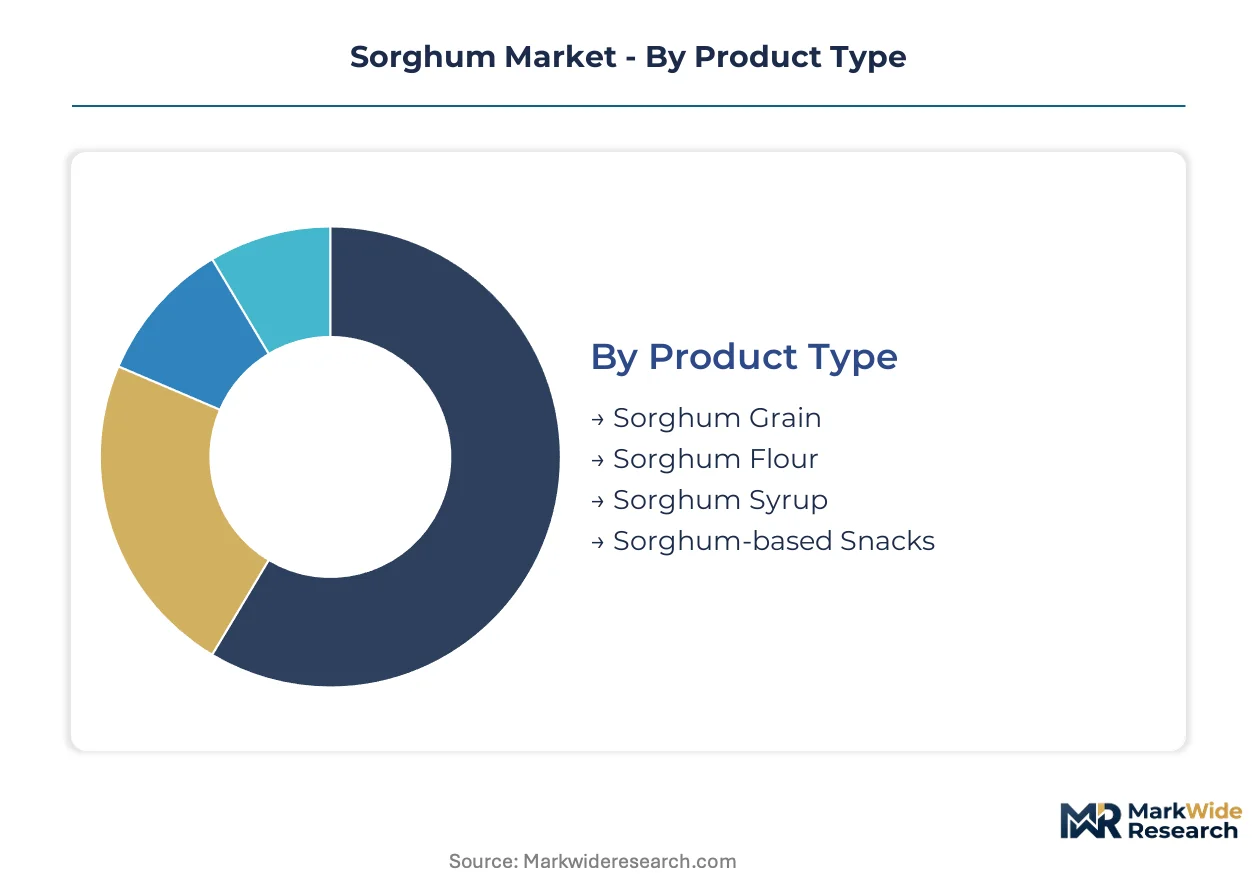
Sorghum's dual identity as commodity feedstock and specialty ingredient creates divergent value pools across product categories. Segmentation reveals how procurement channels, processing intensity, and end-use specifications fragment pricing power and margin capture across the value chain.
Product Type:
Domestic consumption patterns dominate grain and flour segments, while syrup and snack derivatives target export-led premium channels in North American and European retail.
- Sorghum Grain:The standard commercial form contains 9-12% protein and 3-4% fat by dry weight, with tannin variants reducing rumen acidosis in livestock rations. Demand concentrates in China's northern plains where state grain reserves prioritize procurement for baijiu distillation and feed security, reinforced by SAMR's GB quality standards.
- Sorghum Flour:Milled from waxy endosperm varieties, this gluten-free alternative commands specialty pricing in German and British retail channels. North American gluten-free manufacturers now sign multi-year identity-preserved contracts with specific farm clusters, bypassing commodity handlers entirely.
- Sorghum Syrup:Extracted from sweet sorghum cultivars, this natural sweetener serves craft beverage and bakery niches seeking non-GMO label claims.
- Sorghum-based Snacks:Puffed and extruded formats target health-conscious consumers in urban Indian and Brazilian markets.
Sorghum grain holds the largest share; momentum sits with sorghum flour.
End Use:
Volume concentration favors feed and fuel applications, while margin capture concentrates in food-grade and industrial starch segments requiring certification compliance.
- Animal Feed:High-moisture rations incorporating sorghum reduce mycotoxin exposure versus corn during humid Brazilian storage. Beef and poultry integrators in Mato Grosso and Goiás are expanding inclusion rates as corn logistics tighten, with feed mills valuing the lower acidosis risk profile.
- Food & Beverage:Baijiu distillers in China's Shanxi and Sichuan provinces contract directly for tannin-rich grain lots meeting specific aroma profiles. The segment captures premium through state reserve procurement quotas and heritage brand specifications.
- Biofuel:India's PLI scheme for ethanol feedstocks redirects acreage toward industrial varieties, with state-run oil marketing companies contracting directly with farmers.
- Starch Production:Waxy endosperm variants with modified amylopectin ratios unlock industrial applications previously served by maize or tapioca.
Animal feed commands the greatest volume; food and beverage captures the steepest expansion trajectory.
Form:
Processing depth determines logistics economics, with whole grain minimizing handling costs and pelleted formats commanding infrastructure premiums.
- Whole Grain:Unprocessed kernels dominate bulk export and state reserve procurement, minimizing per-unit handling costs across long-haul rail and maritime routes.
- Ground:Hammer-milled meal serves immediate feed incorporation, with particle size specifications varying by livestock category and regional mill equipment.
- Flaked:Steam-rolled grains improve digestibility in dairy rations, requiring capital-intensive processing that limits supplier concentration.
- Pelleted:Compacted feed formulations reduce dust and improve storage stability, commanding premium pricing in humid subtropical climates.
Whole grain generates the highest throughput; pelleted formats are climbing fastest on livestock integration trends.
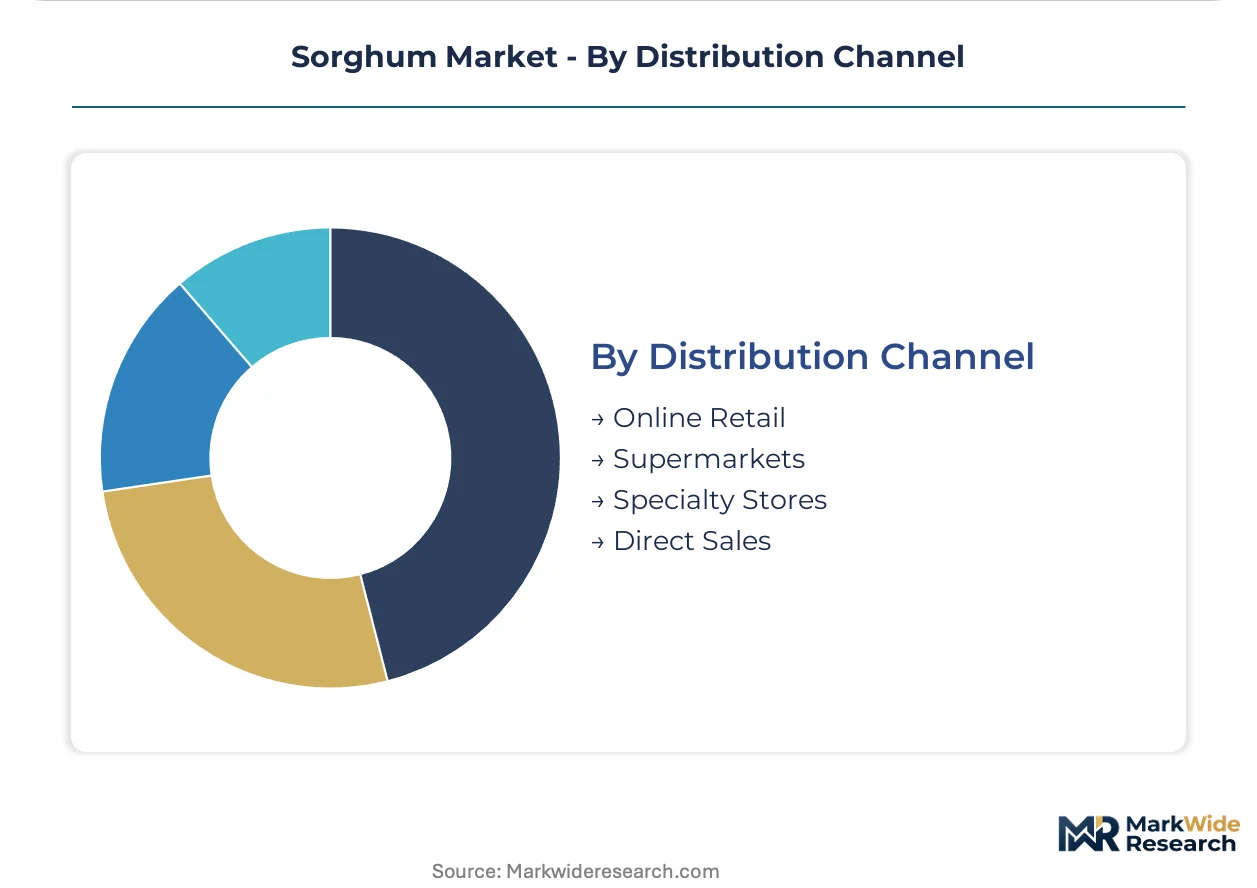
Distribution Channel:
Channel selection splits sharply between commodity bulk handlers and identity-preserved specialty routes, with digital platforms emerging as contract facilitation tools rather than spot markets.
- Online Retail:E-commerce platforms serve gluten-free flour and syrup niches, enabling direct-producer relationships that bypass traditional grain merchants.
- Supermarkets:Mass retail channels move packaged flour and snack formats, with shelf placement contingent on certification compliance and promotional slotting fees.
- Specialty Stores:Health food and ethnic grocery channels capture the highest margins for identity-preserved and heritage varieties.
- Direct Sales:Feed mills and ethanol processors contract directly with farmer cooperatives, eliminating intermediary margins on volume offtake.
Direct sales anchor volume flows; specialty stores deliver the strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major producing geographies. China channels sorghum primarily toward state-controlled distillation and strategic grain reserves, while Brazil and India prioritize livestock feed integration and biofuel mandates respectively.
United States
USDA Risk Management Agency crop insurance actuarial tables favor sorghum plantings across drought-prone counties in Texas and Kansas. The Great Plains region concentrates seed breeding infrastructure, with private and public research stations advancing heat-tolerant hybrid lines for rain-fed production systems.
Brazil
Beef and poultry integrators in Mato Grosso and Goiás are expanding sorghum inclusion rates as corn logistics tighten during peak harvest periods. ANVISA mycotoxin regulations for feed grains reinforce sorghum's lower contamination risk profile relative to humid-stored corn alternatives.
China
SAMR enforces GB quality standards that determine which hybrids qualify for state grain reserve procurement in Shanxi and Sichuan provinces. Baijiu distillers contract directly for tannin-rich grain lots meeting specific aroma profiles tied to heritage brand specifications.
India
FSSAI and CEA jointly regulate sorghum ethanol pathways under the PLI scheme for biofuel feedstocks, redirecting acreage from food-grade to industrial varieties. State-run oil marketing companies now contract directly with farmers in Maharashtra and Karnataka for guaranteed offtake.
Nigeria
National variety release protocols lag breeding advances by three to five years, delaying farmer access to improved genetics in the northern savanna belt. Kano and Kaduna states concentrate smallholder production, where fall armyworm resistance management demands extension investment that public services struggle to deliver.
Sorghum Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence collapsing as genomic selection tools democratize trait development. The upper tier comprises multinational seed-chemical platforms bundling stacked-trait sorghum with adjacent crop protection portfolios. Mid-scale regional breeders occupy the specialist tier, leveraging open-source germplasm and faster regulatory pathways in emerging markets. Competitive moves concentrate on trait licensing convergence and geographic expansion through distribution partnerships rather than direct M&A.
Within the integrated platform tier, Corteva Agriscience and Bayer CropScience exemplify the multinational archetype, each anchoring positions through herbicide-tolerant variety systems tied to proprietary chemical portfolios. Advanta Seeds represents the regional specialist model, with breeding infrastructure calibrated to heat-stressed production environments across Sub-Saharan Africa and South Asia.
| Leading Market Players |
|---|
| KWS |
| S&W Seed Co |
| Corteva Agriscience |
| Proline |
| Dyna-GroSeed |
| Bayer CropScience |
| Nufarm |
| Seed Co Limited |
| Advanta Seeds |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles at Brazilian feed mills compress procurement windows and amplify price volatility when corn logistics tighten, concentrating margin capture among handlers with integrated storage assets. This lead-time compression rewards breeders with certified seed stocks positioned near Mato Grosso integration clusters, while penalizing spot-market dependence.
Pricing Analysis
Long-term offtake contracts dominate procurement flows, with state-run oil marketing companies in India and baijiu distillers in China's Shanxi province locking volume through multi-year agreements. Three-tier pricing structure across premium, standard, and economy levels separates identity-preserved waxy endosperm varieties from commodity grain and feed-grade lots. Cost compression in standard-grade channels is intensifying because nitrogen fertilizer price swings squeeze rain-fed producer margins. Compound feed manufacturers exhibit highest price sensitivity, while specialty flour buyers accept premiums for gluten-free certification.
Supply Chain Analysis
Port congestion at Santos and Paranaguá constrains Brazilian export velocity and forces feed mills toward domestic sorghum substitution during peak corn harvest periods. Supply concentrates in the United States, Brazil, and Nigeria, with germplasm development anchored in Texas and Kansas research stations. Seed production draws from proprietary hybrid lines, open-source CRISPR-edited germplasm, and state-certified foundation stocks. Single-source vulnerability in heat-tolerant trait licensing threatens regional breeder access. Distribution runs through farmer cooperative networks and direct processor contracting, bypassing commodity merchants in specialty segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sorghum breeding platforms benefit from regulatory entrenchment through national variety release protocols and state procurement qualification standards, creating switching costs that lock in hybrid adoption cycles.
For Market Incumbents: Fortify germplasm libraries through exclusive licensing of CRISPR-edited waxy endosperm traits before open-source alternatives erode patent premiums. Expand captive seed production in Maharashtra and Karnataka to secure supply for India's ethanol blending mandate. Corteva and Bayer anchor positions through herbicide-tolerant variety systems; regional specialists must match their certification breadth to defend distributor relationships. For New Entrants and Emerging Players: FSSAI fast-track approval for industrial ethanol varieties offers entry into India's PLI scheme before incumbent seed-chemical giants redirect R&D budgets. Target identity-preserved sorghum flour contracts with German and British specialty grocers, where direct-producer relationships bypass established commodity handlers. Lead with carbon-accounting certification to capture EU Green Deal premium pathways. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational agrochemical parents seeking to divest non-core seed portfolios amid crop protection consolidation. Five-to-ten-year viability hinges on genomic selection platform ownership rather than germplasm scale alone. Watch for inflection when China's SAMR revises GB quality standards to favor gene-edited varieties over stacked-trait hybrids.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Trait Licensing Convergence | Public research institutions in Australia and India release edited lines with open-source terms, fragmenting multinational patent premiums. |
| Identity-Preserved Contracting Expansion | North American gluten-free manufacturers sign multi-year agreements specifying variety and mycotoxin limits, bypassing commodity handlers. |
| Carbon Certification Program Buildout | Brazilian mills certify supply chains to capture EU Green Deal premium pathways for low-carbon ethanol entering European fuel markets. |
| Backward Integration into Seed Production | State-run oil marketing companies in India contract directly with farmers, eliminating intermediary margins on guaranteed ethanol offtake. |
| Regional Distribution Partnership Formation | KWS leverages European breeding infrastructure to distribute heat-tolerant hybrids across Sub-Saharan Africa extension networks. |
Study Parameters
Cross-validation between USDA crop insurance actuarial data and FSSAI ethanol pathway filings anchors the qualitative findings on acreage redirection trends. Primary interviews with seed breeding directors, feed mill procurement managers, and baijiu distillery supply chain leads combine with secondary validation through customs records, state grain reserve procurement disclosures, and PLI scheme implementation reports. Bottom-up triangulation across farmer cooperative contract volumes and top-down reconciliation with national production statistics ensure coverage consistency.
Sensitivity analysis around nitrogen fertilizer price volatility and monsoon timing variations tests projection robustness across the analysis window. The analytical framework models segmentation across product type, end-use application, form specification, and distribution channel, with regional regulatory clusters as an overlay dimension. CAGRs derive from trend extrapolation moderated by policy implementation lag assumptions, incorporating ethanol blending mandate targets and state reserve procurement quotas as demand-side anchors.
Decision-makers should treat outputs as directional under stable climate volatility and policy continuity assumptions; material deviation in monsoon patterns or SAMR standard revisions would warrant model refresh. Practitioners should keep alternative scenarios live as EU Carbon Border Adjustment Mechanism implementation timelines and U.S. IRA biofuel credit structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
South America Wheat Market
Grains
Oat Bran Market
Grains
Organic Oats Market
Grains
Sorghum Flour Market
Grains
Wild Rice Market
Grains
Europe Wheat Market
Grains
Argentina Grains Market
Grains
Lentil Market
Grains
White Beans Market
Grains
Grain Bins Market
Grains
Rice Flour Market
Grains
Global Rice Market
Grains
Cornmeal Market
Grains
Ancient Grain Market
Grains
Chickpeas Market
Grains
Organic Cereals Market