
 Spelt Wheat Market | 2026-2036
Spelt Wheat Market Size, Share, and Industry Trends Forecast 2026-2036
Spelt Wheat Market Analysis
Artisan bakers and clean-label food manufacturers is bifurcating demand away from conventional wheat buyers. Cargill leverages its grain procurement networks to secure premium spelt volumes across North American growing regions. Bob's Red Mill Natural Foods anchors the retail channel with heritage-grain branding and direct-to-consumer distribution. Arnreiter Mühle GmbH dominates Central European milling with specialized dehulling capacity for spelt's tough outer hull.
Spelt wheat is a hexaploid cereal grain (Triticum spelta) containing moderate gluten levels, distinctive nutty flavor, and a tough outer husk requiring specialized dehulling equipment before milling. Its primary commercial purpose centers on premium food applications where consumers seek alternatives to common wheat with perceived digestive tolerance advantages. Whole Spelt and Spelt Flour command the largest volume positions, though Spelt Bran is gaining fastest as fiber-enrichment trends penetrate breakfast cereals and functional snacks. Health Food Stores and Specialty Shops capture the highest margin pools due to educated consumer willingness to pay heritage-grain premiums, while Supermarkets compete on volume with private-label introductions.
EU organic regulations and the EU Green Deal's Farm to Fork strategy shape cultivation practices and labeling claims across European production zones. The USDA's National Organic Program and FDA food labeling requirements govern market access for imported spelt products entering the United States. Stakeholders must monitor evolving gluten-content thresholds and heritage-grain authentication standards as regulatory precision tightens and consumer litigation risk rises.
Market Dynamics
The artisan food movement is fragmenting demand channels as heritage-grain preferences pull procurement away from commodity wheat suppliers toward specialized dehulling and organic-certified milling infrastructure.
Growth Catalysts
- EU Green Deal Farm to Fork:The strategy tightens organic input standards across German and French cultivation zones, accelerating certified spelt acreage conversion.
- Clean-label bakery demand:Artisan bakers in urban clusters seek hexaploid grains with moderate gluten positioning for digestive-tolerance marketing claims.
- Specialized dehulling technology:Mechanical hull-removal advances reduce processing losses for spelt's tough outer husk, improving miller unit economics.
Market Restraints
- Input cost volatility:Organic fertilizer and non-GMO seed premiums fluctuate with energy markets, compressing farm-gate margins.
- German milling concentration:Central European dehulling capacity clusters around established facilities, creating regional supply bottlenecks.
- Common wheat substitution:Price-sensitive industrial bakers default to commodity Triticum aestivum when heritage premiums exceed threshold levels.
Strategic Opportunities
- North American organic acreage:USDA National Organic Program certification expansion allows midwestern US farmers to capture EU import demand.
- Spelt bran functional foods:Fiber-enrichment formulations penetrate breakfast cereal and snack categories beyond traditional flour applications.
- Direct-to-consumer channels:Heritage-grain subscription models bypass conventional supermarket distribution, capturing full premium margins.
Industry Challenges
- Organic certification timelines:Three-year land conversion requirements delay new farmer entry and strain working capital.
- Gluten-content litigation exposure:Evolving FDA labeling thresholds for gluten-free claims create compliance uncertainty and consumer lawsuit risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spelt Wheat Market |
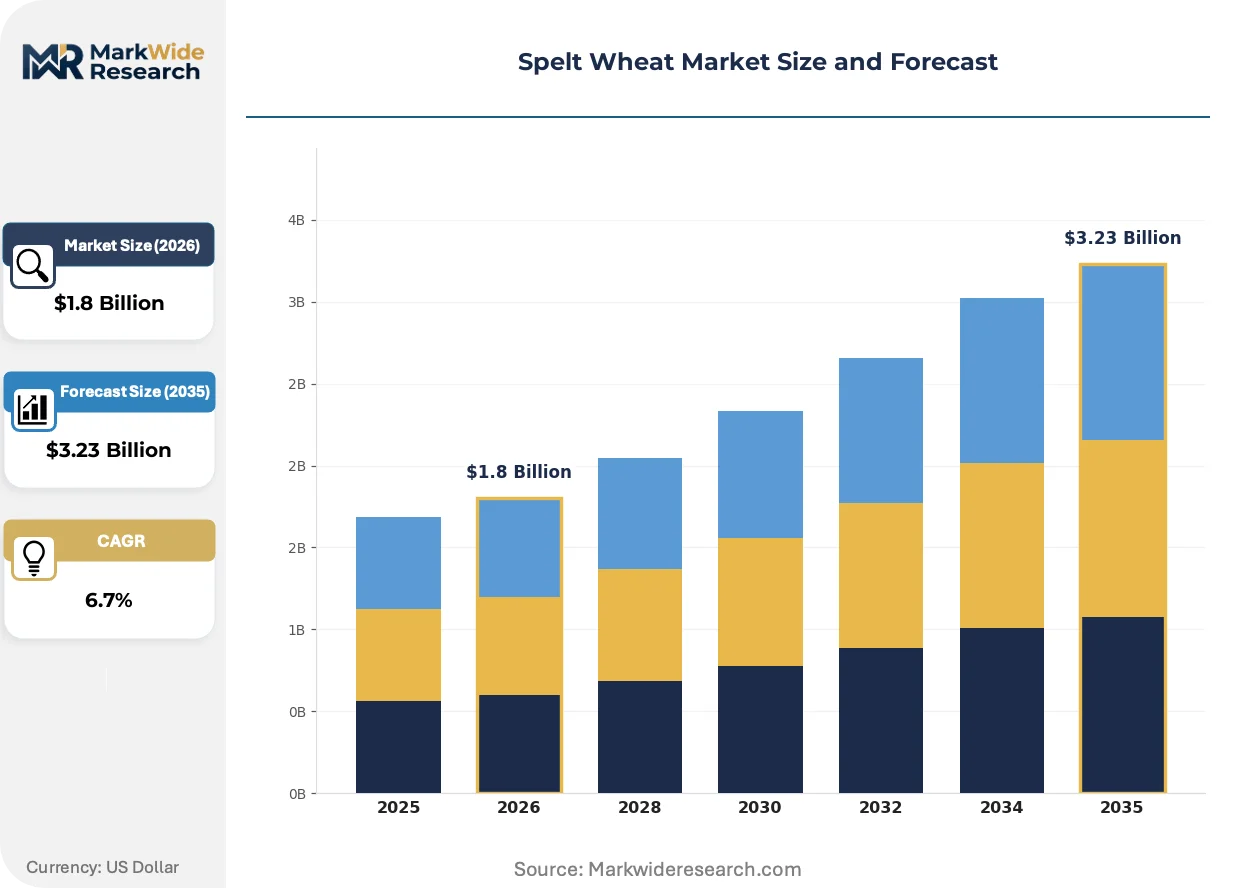
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Spelt, Spelt Flour, Spelt Bran, Spelt Berries End Use: Baking, Pasta, Snack Foods, Cereals Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Packaging Type: Bags, Boxes, Bulk, Eco-friendly Containers |
| Companies Covered | Ardent Mills, Archer Daniels Midland Company, General Mills, Bob’s Red Mill Natural Foods, Cargill, Doves Farm, Sharpham Park, Arnreiter Mühle GmbH, Montana Flour & Grains, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spelt Wheat Market Emerging Trajectories
Equipment miniaturization and regulatory precision are compressing processing economics while procurement channels fragment across direct and legacy retail pathways.
Optical sorting technology for hull and kernel separation is miniaturizing. Small-scale millers in France and southern Germany adopt compact dehulling units that previously required industrial-scale capital. This compression enables farm-level processing, shortening supply chains and capturing organic premiums that centralized facilities previously extracted.
REACH chemical compliance and EU organic regulation revisions tighten mycotoxin thresholds and heritage-grain authentication requirements. German laboratories now mandate DNA verification for spelt varietal claims on packaged flour. Italian pasta producers face reformulation costs to meet evolving gluten-content declarations under EFSA guidance.
Buyer concentration among specialty retailers is fragmenting as direct-to-consumer subscriptions capture educated consumers. Bob's Red Mill's heritage-grain branding established the template; regional millers in Bavaria and Baden-Württemberg now replicate this via localized e-commerce. France shows the fastest channel shift, with Paris-area bakeries sourcing directly from Loire Valley growers.
Spelt Wheat Market Segmentation
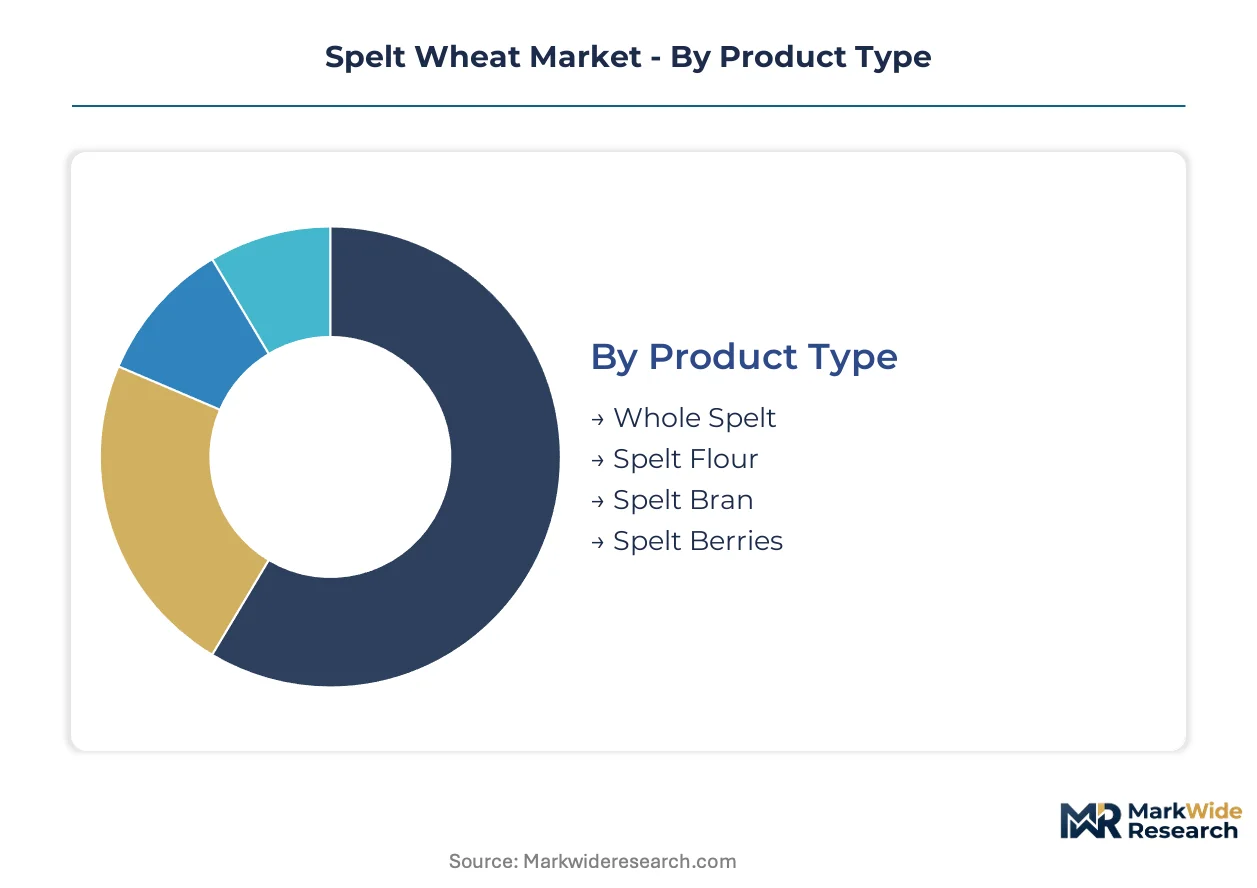
Spelt wheat's specialized dehulling requirements and heritage-grain positioning create sharp segmentation boundaries between commodity-substitutable formats and premium-protected categories. Product form, end-use application, and channel access determine margin capture and vulnerability to common wheat displacement.
Product Type:
Substitution pressure from conventional wheat concentrates in milled flour segments, while hull-intact formats retain protective barriers through processing complexity and authenticity signaling.
- Whole Spelt:Intact kernels with the tough outer hull retained, requiring specialized dehulling equipment before culinary use. German artisan bakeries in Bavaria and Baden-Württemberg drive demand for hull-on authenticity verification and controlled germination protocols.
- Spelt Flour:Fine-milled endosperm with moderate gluten content (10-12% protein), the most exposed to commodity wheat substitution when heritage premiums exceed threshold levels. French organic pasta producers in the Loire Valley specify stone-ground flour for texture differentiation.
- Spelt Bran:Fiber-rich outer layer separated during milling, penetrating breakfast cereal and functional snack formulations as enrichment ingredient.
- Spelt Berries:Dehulled whole kernels ready for cooking, favored by meal-kit services and heritage-grain subscription channels seeking visual authenticity cues.
Whole Spelt anchors the volume base while Spelt Bran gains share at the steepest rate.
End Use:
Application maturity separates established European consumption patterns from emerging functional food opportunities where fiber claims command formulation premiums.
- Baking:Traditional loaves, artisan pastries, and heritage-grain sourdoughs dominate German and Austrian consumption, with stone-milled flour specifications protecting against commodity substitution.
- Pasta:Bronze-extruded shapes from Italian producers in Emilia-Romagna and Marche leverage spelt's nutty flavor profile for premium positioning against durum wheat standards.
- Snack Foods:Puffed kernels, crackers, and extruded crisps in French and Swiss retail channels exploit clean-label positioning and ancient-grain storytelling.
- Cereals:Hot breakfast porridges and granola clusters incorporate spelt flakes for texture differentiation, with German health food retailers driving organic certification requirements.
Baking commands the largest volume commitment while Cereals expand most quickly through functional fiber positioning.
Distribution Channel:
Channel selection determines margin capture, with direct pathways preserving heritage premiums that supermarket private labels compress.
- Online Retail:Subscription models and direct-to-consumer platforms enable full premium capture, with Paris-area bakeries sourcing directly from Loire Valley growers.
- Supermarkets:Volume-driven private-label introductions in German chains like REWE and Edeka compete on price, accelerating commodity wheat substitution risk.
- Health Food Stores:Educated consumer willingness to pay organic premiums sustains highest margin pools, with staff expertise validating heritage-grain authentication claims.
- Specialty Shops:Urban artisan bakeries and Italian delicatessens in Munich, Vienna, and Zurich curate provenance-specific sourcing for culinary credibility.
Health Food Stores retain the strongest margin structure while Online Retail climbs the fastest through subscription model proliferation.
Packaging Type:
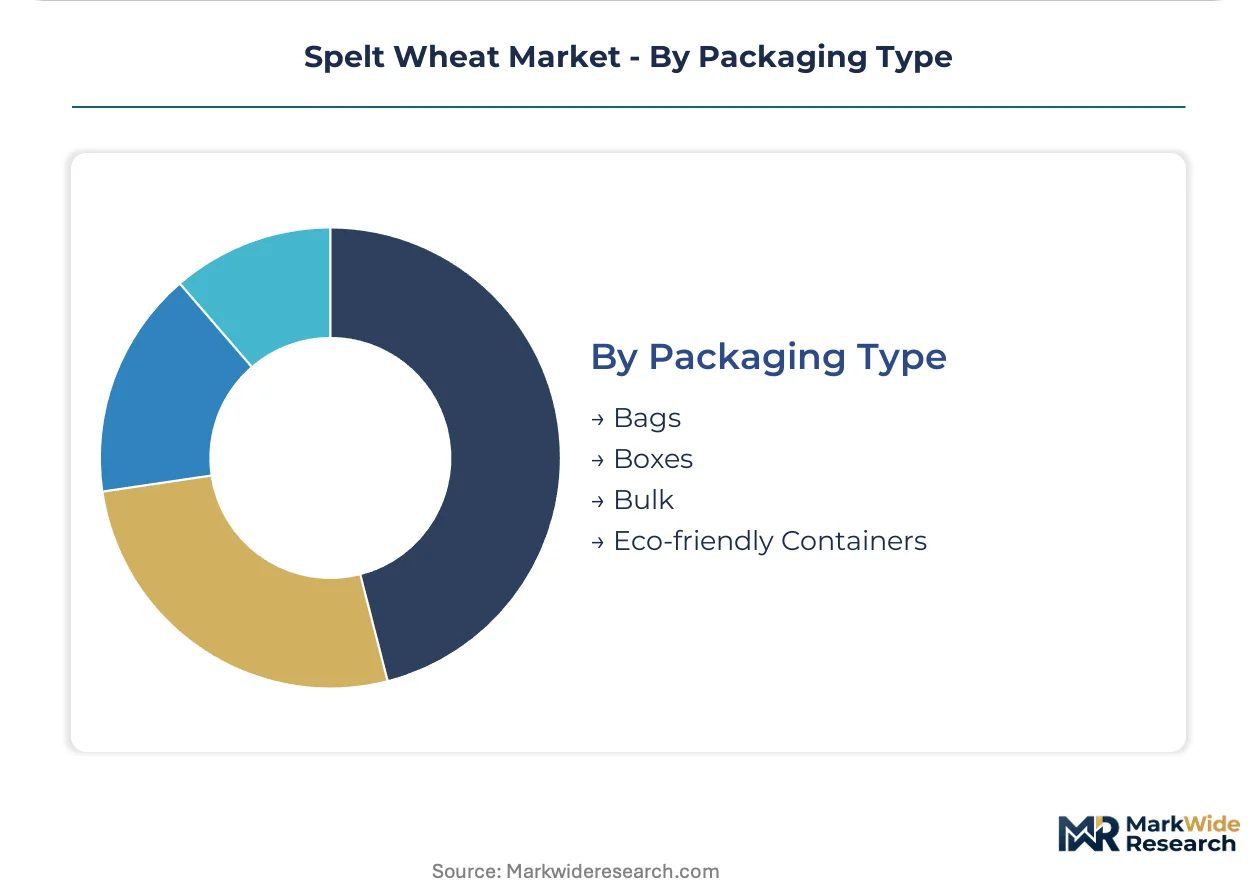
Packaging cost tiers align with channel positioning, from bulk commodity supply to premium single-origin storytelling formats.
- Bags:Standard paper and multilayer plastic formats for retail flour and berry distribution, balancing moisture protection with shelf visibility.
- Boxes:Rigid cartons for premium pasta shapes and cereal assortments, enabling graphic storytelling and gift-market positioning.
- Bulk:Food-service totes and institutional sacks for artisan bakery procurement and milling operations, minimizing per-unit packaging cost.
- Eco-friendly Containers:Compostable films and reusable deposit systems in German organic retail channels respond to EU Green Deal packaging waste directives.
Bulk formats anchor industrial volume while Eco-friendly Containers gain fastest through regulatory pressure and consumer preference alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German spelt exporters supply heritage-grain flour to French artisan bakeries and Italian pasta producers, establishing the Rhine corridor as the dominant trade-flow axis for premium hexaploid wheat.
Germany
Artisan bakeries in Bavaria and Baden-Württemberg drive organic spelt flour consumption for traditional sourdough production. The EU Green Deal's Farm to Fork strategy tightens organic input standards, accelerating certified acreage conversion in Lower Saxony. Arnreiter Mühle GmbH operates specialized dehulling facilities in Bavaria, processing hull-on grain for domestic milling and export.
France
Paris-area bakeries source directly from Loire Valley growers, bypassing conventional distribution channels for heritage-grain authenticity. EFSA guidance on gluten-content declarations shapes pasta producer reformulation requirements in Emilia-Romagna supply relationships. Organic certification under EU regulation 2018/848 governs cross-border flour shipments to Swiss retail channels.
Italy
Bronze-extruded pasta producers in Emilia-Romagna and Marche leverage spelt's nutty flavor profile for premium positioning against durum wheat standards. REACH chemical compliance mandates tighten mycotoxin thresholds for imported grain entering Mediterranean processing zones. Stone-ground flour specifications protect regional pasta makers from commodity wheat substitution in export markets.
United States
USDA National Organic Program certification expansion allows midwestern farmers to capture EU import demand for heritage grains. FDA food labeling requirements govern gluten-content thresholds for domestic flour sales and export eligibility. Montana Flour & Grains anchors organic acreage development in the northern Plains, supplying dehulled berries to specialty food manufacturers.
Switzerland
Swiss health food retailers drive organic premium capture through educated consumer willingness to pay heritage-grain authentication. Swissmedic oversight of food safety standards aligns with EU organic regulation for cross-border flour trade. Zurich-based specialty shops curate provenance-specific sourcing from Bavarian and Baden-Württemberg growers for culinary credibility.
Spelt Wheat Market Vendor Landscape
Listed leaders compete with private specialists across heritage-grain procurement and dehulling capacity deployment. The vendor base concentrates around established milling infrastructure in Central Europe and emerging organic acreage in North America. Three archetypes dominate: diversified grain traders with procurement networks, specialized heritage-grain millers with dehulling technology, and direct-to-consumer brands with subscription distribution. Competitive moves center on backward integration into organic acreage and strategic partnerships with artisan bakery clusters.
Among diversified grain traders, Cargill and Archer Daniels Midland Company represent the procurement-network archetype, securing premium spelt volumes across North American growing regions. Bob's Red Mill Natural Foods exemplifies the direct-to-consumer model with heritage-grain branding. Arnreiter Mühle GmbH anchors the specialized-miller tier with dehulling-focused operations in Central Europe.
| Leading Market Players |
|---|
| Ardent Mills |
| Archer Daniels Midland Company |
| General Mills |
| Bob's Red Mill Natural Foods |
| Cargill |
| Doves Farm |
| Sharpham Park |
| Arnreiter Mühle GmbH |
| Montana Flour & Grains |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Bavarian millers and Baden-Württemberg growers lock in both dehulled berry supply and price visibility across organic conversion cycles, insulating procurement from spot-market volatility in heritage-grain premiums.
Pricing Analysis
Mechanical dehulling technology-generation pricing gaps separate compact farm-scale units from industrial-scale centralized facilities, with miniaturized equipment commanding capital premiums that compress per-ton processing economics. Three-tier pricing structure across organic-certified, conventional, and transitional-grade spelt reflects EU regulation 2018/848 compliance timelines and gluten-content verification costs. Pricing pressure stems from common wheat substitution in supermarket private-label flour, where price-sensitive industrial bakers default to commodity Triticum aestivum when heritage premiums exceed threshold tolerance.
Supply Chain Analysis
Germany and France anchor European spelt production, with Bavarian and Baden-Württemberg growers supplying dehulled berries to Paris-area bakeries and Italian pasta producers across the Rhine corridor. The supply chain draws from specialized organic seed stock, mechanical dehulling equipment, and certified milling infrastructure as critical inputs. Single-source vulnerability concentrates in Central European dehulling capacity clusters around Arnreiter Mühle GmbH facilities. Distribution runs through heritage-grain subscription channels, health food retail networks, and direct farm-to-bakery procurement pathways that bypass conventional supermarket intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward artisan bakery clusters and direct-to-consumer subscription platforms as procurement fragments away from centralized commodity distributors, concentrating volume negotiation leverage among educated heritage-grain consumers.
For Market Incumbents: Consolidate backward integration into organic acreage in Lower Saxony and Bavaria to secure certified supply against EU Green Deal input tightening. Lock in long-term offtake with Loire Valley grower cooperatives before North American organic certification expansion captures EU import demand. Defend margin position through proprietary dehulling technology licensing rather than equipment sales alone. For New Entrants and Emerging Players: Anchor in spelt bran functional food formulations for breakfast cereal and snack enrichment, the fastest-expanding application segment with lowest incumbent concentration. Target Paris-area bakery clusters and Swiss health food retailers for direct sourcing relationships that bypass established milling intermediaries. Pursue USDA National Organic Program certification to access midwestern US acreage development before supply saturates. For Investors and Strategic Acquirers: The market sits at an infrastructure-buildout phase that favors specialized dehulling technology providers and organic-certified milling assets over commodity grain traders. Long-term viability centers on captive supply control and authentication technology for heritage-grain provenance claims. Monitor FDA gluten-content threshold revisions as inflection signal for litigation exposure and reformulation cost impacts across flour segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acreage | Captures EU Green Deal premiums by securing certified supply in German cultivation zones. |
| Compact Dehulling Equipment Deployment | Enables farm-level processing in France and southern Germany, shortening supply chains. |
| Direct-to-Consumer Subscription Launch | Replicates Bob's Red Mill heritage-grain branding model for full margin capture. |
| Spelt Bran Functional Food Formulation | Penetrates fiber-enrichment trends in breakfast cereals beyond traditional flour applications. |
| DNA Authentication Technology Investment | Meets German laboratory mandates for varietal verification on packaged flour claims. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with artisan bakery owners, organic mill procurement directors, heritage-grain subscription platform operators, and EU organic certification auditors. Secondary validation drew from EU regulation 2018/848 compliance databases, USDA National Organic Program acreage reports, German customs trade statistics, and EFSA gluten-content guidance documents. Bottom-up volume modeling across product segments triangulated against top-down market sizing from trade flow analysis.
Across the analysis window, forecasts incorporate segmentation by product form, end-use application, distribution channel, and organic certification status. CAGRs derive from trend extrapolation of certified acreage conversion, dehulling capacity expansion, and channel shift velocity toward direct procurement. Industry-specific inputs include EU Green Deal Farm to Fork implementation timelines, mechanical dehulling technology adoption curves, and FDA labeling threshold evolution.
Material uncertainties — organic fertilizer cost volatility, gluten-content litigation outcomes, and North American organic certification expansion rates — sit outside the modeled envelope. Forecasts reflect assumptions around heritage-grain premium persistence and substitution elasticity to common wheat. Recalibration cycles align with material shifts in EU organic regulation revisions and FDA guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Brazil Maize Market
Grains
Europe Rice Market
Grains
Sorghum Flour Market
Grains
Global Quinoa Market
Grains
Argentina Maize Market
Grains
Green Banana Flour Market
Grains
Grain and Cereal Crop Market
Grains
Grain Storage Silos Market
Grains
Asia-Pacific Guar Market
Grains
Rice Flour Market
Grains
Rye Market
Grains
South American Maize Market
Grains
Gluten Free Ancient Grain Market
Grains
Triticale Market
Grains
Grain Bins Market
Grains
Asia Pacific Maize Market